
 Military Parachute Market | 2026-2036
Military Parachute Market Size, Share, and Industry Trends Forecast 2026-2036
Military Parachute Market Analysis
Special Forces insertion operations is realigning procurement priorities across NATO-aligned militaries. Safran SA leverages its European defense aerospace heritage to sustain long-term supply relationships with French and Belgian airborne units. Airborne Systems North America anchors Pentagon procurement through its dominance in static-line and HALO platform deliveries. Mills Manufacturing Corporation specializes in round parachute production for mass troop drops, occupying a distinct tier below precision-guided ram-air systems.
A military parachute is a personnel descent and cargo delivery system engineered from high-strength fabrics such as Kevlar-reinforced canopies and silicone-coated nylon suspension lines, manufactured through computer-aided cutting and thermo-bonded seam sealing to achieve specified glide ratios and opening shock limits. Ram-air parachutes command premium positioning within product type segmentation due to their steerable wing architecture and precision landing capability for special operations. Static line deployment models retain volume leadership across airborne infantry training and mass tactical jumps, while HALO systems represent the fastest-growing deployment category as covert insertion requirements expand.
The US FAA regulates civilian airworthiness certification for parachute systems carried on military transport aircraft, while NATO standardization agreements govern interoperability requirements across allied airborne forces. ISO quality management frameworks and national military specifications further constrain supplier qualification, elevating barriers for new entrants. Stakeholders must monitor evolving special operations command requirements for reduced radar cross-section materials and GPS-guided precision landing as these specifications will reshape supplier R&D allocation and certification timelines.
Market Dynamics
Special operations command requirements for reduced radar cross-section materials and GPS-guided precision landing are reshaping supplier R&D allocation and certification timelines across the military parachute value chain.
Growth Catalysts
- NATO Standardization Agreements:Interoperability mandates across allied airborne forces drive unified procurement specifications, creating volume consolidation for certified suppliers serving multiple member militaries.
- HALO Platform Expansion:Covert insertion requirements from special operations units accelerate demand for high-altitude, low-opening systems with steerable canopy architectures.
- Kevlar-Reinforced Fabric Adoption:Advanced composite materials with enhanced strength-to-weight ratios enable lighter payload configurations without sacrificing structural integrity under extreme deployment conditions.
Market Restraints
- Silicone-Coated Nylon Price Volatility:Petrochemical input fluctuations and specialized coating supply constraints compress margin predictability for suspension line manufacturers.
- US FAA Certification Bottlenecks:Civilian airworthiness protocols for military transport carriage create extended approval timelines that delay field deployment of next-generation recovery systems.
- Paragliding Equipment Substitution:Commercial recreational parachute technologies adapted for tactical training present lower-cost alternatives for non-combat jump qualification programs.
Strategic Opportunities
- Belgian Airborne Modernization:European defense aerospace heritage relationships position qualified suppliers for sustained long-term contracts as Belgian special forces expand precision insertion capabilities.
- Computer-Aided Cutting Convergence:Integration of automated pattern generation with thermo-bonded seam sealing reduces production variance and accelerates batch consistency for mass tactical orders.
- Reduced Radar Cross-Section Materials:Stealth-compatible canopy fabrics open white space in signature-managed insertion missions previously constrained by detectable nylon-Kevlar signatures.
Industry Challenges
- Airworthiness Board Talent Scarcity:Qualified engineers capable of navigating both FAA civilian protocols and military specification compliance remain concentrated among legacy defense contractors, limiting new entrant technical staffing.
- ISO Quality Management Integration:Dual-track certification requirements combining international frameworks with national military specifications extend qualification timelines and multiply documentation overhead for suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Parachute Market |
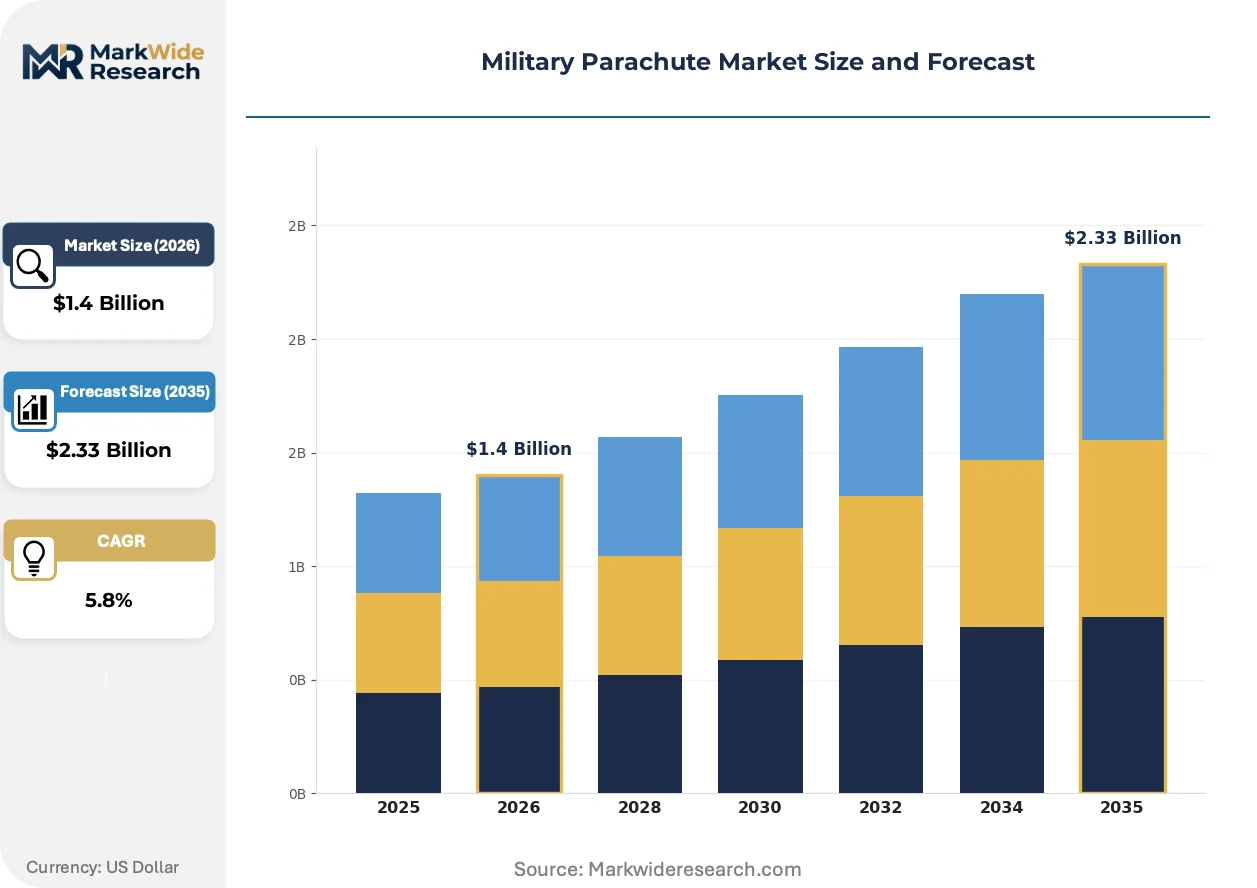
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Round Parachutes, Rectangular Parachutes, 3D Parachutes, Ram-Air Parachutes Deployment Model: Static Line, Free Fall, High Altitude Low Opening, Low Altitude High Opening End User: Military Personnel, Special Forces, Airborne Units, Training Academies Material: Silicone Coated Nylon, Polyamide, Polyester, Kevlar |
| Companies Covered | IrvinGQ, Butler Parachute Systems, Airborne Systems North America, CIMSA Ingenieria, Spekon, Safran SA, FXC Corporation, Aerodyne Research LLC, Mills Manufacturing Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Parachute Market Emerging Trajectories
Active development of precision-guided descent systems and signature-managed materials is compressing the gap between mass tactical drops and special operations insertion requirements across NATO-aligned procurement programs.
GPS-guided precision landing technology is expanding into special operations parachute systems, enabling meter-accurate touchdown capability in denied or contested environments. United States special operations commands are fielding these systems at accelerated procurement cycles. This capability compression is expanding into conventional airborne infantry training programs previously limited to static-line accuracy tolerances.
REACH chemical substance restrictions in Europe are mandating reformulation of silicone-based coating compounds used in suspension line weatherproofing. Industrial consequence includes supplier migration to fluoropolymer alternatives with comparable hydrophobic performance. Ram-air precision systems face the tightest compliance timelines as French and Belgian airborne units prioritize European-sourced material traceability.
Consolidated multi-year framework agreements are displacing annual purchase orders across Pentagon procurement channels. Defense logistics agencies now bundle static-line, HALO, and cargo platform requirements into single-source contracts spanning five-year horizons. This pattern concentrates most visibly in United States special operations command budgets, where platform interoperability requirements favor integrated supplier relationships over component-level competition.
Military Parachute Market Segmentation
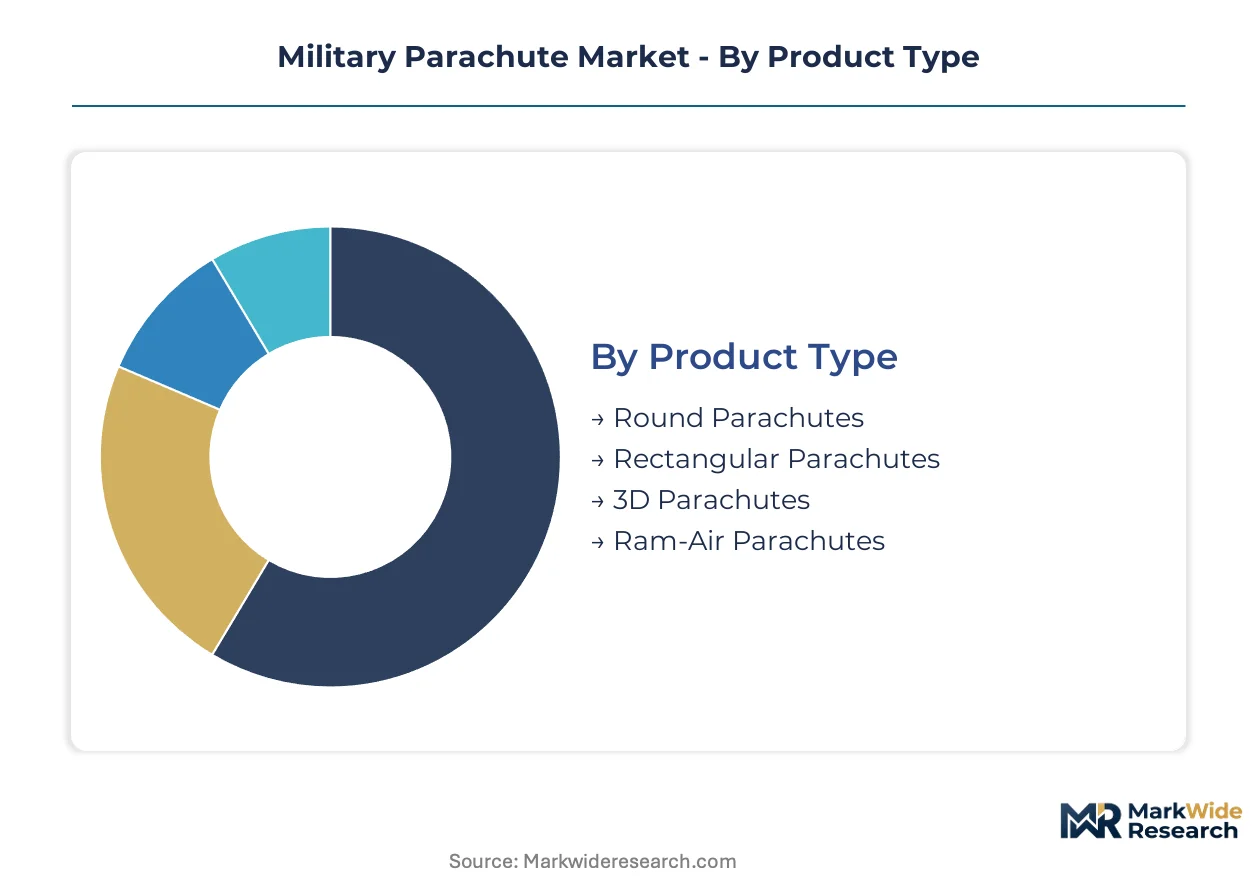
Segmentation in military parachute procurement reflects divergent operational requirements across conventional airborne forces and precision-insertion special operations. Material specifications and deployment architectures determine certification pathways, supplier qualification tiers, and contract value distribution within defense procurement channels.
Product Type:
Buyers in this category select canopy geometries based on mission precision requirements and payload configurations rather than unit cost alone.
- Round Parachutes:Classic circular canopy design with central vent stabilization, manufactured from low-porosity fabrics for predictable descent rates. Mass tactical drops by conventional airborne units sustain procurement volume, though steerability limitations restrict special operations adoption.
- Ram-Air Parachutes:Rectangular wing architecture with pressurized cells generating lift and directional control via brake toggles. Special Forces commands in the United States and France drive specification evolution toward GPS-guided precision landing and reduced radar signature materials.
- Rectangular Parachutes:Non-ram-air rectangular designs offering moderate glide ratio improvements over round configurations. Training academies employ these for intermediate skill progression before HALO qualification.
- 3D Parachutes:Multi-cell canopy geometries optimized for cargo and heavy equipment delivery with enhanced stability under asymmetric load conditions. Military logistics commands specify these for supply drops in contested environments.
Volume sits with Round Parachutes; growth tilts toward Ram-Air Parachutes.
Deployment Model:
Operational altitude and opening timing differentiate insertion profiles from mass airborne assault through covert special operations missions.
- Static Line:Automatic canopy deployment via fixed cord connection to aircraft anchor line cable, eliminating manual pull requirements. United States airborne infantry training programs and NATO mass tactical exercises maintain this as the foundational certification standard.
- HALO (High Altitude Low Opening):Oxygen-assisted exit at altitude with delayed canopy deployment near terrain masking elevation. United States special operations commands field these systems at accelerated procurement cycles for denied-area insertion.
- Free Fall:Unassisted descent with manual deployment timing, serving as the bridge technique between static-line proficiency and HALO qualification. Training academies structure curriculum progression around this intermediate capability.
- LAHO (Low Altitude High Opening):Early deployment at low altitude for extended glide paths into precision landing zones. Belgian and French airborne units specify these for urban insertion scenarios requiring minimal aircraft exposure.
Procurement volume clusters on Static Line; capability investment flows fastest into HALO systems.
End User:
Customer type determines specification stringency, certification overhead, and contract duration within defense procurement frameworks.
- Special Forces:Tier-one operators requiring stealth-compatible materials, GPS precision guidance, and multi-mission platform interoperability. United States SOCOM budgets concentrate supplier relationship investment through consolidated multi-year framework agreements.
- Military Personnel:Conventional service members across army, marine, and air force branches requiring standardized static-line qualification. Volume procurement through defense logistics agencies favors proven designs with minimal field maintenance requirements.
- Airborne Units:Designated parachute infantry formations with specialized equipment tables and rapid-deployment mission profiles. NATO standardization agreements govern interoperability specifications across allied airborne forces.
- Training Academies:Instructional institutions managing progression from initial jump qualification through advanced tactical certifications. These buyers prioritize equipment durability under repetitive use and simplified rigging protocols.
Contract value aggregates with Special Forces; unit volume concentrates with Military Personnel.
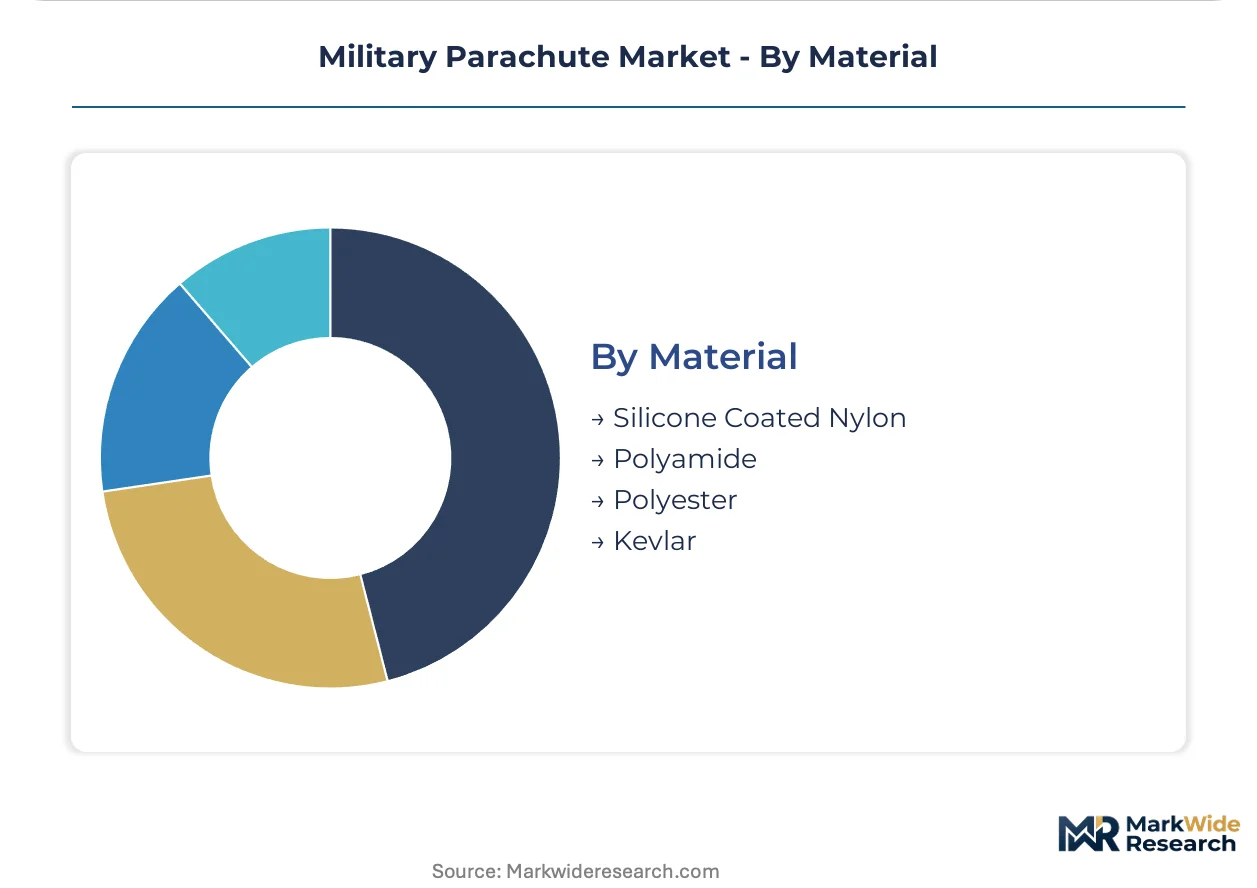
Material:
Raw material selection trades strength-to-weight ratio against signature management and chemical compliance constraints.
- Kevlar:Aramid fiber reinforcement providing exceptional tensile strength for suspension lines and ripstop canopy grids. Special operations requirements for reduced radar cross-section drive specification of Kevlar-dominant fabric weaves in United States and French procurement.
- Silicone Coated Nylon:Petrochemical-derived base fabric with hydrophobic surface treatment for moisture resistance and packability. REACH chemical restrictions in Europe are mandating supplier migration to alternative coating compounds.
- Polyamide:Synthetic polymer family encompassing nylon variants with calibrated elasticity for shock absorption during canopy inflation. Mass tactical parachute production relies on polyamide cost efficiency at scale.
- Polyester:Alternative synthetic with superior UV degradation resistance for extended storage in tropical or desert conditions. Training academies specify polyester-dominant canopies for equipment longevity under high-cycle use.
Silicone Coated Nylon retains volume leadership; Kevlar commands the steepest specification premium expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense aerospace special economic zones in Toulouse, Bangalore, and Fort Bragg corridor concentrate military parachute R&D and airworthiness certification infrastructure. These zones attract tier-one suppliers through accelerated regulatory pathways and co-located testing facilities.
United States
United States Special Operations Command sustains the largest procurement budget for HALO and precision-guided descent systems. FAA airworthiness protocols govern military transport carriage certification, creating extended approval timelines for next-generation recovery systems. Airborne Systems North America anchors Pentagon procurement from manufacturing clusters in North Carolina and California.
France
French airborne units drive specification evolution for reduced radar cross-section materials and GPS-guided precision landing. ANSM and DGA defense procurement frameworks mandate European-sourced material traceability for special forces equipment. Safran SA leverages its Toulouse aerospace heritage to sustain supply relationships with French and Belgian special operations commands.
Belgium
Belgian special forces expansion in precision insertion capabilities creates sustained long-term contract opportunities for qualified suppliers. REACH chemical substance restrictions mandate reformulation of silicone-based coating compounds used in suspension line weatherproofing. Brussels-Antwerp corridor hosts certification bodies serving NATO standardization agreements for allied airborne interoperability.
United Kingdom
UK Defence Equipment and Support prioritizes multi-mission platform interoperability through consolidated framework agreements spanning static-line and HALO requirements. Military Aviation Authority regulations align with NATO standardization protocols for joint airborne exercises. BAE Systems integration partners in Lancashire and Bristol supply canopy fabrication for British special forces.
Germany
German Bundeswehr airborne modernization programs emphasize ISO quality management integration alongside national military specifications. KBA and BAAINBw procurement channels extend qualification timelines through dual-track certification requirements. Bavarian industrial clusters around Munich concentrate thermo-bonded seam sealing and computer-aided cutting capabilities for mass tactical orders.
Military Parachute Market Vendor Landscape
Top-tier vendors anchor Pentagon and NATO procurement channels through consolidated multi-year framework agreements, while mid-tier specialists occupy distinct niches in round parachute production and training equipment. The vendor base stratifies across three archetypes: European defense aerospace heritage firms with long-term supply relationships, North American integrated platform suppliers dominating precision-guided systems, and regional fabricators serving national airborne units with cost-optimized static-line configurations. Competitive moves concentrate on backward integration into Kevlar-reinforced fabric weaving and strategic partnerships for GPS-guided precision landing technology licensing.
Within the European heritage tier, Safran SA exemplifies sustained long-term supply relationships with French and Belgian airborne units. Airborne Systems North America occupies a position as the dominant integrated platform supplier for United States special operations commands. Mills Manufacturing Corporation represents the round parachute specialist archetype, serving mass tactical drop requirements for conventional airborne infantry training programs.
| Leading Market Players |
|---|
| IrvinGQ |
| Butler Parachute Systems |
| Airborne Systems North America |
| CIMSA Ingenieria |
| Spekon |
| Safran SA |
| FXC Corporation |
| Aerodyne Research LLC |
| Mills Manufacturing Corporation |
| Others |
Supply Flow & Price Mechanics
Thermo-bonded seam sealing adoption across North Carolina and Bavarian production clusters simultaneously compresses unit labor costs and concentrates supplier qualification among firms with capital-intensive bonding infrastructure. This production-method transition elevates barriers for fabricators lacking automated pattern generation, tightening procurement options for defense logistics agencies and amplifying pricing power among certified tier-one vendors.
Pricing Analysis
Short lead-time premiums of 15-25% apply to HALO system orders against accelerated fielding schedules, while spot inventory of static-line configurations trades at modest discounts. Three-tier pricing structure across precision-guided ram-air, conventional static-line, and training-grade round parachutes separates special operations procurement from mass tactical and academy volume contracts. Cost compression in silicone-coated nylon suspension lines is intensifying because REACH-mandated coating reformulation feeds fluoropolymer input scarcity. Training academies exhibit highest price sensitivity due to repetitive-use equipment replacement cycles, whereas United States SOCOM budgets show lowest sensitivity given mission-critical precision requirements.
Supply Chain Analysis
Regional distribution centers in Toulouse, Fort Bragg corridor, and Brussels-Antwerp corridor anchor hub-and-spoke fulfillment patterns for NATO-aligned airborne units. Manufacturing gravity centers on the United States, France, and Germany, with Kevlar-reinforced fabric weaving concentrated in North Carolina and Bavarian industrial clusters. Raw material dependencies draw from DuPont aramid fiber supply, petrochemical-derived nylon substrates, and fluoropolymer coating compounds. Single-source vulnerability around FAA-certified airworthiness engineering talent in legacy defense contractors presents structural concentration risk. Distribution runs through defense logistics agency central contracting with direct-to-unit delivery for special operations commands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GPS-guided precision landing technology is displacing legacy static-line accuracy tolerances across both special operations and conventional airborne training programs, compressing capability gaps and reshaping procurement specifications.
For Market Incumbents: To counter paragliding equipment substitution in non-combat jump qualification programs, Airborne Systems North America and Safran SA should deepen backward integration into Kevlar-reinforced fabric weaving to capture margin from aramid fiber supply constraints. Certification investment in reduced radar cross-section materials ISO frameworks will defend positioning against emerging stealth-compatible canopy entrants. For New Entrants and Emerging Players: Digital-channel defense procurement portals offer direct access to training academy and reserve component buyers outside consolidated SOCOM framework agreements. White-space targets include polyester-dominant round parachutes for high-cycle tropical storage applications and REACH-compliant fluoropolymer suspension line coatings for French and Belgian airborne modernization. A specialized coating chemistry go-to-market angle bypasses incumbent Kevlar-weaving capital barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated platform suppliers seeking HALO capability fill-ins rather than financial sponsor buyouts. Long-term viability favors vertically integrated firms with captive aramid fiber supply and FAA airworthiness certification infrastructure. The signal to watch is Belgian special forces precision insertion budget acceleration as a leading indicator of European ram-air procurement inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kevlar Fabric Weaving | Captures margin from DuPont aramid fiber supply constraints affecting suspension line manufacturers. |
| GPS-Guided Precision Landing Certification | Unlocks United States SOCOM multi-year framework agreements for meter-accurate touchdown systems. |
| REACH-Compliant Coating Reformulation | Preserves European market access for French and Belgian airborne units mandating material traceability. |
| Computer-Aided Cutting Scale-Up | Reduces production variance for German Bundeswehr mass tactical orders under ISO quality frameworks. |
| Reduced Radar Cross-Section Material R&D | Opens signature-managed insertion missions previously constrained by detectable nylon-Kevlar signatures. |
Methodological Framework
Independent corroboration across defense procurement officers, airworthiness certification engineers, and special operations equipment program managers underwrites the qualitative findings in this study. Primary fieldwork with NATO standardization agreement technical committees and French DGA procurement frameworks combined with secondary validation from FAA airworthiness directives, REACH chemical substance registrations, and ISO quality management documentation. Bottom-up unit demand modeling across product type, deployment model, and end-user segments triangulates against top-down defense budget appropriation analysis.
Rate-of-change decomposition across the projection horizon separates volume growth from mix-shift effects between static-line, HALO, and precision-guided descent systems. Segmentation dimensions modeled include canopy geometry, operational altitude profile, customer tier stringency, and material specification grade. CAGRs derive from defense modernization budget trajectories and special operations command procurement cycle analysis. Industry-specific forecast inputs incorporate Kevlar-reinforced fabric adoption curves and GPS guidance technology fielding timelines.
The model holds under sustained United States defense appropriation levels and NATO interoperability commitment continuity; deviation in Belgian or French airborne modernization acceleration would shift European demand projections. Periodic stress-testing of base assumptions against REACH regulatory amendment schedules and FAA certification backlog fluctuations is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Military Software Market
Defense and Military Systems and Equipment
Anti-Jamming Equipment Market
Defense and Military Systems and Equipment
Smart War Weapon Market
Defense and Military Systems and Equipment
Europe Defense Market
Defense and Military Systems and Equipment
Military Rifle Market
Defense and Military Systems and Equipment
United Kingdom Defense Market
Defense and Military Systems and Equipment
Command and Control Systems Market
Defense and Military Systems and Equipment
Military High Altitude Radio Jamming System Market
Defense and Military Systems and Equipment
Military Helmet and Helmet Mounted Displays Market
Defense and Military Systems and Equipment
Global Military Laser Rangefinder Market
Defense and Military Systems and Equipment
Network Centric Warfare (NCW) Market
Defense and Military Systems and Equipment
Missiles and Missile Defense Systems Market
Defense and Military Systems and Equipment
Search and Rescue Equipment Market
Defense and Military Systems and Equipment
Military Exoskeleton Market
Defense and Military Systems and Equipment
Mine Clearance System Market
Defense and Military Systems and Equipment
Battle Management System (BMS) Market