
 Military High Altitude Radio Jamming System Market | 2026-2036
Military High Altitude Radio Jamming System Market Size, Share, and Industry Trends Forecast 2026-2036
Military High Altitude Radio Jamming System Market Insights
Consolidation among allied defense procurement agencies is realigning vendor qualification pathways toward multi-year platform contracts. Lockheed Martin leverages its integrated warfare systems division to dominate high-altitude electronic attack program awards. Raytheon Technologies sustains competitive positioning through classified signal-processing architectures developed for airborne jamming pods. Northrop Grumman anchors its presence in next-generation jammer competitions with digital radio frequency memory technologies.
Military High Altitude Radio Jamming Systems are electronic warfare assets engineered to emit targeted electromagnetic energy across VHF through Ku-band spectra, typically deployed from platforms operating above 30,000 feet to maximize line-of-sight propagation and effective radiated power against adversary communications and radar networks. Fixed Station configurations occupy the largest installed base due to persistent territorial defense commitments, while Airborne Platform variants represent the fastest-expanding segment as militaries prioritize maneuverable electronic attack. Digital Signal Processing technology leads investment flows for its software-defined adaptability against frequency-agile threats, though Pulse Jamming retains niche relevance for saturation attacks against legacy radar systems.
The FCC regulates electromagnetic emissions for systems tested within US territory, while NATO's Joint Air Power Competence Centre shapes interoperability standards for coalition electronic warfare operations. The International Telecommunication Union coordinates spectrum allocation treaties that constrain peacetime jamming system testing protocols. Stakeholders must monitor evolving ITU Radio Regulations and national export control harmonization to anticipate compliance costs and market access barriers.
Market Dynamics
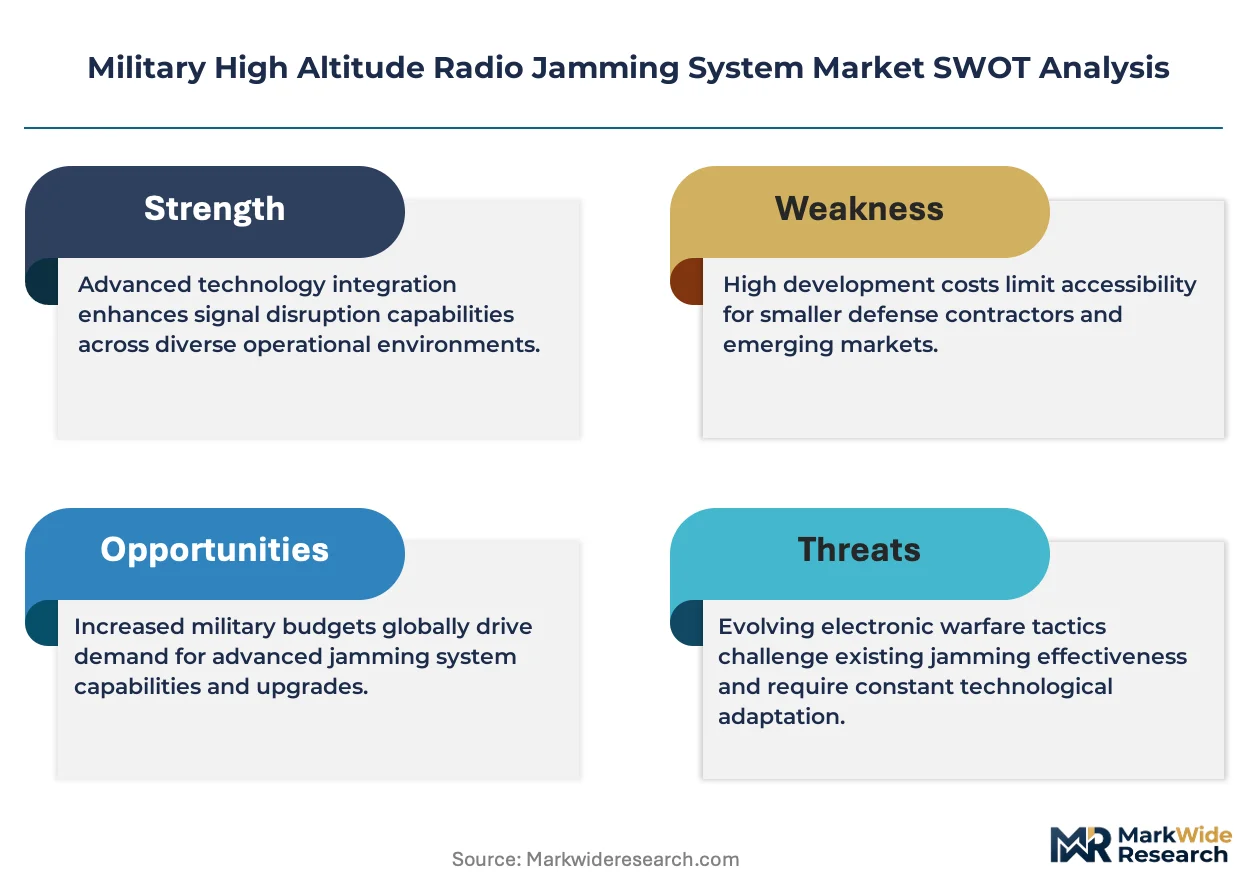
Defense procurement agencies are consolidating electronic warfare requirements into multi-year platform contracts, forcing vendors to restructure qualification pathways around integrated system architectures rather than component sales.
Growth Catalysts
- ITU Radio Regulations:The International Telecommunication Union's spectrum allocation treaties create predictable testing protocols for peacetime jamming system validation, reducing regulatory uncertainty for NATO-aligned manufacturers.
- Frequency-agile threat proliferation:Adversary communications systems employing rapid frequency hopping drive investment in software-defined digital signal processing architectures with real-time adaptability.
- Congressional defense appropriations:United States legislative prioritization of electronic countermeasure modernization programs sustains procurement momentum for high-altitude jamming platforms.
Market Restraints
- Gallium nitride substrate costs:Power amplifier components for Ku-band emissions depend on constrained GaN supply chains concentrated among specialty semiconductor foundries.
- NATO interoperability certification:The Joint Air Power Competence Centre's coalition electronic warfare standards impose multi-year validation timelines that delay revenue recognition for new platform entries.
- Commercial spectrum encroachment:5G C-band deployments compress available military spectrum for high-power jamming operations in populated test corridors.
Strategic Opportunities
- Poland's territorial defense modernization:Eastern NATO flank states are establishing fixed-station jamming architectures for persistent electromagnetic denial along border regions.
- Digital radio frequency memory convergence:DRFM technology paired with machine learning threat libraries enables coherent jamming responses against previously unrecorded signal signatures.
- Airborne pod retrofit programs:Legacy fighter fleets without native electronic attack capability present aftermarket integration demand for external jamming carriage systems.
Industry Challenges
- Cleared workforce scarcity:Radio frequency engineering talent with active security clearances commands premium compensation that compresses program margins.
- Legacy platform integration:Cold War-era aircraft bus architectures lack bandwidth for modern jamming system data throughput, requiring expensive avionics bridge modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military High Altitude Radio Jamming System Market |
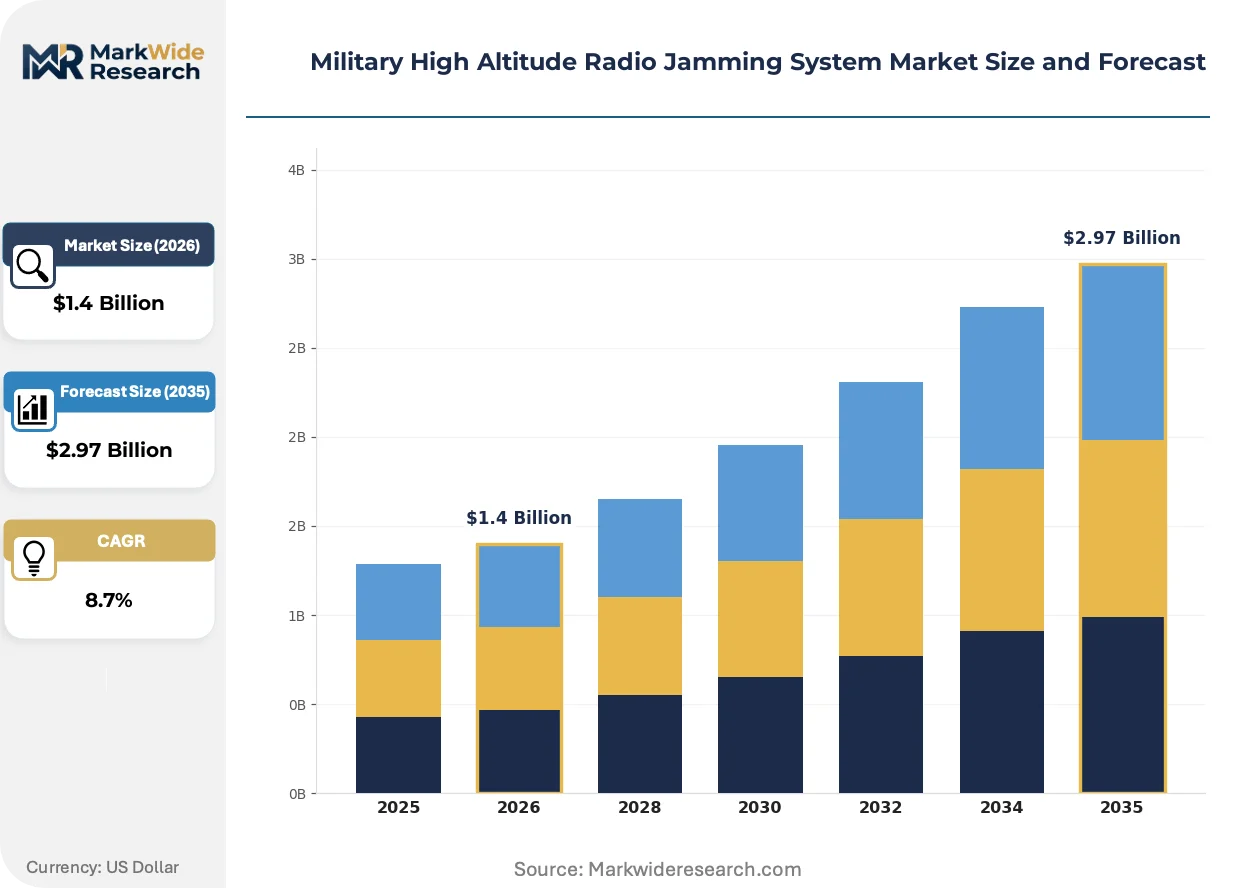
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Station, Mobile Station, Airborne Platform, Portable System Technology: Digital Signal Processing, Frequency Hopping, Spread Spectrum, Pulse Jamming Use Case: Electronic Countermeasures, Signal Interruption, Communications Disruption, Radar Suppression End User: Defense Forces, Intelligence Agencies, Border Patrol Units, Coast Guard |
| Companies Covered | Lockheed Martin, Raytheon Technologies, Northrop Grumman, BAE Systems, L3Harris Technologies, Israel Aerospace Industries, Thales Group, Mercury Systems, Saab AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military High Altitude Radio Jamming System Market Trends and Innovations
Electronic warfare architectures are migrating from hardware-defined to software-configurable platforms, compressing upgrade cycles and reshaping vendor competitive moats around firmware rather than physical design.
Digital signal processing is integrating cognitive radio techniques that autonomously characterize and counter adversary waveforms without operator intervention. United States Air Force electronic attack squadrons are fielding these capabilities through iterative software drops rather than platform replacement. This compression of upgrade cycles is integrating jamming system vendors into continuous service relationships rather than episodic hardware procurement.
The FCC's equipment authorization procedures for electromagnetic emissions testing are tightening documentation requirements for defense contractors operating within US territory. This regulatory friction extends program development timelines by eight to fourteen months for systems requiring domestic validation. Airborne platform segments are responding by relocating critical testing phases to allied nations with reciprocal spectrum agreements.
Defense procurement offices are unbundling electronic warfare system sustainment from initial platform acquisition, creating discrete contract vehicles for software maintenance and threat library updates. This separation is compressing prime contractor margins on hardware while elevating recurring revenue streams for specialized signal processing firms. The United Kingdom's Defence Equipment and Support organization has adopted this model most aggressively among NATO procurement agencies.
Military High Altitude Radio Jamming System Market Segmentation
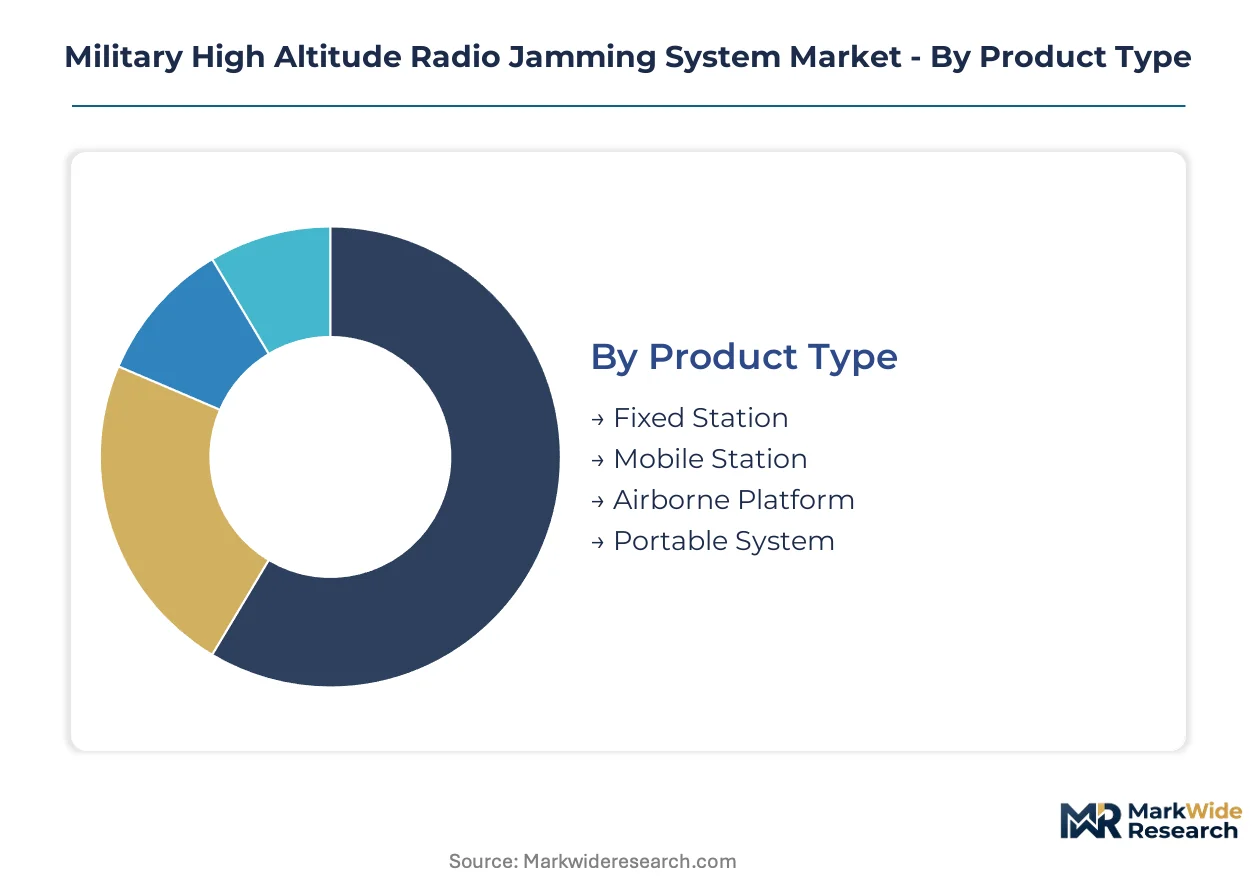
Segmentation in military high-altitude radio jamming systems reveals how procurement priorities diverge between territorial defense and maneuver warfare doctrines. Procurement agencies structure requirements around platform mobility, signal processing sophistication, and operational altitude envelopes.
Product Type:
Customization intensity varies sharply across this category, from bespoke fixed installations to standardized pod configurations.
- Fixed Station:Permanent terrestrial installations with high-power amplifier arrays and dedicated cooling infrastructure. NATO's eastern flank states—Poland, Romania, and the Baltic nations—are deploying these for persistent electromagnetic denial along border corridors. Congressional appropriations for European Deterrence Initiative funding accelerate these deployments.
- Airborne Platform:External pod or internal bay systems carried by fighter and bomber aircraft above 30,000 feet. United States Air Force electronic attack squadrons prioritize these for time-sensitive targeting of mobile adversary command nodes. Frequency-agile threat proliferation drives software-defined architecture upgrades.
- Mobile Station:Vehicle-mounted systems with deployable antenna masts for rapid repositioning. These bridge fixed persistence and airborne reach.
- Portable System:Man-portable units for special operations and forward deployment. Limited effective radiated power constrains these to tactical communications disruption.
Most installed capacity flows through Fixed Station configurations. Expansion is steepest in Airborne Platform variants.
Technology:
Cost tier separation distinguishes software-configurable architectures from legacy hardware-dependent systems.
- Digital Signal Processing:Software-defined radio architectures enabling real-time waveform adaptation against frequency-hopping threats. United States Navy Next-Generation Jammer programs and Royal Air Force E-7 Wedgetail integrations anchor demand. Machine learning threat libraries compress response latency below human operator thresholds.
- Pulse Jamming:High-peak-power burst transmissions for saturation attacks against legacy radar systems. These retain niche relevance in Pacific theater scenarios against older surface-to-air missile batteries. Gallium nitride power amplifiers extend duty cycles beyond earlier tube-based designs.
- Frequency Hopping:Rapid spectral agility to evade adversary direction-finding and counter-jamming. Coalition interoperability requirements from NATO's Joint Air Power Competence Centre shape validation protocols.
- Spread Spectrum:Wideband noise generation for area denial against multiple simultaneous threats. Energy efficiency constraints limit deployment to higher-altitude platforms.
Procurement concentration centers on Digital Signal Processing. Pulse Jamming maintains specialized demand in legacy threat environments.
Use Case:
Application urgency separates continuous electromagnetic operations from time-critical strike support missions.
- Electronic Countermeasures:Active jamming to degrade adversary sensor and weapon system effectiveness. United States Indo-Pacific Command prioritizes these for maritime strike package protection. Real-time threat-emitter correlation demands high-bandwidth datalink integration.
- Communications Disruption:Targeted denial of command-and-control networks. Border Patrol Units in the southwestern United States deploy these against cross-border narcotics trafficking coordination. FCC equipment authorization procedures constrain domestic testing protocols.
- Signal Interruption:Disruption of specific frequency assignments without broader spectral contamination. Intelligence Agencies favor these for surgical operations preserving adjacent spectrum for collection.
- Radar Suppression:Dedicated defeat of ground-based and airborne early warning systems. Penetration mission profiles for stealth aircraft drive integration requirements.
Electronic Countermeasures absorb the largest share of defense appropriations. Communications Disruption is expanding most quickly among homeland security applications.
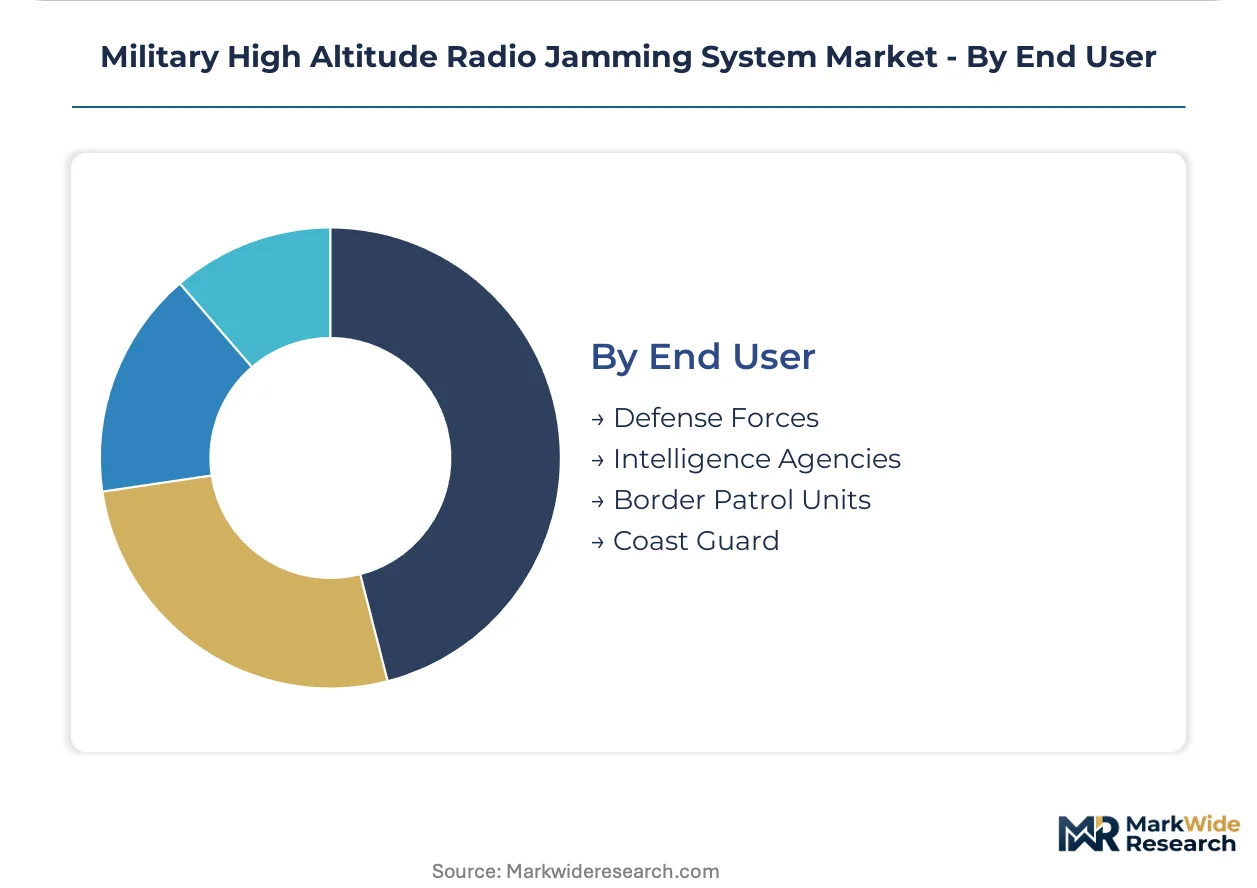
End User:
Customer type determines security classification thresholds and foreign disclosure limitations.
- Defense Forces:Military service branches with organic electronic warfare units. United States Army's 11th Airborne Division and Marine Corps Information Groups are restructuring for high-altitude jamming integration. Multi-domain operations doctrine fuses these capabilities with cyber and space effects.
- Intelligence Agencies:National technical means organizations with signals intelligence overlap. National Security Agency and Government Communications Headquarters coordination shapes dual-use system specifications. Cleared workforce scarcity compresses vendor staffing options.
- Border Patrol Units:Domestic security agencies with spectrum coordination requirements. Customs and Border Protection operates under NTIA frequency assignments distinct from military allocations.
- Coast Guard:Maritime law enforcement with port security and drug interdiction missions. Smaller platform footprints constrain system size and power budgets.
Defense Forces command the preponderance of procurement volume. Intelligence Agencies are gaining share fastest as dual-use architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent with security clearances concentrates in the United States, anchoring North American dominance in high-altitude electronic warfare development. Allied defense procurement consolidation across NATO's eastern flank is redirecting investment toward territorial jamming architectures. Asian-Pacific military modernization programs are accelerating demand for airborne electronic attack platforms.
United States
Congressional defense appropriations prioritize electronic countermeasure modernization through multi-year platform contracts. FCC equipment authorization procedures constrain domestic electromagnetic emissions testing timelines. The Washington-Baltimore corridor hosts classified signal-processing development clusters serving Air Force electronic attack squadrons.
Poland
Territorial defense modernization drives fixed-station jamming procurement along eastern border corridors. European Deterrence Initiative funding accelerates persistent electromagnetic denial deployments. Warsaw-based defense electronics clusters coordinate with NATO's Joint Air Power Competence Centre on interoperability certification.
United Kingdom
Royal Air Force E-7 Wedgetail integrations anchor demand for software-defined jamming architectures. Defence Equipment and Support unbundling of sustainment contracts creates discrete revenue streams for signal processing firms. The Bristol-Bath aerospace corridor concentrates digital radio frequency memory development.
Germany
Bundeswehr electronic warfare restructuring prioritizes maneuverable airborne platforms for coalition operations. National export control harmonization with EU dual-use regulations shapes vendor qualification pathways. Munich-Augsburg defense electronics clusters supply NATO interoperability-certified subsystems.
Israel
Regional threat environments drive investment in frequency-agile countermeasures against rapidly evolving adversary communications. National spectrum management authority coordinates peacetime testing protocols with military operational requirements. Haifa-Tel Aviv corridors concentrate classified waveform development for airborne jamming pods.
Military High Altitude Radio Jamming System Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered qualification pathways. Prime contractors with integrated warfare systems divisions dominate multi-year platform awards, while component suppliers capture recurring software maintenance contracts. Three archetypes prevail: full-spectrum system integrators, specialized signal-processing firms, and state-affiliated defense conglomerates. Consolidation through strategic acquisitions and technology licensing agreements reshapes vendor positioning.
Within the full-spectrum integrator tier, Lockheed Martin and Raytheon Technologies exemplify diversified conglomerates with classified development capabilities. Northrop Grumman occupies a position among specialists leveraging digital radio frequency memory architectures. BAE Systems and Thales Group represent state-affiliated European anchors serving NATO coalition requirements. L3Harris Technologies and Mercury Systems sit within the component-specialist vector, capturing unbundled sustainment contracts as procurement agencies separate hardware acquisition from software maintenance.
| Leading Market Players |
|---|
| Lockheed Martin |
| Raytheon Technologies |
| Northrop Grumman |
| BAE Systems |
| L3Harris Technologies |
| Israel Aerospace Industries |
| Thales Group |
| Mercury Systems |
| Saab AB |
| Others |
Pricing and Supply Chain Analysis
Congressional defense appropriations for multi-year electronic countermeasure modernization programs are compressing vendor margins and forcing supply chain restructuring toward GaN substrate diversification. This procurement consolidation shifts pricing power toward prime contractors with integrated warfare systems divisions while squeezing component specialists on unbundled sustainment contracts.
Pricing Analysis
Capacity additions in United States specialty semiconductor foundries are reshaping price floors for GaN power amplifier components critical to Ku-band jamming systems. Three-tier pricing structure across mission-certified, NATO-interoperable, and export-restricted tiers separates systems by security classification and validation timeline. Cost compression in airborne platform segments is intensifying because prime contractors absorb FCC equipment authorization delays. Intelligence agencies exhibit least price sensitivity due to cleared workforce scarcity and mission-critical procurement urgency.
Supply Chain Analysis
Regional distribution centers in Washington-Baltimore, Munich-Augsburg, and Haifa-Tel Aviv corridors anchor hub-and-spoke patterns for classified signal-processing hardware. Manufacturing concentrates in United States, Germany, and Israel for NATO interoperability certification and security clearance infrastructure. Raw material dependencies include gallium nitride substrates, high-purity aluminum for thermal management, and specialized RF laminates. Single-source vulnerability in GaN foundry capacity presents structural risk. Distribution runs through defense procurement agency direct contracts with limited aftermarket channel penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FCC equipment authorization tightening and NATO Joint Air Power Competence Centre certification requirements continuously elevate compliance barriers and consolidate vendor tiers.
For Market Incumbents: Deepen backward integration into GaN substrate supply through captive semiconductor foundry partnerships or long-term offtake agreements with United States specialty manufacturers. Fortify software-defined architecture roadmaps against pulse jamming specialists exploiting legacy radar saturation demand in Pacific theater scenarios. Certification investment in dual-use signal intelligence interfaces creates defensive moats against emerging pure-play DRFM firms.
For New Entrants and Emerging Players: Direct-to-defense procurement agency digital channels bypass prime contractor gatekeeping for unbundled sustainment contracts and threat library update services. White-space targets include Poland's territorial defense modernization fixed-station deployments and Royal Air Force E-7 Wedgetail software retrofit programs. Machine learning threat library development for previously unrecorded signal signatures offers the most penetrable entry vector against established firmware architectures.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized signal-processing firms capturing recurring revenue from procurement agency unbundling of software maintenance from hardware acquisition. Long-term viability centers on continuous service relationships rather than episodic platform replacement cycles. The signal to monitor is congressional appropriations language shifting from platform procurement to software-defined capability drops as inflection indicator for margin structure transformation.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Foundry Backward Integration | Captive substrate supply secures Ku-band amplifier capacity against specialty semiconductor bottlenecks. |
| Machine Learning Threat Library Development | DRFM-ML convergence enables coherent jamming against unrecorded adversary waveforms for USAF squadrons. |
| NATO Interoperability Certification Investment | JAPCC validation accelerates coalition electronic warfare procurement access across eastern flank states. |
| Airborne Pod Retrofit Program Capture | Legacy fighter fleet integration demand creates aftermarket revenue streams without platform competition. |
| Software-Defined Architecture Roadmap Extension | Iterative firmware drops compress upgrade cycles and elevate recurring maintenance contract capture. |
Research Methodology
Bottom-up defense procurement modeling reconciled against top-down GaN substrate supply tracking forms the analytical core of this study. Primary interviews with electronic warfare program officers, RF engineering directors at prime contractors, cleared workforce recruiters, and NATO JAPCC certification specialists combined with secondary validation from FCC equipment authorization databases, congressional defense appropriations records, SEC 10-K filings of listed defense conglomerates, and ITU Radio Regulation treaty documents. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of electronic countermeasure modernization appropriations established baseline growth patterns across the projection horizon. Segmentation modeling incorporated platform mobility tier, signal processing architecture type, operational altitude envelope, and end-user security classification. CAGRs derived from procurement pipeline visibility and threat environment evolution assumptions. Industry-specific forecast inputs include frequency-agile threat proliferation rates and GaN foundry capacity expansion timelines.
The model assumes a particular technology adoption path; alternative pathways for cognitive radio autonomous waveform characterization would alter the outlook if machine learning integration encounters cleared workforce constraints or security classification barriers. Forecasts reflect documented assumptions regarding congressional funding continuity and NATO interoperability harmonization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
United States Defense Market
Defense and Military Systems and Equipment
Counter-IED Systems Market
Defense and Military Systems and Equipment
Mine Clearance System Market
Defense and Military Systems and Equipment
Mergers and Acquisitions (Manda) in Aerospace and Defense Market
Defense and Military Systems and Equipment
Network Centric Warfare (NCW) Market
Defense and Military Systems and Equipment
Airborne Electronic Warfare Market
Defense and Military Systems and Equipment
Global Military Laser Rangefinder Market
Defense and Military Systems and Equipment
Anti-Drone Guns Market
Defense and Military Systems and Equipment
Military Rifle Market
Defense and Military Systems and Equipment
Military Actuators Market
Defense and Military Systems and Equipment
Command and Control Systems Market
Defense and Military Systems and Equipment
Radar Warning Receiver Market
Defense and Military Systems and Equipment
Explosive Ordnance Disposal (EOD) Equipment Market
Defense and Military Systems and Equipment
Defense Tactical Computers Market
Defense and Military Systems and Equipment
Battle Management System (BMS) Market
Defense and Military Systems and Equipment
Global Digital Battlefield Market