
 Explosive Ordnance Disposal (EOD) Equipment Market | 2026-2036
Explosive Ordnance Disposal (EOD) Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Explosive Ordnance Disposal (EOD) Equipment Market Foresight
ISO 9001 and NATO STANAG 4569 qualification cycles is redrawing competitive entry barriers for armor and robotics suppliers in this sector. L3Harris Technologies, Inc. leverages its communications integration heritage to bundle jam-resistant datalinks with robotic platforms. Cobham Limited sustains its position through captive production of RF-shielded tether systems for remote-controlled vehicles. Northrop Grumman Corporation anchors its presence via unmanned ground vehicle autonomy stacks originally developed for broader defense programs.
Explosive Ordnance Disposal Equipment encompasses protective ensembles, robotic platforms, detection sensors, and disruption tools engineered to neutralize conventional munitions and improvised explosive devices without catastrophic detonation. Bomb disposal suits incorporate composite armor plates rated against fragment velocities exceeding 450 meters per second while maintaining operator mobility for manual render-safe procedures. Remote Controlled Vehicles command the largest product category share as militaries replace legacy tethered systems with semi-autonomous platforms capable of stair-climbing and subterranean access. Detection Equipment represents the fastest-growing segment due to multispectral sensor fusion combining ground-penetrating radar with chemical trace analyzers. Disruption Tools remain a mature margin pool where water-jet projectors and high-power microwave emitters face limited supplier turnover.
FAA regulations govern civilian airspace deployment of EOD drones near airports, while NATO STANAG frameworks harmonize interoperability requirements across allied military procurement. The U.S. Department of Defense mandates MIL-STD-810 environmental testing for all fielded robotic systems, compressing vendor qualification timelines. Stakeholders must monitor how EU AI Act risk classifications apply to autonomous target-recognition algorithms in next-generation EOD robots.
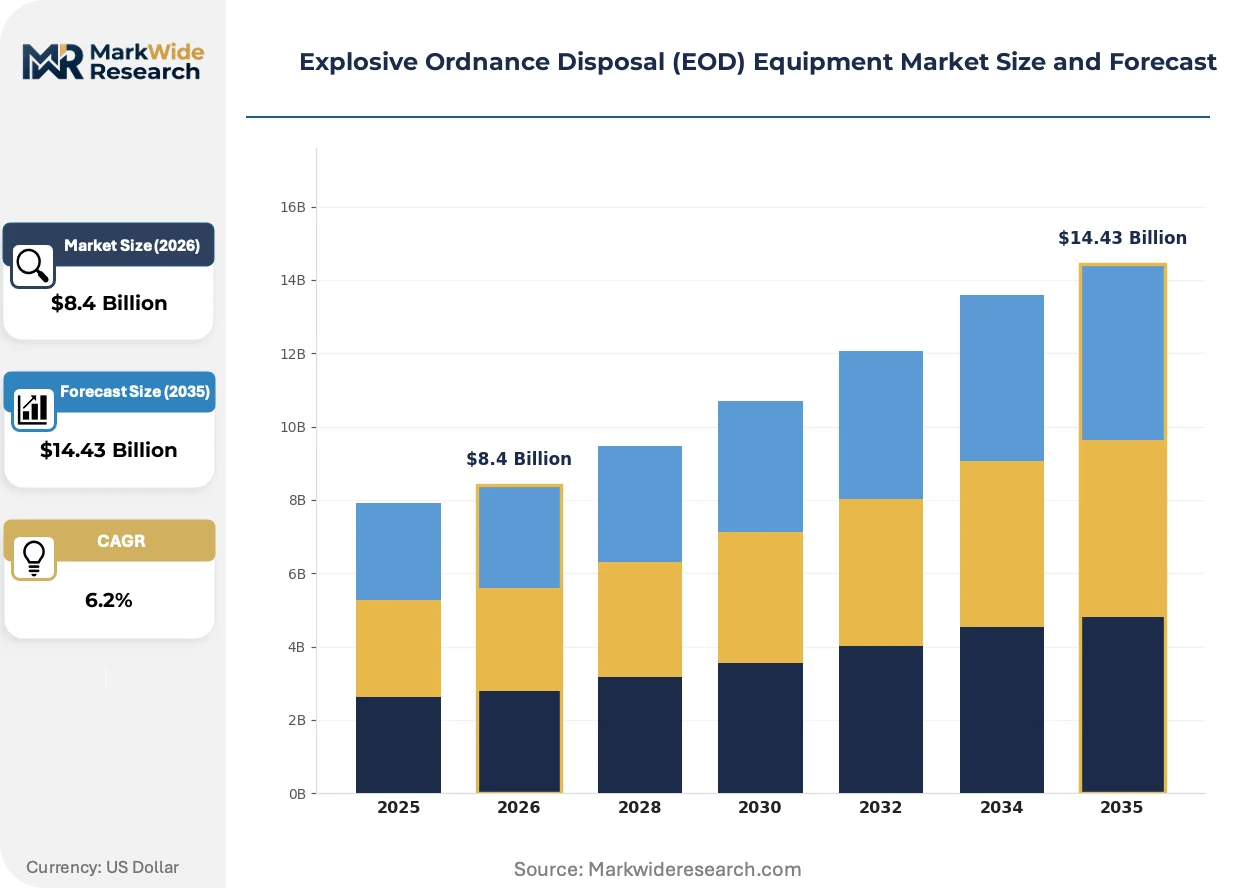
Market Dynamics
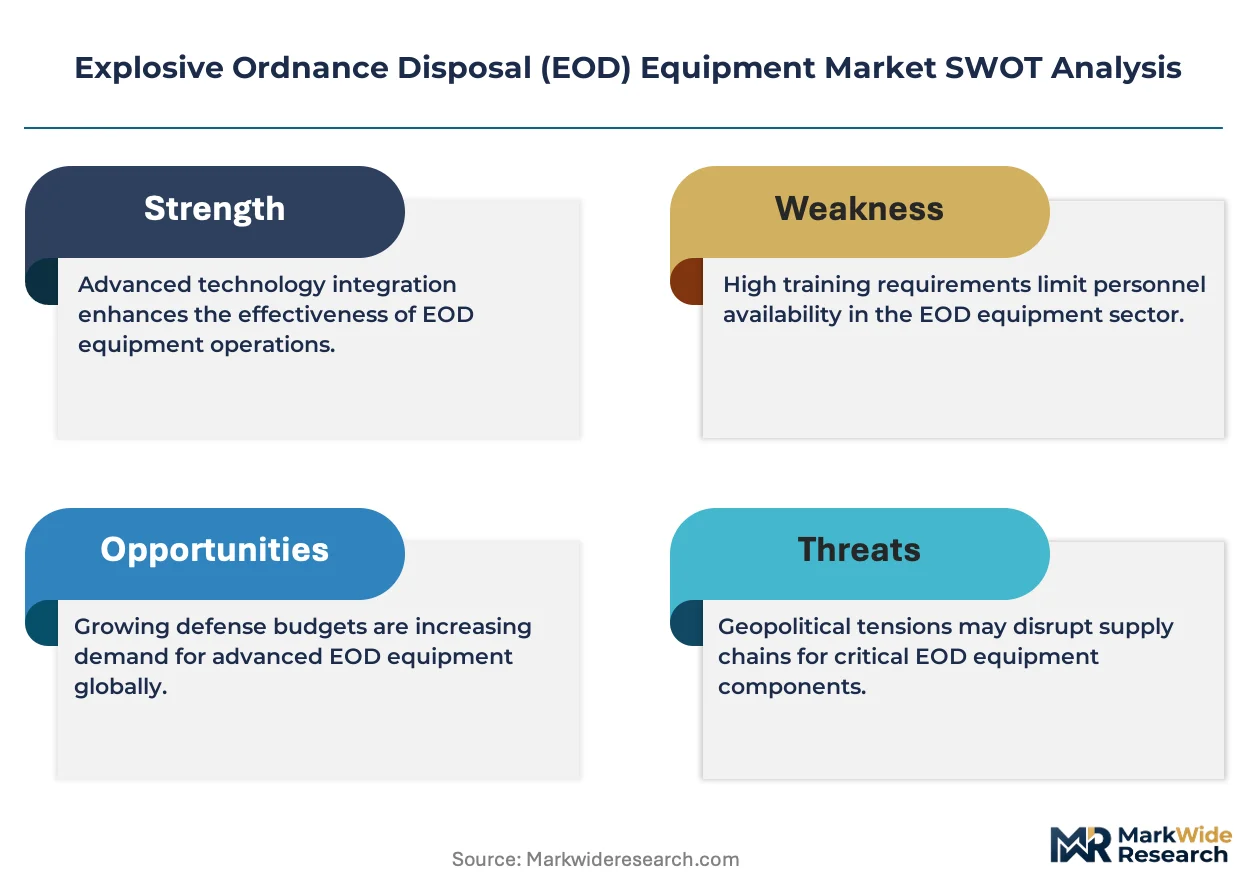
Robotized EOD platforms are compressing procurement cycles as NATO defense agencies accelerate replacement of legacy tethered systems with semi-autonomous ground vehicles, forcing incumbent suppliers to requalify autonomy stacks under tightened environmental testing protocols.
Growth Catalysts
- Counter-IED modernization mandates:NATO STANAG 4569 qualification requirements for armor protection are expanding addressable demand for next-generation bomb disposal suits across allied procurement frameworks.
- Millimeter-wave sensor fusion:Ground-penetrating radar integrated with chemical trace analyzers is elevating detection thresholds for concealed improvised devices in urban clearance operations.
- Subterranean access robotics:Germany and Australia are prioritizing stair-climbing robotic platforms for tunnel and infrastructure inspection, extending operational envelopes beyond legacy flat-terrain systems.
Market Restraints
- Composite armor input concentration:Fragment-rated ceramic plates depend on specialized boron carbide supply chains concentrated among limited advanced ceramics producers.
- MIL-STD-810 qualification compression:U.S. Department of Defense environmental testing timelines are extending vendor onboarding by 18-24 months for new robotic platform entrants.
- High-power microwave disruption alternatives:Directed-energy neutralization tools face substitution pressure from precision water-jet projectors in constrained urban environments.
Strategic Opportunities
- EU AI Act autonomous classification:Risk-tier frameworks for target-recognition algorithms create first-mover advantage for vendors pre-certifying explainable AI decision layers in EOD robotics.
- Civilian airport drone deployment:FAA regulations governing EOD unmanned aerial systems near controlled airspace are opening dual-use procurement channels beyond military end-users.
- RF-shielded tether innovation:Jam-resistant datalink integration with robotic platforms is converging communications and mobility subsystems into bundled procurement specifications.
Industry Challenges
- EOD technician certification pipelines:Render-safe procedure specialists require 24-month training cycles that lag platform deployment schedules, creating operational readiness gaps.
- Legacy system integration friction:Semi-autonomous ground vehicles must interface with existing command-and-control architectures originally designed for fully tethered remote operation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Explosive Ordnance Disposal (EOD) Equipment Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Remote Controlled Vehicles, Bomb Disposal Suits, Detection Equipment, Disruption Tools Technology: Robotic Systems, Sensors, Communication Systems, Imaging Systems End User: Military, Law Enforcement, Civil Defense, Private Security Deployment: On-Site Operations, Training Facilities, Military Bases, Urban Environments |
| Companies Covered | Med-Eng Holdings ULC, Garrett Metal Detectors, L3Harris Technologies, Inc., NABCO Systems LLC, Reamda Ltd., Northrop Grumman Corporation, Cobham Limited, United Shield International Ltd., Teledyne FLIR LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Explosive Ordnance Disposal (EOD) Equipment Market Shifts & Advancements
Multispectral detection architectures and autonomous mobility stacks are redefining operational boundaries between manual render-safe procedures and standoff neutralization, compressing the risk-distance calculus that has governed EOD tactics for decades.
Ground-penetrating radar arrays paired with chemical trace sensors are miniaturizing into backpack-portable detection kits. Bomb disposal units in Australia and Germany are fielding these fused systems for rapid building clearance. The technology is miniaturizing equipment footprints from vehicle-mounted platforms to dismounted operator carry, expanding deployment flexibility in dense urban terrain.
EU AI Act risk classifications for autonomous weapon-recognition algorithms are forcing vendors to document decision-audit trails in next-generation EOD robots. Manufacturers serving European defense procurement must now embed explainability modules alongside target-identification neural networks. This regulatory pressure is accelerating software architecture redesigns ahead of 2025 implementation deadlines.
Defense procurement agencies are consolidating vendor relationships around integrated platform-datalink bundles rather than discrete component sourcing. Traditional suppliers of standalone disruption tools or detection sensors face displacement unless they partner with robotics integrators. The United States and Germany exhibit the most pronounced consolidation, with single-source awards replacing multi-vendor assemblies.
Explosive Ordnance Disposal (EOD) Equipment Market Segmentation
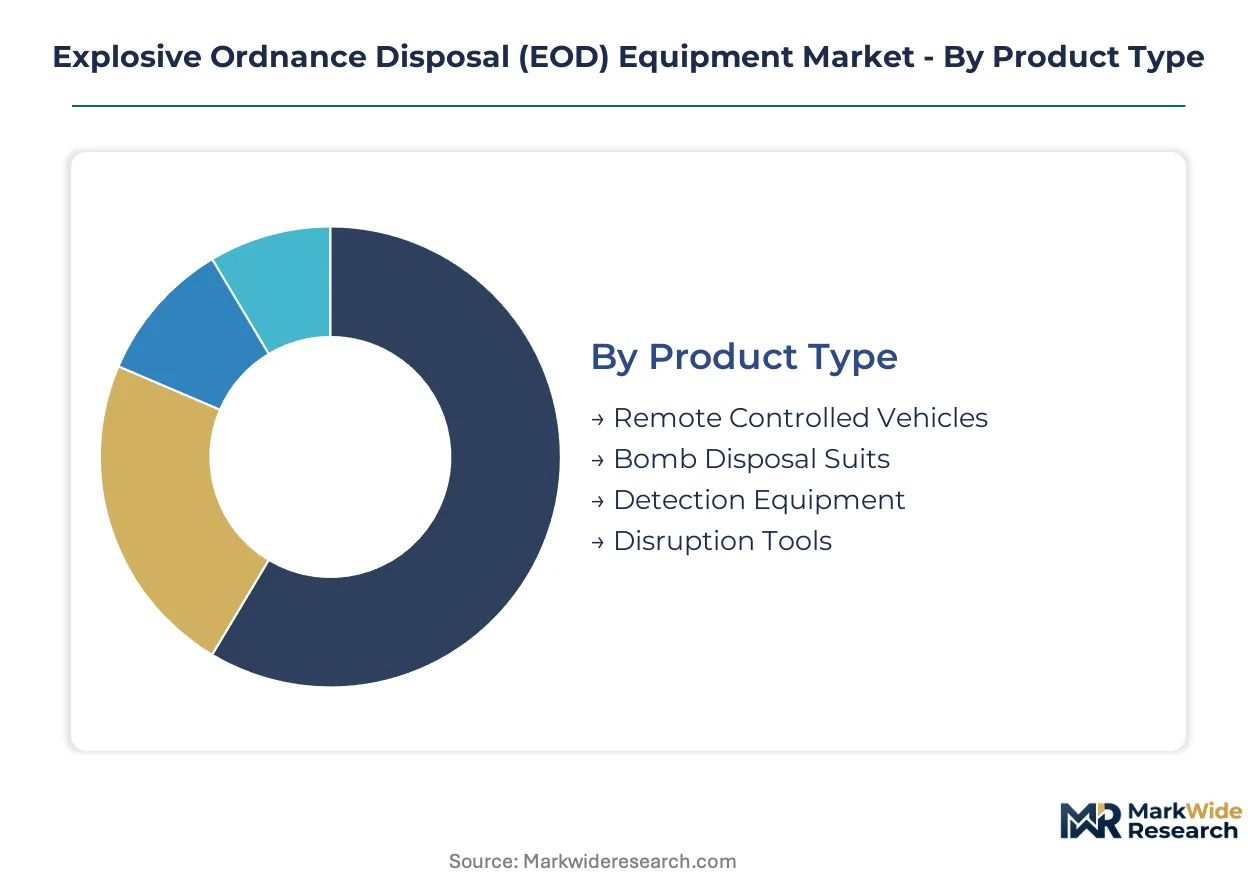
Segmentation in the EOD Equipment Market reveals how procurement specifications diverge across operational contexts. Regulatory frameworks from NATO STANAG to FAA Part 107 reshape technical requirements for each product category, creating distinct competitive arenas with unique qualification barriers.
Product Type:
NATO STANAG 4569 armor ratings and MIL-STD-810 environmental protocols differentiate procurement tiers across product categories, with autonomous platforms facing the most stringent certification demands.
- Remote Controlled Vehicles:Semi-autonomous ground platforms integrate stair-climbing mobility with jam-resistant datalinks. Demand concentrates in Germany and Australia for tunnel infrastructure inspection, driven by defense modernization budgets prioritizing subterranean access capabilities.
- Detection Equipment:Multispectral sensor fusion combines ground-penetrating radar with chemical trace analyzers in backpack-portable configurations. Australian and German bomb disposal units are fielding these systems for rapid urban building clearance, expanding deployment flexibility beyond vehicle-mounted platforms.
- Bomb Disposal Suits:Composite armor plates rated against fragment velocities exceeding 450 meters per second incorporate boron carbide ceramics for operator mobility during manual render-safe procedures.
- Disruption Tools:Water-jet projectors and high-power microwave emitters provide standoff neutralization with limited supplier turnover in this mature product category.
Established volume favors Remote Controlled Vehicles; emerging adoption favors Detection Equipment.
Technology:
Cost stratification separates military-grade hardened systems from commercial-off-the-shelf components, with sensor fusion commanding premium pricing against standalone imaging modules.
- Robotic Systems:Autonomy stacks originally developed for broader defense programs now anchor EOD platform navigation with explainable AI decision layers required under EU AI Act risk classifications.
- Sensors:Millimeter-wave arrays paired with ground-penetrating radar elevate detection thresholds for concealed improvised devices in dense urban terrain clearance operations.
- Communication Systems:RF-shielded tether systems and jam-resistant datalinks bundle with robotic platforms under consolidated procurement specifications from U.S. and German defense agencies.
- Imaging Systems:Thermal and visual spectrum cameras provide remote situational awareness for operator decision-making during standoff procedures.
Procurement consolidation around bundled platform-datalink systems favors Communication Systems; modular retrofit demand favors Sensors.
End User:
Application severity dictates performance tiers, with military operators requiring full STANAG 4569 certification while law enforcement and civilian users operate under relaxed environmental testing protocols.
- Military:NATO member state procurement agencies drive volume through robotized platform orders with compressed replacement cycles for legacy tethered systems.
- Law Enforcement:SWAT and bomb squads in the United States prioritize portable detection kits for rapid deployment in domestic counter-terrorism scenarios.
- Civil Defense:Airport authorities and municipal emergency responders operate under FAA regulations governing drone deployment near controlled airspace.
- Private Security:Critical infrastructure protection contractors source disruption tools and protective ensembles for site-specific threat mitigation.
Defense budget scale favors Military; dual-use civilian-military procurement expansion favors Civil Defense.
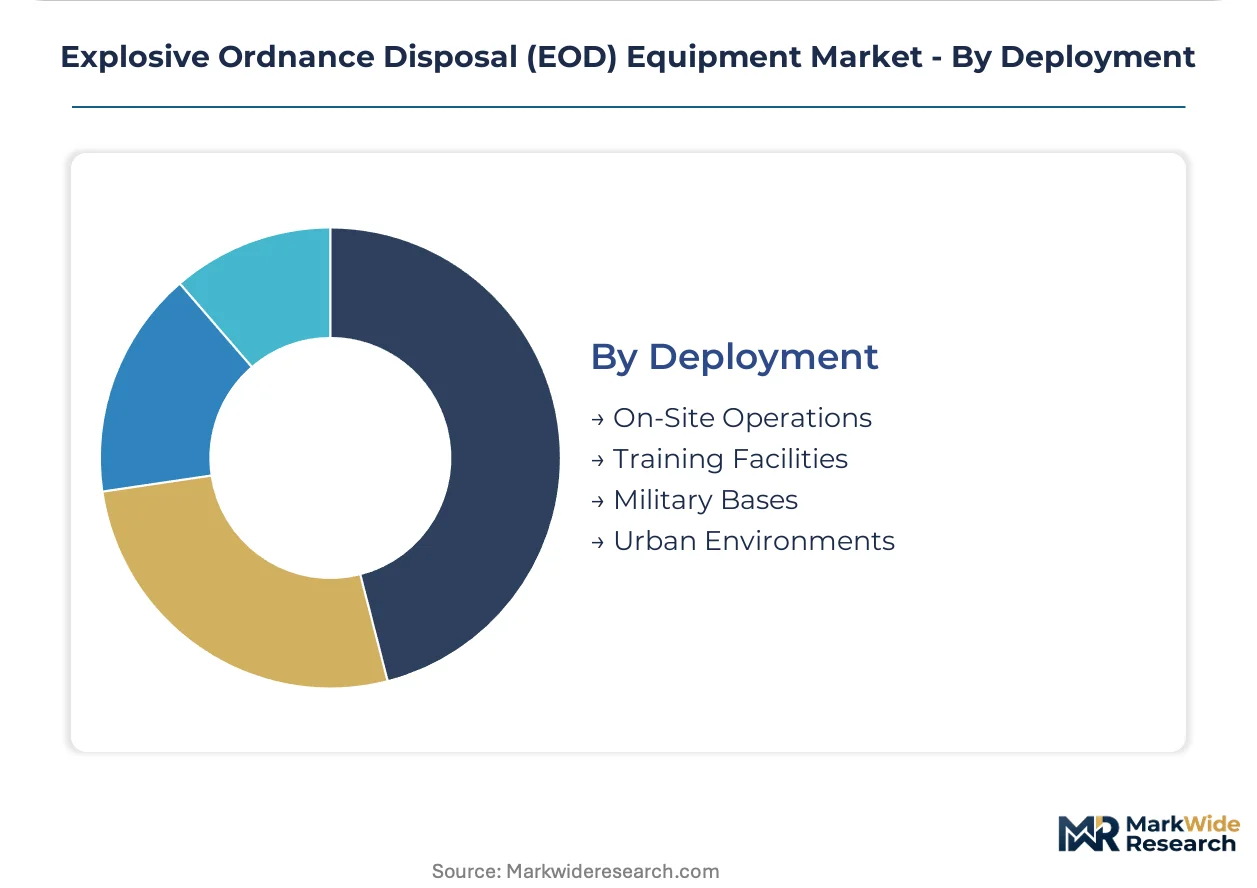
Deployment:
Geographic concentration of operational risk shapes equipment specifications, with urban terrain demanding miniaturized portable systems against fixed-base requirements for hardened infrastructure.
- On-Site Operations:Active threat neutralization in operational theaters requires full-spectrum capability integration from detection through disruption under hostile environmental conditions.
- Training Facilities:Simulation environments replicate render-safe procedures with reduced armor specifications, extending equipment lifecycle through lower-stress utilization patterns.
- Military Bases:Permanent installations maintain dedicated EOD units with comprehensive platform inventories for rapid response to ordnance discoveries.
- Urban Environments:Dense terrain clearance operations in Australia and Germany demand compact, maneuverable systems for building and infrastructure inspection.
Equipment utilization intensity favors On-Site Operations; capability standardization across allied forces favors Military Bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA regulations governing civilian airspace deployment and NATO STANAG harmonization frameworks are redrawing procurement specifications across operational theaters. Defense modernization budgets in specific allied nations are accelerating robotized platform replacement cycles.
United States
MIL-STD-810 environmental testing mandates from the Department of Defense compress vendor qualification timelines for new robotic entrants. The FAA governs EOD drone deployment near controlled airports under Part 107 frameworks. Greater Boston and Washington DC corridors concentrate defense procurement agencies prioritizing counter-IED capabilities.
Germany
Defense agencies prioritize stair-climbing robotic platforms for tunnel infrastructure inspection under expanded modernization allocations. KBA certification requirements intersect with NATO STANAG 4569 armor specifications for cross-border interoperability. Bavaria's defense industrial cluster anchors production of RF-shielded tether systems for remote-controlled vehicles.
Australia
Bomb disposal units field backpack-portable detection kits combining ground-penetrating radar with chemical trace analyzers for urban building clearance. TGA-equivalent defense procurement standards align with allied testing protocols for rapid equipment onboarding. Sydney and Melbourne metropolitan areas concentrate EOD technician training facilities and operational response units.
United Kingdom
Ministry of Defence procurement frameworks emphasize semi-autonomous ground vehicles replacing legacy tethered systems in explosive ordnance operations. UK-specific defense standards incorporate NATO STANAG baselines with additional environmental stress testing. The Midlands defense manufacturing corridor supplies composite armor plates for bomb disposal suits rated against high-velocity fragments.
France
ANSM and defense procurement directorates enforce EU AI Act risk classifications for autonomous target-recognition algorithms in next-generation EOD robots. Île-de-France hosts systems integrators bundling jam-resistant datalinks with robotic platforms under consolidated vendor relationships. French counter-terrorism units demand miniaturized detection equipment for dense urban terrain operations.
Explosive Ordnance Disposal (EOD) Equipment Market Competitive Landscape
Player mix skews toward diversified defense conglomerates with communications and autonomy heritage, compressing entry opportunities for standalone component suppliers. Three archetypes dominate: integrated platform-datalink bundlers, captive RF-shielded subsystem producers, and autonomy stack licensors from broader defense programs. Competitive moves center on strategic partnerships with ceramics suppliers for armor plates and technology licensing for millimeter-wave sensor fusion.
Among North American defense contractors, L3Harris Technologies, Inc. and Northrop Grumman Corporation exemplify the integrated bundling archetype, while Cobham Limited represents the captive RF-shielded subsystem tier. These three occupy positions where communications integration and unmanned ground vehicle autonomy stacks converge under consolidated procurement specifications from U.S. and German defense agencies.
| Leading Market Players |
|---|
| Med-Eng Holdings ULC |
| Garrett Metal Detectors |
| L3Harris Technologies, Inc. |
| NABCO Systems LLC |
| Reamda Ltd. |
| Northrop Grumman Corporation |
| Cobham Limited |
| United Shield International Ltd. |
| Teledyne FLIR LLC |
| Others |
Supply & Pricing Matrix
Eighteen-to-twenty-four-month MIL-STD-810 qualification timelines compress vendor onboarding windows while concentrating pricing power among incumbent robotics integrators with certified autonomy stacks already fielded under NATO procurement frameworks.
Pricing Analysis
Certification level under NATO STANAG 4569 and MIL-STD-810 creates the primary spread between premium autonomous platforms and standard tethered systems. Three-tier pricing structure across expeditionary-grade, field-hardened, and training-configured equipment reflects armor rating and environmental resilience differentiation. Cost compression in training-configured tiers intensifies as simulation-based procurement displaces full-specification orders for non-deployed units. Military procurement agencies exhibit lowest price sensitivity given mission-critical operational requirements, while civil defense and private security buyers demonstrate higher elasticity to unit cost.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port corridors affect boron carbide ceramic plate delivery schedules from European advanced ceramics producers. Component supply concentrates in Germany for RF-shielded tether systems, the United States for autonomy stack processors, and Japan for millimeter-wave sensor arrays. Production draws from specialized boron carbide feedstock vulnerable to single-source concentration among limited advanced ceramics manufacturers. Distribution runs through defense procurement agency direct contracts with integrated platform-datalink bundlers rather than component-tier distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EOD equipment demand sits in early-cycle expansion as NATO member states accelerate legacy system replacement with semi-autonomous platforms, creating sustained procurement velocity through compressed replacement cycles.
For Market Incumbents: Fortify captive supply positions in boron carbide ceramics through backward integration or long-term offtake agreements with German and Japanese advanced materials producers. Deepen autonomy stack certification under EU AI Act risk-tier frameworks to preempt regulatory displacement of opaque neural network architectures. Priority lever rests on embedding explainable AI decision-audit modules ahead of competitor qualification cycles.
For New Entrants and Emerging Players: Lead with modular sensor fusion subsystems for retrofit integration into existing robotic platforms rather than competing for integrated vehicle awards. Most penetrable white-space sits in backpack-portable detection kits for law enforcement and civil defense segments underserved by military-focused incumbents. Go-to-market angle should emphasize FAA Part 107 compliance for airport authority drone deployment channels beyond traditional defense procurement.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified defense conglomerates with underutilized EOD-specific autonomy stacks developed for broader unmanned ground vehicle programs. Five-to-ten-year viability hinges on regulatory pre-certification moats rather than hardware differentiation alone. Signal to watch is EU AI Act enforcement patterns against non-explainable target-recognition algorithms in robotics deployments.
| Strategic Initiative | Industry Significance |
|---|---|
| Autonomy Stack Certification | EU AI Act pre-certification creates regulatory moats against non-compliant competitors in European defense procurement. |
| RF-Shielded Tether Integration | Bundled platform-datalink specifications from U.S. and German agencies favor integrated communications-mobility vendors. |
| Subterranean Access Robotics | German and Australian tunnel inspection priorities extend operational envelopes beyond legacy flat-terrain systems. |
| Multispectral Sensor Fusion | Ground-penetrating radar with chemical trace analyzers elevates detection thresholds for urban clearance operations. |
| Civilian Airport Drone Deployment | FAA Part 107 compliance opens dual-use procurement channels beyond military end-users for EOD unmanned systems. |
Research Methodology
Desk research of NATO STANAG technical documentation, defense procurement agency award databases, and MIL-STD-810 environmental test protocols preceded structured interviews with EOD program managers at allied defense ministries, robotics integration engineers, advanced ceramics procurement leads, and autonomy software architects. Primary fieldwork combined with secondary validation through customs trade data for boron carbide and RF component flows, SEC 10-K filings from listed defense contractors, and EU regulatory implementation guidance. Bottom-up platform deployment estimates and top-down defense budget allocation analysis were triangulated for cross-verification.
Variance decomposition across product type, technology tier, end-user severity, and deployment geography segments drove analytical framework construction over the projection horizon. CAGRs were derived from modeled replacement cycle compression, procurement budget trajectories, and technology adoption S-curves for autonomous versus tethered platforms. Industry-specific forecast inputs incorporated NATO STANAG 4569 armor rating tier migrations and EU AI Act implementation compliance timelines for robotics vendors.
The analysis sits within stated boundaries; outcomes outside sustained NATO defense modernization commitments or accelerated EU AI Act enforcement would require recalibration. Forecasts reflect documented assumptions regarding qualification timeline stability and boron carbide supply chain continuity. Practitioners should keep alternative scenarios live as regulatory enforcement patterns and allied defense budget prioritization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Military Helmet and Helmet Mounted Displays Market
Defense and Military Systems and Equipment
Smart War Weapon Market
Defense and Military Systems and Equipment
Military Phased Array Antenna Market
Defense and Military Systems and Equipment
Global Military Laser Designator Market
Defense and Military Systems and Equipment
United Kingdom Defense Market
Defense and Military Systems and Equipment
Military Exoskeleton Market
Defense and Military Systems and Equipment
Military Embedded System Software Market
Defense and Military Systems and Equipment
Global Battlefield Management System Market
Defense and Military Systems and Equipment
Command and Control Systems Market
Defense and Military Systems and Equipment
Global Military Defense Vehicle Intercom System Market
Defense and Military Systems and Equipment
Soldier System Market
Defense and Military Systems and Equipment
Search and Rescue Equipment Market
Defense and Military Systems and Equipment
Saudi Arabia Defense Market
Defense and Military Systems and Equipment
Defense Integrated Antenna Market
Defense and Military Systems and Equipment
Cognitive Electronic Warfare System Market
Defense and Military Systems and Equipment
Mechanical and Electronic Fuzes Market