
 Search and Rescue Equipment Market | 2026-2036
Search and Rescue Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Search and Rescue Equipment Market Outlook
Multi-source procurement for avionics and beacon subsystems is pivoting toward dual-vendor strategies across NATO-aligned defense ministries. Textron Systems leverages its vertical integration into airframe-integrated rescue kits to sustain long-term service contracts. Garmin Ltd. anchors the consumer and professional GPS device layer with dense channel control in North American outdoor retail. Thales Group competes on encrypted communication modules that dominate military specification tenders.
Search and rescue equipment encompasses purpose-built systems engineered for personnel location, extraction, and survival support under hazardous conditions, typically integrating 406 MHz distress signaling, GPS positioning accuracy within three meters, and materials rated for saltwater corrosion and thermal extremes. Its primary commercial purpose is to reduce mortality and operational risk across maritime, alpine, and combat environments where conventional infrastructure fails. Rescue tools and thermal imaging command the deepest margin pools due to specialized manufacturing and sensor fusion complexity, while drone-based platforms represent the fastest-expanding technology segment as swarm coordination and AI-enabled search patterns mature. Emergency services and military end users absorb the majority of volume, though recreational demand for personal locator beacons is broadening the customer base.
The U.S. FAA mandates emergency locator transmitter standards under 14 CFR Part 91, while the EU's CE marking and EASA certification frameworks govern market access for beacon and aviation rescue equipment sold across Europe. Japan's METI enforces JIS standards for marine safety devices, creating a fragmented compliance landscape that favors manufacturers with multi-certification testing capabilities. Stakeholders must monitor evolving spectrum allocation rules for 406 MHz satellite distress signaling and prepare for interoperability requirements linking national responder networks.
Market Dynamics
Military procurement budgets are expanding adoption of integrated rescue systems, while the U.S. FAA mandates for emergency locator transmitters are tightening certification requirements and compressing product development cycles.
Growth Catalysts
- 406 MHz Satellite Distress Signaling:International Cospas-Sarsat mandates are driving replacement cycles for legacy 121.5 MHz beacons across maritime and aviation fleets.
- Japan's METI JIS Standards:Enforcement of marine safety device regulations is accelerating fleet modernization in the Pacific Rim commercial fishing sector.
- Thermal Imaging Sensor Fusion:Integration of multi-spectral imaging with drone platforms is expanding search coverage in alpine and wilderness rescue operations.
Market Restraints
- Rare Earth Magnet Supply Concentration:Neodymium dependency on Chinese processing capacity creates vulnerability in precision GPS antenna manufacturing.
- Multi-Certification Testing Costs:Fragmented compliance across FAA, EASA, and METI frameworks extends time-to-market for new beacon designs.
- Battery Chemistry Limitations:Lithium-thionyl chloride cell performance degradation in thermal extremes constrains operational reliability in arctic deployments.
Strategic Opportunities
- AI-Enabled Swarm Coordination:Machine learning algorithms for autonomous drone search pattern optimization remain underdeployed in civilian emergency services.
- India's PLI Scheme for Electronics:Production-linked incentives for domestic manufacturing create localized assembly opportunities for personal locator beacons.
- Subscription-Based Fleet Monitoring:SaaS models for real-time asset tracking and maintenance alerts are penetrating commercial maritime operators.
Industry Challenges
- RF Engineer Talent Scarcity:Specialized expertise in 406 MHz antenna design and satellite uplink protocols commands premium compensation and extends hiring timelines.
- Legacy System Integration Complexity:Retrofitting encrypted communication modules into aging military rescue platforms requires custom firmware development and extended field testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Search and Rescue Equipment Market |
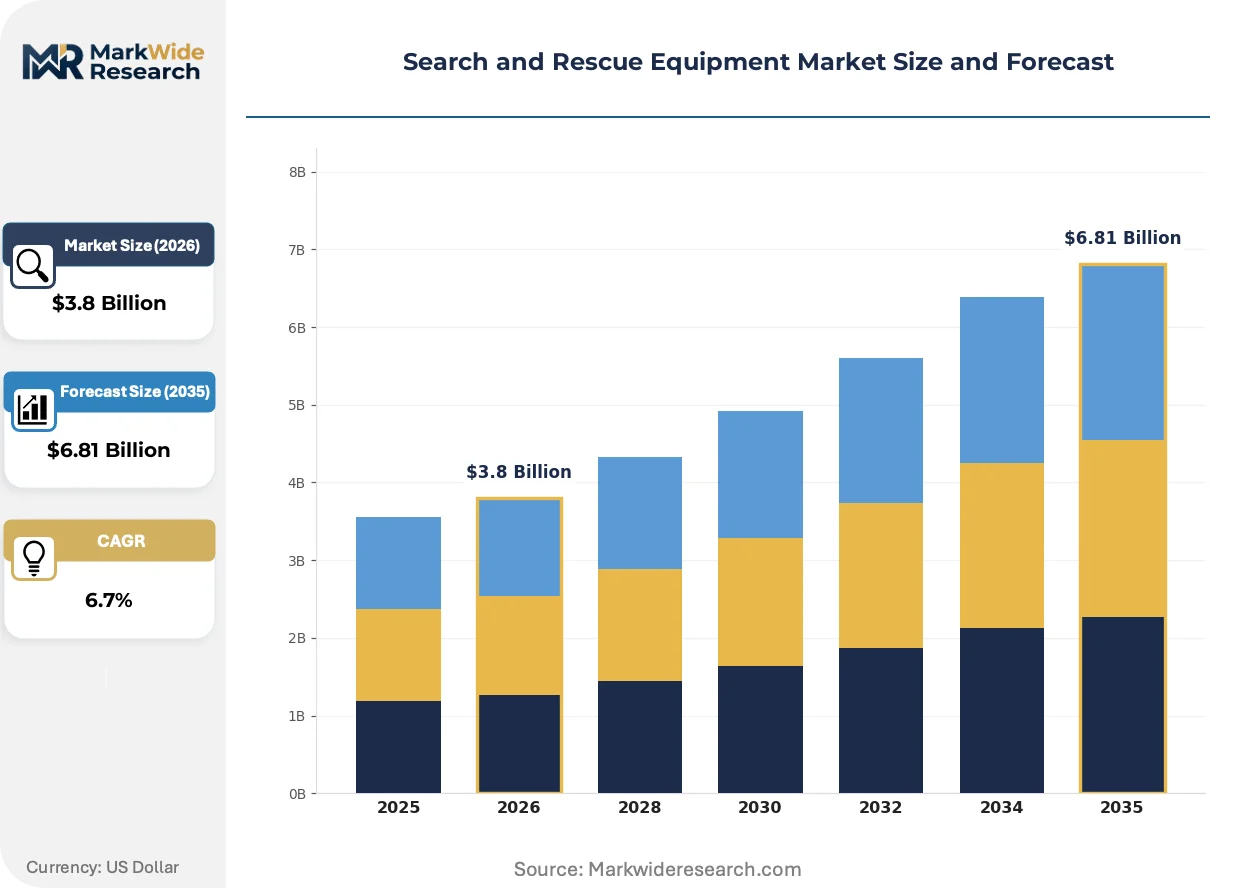
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
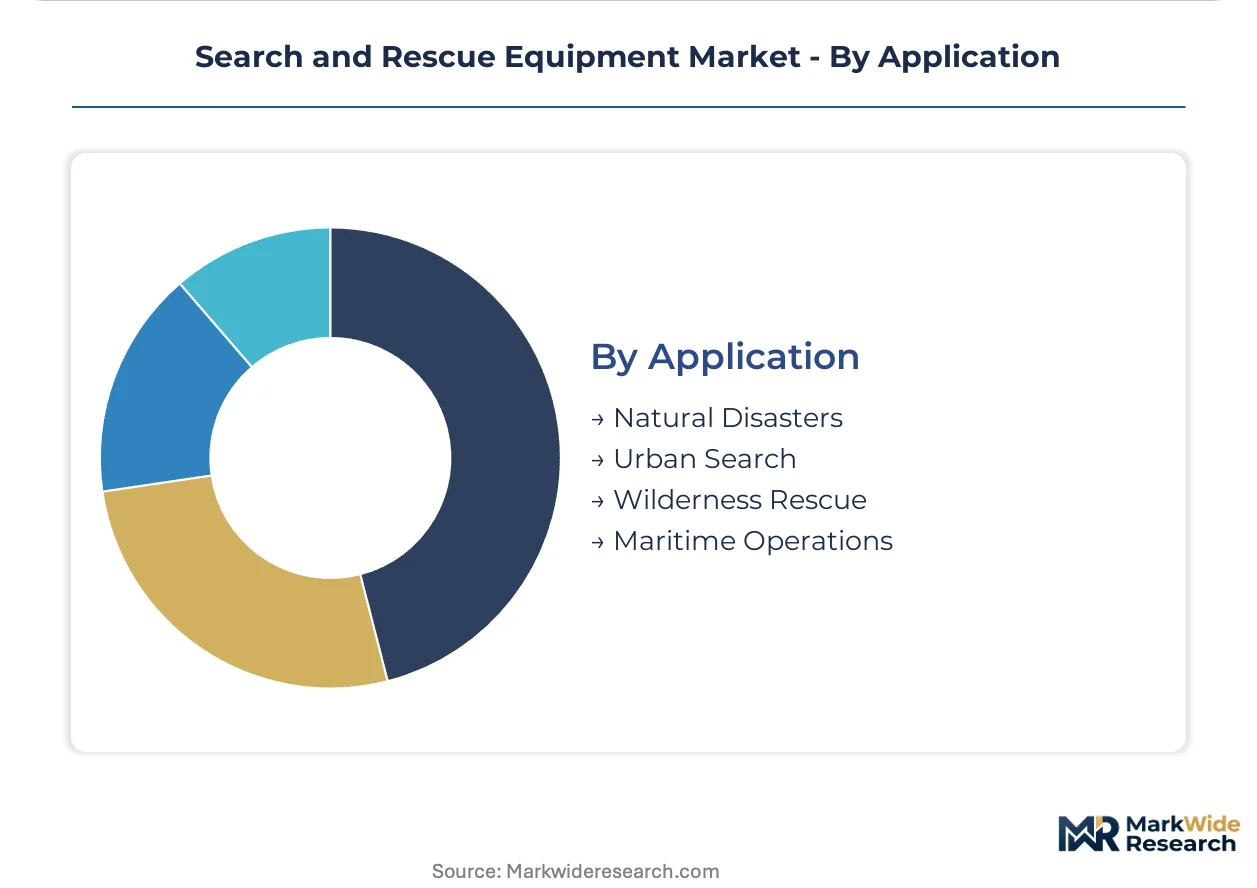
| Segmentation | Product Type: Rescue Tools, Life Jackets, First Aid Kits, Ropes Technology: GPS Devices, Drones, Communication Equipment, Thermal Imaging End User: Emergency Services, Military, NGOs, Recreational Application: Natural Disasters, Urban Search, Wilderness Rescue, Maritime Operations |
| Companies Covered | Textron Systems, Garmin Ltd., Leonardo S.P.A., Cubic Corporation, Elbit Systems Ltd., Thales Group, General Dynamics Corporation, ACR Electronics, Inc., Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Search and Rescue Equipment Market Strategic Shifts
Drone-based platforms are overtaking traditional manned aircraft for initial search phases, while regulatory mandates for 406 MHz signaling are accelerating hardware replacement cycles across maritime and aviation sectors.
Autonomous drone swarms equipped with thermal imaging and AI-enabled object recognition are overtaking single-rotor helicopter deployments for wilderness search operations. Alpine rescue services in Switzerland and Austria are adopting coordinated multi-unit systems that reduce search area coverage time by enabling parallel pattern execution. The structural consequence is compression in the manned aviation support contract market as agencies reallocate operating budgets toward unmanned platform procurement and operator training programs.
EASA certification frameworks for aviation rescue equipment are tightening electromagnetic interference standards and mandating redundant distress signaling pathways. European manufacturers must now demonstrate simultaneous 406 MHz satellite and VHF homing beacon functionality to obtain airworthiness approval. Commercial helicopter operators in Germany and France are responding by accelerating fleet-wide ELT upgrades ahead of mandatory compliance deadlines.
Dual-vendor sourcing strategies are displacing sole-source relationships for avionics and beacon subsystems across NATO-aligned defense ministries. Military procurement offices are fragmenting large integrated rescue kit contracts into separable satellite communication, positioning, and survival equipment lots. This pattern is most visible in United States and United Kingdom tenders, where evaluators now weight supply chain resilience and second-source qualification status alongside unit cost and technical performance metrics.
Search and Rescue Equipment Market Segmentation
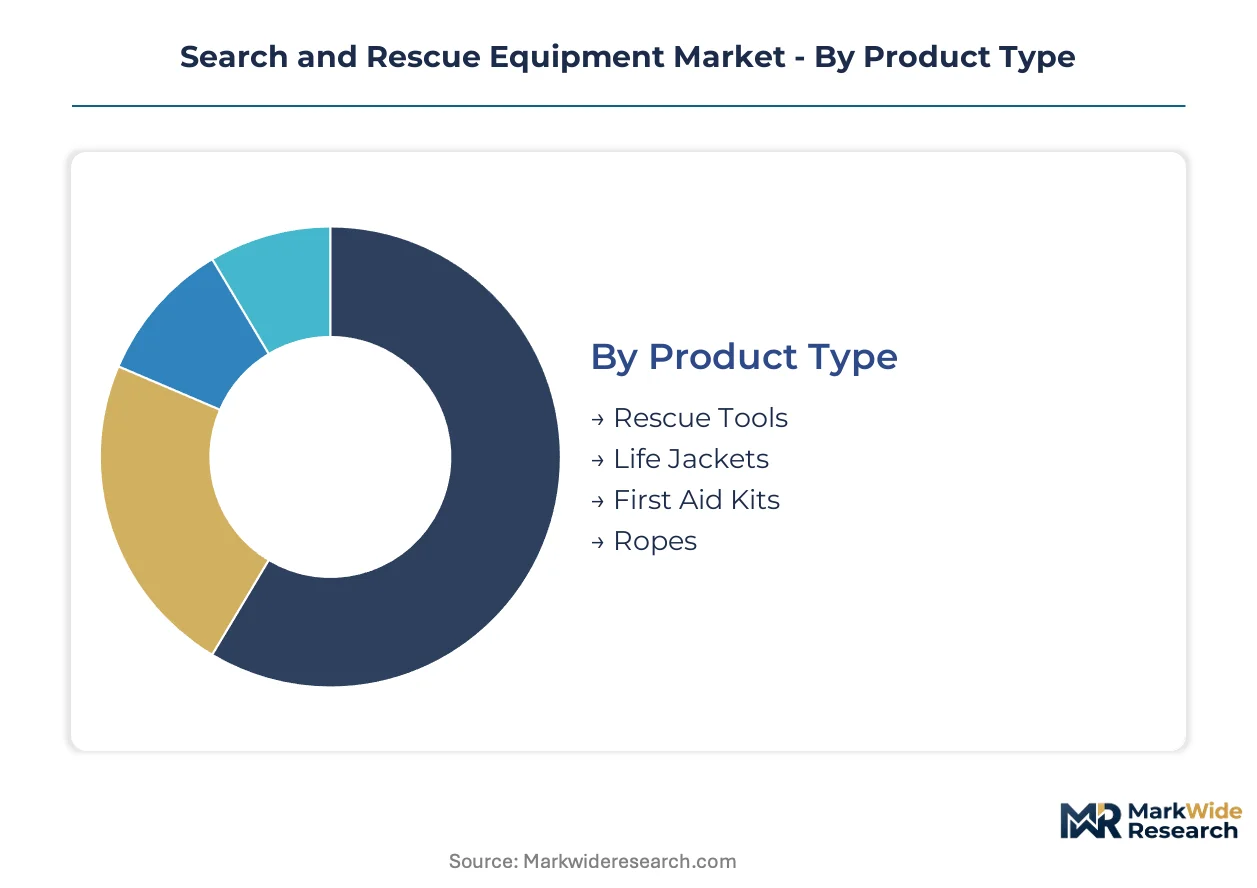
Equipment specifications diverge sharply across rescue scenarios, from saltwater corrosion ratings for maritime beacons to thermal envelope requirements for alpine GPS units. Manufacturers configure product lines around frequency bands, battery chemistries, and payload capacities rather than pursuing universal platforms.
Product Type:
Material science and mechanical engineering specifications define competitive positioning within physical rescue equipment.
- Rescue Tools:Hydraulic spreaders and cutters built from high-strength aluminum alloys dominate vehicle extrication scenarios. German fire departments and Japanese urban search teams are standardizing on battery-powered units to eliminate hydraulic line hazards in collapsed structures.
- Life Jackets:Inflatable personal flotation devices with automatic hydrostatic activation mechanisms command premium positioning. Commercial fishing fleets operating under Japan's METI enforcement are replacing legacy foam designs with compact stowable units.
- First Aid Kits:Modular trauma systems configured for hemorrhage control and hypothermia management.
- Ropes:Static kernmantle constructions rated for rescue loads and dynamic elongation limits.
Mature deployment sits with Rescue Tools. Newer deployment is concentrated in Life Jackets.
Technology:
Signal processing capabilities and sensor fusion complexity separate price tiers within electronic rescue systems.
- GPS Devices:Multi-constellation receivers combining GPS, GLONASS, and Galileo signals achieve sub-three-meter accuracy in canyon and canopy environments. Recreational demand from North American backcountry users is broadening the customer base beyond professional responders.
- Thermal Imaging:Uncooled vanadium oxide microbolometer arrays integrated with drone gimbals enable night operations without active illumination. Alpine rescue services in Switzerland and Austria are adopting these for wilderness search coverage.
- Drones:Multi-rotor platforms with swappable payload bays for cameras, loudspeakers, and supply drops.
- Communication Equipment:Satellite messengers and VHF transceivers with 406 MHz distress uplink capability.
Established volume centers on GPS Devices. Thermal Imaging is climbing the fastest as sensor costs decline and drone integration matures.
End User:
Procurement authority and budget cycles shape equipment specification requirements across customer categories.
- Emergency Services:Municipal fire and ambulance departments with standardized equipment protocols and collective purchasing agreements.
- Military:Integrated rescue kits combining beacons, survival radios, and airframe-integrated ELTs with encrypted communication modules.
- NGOs:Humanitarian organizations operating in infrastructure-degraded environments with emphasis on portability and multi-fuel compatibility.
- Recreational:Individual consumers purchasing personal locator beacons and satellite messengers through outdoor retail channels.
Institutional procurement dominates Emergency Services. Recreational purchasing is gaining share fastest as device miniaturization reduces cost barriers.
Application:
Environmental stress factors determine equipment durability specifications and deployment logistics.
- Maritime Operations:Equipment rated for continuous saltwater exposure, submersion pressure, and flotation stability. Commercial shipping operators and coastal rescue services drive specification requirements.
- Wilderness Rescue:Lightweight systems optimized for helicopter sling load compatibility and extended battery life in temperature extremes.
- Natural Disasters:Rapidly deployable kits for collapsed structure search, flood response, and mass casualty triage.
- Urban Search:Confined space entry tools with explosion-proof ratings and seismic stability monitoring.
Operational maturity rests with Maritime Operations. Natural Disasters represents the steepest expansion trajectory as climate-driven event frequency elevates preparedness budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth magnet processing in China's Jiangxi Province supplies critical neodymium for precision GPS antenna manufacturing, creating geographic dependencies that shape procurement strategies across defense ministries and commercial operators worldwide.
United States
Defense procurement budgets at the Department of Defense are accelerating integrated rescue kit deployments across naval and air force platforms. FAA mandates under 14 CFR Part 91 are compressing ELT certification timelines for commercial aviation operators. Textron Systems maintains vertical integration into airframe-integrated rescue systems from its Providence, Rhode Island headquarters, securing multi-year service contracts.
Germany
EASA certification frameworks are tightening electromagnetic interference standards for helicopter emergency equipment, forcing fleet-wide upgrades among commercial operators. The country's national aviation regulator enforces redundant distress signaling pathways for airworthiness approval. Thales Group competes on encrypted communication modules from its Ditzingen facility, dominating NATO military specification tenders.
Japan
METI enforcement of JIS standards for marine safety devices is accelerating fleet modernization in the Pacific Rim commercial fishing sector. Domestic manufacturers face compressed development cycles as certification requirements tighten for 406 MHz beacon interoperability. Alpine rescue services in Nagano Prefecture are adopting thermal imaging drone platforms for wilderness search coverage.
United Kingdom
Dual-vendor sourcing strategies are displacing sole-source relationships for avionics and beacon subsystems across Ministry of Defence procurement offices. Military tenders now weight supply chain resilience alongside technical performance metrics. Leonardo S.P.A. positions on integrated rescue systems through its UK subsidiary, competing for fragmented contract lots.
Switzerland
Alpine rescue services in the cantons of Valais and Graubünden are deploying autonomous drone swarms with AI-enabled search pattern optimization. Swissmedic certification requirements for emergency medical equipment are creating compliance barriers for imported devices. Garmin Ltd. anchors consumer GPS device distribution through dense channel control in outdoor retail clusters across Zurich and Geneva.
Search and Rescue Equipment Market Competitive Environment
Dual-vendor sourcing dominates the current landscape as NATO-aligned defense ministries fragment large integrated rescue kit contracts into separable lots. The vendor base organizes around three strategic archetypes: defense primes with airframe integration capabilities, sensor specialists competing on encrypted communication and thermal imaging, and consumer-facing manufacturers controlling GPS device distribution. M&A activity and geographic expansion represent the dominant competitive moves as firms seek multi-certification testing capabilities across FAA, EASA, and METI frameworks.
Among defense-integrated primes, Textron Systems and General Dynamics Corporation exemplify the airframe-anchored archetype with captive supply chain control over rescue kit assembly. Garmin Ltd. occupies the consumer-professional boundary, leveraging dense North American retail channel control to broaden personal locator beacon penetration beyond institutional buyers. Thales Group sits within the encrypted systems tier, competing on military specification tenders where dual-vendor qualification status determines contract eligibility.
| Leading Market Players |
|---|
| Textron Systems |
| Garmin Ltd. |
| Leonardo S.P.A. |
| Cubic Corporation |
| Elbit Systems Ltd. |
| Thales Group |
| General Dynamics Corporation |
| ACR Electronics, Inc. |
| Honeywell International Inc. |
| Others |
Value Chain & Pricing Dynamics
Neodymium processing costs in China's Jiangxi Province cascade downstream through GPS antenna manufacturing tiers, with raw magnet pricing volatility compressing margins at precision component suppliers serving both military beacon integrators and consumer device assemblers.
Pricing Analysis
Extended warranty and field service bundling separate premium rescue kit vendors from unbundled equipment suppliers. Three-tier pricing structure across certified-military, commercial-aviation, and recreational-consumer levels reflects FAA, EASA, and CE marking compliance tiers. Cost compression in consumer GPS devices intensifies as Garmin's channel density forces margin concessions from smaller outdoor retail competitors. Emergency services procurement teams exhibit highest price sensitivity due to municipal budget constraints, while defense ministries prioritize dual-source qualification over unit cost.
Supply Chain Analysis
India's PLI scheme for electronics manufacturing is reshaping sourcing patterns for personal locator beacon assembly, pressuring incumbent suppliers to establish localized production. Neodymium magnet processing centers on China, with secondary refining capacity in Vietnam and Malaysia. Lithium-thionyl chloride cells, ceramic antenna substrates, and precision-machined aluminum housings feed from East Asian chemical and materials suppliers. Single-source vulnerability in rare earth magnet supply creates procurement risk for precision GPS antenna manufacturers. Distribution runs through defense prime integrators, commercial aviation OEMs, and outdoor retail channel networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drone-based thermal imaging platforms are displacing manned helicopter contracts across alpine and wilderness rescue services, compressing traditional aviation support markets while expanding sensor fusion and AI software opportunities.
For Market Incumbents: Hedge against drone platform commoditization by deepening encrypted communication module R&D and securing airframe-integrated ELT service contracts with military operators. Textron's captive supply chain model offers defensive positioning against component cost volatility. Dual-vendor qualification status remains the critical lever for NATO defense procurement eligibility.
For New Entrants and Emerging Players: Enter via India's PLI-subsidized manufacturing corridors to bypass established supplier relationships in North American and European markets. Recreational personal locator beacons present the most penetrable segment given Garmin's channel concentration gaps in Southeast Asian outdoor retail. SaaS-enabled fleet monitoring for commercial maritime operators offers recurring revenue positioning distinct from transactional hardware sales.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier thermal imaging sensor specialists with drone platform integration capabilities in Switzerland and Austria. The five-to-ten year viability window favors vendors with multi-certification testing infrastructure spanning FAA, EASA, and METI frameworks. Watch for 406 MHz beacon replacement cycle acceleration as Cospas-Sarsat enforcement deadlines approach.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Certification Testing Infrastructure Buildout | EASA, FAA, and METI compliance capabilities unlock defense and commercial aviation contract eligibility. |
| AI-Enabled Search Pattern Software Development | Machine learning algorithms for drone swarm coordination address underdeployed civilian emergency services demand. |
| Localized Assembly Partnership in India | PLI scheme subsidies reduce landed cost for personal locator beacons targeting South Asian recreational markets. |
| Encrypted Communication Module R&D Expansion | Military specification tenders from NATO defense ministries prioritize Thales-class encryption standards. |
| Subscription Fleet Monitoring Platform Launch | SaaS models penetrate commercial maritime operators seeking real-time ELT maintenance alerts. |
Study Parameters
Document review covered defense procurement databases, FAA certification filings, and EASA airworthiness directives, complemented by interviews with search and rescue equipment program managers at NATO defense ministries, commercial helicopter operator procurement leads, alpine rescue service coordinators, and outdoor retail channel buyers. Secondary validation drew from Cospas-Sarsat beacon registration data, METI marine safety enforcement records, and customs trade statistics for rare earth magnet flows. Bottom-up equipment shipment analysis and top-down defense budget allocation triangulation anchored market sizing.
Historical replacement cycle patterns for 121.5 MHz to 406 MHz beacon upgrades were cross-referenced against expert panel input on regulatory enforcement timelines. Segmentation modeling spanned product type, technology tier, end-user procurement authority, and application environment across the projection horizon. CAGRs were derived from equipment volume forecasts calibrated to military modernization budgets and commercial fleet upgrade schedules. Thermal imaging sensor cost curves and drone platform adoption rates informed technology segment projections.
Forecast precision tightens around the base case; tail outcomes carry wider variance under battery chemistry breakthrough scenarios or sudden rare earth export restrictions. Projections reflect assumptions on regulatory compliance deadline adherence and defense procurement continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Military Laser Systems Market
Defense and Military Systems and Equipment
Airborne Electronic Warfare Market
Defense and Military Systems and Equipment
Anti-Drone Guns Market
Defense and Military Systems and Equipment
Explosive Ordnance Disposal (EOD) Equipment Market
Defense and Military Systems and Equipment
Battle Management System (BMS) Market
Defense and Military Systems and Equipment
Bio-Defense Market
Defense and Military Systems and Equipment
Military Actuators Market
Defense and Military Systems and Equipment
Military High Altitude Radio Jamming System Market
Defense and Military Systems and Equipment
Military Load Carriage System Market
Defense and Military Systems and Equipment
Global Military Laser Rangefinder Market
Defense and Military Systems and Equipment
Military Rifle Market
Defense and Military Systems and Equipment
India Defense Market
Defense and Military Systems and Equipment
Military Exoskeleton Market
Defense and Military Systems and Equipment
Military Embedded System Software Market
Defense and Military Systems and Equipment
Mission Management System Market
Defense and Military Systems and Equipment
Military Embedded System Market