
 Middle East and Africa Defense Market | 2026-2036
Middle East and Africa Defense Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Defense Market Foresight
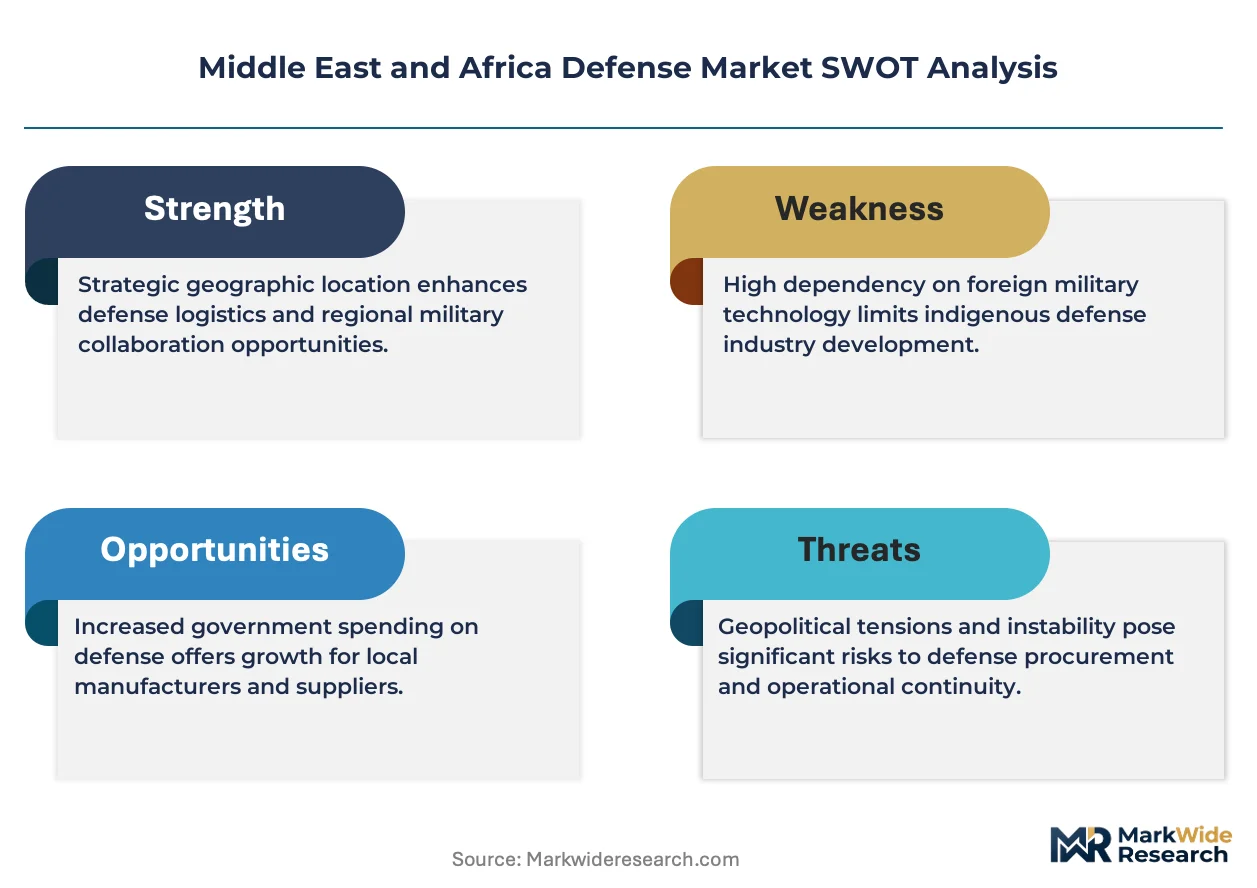
NATO STANAG qualification is bifurcating the supplier landscape across the Middle East and Africa Defense market, separating platforms certified for coalition interoperability from nationally sovereign systems. Elbit Systems leverages its STANAG-compliant portfolio to sustain long-term contracts with NATO-aligned African peacekeeping forces. Baykar competes through vertically integrated drone manufacturing that anchors Turkish export dominance in the region. Aselsan differentiates via indigenous electronic warfare subsystems that reduce foreign dependency for critical NATO periphery states.
The Middle East and Africa Defense sector encompasses the research, development, production, and sustainment of military platforms, subsystems, and services designed for state-level security operations across land, air, sea, and cyber domains. Systems typically integrate hardened communications architectures, thermal management for desert operating conditions, and sovereign data sovereignty protocols to function in contested electromagnetic environments. Armored vehicles and naval systems occupy the mature core where replacement cycles and platform life extension programs concentrate procurement budgets. Drones represent the fastest-expanding product category as asymmetric warfare requirements and border surveillance missions multiply across the Sahel and Arabian Peninsula. Cybersecurity technology commands premium pricing due to capability scarcity and the imperative to protect command-and-control networks from state-sponsored intrusion.
Saudi Arabia's General Authority for Military Industries (GAMI) and the UAE's Tawazun Council are enforcing localization mandates that redirect foreign OEM revenue shares into domestic joint ventures and workforce development. Israel's Ministry of Defense and South Africa's Armaments Corporation (Armscor) maintain parallel certification regimes that shape regional alliance structures and technology access tiers. Stakeholders must monitor how GAMI's offset requirements and Tawazun's venture capital mechanisms reshape partnership terms for foreign primes seeking long-term platform positions.
Market Dynamics
Sovereign wealth capital injection into domestic manufacturing bases is compressing traditional foreign OEM revenue models across the Middle East and Africa Defense market. Saudi Arabia's GAMI localization mandates and the UAE's Tawazun venture mechanisms are forcing primes to surrender equity stakes and technology access in exchange for contract eligibility.
Growth Catalysts
- Asymmetric warfare requirements:Border surveillance missions across the Sahel and Arabian Peninsula are multiplying demand for unmanned aerial platforms with extended endurance.
- GAMI offset enforcement:Saudi Arabia's General Authority for Military Industries redirects foreign contractor revenue into domestic joint ventures and workforce development programs.
- Thermal management innovation:Hardened communications architectures designed for desert operating conditions are opening procurement windows for subsystem specialists.
Market Restraints
- Technology transfer friction:Israel's Ministry of Defense procurement reforms impose accelerating technology transfer requirements that foreign primes resist.
- Input cost volatility:Rare earth magnet supply concentration in East Asian processing facilities creates pricing instability for precision-guided munition actuators.
- Certification fragmentation:Parallel NATO STANAG, Israeli MoD, and South African Armscor regimes force redundant qualification spending on single platforms.
Strategic Opportunities
- Cybersecurity capability scarcity:Premium pricing for command-and-control network protection creates margin expansion for indigenous security architecture developers.
- Drone manufacturing localization:Turkey's vertically integrated production model offers template for UAE and Saudi captive supply development.
- Electronic warfare subsystem demand:NATO periphery states seek indigenous EW capabilities to reduce foreign dependency, opening slots for subsystem specialists.
Industry Challenges
- Electromagnetic spectrum integration:Hardened communications architectures must interoperate with legacy Soviet-era platforms still fielded across North African forces.
- Skilled technician pipelines:Domestic joint ventures face shortages of avionics and precision machining specialists needed for sovereign maintenance capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Defense Market |
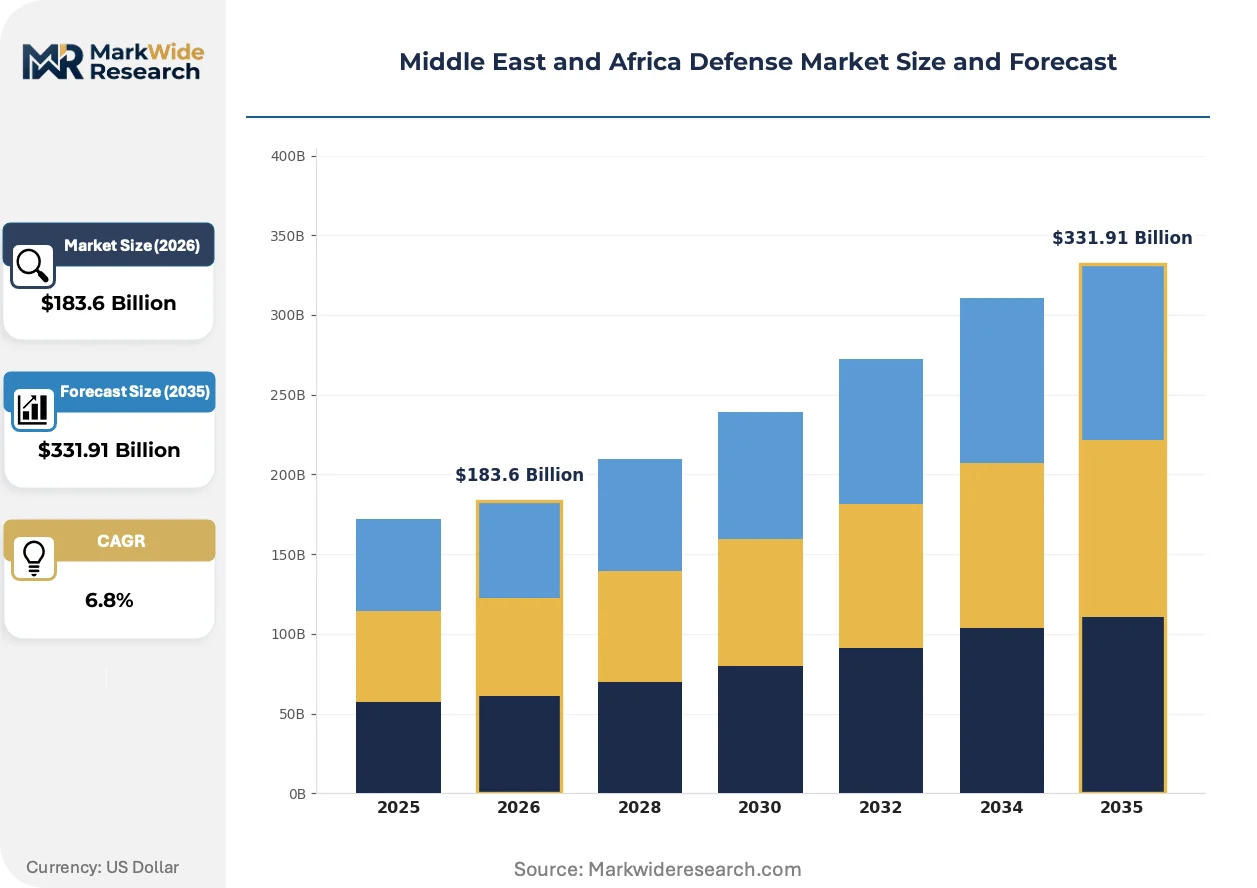
| Market Size in 2026 | $183.6 Billion |
| Market Size in 2035 | $331.91 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
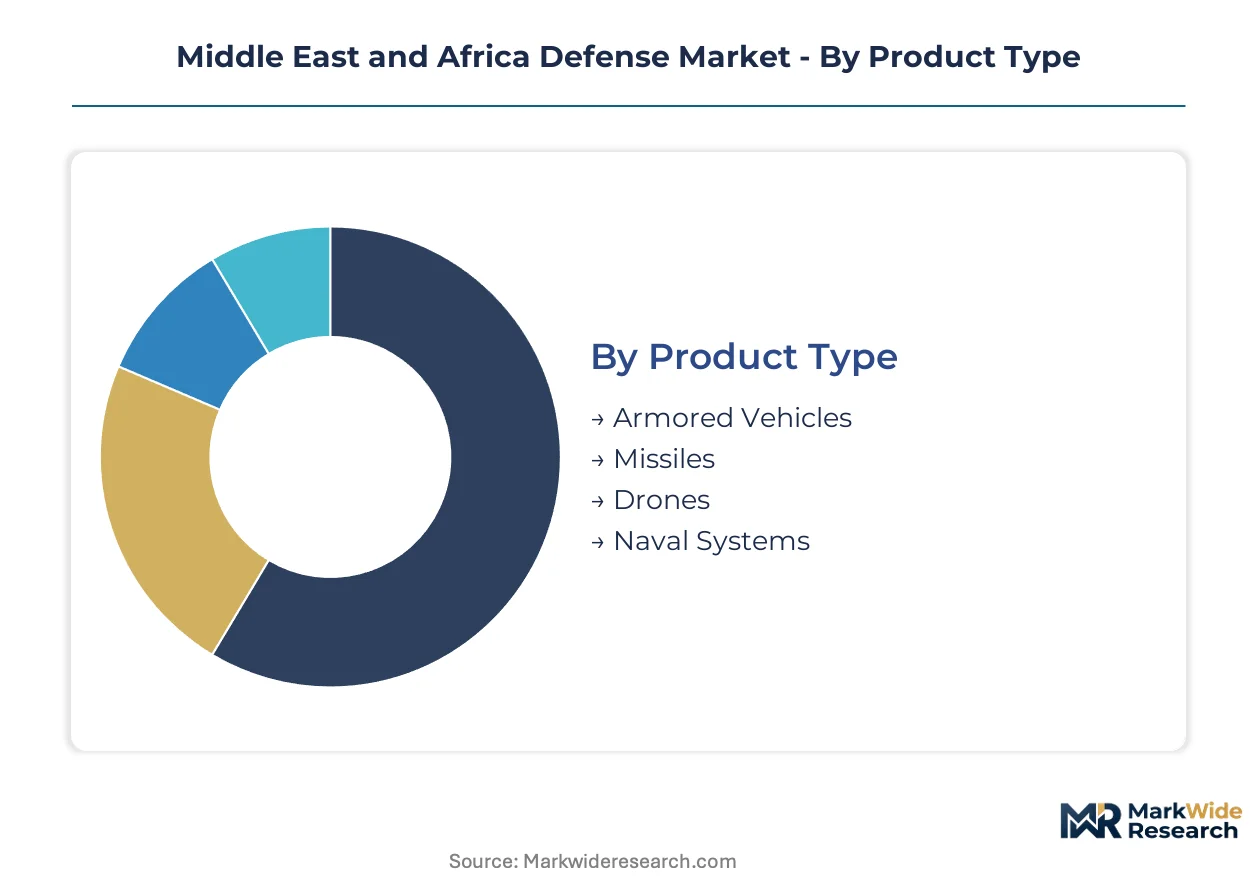
| Segmentation | Product Type: Armored Vehicles, Missiles, Drones, Naval Systems Technology: Surveillance, Communication, Cybersecurity, Simulation End User: Military, Government, Private Security, Peacekeepers Application: Intelligence, Combat, Training, Logistics |
| Companies Covered | EDGE Group, Baykar, Elbit Systems, Roketsan, Turkish Aerospace Industries, Israel Aerospace Industries, Aselsan, Denel SOC Ltd, Rafael, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Defense Market Shifts & Advancements
Unmanned platforms and sovereign data architectures are actively reshaping competitive positioning across the Middle East and Africa Defense market. Buyers are prioritizing systems with indigenous control over data flows and maintenance sovereignty.
Autonomous swarm coordination algorithms are supplanting single-platform drone operations in border surveillance missions. UAE and Saudi forces are fielding networked unmanned clusters for perimeter monitoring. This compression of unit economics is displacing manned reconnaissance aircraft procurement in favor of disposable sensor networks.
SFDA and MOHAP regulatory frameworks in Saudi Arabia and the UAE are tightening data sovereignty protocols for military communications equipment. Foreign OEMs must now establish domestic data centers and encryption key custody within national borders. The cybersecurity subsystem segment is responding with localized hardware security module production partnerships.
Defense ministries are unbundling platform acquisition from through-life support contracts. Traditional prime integrators now compete against domestic MRO consortia for sustainment revenue streams. This shift is most visible in the UAE's Tawazun-led defense industrial corridor, where EDGE Group facilities capture maintenance work previously reserved for foreign OEMs.
Middle East and Africa Defense Market Segmentation
Defense procurement across the Middle East and Africa flows through distinct channels shaped by sovereign wealth deployment and localization mandates. Each segment category carries unique certification requirements and partnership structures that determine vendor access and contract terms.
Product Type:
Channel distribution varies sharply by platform maturity and offset eligibility. Armored vehicles and naval systems flow through state-directed joint ventures with foreign primes. Drones and missiles increasingly route through domestic manufacturing facilities backed by venture capital mechanisms.
- Armored Vehicles:Heavy platforms integrate hardened thermal management systems for desert operations. Saudi GAMI and UAE Tawazun councils mandate domestic assembly for main battle tank and infantry fighting vehicle procurement, compressing traditional foreign OEM margins.
- Drones:Unmanned aerial systems with autonomous swarm coordination capabilities anchor the fastest-expanding procurement category. Border surveillance missions across the Sahel and Arabian Peninsula concentrate demand for extended-endurance platforms with indigenous data sovereignty protocols.
- Missiles:Precision-guided munitions depend on rare earth magnet supply chains concentrated in East Asian processing facilities.
- Naval Systems:Frigate and corvette programs concentrate in Gulf Cooperation Council states with sovereign maintenance requirements.
By volume, armored vehicles lead. By growth pace, drones are ahead.
Technology:
Cost tiers separate sovereign-critical capabilities from commoditized subsystems. Cybersecurity and surveillance command premium pricing due to capability scarcity and data localization mandates. Communication and simulation occupy standard procurement tiers with broader vendor pools.
- Cybersecurity:Command-and-control network protection systems carry premium pricing due to indigenous architecture requirements. SFDA and MOHAP regulatory frameworks in Saudi Arabia and the UAE mandate domestic encryption key custody and localized hardware security module production.
- Surveillance:Electro-optical and signals intelligence platforms integrate hardened communications architectures for contested electromagnetic environments. Asymmetric warfare requirements across North African and Arabian Peninsula theaters drive procurement concentration.
- Communication:NATO STANAG-compliant systems bifurcate from nationally sovereign architectures.
- Simulation:Training systems face certification fragmentation across Israeli MoD, South African Armscor, and NATO STANAG regimes.
By margin contribution, cybersecurity leads. By deployment velocity, surveillance is expanding most quickly.
End User:
Customer type determines contract structure and technology transfer intensity. Military end-users impose the strictest localization and offset requirements. Government and peacekeeping channels offer alternative access routes with modified certification demands.
- Military:State defense ministries enforce equity stake surrender and technology access provisions through GAMI and Tawazun mechanisms. Procurement concentrates in platform life extension programs and replacement cycles for legacy Soviet-era systems.
- Peacekeepers:NATO-aligned African peacekeeping forces prioritize STANAG-compliant platforms for coalition interoperability. Elbit Systems sustains long-term contracts through certified portfolio alignment.
- Government:Interior ministries and border agencies drive demand for perimeter monitoring systems.
- Private Security:Commercial operators face restricted access to sovereign-class capabilities and encrypted architectures.
By contract value, military end-users dominate. By access flexibility, peacekeeping channels offer the steepest expansion trajectory for certified vendors.
Application:
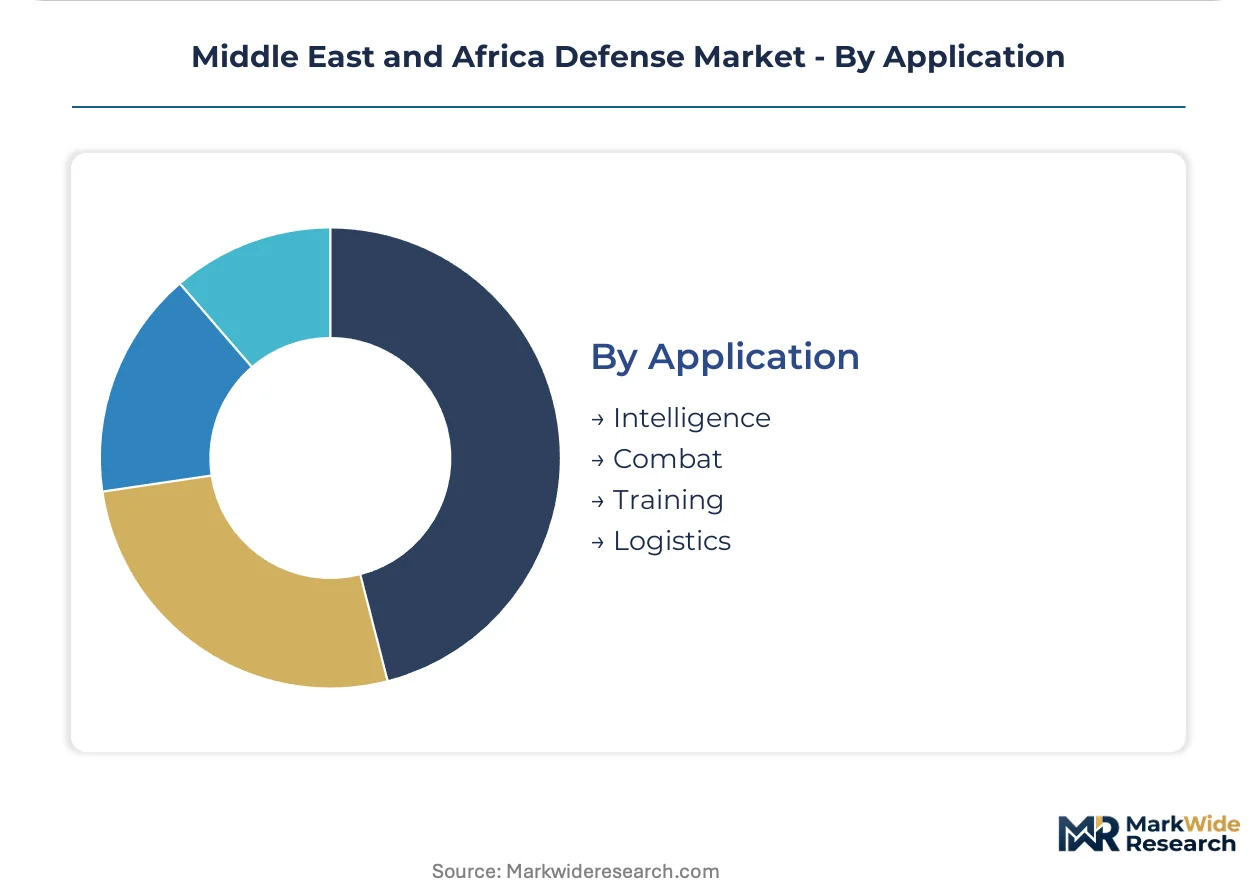
Maturity gradients separate established operational domains from emerging capability areas. Combat and logistics represent mature procurement segments with defined vendor relationships. Intelligence and training applications attract new entrants through technology disruption.
- Intelligence:Multi-domain sensor fusion and data analytics platforms integrate sovereign data architectures. SFDA and MOHAP frameworks mandate domestic data center establishment for foreign OEMs seeking contract eligibility.
- Combat:Kinetic operations concentrate procurement in precision strike and force protection systems with through-life support unbundling.
- Training:Simulation-based instruction faces redundant qualification spending across parallel Israeli, South African, and NATO certification regimes.
- Logistics:Supply chain and maintenance operations shift toward domestic MRO consortia in the UAE's Tawazun-led industrial corridor.
By platform integration depth, combat applications lead. By capability refresh rate, intelligence is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Suez Canal anchors Egypt's strategic position as a logistics artery for military equipment transit between European NATO suppliers and Gulf procurement hubs. This maritime chokepoint underwrites Cairo's diplomatic leverage in defense trade negotiations.
Saudi Arabia
GAMI localization mandates redirect foreign contractor revenue into domestic joint ventures and workforce development programs. The General Authority for Military Industries enforces equity stake surrender requirements for contract eligibility. Riyadh's defense industrial corridor concentrates platform assembly and MRO capabilities.
United Arab Emirates
Tawazun Council venture capital mechanisms force primes to surrender technology access in exchange for long-term positions. MOHAP regulatory frameworks mandate domestic data center establishment and encryption key custody within national borders. Abu Dhabi's EDGE Group facilities capture maintenance work previously reserved for foreign OEMs.
Israel
Ministry of Defense procurement reforms impose accelerating technology transfer requirements that reshape partnership terms for foreign primes. The country's parallel certification regime creates distinct technology access tiers separate from NATO STANAG alignment. Tel Aviv's defense technology cluster sustains indigenous electronic warfare and aerospace development.
Turkey
Vertically integrated drone manufacturing anchors Turkish export dominance across North African and Arabian Peninsula theaters. Baykar and Turkish Aerospace Industries exemplify the captive supply model that Gulf states seek to replicate. Ankara's defense industrial base concentrates unmanned platform production and precision-guided munition development.
South Africa
Armscor maintains certification regimes that shape regional alliance structures and technology access tiers across sub-Saharan peacekeeping forces. Denel SOC Ltd anchors state-directed platform development despite fiscal constraints. Pretoria's defense industrial corridor concentrates armored vehicle refurbishment and legacy Soviet-era system sustainment.
Middle East and Africa Defense Market Competitive Landscape
Listed leaders compete with private specialists across platform integration and subsystem supply. The supplier landscape bifurcates between STANAG-certified vendors serving NATO-aligned forces and nationally sovereign system providers. Three archetypes dominate: state-backed industrial champions with captive domestic demand, vertically integrated drone specialists with export-focused production, and electronic warfare subsystem developers reducing foreign dependency for periphery states. Competitive moves concentrate on localization partnerships and technology transfer negotiations rather than pure price competition.
Among state-backed champions, EDGE Group exemplifies the sovereign wealth-funded model with integrated platform and MRO capabilities. Baykar and Elbit Systems occupy distinct positions: the former represents vertically integrated unmanned systems production, while the latter anchors STANAG-compliant portfolio alignment for coalition interoperability requirements. Aselsan sits within the electronic warfare specialization tier, supplying indigenous subsystem capabilities to reduce foreign dependency.
| Leading Market Players |
|---|
| EDGE Group |
| Baykar |
| Elbit Systems |
| Roketsan |
| Turkish Aerospace Industries |
| Israel Aerospace Industries |
| Aselsan |
| Denel SOC Ltd |
| Rafael |
| Others |
Supply & Pricing Matrix
NATO STANAG certification gates both supplier qualification and price differentiation simultaneously, separating coalition-interoperable platforms from nationally sovereign systems. This bifurcation creates parallel procurement channels where certified vendors command premium positioning while non-certified suppliers compete on localization terms.
Pricing Analysis
Volume-discount tiering structures dominate procurement contracts across GCC defense ministries, with platform-scale orders attracting 15-25% unit cost reductions. Three-tier pricing stratifies across STANAG-certified systems, nationally sovereign architectures, and offset-compliant joint ventures. Cost compression in the sovereign tier is intensifying because GAMI and Tawazun localization mandates force foreign primes to surrender margin through equity stakes and technology transfer. Peacekeeping forces demonstrate highest price sensitivity due to budget constraints, while military end-users prioritize capability over unit cost.
Supply Chain Analysis
Port congestion at Jebel Ali and container availability constraints on Asia-Gulf trade lanes are elevating inbound logistics costs for precision-guided munition components. Rare earth magnet processing concentrates in East Asian facilities, with actuators and guidance systems drawing from Chinese and Japanese supply bases. Single-source vulnerability permeates the drone propulsion segment where Turkish manufacturers anchor regional availability. Distribution runs through state-directed joint ventures in Saudi Arabia's defense industrial corridor and UAE Tawazun-backed facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autonomous swarm coordination algorithms are disrupting traditional platform economics, creating a high-growth inflection as disposable sensor networks displace manned reconnaissance procurement across the Arabian Peninsula and Sahel theaters.
For Market Incumbents: Consolidate through-life support capabilities against domestic MRO consortia capturing maintenance revenue previously reserved for foreign OEMs. Deepen certification investment across Israeli MoD and South African Armscor parallel regimes to defend platform positions against emerging subsystem specialists.
For New Entrants and Emerging Players: Cybersecurity architecture gaps where incumbents under-serve indigenous encryption key custody requirements present immediate white-space opportunity. SFDA and MOHAP regulatory frameworks in Saudi Arabia and the UAE mandate domestic data center establishment, creating penetrable entry points for localized hardware security module production partnerships.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across drone manufacturing localization as Gulf states replicate Turkey's vertically integrated production model. Long-term viability favors acquisition targets with captive supply chain control and sovereign wealth fund backing. The signal to watch is Tawazun Council venture capital deployment velocity into domestic unmanned platform assembly.
| Strategic Initiative | Industry Significance |
|---|---|
| Localization Partnership Formation | GAMI offset mandates force foreign primes to establish Saudi joint ventures for contract eligibility. |
| STANAG Certification Investment | Coalition interoperability requirements sustain Elbit Systems' long-term African peacekeeping contracts. |
| Data Sovereignty Infrastructure | MOHAP frameworks require domestic encryption key custody within UAE national borders. |
| Electronic Warfare Subsystem Development | Aselsan's indigenous capabilities reduce foreign dependency for NATO periphery states. |
| Autonomous Swarm Integration | Networked unmanned clusters displace manned reconnaissance across UAE and Saudi border surveillance missions. |
Research Methodology
Desk research of defense procurement databases, customs trade records, and regulatory filing precedents preceded structured interviews with defense ministry procurement officers, platform engineering directors, sovereign wealth fund investment leads, and aftermarket service heads. Primary fieldwork across Riyadh, Abu Dhabi, and Tel Aviv defense industrial corridors combined with secondary validation from GAMI localization reports, Tawazun venture disclosures, and Armscor certification registries. Bottom-up platform shipment analysis triangulated against top-down defense budget allocation models.
Variance decomposition across technology maturity curves, localization mandate enforcement timelines, and certification regime adoption rates shaped the analytical framework. Segmentation dimensions modeled include platform type, technology tier, end-user category, and application domain alongside regional regulatory cluster alignment. CAGRs derived from fitted growth curves applied to disclosed procurement volumes and announced program budgets. Rare earth supply concentration indices and electromagnetic spectrum allocation policies served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in GAMI localization mandates, Tawazun venture mechanisms, and Israeli MoD procurement reforms; material policy shifts would require re-modeling. Technology transfer friction intensity and sovereign wealth fund deployment velocity represent specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Mission Management System Market
Defense and Military Systems and Equipment
Global Military Laser Designator Market
Defense and Military Systems and Equipment
Military Helmet and Helmet Mounted Displays Market
Defense and Military Systems and Equipment
Global Digital Battlefield Market
Defense and Military Systems and Equipment
Global Military Laser Rangefinder Market
Defense and Military Systems and Equipment
Explosive Ordnance Disposal (EOD) Equipment Market
Defense and Military Systems and Equipment
Missiles and Missile Defense Systems Market
Defense and Military Systems and Equipment
Military High Altitude Radio Jamming System Market
Defense and Military Systems and Equipment
Military Phased Array Antenna Market
Defense and Military Systems and Equipment
Bio-Defense Market
Defense and Military Systems and Equipment
Mechanical and Electronic Fuzes Market
Defense and Military Systems and Equipment
Explosive Ordnance Disposal Market
Defense and Military Systems and Equipment
Soldier System Market
Defense and Military Systems and Equipment
India Defense Market
Defense and Military Systems and Equipment
Search and Rescue Equipment Market
Defense and Military Systems and Equipment
Airborne Electronic Warfare Market