
 Military Laser Systems Market | 2026-2036
Military Laser Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Military Laser Systems Market Intelligence
The gap between laboratory-grade directed energy systems and field-deployable tactical lasers is realigning procurement patterns across NATO defense ministries. Lockheed Martin leverages its integrated battle management heritage to anchor high-power laser contracts with the US Navy. BAE Systems competes through specialized naval platform integration, while Elbit Systems Ltd differentiates via electro-optical payloads tailored to asymmetric threat environments.
Military laser systems encompass solid-state, fiber, and chemical laser architectures engineered to deliver precise energy on target at tactically relevant ranges, typically operating across infrared wavelengths with output powers from kilowatt-scale counter-UAS systems to multi-megawatt strategic interceptors. Fiber lasers dominate current naval deployment programs due to superior thermal management and beam quality, while solid-state lasers occupy the maturity segment with established supply chains for rangefinding and target designation. Directed energy applications capture the fastest expansion trajectory as militaries prioritize speed-of-light engagement against drone swarms and hypersonic threats.
The US Department of Defense, NATO Standardization Office, and ISO/IEC laser safety frameworks collectively shape market access through interoperability mandates and personnel protection thresholds. Pentagon acquisition reform under rapid fielding authorities is compressing test cycles and redirecting procurement toward commercially derived components. Stakeholders must monitor how classification requirements evolve for directed energy performance data, as transparency rules will determine which contractors qualify for allied joint development programs.
Market Dynamics
Directed energy weapons programs are compressing development timelines from laboratory demonstration to field deployment, with Pentagon rapid fielding authorities bypassing traditional acquisition stages to accelerate counter-drone and missile defense capabilities.
Growth Catalysts
- Replicator Initiative Priorities:The US Department of Defense's rapid prototyping pathways are redirecting procurement toward commercially derived laser components, collapsing multi-year development cycles into months.
- NATO Interoperability Mandates:The NATO Standardization Office is driving common directed energy interfaces across allied naval platforms, creating pooled procurement volumes for fiber laser systems.
- Hypersonic Threat Response:Speed-of-light engagement requirements against maneuvering hypersonic vehicles are forcing investment in multi-megawatt solid-state architectures for terminal defense.
Market Restraints
- Rare-Earth Supply Concentration:Neodymium and ytterbium fiber laser feedstock production concentrates in China, exposing Western defense supply chains to export control vulnerability.
- Atmospheric Degradation Physics:Thermal blooming and beam wander in maritime environments impose hard range limitations on tactical laser effectiveness against low-altitude threats.
- Classification Barriers:Special access program restrictions on directed energy performance data prevent allied joint development, fragmenting procurement into national silos.
Strategic Opportunities
- Counter-UAS Swarm Defense:Kilowatt-class fiber lasers for base protection against drone swarms represent underpenetrated demand in European and Indo-Pacific allied forces.
- AI-Driven Beam Control:Convergence of machine learning with adaptive optics enables real-time atmospheric compensation, extending effective range without power increases.
- Commercial Component Leverage:The IRA domestic manufacturing incentives for semiconductor and optical component production are creating alternative supply pathways for defense laser subsystems.
Industry Challenges
- Directed Energy Workforce Scarcity:Specialized expertise in high-power thermal management and wavefront engineering remains concentrated in a handful of national laboratories and defense contractors.
- Legacy Platform Integration:Retrofitting fiber laser weapons onto existing naval combatants requires hull, power, and cooling modifications that compress available magazine space and strain shipboard electrical generation.
- Test Range Limitations:Open-air laser testing against realistic threat profiles faces restricted airspace availability and environmental compliance delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Laser Systems Market |
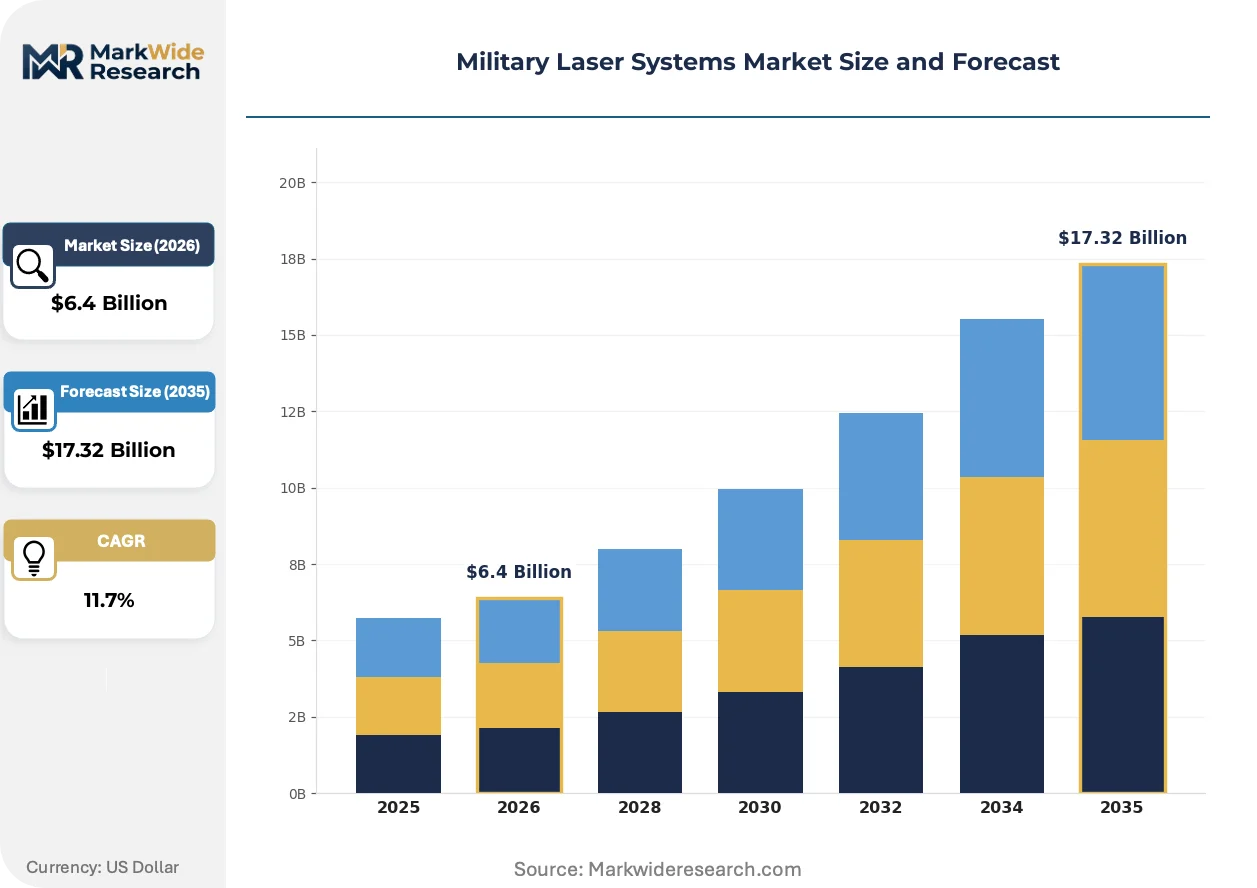
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Power Lasers, Fiber Lasers, Solid-State Lasers, Gas Lasers Application: Targeting, Communication, Weaponry, Measurement Technology: Directed Energy, Non-Lethal, Tactical, Rangefinding End User: Defense Forces, Government Agencies, Research Institutions, Contractors |
| Companies Covered | BAE Systems, Elbit Systems Ltd, Lockheed Martin Corporation, L3Harris Technologies Inc., Thales Group, Raytheon Technologies Corporation, The Boeing Company, MBDA, Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Laser Systems Market Strategic Shifts & Innovations
Beam combining architectures and solid-state thermal management are converging to push tactical lasers past the 300-kilowatt threshold, while acquisition reform is collapsing the barrier between developmental prototypes and operational fielding.
Fiber laser technology is integrating coherent beam combining of multiple kilowatt modules to achieve tactically relevant power levels without single-aperture thermal limits. Naval surface warfare centers are adopting these architectures for shipboard counter-cruise-missile applications at compressed development schedules. This integration is enabling prime contractors to bypass traditional subsystem qualification stages and field operational prototypes within 24-month cycles.
The EU AI Act's risk classification framework is extending to autonomous targeting systems, requiring human-in-the-loop verification for lethal directed energy engagements. European defense ministries are responding by mandating interpretable AI decision logs for laser weapon fire control, adding software development overhead but creating compliance differentiation for export systems. Naval platform integrators in France and Germany are most affected, restructuring software stacks to satisfy both operational tempo and auditability requirements.
Allied defense ministries are consolidating directed energy procurement through framework agreements rather than discrete program offices, concentrating demand volume with pre-qualified system integrators. The UK Ministry of Defence and Australian Defence Force are piloting this approach for counter-UAS laser programs, replacing competitive prototyping with spiral capability upgrades. This pattern is most visible in Five Eyes intelligence-sharing arrangements, where common threat assessments drive synchronized fielding timelines.
Military Laser Systems Market Segmentation
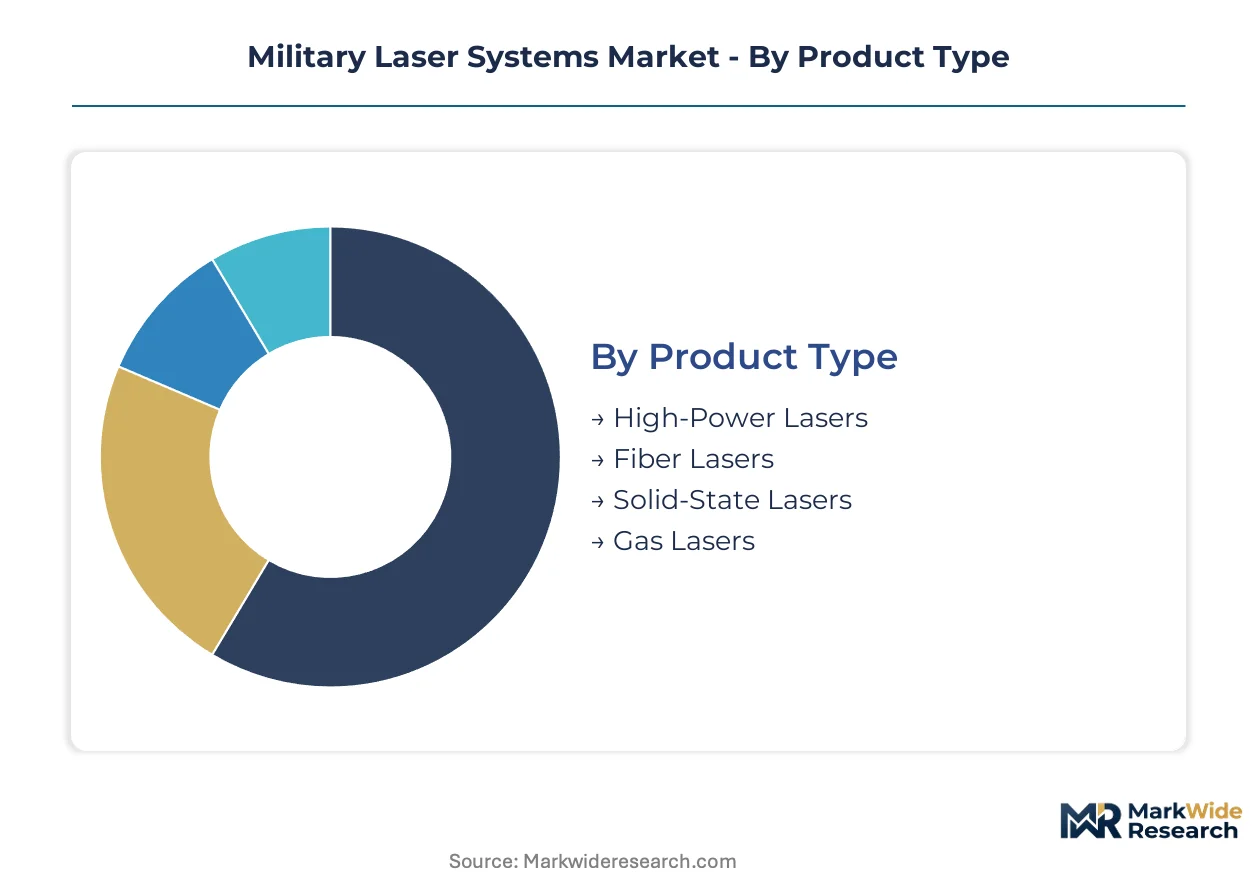
Military laser procurement splits between mature rangefinding systems and developmental directed energy weapons, with each segment demanding distinct supply chain configurations and contracting mechanisms. The divergence between commercial fiber laser components and classified high-power architectures creates parallel qualification pathways that reshape vendor participation.
Product Type:
Standardization dominates fiber and solid-state platforms with established test protocols, while high-power and gas laser systems require extensive customization for platform-specific integration.
- Fiber Lasers:Coherent beam combining of kilowatt modules enables scalable power output without single-aperture thermal limits. Naval surface warfare centers in the United States prioritize these architectures for shipboard counter-cruise-missile programs, compressing fielding timelines through commercial component leverage.
- Solid-State Lasers:Mature diode-pumped architectures with proven supply chains for target designation and rangefinding applications. Demand concentrates in legacy platform retrofits across NATO ground forces, constrained by rare-earth magnet feedstock concentration in China.
- High-Power Lasers:Multi-megawatt systems for strategic missile defense requiring specialized thermal management.
- Gas Lasers:Chemical oxygen-iodine platforms with declining procurement volume outside specific naval programs.
Most installed capacity flows through Fiber Lasers. Expansion is steepest in High-Power Lasers.
Application:
Cost tiers separate mission-critical weaponry programs from support functions, with targeting and measurement systems operating on fixed-price contracts while directed energy weaponry uses cost-plus development vehicles.
- Weaponry:Directed energy interceptors for counter-drone and missile defense applications. Pentagon rapid fielding offices in the United States drive demand through Replicator initiative priorities, collapsing multi-year development cycles.
- Targeting:Laser designators for precision-guided munitions with established NATO interoperability standards.
- Communication:Free-space optical links for satellite and airborne platforms.
- Measurement:Lidar and rangefinding systems for artillery and reconnaissance applications.
Procurement volume clusters in Weaponry. Capability gaps are narrowing fastest in Communication.
Technology:
Maturity gradients separate field-proven rangefinding from developmental directed energy, with non-lethal systems occupying an intermediate position requiring dual-use export licensing.
- Directed Energy:Speed-of-light engagement systems for hypersonic threat response and drone swarm defense. The US Department of Defense's special access programs restrict performance data transparency, fragmenting allied joint development.
- Tactical:Compact systems for dismounted soldier and vehicle platforms with volume manufacturing potential.
- Non-Lethal:Dazzling and denial applications for perimeter security and crowd control.
- Rangefinding:Mature laser radar with established ISO/IEC safety certification pathways.
Revenue concentration sits with Rangefinding. Investment intensity is highest in Directed Energy.
End User:
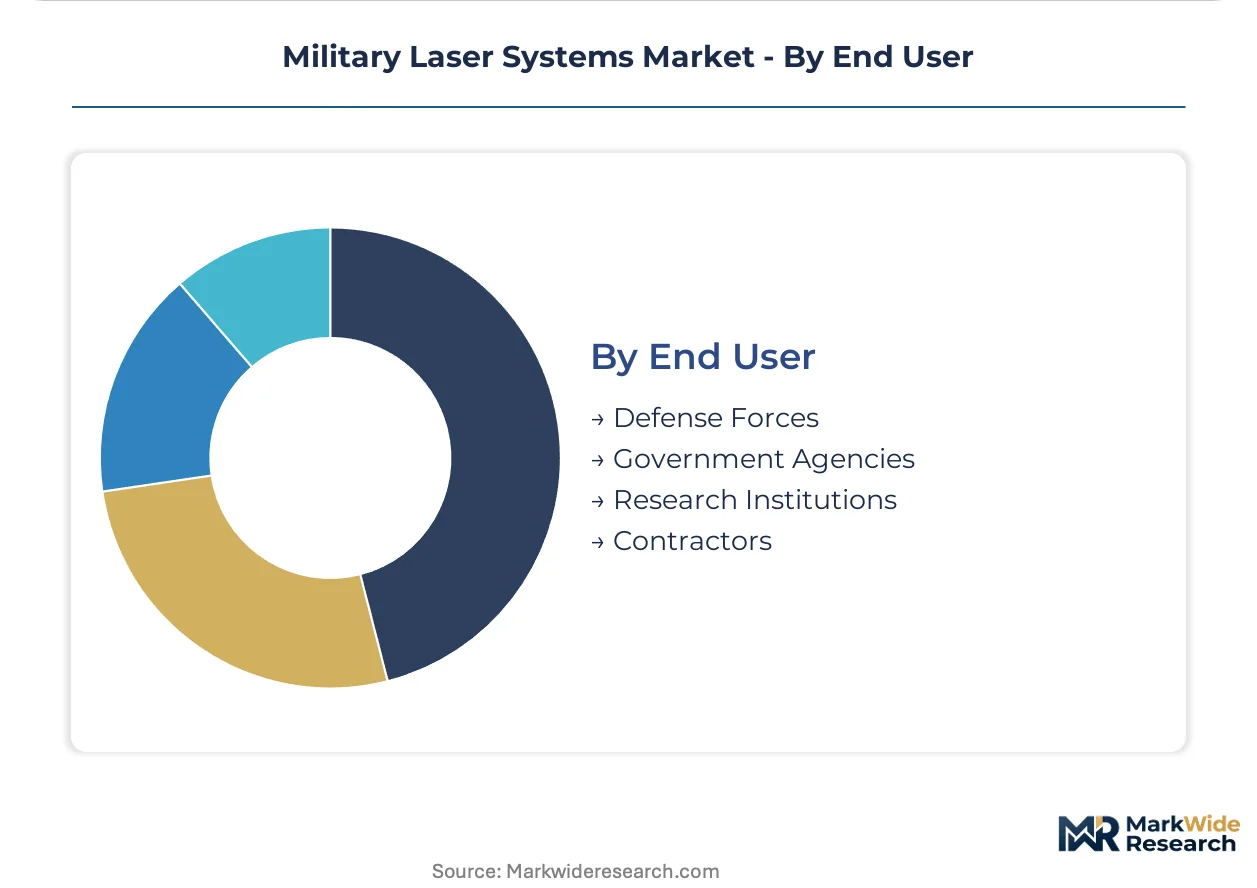
Customer type determines contracting flexibility, with defense forces driving classified programs while contractors and research institutions operate under broader competitive access.
- Defense Forces:Pentagon-directed rapid fielding offices and NATO naval commands with compressed acquisition timelines. The United States accounts for dominant procurement volume through classified special access programs.
- Government Agencies:Border security and coast guard organizations with civilian oversight requirements.
- Research Institutions:National laboratories with directed energy workforce concentration in high-power thermal management.
- Contractors:Prime integrators managing subsystem qualification and platform integration risk.
Budget authority concentrates with Defense Forces. Research Institutions channel the steepest funding growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates directed energy procurement through classified special access programs, while Germany accelerates naval laser integration under EU defense autonomy initiatives. Procurement patterns diverge between Pentagon rapid fielding offices and NATO standardization frameworks.
United States
Pentagon-directed rapid fielding offices drive demand through Replicator initiative priorities, compressing multi-year development cycles into months. The Department of Defense operates under special access program restrictions that fragment performance data transparency. Naval surface warfare centers in Virginia and California anchor fiber laser prototyping for shipboard counter-cruise-missile applications.
United Kingdom
The Ministry of Defence consolidates directed energy procurement through framework agreements replacing discrete program offices, concentrating demand with pre-qualified integrators. UK laser safety regulations align with ISO/IEC personnel protection thresholds. Defence Science and Technology Laboratory facilities in Wiltshire host atmospheric compensation testing for maritime beam propagation.
Germany
Federal Ministry of Defence mandates interpretable AI decision logs for laser weapon fire control under EU AI Act compliance requirements. Naval platform integrators in Kiel and Hamburg restructure software stacks to satisfy operational tempo and auditability standards. Thyssenkrupp Marine Systems facilities concentrate high-power thermal management expertise for frigate-mounted directed energy systems.
Israel
Asymmetric threat environments drive electro-optical payload specialization for drone swarm defense applications. Ministry of Defense procurement operates through classified bilateral arrangements with limited NATO interoperability disclosure. Rafael Advanced Defense Systems and Elbit Systems anchor development clusters in Haifa and Rehovot for tactical laser integration.
Australia
Australian Defence Force pilots framework procurement for counter-UAS laser programs synchronized with Five Eyes intelligence-sharing arrangements. Defence Science and Technology Group facilities in Canberra coordinate spiral capability upgrades replacing competitive prototyping. Joint development with US Navy surface warfare centers accelerates Indo-Pacific maritime laser deployment timelines.
Military Laser Systems Market Key Industry Players
Top-tier vendors anchor prime integration contracts, while specialized subsystem suppliers occupy mid-tier positions with platform-specific thermal management expertise. The vendor structure concentrates around naval and air defense platform integrators with established battle management heritage. Three archetypes dominate: vertically integrated primes managing end-to-end qualification, electro-optical payload specialists tailoring systems to asymmetric environments, and naval platform integrators optimizing hull-power-cooling configurations. Competitive moves center on coherent beam combining technology licensing and rapid fielding authority partnerships with Pentagon acquisition offices.
Within the prime integrator tier, Lockheed Martin Corporation and Northrop Grumman Corporation occupy positions anchored by integrated battle management heritage and naval combat system integration respectively. Raytheon Technologies Corporation exemplifies the directed energy specialization archetype through its positioning across multi-megawatt solid-state development programs. Elbit Systems Ltd represents electro-optical payload differentiation tailored to threat environments requiring compact tactical configurations.
| Leading Market Players |
|---|
| BAE Systems |
| Elbit Systems Ltd |
| Lockheed Martin Corporation |
| L3Harris Technologies Inc. |
| Thales Group |
| Raytheon Technologies Corporation |
| The Boeing Company |
| MBDA |
| Northrop Grumman Corporation |
| Others |
Cost & Logistics Intelligence
Ytterbium-doped fiber feedstock originating in Chinese rare-earth processing facilities cascades through three pricing tiers: laboratory-grade components for research institutions, ruggedized naval-qualified subsystems for prime integrators, and commercially derived modules for rapid fielding programs under Pentagon Replicator authorities.
Pricing Analysis
Capacity additions in domestic US semiconductor and optical component production under IRA manufacturing incentives are reshaping price floors for defense-qualified laser subsystems. Contract structures stratify across development prototypes, low-rate initial production, and full-rate manufacturing phases. Price differentiation rests on thermal management certification tier and platform integration complexity. Cost compression in kilowatt-class fiber modules is intensifying because commercial telecommunications component leverage collapses subsystem qualification timelines. Government rapid fielding offices exhibit lowest price sensitivity; allied naval procurement authorities with fixed defense budgets face highest pressure.
Supply Chain Analysis
ITAR and special access program qualification requirements gate vendor participation before geographic sourcing considerations apply. Rare-earth element concentration in China for neodymium and ytterbium feedstock, precision optical component manufacturing in Germany and Japan, and thermal management subsystem integration in the United States define supply geography. Raw material dependencies include ytterbium-doped fiber, high-purity laser diodes, and specialized ceramic thermal substrates. Single-source vulnerability concentrates in Chinese rare-earth export licensing. Distribution runs through prime integrator-managed qualification pipelines to defense procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where Pentagon rapid fielding authorities and NATO Standardization Office interoperability mandates accelerate procurement velocity beyond traditional defense acquisition cycles.
For Market Incumbents: Hedge against rare-earth supply disruption by securing alternative feedstock pathways through IRA domestic manufacturing incentives and Australian critical minerals partnerships. Anchor position in naval platform integration contracts where hull-power-cooling modifications create switching costs. Prioritize coherent beam combining R&D to maintain performance differentiation against commercial component entrants.
For New Entrants and Emerging Players: Launch via subcontractor relationships to prime integrators for atmospheric compensation software and adaptive optics subsystems. Target counter-UAS base protection programs in European and Indo-Pacific allied forces where procurement frameworks favor spiral capability upgrades over legacy prime relationships. Emphasize AI-driven beam control as a compliance-differentiated offering under EU AI Act interpretability requirements.
For Investors and Strategic Acquirers: Roll-up economics work for specialized thermal management and wavefront engineering boutiques because directed energy workforce scarcity concentrates expertise in fragmented national laboratories and mid-tier defense subcontractors. Five-to-ten-year viability hinges on sustained Replicator initiative funding and NATO naval laser standardization. Watch for classification barrier relaxation as the signal enabling allied joint development program participation.
| Strategic Initiative | Industry Significance |
|---|---|
| Coherent Beam Combining Technology Licensing | Enables scalable power output without single-aperture thermal limits for naval surface warfare centers. |
| Rapid Fielding Authority Partnership | Compresses 24-month prototype cycles through Pentagon Replicator initiative procurement pathways. |
| EU AI Act Compliance Software Stack | Creates export differentiation via interpretable decision logs for European naval platform integrators. |
| Domestic Rare-Earth Processing Investment | Reduces Chinese export control exposure under IRA critical minerals manufacturing incentives. |
| Framework Agreement Procurement Consolidation | Replaces competitive prototyping with spiral upgrades for UK Ministry of Defence and Australian Defence Force. |
Research Approach
Direct dialogue with Pentagon rapid fielding office program managers, naval surface warfare center engineers, prime integrator directed energy division heads, and national laboratory thermal management specialists grounded qualitative assessment. Secondary validation drew from Department of Defense budget justification documents, NATO Standardization Office technical standards, SEC contractor filings, and EU defense procurement databases. Bottom-up segmentation modeling triangulated against top-down defense expenditure forecasts.
Top-down defense budget allocation analysis anchored volume projections while bottom-up program office procurement timelines shaped segment-level growth trajectories across the projection horizon. Segmentation dimensions modeled include laser architecture type, application tier from rangefinding to strategic intercept, technology maturity gradient, and end-user contracting authority. CAGRs derived from program office funding profiles and rapid fielding initiative acceleration rates. Atmospheric compensation technology readiness and rare-earth supply chain resilience served as industry-specific forecast sensitivity inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Chinese rare-earth export restriction scenarios or Pentagon acquisition reform reversal. Projections reflect assumptions regarding sustained Replicator initiative prioritization and NATO interoperability mandate adoption. A model refresh is warranted upon material change in special access program classification guidance or EU AI Act enforcement interpretation for autonomous targeting systems.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Military Software Market
Defense and Military Systems and Equipment
India Defense Market
Defense and Military Systems and Equipment
Military Embedded System Market
Defense and Military Systems and Equipment
Military Actuators Market
Defense and Military Systems and Equipment
Network Centric Warfare (NCW) Market
Defense and Military Systems and Equipment
Search and Rescue Equipment Market
Defense and Military Systems and Equipment
Explosive Ordnance Disposal Market
Defense and Military Systems and Equipment
Military Load Carriage System Market
Defense and Military Systems and Equipment
Command and Control Systems Market
Defense and Military Systems and Equipment
Military Embedded System Software Market
Defense and Military Systems and Equipment
Global Battlefield Management System Market
Defense and Military Systems and Equipment
Battle Management System (BMS) Market
Defense and Military Systems and Equipment
Global Military Defense Vehicle Intercom System Market
Defense and Military Systems and Equipment
Radar Warning Receiver Market
Defense and Military Systems and Equipment
United Kingdom Defense Market
Defense and Military Systems and Equipment
GCC Defense Market