
 Europe Defense Market | 2026-2036
Europe Defense Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Defense Market Foresight
Software-defined electronic warfare and predictive maintenance subscriptions are pivoting how European defense primes monetize platforms. Thales leverages its cybersecurity heritage to bundle SaaS threat-intelligence layers with radar exports. Rheinmetall anchors ground-system modernization through captive ammunition supply chains stretching from Germany to NATO allies. Leonardo competes on sovereign rotorcraft and naval electronics specialization across Mediterranean basins.
Europe Defense encompasses sovereign military capability spanning kinetic platforms, C4ISR networks, and dual-use aerospace systems manufactured to STANAG interoperability standards and national military specifications. Its primary purpose is territorial deterrence, expeditionary mission support, and industrial base preservation through offset and local-content requirements. The aerial defense application segment leads procurement volume as layered air-and-missile defense architectures replace single-platform point defense across NATO's eastern flank. Cybersecurity technology commands premium margins within the technology segment as national cyber commands elevate sovereign encryption and zero-trust mandates above commercial-grade alternatives. Armored vehicles within product type remain structurally mature, with margin pools shifting to life-extension kits and remote turret upgrades rather than new hull production.
EU Green Deal carbon-accounting rules and PESCO joint procurement frameworks are tightening access for non-European suppliers while mandating sustainable manufacturing disclosures across the supply chain. EDA capability-development targets and NATO STANAG certification requirements shape what platforms member states can field interoperably. Stakeholders must monitor how the next multiannual financial framework allocates collaborative defense research funding versus national sovereignty priorities.
Market Dynamics
The EU Green Deal carbon-accounting rules are forcing defense primes to reconfigure supply chains for sustainable manufacturing disclosures across NATO STANAG-certified platforms.
Growth Catalysts
- Permanent Structured Cooperation:PESCO joint procurement frameworks enable cross-border capability development and pooled R&D funding among participating EU member states.
- AI-enabled electronic warfare:Software-defined systems allow real-time spectrum adaptation, with NATO cyber commands mandating sovereign encryption layers on all new C4ISR procurements.
- Poland:Accelerated sovereign capability investments in layered air-and-missile defense architectures drive procurement volume across the eastern flank.
Market Restraints
- Specialized alloy supply concentration:Titanium and rare-earth processing capacity concentrates outside European borders, exposing armored vehicle and aerospace programs to input volatility.
- REACH compliance friction:ECHA substance restrictions on chromates and cadmium coatings complicate life-extension kit production for legacy hull fleets.
- Skilled welder scarcity:Certified armor-grade fabrication specialists face demographic retirement waves across German and French industrial bases.
Strategic Opportunities
- EU AI Act alignment:Defense applications of machine learning for predictive maintenance gain regulatory clarity, unlocking SaaS subscription models for platform sustainment.
- Sweden and Finland:NATO accession creates demand convergence for interoperable C4ISR and naval electronics across Baltic Sea basins.
- Dual-use hydrogen propulsion:Convergence of fuel-cell technology with maritime platform requirements opens naval modernization pathways under Green Deal incentives.
Industry Challenges
- STANAG-NATO interoperability certification:Multi-year testing protocols delay fielding of software-defined systems against compressed procurement timelines.
- Legacy analog integration:Cold War-era platforms require bespoke middleware for connectivity with IP-based networks, inflating program risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Defense Market |
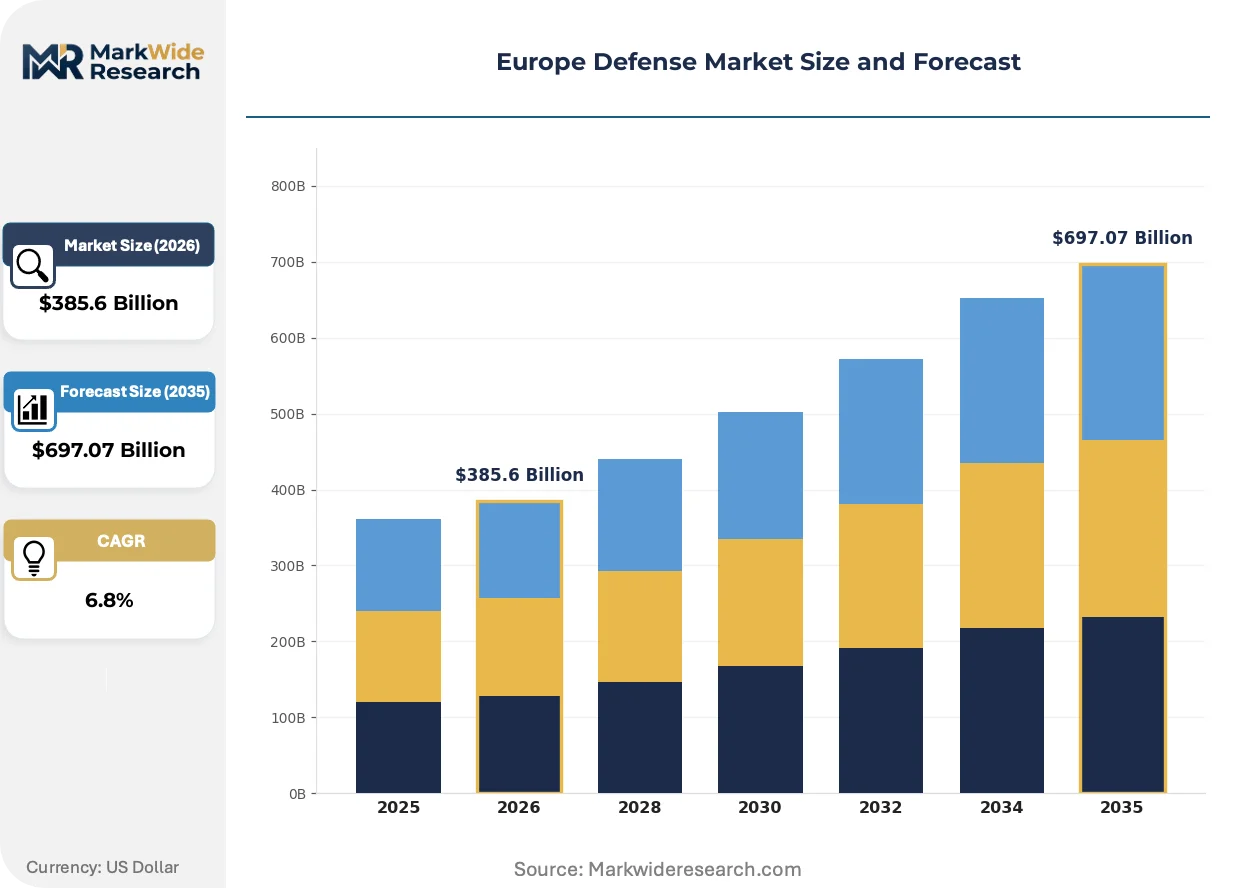
| Market Size in 2026 | $385.6 Billion |
| Market Size in 2035 | $697.07 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Armored Vehicles, Missiles, Drones, Communication Systems End User: Military, Government Agencies, Defense Contractors, Research Institutions Technology: Cybersecurity, AI Systems, Radar Technology, Navigation Systems Application: Aerial Defense, Ground Combat, Naval Operations, Training Simulators |
| Companies Covered | Leonardo, Saab, Airbus, Safran, Dassault, Rheinmetall, Thales, Naval Group, BAE Systems, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Defense Market Shifts & Advancements
Defense primes are restructuring platform economics around software layers and predictive sustainment, displacing transactional hardware sales with recurring revenue architectures.
Software-defined radio and cognitive electronic warfare is decentralizing spectrum dominance from centralized jamming platforms to distributed node networks. NATO expeditionary forces are fielding man-portable systems at brigade scale. This compression of electronic attack capability to tactical echelons is decentralizing procurement authority from national ministries to operational commands.
EU Green Deal sustainable manufacturing disclosures now mandate supply chain carbon accounting for all platforms procured through EDA collaborative frameworks. Defense industrial primes must document Scope 3 emissions from rare-earth extraction through final assembly. Naval shipbuilding and rotorcraft production face the steepest compliance gradients given energy-intensive hull fabrication and composite curing processes.
Subscription-based predictive maintenance is displacing transactional spare-part sales for armored vehicle fleets. Rheinmetall and Thales are bundling sensor-analytics platforms with original equipment, capturing lifecycle value through data monetization. Germany's Bundeswehr and France's Army de Terre represent the most advanced adopters, with multi-year availability contracts replacing traditional depot-maintenance schedules.
Europe Defense Market Segmentation
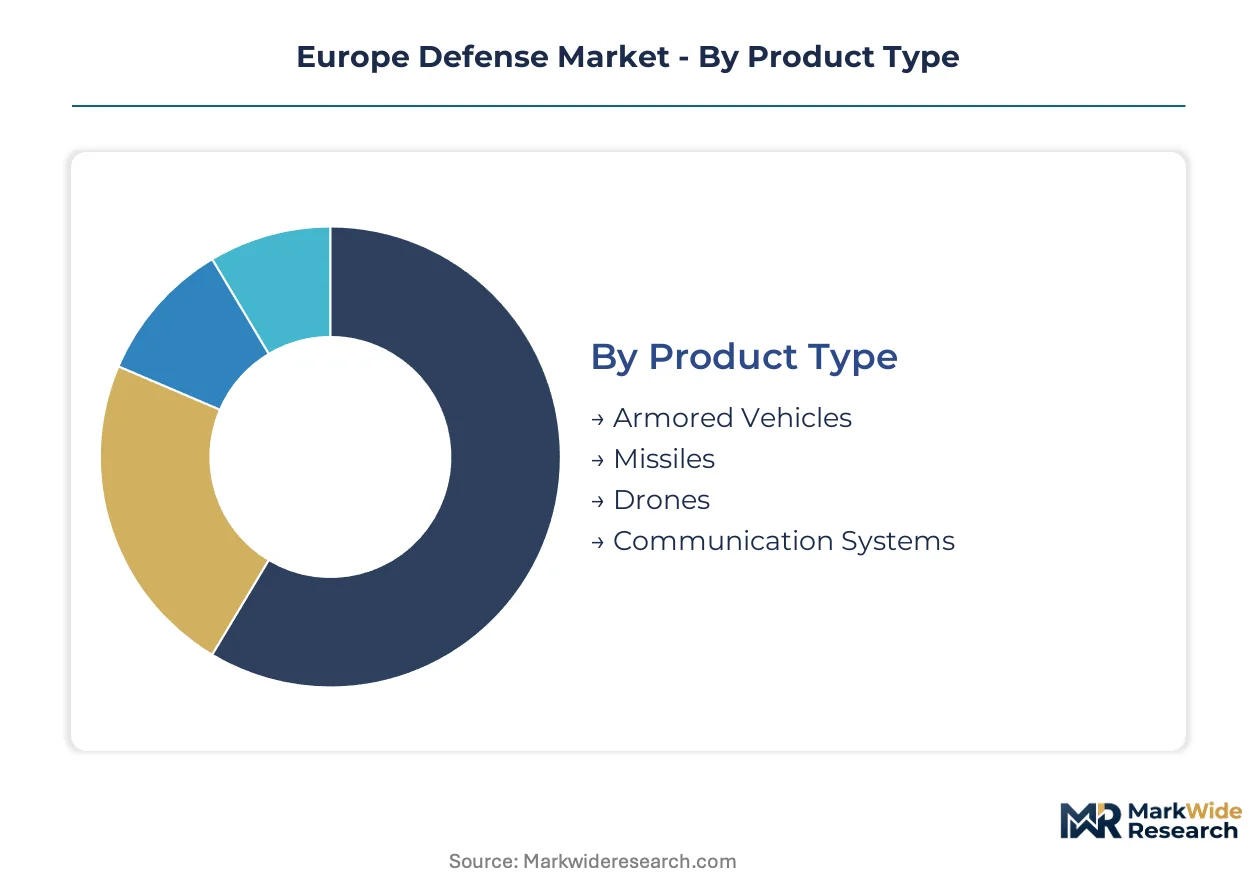
Defense procurement across Europe fragments along capability tiers and interoperability mandates. Upgrade cycles and sovereign specification requirements reshape how primes structure platform offerings and aftermarket service bundles.
Product Type:
Replacement timelines for legacy hulls and munitions stockpiles stretch procurement pipelines across multi-year modernization windows.
- Armored Vehicles:Life-extension kits and remote turret retrofits dominate spending as NATO members prioritize fleet availability over new hull acquisition. German and Polish land forces anchor demand for tracked platform modernization.
- Missiles:Layered air-and-missile defense architectures require interoperable effectors from short-range point defense to integrated theater systems. Procurement concentrates along NATO's eastern flank where sovereign ammunition supply chains face urgent replenishment.
- Drones:Tactical uncrewed systems proliferate at brigade echelon for reconnaissance and electronic warfare missions.
- Communication Systems:Software-defined radio platforms enable spectrum agility across multinational expeditionary formations.
Volume placements concentrate in Armored Vehicles; the faster expansion belongs to Missiles.
End User:
Customer archetypes diverge sharply on procurement authority and technical specification control.
- Military:Service branches wield capital budget authority for platform acquisition and dictate STANAG interoperability requirements. NATO cyber commands mandate sovereign encryption layers on all C4ISR procurements.
- Government Agencies:National ministries coordinate collaborative frameworks through PESCO and EDA mechanisms. Dual-use hydrogen propulsion research channels through energy and defense ministry joint programs.
- Defense Contractors:Primes subcontract specialized subsystems to tier-two suppliers under offset and local-content mandates.
- Research Institutions:University and national laboratory consortia validate AI-enabled predictive maintenance algorithms before operational fielding.
Contract flow concentrates through Military procurement channels; Research Institutions are expanding their share fastest.
Technology:
Margin pools shift toward software layers and data-centric sustainment architectures.
- Cybersecurity:Zero-trust network mandates and sovereign encryption requirements elevate premium pricing above commercial-grade alternatives. National cyber commands in France and Germany drive specification stringency.
- AI Systems:Predictive maintenance subscriptions monetize sensor data across armored vehicle fleets. EU AI Act alignment provides regulatory clarity for defense machine-learning applications.
- Radar Technology:Cognitive electronic warfare systems decentralize spectrum dominance to distributed node networks.
- Navigation Systems:Resilient positioning alternatives to GNSS jamming proliferate for expeditionary formations.
Revenue concentration sits with Cybersecurity; AI Systems are climbing the fastest.
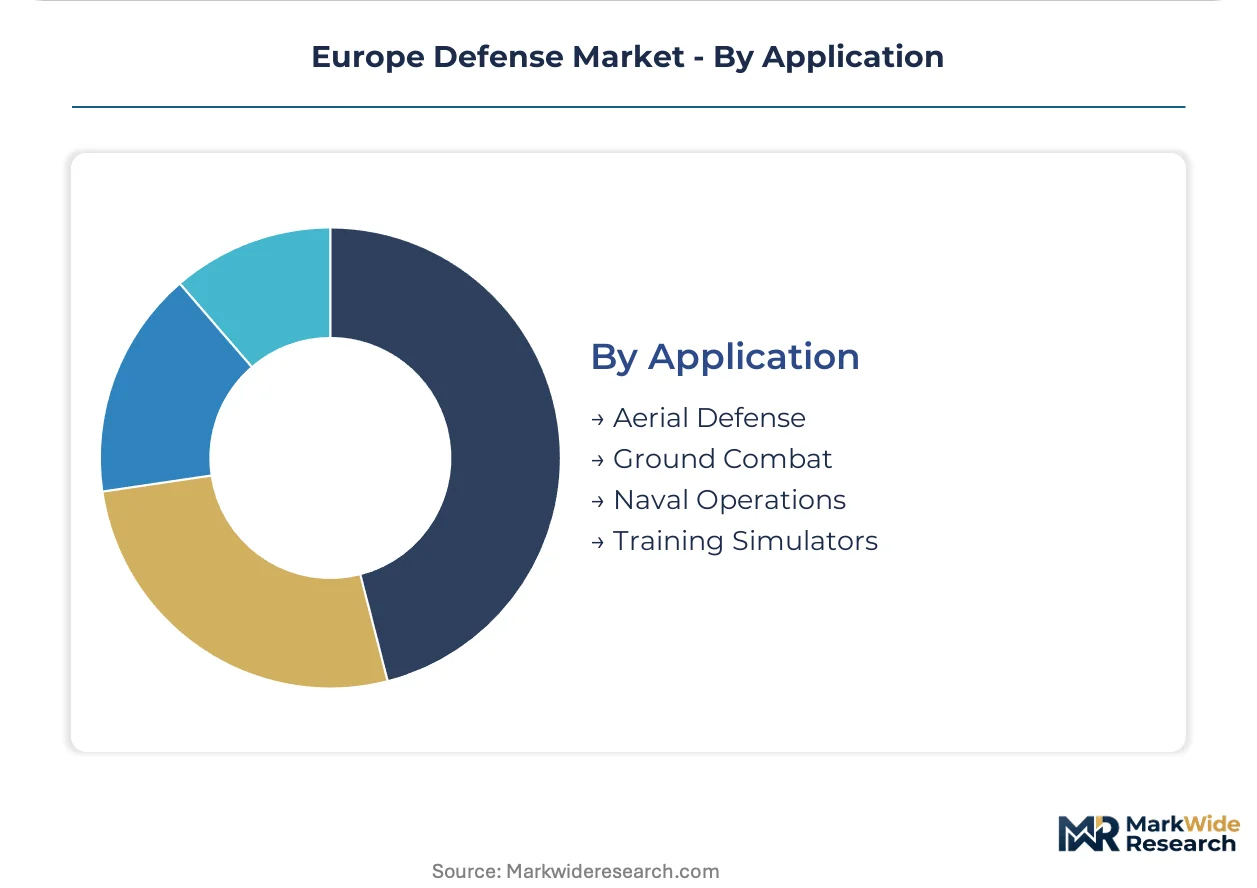
Application:
Mission profiles determine platform interoperability requirements and upgrade pathway feasibility.
- Aerial Defense:Layered architectures integrating ground-based air defense with fighter command-and-control networks replace single-platform point defense. Poland and Baltic states anchor procurement volume.
- Ground Combat:Brigade modernization programs emphasize manned-unmanned teaming and electronic warfare integration.
- Naval Operations:Surface and submarine platform requirements converge on dual-use hydrogen propulsion under Green Deal incentives.
- Training Simulators:Synthetic environment fidelity improves as AI-generated scenarios reduce live-exercise costs.
Program scale favors Aerial Defense; Naval Operations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Germany and France while procurement demand spreads across NATO's eastern periphery. This geographic split shapes cross-border supply chains and joint development frameworks.
Germany
Bundeswehr land-system modernization and naval vessel replacement drive sovereign capability investments. The EU AI Act and EU Green Deal carbon-accounting rules mandate sustainable manufacturing disclosures for defense platforms. Rheinmetall anchors ground-system production across North Rhine-Westphalia and Lower Saxony industrial corridors.
France
Armée de Terre and Marine Nationale procurement prioritizes nuclear deterrence modernization and carrier strike group renewal. Direction Générale de l'Armement enforces sovereign encryption mandates on all C4ISR acquisitions. Thales and Dassault cluster aerospace and naval electronics capabilities in Île-de-France and Provence-Alpes-Côte d'Azur.
Poland
Accelerated layered air-and-missile defense architectures address eastern flank deterrence requirements. NATO STANAG certification requirements shape interoperable platform selections. Defense industrial development concentrates in Warsaw and Poznań corridors with ammunition supply chain investments.
United Kingdom
Royal Navy submarine replacement and RAF sixth-generation fighter programs anchor capital expenditure. Ministry of Defence procurement frameworks emphasize sovereign encryption and zero-trust network mandates. BAE Systems anchors naval and aerospace production across Scotland and North England industrial bases.
Sweden
NATO accession converges Baltic Sea C4ISR and naval electronics requirements with alliance interoperability standards. FMV procurement authority mandates STANAG-certified platforms for expeditionary formations. Saab clusters aerospace and submarine capabilities in Linköping and Karlskrona defense industrial zones.
Europe Defense Market Competitive Landscape
Capital-heavy platform manufacturers compete with specialized subsystem suppliers for program integration roles. The vendor base organizes around three tiers: full-system primes with sovereign design authority, mid-tier subsystem specialists capturing offset mandates, and component suppliers feeding multinational supply chains. Prime contractors defend position through captive ammunition supply chains and software-layer subscriptions. Mid-tier players capture value via STANAG certification capabilities and national cyber command relationships.
Among continental European primes, Leonardo, Rheinmetall, and Thales exemplify divergent specialization archetypes. Leonardo occupies a position in sovereign rotorcraft and naval electronics across Mediterranean basins. Rheinmetall anchors ground-system modernization through in-house production of armored platforms and ammunition supply chains. Thales sits within the cybersecurity-integrated sensor tier, bundling threat-intelligence subscriptions with radar exports.
| Leading Market Players |
|---|
| Leonardo |
| Saab |
| Airbus |
| Safran |
| Dassault |
| Rheinmetall |
| Thales |
| Naval Group |
| BAE Systems |
| Others |
Supply & Pricing Matrix
Software-defined electronic warfare architectures are compressing platform economics toward recurring revenue models, simultaneously fragmenting procurement authority across NATO operational commands and concentrating margin pools with primes capable of bundling SaaS threat-intelligence layers. This technology shift forces tier-two suppliers to absorb REACH compliance costs for chromate-restricted coatings while defense ministries negotiate multi-year availability contracts that displace transactional spare-part sales.
Pricing Analysis
Margin tightening in armored vehicle life-extension kits reflects skilled welder scarcity across German and French industrial corridors. Three-tier pricing structure across premium, standard, and economy levels stratifies by STANAG certification grade and sovereign encryption mandate compliance. Cost-down pressure on ground-system modernization accelerates because Polish and Baltic procurement authorities prioritize fleet availability metrics over hull acquisition premiums. Military end users exhibit lowest price sensitivity for cybersecurity-integrated C4ISR platforms, while research institutions face budget constraints on AI-enabled predictive maintenance validation.
Supply Chain Analysis
Dual-sourcing requirements for titanium and rare-earth processing capacity now mandate qualified supplier pools spanning Germany, France, and Poland. Raw material dependencies center on specialized alloys, chromate coatings, and composite curing feedstocks. Single-source vulnerability concentrates in non-European rare-earth processing nodes outside ECHA regulatory jurisdiction. Distribution runs through EDA collaborative frameworks and PESCO joint procurement mechanisms, with national offset mandates fragmenting downstream channel structure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European defense primes are racing to deepen captive control over ammunition supply chains and software-layer subscriptions, with upstream integration into sovereign encryption development and downstream capture of predictive maintenance data monetization determining competitive position.
For Market Incumbents: Anchor ground-system modernization through in-house production of armored platforms and captive ammunition supply chains stretching to NATO eastern flank allies. Invest in STANAG certification capabilities for software-defined radio platforms to defend against emerging subsystem specialists. Prioritize EU Green Deal carbon-accounting compliance documentation to maintain EDA framework eligibility. For New Entrants and Emerging Players: The premium-to-economy price gap in tactical uncrewed systems offers white-space entry for mid-tier players capable of man-portable electronic warfare production. Target brigade-echelon procurement authority decentralization across expeditionary formations. Pursue offset mandate qualification in Polish and Baltic industrial corridors as the primary go-to-market pathway. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier subsystem specialists possessing STANAG certification capabilities and national cyber command relationships given NATO interoperability mandate expansion. Long-term viability hinges on sustained sovereign capability investment cycles across Germany, France, and Poland. Monitor PESCO collaborative defense research funding allocations as the critical inflection signal for platform economics.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Ammunition Supply Chain Buildout | Rheinmetall's backward integration into propellant production secures replenishment priority for Polish layered defense architectures. |
| SaaS Threat-Intelligence Platform Launch | Thales bundles cybersecurity heritage with radar exports to capture recurring revenue from NATO cyber command mandates. |
| Dual-Use Hydrogen Propulsion Partnership | Naval primes align with EU Green Deal incentives to open maritime modernization pathways under sustainable manufacturing disclosures. |
| STANAG Certification Capability Acquisition | Mid-tier players capture value via interoperability testing infrastructure required for software-defined system fielding. |
| Predictive Maintenance Algorithm Validation | Research institution consortia secure multi-year availability contracts through Bundeswehr and Armée de Terre adoption. |
Research Methodology
Document review covered EDA capability-development targets, NATO STANAG certification protocols, and EU Green Deal carbon-accounting rulemakings, complemented by interviews with defense procurement officers at national ministries, platform engineering directors at continental primes, and supply chain managers at tier-two subsystem suppliers. Secondary validation drew from ECHA substance restriction databases, PESCO project disclosure filings, and national cyber command specification documents. Bottom-up platform economics modeling triangulated against top-down NATO capability-gap assessments.
Cross-referencing historical procurement cycle patterns with expert panel input on software-defined system adoption timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user archetype, technology layer, and application mission profile, with sovereign specification requirements and interoperability mandate tiers as defense-specific overlays. CAGRs were derived from capability-investment trajectory analysis and collaborative framework funding allocation trends, incorporating AI-enabled electronic warfare fielding schedules and Green Deal compliance cost curves as industry-specific inputs.
Inputs from EDA collaborative procurement databases and NATO capability-target documentation were available through the study window; gaps in classified program budget disaggregation and classified threat-intelligence subscription pricing introduce uncertainty bands around software-layer revenue projections. Deviation in PESCO funding allocation ratios versus national sovereignty priorities would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Explosive Ordnance Disposal Market
Defense and Military Systems and Equipment
Soldier System Market
Defense and Military Systems and Equipment
Military Embedded System Market
Defense and Military Systems and Equipment
Military Actuators Market
Defense and Military Systems and Equipment
Cognitive Electronic Warfare System Market
Defense and Military Systems and Equipment
Counter-IED Systems Market
Defense and Military Systems and Equipment
Military Laser Systems Market
Defense and Military Systems and Equipment
Mechanical and Electronic Fuzes Market
Defense and Military Systems and Equipment
United States Defense Market
Defense and Military Systems and Equipment
Search and Rescue Equipment Market
Defense and Military Systems and Equipment
Europe Defense Logistics Market
Defense and Military Systems and Equipment
Radar Warning Receiver Market
Defense and Military Systems and Equipment
Anti-Drone Guns Market
Defense and Military Systems and Equipment
Bio-Defense Market
Defense and Military Systems and Equipment
Military Rifle Market
Defense and Military Systems and Equipment
Military Parachute Market