
 United Kingdom Defense Market | 2026-2036
United Kingdom Defense Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Defense Market Analytics
Composite armor materials are replacing traditional steel plate in vehicle protection systems, which is recalibrating cost structures across land platforms. BAE Systems plc leverages its Glasgow shipyards and Barrow-in-Furness submarine facilities to anchor UK naval production. Rolls-Royce dominates nuclear propulsion reactor design and manufacturing for the Dreadnought-class ballistic missile submarines. Thales Group competes in electronic warfare and sensor integration for both air and naval programs.
The United Kingdom Defense sector encompasses military equipment, services, and technologies designed to protect national security interests and project strategic power, spanning platforms that must operate across electromagnetic spectrum frequencies from 2 MHz to 40 GHz for communications and radar functions. Air Systems within the product type category leads current procurement volume through the Tempest future combat aircraft program and F-35 Lightning II commitments, while Cyber Security represents the fastest-expanding segment as the National Cyber Force expands operational mandates. Within the technology dimension, Artificial Intelligence is displacing legacy command-and-control architectures across RAF and Royal Navy platforms, concentrating R&D investment and margin pools around autonomous decision-support systems.
The Ministry of Defence's Defence and Security Industrial Strategy shapes supplier selection criteria and sovereign capability requirements, while the Strategic Defence Review process determines multi-year equipment budgets that lock in demand patterns. The UK Cyber Security Council and National Cyber Security Centre establish professional standards and threat frameworks that dictate product certification pathways for defense technology vendors. Stakeholders must monitor how the next spending review reconciles nuclear modernization commitments with conventional force investments across all service branches.
Market Dynamics
The Ministry of Defence's Integrated Review Refresh is compressing multi-year equipment budgets into prioritized capability pillars, forcing trade-offs between nuclear submarine modernization and conventional force readiness across all three services.
Growth Catalysts
- Defence Industrial Strategy:The Ministry of Defence's sovereign capability requirements are mandating domestic procurement preferences for sensitive technologies, redirecting contract flows toward UK-based suppliers.
- Scotland's central belt:Submarine and shipbuilding activity clusters around Glasgow and Faslane are concentrating skilled labor pools and supplier networks, creating localized economies of scale in naval production.
- Artificial Intelligence:Autonomous decision-support systems are absorbing legacy command-and-control architectures across RAF and Royal Navy platforms, opening new R&D investment channels.
Market Restraints
- Specialized steel alloys:Naval-grade steel plate supply concentrates among a handful of European mills, exposing shipbuilding programs to input cost volatility and delivery timeline risk.
- Strategic Defence Review cycles:Five-year equipment plan lock-ins create procurement inflexibility, preventing rapid budget reallocation when threat priorities shift mid-cycle.
- Composite armor substitution:Ceramic and polymer matrix materials are displacing traditional steel in vehicle protection systems, forcing capital retooling at legacy foundries.
Strategic Opportunities
- Cyber Security Council certification pathways:Professional standards mandates for defense technology vendors are creating first-mover advantages for accredited suppliers.
- Electromagnetic spectrum convergence:Platforms operating across 2 MHz to 40 GHz frequencies are driving integrated communications-radar system demand, collapsing previously separate procurement categories.
- Barrow-in-Furness:Nuclear propulsion reactor manufacturing concentration is attracting specialized component suppliers to co-locate, deepening the submarine industrial base.
Industry Challenges
- Nuclear engineering talent pipeline:Reactor design and manufacturing skills are aging out faster than apprenticeship programs can replenish, constraining Dreadnought-class production timelines.
- Legacy platform integration:Artificial Intelligence insertion into existing RAF and Royal Navy systems requires extensive software architecture rework, extending development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Defense Market |
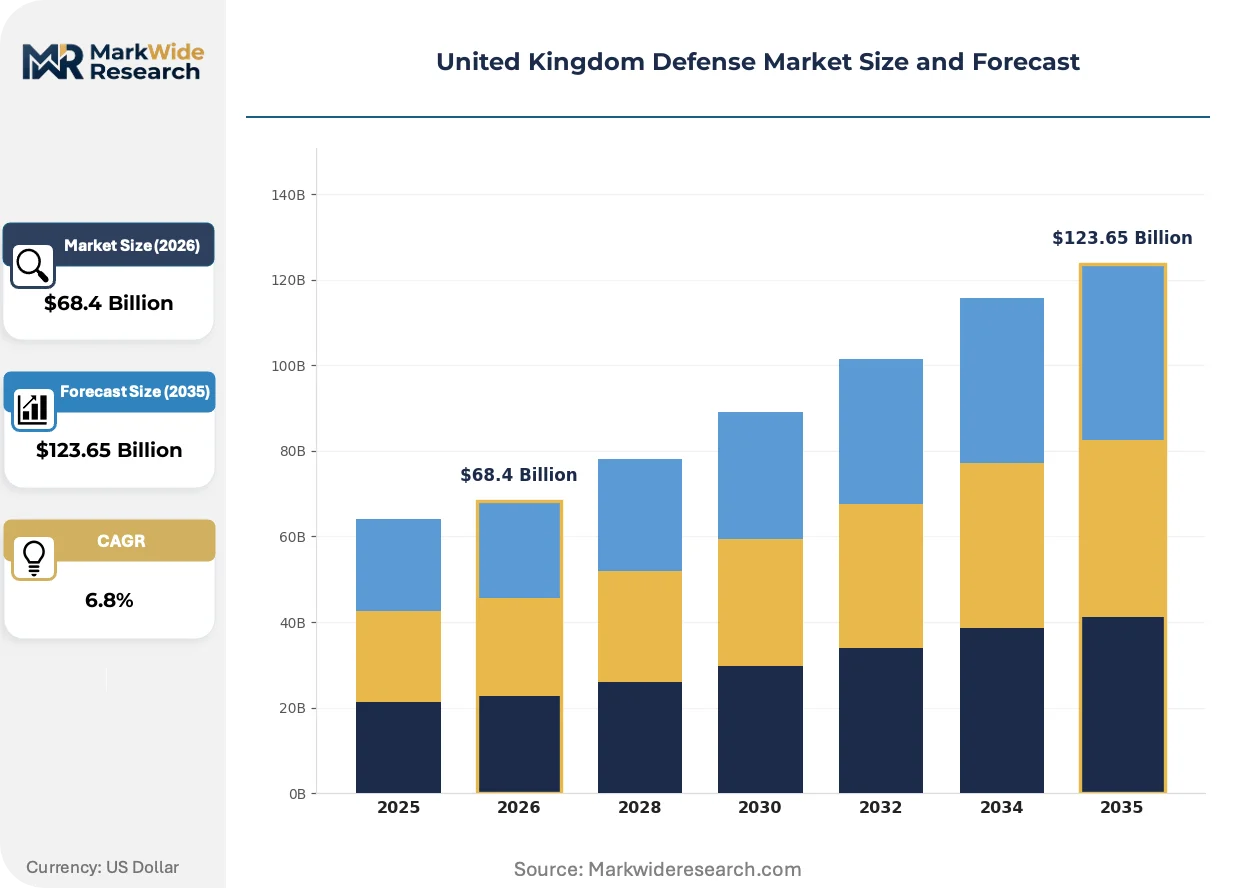
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Land Systems, Naval Systems, Air Systems, Cyber Security End User: Military, Government Agencies, Defense Contractors, Research Institutions Technology: Artificial Intelligence, Robotics, Communication Systems, Surveillance Service Type: Maintenance, Training, Logistics, Consulting |
| Companies Covered | BAE Systems plc, Babcock International Group PLC, QinetiQ Limited, Leonardo S.p.A., Thales Group, Rolls-Royce, Chemring, Lockheed Martin, Airbus, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Defense Market Evolving Landscape
Digital engineering practices are collapsing traditional development timelines across UK defense programs, compressing design-to-field intervals while raising interoperability standards for multi-domain operations.
Composite armor materials are absorbing ballistic protection functions previously assigned to rolled homogeneous steel, enabling lighter vehicle platforms without sacrificing crew survivability. The British Army's mechanized infantry vehicle programs are specifying ceramic matrix composites for underbody blast protection, shifting supplier qualification requirements toward materials science specialists. This transition is absorbing margin pools from traditional steel foundries and redirecting them toward advanced manufacturing facilities.
The National Cyber Security Centre's threat frameworks are mandating product certification pathways that vendors must complete before Ministry of Defence contract eligibility. These professional standards are compressing supplier onboarding timelines while raising compliance costs for smaller technology entrants. Cyber Security Council accreditation is becoming a gatekeeping mechanism for software and hardware procurement across all service branches.
Platform-as-a-service contracting is displacing traditional capital acquisition models for non-core capabilities, transferring lifecycle risk to prime contractors. The Royal Navy's unmanned surface vessel trials are pioneering availability-based payment structures, where contractors retain ownership and charge for operational hours. This pattern is most visible in maritime surveillance and electronic warfare domains, where technology refresh cycles outpace conventional depreciation schedules.
United Kingdom Defense Market Segmentation
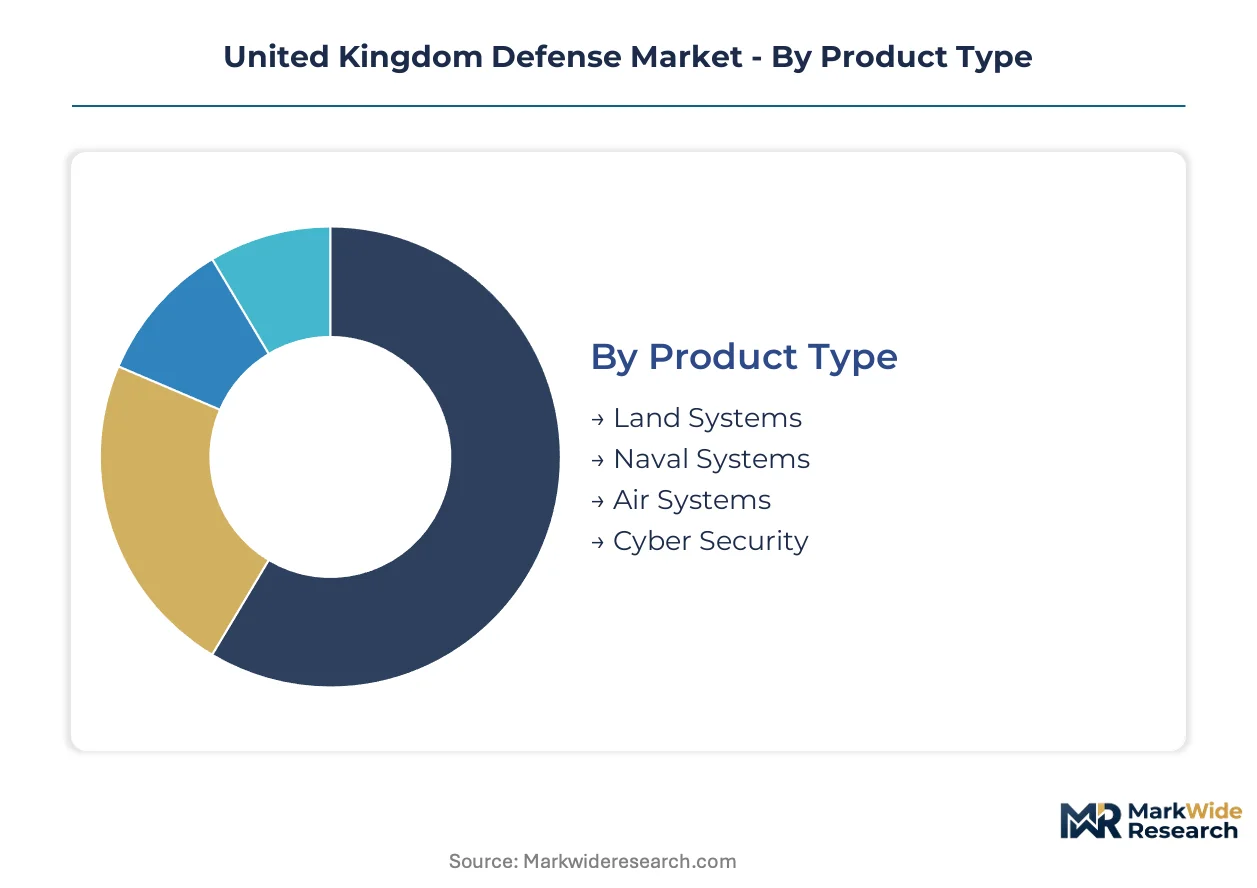
Segmentation in UK defense procurement reveals how certification requirements from the Ministry of Defence, National Cyber Security Centre, and UK Cyber Security Council create divergent compliance burdens across supplier tiers. Understanding these pathways determines contract eligibility and margin capture for vendors competing across land, naval, air, and cyber domains.
Product Type:
Cyber Security Council accreditation and NCSC threat framework compliance impose the steepest certification requirements on software-intensive segments, while physical platforms face sovereign manufacturing mandates under the Defence Industrial Strategy.
- Air Systems:Combat aircraft and unmanned aerial platforms integrate electronic warfare suites operating across 2 MHz to 40 GHz spectrum bands. Procurement concentrates around the Tempest future combat aircraft program and F-35 Lightning II commitments, absorbing the largest share of multi-year equipment budgets.
- Naval Systems:Submarine modernization programs including Dreadnought-class ballistic missile submarines drive demand for nuclear-grade components. Production clusters around Barrow-in-Furness and Glasgow's central belt, where skilled labor pools and specialized suppliers have co-located.
- Land Systems:Mechanized infantry vehicles specify ceramic matrix composites for underbody blast protection, displacing traditional rolled homogeneous steel. British Army modernization programs are redirecting supplier qualification toward materials science specialists.
- Cyber Security:National Cyber Force operational expansion is accelerating demand for threat detection, secure communications, and zero-trust architectures. NCSC certification pathways gate Ministry of Defence contract eligibility for software and hardware vendors.
Leading the category by volume: Air Systems. Growing fastest: Cyber Security.
End User:
Contracting authority determines procurement flexibility, with direct Ministry of Defence acquisitions facing stricter sovereign capability requirements than subcontractor flows.
- Military:Royal Navy, British Army, and Royal Air Force operate as consolidated demand centers with locked five-year equipment plans. Strategic Defence Review cycles constrain rapid budget reallocation even when threat priorities shift.
- Defense Contractors:Prime contractors including BAE Systems and Rolls-Royce subcontract specialized components while retaining lifecycle risk under platform-as-a-service models. Tier-2 and tier-3 suppliers compete for accreditation-driven qualification slots.
- Government Agencies:National Cyber Security Centre and UK Cyber Security Council establish professional standards that cascade through all service branch procurement. Agency mandates compress supplier onboarding timelines.
- Research Institutions:Defence Science and Technology Laboratory and university-affiliated centers drive artificial intelligence and autonomous systems R&D. Funding flows concentrate around dual-use technology transfer programs.
Capturing highest contract value: Military. Expanding procurement flexibility fastest: Defense Contractors.
Technology:
Technology maturity curves determine whether segments absorb investment or face displacement by adjacent capabilities.
- Artificial Intelligence:Autonomous decision-support systems are replacing legacy command-and-control architectures across RAF and Royal Navy platforms. Integration into existing systems requires extensive software architecture rework.
- Surveillance:Integrated communications-radar systems collapse previously separate procurement categories as platforms converge across electromagnetic spectrum frequencies. Maritime surveillance programs pioneer availability-based payment structures.
- Robotics:Unmanned surface vessel trials transfer lifecycle risk to prime contractors through platform-as-a-service contracting. Royal Navy experimentation is validating operational concepts before scale procurement.
- Communication Systems:Secure datalinks and software-defined radios must interoperate across multi-domain operations. Digital engineering practices are compressing traditional development timelines.
Absorbing R&D investment most intensively: Artificial Intelligence. Steepest expansion trajectory: Surveillance.
Service Type:
Service contracting models are shifting from capital acquisition to outcome-based availability payments, redistributing risk across the supply chain.
- Maintenance:Through-life support contracts for nuclear submarines and combat aircraft lock in decades-long revenue streams. Specialized engineering talent constraints limit supplier pool expansion.
- Logistics:Supply chain resilience mandates under the Defence Industrial Strategy prioritize domestic warehousing and distribution networks. Platform-as-a-service models transfer inventory risk to contractors.
- Training:Synthetic training environments reduce live-fly and live-fire exercise costs. RAF and Royal Navy simulation programs integrate artificial intelligence for adaptive scenario generation.
- Consulting:Strategic advisory services support Strategic Defence Review preparation and capability trade-off analysis. Demand fluctuates with review cycle timing.
Generating longest contract tenures: Maintenance. Gaining share fastest: Logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement concentrates in Scotland's central belt, where submarine and shipbuilding activity clusters around Glasgow and Faslane. The Ministry of Defence's sovereign capability requirements redirect contract flows toward UK-based suppliers. Industrial specialization deepens in nuclear propulsion and advanced naval systems.
Scotland
The Dreadnought-class ballistic missile submarine program drives nuclear-grade component demand around Barrow-in-Furness and Faslane. HM Naval Base Clyde anchors the UK's continuous at-sea deterrent. Glasgow's central belt concentrates skilled labor pools and supplier networks for naval production.
North West England
Barrow-in-Furness hosts the UK's sole nuclear submarine construction facility. Rolls-Royce reactor manufacturing attracts specialized component suppliers to co-locate. The Ministry of Defence's Defence Industrial Strategy prioritizes this region for sovereign submarine capability.
South West England
HMNB Devonport handles submarine maintenance and refit operations. Babcock International Group PLC operates the UK's sole nuclear dockyard. The National Cyber Security Centre in Cheltenham establishes threat frameworks cascading through service branch procurement.
South East England
RAF bases and Defence Science and Technology Laboratory facilities concentrate R&D investment. QinetiQ Limited operates test and evaluation ranges. The UK Cyber Security Council shapes professional standards for defense technology vendors.
United Kingdom Defense Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with primes retaining lifecycle risk under platform-as-a-service models while tier-2 suppliers compete for accreditation-driven qualification slots. The vendor structure organizes around three archetypes: integrated primes controlling nuclear and air platforms, mid-tier specialists in electronic warfare and sensors, and materials-science entrants displacing legacy foundries. Competitive moves concentrate on sovereign capability partnerships and digital engineering capability acquisition.
Within the integrated prime tier, BAE Systems plc and Rolls-Royce anchor UK naval and aerospace production. BAE Systems leverages Glasgow shipyards and Barrow-in-Furness submarine facilities to represent sovereign manufacturing mandates. Rolls-Royce occupies a position in nuclear propulsion reactor design. Thales Group exemplifies the mid-tier specialist archetype in electronic warfare and sensor integration.
| Leading Market Players |
|---|
| BAE Systems plc |
| Babcock International Group PLC |
| QinetiQ Limited |
| Leonardo S.p.A. |
| Thales Group |
| Rolls-Royce |
| Chemring |
| Lockheed Martin |
| Airbus |
| Others |
Value Network & Pricing Analysis
The Ministry of Defence's sovereign capability mandates under the Defence Industrial Strategy are compressing supplier pools toward UK-based accreditation holders, forcing tier-2 and tier-3 vendors to absorb compliance costs or exit. This demand-side consolidation is reshaping margin distribution across naval steel, nuclear components, and cyber certification pathways.
Pricing Analysis
High-volume naval platforms absorb capital-intensive production cycles with thin margins, while cyber security and AI-enabled subsystems capture disproportionate value through recurring certification and software refresh revenues. Price differentiation hinges on NCSC accreditation tier and sovereign manufacturing compliance rather than unit scale alone. Pricing pressure stems from the Strategic Defence Review's five-year budget lock-ins, which prevent mid-cycle reallocation when input costs spike. Tier-1 primes exhibit lowest price sensitivity due to through-life service contracts, whereas materials suppliers face acute margin compression from composite armor substitution.
Supply Chain Analysis
Dual-sourcing requirements for nuclear-grade steel alloys and reactor components mandate qualification across UK and French mills, though actual production concentrates in Sheffield, Rotherham, and a handful of continental European foundries. The supply chain draws from specialized inputs including naval-grade steel plate, ceramic matrix composites for vehicle protection, and radiation-hardened electronics for submarine systems. Single-source vulnerability runs through Rolls-Royce's monopoly on reactor design and the aging nuclear engineering talent pipeline. Distribution runs through Ministry of Defence prime contracting with BAE Systems and Babcock, cascading to tier-2 specialists via accreditation-gated subcontracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom Defense Market is becoming a vertical-integration race, with primes capturing reactor manufacturing and digital engineering capabilities to lock out specialized entrants. Sovereign capability mandates are the downstream lever accelerating this consolidation.
For Market Incumbents: Anticipate composite armor substitution displacing traditional steel foundries by accelerating materials science partnerships or captive ceramic matrix composite production. Secure nuclear engineering talent through apprenticeship pipeline investments before demographic retirement peaks constrain Dreadnought-class timelines. Platform-as-a-service contracting models transfer lifecycle risk but require balance sheet capacity that tier-2 suppliers lack. For New Entrants and Emerging Players: The mid-tier price-point gap between NCSC-accredited cyber vendors and uncertified software houses offers entry through accelerated certification investment targeting National Cyber Force operational expansion. White-space concentrates in electromagnetic spectrum convergence technologies integrating communications-radar functions, where procurement categories are collapsing. Go-to-market through Defence and Security Accelerator programs bypasses traditional prime contractor gatekeeping. For Investors and Strategic Acquirers: The window for entry favors mid-tier specialists with existing NCSC or Cyber Security Council accreditation, as compliance timelines now exceed 18 months for new entrants. Long-term viability rests on positioning ahead of the next Strategic Defence Review cycle, when artificial intelligence and autonomous systems mandates will reshape procurement priorities. Watch for Ministry of Defence platform-as-a-service contract awards as the inflection signal for availability-based revenue models displacing capital acquisition.| Strategic Initiative | Industry Significance |
|---|---|
| NCSC Certification Fast-Track | Accelerated accreditation compresses supplier onboarding timelines for National Cyber Force procurement. |
| Nuclear Talent Pipeline Investment | Apprenticeship programs at Barrow-in-Furness secure reactor manufacturing capacity for Dreadnought-class delivery. |
| Ceramic Matrix Composite Capacity | Domestic production of blast protection materials displaces steel foundry dependence for British Army vehicles. |
| Platform-as-a-Service Contracting | Availability-based payment structures transfer lifecycle risk from Ministry of Defence to prime contractors. |
| Electromagnetic Spectrum Integration | Unified communications-radar systems collapse separate procurement categories across RAF and Royal Navy platforms. |
Research Methodology
Document review covered Ministry of Defence equipment plans, National Cyber Security Centre threat frameworks, and Defence Industrial Strategy policy papers, complemented by interviews with naval program directors, cyber security procurement officers, and nuclear engineering specialists at Barrow-in-Furness and Faslane. Secondary validation drew from parliamentary defense committee reports, Strategic Defence Review documentation, and UK Cyber Security Council accreditation records. Bottom-up platform deployment data and top-down budget allocation analysis were triangulated to reconcile supply-side capacity with demand-side procurement commitments.
Market sizing outputs reflect segment-level modeling across air, naval, land, and cyber systems, with technology trajectories for artificial intelligence, surveillance, and autonomous platforms tracked throughout the forecast period. CAGRs were derived from equipment plan lock-ins, nuclear modernization timelines, and cyber force expansion mandates. Segmentation dimensions included product type, end user contracting authority, technology maturity, and service delivery model, with regional concentration around Scotland's central belt and South West England explicitly incorporated.
Inputs from Ministry of Defence spending reviews and National Cyber Security Centre certification databases were available through the study window; gaps in classified submarine program cost data and artificial intelligence integration timelines introduce uncertainty bands around out-year projections. Deviation in Strategic Defence Review timing or nuclear engineering talent availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Military Phased Array Antenna Market
Defense and Military Systems and Equipment
Europe Defense Market
Defense and Military Systems and Equipment
Military Helmet and Helmet Mounted Displays Market
Defense and Military Systems and Equipment
Global Digital Battlefield Market
Defense and Military Systems and Equipment
Mergers and Acquisitions (Manda) in Aerospace and Defense Market
Defense and Military Systems and Equipment
Defense Integrated Antenna Market
Defense and Military Systems and Equipment
Global Military Laser Rangefinder Market
Defense and Military Systems and Equipment
Mission Management System Market
Defense and Military Systems and Equipment
Command and Control Systems Market
Defense and Military Systems and Equipment
Cognitive Electronic Warfare System Market
Defense and Military Systems and Equipment
Mine Clearance System Market
Defense and Military Systems and Equipment
Anti-Drone Guns Market
Defense and Military Systems and Equipment
Military Load Carriage System Market
Defense and Military Systems and Equipment
Global Non Lethal Biochemical Weapon Market
Defense and Military Systems and Equipment
Smart War Weapon Market
Defense and Military Systems and Equipment
Airborne Electronic Warfare Market