
 Anti-Drone Guns Market | 2026-2036
Anti-Drone Guns Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Drone Guns Market Insights
The buyer base for anti-drone guns is broadening beyond traditional military customers to include law enforcement agencies and private security contractors at major commercial venues. RTX leverages its radar-integration expertise to bundle detection with defeat capabilities. Lockheed Martin Corporation anchors its position through directed-energy programs targeting swarm threats. DroneShield Ltd specializes in man-portable systems that compete on rapid deployment timelines.
Anti-drone guns are kinetic and non-kinetic devices designed to neutralize unmanned aerial vehicles through radio frequency disruption, laser incapacitation, or directed-energy engagement, typically operating at ranges from several hundred meters to multiple kilometers depending on power output and environmental conditions. These systems serve military, law enforcement, and critical infrastructure operators requiring portable or fixed-site airspace denial against hostile or unauthorized drone incursions. Radio Frequency Jammer units dominate current procurement volumes due to lower per-unit cost and reduced regulatory friction for export licensing. Laser Gun platforms represent the fastest-expanding margin pool as fiber-laser efficiency gains shrink thermal management footprints and extend effective range. Handheld Units across the Deployment dimension occupy the highest growth trajectory among form factors, driven by infantry and tactical police demand for dismounted counter-UAS capability.
The FAA and FCC in the United States restrict frequency bands available for jamming operations, forcing manufacturers to engineer spectrum-agile architectures that comply with civilian communications protections while maintaining threat effectiveness. EASA and national spectrum regulators across Europe enforce comparable constraints under the Radio Equipment Directive and CE marking requirements, elevating compliance costs for market entry. Stakeholders must monitor evolving classification debates over whether anti-drone guns constitute weapons systems or electronic warfare equipment, as this determination shapes export control regimes and domestic deployment authorities.
Market Dynamics
Spectrum fragmentation between military and civilian frequency allocations is forcing manufacturers to engineer modular jamming architectures that can reconfigure for NATO interoperability, FCC compliance, and export licensing constraints without hardware redesign.
Growth Catalysts
- Swarm threat proliferation:Military operators in conflict zones now face coordinated multi-drone attacks that exceed the capacity of single-target systems, driving procurement of multi-beam RF jammers and rapid-fire directed-energy platforms.
- Critical infrastructure hardening:Power utilities and data center operators across the United States are deploying handheld units under FAA-coordinated airspace protection programs to guard against reconnaissance and payload delivery.
- Fiber-laser efficiency gains:Solid-state laser sources now achieve 40% wall-plug efficiency, shrinking thermal management footprints and extending engagement ranges without the ammunition logistics burden of kinetic interceptors.
Market Restraints
- Gallium nitride component concentration:High-power RF amplifiers depend on GaN substrates sourced primarily from East Asian foundries, creating single-source vulnerability for jammer manufacturers.
- FCC frequency-use restrictions:Civilian jamming prohibitions under US Code Title 47 limit domestic law enforcement deployment to federal waiver holders, constraining addressable market expansion.
- Directed-energy atmospheric degradation:Laser and microwave weapons suffer 30-50% effectiveness loss in rain, dust, or fog, limiting all-weather reliability against time-critical threats.
Strategic Opportunities
- India border security modernization:The country's defense procurement is accelerating counter-UAS trials along Himalayan and desert frontiers, creating demand for man-portable systems compatible with existing small-arms logistics.
- EU Green Deal defense exemption pathway:Military procurement is receiving streamlined environmental compliance waivers, reducing certification timelines for battery-powered handheld units versus vehicle-mounted diesel generators.
- RF-laser convergence architectures:Hybrid systems combining software-defined radio jamming with low-power laser dazzlers are expanding into VIP protection details where collateral damage minimization outweighs unit cost.
Industry Challenges
- Spectrum engineering talent scarcity:The intersection of microwave engineering, digital signal processing, and thermal management requires specialists rarely produced by standard electrical engineering curricula.
- CE marking timeline compression:EASA and national regulators are extending electromagnetic compatibility testing requirements for counter-UAS equipment, stretching product launch schedules by 8-14 months.
- Legacy radar integration complexity:Fixed-site detection networks from 1990s-era air defense systems lack data interfaces compatible with modern jamming cueing protocols, forcing expensive gateway development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Drone Guns Market |
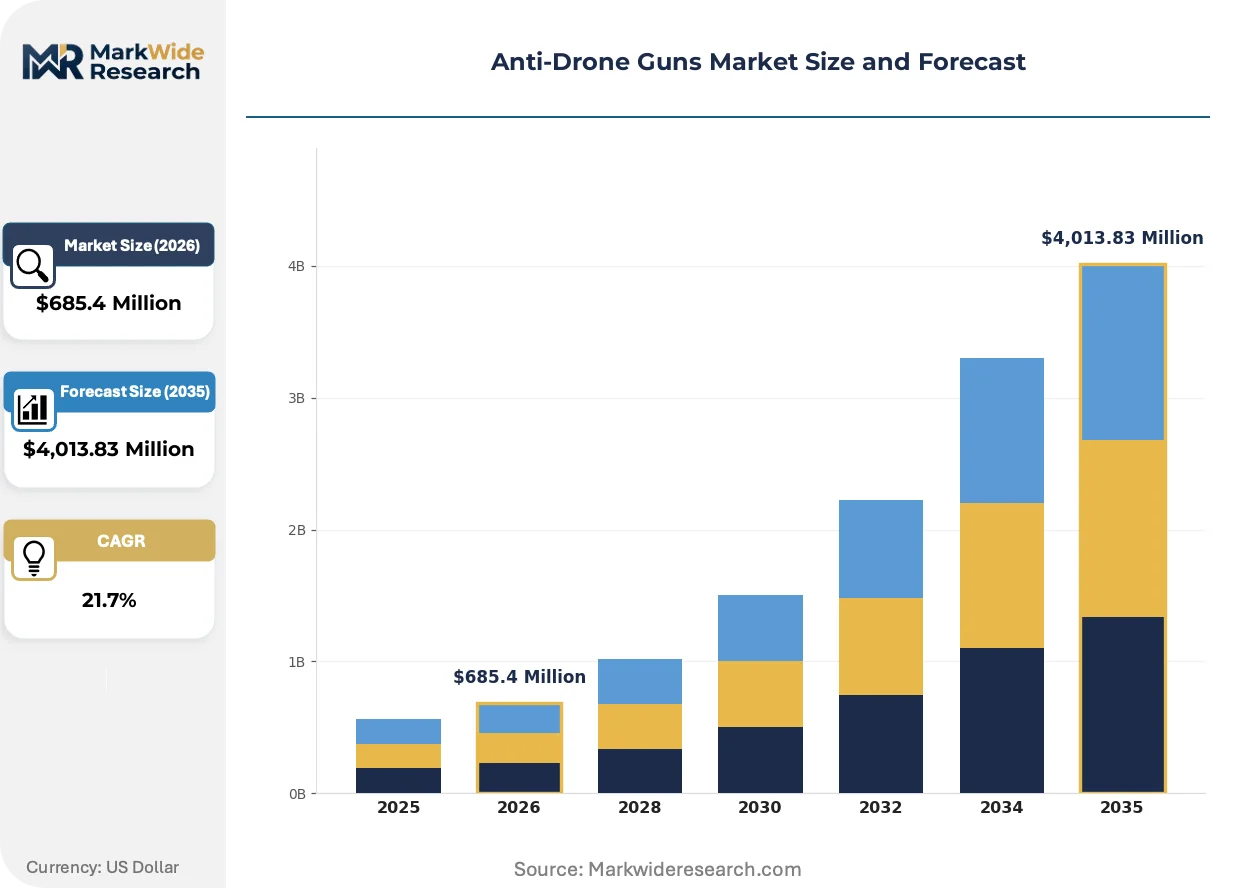
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $4,013.83 Million |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radio Frequency Jammer, Laser Gun, Microwave Emitter, Acoustic Device, Directed Energy Weapon Deployment: Mobile Systems, Fixed Installations, Handheld Units, Vehicle-Mounted Solutions Application: Border Security, Event Protection, Critical Infrastructure Defense, VIP Protection, Maritime Surveillance End User: Military Forces, Law Enforcement, Private Security Companies, Infrastructure Operators, Event Management Organizations |
| Companies Covered | RTX, Lockheed Martin Corporation, Rafael Advanced Defense Systems, Israel Aerospace Industries, Thales Group, Saab, Leonardo S.p.A., DroneShield Ltd, Dedrone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Drone Guns Market Trends and Innovations
Active electronically scanned array technology is migrating from radar into jamming apertures, enabling simultaneous multi-target engagement without mechanical steering delays. This shift is compressing reaction timelines against drone swarms.
Solid-state phased arrays are expanding into handheld form factors previously dominated by mechanically steered dish antennas. Infantry units in NATO member states are field-testing these units for dismounted counter-UAS capability. The technology is expanding into squad-level operations by eliminating moving parts and reducing power draw below 500 watts.
The EU AI Act's risk classification framework is capturing autonomous targeting algorithms under high-risk system requirements. Manufacturers must now document decision logic for engagement authorization, adding software verification costs. Military procurement channels are responding by segregating human-in-the-loop variants for European deployment from fully automated export configurations.
Leasing arrangements for temporary event security are displacing capital purchases among stadium operators and festival organizers. Rental providers in the United States are building fleet inventories of FCC-certified handheld units. This model concentrates most visibly in Texas and California where large outdoor venues face seasonal drone incursion spikes.
Anti-Drone Guns Market Segmentation
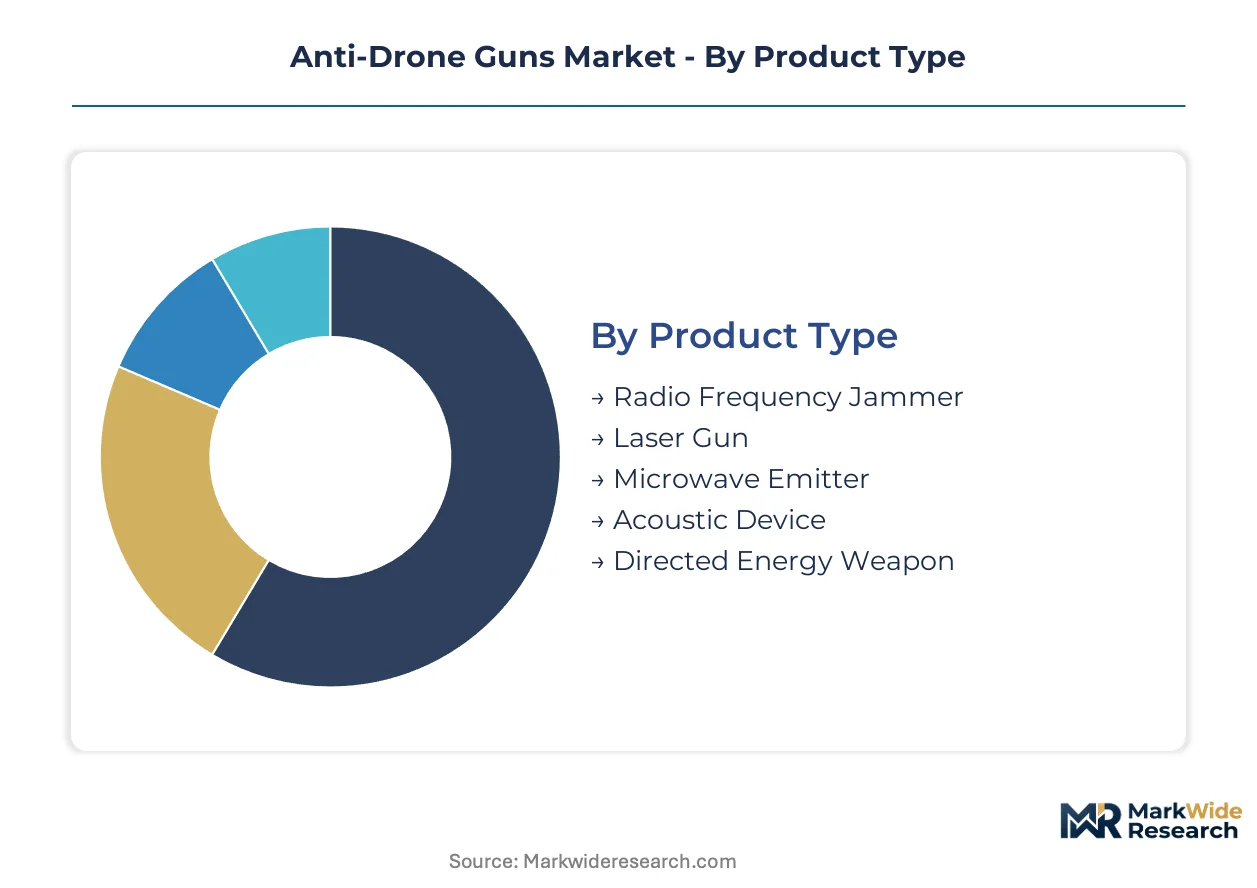
Segmentation in the anti-drone guns market reveals distinct procurement patterns across product architectures and operational contexts. Each dimension carries implications for regulatory compliance, integration complexity, and total cost of ownership.
Product Type:
Supply concentration in high-power RF components shapes competitive positioning across product categories.
- Radio Frequency Jammer:These systems disrupt drone command links through targeted spectrum interference, typically operating across 400 MHz to 6 GHz bands. Military procurement across NATO members concentrates demand for multi-band units capable of simultaneous threat neutralization. FCC and FAA frequency restrictions in the United States constrain civilian variants to federal waiver holders.
- Laser Gun:Fiber-laser platforms achieve engagement through thermal damage to airframe structures or electro-optical sensors. Solid-state efficiency gains now reach 40% wall-plug conversion, shrinking thermal management requirements for infantry-portable designs. Demand clusters in critical infrastructure defense where ammunition logistics present operational burdens.
- Microwave Emitter:High-power microwave systems generate electromagnetic pulses to disable electronics through front-door coupling.
- Acoustic Device:Sonic disruption platforms interfere with gyroscopic stabilization through resonant frequency targeting.
- Directed Energy Weapon:Integrated high-energy laser and microwave architectures address hardened or swarm-configured threats.
Radio Frequency Jammers absorb the bulk of installed capacity; Laser Guns are expanding most quickly.
Deployment:
Cost tier differentiation separates capital-intensive fixed installations from rapidly deployable alternatives.
- Handheld Units:Man-portable systems under 15 kg enable dismounted counter-UAS capability for infantry and tactical police units. NATO member states are accelerating field trials for squad-level deployment. Battery-powered variants receive streamlined environmental compliance under EU Green Deal defense exemptions.
- Vehicle-Mounted Solutions:These platforms integrate detection and defeat capabilities onto tactical vehicles, drawing power from onboard generators. Border security modernization in India drives demand for systems compatible with existing small-arms logistics chains.
- Mobile Systems:Trailer or containerized configurations enable rapid repositioning between threat vectors.
- Fixed Installations:Permanent-site deployments protect critical infrastructure through layered defense architectures.
Fixed Installations retain the largest installed base; Handheld Units are climbing the fastest.
Application:
Customer type concentration distinguishes sovereign security applications from commercial venue protection.
- Critical Infrastructure Defense:Power utilities and data center operators deploy layered counter-UAS systems under FAA-coordinated airspace protection programs. Procurement emphasizes all-weather reliability and minimal collateral interference with civilian communications.
- Event Protection:Stadium operators and festival organizers in Texas and California are shifting from capital purchases to leasing arrangements for seasonal demand spikes. Rental fleet buildouts concentrate around FCC-certified handheld units.
- Border Security:Sovereign perimeter defense applications demand extended-range detection and engagement.
- VIP Protection:Executive security details prioritize collateral damage minimization over unit cost considerations.
- Maritime Surveillance:Naval and coast guard applications address drone threats to vessels and offshore installations.
Critical Infrastructure Defense commands the dominant procurement volume; Event Protection is gaining share fastest.
End User:
Maturity gradients separate established military procurement channels from emerging commercial adopters.
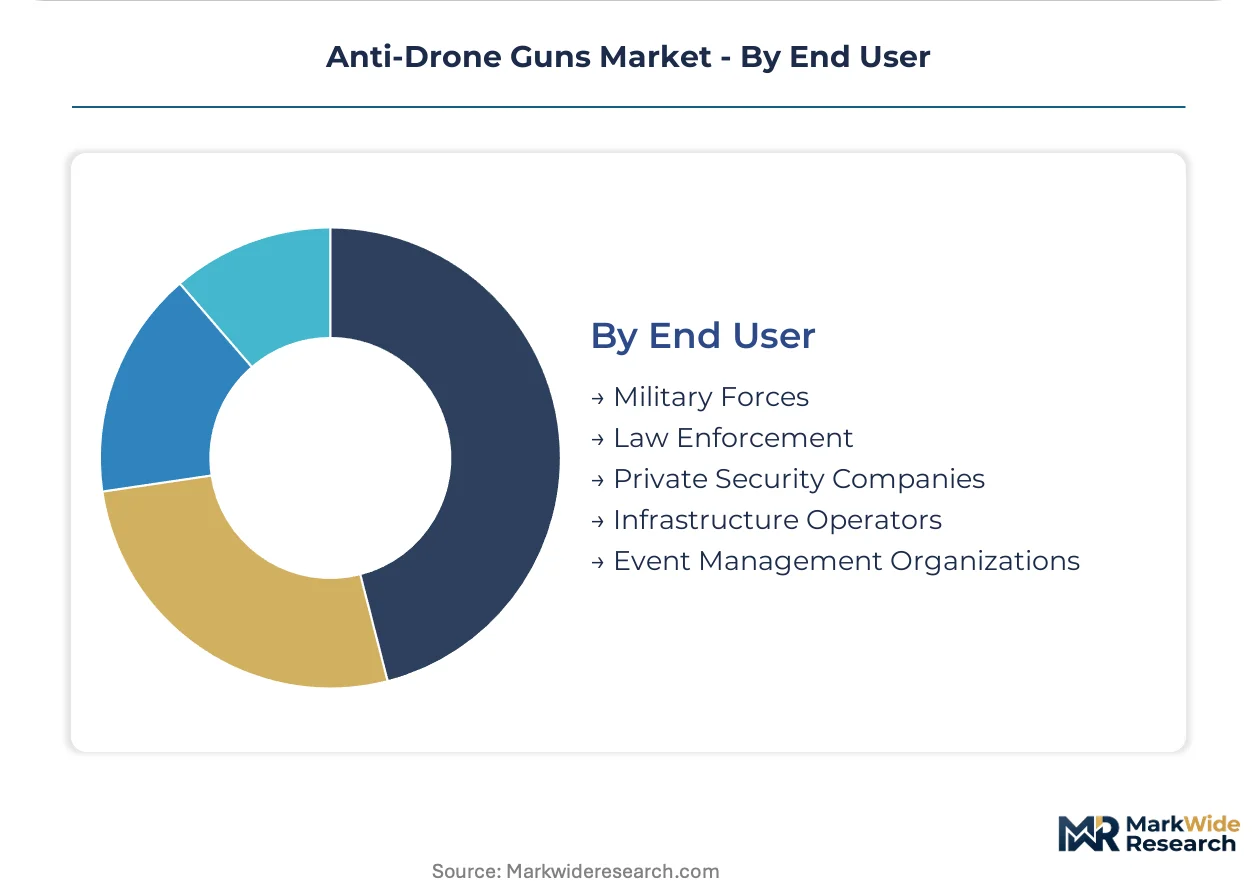
- Military Forces:Defense procurement budgets across NATO members prioritize multi-beam RF jammers and rapid-fire directed-energy platforms for swarm threat engagement. Classification debates over weapons versus electronic warfare status shape export control compliance.
- Law Enforcement:Police agencies face FCC restrictions limiting domestic jamming deployment to federal waiver holders, constraining addressable market expansion despite operational demand.
- Private Security Companies:Commercial contractors at major venues drive handheld unit adoption where federal coordination enables lawful deployment.
- Infrastructure Operators:Utility and data center security teams procure under FAA-coordinated programs with standardized certification requirements.
- Event Management Organizations:Temporary security providers build rental fleets for seasonal outdoor venue protection.
Military Forces account for the preponderance of current procurement; Private Security Companies are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gallium nitride substrate production concentrates in East Asian foundries, creating single-source vulnerability for RF amplifier manufacturers while shaping procurement security strategies across NATO member states.
United States
Federal agencies are expanding domestic airspace protection programs for critical infrastructure operators. The FCC and FAA impose strict frequency-use rules under US Code Title 47 that limit civilian jamming deployment to federal waiver holders. Texas and California host the largest rental fleet buildouts for seasonal outdoor venue protection.
Germany
Bundeswehr procurement prioritizes multi-beam RF jammers for swarm threat engagement alongside NATO interoperability requirements. CE marking under the Radio Equipment Directive and electromagnetic compatibility testing extend product launch schedules. Bavaria-based defense contractors anchor continental European production capacity.
India
Border security modernization drives counter-UAS trials along Himalayan and desert frontiers with demand for man-portable systems compatible with small-arms logistics. The country's defense procurement acceleration supports sovereign perimeter defense applications. Domestic production incentives align with Make in India localization mandates.
United Kingdom
Royal Air Force and police agencies coordinate layered defense architectures for critical national infrastructure. Classification debates over weapons versus electronic warfare status shape export control compliance frameworks. Southeast England clusters specialist contractors serving NATO procurement channels.
Israel
Directed-energy programs targeting swarm threats benefit from concentrated microwave engineering expertise and dual-use technology development. National spectrum regulators enforce civilian communications protections while maintaining threat effectiveness. Tel Aviv metropolitan area hosts integrated high-energy laser and microwave architecture specialists.
Anti-Drone Guns Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in directed-energy and acoustic disruption. The supplier base stratifies across defense prime contractors with radar-integration expertise, specialist counter-UAS pure-plays, and RF component manufacturers with jamming-aperture capabilities. Three archetypes dominate: systems integrators bundling detection with defeat, component specialists supplying high-power amplifiers, and portable-system innovators competing on rapid deployment timelines. Competitive moves concentrate on strategic partnerships for spectrum-agile architectures and geographic expansion into Indo-Pacific border security programs.
Among defense prime contractors, RTX and Lockheed Martin Corporation exemplify systems-integration archetypes, while DroneShield Ltd occupies a position within the portable-system specialist tier. These entities represent contrasting strategic postures: the former anchor layered defense architectures through radar and directed-energy convergence, while the latter competes on dismounted counter-UAS capability for tactical police and infantry applications.
| Leading Market Players |
|---|
| RTX |
| Lockheed Martin Corporation |
| Rafael Advanced Defense Systems |
| Israel Aerospace Industries |
| Thales Group |
| Saab |
| Leonardo S.p.A. |
| DroneShield Ltd |
| Dedrone |
| Others |
Pricing and Supply Chain Analysis
Specialist microwave engineering talent concentrated in Tel Aviv and Southeast England drives labor-cost differentials that widen pricing-tier spreads between defense-prime systems and emerging portable alternatives.
Pricing Analysis
Volume concentrates in radio frequency jammers while margin pools shift toward laser platforms. Three-tier pricing structure across military-specification, law enforcement-certified, and commercial-rental levels separates NATO-interoperable systems from FCC-waiver-limited variants. Cost compression in handheld RF units intensifies because GaN amplifier sourcing bottlenecks constrain supply elasticity. Private security contractors exhibit highest price sensitivity; military procurement offices prioritize performance over unit cost.
Supply Chain Analysis
GaN substrate supply rests on East Asian foundries in Taiwan, South Korea, and Japan, with fiber-laser diodes drawing from German and US specialty photonics manufacturers. High-power RF amplifiers, solid-state laser sources, and thermal management subsystems anchor component dependencies. Single-source vulnerability in semiconductor substrates creates procurement security exposure for jammer manufacturers. Distribution runs through defense prime contractor integration channels and direct-to-agency procurement for handheld units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained story where GaN component scarcity props pricing across all tiers and limits rapid capacity scaling.
For Market Incumbents: Anchor layered defense architectures through radar-integration partnerships that bundle detection with defeat capabilities. Deepen backward integration into GaN amplifier supply through captive foundry arrangements or long-term offtake agreements with East Asian substrate producers. Lockheed Martin Corporation and RTX exemplify this posture; emerging fiber-laser specialists threaten margin compression in directed-energy segments. For New Entrants and Emerging Players: The $2,000-$15,000 price-point gap between premium military-specification systems and economy-tier rental units opens white-space targets in law enforcement handheld procurement. Event protection leasing in Texas and California presents the most penetrable commercial application. Pursue FCC certification investment as the primary go-to-market angle, as federal waiver eligibility unlocks domestic law enforcement demand. For Investors and Strategic Acquirers: Re-rating potential sits with portable-system specialists given NATO squad-level deployment acceleration and EU Green Deal battery-powered exemptions. Five-to-ten-year viability favors manufacturers with software-defined radio architectures that reconfigure for spectrum fragmentation without hardware redesign. Watch CE marking timeline compression as the inflection signal—regulatory delay reductions indicate supply chain readiness for European volume scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Spectrum-Agile Architecture Development | Enables FCC, EASA, and NATO interoperability without hardware redesign cycles. |
| GaN Supply Chain Security Investment | Reduces single-source vulnerability from East Asian foundry concentration. |
| Directed-Energy Efficiency Advancement | Extends engagement range through fiber-laser wall-plug efficiency gains above 40%. |
| Leasing Fleet Buildout | Captures seasonal event protection demand in Texas and California venue markets. |
| CE Marking Pre-Certification | Compresses EASA electromagnetic compatibility testing timelines by 8-14 months. |
Research Methodology
Independent corroboration across defense procurement officers, RF engineering directors, and critical infrastructure security managers underwrites the qualitative findings. Primary fieldwork encompassed program managers at NATO member defense ministries, FAA airspace protection coordinators, and private security contractors operating major US venues. Secondary validation drew from FCC equipment authorization databases, EASA certification registries, and defense budget appropriation documents. Bottom-up unit shipment estimates triangulated against top-down military expenditure allocations across the analysis window.
Rate-of-change decomposition separated volume growth from price-mix effects across product type, deployment form factor, application, and end-user dimensions. CAGRs were derived from logistic diffusion modeling of technology adoption curves, with swarm-threat incident frequency and fiber-laser efficiency trajectories serving as industry-specific forecast inputs. Segmentation granularity captured handheld versus fixed-installation mix shifts and military-to-commercial buyer migration patterns throughout the projection horizon.
Inputs from defense procurement databases and spectrum regulator filings were available through the study window; gaps in classified program budgets and export-licensing denial records introduce uncertainty bands around military segment estimates. Forecasts reflect documented assumptions regarding NATO interoperability timelines and GaN substrate supply elasticity. Regulatory reclassification of anti-drone guns as weapons versus electronic warfare equipment, plus directed-energy atmospheric degradation in monsoon climates, warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Military Helmet and Helmet Mounted Display Systems Market
Defense and Military Systems and Equipment
Military Software Market
Defense and Military Systems and Equipment
Military Laser Systems Market
Defense and Military Systems and Equipment
Military Phased Array Antenna Market
Defense and Military Systems and Equipment
Global Military Laser Designator Market
Defense and Military Systems and Equipment
India Defense Market
Defense and Military Systems and Equipment
Europe Missiles and Missile Defense Systems Market
Defense and Military Systems and Equipment
Military Actuators Market
Defense and Military Systems and Equipment
Asia-Pacific Digital Battlefield Market
Defense and Military Systems and Equipment
Explosive Ordnance Disposal (EOD) Equipment Market
Defense and Military Systems and Equipment
Defense Integrated Antenna Market
Defense and Military Systems and Equipment
Command and Control Systems Market
Defense and Military Systems and Equipment
Battle Management System (BMS) Market
Defense and Military Systems and Equipment
Mission Management System Market
Defense and Military Systems and Equipment
Airborne Electronic Warfare Market
Defense and Military Systems and Equipment
Smart War Weapon Market