
 Cognitive Electronic Warfare System Market | 2026-2036
Cognitive Electronic Warfare System Market Size, Share, and Industry Trends Forecast 2026-2036
Cognitive Electronic Warfare System Market Analysis
A shortage of radio-frequency engineers with machine learning expertise is redrawing competitive boundaries across the sector. BAE Systems PLC leverages its UK-based defense electronics heritage to sustain long-term military relationships. Northrop Grumman Corporation anchors its position through advanced digital signal processing capabilities. Elbit Systems Ltd. competes aggressively in Israeli and export markets with integrated EW suites.
Cognitive electronic warfare systems employ artificial intelligence and real-time spectrum analysis to detect, classify, and counter dynamic radio-frequency threats without human intervention, typically processing signals across 2 MHz to 40 GHz bands. These platforms serve primarily to neutralize adaptive enemy communications and radar systems that traditional jamming cannot reliably suppress. Jammers and signal processors together capture the dominant share of product-type revenue as legacy hardware refresh cycles coincide with AI retrofit programs. Machine learning and cognitive radio technologies are expanding fastest among technology segments as militaries prioritize autonomous threat response over operator-dependent workflows.
The US Department of Defense imposes strict software assurance and electromagnetic compatibility standards through NIST and MIL-STD frameworks that vendors must satisfy for program eligibility. European procurement follows EDF and NATO STANAG guidelines that increasingly mandate interoperability and sovereign data control across member arsenals. Stakeholders must monitor how export control revisions and classified algorithm certification requirements reshape supplier eligibility and partnership structures.
Market Dynamics
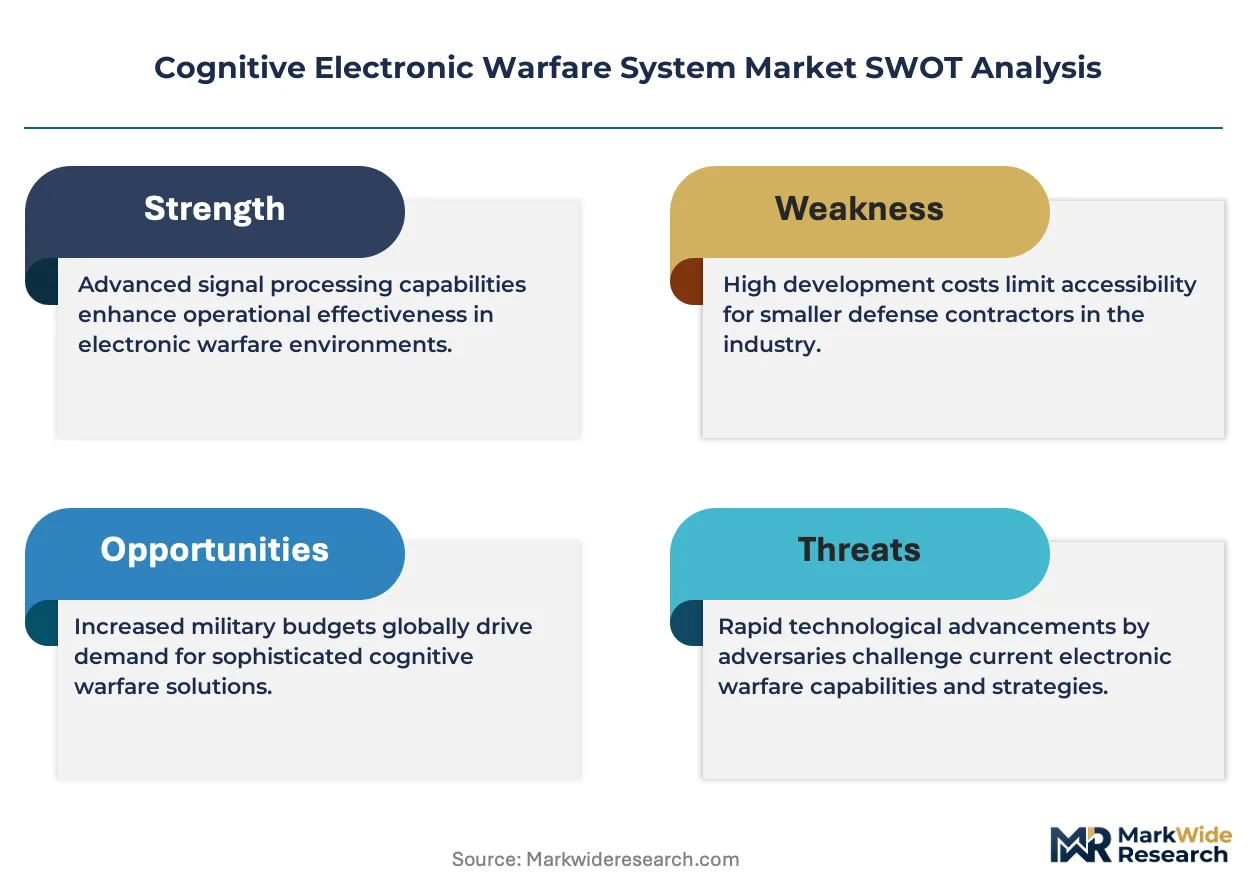
The US Department of Defense's software-defined radio mandates and machine learning integration requirements are forcing vendors to restructure qualification criteria around autonomous threat-response capabilities.
Growth Catalysts
- AI-enabled platform mandates:NATO procurement guidelines now require cognitive capabilities for spectrum dominance, accelerating retrofit programs across member arsenals.
- Adaptive radar proliferation:Peer adversaries deploy frequency-agile systems that traditional jamming cannot suppress, creating urgent operational demand for autonomous countermeasures.
- Software assurance frameworks:NIST cybersecurity standards for military systems validate vendors with mature algorithm development pipelines.
Market Restraints
- Gallium nitride supply concentration:Critical high-power amplifier substrates depend on limited foundry capacity in East Asia, exposing programs to single-source vulnerability.
- Classified algorithm certification:NSA and GCHQ validation timelines for AI-driven EW logic extend 18-36 months, compressing competitive windows for new entrants.
- Legacy hardware refresh costs:Platform integration with existing aircraft and shipboard architectures demands expensive mechanical and thermal redesign.
Strategic Opportunities
- Israeli export market expansion:IDF operational experience with integrated EW suites creates reference architectures for NATO and Asia-Pacific customers seeking proven autonomous systems.
- Space-based spectrum operations:Low Earth orbit constellations require cognitive interference management, opening adjacent demand from satellite operators and space defense agencies.
- Dual-use commercial crossover:5G network interference mitigation applies military-developed machine learning classifiers to civilian spectrum management contracts.
Industry Challenges
- RF-ML engineering scarcity:The intersection of radio-frequency hardware design and neural network deployment attracts fewer graduates than program demand requires, inflating compensation costs.
- Platform integration complexity:Cognitive EW systems must interface with legacy mission computers using obsolete bus architectures, requiring extensive middleware development.
- Real-time certification burden:Safety-critical avionics standards demand deterministic latency guarantees that stochastic AI processing struggles to satisfy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cognitive Electronic Warfare System Market |
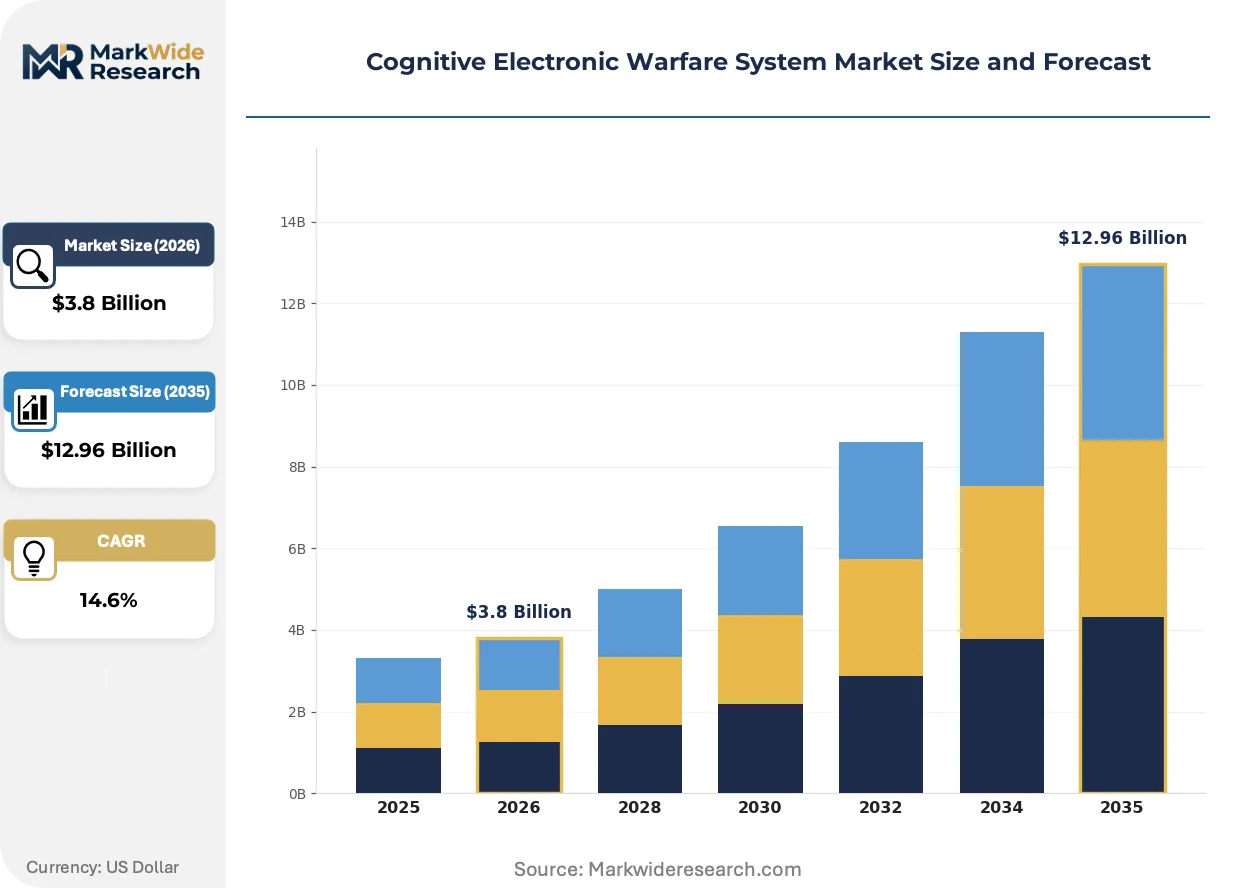
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jammers, ECM Systems, Detection Systems, Signal Processors Technology: Artificial Intelligence, Machine Learning, Cognitive Radio, Digital Signal Processing End User: Military, Defense Contractors, Government Agencies, Research Institutions Application: Surveillance, Threat Detection, Countermeasures, Communication Security |
| Companies Covered | L3Harris Technologies, Inc., Thales Group, BAE Systems PLC, Hensoldt AG, Elbit Systems Ltd., Lockheed Martin Corporation, RTX Corporation, Leonardo S.p.A., Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cognitive Electronic Warfare System Market Emerging Trajectories
Artificial intelligence is migrating from decision-support tools to autonomous execution layers, compressing operator-in-the-loop timelines from seconds to milliseconds across contested electromagnetic environments.
Deep learning-based signal classification is displacing rule-based expert systems in threat detection workflows. Naval and airborne platforms now deploy neural networks trained on millions of synthetic emitter signatures. This capability compression eliminates the manual database updates that previously required weeks of analyst labor.
EU defense procurement through the European Defence Fund increasingly mandates sovereign algorithm control and cross-border interoperability standards. Member states must demonstrate domestic development of core cognitive functions to qualify for collaborative funding. French and German programs now require open-architecture interfaces that prevent vendor lock-in.
Defense agencies are unbundling hardware procurement from software sustainment, creating separate contracting vehicles for algorithm updates and threat library refreshes. This service-model transition favors vendors with continuous integration pipelines over those selling static product configurations. The UK Ministry of Defence's approach to iterative capability delivery exemplifies this operational shift.
Cognitive Electronic Warfare System Market Segmentation
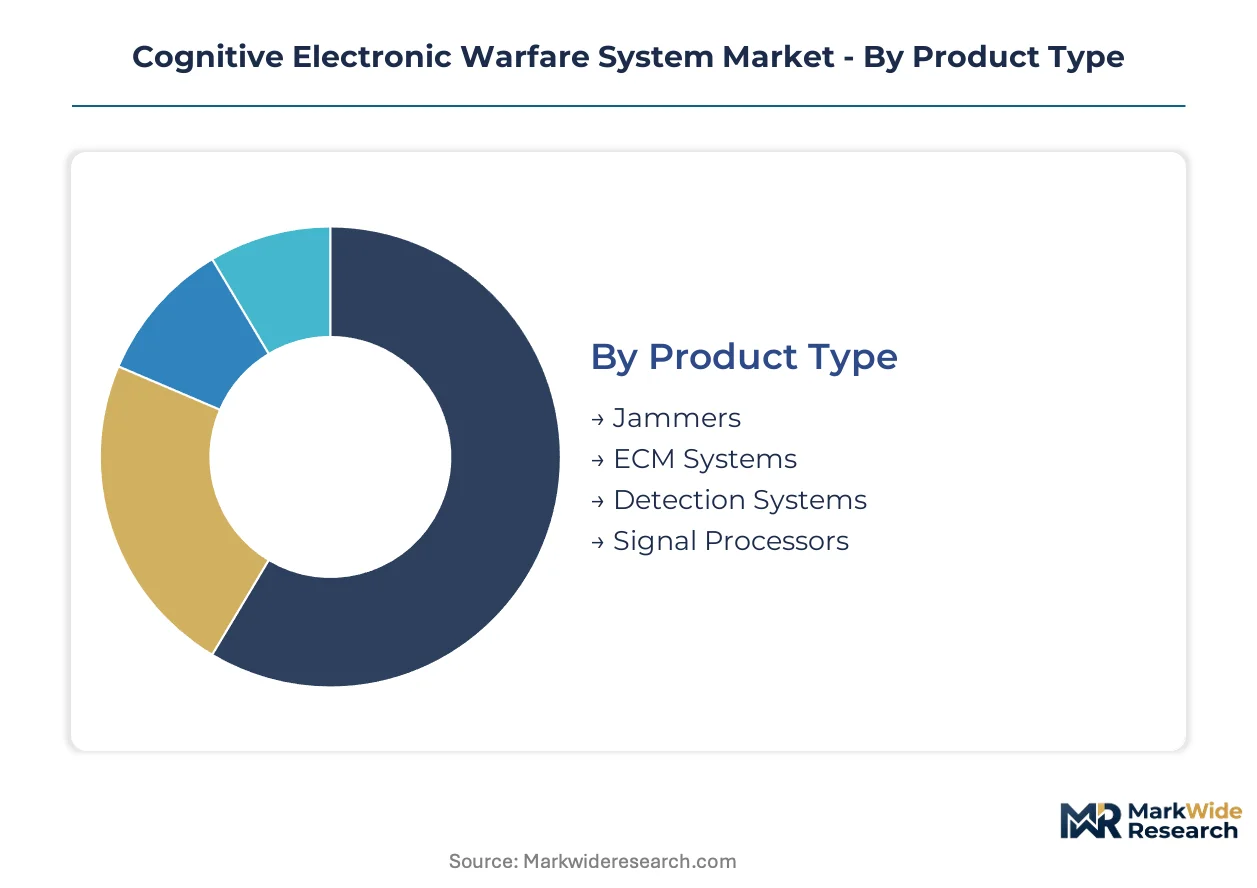
Segmentation in cognitive electronic warfare reveals how procurement priorities diverge between sovereign capability development and coalition interoperability requirements. Technology maturity and platform integration complexity create distinct competitive arenas across product categories.
Product Type:
Domestic procurement concentrates on platform-integrated suites, while export demand favors modular, rapidly deployable configurations.
- Jammers:High-power transmitters with gallium nitride amplifiers generate electromagnetic interference across 2 MHz to 40 GHz bands. United States Navy shipboard programs and Israeli Air Force fighter upgrades anchor demand, driven by peer adversary frequency-agile radar proliferation.
- Signal Processors:Real-time spectrum analyzers employ field-programmable gate arrays and neural network accelerators for emitter classification. United Kingdom Ministry of Defence iterative capability delivery programs prioritize these units, constrained by NIST software assurance validation timelines.
- ECM Systems:Integrated electronic countermeasure suites combine detection, decision, and response functions in single platform installations.
- Detection Systems:Passive receivers intercept and geolocate radio-frequency emissions without revealing platform presence.
Jammers command the established base. The steepest expansion runs through Signal Processors.
Technology:
Cost tiers separate legacy digital signal processing investments from premium AI-enabled autonomous response capabilities.
- Machine Learning:Neural networks trained on synthetic emitter signatures enable autonomous threat classification without manual database updates. Research institutions in Israel and defense contractors across NATO member states drive adoption, facing 18-36 month NSA and GCHQ algorithm certification cycles.
- Artificial Intelligence:Autonomous execution layers compress operator-in-the-loop timelines from seconds to milliseconds in contested electromagnetic environments. United States Department of Defense software-defined radio mandates accelerate procurement, limited by deterministic latency requirements for safety-critical avionics.
- Cognitive Radio:Dynamic spectrum access protocols enable systems to sense, learn, and adapt transmission parameters in real-time.
- Digital Signal Processing:Established Fast Fourier Transform and wavelet analysis methods provide deterministic, certifiable processing for legacy platform integration.
Digital Signal Processing retains the installed base. Machine Learning claims the steepest growth trajectory.
End User:
Application maturity distinguishes operational military deployments from developmental research programs.
- Military:Operational commands across United States Air Force, Royal Air Force, and Israeli Defense Forces field cognitive EW for active suppression of enemy air defenses. Budget allocation concentrates on fighter and shipboard platform integration, complicated by obsolete mission computer bus architectures.
- Defense Contractors:System integrators develop and sustain platform-specific implementations under long-term performance-based logistics contracts. BAE Systems, Northrop Grumman, and Elbit Systems anchor this segment, competing on software-defined radio qualification credentials.
- Government Agencies:National laboratories and signals intelligence organizations advance foundational algorithms and threat libraries.
- Research Institutions:Academic and defense research centers prototype next-generation cognitive radio and machine learning classifiers.
Military end users command the established base. Defense Contractors capture the steepest expansion.
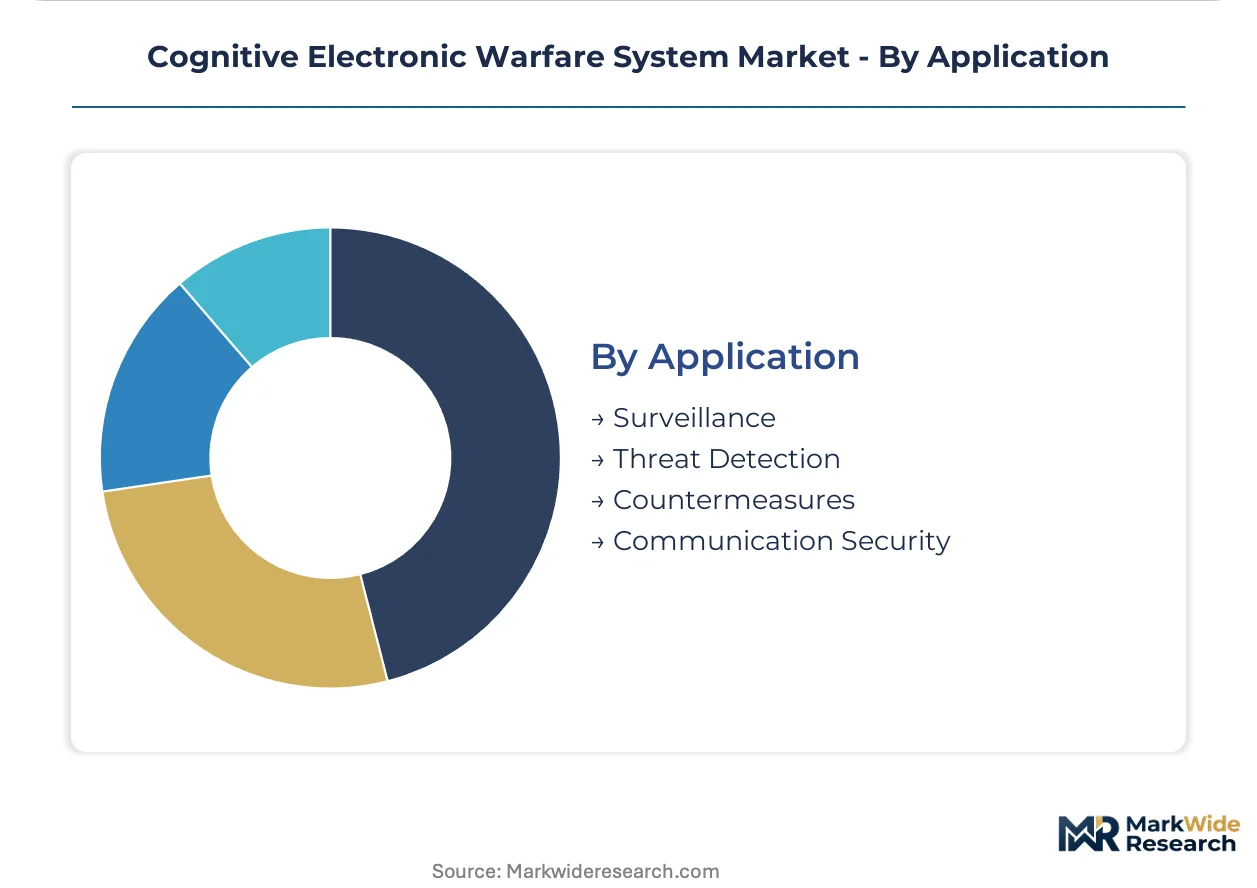
Application:
Customer type segmentation separates intelligence-driven surveillance from kinetic countermeasure operations.
- Countermeasures:Active jamming and deception techniques neutralize radar and communications systems in contested environments. United States Navy and Israeli Air Force operational experience creates reference architectures for NATO and Asia-Pacific export customers.
- Threat Detection:Passive signal intelligence identifies, classifies, and tracks adversary electromagnetic emissions. United Kingdom and German programs emphasize sovereign algorithm control under European Defence Fund guidelines.
- Surveillance:Persistent spectrum monitoring supports electronic order of battle construction and emitter mapping.
- Communication Security:Cognitive anti-jam techniques protect friendly networks from adversary interference.
Threat Detection commands the established base. Countermeasures drive the steepest expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price premiums for cognitive EW systems in the United States exceed equivalent procurements in the United Kingdom by 20-35 percent, reflecting divergent software assurance requirements and platform integration complexity. This asymmetry concentrates vendor investment toward NATO standardization while fragmenting export market access.
United States
Department of Defense software-defined radio mandates and machine learning integration requirements drive procurement volume. NIST cybersecurity frameworks and MIL-STD electromagnetic compatibility standards govern vendor qualification. Defense contractors cluster around Washington DC metro, Huntsville, and San Diego, where RTX Corporation and Northrop Grumman maintain advanced signal processing development centers.
United Kingdom
Ministry of Defence iterative capability delivery programs prioritize modular signal processor retrofits over platform-integrated suites. EDF and NATO STANAG guidelines mandate sovereign algorithm control and cross-border interoperability. BAE Systems anchors defense electronics activity across Lancashire and Bristol, competing on long-term military relationships and software sustainment contracts.
Israel
Israel Defense Forces operational experience with integrated EW suites generates reference architectures for export customers. Israeli procurement emphasizes autonomous threat-response capabilities validated through combat deployment. Elbit Systems concentrates development in Haifa and Beer-Sheva, leveraging integrated EW suite expertise for NATO and Asia-Pacific markets.
Germany
Bundeswehr requirements for sovereign cognitive radio capabilities accelerate domestic algorithm development. EDF funding eligibility demands demonstration of core cognitive function development within member states. Hensoldt AG anchors activity in Taufkirchen and Ulm, competing on open-architecture interfaces that prevent vendor lock-in.
France
Direction Générale de l'Armement procurement mandates sovereign control of machine learning classifiers for spectrum operations. EU AI Act and European Defence Fund guidelines shape qualification criteria for collaborative funding. Thales Group maintains electronic warfare development across Élancourt and Cholet, emphasizing neural network training on synthetic emitter signatures.
Cognitive Electronic Warfare System Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with AI-enabled autonomous response capabilities commanding premium positioning against legacy digital signal processing specialists. The vendor base stratifies across three tiers: integrated platform providers with long-term military relationships, modular subsystem specialists competing on rapid deployment, and emerging algorithm developers seeking certification credentials. Dominant competitive moves include M&A activity targeting RF-ML engineering talent and strategic partnerships bridging hardware procurement with software sustainment contracting.
Among US-based defense primes, L3Harris Technologies, Inc. and Lockheed Martin Corporation exemplify the integrated platform archetype, anchoring positions through software-defined radio qualification credentials and sustained military relationships. European competition concentrates on sovereign capability development, with Thales Group and Leonardo S.p.A. representing the modular subsystem specialist tier competing for EDF-funded collaborative programs.
| Leading Market Players |
|---|
| L3Harris Technologies, Inc. |
| Thales Group |
| BAE Systems PLC |
| Hensoldt AG |
| Elbit Systems Ltd. |
| Lockheed Martin Corporation |
| RTX Corporation |
| Leonardo S.p.A. |
| Northrop Grumman Corporation |
| Others |
Supply Flow & Price Mechanics
Gallium nitride foundry scale economies in East Asia establish cost floors that propagate through amplifier pricing tiers, concentrating bargaining power among integrated platform providers while fragmenting modular subsystem margins. This concentration dynamic compresses pricing flexibility for vendors lacking captive gallium nitride supply or long-term foundry offtake agreements.
Pricing Analysis
The customization-premium spread between configured-to-order platform-integrated suites and standard modular configurations spans 20-35 percent, reflecting NIST software assurance validation burdens and platform-specific thermal redesign costs. Three-tier pricing structure across premium AI-enabled autonomous systems, standard machine-learning retrofits, and economy digital signal processing tiers segments buyer archetypes, with defense contractors absorbing premium tiers and export customers gravitating toward economy configurations. Cost compression in standard-tier signal processors intensifies because Israeli and UK iterative delivery programs consolidate procurement volumes around qualified vendors. Government agencies exhibit lowest price sensitivity due to sovereign capability mandates, while research institutions face strict budget ceilings that favor economy-tier detection systems.
Supply Chain Analysis
Strategic stockpiling of gallium nitride substrates and field-programmable gate arrays dominates inventory strategy, with prime contractors maintaining 6-12 month buffers against foundry allocation constraints rather than just-in-time procurement. Geographic supply concentration centers on Taiwan and South Korea for gallium nitride high-power amplifiers, the United States for neural network accelerators, and Israel for integrated EW suite final assembly. Raw material dependencies include gallium nitride wafers, rare-earth magnet components for transmitters, and synthetic sapphire for RF windows. Single-source vulnerability in East Asian foundry capacity exposes programs to export restriction risk. Distribution runs through prime contractor integration facilities with direct military depot delivery, bypassing traditional distribution intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among defense procurement agencies unbundling hardware from software sustainment, with the UK Ministry of Defence and US Department of Defense consolidating vendor pools around continuous integration pipelines.
For Market Incumbents: Consolidate RF-ML engineering talent through targeted acquisition of Israeli algorithm developers and UK-based signal processing specialists, defending against modular subsystem specialists competing on rapid deployment timelines. Deepen backward integration into gallium nitride substrate supply through long-term foundry offtake agreements or captive wafer production, securing cost position against supply concentration risk. Prioritize NSA and GCHQ certification pipeline investment to compress 18-36 month validation timelines and lock out emerging algorithm developers. For New Entrants and Emerging Players: Lead with space-based spectrum operations as the most penetrable adjacent market, where Low Earth orbit constellation operators lack incumbent defense vendor relationships and prioritize rapid cognitive interference management deployment over legacy platform integration. Target dual-use 5G network interference mitigation contracts as a commercial beachhead, applying military-developed machine learning classifiers to civilian spectrum management procurement. Pursue strategic partnership with prime contractor software sustainment vehicles rather than direct platform competition. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors algorithm developers with active NSA or GCHQ certification pipelines over hardware-centric platform integrators, as autonomous execution layer migration compresses operator-in-the-loop timelines and elevates software valuation multiples. Long-term viability across the 5-10 year horizon rests on demonstrated sovereign algorithm control under EDF and NATO STANAG guidelines, with EU AI Act compliance emerging as a gatekeeping requirement. Signal to watch: European Defence Fund collaborative program awards that mandate open-architecture interfaces and domestic cognitive function development, favoring modular subsystem specialists with cross-border interoperability credentials.| Strategic Initiative | Industry Significance |
|---|---|
| RF-ML Engineering Talent Acquisition | Addresses scarcity at the radio-frequency machine learning intersection that inflames compensation costs across NATO member states. |
| Gallium Nitride Supply Agreement | Secures high-power amplifier substrate allocation against East Asian foundry concentration and single-source vulnerability. |
| NSA/GCHQ Algorithm Certification | Validates AI-driven EW logic for program eligibility under strict software assurance frameworks. |
| Space-Based Spectrum Operations Entry | Captures adjacent demand from Low Earth orbit constellations requiring cognitive interference management. |
| Dual-Use 5G Commercial Crossover | Applies military machine learning classifiers to civilian spectrum management contracts outside defense procurement cycles. |
Methodological Framework
A standing panel of electronic warfare program managers, RF systems engineers, defense procurement officers, and signals intelligence analysts provided ongoing calibration across primary interview cycles, with secondary validation drawing from Department of Defense budget justification documents, NATO STANAG technical specifications, EDF collaborative program announcements, and vendor software-defined radio qualification filings. Bottom-up triangulation across platform retrofit program pipelines converged with top-down assessment of sovereign capability investment trends.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with analytical framework modeling product type, technology maturity tier, end-user operational status, and application mission profile dimensions. CAGRs were derived from segment-level growth trajectory synthesis incorporating AI mandate acceleration curves, legacy hardware refresh cycle timing, and export market access expansion patterns. Industry-specific forecast inputs included NSA algorithm certification pipeline throughput estimates and gallium nitride foundry capacity utilization projections.
Underlying assumptions cover sustained NATO defense budget allocation, stable East Asian foundry supply, and unimpeded export control frameworks, with deviation risk concentrated in classified algorithm certification timeline extensions and sovereign algorithm control mandate intensification under EU AI Act implementation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Land-Based Smart Weapons Market
Defense and Military Systems and Equipment
Bio-Defense Market
Defense and Military Systems and Equipment
Global Military Defense Vehicle Intercom System Market
Defense and Military Systems and Equipment
Search and Rescue Equipment Market
Defense and Military Systems and Equipment
Global Non Lethal Biochemical Weapon Market
Defense and Military Systems and Equipment
Mergers and Acquisitions (Manda) in Aerospace and Defense Market
Defense and Military Systems and Equipment
Anti-Jamming Equipment Market
Defense and Military Systems and Equipment
India Defense Market
Defense and Military Systems and Equipment
Global Military Laser Rangefinder Market
Defense and Military Systems and Equipment
Defense Integrated Antenna Market
Defense and Military Systems and Equipment
United States Defense Market
Defense and Military Systems and Equipment
Mine Clearance System Market
Defense and Military Systems and Equipment
Mechanical and Electronic Fuzes Market
Defense and Military Systems and Equipment
Airborne Electronic Warfare Market
Defense and Military Systems and Equipment
Military Exoskeleton Market
Defense and Military Systems and Equipment
Missiles and Missile Defense Systems Market