
 Telescopic Crane Market | 2026-2036
Telescopic Crane Market Size, Share, and Industry Trends Forecast 2026-2036
Telescopic Crane Market Insights
The gap between premium all-terrain systems and commodity truck-mounted units is expanding as project complexity splits procurement criteria. Liebherr dominates the high-capacity segment through in-house boom fabrication and proprietary luffing technology. XCMG Group competes aggressively on cost-engineered rough-terrain models for developing-market contractors. SANY Group anchors its position with integrated hydraulic component manufacturing that shortens delivery cycles.
A telescopic crane employs nested tubular boom sections that extend and retract via hydraulic or mechanical systems to vary working radius and lift height without disassembly, typically achieving load capacities from 20 to over 1,000 metric tons depending on configuration and outrigger deployment. Its primary purpose centers on vertical and horizontal material placement across constrained jobsites where mobility and rapid setup outweigh tower crane economics. Crawler-mounted variants command the highest margin pools due to specialized undercarriage engineering and limited supplier concentration. Hydraulic technology leads unit shipments while electric-driven systems attract premium pricing in urban emission-controlled zones. Mining applications sustain the longest replacement cycles but generate the highest aftermarket service attachment rates.
OSHA crane operator certification requirements in the United States, CE machinery directives in Europe, and China's GB/T national standards collectively elevate safety system costs while restricting market access for non-compliant equipment. EPA Tier 4 Final and Euro Stage V emissions frameworks are forcing diesel-engine technology investments that favor larger manufacturers with dedicated powertrain engineering resources. Stakeholders must monitor how regional decarbonization timelines reshape powertrain technology roadmaps and aftermarket parts compatibility across installed fleets.
Market Dynamics
EPA Tier 4 Final and Euro Stage V emissions mandates are compressing diesel-engine supplier pools while accelerating electric-hybrid development cycles across telescopic crane portfolios.
Growth Catalysts
- Offshore Wind Installation:China's coastal provinces and North Sea markets require crawler-mounted units with 1,000+ ton capacity for turbine component placement.
- CE Machinery Directive:European safety certification requirements are standardizing control system architectures that reduce operator error rates.
- Port Modernization:Automated container terminals in Singapore, Rotterdam, and Shanghai specify telescopic reach stackers with integrated load-moment indicators.
Market Restraints
- Specialized Steel Supply:High-strength boom fabrication depends on concentrated European and Japanese specialty steel mills.
- Emissions Compliance Costs:EPA Tier 4 Final aftertreatment systems add 15-20% to powertrain unit costs.
- Tower Crane Substitution:Fixed tower systems capture multi-year infrastructure projects where mobility provides limited incremental value.
Strategic Opportunities
- Saudi Giga-Projects:NEOM and Red Sea tourism developments specify rough-terrain fleets for desert construction logistics.
- Battery-Electric Convergence:Lithium-ion pack integration with hydraulic power units enables zero-emission urban crane deployment.
- India PLI Scheme:Production-linked incentives for construction equipment manufacturing reduce import dependency for domestic contractors.
Industry Challenges
- Certified Operator Scarcity:OSHA crane operator credentialing creates 6-12 month hiring delays for US contractors expanding fleets.
- Legacy Fleet Integration:Telematics retrofits for pre-2015 equipment require proprietary hydraulic sensor adaptations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telescopic Crane Market |
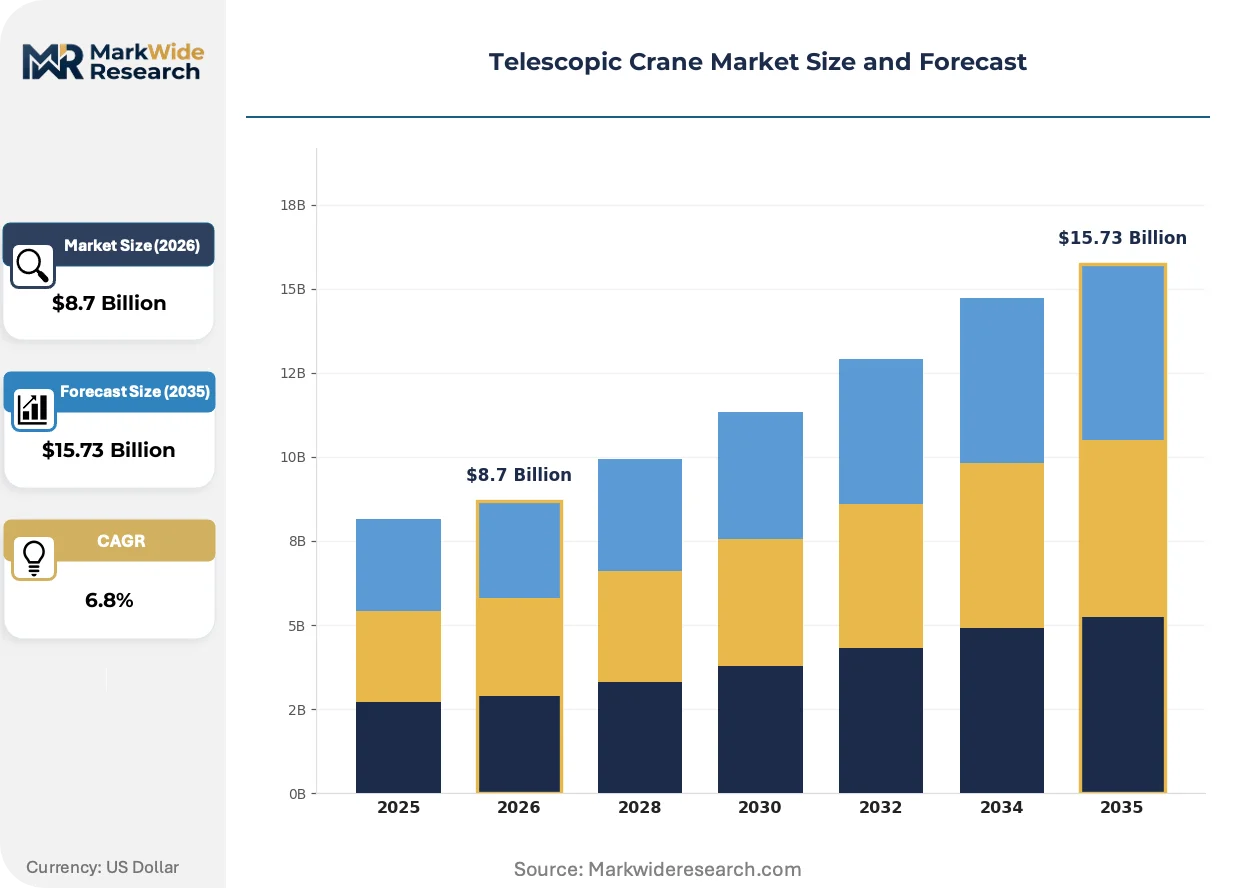
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Truck-Mounted, Crawler, Rough Terrain, All Terrain Technology: Hydraulic, Electric Driven, Diesel Engine, Pneumatic Application: Construction Projects, Infrastructure Development, Mining Operations, Shipping Yards, Oil & Gas Exploration End User: Construction Contractors, Mining Companies, Maritime Operators, Energy Producers |
| Companies Covered | Liebherr, Tadano, Terex, Manitowoc, Konecranes, SANY Group, XCMG Group, Zoomlion Heavy Industry Science and Technology, PALFINGER, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telescopic Crane Market Trends and Innovations
Powertrain electrification and digital load management are compressing equipment lifecycles while opening premium pricing tiers for emission-compliant configurations.
Variable displacement pump technology is unifying hydraulic efficiency across boom extension, luffing, and slewing functions. Mining contractors in Western Australia and Chilean copper belts are specifying these systems for fuel consumption reduction. The technology is unifying previously separate hydraulic circuits into single intelligent pressure-management architectures.
EU Green Deal carbon border adjustment mechanisms are reshaping equipment import economics for non-European manufacturers. CE marking compliance now requires documented lifecycle carbon footprints for steel and hydraulic fluid content. Chinese exporters to Germany and France are restructuring supply chains to capture process emissions data.
Rental fleet operators are consolidating procurement around full-service lease structures that bundle maintenance, insurance, and operator training. Equipment lessors in Texas and Alberta are displacing traditional purchase-finance models with hourly-usage contracts. This shift concentrates buyer power among national rental chains with centralized specification authority.
Telescopic Crane Market Segmentation
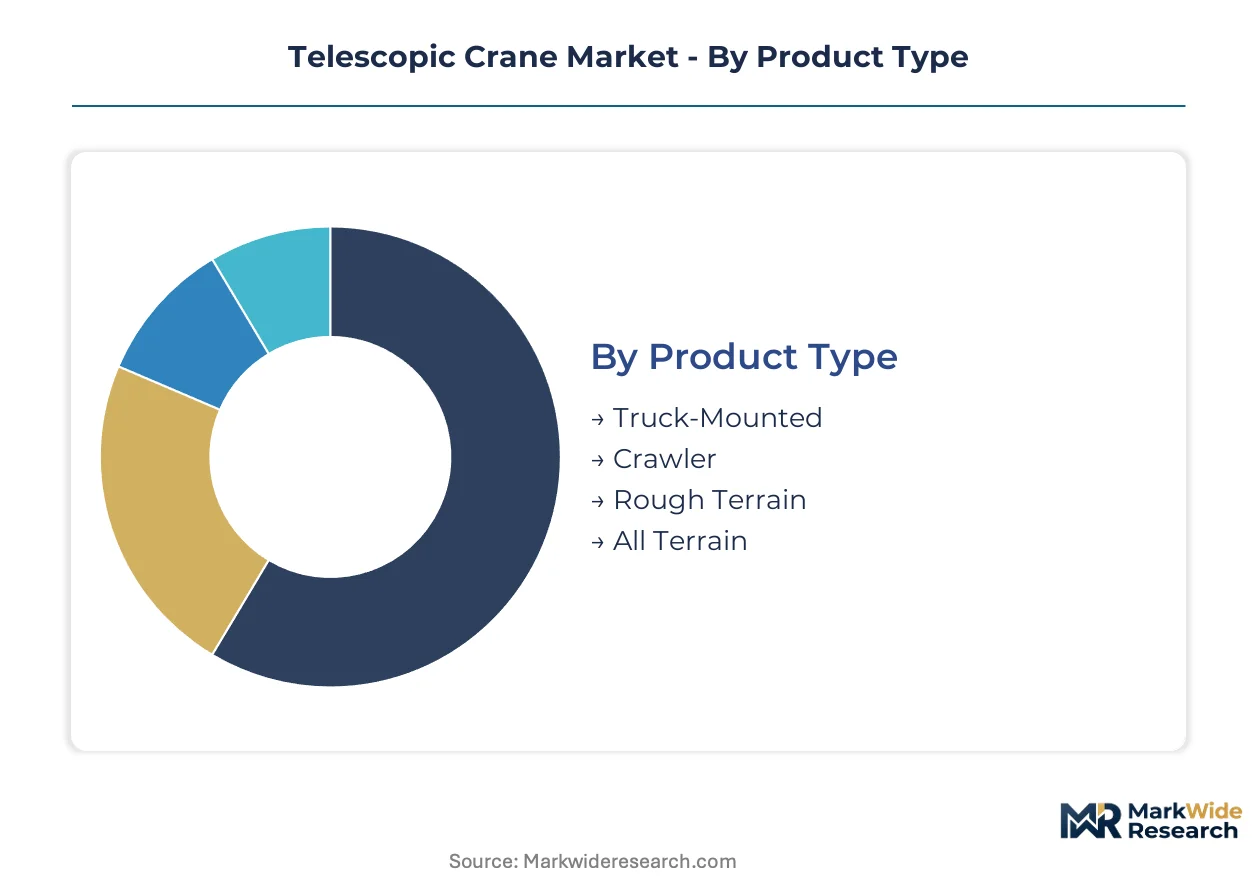
Telescopic crane procurement patterns diverge sharply across mobility requirements, powertrain configurations, and project duration economics. Equipment specification cascades from terrain constraints through regulatory exposure to total cost of ownership calculations that favor certain configurations in specific operating environments.
Product Type:
Supply concentration in high-capacity crawler undercarriage engineering creates margin stratification across mobility categories.
- Truck-Mounted:Highway-legal chassis with telescopic booms mounted on commercial truck frames enable rapid site-to-site transit without low-loader transport. Fleet operators in Texas and Germany favor these units for urban utility work where daily relocation is routine.
- Crawler:Tracked undercarriage distributes ground pressure below one pound per square inch, enabling operation on unprepared surfaces and soft ground conditions. Western Australian iron ore mines and North Sea offshore wind projects specify 1,000+ ton capacity units from Liebherr and XCMG for turbine nacelle placement.
- Rough Terrain:Compact four-wheel-drive carriers with outrigger stabilization target developing-market contractors in Saudi Arabia's NEOM corridor and India's infrastructure corridors where paved access is limited.
- All Terrain:Dual-mode highway and off-road capability with multi-axle steering commands premium pricing for European rental fleets serving nuclear decommissioning and bridge replacement projects.
Truck-mounted units absorb the bulk of installed capacity; crawler configurations are expanding most quickly on offshore wind demand.
Technology:
Emissions compliance timelines are forcing divergent powertrain investment patterns across manufacturer portfolios.
- Hydraulic:Variable displacement pumps unify boom extension, luffing, and slewing circuits into intelligent pressure-management architectures. Mining contractors in Chilean copper belts specify these systems for fuel consumption reduction in 24-hour extraction operations.
- Electric Driven:Lithium-ion battery packs integrated with hydraulic power units enable zero-emission deployment in EU urban emission-controlled zones. Rotterdam and Shanghai port terminals are specifying these for container handling within regulated airsheds.
- Diesel Engine:EPA Tier 4 Final and Euro Stage V aftertreatment systems add 15-20% to powertrain costs, compressing supplier pools toward manufacturers with dedicated engine engineering resources.
- Pneumatic:Compressed air actuation serves niche explosive-atmosphere applications in oil and gas facilities where spark elimination is mandatory.
Diesel configurations retain dominant installed base; electric-driven systems are climbing the fastest on regulatory pressure in German and French urban zones.
Application:
Project duration and mobility requirements split demand across fixed-installation versus fleet-deployment economics.
- Construction Projects:Commercial and residential building sites specify rough-terrain and all-terrain units for steel erection and concrete placement where tower crane mobilization is uneconomical.
- Infrastructure Development:Bridge replacement and highway expansion projects in China's coastal provinces sustain demand for high-capacity crawler units with extended reach capabilities.
- Mining Operations:Open-pit extraction in Western Australia and Chile generates the longest equipment replacement cycles but highest aftermarket service attachment rates for boom inspection and hydraulic component rebuilds.
- Shipping Yards:Automated container terminals in Singapore and Rotterdam specify telescopic reach stackers with integrated load-moment indicators for safety-critical container handling.
- Oil & Gas Exploration:Remote Arctic and desert drilling operations require explosion-proof pneumatic systems for wellhead maintenance in hazardous atmospheres.
Infrastructure development absorbs dominant procurement volume; offshore wind installation within shipping yard applications is gaining share fastest on turbine component handling demand.
End User:
Capital intensity and fleet utilization rates create distinct buying behaviors across contractor categories.
- Construction Contractors:Project-based procurement with rental preference for specialized high-capacity units drives consolidation toward national rental chains with centralized specification authority.
- Mining Companies:Captive fleet ownership with 15-20 year replacement cycles and intensive aftermarket service relationships favors manufacturers with regional parts depots.
- Maritime Operators:Port authorities and terminal operators in Shanghai and Rotterdam specify emission-compliant electric-hybrid configurations for automated container terminals.
- Energy Producers:Utility-scale wind and solar developers in the North Sea and China's coastal provinces drive crawler crane demand for turbine component placement at height.
Construction contractors represent the largest addressable base; energy producers are expanding most quickly on renewable installation timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's Yangshan Deep Water Port drives China's telescopic crane procurement, with automated container terminals specifying electric-hybrid reach stackers for emission-controlled operations.
China
Coastal provinces from Jiangsu to Guangdong sustain crawler crane demand for offshore wind turbine installation at scale. GB/T national standards for crane safety systems elevate compliance costs for domestic manufacturers. The Yangtze River Delta cluster around Shanghai anchors port modernization investments requiring 1,000+ ton capacity units.
Germany
North Sea offshore wind developments and nuclear decommissioning projects command premium all-terrain crane specifications. EU Green Deal carbon border adjustments reshape import economics for non-European equipment suppliers. The Ruhr industrial corridor concentrates rental fleet operators consolidating procurement around full-service lease structures.
United States
Texas utility-scale wind installations and Gulf Coast petrochemical expansion sustain rough-terrain crane deployment. OSHA crane operator certification requirements create 6-12 month hiring delays for contractors expanding fleets. The Permian Basin energy corridor generates concentrated demand for explosion-proof pneumatic systems in hazardous atmospheres.
Saudi Arabia
NEOM and Red Sea tourism developments specify desert-capable rough-terrain fleets for construction logistics in unpaved conditions. The national regulator mandates adherence to construction equipment safety protocols for giga-project participation. The Tabuk Province in northwest Saudi Arabia hosts the primary NEOM construction zone driving equipment procurement timelines.
Australia
Western Australian iron ore mines generate the longest equipment replacement cycles but highest aftermarket service attachment rates for boom inspection. The country's national mining safety regulator enforces rigorous crane inspection protocols for open-pit extraction operations. The Pilbara region concentrates demand for high-capacity crawler units with specialized undercarriage engineering.
Telescopic Crane Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a tiered market structure where boom fabrication capabilities and proprietary hydraulic architectures determine margin capture. The vendor base stratifies between integrated manufacturers controlling specialty steel supply chains and assemblers sourcing standardized components. Three archetypes dominate: European precision-engineering specialists, Chinese cost-optimized volume producers, and Japanese reliability-focused mid-cap players. Competitive dynamics center on M&A consolidation for technology access and geographic expansion through regional distribution partnerships.
Within the integrated manufacturing tier, Liebherr and SANY Group exemplify divergent approaches to vertical scope—one through in-house boom fabrication, the other via captive hydraulic component production. Tadano occupies a position bridging Japanese engineering heritage with global rental fleet relationships. These three anchors illustrate how geographic origin and corporate structure shape competitive positioning without dictating specific strategic moves.
| Leading Market Players |
|---|
| Liebherr |
| Tadano |
| Terex |
| Manitowoc |
| Konecranes |
| SANY Group |
| XCMG Group |
| Zoomlion Heavy Industry Science and Technology |
| PALFINGER |
| Others |
Pricing and Supply Chain Analysis
Capacity-certification divergence between premium all-terrain systems and commodity truck-mounted units manifests in parallel pricing and sourcing configurations. Premium tiers command outcome-based contracts tied to uptime guarantees and specialized operator training, while commodity segments compete on equipment-only lease rates with minimal service bundling.
Pricing Analysis
Uptime-guarantee contracts anchor value-based pricing for crawler-mounted units in Western Australian mining and North Sea offshore wind applications. Three-tier pricing structure across premium, standard, and economy levels separates CE-certified all-terrain fleets from rough-terrain workhorses and aging truck-mounted inventory. Cost compression in the truck-mounted tier is intensifying because rental fleet operators consolidate procurement around national chains with centralized specification authority. Developing-market contractors in Saudi Arabia and India exhibit highest price sensitivity, while European nuclear decommissioning projects show least sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Dual-sourcing requirements for high-strength boom steel compel manufacturers to qualify mills in Germany, Japan, and South Korea simultaneously. Specialty steel plate, precision hydraulic valves, and lithium-ion battery packs constitute critical input dependencies. Single-source vulnerability concentrates in European and Japanese specialty steel mills serving the crawler undercarriage segment. Distribution runs through manufacturer-direct channels for large mining fleets and national rental chains, with regional dealers serving fragmented construction contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The telescopic crane sector sits in a powertrain-transition phase where electric-hybrid systems are displacing Tier 4 Final diesel configurations in EU urban emission zones. This technology replacement cycle compresses legacy fleet residual values while opening premium pricing tiers for zero-emission configurations.
For Market Incumbents: Anticipate margin compression in the truck-mounted segment as Chinese cost-optimized producers expand into European rental markets. Defensive consolidation should prioritize captive boom fabrication capacity and proprietary luffing technology patents. Capacity addition in India's PLI-subsidized manufacturing corridors offers tariff-advantaged supply positioning for Middle East and African demand. For New Entrants and Emerging Players: Digital rental-platform routes into the North American contractor market bypass established dealer networks with hourly-usage contract structures. White-space targets include battery-electric rough-terrain units for Saudi giga-projects and telematics retrofit services for pre-2015 legacy fleets. The most penetrable segment is mid-cap construction contractors in Texas and Alberta seeking flexible lease structures over capital purchase. For Investors and Strategic Acquirers: Re-rating potential sits with integrated hydraulic component manufacturers given EU Green Deal carbon border adjustment mechanisms reshaping import economics. Long-term viability favors producers with documented lifecycle carbon footprints and regional parts depot networks serving 15-20 year mining replacement cycles. The signal to watch is offshore wind installation timelines in China's coastal provinces as a demand inflection indicator for 1,000+ ton crawler capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Steel | Captive boom fabrication secures margin pools concentrated in European and Japanese mills. |
| Electric-Hybrid Powertrain Development | Zero-emission configurations unlock premium pricing in Rotterdam and Shanghai port terminals. |
| Full-Service Lease Structure Expansion | Hourly-usage contracts displace purchase-finance models among Texas and Alberta rental operators. |
| Telematics Retrofit Service Launch | Proprietary hydraulic sensor adaptations address legacy fleet integration challenges for pre-2015 equipment. |
| Regional Distribution Partnership | Local specification authority in India's infrastructure corridors reduces import dependency for domestic contractors. |
Research Methodology
Multi-period observation of fleet replacement cycles, emissions compliance timelines, and port modernization investments anchored the trend analysis, supplemented by interviews with equipment procurement directors at mining operators, rental fleet managers, and aftermarket service heads. Secondary validation drew from customs trade data, OEM SEC filings, and EU ETS carbon disclosure databases. Bottom-up unit shipment modeling and top-down infrastructure spending allocation were triangulated against manufacturer revenue disclosures.
Input-output matrices mapped crane capacity specifications against project-scale requirements across the analysis window. Segmentation dimensions modeled include mobility configuration, powertrain technology, end-use application, and regional regulatory cluster. CAGRs were derived from regression analysis of historical fleet data and project pipeline visibility. Industry-specific forecast inputs incorporated offshore wind installation schedules and mining commodity price corridors affecting equipment replacement timing.
Inputs from OEM production disclosures and port authority procurement records were available through the study window; gaps in emerging market rental fleet utilization data introduce uncertainty bands around developing economy penetration rates. Forecasts reflect documented assumptions regarding emissions regulation phase-in schedules and steel supply continuity. A model refresh is warranted upon material change in EU carbon border adjustment implementation timelines or Chinese offshore wind subsidy structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Cable Conduit Market
Material Handling Equipment
Cherry Picker Forklift Market
Material Handling Equipment
Dewatering Screen Market
Material Handling Equipment
Construction Lifts Market
Material Handling Equipment
India Automated Material Handling (AMH) Market
Material Handling Equipment
Loaded Container Handler Market
Material Handling Equipment
Global Bucket Loader Market
Material Handling Equipment
Retractable Lift Market
Material Handling Equipment
Die Casting Market
Material Handling Equipment
Portable Loading Ramps Market
Material Handling Equipment
Resistance Welding Products Market
Material Handling Equipment
Hydraulic Hose Market
Material Handling Equipment
Mining Hoses Market
Material Handling Equipment
Pallet Truck Market
Material Handling Equipment
Industrial Carts Market
Material Handling Equipment
Stair Lifts and Climbing Devices Market