
 Cranial Closure and Fixation Devices Market | 2026-2036
Cranial Closure and Fixation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Cranial Closure and Fixation Devices Market Analysis
The capability gap between capital-heavy integrated manufacturers and smaller assembly-dependent suppliers is collapsing. Stryker Corporation leverages captive titanium forging capacity to control input costs across its neurosurgical portfolio. Medtronic Plc sustains broad geographic coverage through direct hospital contracting networks that lock in multi-year cranial implant supply agreements. Integra LifeSciences Corporation specializes in biologics-cum-hardware combinations that command premium positioning in complex cranioplasty cases.
Cranial closure and fixation devices encompass plates, screws, mesh systems, and adhesive agents engineered from titanium alloys, resorbable polymers, or ceramic composites to restore skull integrity after trauma, tumor resection, or congenital defect correction. Titanium bone plates machined to sub-millimeter tolerances provide rigid fixation while permitting postoperative CT imaging without artifact distortion. Hospitals as the dominant end-user channel capture the deepest margin pools through bundled procedural contracts, while biodegradable polymer segments are expanding fastest as surgeons seek to eliminate secondary removal surgeries in pediatric populations. 3D printing technology is displacing traditional milling for patient-specific implant production, concentrating manufacturing value in design software and powder-bed fusion equipment rather than conventional tool-and-die operations.
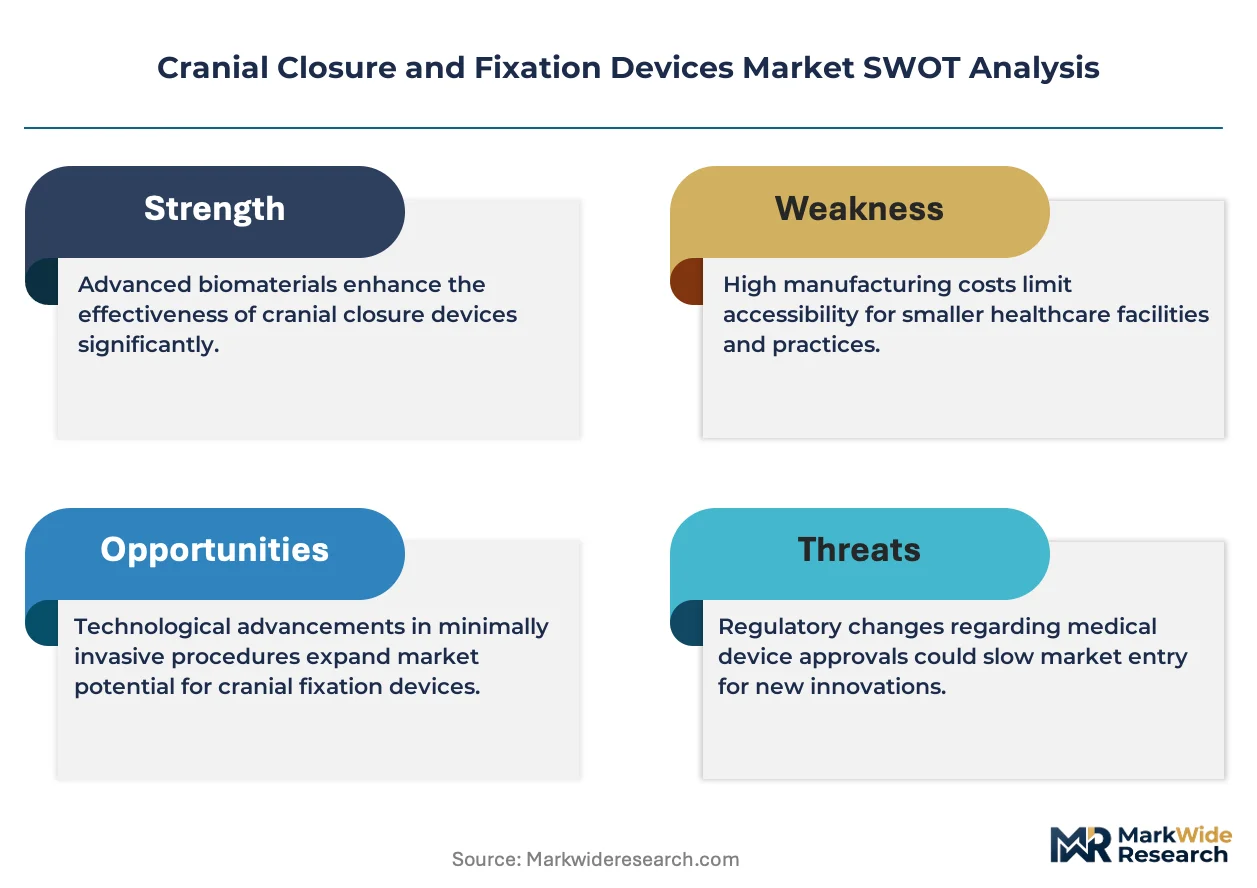
FDA 510(k) premarket notification requirements govern titanium and stainless steel implantable devices in the United States, while the EU Medical Device Regulation (MDR) mandates clinical evidence and notified body oversight for cranial fixation systems marketed in Europe. Japan's PMDA enforces stringent biocompatibility testing under JIS T 0301 for permanent implant materials, creating a compliance threshold that filters out lower-specification competitors. Stakeholders must monitor how evolving MDR post-market surveillance obligations and FDA digital health pre-certification pilots for surgical planning software reshape competitive access and product lifecycle economics.
Market Dynamics
Patient-specific implant fabrication is collapsing the traditional tooling economics of cranial device manufacturing, concentrating value in digital design workflows and metal powder supply chains rather than conventional machining operations.
Growth Catalysts
- FDA 510(k) Streamlining:The premarket notification pathway for titanium mesh and bioresorbable plates accelerates product entry timelines for manufacturers targeting United States neurosurgical centers.
- Pediatric Bioresorbables:Surgeons in pediatric neurosurgery units are eliminating secondary removal procedures through expanded adoption of biodegradable polymer fixation systems.
- German Precision Clustering:Manufacturing density around Tuttlingen and Freiburg im Breisgau creates supplier ecosystems that reduce prototyping-to-production cycles for complex cranial plates.
Market Restraints
- Titanium Input Volatility:Sponge and alloy price swings from Russian and Chinese feedstock disruptions compress margins for non-integrated device assemblers.
- PMDA Biocompatibility Thresholds:Japan's JIS T 0301 permanent implant testing requirements filter out lower-specification competitors from Asia-Pacific market entry.
- Secondary Surgery Avoidance:Non-resorbable hardware in pediatric populations creates lifetime cost liabilities that constrain reimbursement flexibility for metallic fixation.
Strategic Opportunities
- EU MDR Post-Market Surveillance:Evolving vigilance obligations for cranial fixation systems create first-mover advantages for manufacturers with established clinical evidence databases.
- 3D Printing Convergence:Powder-bed fusion equipment paired with surgical planning software enables same-day implant design-to-sterilization workflows at academic medical centers.
- Direct Hospital Contracting:Multi-year supply agreements locking in cranial implant volumes bypass distributor markups and secure predictable demand visibility.
Industry Challenges
- Design Software Integration:Surgical planning platforms require specialized biomedical engineering talent scarce outside major metropolitan hospital systems.
- Notified Body Bottlenecks:EU MDR certification queues for Class III implantable devices extend commercialization timelines by 12-18 months.
- Legacy CT Artifact Standards:Radiological imaging protocols optimized for titanium compatibility demand revalidation when transitioning to novel ceramic composites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cranial Closure and Fixation Devices Market |
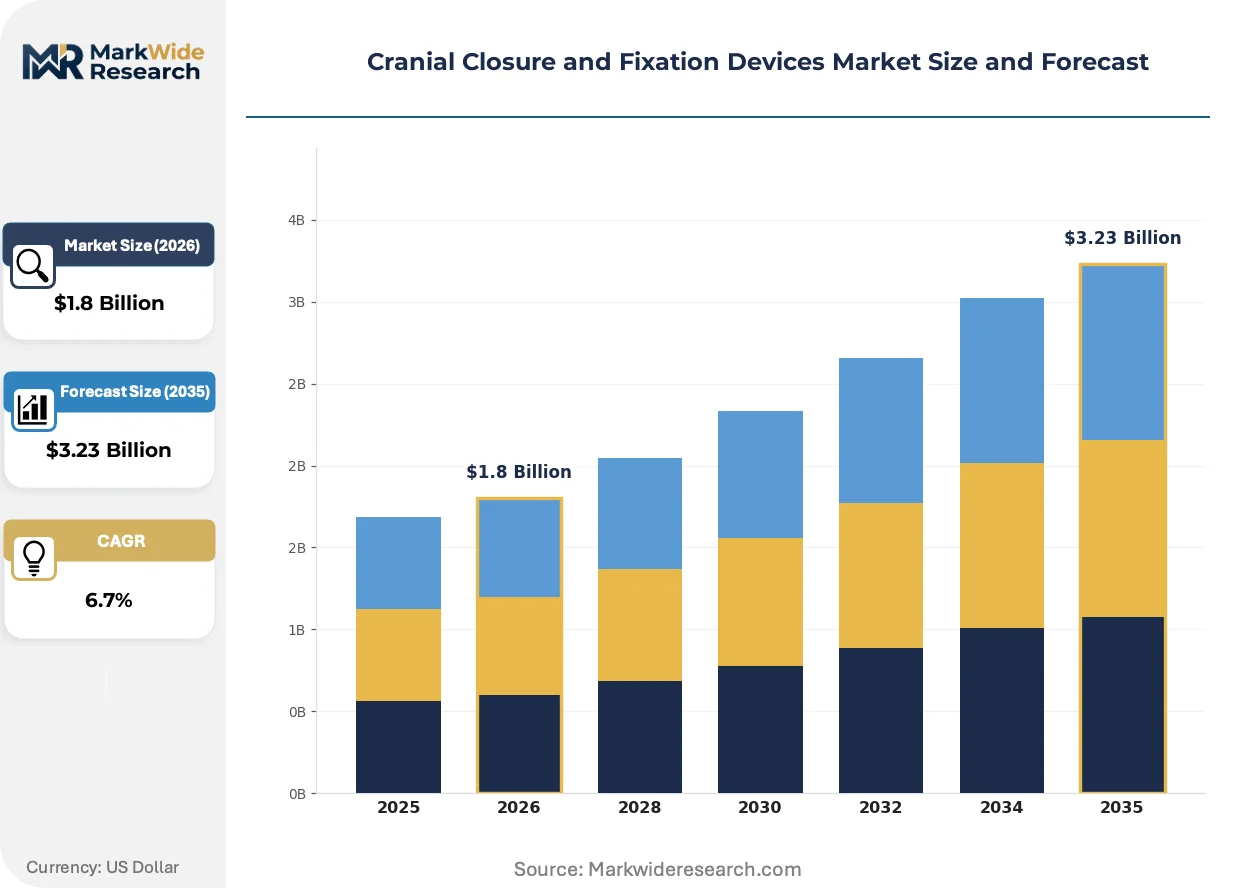
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bone Plates, Screws, Mesh, Adhesives End User: Hospitals, Surgical Centers, Trauma Units, Clinics Material: Stainless Steel, Titanium, Biodegradable Polymers, Ceramics Technology: 3D Printing, Minimally Invasive, Robotic Surgery, Traditional Surgery |
| Companies Covered | Stryker Corporation, Medtronic Plc, Integra LifeSciences Corporation, DePuy Synthes, B. Braun Melsungen AG, Zimmer Biomet Holdings Inc., Johnson & Johnson, KLS Martin Group, Evonos GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cranial Closure and Fixation Devices Market Emerging Trajectories
Digital manufacturing workflows are eroding the capital barriers that historically protected integrated device manufacturers from specialized competitors.
Electron beam melting is supplanting subtractive milling for patient-specific cranial plate production. Academic neurosurgical units in Germany and the United States are adopting powder-bed fusion systems for on-site implant fabrication. This shift compresses tooling lead times from weeks to hours while transferring manufacturing value from machine shops to biomedical design software licenses.
The EU Medical Device Regulation's clinical evidence requirements for Class III implantable devices are restructuring competitive access in Europe. Manufacturers must now maintain post-market surveillance systems that track long-term biocompatibility outcomes. Smaller suppliers lacking clinical affairs infrastructure are withdrawing from European markets, concentrating share among established notified body relationships.
Hospital procurement departments are consolidating cranial implant purchasing through bundled procedural contracts that span fixation hardware, biologics, and instrumentation. United States academic medical centers are negotiating multi-year agreements that lock in volume commitments and technical support obligations. Distributor relationships are compressing as direct manufacturer contracting captures margin pools previously fragmented across supply chain intermediaries.
Cranial Closure and Fixation Devices Market Segmentation
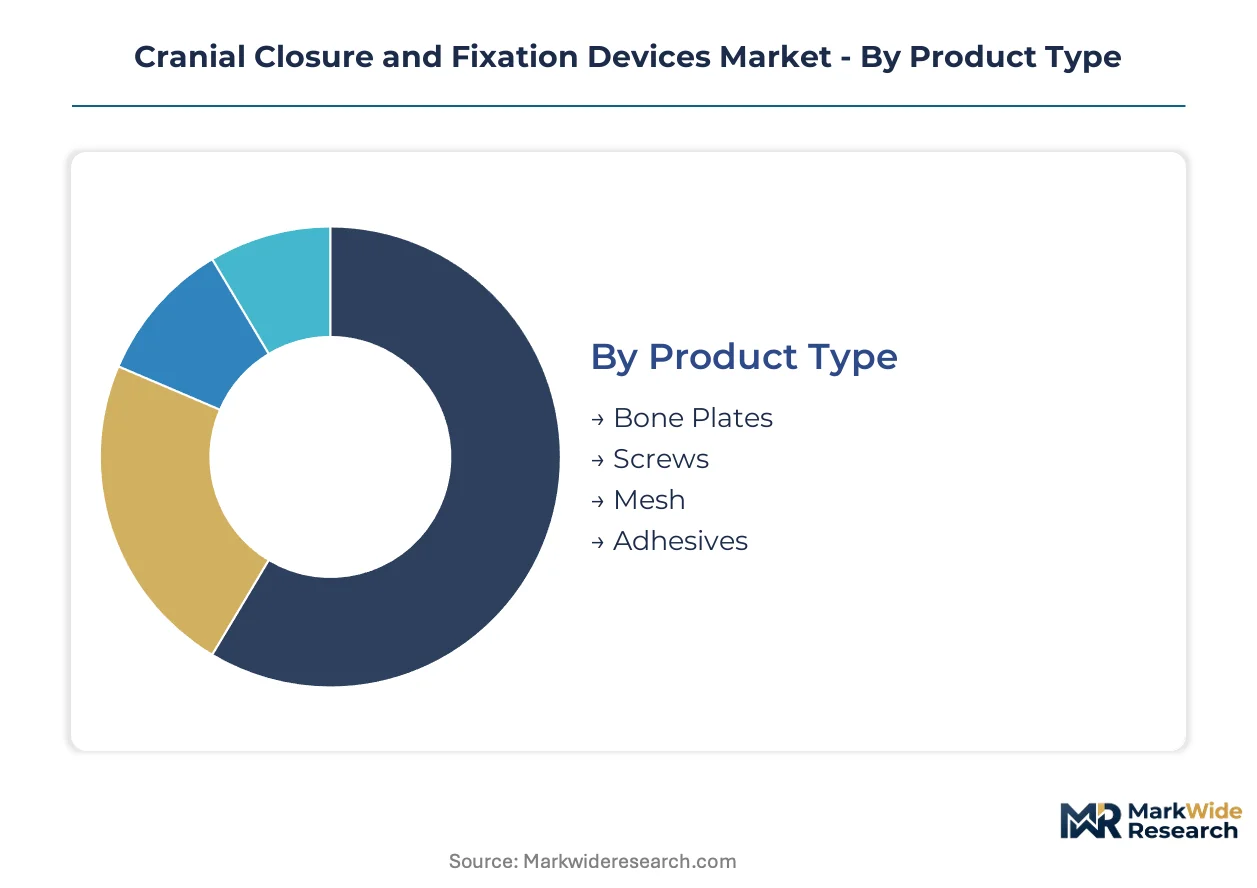
Cranial closure and fixation devices fragment across four distinct category axes, each with unique margin dynamics. Product type and material composition concentrate value in premium hardware, while technology and end-user channels determine access economics.
Product Type:
Margin pools concentrate in permanent fixation hardware, with consumable adjuncts capturing secondary value.
- Bone Plates:Machined titanium or resorbable polymer plates provide rigid structural fixation for craniotomy closure. Academic medical centers in Germany and the United States drive demand for patient-specific geometries that match individual cranial contours. Premium positioning reflects the complexity of sub-millimeter tolerance manufacturing and sterilization validation.
- Screws:Self-tapping and locking screw designs secure plates to cranial bone with torque-controlled insertion. Pediatric neurosurgery units favor resorbable polymer screws to eliminate secondary removal procedures in growing patients.
- Mesh:Titanium mesh systems enable contourable reconstruction of complex cranial defects. The material permits postoperative CT imaging without radiographic artifact distortion.
- Adhesives:Tissue adhesives and sealants supplement mechanical fixation in select cranioplasty applications. Regulatory pathways through FDA 510(k) notification govern biocompatibility requirements.
The dominant share belongs to Bone Plates, while Adhesives is closing the gap fastest.
End User:
Procurement concentration shapes channel economics, with integrated health systems extracting volume discounts unavailable to fragmented purchasers.
- Hospitals:Academic medical centers and tertiary care hospitals perform the majority of complex cranioplasty and trauma reconstruction procedures. Bundled procedural contracts spanning fixation hardware, biologics, and instrumentation capture the deepest margin pools through multi-year manufacturer agreements.
- Surgical Centers:Ambulatory surgical centers concentrate elective cranial procedures requiring shorter recovery windows. Medicare reimbursement policies for outpatient neurosurgical interventions determine case migration from inpatient settings.
- Trauma Units:Level I trauma centers require immediate availability of fixation systems for emergency craniotomy. Inventory positioning and sterilization turnaround times constrain supplier selection.
- Clinics:Outpatient clinics manage postoperative monitoring and minor revision procedures. Hardware removal and wound care generate recurring consumable demand.
Hospitals command the largest volume position, though Surgical Centers is expanding most quickly as outpatient migration accelerates.
Material:
Raw material specifications determine regulatory pathway complexity and manufacturing cost structure.
- Stainless Steel:Austenitic stainless steel alloys provide cost-effective fixation with established biocompatibility profiles. Japan's PMDA enforces JIS T 0301 testing requirements that filter lower-specification competitors from permanent implant markets.
- Titanium:Ti-6Al-4V and commercially pure titanium dominate premium cranial fixation due to strength-to-weight ratio and MRI compatibility. Stryker Corporation leverages captive titanium forging capacity to control input costs across neurosurgical portfolios.
- Biodegradable Polymers:Polylactic acid and polyglycolic acid copolymers eliminate secondary removal surgeries in pediatric populations. Surgeons in pediatric neurosurgery units are eliminating secondary removal procedures through expanded adoption of these systems.
- Ceramics:Hydroxyapatite and calcium phosphate ceramics support osteointegration in cranial defect reconstruction. Radiological imaging protocols optimized for titanium compatibility demand revalidation when transitioning to ceramic composites.
Titanium holds the established volume lead, while Biodegradable Polymers is gaining share fastest as pediatric applications expand.
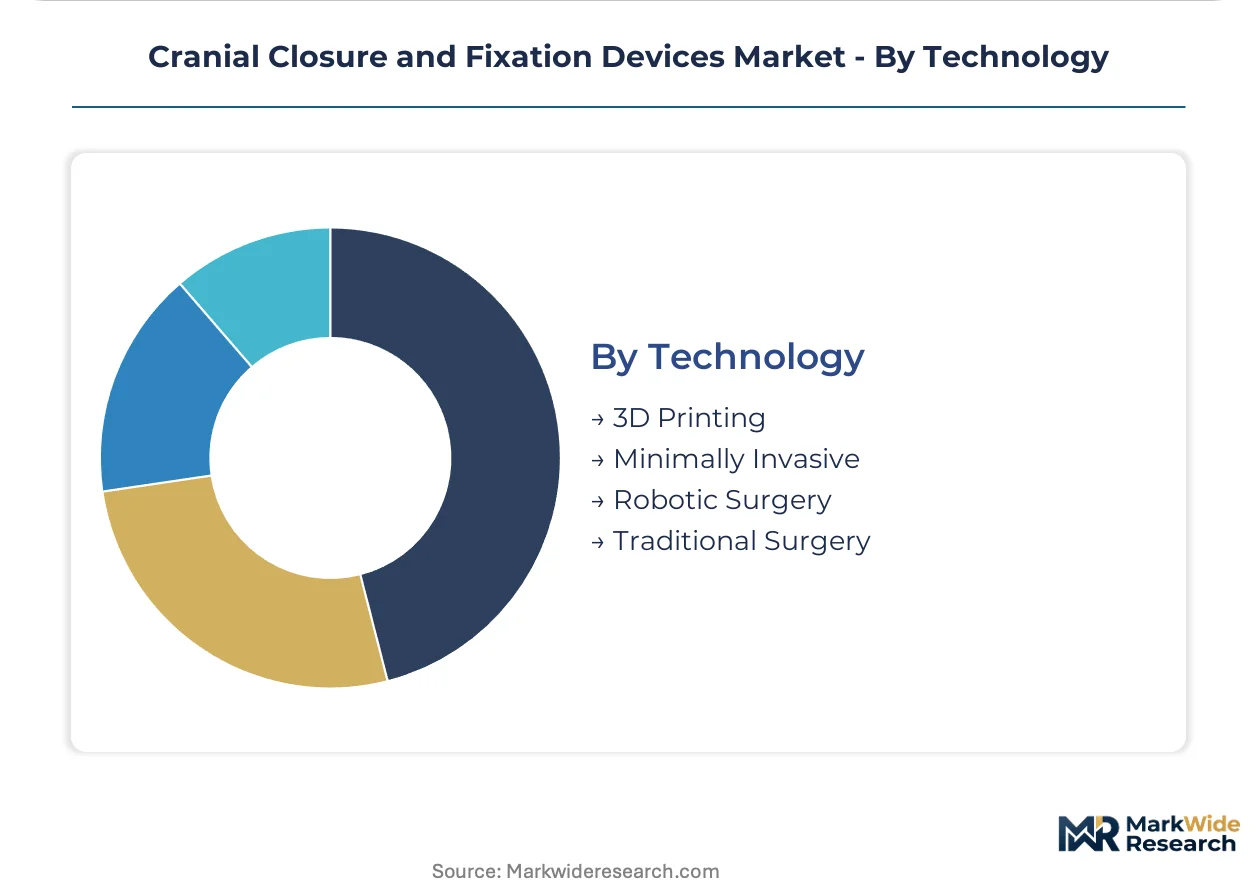
Technology:
Digital manufacturing workflows are eroding capital barriers that historically protected integrated device manufacturers from specialized competitors.
- 3D Printing:Powder-bed fusion and electron beam melting enable patient-specific implant fabrication without conventional tooling. Academic neurosurgical units in Germany and the United States are adopting these systems for on-site implant production.
- Minimally Invasive:Endoscopic and keyhole approaches reduce soft tissue disruption and recovery times. Surgical planning software paired with navigation systems enables precise hardware placement through limited access corridors.
- Robotic Surgery:Robotic platforms provide sub-millimeter precision in screw trajectory planning and execution. Capital equipment requirements and training curves constrain adoption to major metropolitan hospital systems.
- Traditional Surgery:Open craniotomy with direct visualization remains standard for complex tumor resection and trauma reconstruction. Established instrumentation and training infrastructure sustain volume in emergent and resource-limited settings.
Traditional Surgery retains the largest procedure base, though 3D Printing is climbing the fastest as digital workflows compress design-to-implant timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across neurosurgical procurement channels. Academic medical centers in Germany absorb premium pricing for patient-specific titanium implants, while cost-conscious hospital systems in India and Brazil prioritize standardized fixation hardware.
United States
FDA 510(k) premarket notification pathways streamline titanium mesh and bioresorbable plate approvals, accelerating product entry timelines. Academic medical centers in Boston and Baltimore negotiate multi-year bundled contracts spanning fixation hardware, biologics, and instrumentation. The FDA's digital health pre-certification pilots for surgical planning software are reshaping competitive access economics.
Germany
KLS Martin Group and Evonos GmbH anchor precision manufacturing clusters around Tuttlingen and Freiburg im Breisgau. The EU Medical Device Regulation mandates clinical evidence and notified body oversight for cranial fixation systems, filtering smaller suppliers from European markets. Powder-bed fusion systems at academic neurosurgical units in Heidelberg and Munich enable on-site patient-specific implant fabrication.
Japan
PMDA enforces stringent JIS T 0301 biocompatibility testing for permanent implant materials, creating compliance thresholds that exclude lower-specification competitors. Tokyo and Osaka metropolitan hospital systems concentrate demand for titanium fixation systems with MRI compatibility. The regulator's permanent implant testing requirements sustain premium positioning for established manufacturers.
China
NMPA oversight of Class III implantable devices intensifies clinical evidence requirements for cranial fixation systems. Shanghai and Beijing academic medical centers drive adoption of 3D-printed patient-specific implants through hospital-based manufacturing partnerships. Domestic titanium forging capacity is expanding to reduce dependency on imported alloy feedstock.
India
CDSCO regulatory pathways for orthopedic and neurosurgical implants are streamlining, though permanent implant biocompatibility testing remains rigorous. Mumbai and Delhi-NCR hospital systems concentrate trauma reconstruction demand where cost sensitivity favors stainless steel over titanium fixation. Government medical colleges are expanding neurosurgical training programs that standardize hardware selection protocols.
Cranial Closure and Fixation Devices Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the cranial fixation market. Integrated manufacturers with captive titanium forging capacity control input costs and supply security, while specialized design firms concentrate value in patient-specific digital workflows. Three archetypes dominate: capital-heavy integrated manufacturers, precision-focused European specialists, and assembly-dependent regional suppliers. Competitive moves center on direct hospital contracting to bypass distributor markups and 3D printing convergence to compress design-to-implant timelines.
Among integrated manufacturers, Stryker Corporation and Medtronic Plc occupy positions spanning broad neurosurgical portfolios. KLS Martin Group represents the precision-specialist archetype with concentrated European manufacturing density. These three anchors illustrate how competitive positioning splits between scale-driven supply security and design-driven customization capabilities.
| Leading Market Players |
|---|
| Stryker Corporation |
| Medtronic Plc |
| Integra LifeSciences Corporation |
| DePuy Synthes |
| B. Braun Melsungen AG |
| Zimmer Biomet Holdings Inc. |
| Johnson & Johnson |
| KLS Martin Group |
| Evonos GmbH & Co. KG |
| Others |
Supply Flow & Price Mechanics
Electron beam melting displacing subtractive milling for patient-specific cranial plate production simultaneously redistributes manufacturing value toward biomedical design software licenses and concentrates supply geography around academic medical centers in Germany and the United States equipped with powder-bed fusion systems.
Pricing Analysis
After-sales service contracts spanning sterilization validation, technical support, and revision surgeries drive lifetime value for cranial fixation manufacturers. Three-tier pricing structure across premium patient-specific titanium implants, standard modular plate systems, and economy stainless steel hardware reflects certification grade and customization level. Pricing pressure stems from hospital procurement consolidation through bundled procedural contracts that extract volume discounts. Academic medical centers in Boston and Baltimore absorb premium pricing, while cost-conscious hospital systems in India prioritize standardized fixation hardware.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for titanium alloy feedstock sourced from Chinese and Russian sponge producers. Manufacturing concentrates in Germany, the United States, and China, with raw material dependencies spanning titanium sponge, polylactic acid polymers, and cobalt-chrome alloys. Single-source vulnerability in titanium forging capacity exposes non-integrated assemblers to input cost volatility. Distribution runs through direct hospital contracting networks that bypass traditional distributor markups and secure multi-year volume commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cranial closure and fixation devices market rewards specialized biomedical engineering talent scarce outside major metropolitan hospital systems, creating capability gaps that determine competitive access in patient-specific implant fabrication and surgical planning software integration.
For Market Incumbents: Secure captive titanium forging capacity to buffer input cost volatility from Russian and Chinese feedstock disruptions. Lock in multi-year direct hospital contracts with academic medical centers to preempt emerging competitors from establishing volume relationships. FDA 510(k) clearance databases and established notified body relationships in Europe constitute defensive moats against specialized design firms lacking clinical affairs infrastructure. For New Entrants and Emerging Players: Differentiate on pediatric bioresorbable polymer systems where secondary surgery avoidance creates reimbursement flexibility unavailable to metallic fixation competitors. Target ambulatory surgical centers migrating elective cranial procedures from inpatient settings under Medicare reimbursement pressure. White-space exists in hospital-based 3D printing partnerships that compress design-to-implant timelines for trauma reconstruction cases. For Investors and Strategic Acquirers: Secondary-cycle assets sit with precision-focused European specialists concentrated around Tuttlingen and Freiburg im Breisgau manufacturing clusters. Long-term viability over a multi-year horizon hinges on clinical evidence databases supporting EU MDR post-market surveillance obligations. Watch FDA digital health pre-certification pilots for surgical planning software as an inflection indicator reshaping competitive access economics.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Optimization | Streamlined premarket notification accelerates titanium mesh and bioresorbable plate entry timelines for United States neurosurgical centers. |
| EU MDR Clinical Evidence Investment | Post-market surveillance systems tracking long-term biocompatibility outcomes filter smaller suppliers from European markets. |
| Direct Hospital Contracting Expansion | Multi-year supply agreements with academic medical centers capture margin pools previously fragmented across distributor intermediaries. |
| 3D Printing Convergence | Powder-bed fusion equipment paired with surgical planning software enables same-day implant design-to-sterilization workflows. |
| Pediatric Bioresorbable Portfolio Buildout | Polylactic acid and polyglycolic acid copolymer systems eliminate secondary removal surgeries in growing patient populations. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with neurosurgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation through FDA 510(k) filings, EU MDR notified body certifications, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up segment sizing triangulated against top-down market estimates ensured methodological consistency.
Across the analysis window, the forecasting framework modeled volume and value trajectories across product type, material composition, technology platform, and end-user channel dimensions. CAGRs derived from procedure volume growth, pricing trend analysis, and technology adoption curves. Industry-specific inputs included neurosurgical training program expansion rates and 3D printing equipment installation data at academic medical centers.
The analysis sits within stated boundaries; outcomes outside stable FDA 510(k) clearance timelines, sustained titanium alloy supply availability, and continued hospital capital expenditure on digital manufacturing equipment would require recalibration. Forecasts reflect documented assumptions about reimbursement policy continuity and regulatory pathway stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Intravascular Warming Systems Market
Medical Devices
Medical Bionic Implant/Artificial Organs Market
Medical Devices
South America C-Arms Market
Medical Devices
Specimen Retrieval Market
Medical Devices
Telehealth Device Market
Medical Devices
Global Closed System Transfer Devices Market
Medical Devices
Global Disability Devices Market
Medical Devices
Asia-Pacific Antimicrobial Coating for Medical Devices Market
Medical Devices
Compression Therapy Devices Market
Medical Devices
Europe Spinal Fusion Devices Market
Medical Devices
India Spinal Fusion Devices Market
Medical Devices
EEG Electrodes Market
Medical Devices
Capsule Endoscope and Workstations Market
Medical Devices
Vaginal Pessary Market
Medical Devices
Posterior Chamber Lens Market
Medical Devices
Europe Ambulatory Infusion Pumps Market