
 Mini Spray Bottles Market | 2026-2036
Mini Spray Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Mini Spray Bottles Market Foresight
Asset-light contract manufacturing is reconfiguring competitive entry barriers for mini spray bottle producers. Berry Global Group Inc. leverages its broad thermoforming footprint to serve mid-tier personal care brands with flexible volume commitments. Silgan Holdings Inc. anchors North American supply through captive resin sourcing and in-house mold fabrication. ALPHA PACKAGING differentiates via FDA-registered cleanroom capacity for pharmaceutical-grade mist applications.
Mini spray bottles are precision-dispensing containers, typically 50ml to 200ml, engineered with actuator mechanisms producing droplet sizes from 20 to 100 microns for controlled liquid atomization. PET dominates material selection due to chemical resistance, clarity, and compatibility with existing recycling streams, though aluminum gains traction in premium fragrance segments seeking tactile differentiation. Fine mist formats lead household and personal care applications where even coating matters, while continuous spray systems represent the fastest-growing mechanical category driven by sunscreen and body mist adoption. The 100ml size band captures the densest margin pool by balancing TSA-compliant travel convenience with per-unit economics that justify decoration investments.
FDA regulations govern refillable spray packaging intended for cosmetic and over-the-counter drug applications, requiring material stability documentation and child-resistant closure compliance where applicable. EPA rules intersect when bottles carry disinfectant or pesticide formulations, mandating specific labeling and permeation resistance thresholds. ISO 8317 child-resistant packaging standards and EU MDR traceability requirements for medical device spray systems further segment compliance obligations. Stakeholders must monitor evolving extended producer responsibility frameworks in California and the EU, as these jurisdictions test deposit-return schemes that would restructure post-consumer collection economics for single-use miniaturized packaging.
Market Dynamics
REACH compliance in Europe is tightening material specifications for plastic formulations, forcing producers to requalify resin grades and actuator assemblies while China's domestic beauty brands scale miniaturized packaging lines at unprecedented velocity.
Growth Catalysts
- Personal Care Format Miniaturization:Portable fragrance and skincare applications are pulling 50ml to 100ml formats into mass-market distribution, with TSA-compliant travel sizes becoming default SKU configurations for premium brands.
- REACH Material Requalification:European chemical safety standards are accelerating substitution of conventional plastics toward verified recyclable PET grades, creating upgrade cycles across existing installed base.
- Dual Carbon Goals:China's national emissions targets are incentivizing lightweight packaging adoption, with domestic converters investing in thinner-wall PET technologies to reduce polymer intensity per unit.
Market Restraints
- Resin Price Volatility:PET feedstock costs fluctuate with crude oil derivatives and recycled flake availability, compressing margin visibility for converters operating on quarterly price agreements.
- Mold Fabrication Concentration:Precision actuator mold production concentrates among specialized toolmakers in Germany and Japan, creating lead time bottlenecks for new product qualification.
- Aluminum Substitution in Premium Fragrance:Tactile differentiation demands from luxury houses are displacing PET in high-margin 30ml to 50ml fragrance formats, constraining volume growth in highest-value applications.
Strategic Opportunities
- Pharmaceutical-Grade Cleanroom Capacity:FDA-registered mist applications for over-the-counter drug delivery remain underpenetrated relative to cosmetic uses, offering margin expansion for qualified producers.
- Extended Producer Responsibility Schemes:California and EU deposit-return pilots are restructuring post-consumer collection economics, creating first-mover advantages for vertically integrated recyclers.
- Continuous Spray Mechanism Convergence:Sunscreen and body mist adoption is accelerating demand for bag-on-valve and mechanical continuous systems, displacing traditional finger-pump formats in outdoor recreation channels.
Industry Challenges
- ISO 8317 Child-Resistant Certification Timelines:Closure testing protocols for pharmaceutical applications require 12 to 18 month validation cycles, delaying product launches and tying up engineering resources.
- Actuator-Material Compatibility Matrix Complexity:Formulation-specific chemical resistance requirements for disinfectant and pesticide applications demand extensive permeation testing, fragmenting SKU proliferation control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mini Spray Bottles Market |
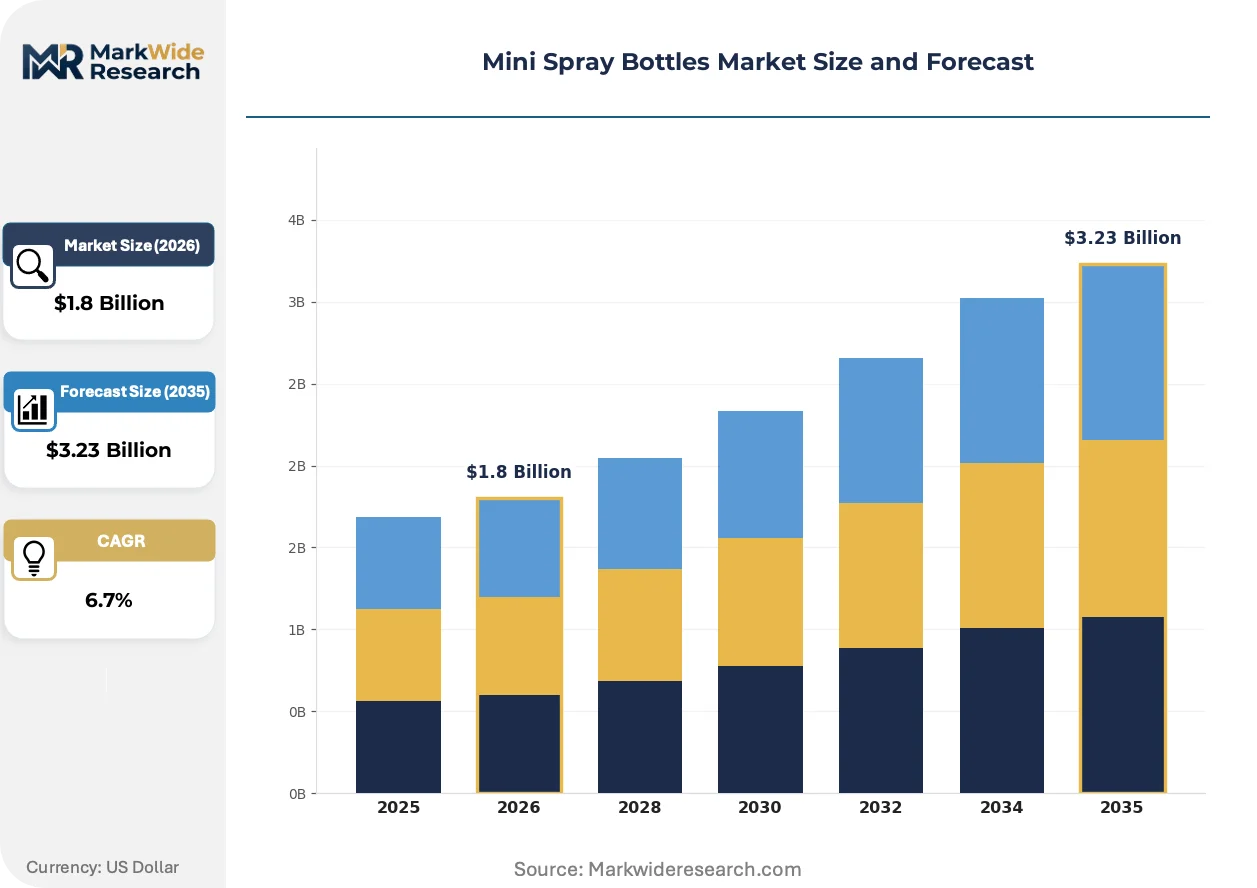
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fine Mist, Pump Spray, Trigger Spray, Continuous Spray Material: Plastic, Glass, Aluminum, PET End User: Household, Personal Care, Industrial, Automotive Size: 50ml, 100ml, 150ml, 200ml |
| Companies Covered | Gerresheimer AG, Berry Global Group Inc., Silgan Holdings Inc., Albea Group, Amcor plc, RPC Group Plc, ALPHA PACKAGING, Frapak Packaging, Graham Packaging Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mini Spray Bottles Market Shifts & Advancements
Actuator precision engineering and regulatory material requalification are converging to reshape competitive differentiation, while downstream procurement patterns compress supplier qualification cycles and reward technical service capabilities over pure unit economics.
Bag-on-valve continuous spray systems integrate compressed gas propellants with laminated aluminum pouches to deliver 360-degree dispensing without flammable hydrocarbons. Premium sunscreen and body mist brands are adopting these systems at triple-digit annual rates for outdoor and athletic positioning. Traditional piston-pump finger actuators are rendering obsolete in applications demanding even coating coverage during physical activity.
EU MDR traceability requirements for medical device spray systems mandate unique device identification and post-market surveillance documentation. Device manufacturers must now maintain technical files spanning material stability, biocompatibility, and clinical performance data. Pharmaceutical-grade mist applications face the steepest compliance burden, with European notified bodies extending review timelines by six to nine months.
Beauty brand procurement teams are consolidating supplier panels from fifteen-plus vendors to three to four strategic partners capable of integrated decoration, assembly, and regulatory documentation. Direct brand-contract manufacturer relationships are displacing traditional distributor intermediaries in North American and European supply chains. Personal care multinationals headquartered in France and Germany are most aggressive in supplier consolidation, demanding end-to-end accountability for compliance and sustainability claims.
Mini Spray Bottles Market Segmentation
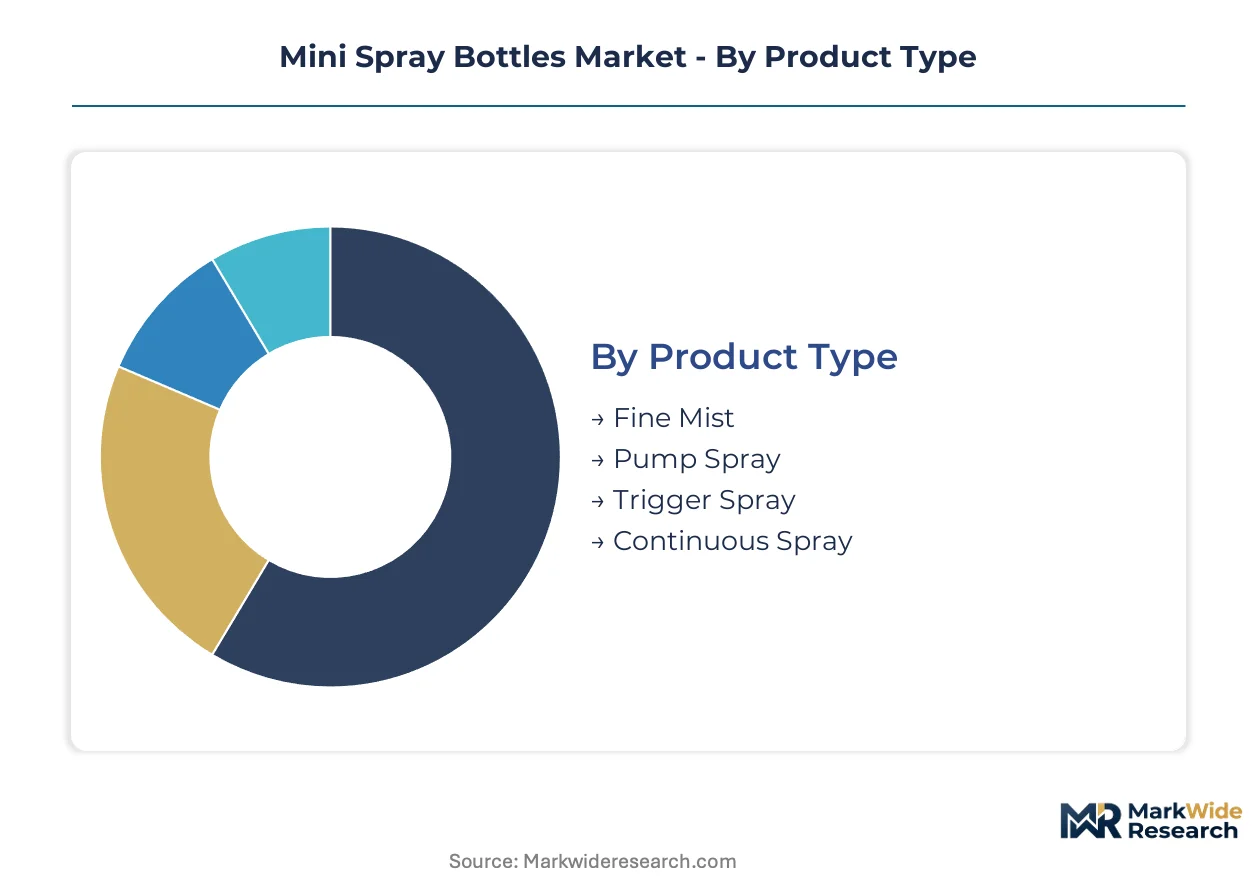
Mini spray bottles fragment across four structural dimensions that determine pricing power and regulatory exposure. Product type and material selection drive manufacturing complexity, while end-user concentration and size bands dictate volume economics and channel strategy.
Product Type:
Actuator mechanisms span a functional spectrum from precision dosing to broad-area coverage, with each format commanding distinct tooling investments and formulation compatibility requirements.
- Fine Mist:Engineered with 20-100 micron droplet precision for even coating applications. Personal care brands in France and Germany specify this format for facial toners and fragrance layering, though REACH-compliant actuator requalification has extended supplier onboarding timelines.
- Continuous Spray:Bag-on-valve and mechanical systems enable 360-degree dispensing without finger fatigue. Sunscreen and body mist adoption in China's outdoor recreation channels is climbing the fastest as domestic athletic brands scale summer SKU lines.
- Pump Spray:Traditional piston-actuated systems dominate household cleaning and automotive detailing with lower per-unit cost structures.
- Trigger Spray:Higher-volume formats serve industrial disinfectant and agricultural chemical applications where hand fatigue resistance matters.
The dominant share belongs to Fine Mist, while Continuous Spray is closing the gap fastest.
Material:
Substrate selection trades chemical resistance, optical clarity, and sustainability positioning against unit cost and decoration flexibility.
- PET:Virgin and recycled grades offer clarity, shatter resistance, and established recycling stream compatibility. European personal care brands specify verified recyclable PET grades under ECHA pressure, though recycled flake availability constrains volume scaling.
- Aluminum:Tactile weight and premium perception drive adoption in 30-50ml fragrance formats. Luxury houses in Italy and France are displacing plastic in high-margin applications where shelf differentiation justifies material cost premiums.
- Plastic:Polypropylene and HDPE variants serve cost-sensitive household and industrial channels with lower decoration investment.
- Glass:Limited to pharmaceutical and ultra-premium fragrance segments requiring inert material contact and UV protection.
PET retains volume leadership, yet Aluminum is expanding most quickly in premium repositioning strategies.
End User:
Demand concentrates in personal care and household applications, with industrial and automotive segments imposing distinct chemical resistance and durability specifications.
- Personal Care:TSA-compliant travel sizes and portable fragrance formats dominate SKU proliferation. China's domestic beauty brands—Perfect Diary, Florasis, and Winona—are scaling miniaturized packaging lines at unprecedented velocity, pulling 50-100ml formats into mass distribution.
- Household:Surface cleaners and air fresheners drive volume throughput with lower margin tolerance and higher decoration standardization.
- Industrial:Disinfectant and pesticide formulations trigger EPA permeation resistance requirements and specialized labeling mandates in US agricultural and food processing channels.
- Automotive:Detailing sprays and tire dressings demand solvent-resistant actuators and UV-stable substrates for garage and retail auto care segments.
Personal Care commands the dominant revenue pool, while Industrial is gaining share fastest through pandemic-persistent sanitization protocols.
Size:
Volume bands align with regulatory thresholds, travel convenience, and per-unit economics that justify decoration investment.
- 100ml:The densest margin band balances TSA-compliant travel convenience with sufficient surface area for premium decoration. International airlines and duty-free retailers specify this as the default configuration for fragrance and skincare sampler programs.
- 50ml:Pocket-portable formats serve on-the-go fragrance reapplication and gym bag skincare routines. Japanese and South Korean beauty brands favor this band for capsule collection marketing and subscription box inclusion.
- 150ml:Mid-size household and body mist applications where per-use cost efficiency outweighs portability requirements.
- 200ml:Maximum capacity in the mini category, serving automotive detailing and industrial concentrate dilution with pump or trigger actuation.
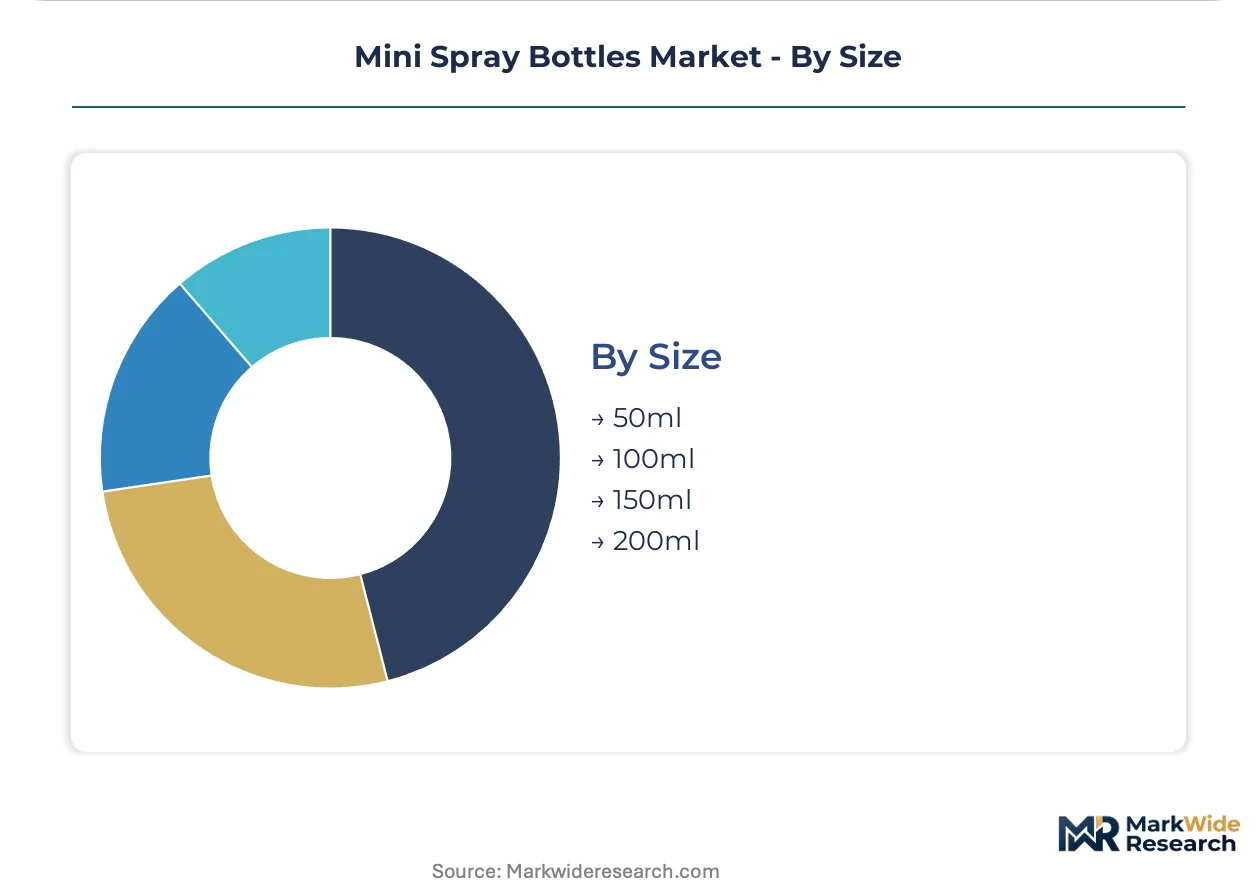
The 100ml specification holds the dominant position, while 50ml is ascending fastest through travel retail and subscription channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals are reshaping converter investment patterns across the mini spray bottle value chain, with domestic beauty brands accelerating miniaturized packaging adoption. Germany's REACH enforcement is tightening material specifications and extending supplier qualification timelines. The United States maintains dense pharmaceutical-grade demand through FDA-registered channels.
China
Domestic beauty brands—Perfect Diary, Florasis, and Winona—are scaling 50-100ml format lines at unprecedented velocity. The country's dual carbon targets under MEE oversight are incentivizing thinner-wall PET technologies to reduce polymer intensity per unit. Yangtze River Delta converters in Zhejiang and Jiangsu provinces are capturing outbound orders from European personal care brands seeking cost-competitive TSA-compliant travel sizes.
Germany
ECHA's REACH compliance protocols are forcing resin grade requalification across existing installed base, extending actuator assembly validation cycles. Personal care multinationals headquartered in France and Germany are consolidating supplier panels to three-to-four strategic partners. The Rhine-Ruhr industrial corridor hosts specialized toolmakers producing precision actuator molds with 12-18 month lead times.
United States
FDA regulations govern refillable spray packaging for cosmetic and over-the-counter drug applications, requiring material stability documentation. EPA rules intersect when bottles carry disinfectant formulations, mandating specific labeling and permeation resistance thresholds. California's extended producer responsibility pilots are testing deposit-return schemes that would restructure post-consumer collection economics.
France
Luxury fragrance houses are displacing PET with aluminum in 30-50ml formats seeking tactile differentiation and shelf presence. ANSM oversight of medical device spray systems under EU MDR mandates unique device identification and post-market surveillance documentation. The Île-de-France region anchors premium decoration investment for international airline and duty-free retailer sampler programs.
Japan
South Korean and Japanese beauty brands favor 50ml pocket-portable formats for capsule collection marketing and subscription box inclusion. METI standards guide chemical resistance specifications for household and automotive detailing applications. The Kanto region around Tokyo concentrates demand for precision-dispensing containers in on-the-go fragrance reapplication segments.
Mini Spray Bottles Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Asset-light contract manufacturing is lowering entry barriers for mid-tier personal care brands seeking flexible volume commitments. Three archetypes dominate: broad thermoforming footprint operators, captive resin sourcing integrators, and FDA-registered cleanroom specialists. Competitive moves concentrate on supplier panel consolidation by downstream beauty brands and vertical integration into precision mold fabrication.
Among North American packaging conglomerates, Berry Global Group Inc. and Silgan Holdings Inc. exemplify scale-driven channel control through flexible volume structures and captive resin sourcing respectively. ALPHA PACKAGING occupies a position within the pharmaceutical-grade specialist tier, representing FDA-registered cleanroom capacity for over-the-counter drug delivery applications. These three anchors illustrate the divergence between commodity-scale personal care supply and regulated medical-device qualification pathways.
| Leading Market Players |
|---|
| Gerresheimer AG |
| Berry Global Group Inc. |
| Silgan Holdings Inc. |
| Albea Group |
| Amcor plc |
| RPC Group Plc |
| ALPHA PACKAGING |
| Frapak Packaging |
| Graham Packaging Company |
| Others |
Supply & Pricing Matrix
Undercapacity in precision actuator mold fabrication across Germany and Japan is forcing converters to accept 12-18 month lead times and pre-pay tooling deposits, compressing margin visibility and shifting pricing power toward specialized toolmakers.
Pricing Analysis
Certification level creates the primary spread between commodity personal care supply and pharmaceutical-grade applications. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA registration status, ISO 8317 child-resistant compliance, and cleanroom production capability. Cost compression in standard-tier PET formats is intensifying because recycled flake availability lags brand commitments. Mass-market personal care brands exhibit highest price sensitivity, while pharmaceutical contract manufacturers prioritize qualification speed over unit cost.
Supply Chain Analysis
Asset-light contract manufacturers including Berry Global and Silgan Holdings anchor North American capacity, while Yangtze River Delta converters in Zhejiang and Jiangsu provinces capture outbound European orders. PET resin draws from crude oil derivatives and post-consumer recycled flake streams, with actuator assemblies resting on specialized toolmaking in Germany and Japan. Single-source vulnerability concentrates in precision mold fabrication. Distribution runs through direct brand-contract manufacturer relationships displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aluminum substitution in premium fragrance formats threatens PET incumbents with displacement from highest-margin applications, demanding defensive repositioning around regulatory qualification barriers.
For Market Incumbents: Entrench pharmaceutical-grade cleanroom capacity as a substitution shield against aluminum's tactile differentiation push. Deepen backward integration into captive resin sourcing to buffer PET feedstock volatility. Prioritize FDA registration maintenance as the priority lever for margin defense. For New Entrants and Emerging Players: China's domestic beauty brand supply gap represents the most penetrable white-space, with Perfect Diary and Florasis scaling miniaturized lines faster than qualified converter capacity. Target pharmaceutical-grade mist applications where ISO 8317 certification timelines deter commodity competition. Pursue asset-light contract manufacturing partnerships to bypass mold fabrication bottlenecks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among FDA-registered cleanroom specialists serving over-the-counter drug delivery. Five-to-ten-year viability favors vertically integrated players with captive resin sourcing and in-house mold fabrication. Watch for ECHA REACH enforcement intensity as the signal indicating upgrade-cycle timing for European installed base replacement.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Cleanroom Investment | FDA registration creates defensible margin pools against aluminum substitution in premium segments. |
| Backward Integration into Resin Sourcing | Captive PET supply buffers crude oil derivative volatility and secures recycled flake allocation. |
| Precision Mold Fabrication Acquisition | In-house toolmaking collapses 12-18 month lead times and accelerates new product qualification. |
| Extended Producer Responsibility Partnership | Vertical integration into recycling infrastructure captures deposit-return scheme economics in California and EU pilots. |
| Continuous Spray Mechanism Development | Bag-on-valve expertise positions for sunscreen and body mist adoption in China's outdoor recreation channels. |
Research Methodology
Desk research of regulatory filings, customs trade records, and industry association disclosures preceded structured interviews with packaging procurement directors, contract manufacturing executives, precision mold toolmakers, and ECHA compliance officers. Primary fieldwork with brand-side sustainability leads and converter operations managers cross-validated secondary data from FDA registration databases, REACH substance dossiers, and EU MDR technical file repositories. Bottom-up volume modeling triangulated against top-down category spend analysis.
Assumptions held fixed include REACH enforcement intensity, dual carbon goal trajectory under China's MEE, and TSA liquid restriction thresholds. Variable inputs spanned crude oil price bands, recycled PET flake availability, and pharmaceutical qualification timeline extensions. Segmentation dimensions covered actuator mechanism type, material substrate, end-use industry concentration, and size band economics. CAGRs derived from regression against historical packaging intensity ratios and beauty brand SKU proliferation rates. Continuous spray adoption curves and aluminum substitution elasticity informed scenario-weighted outputs.
Practitioners should monitor ECHA substance restriction proposals, MEE carbon intensity enforcement, and California deposit-return pilot expansion for early signals of forecast revision. Quarterly review of resin price indices, mold fabrication lead times, and FDA 510(k) submission volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Trigger Sprayer Market
Containers
Shipping Container Liners Market
Containers
HDPE Bottles Market
Containers
Essential Oil Containers Market
Containers
Water Resistant Packing Cubes Market
Containers
Foam Containers Market
Containers
Oblong Tub Lids Market
Containers
HDPE Containers Market
Containers
Stock Clamshell Packaging Market
Containers
ISO Ocean Containers Market
Containers
Lift-Off Lid Box Market
Containers
Grab and Go Containers Market
Containers
Spout Containers Market
Containers
Old Corrugated Containers (OCC) Market
Containers
Lever Lid Cans Market
Containers
Carboy Market