
 Milk Sterilizer Machine Market | 2026-2036
Milk Sterilizer Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Milk Sterilizer Machine Market Foresight
Small and mid-sized dairy cooperatives is rotating toward automated continuous sterilizer lines as labor costs climb and batch inefficiencies erode margins. Tetra Pak International leverages its integrated packaging-sterilizer ecosystem to lock in long-term dairy contracts across Southeast Asia and Africa. GEA Group anchors its position through captive engineering services that reduce plant commissioning time for greenfield dairy facilities. Alfa Laval competes on heat exchanger density, offering compact UHT modules that fit retrofitted European plants with constrained floor space.
A milk sterilizer machine heats raw milk to temperatures that eliminate pathogenic microorganisms, typically operating between 72°C for HTST pasteurization and 140°C for UHT treatment, with precise hold-time control to preserve nutritional integrity while extending shelf life. Continuous sterilizers dominate volume sales in large-scale dairy processing due to throughput economics, while batch systems retain share among artisanal creameries and pharmaceutical-grade milk ingredient producers where flexibility outweighs unit cost. Thermal sterilization technology leads installed base but faces margin compression from energy costs, pushing R&D toward hybrid thermal-filtration systems that cut steam consumption.
FDA pasteurized milk ordinance and EU MDR-equivalent food contact material rules shape equipment design standards, forcing manufacturers to validate every surface alloy and seal compound for thermal cycling durability. India's FSSAI dairy safety codes and China's GB standards for sterilized milk are tightening pathogen detection thresholds, which drives replacement demand for older machines that cannot log HACCP-compliant temperature traces. Stakeholders must weigh energy retrofit economics against full equipment replacement as carbon border adjustments begin factoring into dairy export compliance costs.
Market Dynamics
Dairy processors face mounting pressure to cut thermal energy intensity as carbon border adjustments reshape export compliance costs. Continuous sterilizer adoption accelerates where cooperative networks consolidate processing volumes.
Growth Catalysts
- FSSAI dairy safety codes:India's tightened pathogen detection thresholds force replacement of legacy machines lacking HACCP-compliant temperature logging.
- HTST-to-UHT upgrade cycles:Shelf-stable milk demand in tropical climates drives continuous sterilizer procurement across Southeast Asian dairy cooperatives.
- Hybrid thermal-filtration R&D:Steam consumption reduction targets push equipment makers toward membrane-integrated sterilization architectures.
Market Restraints
- Stainless steel alloy volatility:316L and 304 grade price swings compress margins for heat exchanger fabricators serving mid-tier dairy plants.
- Commissioning specialist scarcity:Greenfield dairy facilities in Sub-Saharan Africa face 8-14 week delays securing certified sterilizer installation engineers.
- Electrical thermal substitution:Steam-based sterilizer installed base faces displacement risk from resistive heating modules in markets with grid decarbonization mandates.
Strategic Opportunities
- EU F-Gas Regulation phase-down:Refrigeration-dependent dairy processors seek sterilizer-integrated cooling systems using natural refrigerants.
- Artisanal creamery automation:Small-batch flexibility gaps create white space for compact continuous sterilizers with rapid product changeover.
- Pharmaceutical-grade milk ingredients:Infant formula and medical nutrition producers demand validated aseptic processing lines with isolator technology.
Industry Challenges
- Commissioning timeline compression:Dairy cooperatives in India demand 90-day plant startup windows that strain captive engineering service capacity.
- Retrofit integration complexity:European plants with constrained floor space struggle to accommodate compact UHT modules alongside legacy batch infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Milk Sterilizer Machine Market |
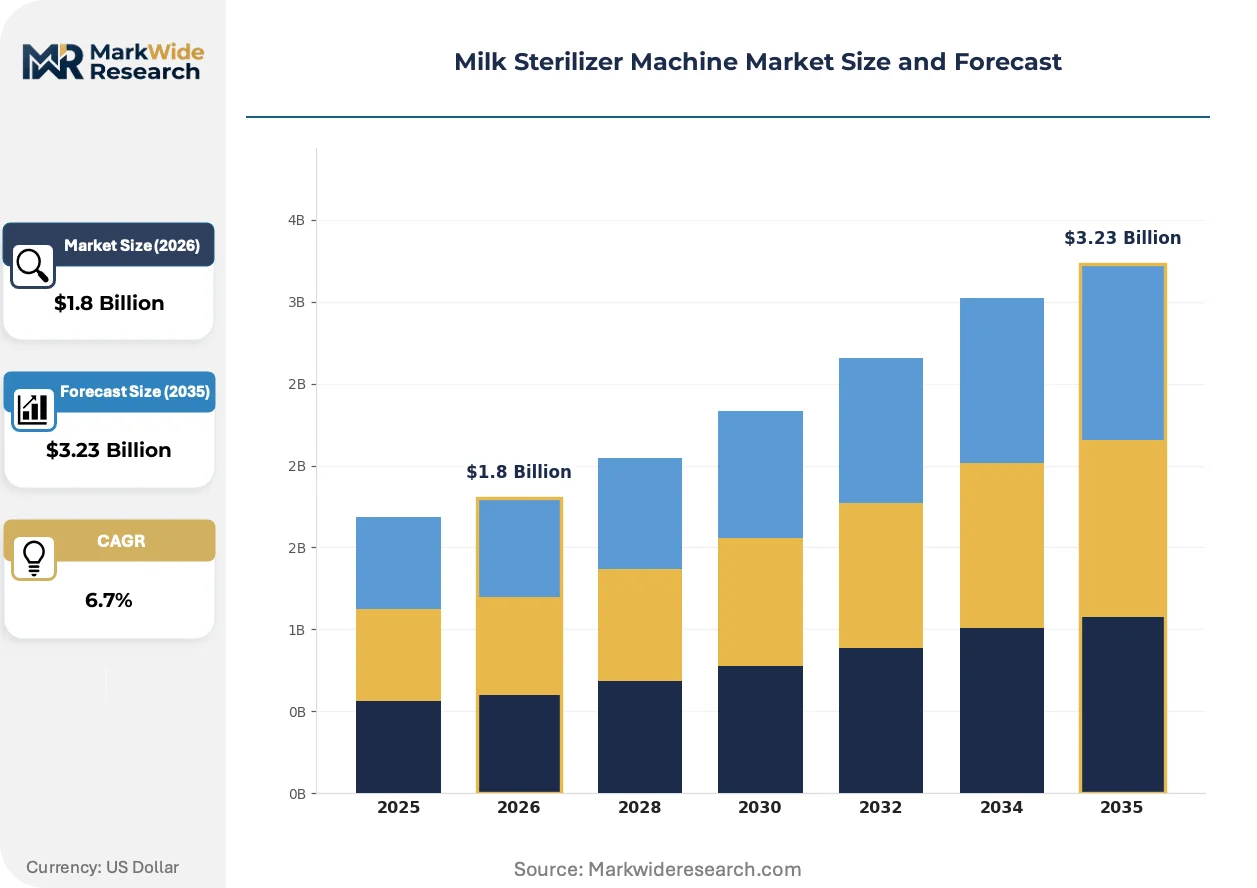
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Sterilizer, Continuous Sterilizer, UHT Sterilizer, Instant Sterilizer Application: Dairy Processing, Food Preservation, Pharmaceuticals, Beverage Industry Technology: Thermal Sterilization, Filtration Sterilization, Chemical Sterilization, Radiation Sterilization End User: Dairy Manufacturers, Food Service Providers, Retailers, Institutions |
| Companies Covered | Tetra Pak International, GEA Group, Krones, SPX Flow, Alfa Laval, Della Toffola, INOXPA, Dion Engineering, JBT Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Milk Sterilizer Machine Market Shifts & Advancements
Equipment architecture is fragmenting as energy costs and carbon accounting force dairy processors to reevaluate thermal sterilization economics. Three distinct vectors are reshaping competitive positioning.
Hybrid thermal-filtration systems are decomposing the traditional steam-heated sterilizer value proposition. Large-scale dairy processors in Brazil and Mexico pilot membrane-integrated UHT lines that cut steam consumption by pre-concentrating milk solids. This convergence is decomposing the installed base advantage of pure thermal equipment makers.
EU MDR-equivalent food contact material rules now govern seal compound validation for thermal cycling durability. Equipment manufacturers must document alloy surface treatments and elastomer performance across 10,000+ cycle lifespans. European retrofit projects face 6-9 month certification delays as notified bodies queue material dossier reviews.
Service unbundling is fragmenting traditional sterilizer procurement. Dairy cooperatives in Gujarat and Karnataka now separate equipment purchase from commissioning contracts, pitting Tetra Pak's integrated ecosystem against standalone engineering firms. This disaggregation is most visible where government-backed dairy infrastructure programs mandate open tendering for sterilizer lines.
Milk Sterilizer Machine Market Segmentation
Milk sterilizer procurement patterns diverge sharply between high-throughput dairy cooperatives and small-batch artisanal producers. Equipment selection hinges on thermal energy economics, regulatory compliance architecture, and floor space constraints that vary by processing scale.
Product Type:
Continuous sterilizers face the most acute substitution pressure from hybrid thermal-filtration systems that promise steam consumption reductions.
- Continuous Sterilizer:These systems maintain unbroken product flow through plate or tubular heat exchangers, achieving throughput rates that batch systems cannot match. Demand concentrates in Indian cooperative dairy networks where government-backed infrastructure programs mandate bulk procurement of UHT-capable lines. The 90-day plant startup windows common in Gujarat and Karnataka strain engineering service capacity.
- UHT Sterilizer:Operating at 135-150°C with 2-8 second hold times, these units deliver shelf-stable milk for tropical distribution. Southeast Asian dairy processors favor Alfa Laval's compact modules where retrofitted European plants face floor space constraints.
- Batch Sterilizer:Flexibility for artisanal creameries and pharmaceutical-grade milk ingredient producers where product changeover frequency outweighs unit cost penalties.
- Instant Sterilizer:Direct steam injection systems for beverage industry applications requiring minimal thermal degradation of flavor compounds.
Continuous sterilizers anchor the volume base while UHT sterilizers gain share at the steepest rate.
Application:
Cost tier stratification separates commodity milk processing from validated aseptic lines serving medical nutrition markets.
- Dairy Processing:HTST pasteurization at 72°C for fresh milk distribution competes against UHT treatment for ambient shelf life extension. Brazilian and Mexican processors pilot membrane-integrated lines that pre-concentrate milk solids before thermal treatment.
- Pharmaceuticals:Infant formula and medical nutrition producers demand isolator technology with validated aseptic processing documentation. EU MDR-equivalent food contact material rules govern seal compound validation for thermal cycling durability across 10,000+ cycle lifespans.
- Food Preservation:Extended shelf-life dairy ingredients for bakery and confectionery applications.
- Beverage Industry:Plant-based milk alternatives and formulated dairy drinks requiring precise protein denaturation control.
Dairy processing commands the installed base while pharmaceutical applications expand most quickly on per-unit value metrics.
Technology:
Volume concentration favors thermal methods, though R&D investment tilts toward membrane-integrated architectures.
- Thermal Sterilization:Steam-heated plate heat exchangers dominate installed capacity but face margin compression from energy costs. Carbon border adjustments reshape export compliance economics for carbon-intensive thermal processing.
- Filtration Sterilization:Microfiltration and ultrafiltration membranes remove bacteria without thermal degradation, preserving heat-sensitive whey proteins. Hybrid systems combining membrane pre-concentration with reduced thermal treatment cut steam consumption in Brazilian pilot installations.
- Chemical Sterilization:Peroxide-based cold sterilization for packaging materials in aseptic filling systems.
- Radiation Sterilization:Limited dairy application due to consumer acceptance barriers and regulatory complexity.
Thermal sterilization retains volume leadership while filtration-thermal hybrids climb the fastest on energy efficiency mandates.
End User:
Customer type determines procurement bundling preferences, with cooperates increasingly unbundling equipment purchase from commissioning contracts.
- Dairy Manufacturers:Large-scale processors in India, Brazil, and Mexico drive continuous sterilizer procurement through consolidated cooperative networks. Tetra Pak's integrated packaging-sterilizer ecosystem competes against standalone engineering firms where open tendering rules apply.
- Food Service Providers:Central kitchens and catering operations requiring batch flexibility for menu-diverse dairy procurement.
- Retailers:Private-label milk processors seeking standardized UHT capacity for store-brand shelf-stable products.
- Institutions:Hospital and school feeding programs with predictable volume requirements but limited technical staffing for complex system maintenance.
Dairy manufacturers anchor procurement volume while food service providers represent the most fragmented expansion opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Western Dedicated Freight Corridor and allied cold-chain rail infrastructure underwrite India's role as the dominant procurement geography for continuous sterilizer systems. Brazil's Santos Port complex anchors Latin American dairy equipment flows into the Mercosur processing belt. Germany's Rhine-Ruhr industrial corridor channels engineering services across European retrofit markets.
India
Cooperative dairy networks in Gujarat and Karnataka drive bulk procurement of UHT-capable continuous lines. FSSAI dairy safety codes mandate HACCP-compliant temperature logging that obsolete equipment cannot satisfy. The Anand milk shed and surrounding districts concentrate government-backed infrastructure programs consolidating processing volumes.
Brazil
Large-scale processors pilot membrane-integrated UHT lines that pre-concentrate milk solids before thermal treatment. ANVISA's tightening pathogen detection thresholds accelerate replacement cycles for legacy steam-heated systems. São Paulo state's dairy belt anchors Mercosur equipment demand as cooperative networks consolidate.
Germany
Engineering-intensive retrofit projects dominate as constrained floor space forces compact module adoption. EU MDR-equivalent food contact material rules govern seal compound validation across 10,000+ cycle lifespans. The Rhine-Ruhr corridor channels captive commissioning services toward Eastern European greenfield facilities.
United States
FDA pasteurized milk ordinance shapes equipment design standards for thermal cycling durability. The Upper Midwest dairy belt concentrates HTST-to-UHT upgrade demand as shelf-stable milk formats expand distribution reach. Wisconsin and Minnesota processing cooperatives face carbon border adjustment pressures reshaping thermal energy economics.
China
GB standards for sterilized milk tighten pathogen detection thresholds driving equipment replacement. The Yangtze River Delta dairy processing cluster absorbs compact UHT modules from European suppliers. State-backed dairy infrastructure programs in Shandong and Hebei provinces mandate open tendering for sterilizer lines.
Milk Sterilizer Machine Market Competitive Landscape
Listed leaders compete with private specialists across engineering service bundling and packaging integration dimensions. The vendor base organizes around three strategic archetypes: integrated packaging-sterilizer ecosystem providers, standalone heat exchanger fabricators, and captive engineering service operators. Consolidation pressure concentrates in Indian cooperative procurement where government tendering rules favor unbundled equipment purchase. Dominant competitive moves include geographic expansion through local commissioning partnerships and portfolio diversification into hybrid thermal-filtration architectures.
Among European-listed engineering groups, GEA Group and Alfa Laval occupy positions anchoring the premium equipment tier through differentiated heat exchanger density and service bundling. Tetra Pak International exemplifies the integrated ecosystem archetype competing against disaggregated procurement patterns in emerging markets. These three entities represent the competitive structure governing large-scale dairy cooperative procurement across India, Southeast Asia, and Latin America.
| Leading Market Players |
|---|
| Tetra Pak International |
| GEA Group |
| Krones |
| SPX Flow |
| Alfa Laval |
| Della Toffola |
| INOXPA |
| Dion Engineering |
| JBT Corporation |
| Others |
Supply & Pricing Matrix
Membrane-integrated sterilization architectures replacing pure thermal systems are redrawing procurement geography toward Brazilian and Mexican pilot installations while compressing price premiums for legacy steam-heated equipment. This substitution dynamic simultaneously concentrates engineering service demand in India and fragments equipment bundling as dairy cooperatives unbundle purchase from commissioning contracts.
Pricing Analysis
Volume-discount tiering structures separate multinational dairy cooperatives procuring UHT-capable continuous lines from artisanal creameries sourcing batch systems. Pricing stratifies across premium certification tiers for pharmaceutical-grade aseptic processing, standard dairy processing modules, and economy-grade batch equipment for emerging cooperatives. Cost compression in the standard tier is intensifying because stainless steel 316L and 304 grade volatility erodes fabricator margins. Mid-tier dairy plants exhibit highest price sensitivity, while infant formula producers accept premium positioning for validated isolator technology.
Supply Chain Analysis
Port congestion at Santos and Mumbai trade lanes elevates inbound logistics costs for European heat exchanger fabricators serving Latin American and South Asian greenfield facilities. Supply concentrates in Germany's Rhine-Ruhr engineering corridor, India's Anand milk shed equipment clusters, and China's Yangtze River Delta manufacturing belt. Component sourcing draws from Italian seal compound specialists, Swedish heat exchanger plate suppliers, and domestic stainless steel processors. Single-source vulnerability in certified installation engineering creates 8-14 week commissioning delays for Sub-Saharan African facilities. Distribution runs through captive engineering service networks for integrated ecosystem providers and open-tender channels for unbundled procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The milk sterilizer machine market functions as a service-attach opportunity where commissioning and aftermarket engineering contracts expand faster than hardware sales as dairy cooperatives demand 90-day plant startup guarantees.
For Market Incumbents: Shield installed base advantage by deepening captive engineering capacity in Gujarat and Karnataka where government tendering mandates unbundled procurement. Accelerate certification investment for EU MDR-equivalent food contact material rules governing seal compound validation across 10,000+ cycle lifespans. Vertical integration into membrane-integrated hybrid architectures defends margin position against pure thermal equipment displacement. For New Entrants and Emerging Players: Lead with compact continuous sterilizer designs targeting artisanal creamery automation gaps where rapid product changeover capability commands pricing flexibility. Target pharmaceutical-grade milk ingredient processors in medical nutrition markets where isolator technology requirements create specialist entry barriers. Pursue commissioning-only engineering contracts where Indian cooperative networks have already separated equipment purchase from installation services. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors engineering-service-heavy equipment specialists over pure hardware fabricators. Long-term viability rests on hybrid thermal-filtration R&D pipelines and regulatory certification depth rather than manufacturing scale alone. Monitor FSSAI enforcement intensity as the inflection signal indicating replacement cycle acceleration for legacy temperature-logging equipment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Manufacturing | GEA Group and Alfa Laval secure supply of filtration components for hybrid sterilizer architectures. |
| Captive Engineering Service Expansion | Tetra Pak extends commissioning capacity to meet 90-day startup windows demanded by Indian dairy cooperatives. |
| Certification Investment for EU MDR-Equivalent Rules | Equipment makers document alloy surface treatments and elastomer performance to access European retrofit markets. |
| Compact Module Development for Floor-Constrained Plants | Alfa Laval targets retrofitted European facilities with heat exchanger density advantages in constrained spaces. |
| Open Tendering Partnership Programs | Standalone engineering firms align with government-backed dairy infrastructure programs in Karnataka and Shandong. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC filings from listed engineering groups, and FSSAI regulatory notifications. Primary interviews engaged dairy plant engineers, cooperative procurement managers, sterilizer commissioning specialists, and aftermarket service heads. Secondary validation drew from EU MDR-equivalent food contact material rule filings, ANVISA pathogen detection threshold updates, and equipment tender documentation from Indian state dairy federations. Bottom-up unit economics triangulate against top-down market sizing across the analysis window.
Segmentation dimensions modeled include sterilizer product type, application tier, technology architecture, and end-user procurement pattern. CAGRs derive from installed base replacement cycles, cooperative network consolidation trajectories, and energy retrofit economics against full equipment replacement. Forecast inputs incorporate stainless steel alloy price volatility assumptions and carbon border adjustment implementation timelines affecting thermal processing export compliance.
Forecasts assume regulatory continuity in FSSAI dairy safety codes, EU MDR-equivalent food contact material rules, and FDA pasteurized milk ordinance standards; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Tunnel Oven Market
Food Processing Equipment
Flakes Making Machine Market
Food Processing Equipment
Food Waste Disposal Equipment Market
Food Processing Equipment
Industrial Food Slicers Market
Food Processing Equipment
Portable Clean-In-Place Market
Food Processing Equipment
Ribbon Blenders Market
Food Processing Equipment
Oceania Commercial Ice Machine Market
Food Processing Equipment
Europe Industrial Food and Beverages Filtration System Market
Food Processing Equipment
North America Beverage Filling and Capping Machine Market
Food Processing Equipment
Global Food Processing Market
Food Processing Equipment
Cider Brewing Equipment Market
Food Processing Equipment
Global Meat Mixer Market
Food Processing Equipment
Automatic Evisceration System Market
Food Processing Equipment
Salmon Fish Scaling Machine Market
Food Processing Equipment
Cake Cutting Machines Market
Food Processing Equipment
Countertop Convection Oven Market