
 Tunnel Oven Market | 2026-2036
Tunnel Oven Market Size, Share, and Industry Trends Forecast 2026-2036
Tunnel Oven Market Analytics
Buyer concentration across European commercial bakeries is rebalancing as mid-sized producers merge to secure retail supply contracts, while artisan cooperatives fragment procurement across smaller custom units. Middleby Corporation leverages its portfolio breadth to serve consolidated bakery groups with integrated thermal systems. Sveba Dahlen specializes in Scandinavian precision engineering for high-throughput lines. Baker's Pride anchors North American supply through durable gas-fired platforms for independent operators.
A tunnel oven is a continuous baking system where products move on a conveyor belt through a heated chamber, typically operating at temperatures between 150°C and 300°C with residence times adjusted via belt speed control for uniform crust development and moisture extraction. Electric and gas configurations dominate current installations, though hybrid systems are capturing margin pools as energy volatility prompts dual-fuel redundancy. Convection technology leads in throughput efficiency for standard bread and pastry formats, while radiant heat retains preference in premium confectionery where surface browning precision commands price premiums.
EMA machinery safety directives, FDA food contact surface regulations, and BIS electrical safety standards for commercial cooking equipment collectively shape product certification requirements and cross-border market access protocols. OSHA ventilation and combustion safety rules in the United States further constrain equipment design for gas-fired installations. Stakeholders must monitor evolving carbon border adjustments and energy labeling schemes to anticipate which thermal technologies will retain procurement eligibility across key national markets.
Market Dynamics
Energy efficiency mandates under the EU Ecodesign Directive are forcing accelerated replacement cycles across European commercial baking operations, compressing equipment lifespans from fifteen to eight years in Germany and Italy.
Growth Catalysts
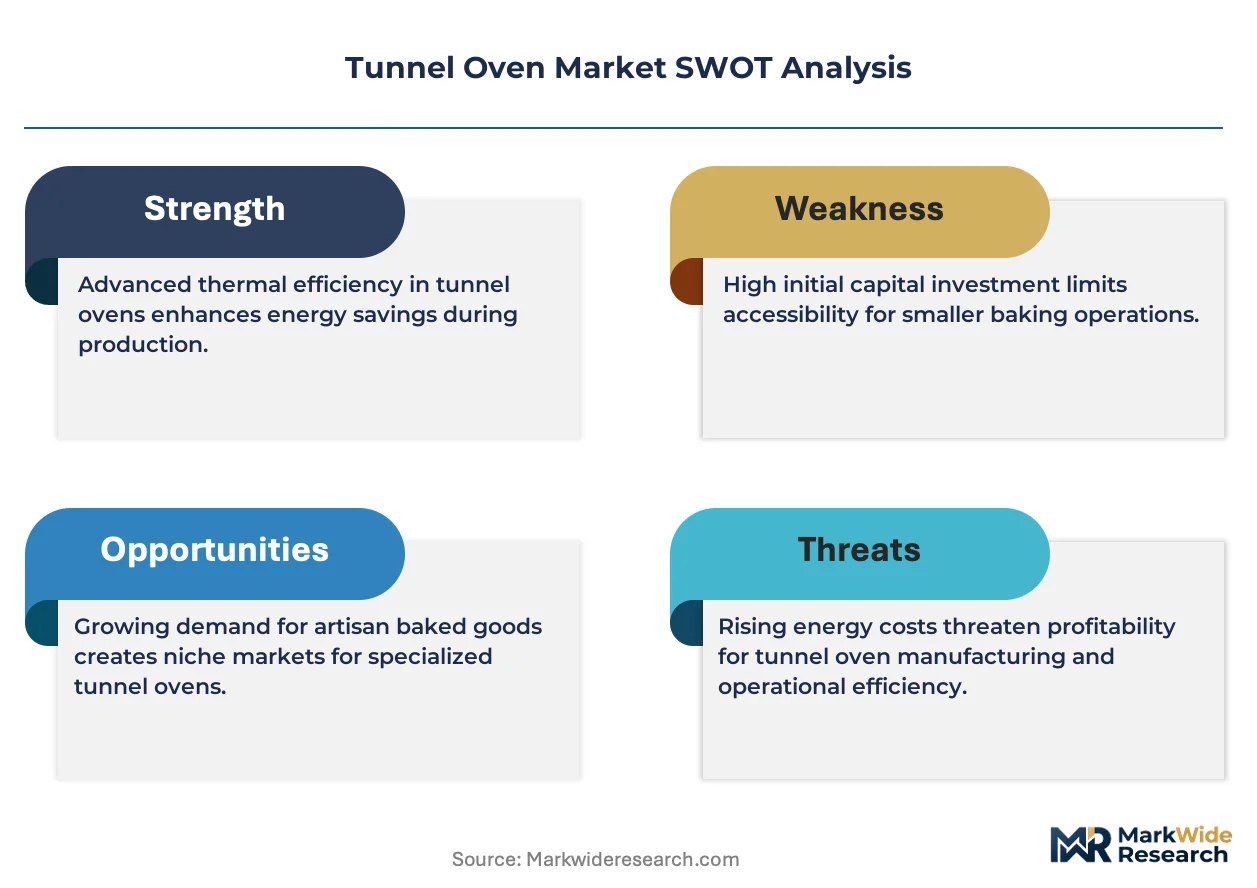
- EU Ecodesign Directive compliance deadlines:Mandatory efficiency thresholds are compelling bakeries in Germany and Italy to retire legacy thermal systems ahead of schedule, creating replacement demand.
- Artisan cooperative fragmentation:Small-scale baking collectives across Scandinavia are procuring custom-configured tunnel ovens for specialty product lines, diversifying the buyer base.
- Hybrid fuel redundancy:Dual electric-gas configurations are capturing procurement preference as energy price volatility prompts bakeries to secure operational continuity.
Market Restraints
- Stainless steel input volatility:Fluctuations in nickel and chromium prices are compressing equipment margins and extending quote validity periods for European manufacturers.
- Combustion safety retrofit costs:OSHA ventilation rules in the United States require costly hood and exhaust modifications for gas-fired installations, constraining upgrade decisions.
- Radiant heat throughput ceiling:Premium confectionery producers face hard limits on line speed when precise surface browning is required, capping volume scalability.
Strategic Opportunities
- India commercial bakery expansion:Urban retail chains in Mumbai and Bangalore are installing automated lines, creating first-mover advantage for equipment suppliers meeting BIS electrical safety standards.
- Carbon border adjustment readiness:EU Green Deal implementation is rewarding low-carbon thermal technology, positioning electric and hybrid oven suppliers for preferential procurement.
- Convection-radiant convergence:Hybrid heating architectures combining throughput efficiency with browning precision are opening margin pools in premium bread segments.
Industry Challenges
- Thermal process engineering talent scarcity:Specialized expertise in heat transfer optimization for continuous baking systems is concentrating at a handful of technical institutes in Germany and Sweden.
- Legacy PLC integration complexity:Bakeries with Siemens or Allen-Bradley automation infrastructure face protocol mismatches when retrofitting new oven controls, extending commissioning timelines.
- Multi-jurisdiction certification timelines:Simultaneous EMA machinery safety, FDA food contact, and BIS electrical approvals are stretching product launch schedules by fourteen to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tunnel Oven Market |
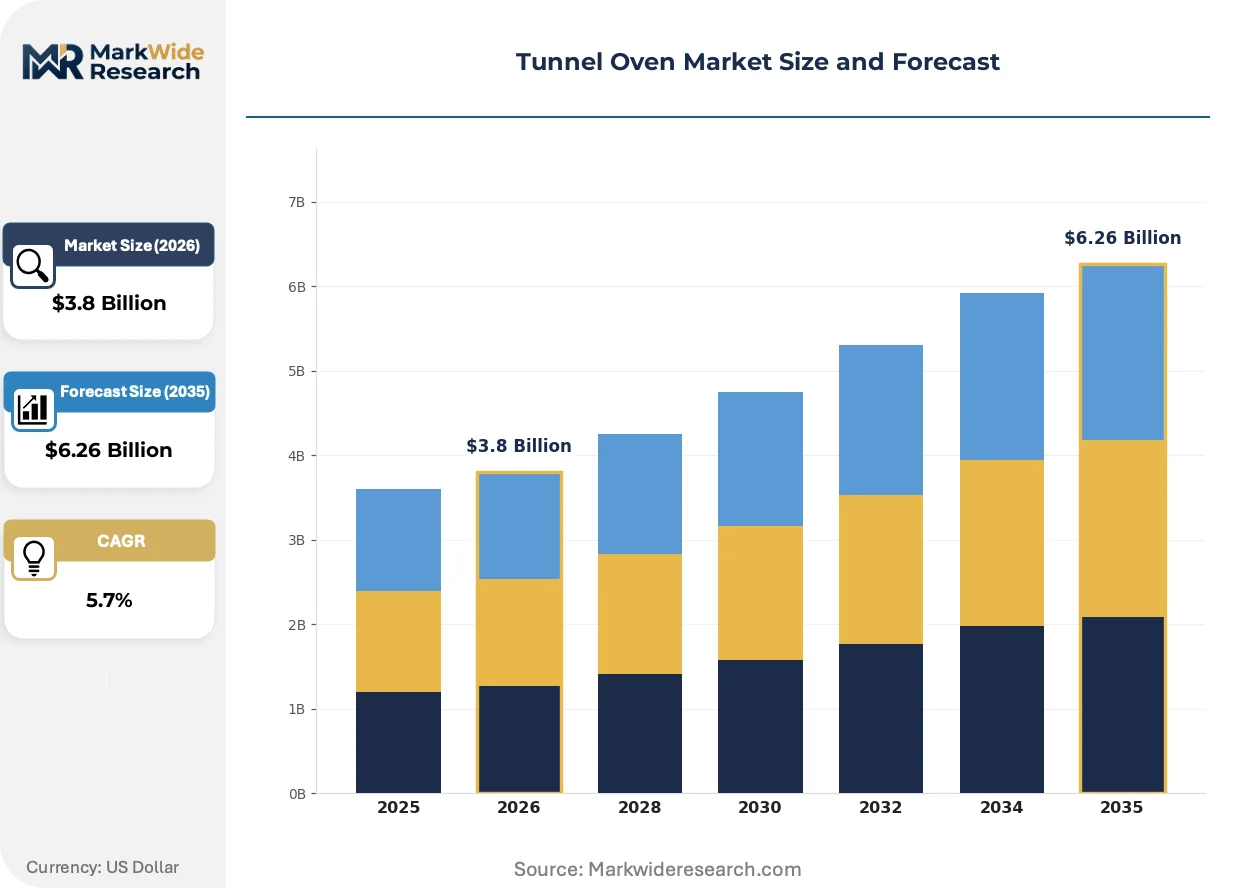
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Gas, Hybrid, Infrared End User: Bakery, Confectionery, Snack Production, Pharmaceuticals Technology: Direct Flame, Convection, Radiant Heat, Contact Size: Small, Medium, Large, Custom |
| Companies Covered | Sveba Dahlen, Middleby Corporation, Blodgett, Baker's Pride, Cleveland, Doyon, Hobart, Moffat, Rational, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tunnel Oven Market Evolving Landscape
Thermal system architectures are bifurcating as energy price instability and precision requirements pull equipment design in divergent directions, rewarding suppliers with configurable platform strategies.
Infrared radiant heating modules are absorbing capital allocation from conventional convection systems in premium confectionery segments where surface chemistry control commands price premiums. Belgian chocolate manufacturers and French patisserie chains are specifying these configurations despite twenty-five percent throughput penalties. The technology is absorbing margin from standard equipment tiers by enabling product differentiation that justifies higher retail pricing.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in auxiliary cooling systems, compelling oven manufacturers to specify alternative heat recovery architectures. Industrial bakeries in the Netherlands and Denmark are retrofitting exhaust-to-water heat exchangers to maintain operational permits. German equipment suppliers are responding with integrated thermal management packages that eliminate auxiliary cooling loads entirely.
Retail contract consolidation is compressing equipment procurement cycles as merged bakery groups centralize capital planning and standardize platform specifications. Mid-sized producers in Bavaria and Baden-Württemberg are consolidating previously fragmented purchasing authority into technical committees. This concentration is visible most acutely in southern Germany, where industrial baking clusters around Munich and Stuttgart drive premium equipment procurement with accelerated decision timelines.
Tunnel Oven Market Segmentation
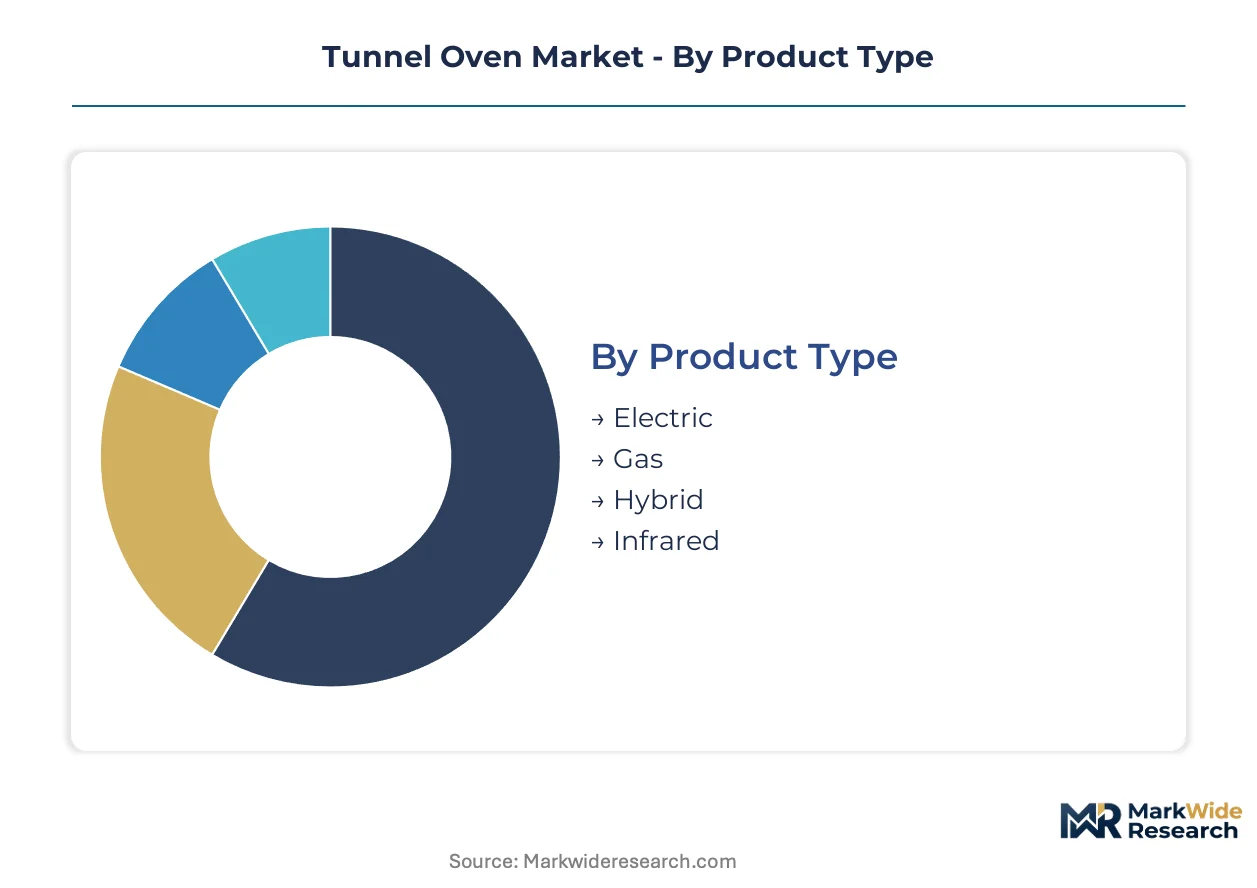
Tunnel oven procurement patterns diverge sharply between commodity bread operations seeking throughput maximization and premium confectionery producers prioritizing thermal precision. Equipment specification cascades from fuel availability, product chemistry requirements, and facility footprint constraints.
Product Type:
Standardization dominates at the commodity tier while hybrid architectures capture margin in volatile energy markets.
- Electric:Resistance heating elements deliver temperature stability within ±2°C for consistent crust formation. German industrial bakeries around Munich favor these configurations under EU Ecodesign Directive efficiency mandates, though grid dependency creates operational risk during peak demand periods.
- Gas:Direct-fired burners achieve faster heat-up cycles and lower per-unit energy costs where pipeline infrastructure exists. North American independent operators specify these for durability in high-volume bread production, constrained by OSHA ventilation retrofit requirements.
- Hybrid:Dual-fuel redundancy permits fuel switching based on real-time pricing. Scandinavian artisan cooperatives are procuring these systems to hedge against Nordic electricity volatility.
- Infrared:Ceramic radiant modules enable precise surface browning control for premium confectionery. Belgian chocolate manufacturers absorb throughput penalties for chemistry precision.
Most installed capacity flows through Gas configurations. Expansion is steepest in Hybrid systems.
End User:
Volume scale and margin structure determine thermal system complexity across buyer categories.
- Bakery:Commercial bread and pastry operations constitute the core demand base, with German retail contract consolidation driving automated line investments in Bavaria and Baden-Württemberg.
- Confectionery:Chocolate and fine patisserie producers specify radiant and infrared modules where Maillard reaction control commands price premiums. French chains prioritize surface chemistry over throughput.
- Snack Production:Cracker and biscuit lines require extended residence times with zoned temperature profiles. Indian urban retail chains in Mumbai are installing these for packaged snack growth.
- Pharmaceuticals:Drying and sterilization applications demand validated thermal uniformity with batch traceability. FDA food contact surface regulations shape equipment specification.
Procurement volume concentrates in Bakery operations. Margin capture is strongest in Confectionery.
Technology:
Heat transfer mechanism selection trades speed against precision in product-specific configurations.
- Direct Flame:Burner arrays impinge combustion gases directly on product carriers, achieving highest thermal intensity for flatbread and pizza crust production. Italian equipment dominates this niche.
- Convection:Forced hot air circulation delivers uniform temperature distribution across wide belt widths. This architecture leads throughput efficiency for standard bread formats in high-volume German plants.
- Radiant Heat:Infrared and ceramic emitters provide zoned browning control without air movement that disturbs delicate dough structures. Premium confectionery producers accept hard line speed limits for precision.
- Contact:Heated platens or drums transfer thermal energy through direct product interface. Tortilla and flatbread specialists specify these for rapid heat transfer with minimal moisture loss.
Convection technology holds the largest installed base. Radiant Heat configurations are climbing the fastest in revenue terms.
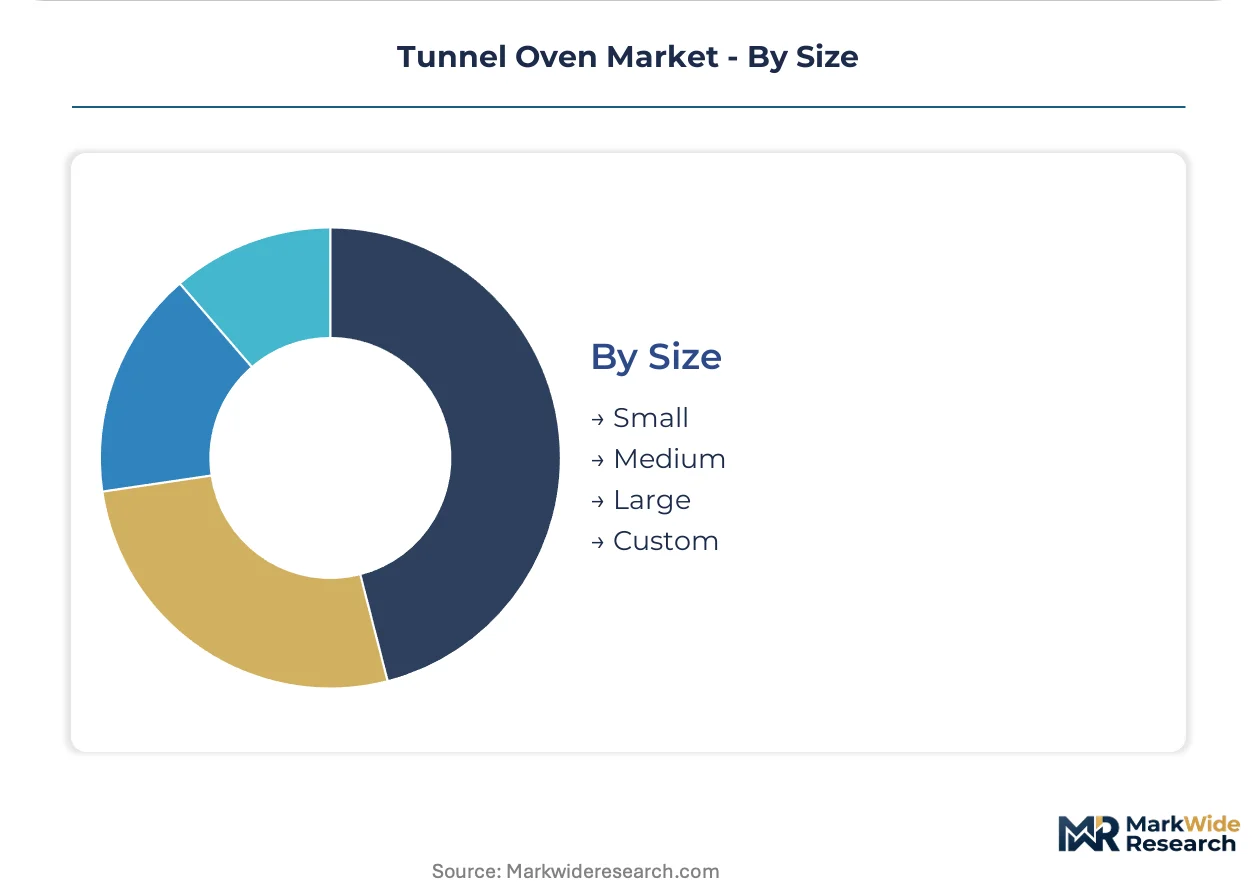
Size:
Facility footprint and production scale determine dimensional specification across buyer tiers.
- Small:Compact units under five meters in length serve artisan bakeries and pilot production facilities. Scandinavian cooperatives fragment procurement across these custom-configured systems.
- Medium:Mid-scale installations balance throughput with flexibility for product changeovers. Mid-sized German producers merging to secure retail contracts standardize on these dimensions.
- Large:Industrial tunnel systems exceeding twenty meters serve dedicated high-volume lines. Southern German baking clusters around Stuttgart deploy these for contract manufacturing scale.
- Custom:Engineered-to-order dimensions accommodate irregular facility layouts or specialty product requirements. Belgian chocolate manufacturers specify these for integrated cooling tunnel attachment.
Medium-size equipment represents the dominant procurement category. Custom configurations are gaining share fastest among premium producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thermal process engineering talent concentrates in German and Swedish technical institutes, anchoring European equipment innovation. Indian urban retail chains and North American independent operators drive divergent procurement patterns. Regulatory fragmentation across EMA machinery safety, FDA food contact, and BIS electrical standards shapes cross-border market access.
Germany
Industrial baking clusters around Munich and Stuttgart drive premium equipment procurement with accelerated decision timelines. EU Ecodesign Directive efficiency mandates are compressing equipment lifespans from fifteen to eight years. Mid-sized producers in Bavaria and Baden-Württemberg are consolidating purchasing authority into technical committees.
United States
Independent operators anchor North American demand for durable gas-fired platforms. OSHA ventilation and combustion safety rules require costly hood and exhaust modifications for gas-fired installations. Regional procurement concentrates in legacy manufacturing corridors where retrofit constraints slow upgrade cycles.
India
Urban retail chains in Mumbai and Bangalore are installing automated lines for packaged snack growth. BIS electrical safety standards for commercial cooking equipment shape equipment specification and import protocols. Western and southern metropolitan markets lead capital deployment as organized retail penetration deepens.
Italy
Direct-flame burner arrays dominate flatbread and pizza crust production equipment. National standards parallel EU Ecodesign Directive thresholds, accelerating replacement cycles. Northern industrial zones sustain equipment fabrication clusters serving Mediterranean export markets.
Belgium
Chocolate manufacturers specify infrared radiant modules despite throughput penalties for surface chemistry precision. EU F-Gas Regulation phase-down of hydrofluorocarbon refrigerants compels heat recovery architecture retrofits. Premium confectionery producers in Flemish industrial corridors absorb margin premiums for thermal precision.
Tunnel Oven Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market segments. The vendor base spans integrated thermal system providers, precision engineering houses, and durable equipment fabricators serving distinct buyer archetypes. Strategic archetypes include conglomerates with portfolio breadth, regional specialists with engineering depth, and independent operators with service proximity. Competitive moves concentrate on geographic expansion through distribution partnerships and technology licensing for hybrid fuel configurations.
Among Scandinavian precision engineering specialists, Sveba Dahlen occupies a position exemplifying high-throughput line expertise. Middleby Corporation represents the diversified conglomerate archetype with integrated thermal system capabilities. Baker's Pride anchors the durable equipment fabricator tier serving independent operators. These three companies illustrate the competitive spectrum from focused engineering depth to portfolio breadth and regional service density.
| Leading Market Players |
|---|
| Sveba Dahlen |
| Middleby Corporation |
| Blodgett |
| Baker's Pride |
| Cleveland |
| Doyon |
| Hobart |
| Moffat |
| Rational |
| Others |
Value Network & Pricing Analysis
Backward integration into stainless steel component fabrication anchors supply position and pricing power for European tunnel oven manufacturers facing nickel and chromium input volatility. German equipment suppliers with captive heat exchanger production command margin premiums over competitors sourcing from fragmented metalworking subcontractors.
Pricing Analysis
Capacity additions in Italy are reshaping price floors for direct-flame burner configurations as domestic fabrication clusters expand output. Three-tier pricing structure across premium, standard, and economy levels separates EU Ecodesign-certified systems from legacy thermal platforms and basic export-tier equipment. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in standard convection tiers is intensifying because mid-sized German producers are consolidating procurement into technical committees. Artisan cooperatives across Scandinavia exhibit highest price sensitivity, while Belgian chocolate manufacturers demonstrate lowest sensitivity due to surface chemistry precision requirements.
Supply Chain Analysis
Dual-sourcing requirements for PLC control systems are mandating multi-supplier qualification across Siemens and Allen-Bradley automation infrastructure. Component fabrication concentrates in Germany, Italy, and Sweden. Supply chains draw from nickel-chromium stainless steel alloys, ceramic radiant emitter modules, and precision burner assemblies. Single-source vulnerability sits with specialized thermal process engineering talent concentrated at technical institutes in Germany and Sweden. Distribution runs through OEM-direct channels for large industrial accounts and regional equipment distributors serving independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tunnel oven procurement functions as a geographic-arbitrage play where EU Ecodesign Directive compliance costs in Germany and Italy create displacement opportunities for suppliers with pre-certified platforms in lower-regulation export markets.
For Market Incumbents: Anchor market position through captive heat recovery architecture production and integrated thermal management package development. Defend against Scandinavian precision engineering specialists by securing exclusive service contracts with consolidated Bavarian bakery groups. Invest in hybrid fuel control system R&D to offset electric grid dependency risks for German industrial clients. For New Entrants and Emerging Players: E-commerce platform sales channels offer direct access to fragmented artisan cooperative procurement across Scandinavia without established distributor relationships. Target Indian urban retail chains in Mumbai and Bangalore where BIS electrical safety certification creates qualified supplier scarcity. Pursue technology licensing partnerships with German technical institutes for thermal process engineering expertise transfer. For Investors and Strategic Acquirers: Roll-up economics work for regional precision engineering specialists because buyer consolidation in southern Germany is compressing equipment procurement cycles and favoring suppliers with localized service density. Five-to-ten year viability hinges on carbon border adjustment readiness and low-carbon thermal technology positioning. Monitor EU Green Deal implementation pace as the inflection indicator for preferential procurement shifts toward electric and hybrid oven suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Fuel Configuration Development | Dual electric-gas redundancy captures procurement preference as Nordic electricity volatility intensifies. |
| Heat Recovery Architecture Retrofit | Exhaust-to-water systems maintain Dutch and Danish operational permits under EU F-Gas Regulation phase-down. |
| Infrared Radiant Module Integration | Ceramic emitter precision enables Belgian chocolate manufacturers to command retail price premiums. |
| PLC Control System Standardization | Protocol compatibility with Siemens infrastructure reduces German bakery commissioning timeline extensions. |
| Regional Service Network Expansion | Localized technical presence secures maintenance contracts with consolidated Bavarian baking groups. |
Research Methodology
Multiple input streams — equipment procurement databases, regulatory filing repositories, and trade flow records — were reconciled with primary field intelligence. Interviews with plant engineers at commercial bakeries, OEM procurement teams, and aftermarket service heads were cross-validated against EMA machinery safety directives, FDA food contact surface regulations, and BIS electrical standards documentation. Secondary sources included customs trade data, EU Ecodesign Directive compliance filings, and SEC disclosures from diversified thermal equipment conglomerates. Bottom-up unit economics and top-down market sizing approaches were triangulated to ensure consistency.
Data-stream reconciliation informed the analytical framework across the projection horizon. Segmentation dimensions modeled include fuel configuration, heat transfer technology, end-use application, equipment size tier, and regional regulatory cluster. CAGRs were derived from installed base turnover rates and replacement cycle compression under efficiency mandates. Forecast inputs incorporated EU Green Deal carbon border adjustment timelines and F-Gas Regulation phase-down schedules for auxiliary cooling systems.
The model assumes a particular technology adoption path; alternative pathways for hydrogen-fired burner systems would alter the outlook for gas configuration demand. Forecasts reflect assumptions about artisan cooperative fragmentation rates and mid-sized producer consolidation trajectories. Deviation in EU Ecodesign Directive enforcement intensity or OSHA ventilation rule retroactivity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Bread Maker Market
Food Processing Equipment
Hand Blender Market
Food Processing Equipment
Coffee Processing Machine Market
Food Processing Equipment
Brewing Chiller Market
Food Processing Equipment
Smart Meat Thermometer Market
Food Processing Equipment
Automatic Grilling Machine Market
Food Processing Equipment
Edible Oil Extracting Machine Market
Food Processing Equipment
North America Multi Cooker Market
Food Processing Equipment
Food Processing Blades Market
Food Processing Equipment
Insect Protein Processing Equipment Market
Food Processing Equipment
Dual-Ovenable Cook Trays Market
Food Processing Equipment
French Fries Cutter Market
Food Processing Equipment
Optical Sorter Market
Food Processing Equipment
Walk-In Coolers and Freezers Market
Food Processing Equipment
Portioning Machines Market
Food Processing Equipment
Automatic Fish Scaling Machine Market