
 North America Beverage Filling and Capping Machine Market | 2026-2036
North America Beverage Filling and Capping Machine Market Size, Share, and Industry Trends Forecast 2026-2036
North America Beverage Filling and Capping Machine Market Analytics
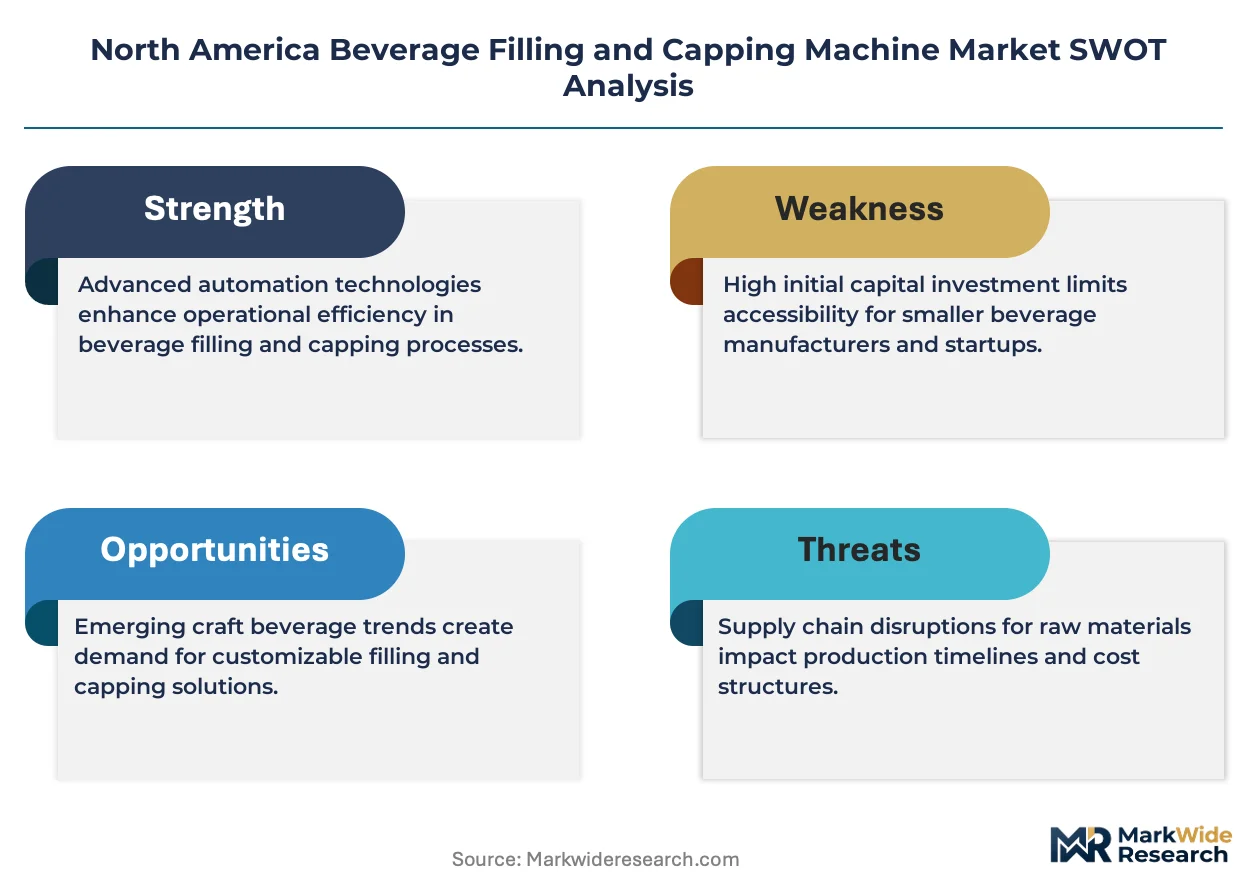
Mexico's manufacturing corridor is fragmenting as beverage multinationals expand canning and bottling capacity to serve both domestic consumption and export duties under USMCA. KHS Group leverages its rotary filler engineering to anchor large-scale brewery installations across the American Midwest. ProMach competes through modular inline systems that allow craft producers to scale without full line replacement. Tetra Laval International S.A. sustains dominance in aseptic carton filling through captive technology ecosystems that lock in dairy and juice processors.
Beverage filling and capping machines are electromechanical and pneumatic production systems designed to meter liquid or semi-liquid products into containers at speeds ranging from 100 to 120,000 units per hour, then seal them with screw caps, crown caps, or snap-fit closures to maintain product integrity and shelf stability. Rotary fillers command the largest installed base in carbonated soft drink bottling, though aseptic fillers are capturing the fastest growth as ambient-stable plant-based milks and functional waters displace refrigerated distribution. Electromechanical technology leads new capital expenditure for its precision and energy efficiency, while pneumatic systems retain share in cost-sensitive medium-scale operations where compressed air infrastructure already exists.
The FDA's Food Safety Modernization Act and OSHA machine guarding standards jointly shape equipment design, mandating clean-in-place capability and operator safety interlocks that add engineering cost but bar non-compliant imports. The EPA's Clean Air Act enforcement on volatile organic compound emissions from solvent-based lubricants is pushing manufacturers toward dry-running capper technologies and food-grade synthetic oils. Stakeholders must monitor how Mexico's PROY-NOM sanitary standards evolve relative to FDA benchmarks, as divergence would bifurcate supply chains and force dual-certification investments.
Market Dynamics
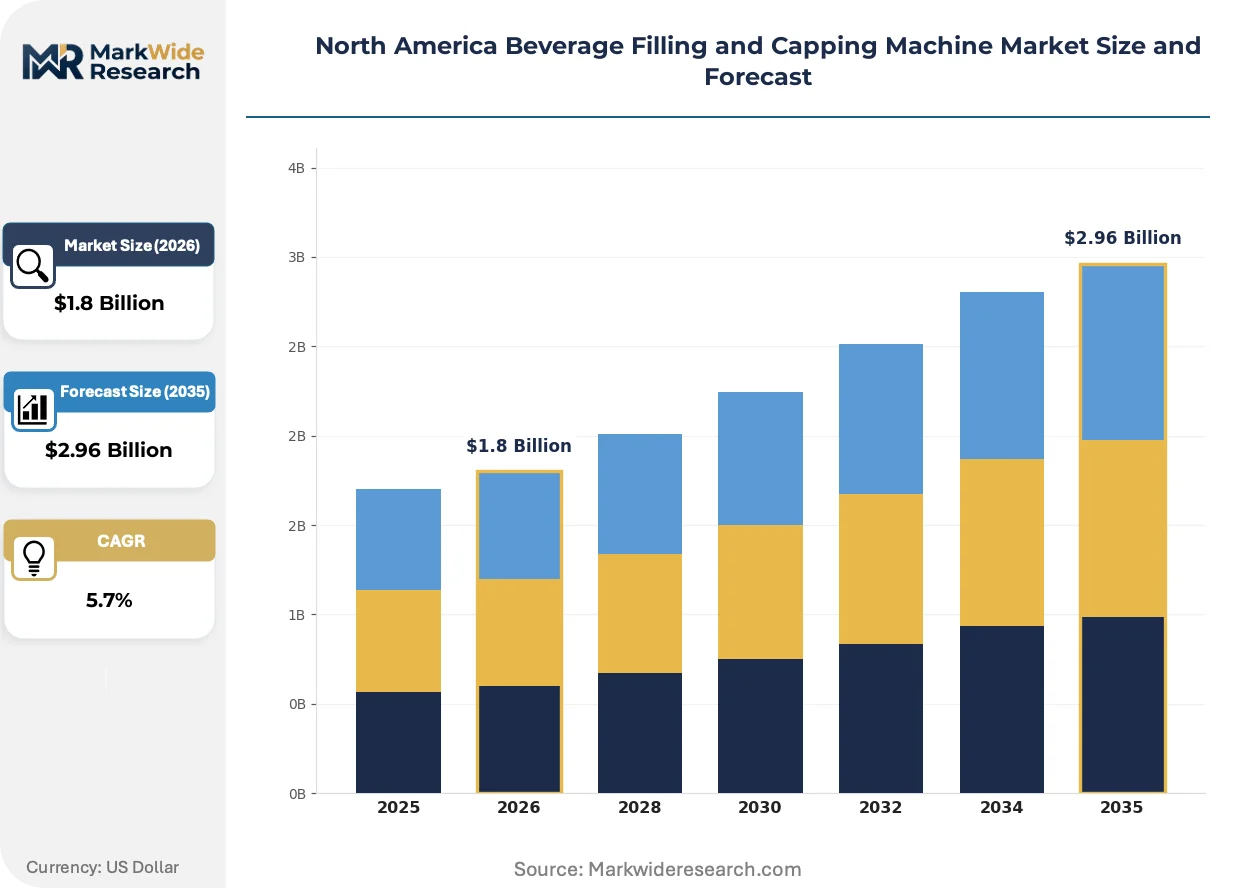
The USMCA trade framework and FDA's Food Safety Modernization Act are jointly restructuring capital deployment across North American beverage packaging, forcing producers to choose between dual-certification investments or single-geometry standardization.
Growth Catalysts
- Hard seltzer shelf-stability mandates:Ambient-stable formulations require aseptic filling systems that rotary carbonated lines cannot retrofit, pulling capital toward electromechanical platforms.
- California Central Valley bottling corridor expansion:Concentrated fruit and juice processors are consolidating multi-site operations into single high-throughput facilities to capture scale economies in land-constrained zones.
- USMCA rules of origin compliance:Beverage multinationals are relocating canning and bottling capacity to Mexican manufacturing belts to satisfy regional content requirements for duty-free US export.
Market Restraints
- Stainless steel input cost volatility:Grade 316L and 304 price swings compress margin visibility for equipment manufacturers with fixed-price contract exposure.
- Rotary filler supply concentration:Precision-machined turret and valve assemblies depend on a narrow base of German and Italian component specialists, creating single-source vulnerability.
- Pneumatic infrastructure lock-in:Existing compressed air systems in mid-scale Midwest breweries block electromechanical upgrades despite superior energy efficiency.
Strategic Opportunities
- Plant-based milk aseptic transition:Oat and almond beverage processors are replacing refrigerated distribution with ambient-stable cartons, opening filler replacement cycles.
- Mexico PROY-NOM standard evolution:Anticipated convergence with FDA sanitary design rules would eliminate dual-certification costs for cross-border equipment suppliers.
- Clean-in-place automation convergence:Integration of UV-C sterilization modules with electromechanical fillers reduces chemical usage and water discharge compliance burdens.
Industry Challenges
- Mechatronics technician scarcity:Servo-driven filler maintenance requires hybrid electrical-mechanical skills that vocational pipelines in the American Midwest and Northern Mexico have not scaled to match equipment deployment.
- Legacy line integration complexity:Craft breweries operating 1990s-era pneumatic systems face prohibitive downtime costs when retrofitting electromechanical cappers onto existing conveyor geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Beverage Filling and Capping Machine Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aseptic Fillers, Inline Fillers, Rotary Fillers, Capping Machines Technology: Electromechanical, Pneumatic, Hydraulic, Vacuum End User: Food and Beverage, Pharmaceuticals, Cosmetics, Household Products Scale: Small Scale, Medium Scale, Large Scale, Industrial Scale |
| Companies Covered | KHS Group, SIG, Tetra Laval International S.A., Coesia S.p.A., I.M.A. Industria Macchine Automatiche S.p.A., Syntegon Technology GmbH, GEA Group Aktiengesellschaft, ProMach, Duravant, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Beverage Filling and Capping Machine Market Evolving Landscape
Electromechanical precision is displacing pneumatic actuation across North American bottling lines, while regulatory pressure on chemical discharge and operator safety is rewriting equipment specification standards.
Dry-running capper technology is migrating from niche pharmaceutical applications into mainstream beverage packaging. These systems eliminate lubricant contact with food zones through engineered polymer bearings and ceramic coatings. Large-scale breweries in Texas and Wisconsin are piloting retrofits to preempt EPA Clean Air Act enforcement on volatile organic compound emissions from synthetic oil aerosols. The structural consequence is a compression in pneumatic component supplier margins as compressed air infrastructure becomes stranded capital.
OSHA machine guarding standards and FDA sanitary equipment design rules are tightening in parallel, mandating interlocked access panels and sloped surfaces without horizontal ledges. Equipment manufacturers serving California's dairy and juice processors must now engineer clean-in-place protocols that satisfy both agencies without redundant hardware. The segment most affected is mid-scale craft breweries, which are responding by deferring automation investments until regulatory clarity stabilizes.
After-sales service unbundling is fragmenting traditional full-line supplier relationships. Craft producers in Oregon and Vermont are procuring fillers, cappers, and labelers from separate specialists rather than accepting bundled maintenance contracts. This pattern compresses supplier switching costs and accelerates technology refresh cycles. The geographic concentration is most visible in the American Northeast, where smaller batch sizes and seasonal production swings favor modular equipment procurement over integrated line commitments.
North America Beverage Filling and Capping Machine Market Segmentation
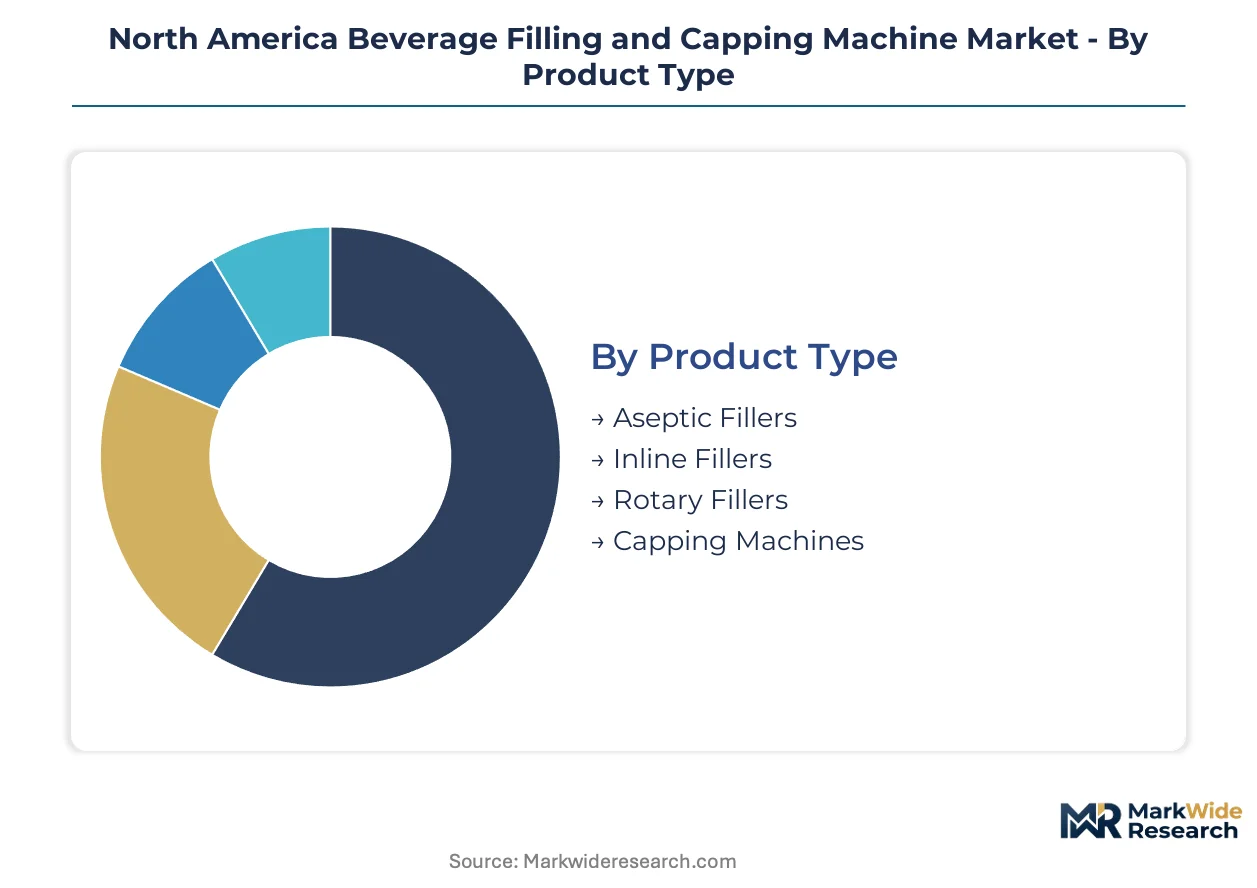
Beverage filling and capping machine procurement patterns diverge sharply across equipment types, automation levels, and production scales. Understanding these fault lines reveals where service contracts concentrate and where capital deployment accelerates.
Product Type:
After-sales service intensity varies dramatically by filler architecture, with aseptic systems demanding specialized technician networks and rotary platforms requiring precision component replacement programs.
- Rotary Fillers:Turret-based systems with 12 to 144 filling heads dominate carbonated soft drink bottling across Texas and Wisconsin. Midwest breweries favor these for throughput rates exceeding 60,000 bottles per hour, though turret valve rebuilds require factory-authorized service intervals that lock producers into OEM maintenance contracts.
- Aseptic Fillers:Sterile barrier isolators with hydrogen peroxide decontamination cycles enable shelf-stable plant-based milks and functional waters. California's Central Valley processors are retrofitting refrigerated juice lines to capture ambient distribution economics, driving demand for FDA-validated clean-in-place protocols.
- Inline Fillers:Linear indexing systems suit craft brewery scale-up trajectories in Oregon and Vermont.
- Capping Machines:Screw, crown, and snap-fit closure systems integrate with filler turrets or operate as standalone stations.
By volume, rotary fillers lead. By growth pace, aseptic fillers are expanding most quickly.
Technology:
Capital allocation patterns across electromechanical and pneumatic platforms reflect divergent energy cost structures and maintenance skill requirements.
- Electromechanical:Servo-driven actuators with programmable motion profiles deliver fill accuracy within 0.5% deviation. Large-scale facilities in California and Mexico's Tecate corridor are specifying these to satisfy EPA energy efficiency benchmarks and reduce compressed air infrastructure overhead.
- Pneumatic:Compressed air cylinders with mechanical cams retain installed base across legacy Midwest breweries where maintenance crews possess pneumatic troubleshooting expertise.
- Hydraulic:High-force actuation systems for viscous product handling in select dairy applications.
- Vacuum:Negative-pressure filling for oxygen-sensitive wines and specialty beverages.
Electromechanical systems command premium pricing. Pneumatic platforms retain cost-sensitive share.
End User:
Regulatory validation requirements create distinct equipment specification tiers across beverage, pharmaceutical, and adjacent sectors.
- Food and Beverage:FDA Food Safety Modernization Act compliance mandates sanitary equipment design with sloped surfaces and clean-in-place capability. Hard seltzer producers across the American Northeast are driving aseptic filler demand as ambient-stable formulations displace refrigerated distribution.
- Pharmaceuticals:cGMP-validated systems with batch documentation and isolator technology for sterile liquid dosing.
- Cosmetics:Viscous product handling with precision dosing for creams and serums.
- Household Products:Corrosion-resistant construction for chemical filling applications.
Food and beverage dominates unit demand. Pharmaceutical applications carry the steepest margin structure.
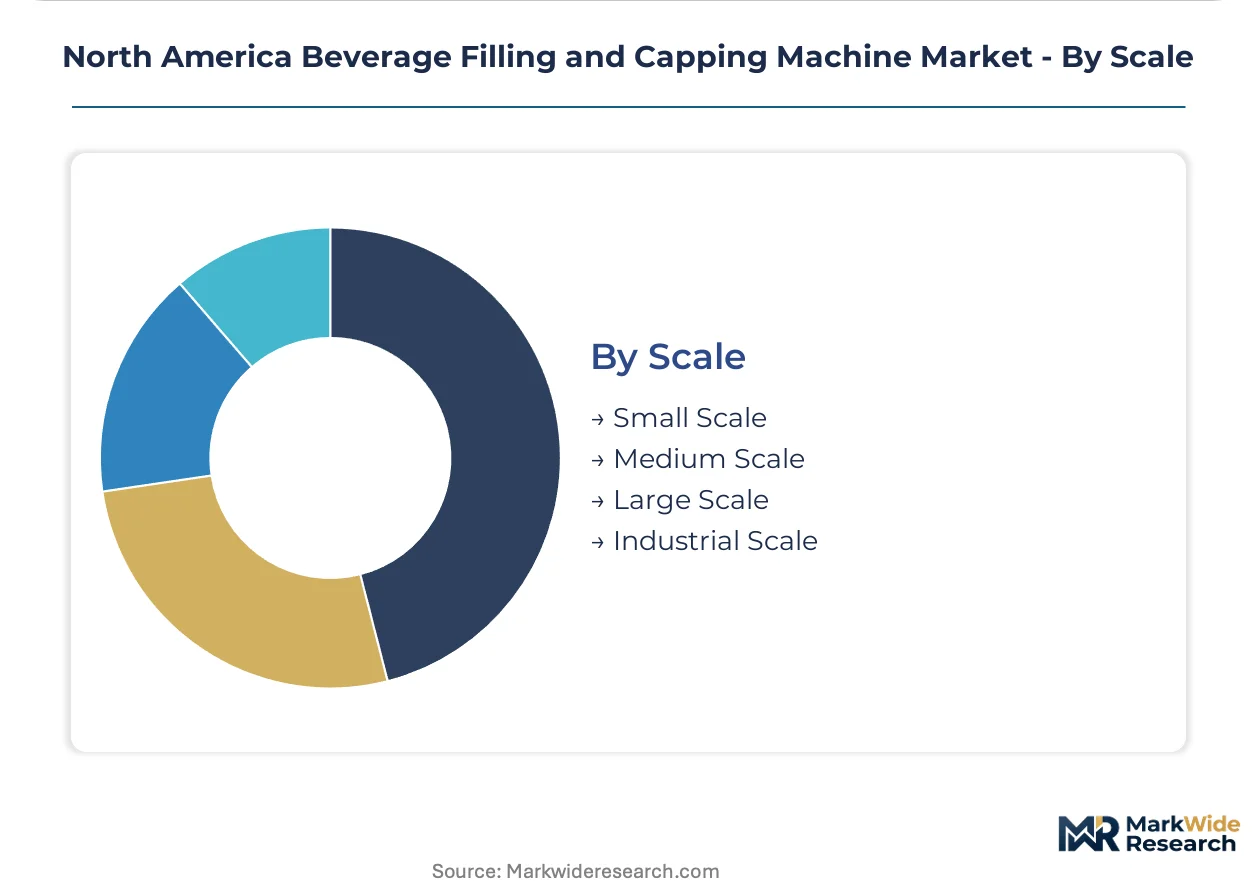
Scale:
Equipment specification, financing structure, and supplier relationship intensity correlate directly with production volume tier.
- Large Scale:Integrated rotary lines exceeding 40,000 units per hour with centralized HMI control and predictive maintenance analytics. Multinational beverage producers in Mexico's Guadalajara manufacturing belt deploy these under USMCA rules of origin compliance strategies.
- Industrial Scale:Continuous operation systems with redundant filling heads for 24/7 production environments.
- Medium Scale:Modular inline systems allowing craft producers to add capacity without line replacement, favored by Oregon and Vermont breweries.
- Small Scale:Semi-automatic benchtop units for pilot production and seasonal SKU testing.
Large-scale installations anchor supplier revenue. Medium-scale procurement is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA sanitary equipment design rules and USMCA rules of origin compliance are restructuring capital deployment across North American beverage packaging corridors. Equipment procurement concentrates in three national markets with distinct regulatory and industrial logics.
United States
Hard seltzer producers across the American Northeast are retrofitting refrigerated distribution lines with aseptic filling systems to achieve ambient shelf stability. FDA Food Safety Modernization Act mandates on clean-in-place capability and sloped surface design are compelling legacy brewery upgrades. California's Central Valley bottling corridor hosts concentrated fruit and juice processors consolidating multi-site operations into single high-throughput facilities.
Mexico
Beverage multinationals are expanding canning and bottling capacity in the Tecate-Guadalajara manufacturing belt to satisfy USMCA regional content requirements for duty-free export to the United States. PROY-NOM sanitary standards evolution remains uncertain relative to FDA benchmarks, creating dual-certification risk for cross-border equipment suppliers. Northern border states are capturing assembly plant investment as producers seek proximity to American distribution networks.
Canada
Health Canada and PMRA regulations on food contact materials and equipment sanitation are converging with FDA frameworks, reducing compliance friction for integrated North American supply chains. Ontario and Quebec host dairy and beverage processors modernizing legacy pneumatic lines to meet energy efficiency benchmarks under federal carbon reduction programs. Prairie provinces are seeing craft brewery consolidation driving demand for modular inline systems.
North America Beverage Filling and Capping Machine Market Competitive Landscape
Rotary filler specialists and modular inline system fabricators split the market between high-throughput carbonated beverage installations and craft-scale scalable platforms. The vendor base organizes around three strategic archetypes: European engineering houses with precision turret capabilities, North American integrators emphasizing flexible configuration, and diversified packaging conglomerates with captive technology ecosystems. Competitive dynamics center on M&A activity targeting regional service networks and technology licensing arrangements for aseptic barrier isolator systems.
Among European engineering houses, KHS Group and GEA Group Aktiengesellschaft occupy positions anchored in rotary filler precision manufacturing. Syntegon Technology GmbH represents the diversified technology conglomerate archetype with integrated aseptic and electromechanical portfolios. ProMach exemplifies the North American modular integrator model serving craft and mid-scale producers with scalable inline configurations.
| Leading Market Players |
|---|
| KHS Group |
| SIG |
| Tetra Laval International S.A. |
| Coesia S.p.A. |
| I.M.A. Industria Macchine Automatiche S.p.A. |
| Syntegon Technology GmbH |
| GEA Group Aktiengesellschaft |
| ProMach |
| Duravant |
| Others |
Value Network & Pricing Analysis
Freight corridors connecting Germany's precision component clusters to Mexico's Tecate-Guadalajara manufacturing belt transmit stainless steel cost volatility into regional price spreads, while FDA-PROY-NOM certification divergence forces dual-tier pricing for cross-border equipment.
Pricing Analysis
Electromechanical systems command 15-25% premiums over pneumatic platforms across California and the American Midwest, with price differentiation anchored in servo precision and energy efficiency certification tiers. Stainless steel input cost swings compress margin visibility for fixed-price contracts, pressuring OEMs toward indexed pricing clauses. Craft breweries in Oregon and Vermont exhibit highest price sensitivity, deferring automation investments until regulatory clarity stabilizes, while multinational beverage producers in Mexico absorb premium pricing to secure USMCA compliance.
Supply Chain Analysis
Tariff exposure between Germany and the United States dominates supply chain risk for precision-machined turret and valve assemblies that rotary filler OEMs cannot source domestically. Component fabrication concentrates in Germany, Italy, and Japan, with Grade 316L stainless steel drawn from South Korean and Belgian mills. Single-source vulnerability in ceramic bearing supply for dry-running cappers threatens production continuity. Distribution runs through regional service depots in Chicago, Monterrey, and Toronto that coordinate spare parts logistics and technician deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as craft brewery consolidation across the American Northeast and Pacific Northwest reduces supplier fragmentation, enabling procurement teams to extract modular equipment configurations and unbundled service terms.
For Market Incumbents: Pre-empt electromechanical displacement by acquiring regional service networks in Mexico's northern border states before PROY-NOM-FDA convergence eliminates dual-certification barriers. Anchor large-scale brewery accounts through captive maintenance contracts that lock out modular competitors. Defend against ProMach's scalable inline systems by embedding predictive analytics into rotary filler HMIs, creating switching costs through operational data integration. For New Entrants and Emerging Players: Build out aftermarket parts distribution for legacy pneumatic systems in the American Midwest, where maintenance crew expertise creates stickiness against electromechanical conversion. Target medium-scale craft producers in Vermont and Oregon with subscription-based equipment-as-a-service models that eliminate upfront capital barriers. Penetrate through clean-in-place automation modules that retrofit existing lines, avoiding greenfield installation complexity. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates divesting non-core beverage assets to focus on pharmaceutical barrier isolator growth. European engineering houses with stranded rotary filler technology but intact Mexican service networks represent optimal acquisition profiles. Monitor USMCA rules of origin enforcement intensity as the inflection signal—accelerated compliance audits would trigger immediate capacity relocation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Service Network Acquisition | Captures PROY-NOM certification readiness in Mexico's northern border states before regulatory convergence. |
| Electromechanical Platform Migration | Positions OEMs for EPA energy efficiency benchmarks and California carbon reduction mandates. |
| Clean-in-Place Module Integration | Reduces FDA compliance costs for Central Valley juice processors retrofitting refrigerated lines. |
| Equipment-as-a-Service Launch | Neutralizes price sensitivity among Oregon and Vermont craft breweries with seasonal production swings. |
| Dry-Running Capper Technology Licensing | Preempts EPA Clean Air Act enforcement on volatile organic compound emissions from synthetic lubricants. |
Research Methodology
Desk research of trade association filings, customs import records, and FDA equipment validation databases preceded structured interviews with plant engineers at California juice processors, maintenance directors at Midwest breweries, and procurement leads at Mexican beverage multinationals. Primary fieldwork with OEM sales executives and aftermarket service managers validated secondary estimates of installed base and replacement cycles. Bottom-up unit economics triangulated against top-down capital expenditure surveys from regional trade associations.
Forecast assumptions held USMCA rules of origin compliance stable across the analysis window while varying PROY-NOM-FDA convergence scenarios and stainless steel price trajectory sensitivities. Segmentation modeling spanned equipment architecture, automation technology, production scale tier, and end-use application. CAGRs derived from replacement cycle analysis, capacity expansion announcements, and regulatory mandate implementation timelines. Hard seltzer shelf-stability mandates and plant-based milk aseptic transition rates served as volume drivers.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration by European engineering houses into Mexican assembly operations would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Loss-In-Weight Feeder Market
Food Processing Equipment
Air Cooled Cube Ice Machines Market
Food Processing Equipment
Mooncake Production Line Market
Food Processing Equipment
Spiral Cooler Market
Food Processing Equipment
Multiple Unit Pellet Systems Market
Food Processing Equipment
Brewing Equipment Market
Food Processing Equipment
Ice Flaking Machine Market
Food Processing Equipment
Plastic Processing Equipment Market
Food Processing Equipment
Used Commercial Freezer Market
Food Processing Equipment
Residential Food Waste Disposer Market
Food Processing Equipment
Deaeration Machine Market
Food Processing Equipment
North America Ginger Processing Market
Food Processing Equipment
Microbrewery Equipment Market
Food Processing Equipment
Pizza Preparation Refrigerator Market
Food Processing Equipment
Insect Protein Processing Equipment Market
Food Processing Equipment
Food Automation Market