
 Ribbon Blenders Market | 2026-2036
Ribbon Blenders Market Size, Share, and Industry Trends Forecast 2026-2036
Ribbon Blenders Market Analytics
A capital-intensity divergence between large-scale fabricators and boutique assembly shops is unwinding competitive stability across the ribbon blender supply base. Charles Ross and Son Company leverages its century-old fabrication footprint to dominate custom-engineered batch systems for pharmaceutical clients. Munson Machinery anchors its position through aggressive vertical integration into bulk material handling peripherals, starving regional competitors of attach-rate revenue. PerMix specializes in sanitary-grade portable units, navigating price pressure from Asian entrants through rapid-turnaround customization.
Ribbon blenders are horizontal or vertical mixing vessels employing helical agitators to achieve convective blending of powders, granules, pastes, or slurries at tip speeds typically below 300 fpm, with batch capacities spanning laboratory-scale units to industrial systems exceeding 1,000 cubic feet. Horizontal configurations lead in chemical manufacturing due to superior discharge efficiency and lower residual holdup, while portable units represent the fastest-expanding product type as contract manufacturers prioritize equipment mobility across multi-product lines. Food processing end users command the deepest margin pools, driven by stringent sanitary welding requirements and 3-A SSI-compliant surface finishes that filter out commodity competitors.
FDA food-contact surface regulations and OSHA combustible dust standards shape equipment specification in North American facilities, while CE marking and ATEX directives govern European market access for powder-handling configurations. The EU's evolving F-Gas Regulation indirectly pressures drying-integrated blender designs toward closed-loop thermal systems. Stakeholders must monitor how evolving ESG disclosure frameworks, particularly the EU CSRD, redirect capital toward energy-efficient drive systems and regenerative braking on large-capacity units.
Market Dynamics
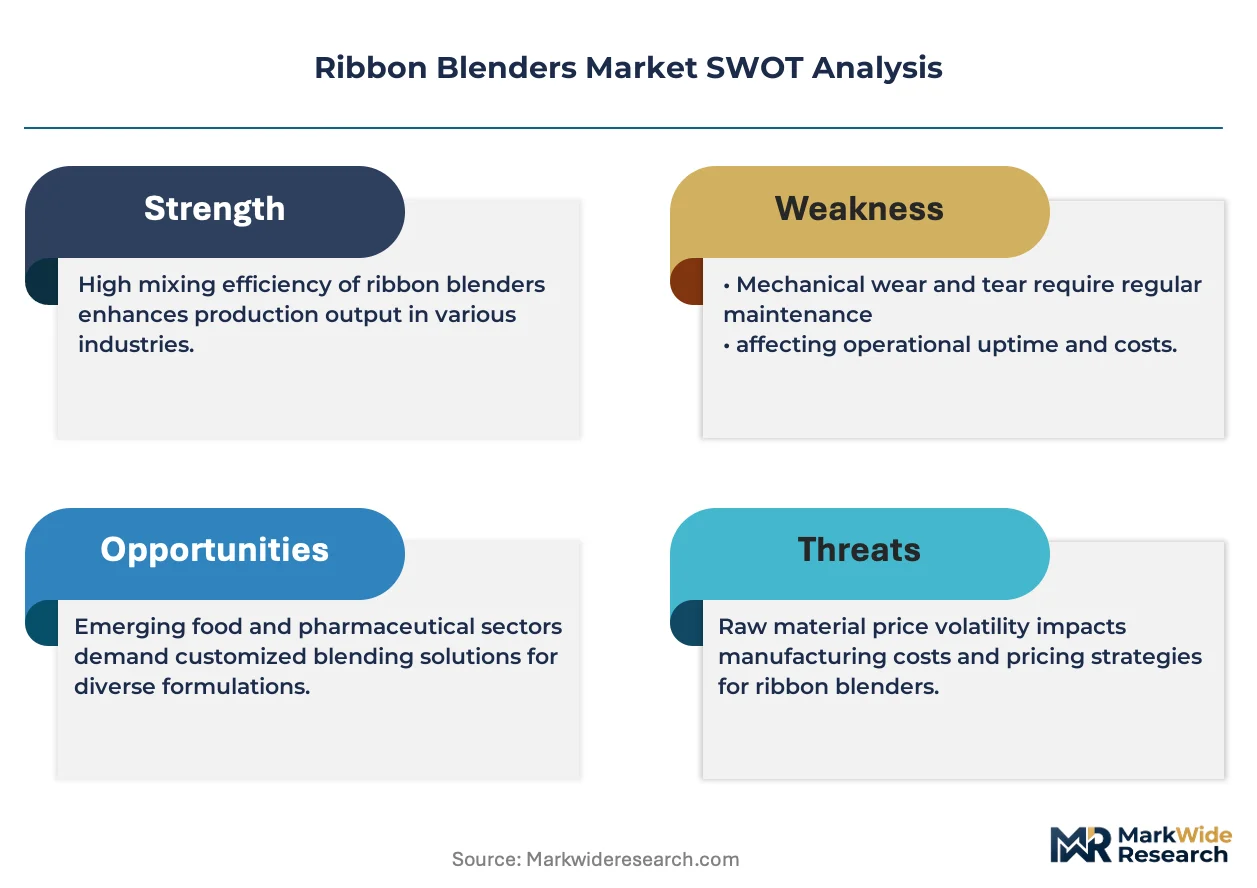
Precision-engineered sanitary welding and 3-A SSI surface finish compliance are filtering commodity fabricators from pharmaceutical and food-grade procurement pools, concentrating contract awards among certified specialists.
Growth Catalysts
- REACH compliance elevation:European chemical manufacturers face mandatory substance registration thresholds that favor stainless-steel ribbon blenders with full material traceability, accelerating replacement cycles for legacy carbon-steel units.
- Contract manufacturing mobility:Multi-product pharmaceutical toll processors in North America prioritize portable blender configurations to minimize cross-contamination risk and line changeover downtime.
- Industrial bakery automation:Powder-to-paste versatility in horizontal ribbon designs supports continuous dough and filling production lines across large-scale confectionery plants.
Market Restraints
- Nickel alloy price volatility:316L stainless steel feedstock costs fluctuate with nickel futures, compressing fabrication margins for mid-cap OEMs without long-term supply agreements.
- Fabrication cluster concentration:Precision machining capabilities for sanitary-grade agitator assemblies concentrate in southwestern Germany, creating geographic supply risk for non-European buyers.
- Fluid bed dryer substitution:Continuous processing lines in chemical manufacturing increasingly specify integrated fluid bed systems that bypass batch ribbon blending entirely.
Strategic Opportunities
- India pharmaceutical expansion:CDSCO manufacturing license requirements for active pharmaceutical ingredient facilities drive demand for documented sanitary-grade batch equipment with IQ/OQ validation packages.
- EU CSRD energy disclosure:The Corporate Sustainability Reporting Directive mandates granular equipment energy consumption tracking, creating pull for variable-frequency drive systems with embedded metering.
- Regenerative braking integration:Large-capacity units equipped with energy recovery motors command premium positioning against standard drive configurations in ESG-focused capital budgets.
Industry Challenges
- Orbital welding certification scarcity:Qualified sanitary welders capable of executing 3-A SSI-compliant surface finishes command wage premiums that inflate final assembly costs by double-digit percentages.
- Legacy control system integration:Modern variable-frequency drives must interface with decades-old SCADA architectures prevalent in established chemical processing facilities, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ribbon Blenders Market |
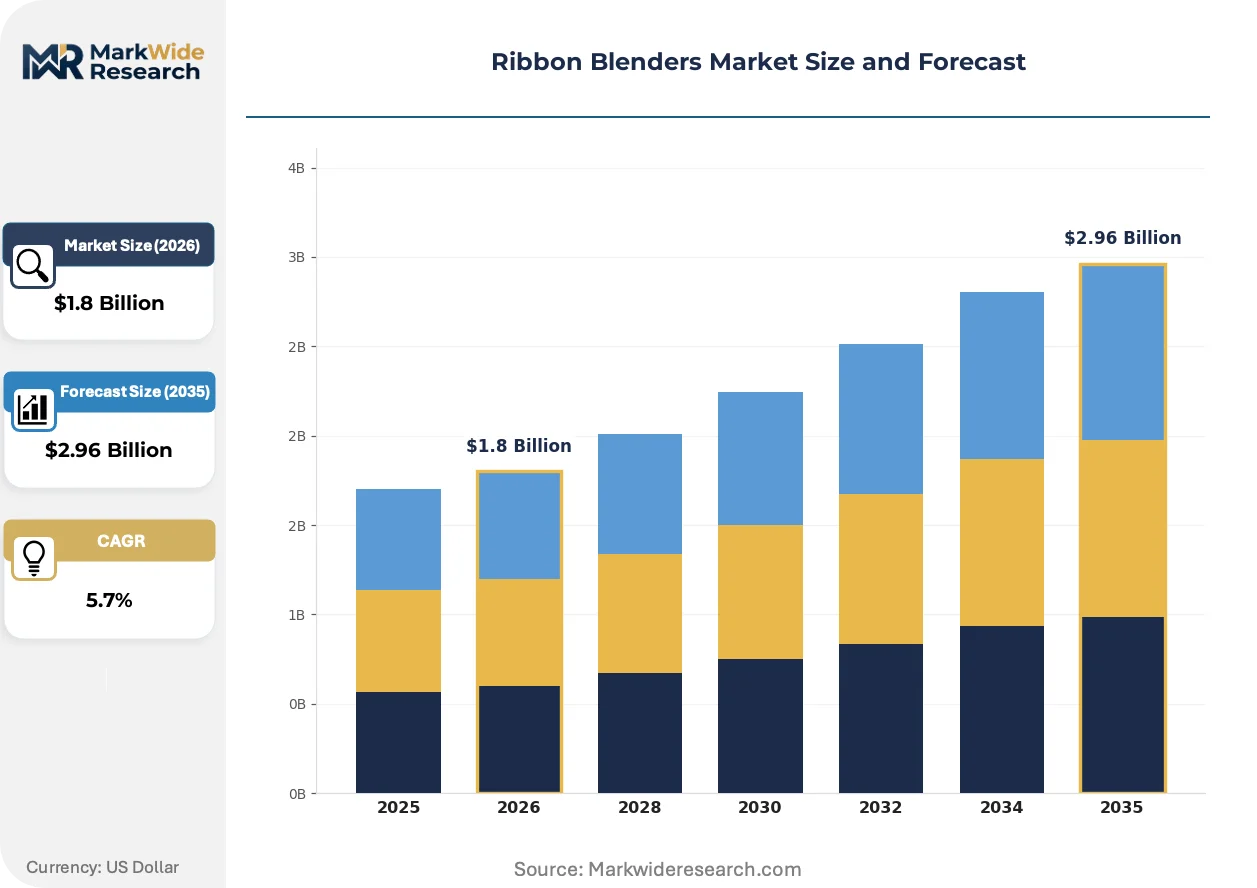
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal, Vertical, Portable, Laboratory End User: Food Processing, Chemical Manufacturing, Pharmaceuticals, Plastics Material Type: Powder, Granules, Paste, Slurry Application: Mixing, Coating, Drying, Blending |
| Companies Covered | Amixon GmbH, Charles Ross and Son Company, Kason Corporation, Paul O. Abbe, Allpack, PerMix, Munson Machinery, CMT process solutions, EIRICH Machines, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ribbon Blenders Market Evolving Landscape
Active magnetic bearing systems and IoT-enabled vibration monitoring are redefining maintenance economics for high-duty-cycle installations, while regulatory pressure on thermal efficiency accelerates closed-loop heat integration.
Magnetic bearing support systems for large-capacity agitator shafts are displacing traditional mechanical seal arrangements in pharmaceutical applications. Johnson and Johnson's manufacturing standards division mandates zero-lubricant contact for high-shear mixing operations, compressing acceptable vendor lists to specialists with magnetic levitation expertise. This displacement is eliminating regional fabricators lacking precision electromagnetic engineering partnerships.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is forcing drying-integrated blender designs toward closed-loop thermal systems with heat pump recovery. Equipment specifiers in German chemical parks now require documentation of global warming potential for all auxiliary thermal equipment. This regulatory compression favors OEMs with in-house thermal engineering capabilities over pure mechanical fabricators.
Equipment-as-a-service contracting is fragmenting traditional capital purchase patterns among North American contract manufacturers. Bakeries and toll processors in the US Midwest increasingly specify throughput-based payment structures that transfer residual value risk to OEMs. This financing innovation is most visible in Illinois and Wisconsin, where multi-site operators prioritize balance sheet flexibility over equipment ownership.
Ribbon Blenders Market Segmentation
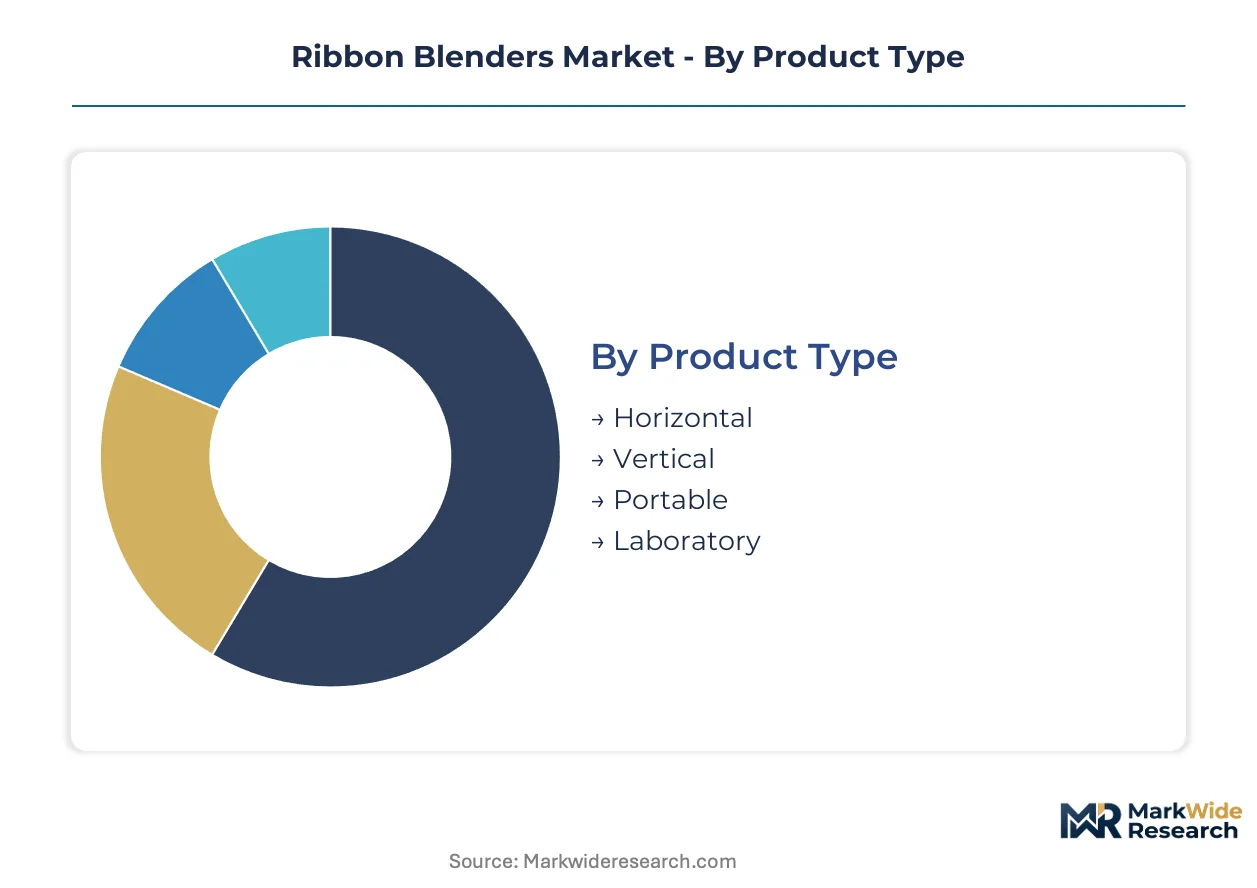
Ribbon blender procurement patterns diverge sharply across product configurations and end-use verticals. Equipment specification in pharmaceutical toll manufacturing demands sanitary-grade surface finishes that commodity fabricators cannot deliver.
Product Type:
Domestic fabrication dominates horizontal and vertical installations for chemical plants, while portable configurations increasingly ship from Asian contract manufacturers serving North American contract manufacturers.
- Horizontal:U-shaped troughs with double-helix agitators achieve discharge efficiencies below 0.5% residual holdup. German chemical parks around Cologne and Leverkusen specify these for continuous powder-to-paste operations under REACH material traceability requirements.
- Portable:Sanitary-grade units on casters with quick-disconnect fittings enable multi-product pharmaceutical toll processors to slash line changeover downtime. CDSCO-compliant validation packages from Indian OEMs are penetrating this segment fastest.
- Vertical:Conical-bottom designs suit abrasive mineral processing with gravity-assisted discharge.
- Laboratory:Bench-scale units with 1-20 liter capacities support R&D formulation work.
Horizontal configurations command the established base. The steepest expansion runs through portable units.
End User:
Margin structures vary threefold across verticals, with food processing and pharmaceuticals extracting premium pricing for certified sanitary welding while chemical manufacturing prioritizes throughput economics.
- Food Processing:Industrial bakeries and confectionery plants specify 3-A SSI surface finishes with documented orbital weld maps. FDA food-contact material rules and FSSAI licensing in India filter commodity suppliers from contract awards.
- Pharmaceuticals:Active pharmaceutical ingredient facilities require IQ/OQ validation packages with full material traceability. Johnson and Johnson's zero-lubricant standards for high-shear operations compress vendor lists to magnetic bearing specialists.
- Chemical Manufacturing:Bulk powder handling prioritizes discharge efficiency and ATEX-compliant explosion protection over surface finish premiums.
- Plastics:Color masterbatch and additive compounding drives demand for heat-resistant agitator alloys.
Food processing commands the established base. The steepest expansion runs through pharmaceuticals.
Material Type:
Application complexity escalates from free-flowing powders through cohesive pastes, with slurry handling requiring specialized shaft seal arrangements that concentrate procurement among German and Swiss specialists.
- Powder:Free-flowing bulk solids dominate chemical manufacturing volumes with minimal agitator torque requirements.
- Paste:High-viscosity dough and filling applications in industrial bakeries demand reinforced agitator ribbons and variable-frequency drive systems for torque management.
- Granules:Fertilizer and mineral processing applications require abrasion-resistant trough linings.
- Slurry:Liquid-solids suspensions need mechanical seal or magnetic bearing configurations to prevent shaft leakage in pharmaceutical applications.
Powder handling commands the established base. The steepest expansion runs through paste applications.
Application:
Integrated process design is blurring traditional application boundaries, with coating and drying functions increasingly specified as combined operations in closed-loop thermal systems.
- Mixing:Convective blending remains the core function across all product configurations, with tip speeds below 300 fpm preventing thermal degradation of heat-sensitive formulations.
- Drying:Heat-integrated designs with heat pump recovery are displacing standalone fluid bed systems under EU F-Gas Regulation pressure on hydrofluorocarbon refrigerants.
- Coating:Liquid addition nozzles and spray bars enable uniform encapsulation of granules and powders.
- Blending:Gentle low-shear operations for fragile granules and instantized food ingredients.
Mixing commands the established base. The steepest expansion runs through drying.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains a substantial export surplus in precision-engineered ribbon blenders, while the United States and India absorb the bulk of sanitary-grade imports for pharmaceutical and food processing applications. Trade flows concentrate through specialized machinery corridors linking German fabrication clusters to North American toll manufacturers and Indian API facilities.
Germany
REACH compliance mandates and ATEX certification requirements drive replacement demand for legacy carbon-steel units in chemical parks around Cologne and Leverkusen. The F-Gas Regulation pressures drying-integrated designs toward closed-loop thermal systems with documented global warming potential. Precision machining capabilities for sanitary-grade agitator assemblies concentrate in North Rhine-Westphalia, anchoring specialized OEM output for European pharmaceutical clients.
United States
FDA food-contact surface regulations and OSHA combustible dust standards shape equipment specification across industrial bakeries and confectionery plants in Illinois and Wisconsin. Equipment-as-a-service contracting fragments traditional capital purchase patterns among multi-site toll processors prioritizing balance sheet flexibility. Midwestern contract manufacturers specify throughput-based payment structures that transfer residual value risk to OEMs.
India
CDSCO manufacturing license requirements for active pharmaceutical ingredient facilities drive procurement of documented sanitary-grade batch equipment with IQ/OQ validation packages. FSSAI licensing filters commodity suppliers from food processing contract awards. Domestic OEMs in Gujarat and Maharashtra penetrate the portable blender segment fastest with rapid-turnaround customization capabilities.
China
MIIT industrial upgrading directives and GB standards for powder-handling equipment elevate specification rates for stainless-steel configurations in chemical manufacturing. NMPA pharmaceutical manufacturing guidelines compress vendor lists for high-shear mixing operations. Yangtze River Delta fabrication clusters serve both domestic demand and export markets for standard-capacity units.
Switzerland
Swissmedic pharmaceutical manufacturing standards and precision engineering traditions sustain premium positioning for specialized agitator assemblies. Magnetic bearing expertise concentrates around Basel and Zurich, serving Johnson and Johnson's zero-lubricant mandates for high-shear operations. Swiss specialists command wage premiums for orbital welding certification that inflate final assembly costs.
Ribbon Blenders Market Competitive Landscape
Concentration sits with century-old fabrication specialists and vertically integrated machinery conglomerates that control attach-rate revenue streams. The vendor base stratifies across three tiers: premium sanitary-grade specialists with full validation capabilities, mid-cap fabricators serving chemical manufacturing throughput economics, and Asian contract manufacturers competing on portable unit price points. Dominant competitive moves include backward integration into bulk material handling peripherals and rapid-turnaround customization services for multi-product pharmaceutical toll processors.
Among German precision engineering specialists, Amixon GmbH exemplifies the sanitary-grade archetype with documented material traceability systems. Charles Ross and Son Company anchors the custom-engineered batch systems tier for North American pharmaceutical clients. PerMix occupies a position within the portable unit specialization vector, navigating price pressure through rapid-turnaround customization capabilities. Munson Machinery represents the vertically integrated machinery conglomerate archetype with captive supply of bulk material handling peripherals.
| Leading Market Players |
|---|
| Amixon GmbH |
| Charles Ross and Son Company |
| Kason Corporation |
| Paul O. Abbe |
| Allpack |
| PerMix |
| Munson Machinery |
| CMT process solutions |
| EIRICH Machines |
| Others |
Value Network & Pricing Analysis
Eighteen-week lead times for sanitary-grade agitator assemblies from North Rhine-Westphalia concentrate pricing power among German specialists, while Asian contract manufacturers exploit container-rate volatility to undercut portable unit quotations. This temporal-spatial asymmetry rewards buyers with flexible specifications and punishes those locked into REACH-traceable material documentation.
Pricing Analysis
The customization-premium spread spans three-to-five-fold between standard horizontal chemical units and pharmaceutical-grade systems with magnetic bearing configurations and full IQ/OQ validation packages. Pricing stratifies across premium sanitary specialists, standard chemical fabricators, and economy portable assemblers, with nickel alloy feedstock volatility compressing margins most acutely at the mid-tier. Cost compression in standard-capacity chemical units is intensifying because Yangtze River Delta exporters are absorbing freight volatility to gain North American toll-processor share. Contract manufacturers in Illinois and Wisconsin exhibit highest price sensitivity due to equipment-as-a-service contracting adoption, while Johnson and Johnson's zero-lubricant mandates render approved magnetic bearing vendors essentially price-inelastic.
Supply Chain Analysis
Inbound logistics costs from Shanghai to Los Angeles and Hamburg fluctuate with container availability, distorting landed-cost comparisons between Asian contract manufacturers and German precision specialists. Fabrication draws from three dominant supply nodes: North Rhine-Westphalia for sanitary-grade agitator machining, the Yangtze River Delta for standard-capacity unit assembly, and Gujarat for CDSCO-compliant portable configurations. Nickel futures volatility and 316L stainless steel single-source vulnerability from specific European mills concentrate risk for mid-cap OEMs lacking long-term metallurgical agreements. Distribution runs through specialized machinery corridors linking German clusters to North American pharmaceutical toll manufacturers and Indian API facilities, with regional service attach rates determining ultimate vendor selection.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ribbon blender procurement sits in early-cycle expansion as pharmaceutical toll manufacturing mobility and EU CSRD energy disclosure mandates accelerate replacement demand ahead of historical depreciation schedules.
For Market Incumbents: Secure orbital welding certification pipelines to defend against Asian portable unit price erosion, while backward integration into heat pump thermal systems captures F-Gas Regulation-driven specification shifts. Magnetic bearing expertise and documented material traceability systems represent the primary defensive moats against commodity fabricators exploiting nickel price volatility. For New Entrants and Emerging Players: Anchor in Indian pharmaceutical portable configurations where CDSCO validation package demand outpaces domestic OEM capacity, or target Midwestern US contract manufacturers seeking throughput-based equipment-as-a-service structures. Rapid-turnaround customization capabilities and embedded variable-frequency drive metering deliver the most penetrable go-to-market angle against century-old fabrication incumbents. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive ribbon blender divisions lacking standalone sanitary-grade certification infrastructure. The five-to-ten year viability window favors precision engineering specialists with magnetic levitation partnerships and in-house thermal engineering capabilities over pure mechanical fabricators. Monitor Johnson and Johnson manufacturing standards division updates as the critical inflection signal for vendor list compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Orbital Welding Certification Investment | 3-A SSI-compliant surface finish capability filters commodity competitors from pharmaceutical procurement pools. |
| Magnetic Bearing Technology Partnership | Zero-lubricant mandates from major pharmaceutical OEMs compress acceptable vendor lists to electromagnetic engineering specialists. |
| Heat Pump Thermal System Integration | EU F-Gas Regulation phasedown favors OEMs with closed-loop thermal engineering over pure mechanical fabricators. |
| Equipment-as-a-Service Contracting Launch | Throughput-based payment structures transfer residual value risk while capturing balance-sheet-flexible toll processors. |
| CDSCO Validation Package Development | Indian API facility licensing requirements drive documented sanitary-grade batch equipment demand with rapid customization. |
Research Methodology
The analysis maps horizontal, vertical, portable, and laboratory ribbon blender configurations, each validated through maintenance directors at industrial bakeries, pharmaceutical plant engineers, chemical procurement leads, and aftermarket service heads. Primary interview intelligence combined with secondary validation from FDA food-contact material rulings, ECHA REACH substance registrations, SEC 10-K filings from listed machinery OEMs, and customs trade data for stainless-steel processing equipment imports. Bottom-up unit shipment estimates triangulate against top-down capital expenditure patterns across end-use verticals.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation dimensions spanning product configuration, end-use vertical, material type, and application function. CAGRs derived from historical replacement cycle analysis, regulatory compliance-driven acceleration factors, and penetration rate modeling for portable configurations in contract manufacturing. Industry-specific forecast inputs incorporated nickel futures trajectory impacts on fabrication margins and equipment-as-a-service contracting adoption curves among North American toll processors.
Decision-makers should treat outputs as directional under assumptions of sustained REACH enforcement stringency and continued pharmaceutical outsourcing trends; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding nickel alloy price stabilization and F-Gas Regulation implementation timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Loss-In-Weight Feeder Market
Food Processing Equipment
Brewing Boiler Market
Food Processing Equipment
Ice Cream Equipment Market
Food Processing Equipment
Commercial Panini Machine Market
Food Processing Equipment
Plastic Processing Machinery Market
Food Processing Equipment
Multi Ovens Market
Food Processing Equipment
Industrial Graters Market
Food Processing Equipment
Cereal Rolling Machine Market
Food Processing Equipment
Industrial Planetary Mixers Market
Food Processing Equipment
Canning Machine Market
Food Processing Equipment
Alternative Protein Processing Equipment Market
Food Processing Equipment
Bread Maker Market
Food Processing Equipment
Global Industrial Bakery Processing Equipment Market
Food Processing Equipment
Global Non-Thermal Pasteurization Market
Food Processing Equipment
Tomato Processing Machine Market
Food Processing Equipment
Pasty Products Filling Machine Market