
 Food Waste Disposal Equipment Market | 2026-2036
Food Waste Disposal Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Food Waste Disposal Equipment Market Foresight
CE marking under the EU Machinery Directive is unwinding the competitive field for manufacturers seeking European market access. InSinkErator leverages its century-long brand heritage and extensive distribution network to dominate residential channels in North America. Emerson Electric anchors the industrial segment through its motor technology leadership and captive component supply. Hobart Corporation specializes in heavy-duty commercial systems designed for institutional canteens and food processing environments.
Food waste disposal equipment encompasses electromechanical units that shred, grind, or pulverize organic refuse through rotating impeller plates and grinding rings, typically operating at 1725-1800 RPM with ½ to 10 horsepower motors to render waste suitable for sewer systems or composting streams. Garbage disposers lead the product type category in installed base across residential and light commercial settings, while automatic sensor-based technology commands premium positioning due to water conservation features and reduced cross-contamination risk. Commercial kitchens and food processing units represent the most structurally significant application segments, with the former driving replacement cycles and the latter requiring customized high-capacity configurations.
The EPA administers food waste diversion guidelines that shape procurement criteria for institutional buyers in the United States, while CE marking and EU Machinery Directive compliance govern product safety and electromagnetic compatibility standards across European markets. India's BIS certification mandates electrical safety testing for imported disposal equipment, creating a compliance threshold that filters smaller exporters. Stakeholders must monitor how municipal organic waste ordinances evolve in major metropolitan areas, as these local regulations increasingly mandate pre-treatment equipment installation rather than voluntary adoption.
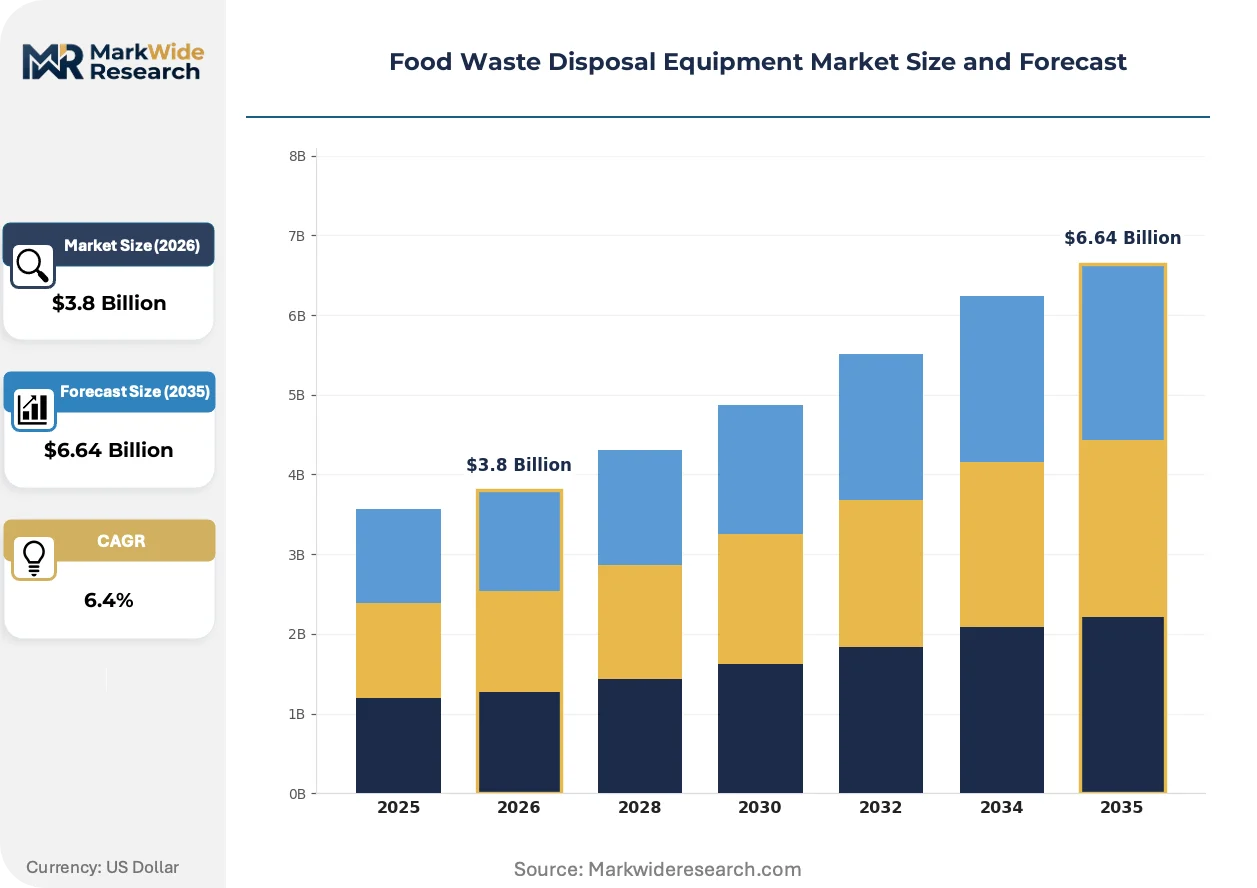
Market Dynamics
Municipal organic waste ordinances are shifting from voluntary adoption to mandatory pre-treatment equipment installation, compelling food service operators and institutional kitchens to upgrade disposal infrastructure ahead of compliance deadlines.
Growth Catalysts
- EPA Diversion Mandates:The EPA's food waste diversion guidelines in the United States are compelling institutional buyers to specify certified disposal equipment in procurement contracts.
- German Organic Waste Laws:Municipal organic waste separation laws in Germany are among the strictest in Europe, driving replacement cycles in commercial kitchens.
- Sensor-Based Automation:Automatic sensor-based technology with water conservation features is commanding premium positioning in hospitality procurement.
Market Restraints
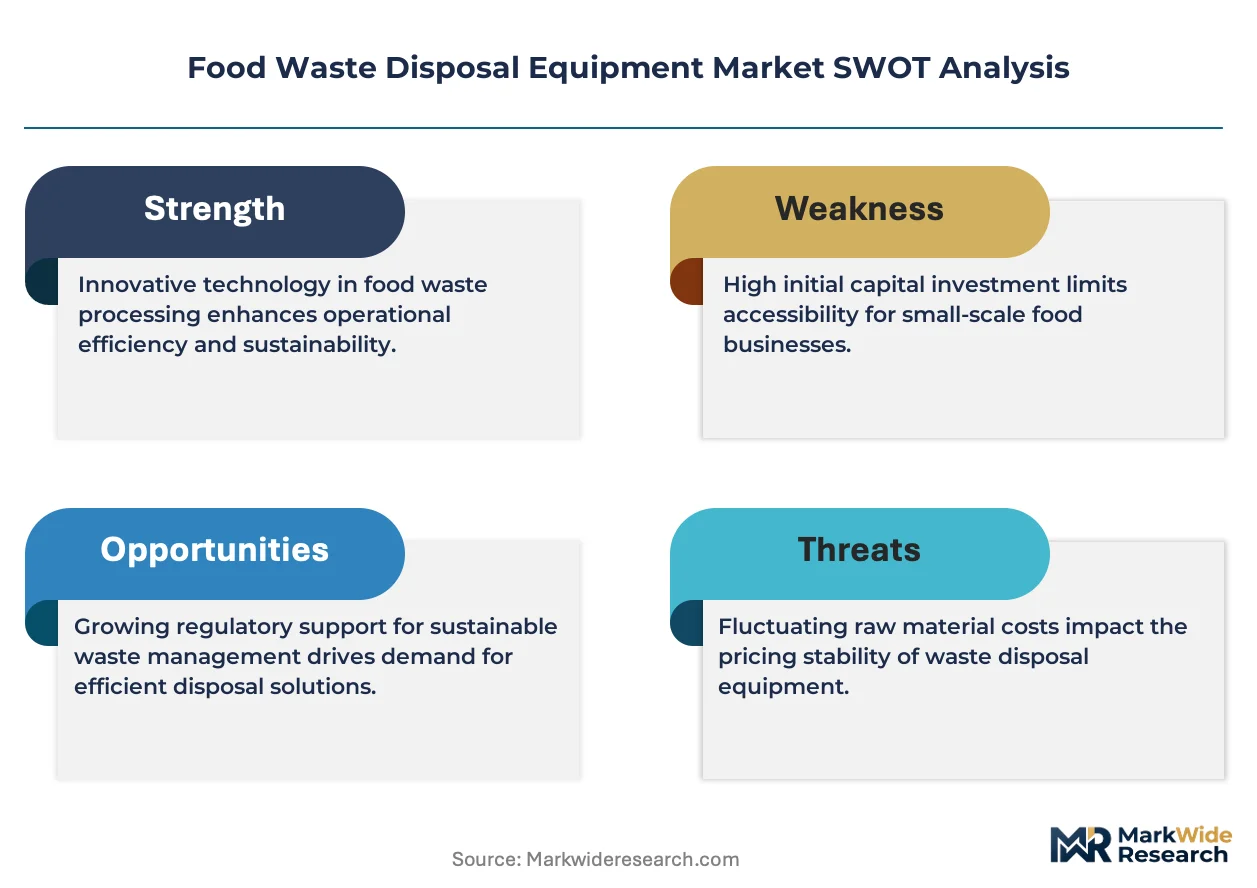
- Copper and Electrical Steel Volatility:Motor laminations and winding materials face input cost swings that compress margins for manufacturers of ½ to 10 horsepower units.
- CE Marking Compliance Burden:The EU Machinery Directive and electromagnetic compatibility standards create a fixed cost barrier that filters smaller exporters from European market access.
- Composting Infrastructure Substitution:Centralized municipal composting facilities in Scandinavian cities are reducing the economic case for on-site disposal equipment in residential settings.
Strategic Opportunities
- India BIS Certification Gap:Electrical safety testing mandates for imported equipment create a compliance threshold that domestic manufacturers can exploit against smaller exporters.
- Food Processing Customization:High-capacity configurations for food processing units represent an underserved segment requiring engineered grinding ring and impeller plate specifications.
- Water-Scarce Region Premium:Sensor-based systems with reduced water consumption are capturing procurement preference in drought-prone Australian and Southwestern US municipalities.
Industry Challenges
- Electromechanical Technician Scarcity:Maintenance of 1725-1800 RPM grinding systems requires specialized motor repair skills that food service operators struggle to source.
- Legacy Sewer Infrastructure Compatibility:Older municipal sewer systems in Eastern European cities impose technical constraints on waste particle size that limit equipment specification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Waste Disposal Equipment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Garbage Disposers, Shredders, Compactors, Grinders, Pulverizers Application: Commercial Kitchens, Food Processing Units, Hospitality, Institutional Canteens, Catering Services Technology: Batch Processing, Continuous Flow, Manual Operation, Automatic Sensor-Based, High-Efficiency Motors End User: Restaurants, Food Manufacturers, Waste Management Firms, Hotels, Cafeterias |
| Companies Covered | InSinkErator, Emerson Electric, Whirlpool Corporation, Waste King, GE Appliances, Moen, BioHiTech, Somat, Hobart Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Waste Disposal Equipment Market Shifts & Advancements
Equipment form factors and control architectures are converging around water efficiency and space constraints, reshaping how manufacturers differentiate residential and commercial product lines.
Brushless DC motor technology is replacing traditional induction motors in mid-range residential disposers, cutting energy draw and enabling variable speed control. Apartment developers in Tokyo and Singapore are specifying these units for high-density installations where electrical load management is critical. The technology is miniaturizing motor housings while maintaining torque output, allowing under-sink placement in tighter cabinet configurations.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in refrigeration-linked food waste systems, indirectly pressuring disposal equipment makers to decouple from cold-chain integrated units. Manufacturers are responding with standalone grinding systems that bypass refrigeration entirely. Commercial kitchen operators in France and Italy are accelerating procurement of these decoupled units ahead of enforcement milestones.
Leasing models with bundled maintenance are displacing capital purchase in North American hospitality chains. Equipment-as-a-service contracts shift grinder replacement risk to vendors while guaranteeing uptime for high-volume casino and stadium kitchens. This restructuring is most visible in Las Vegas and Atlantic City food service clusters where operational continuity outweighs ownership preference.
Food Waste Disposal Equipment Market Segmentation
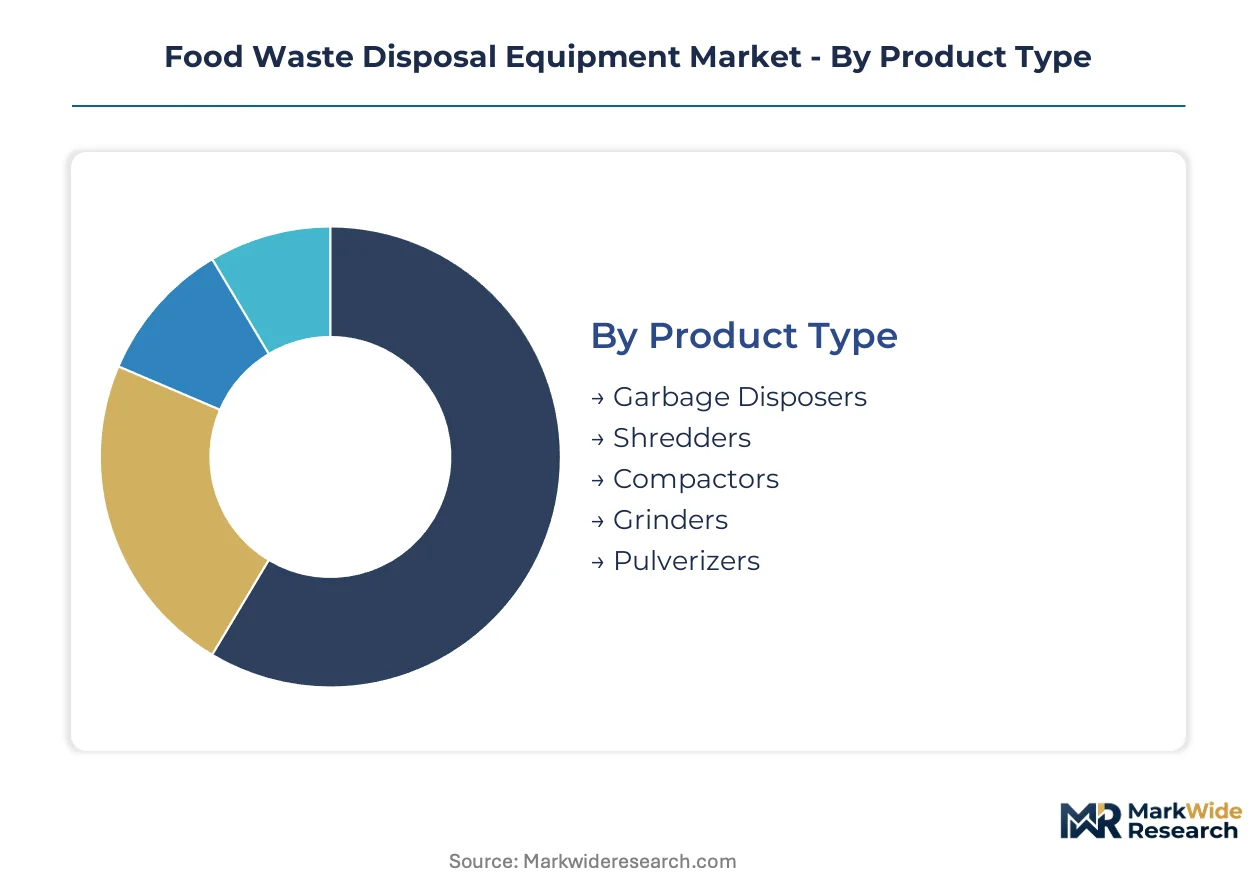
Equipment specification varies sharply across operational contexts, from residential under-sink units to industrial grinding systems processing metric tons hourly. Procurement criteria diverge by end-use intensity, regulatory exposure, and infrastructure compatibility, creating distinct competitive arenas within each segment category.
Product Type:
Domestic demand concentrates in garbage disposers and compactors for residential retrofit markets, while export volumes favor heavy-duty shredders and pulverizers for food processing installations in Germany, Japan, and Australia.
- Garbage Disposers:Electromechanical units with ½ to 1 horsepower induction motors operating at 1725 RPM, designed for residential sink mounting and sewer discharge. Demand clusters in US metropolitan areas with legacy waste diversion mandates and established sewer infrastructure, driven by replacement cycles in housing stock built before 2010.
- Shredders:High-torque rotary systems with hardened steel cutting assemblies processing 500-2000 kg per hour for food manufacturing pre-treatment. Export-led sales concentrate in German organic waste compliance environments where municipal separation laws mandate particle size reduction ahead of anaerobic digestion.
- Compactors:Hydraulic compression units reducing waste volume by 75-90% for hospitality and institutional settings with constrained storage footprint.
- Grinders:Industrial-scale impeller-plate systems with 5-10 horsepower motors rendering organic refuse for composting or biogas feedstock preparation.
- Pulverizers:High-speed hammer-mill configurations achieving sub-5mm particle consistency for specialized food processing and pharmaceutical waste streams.
Garbage disposers command the established base. The steepest expansion runs through shredders.
Application:
Cost tier differentiation separates capital-intensive continuous-operation systems from intermittent-use equipment, with procurement budgets ranging from $200 residential units to $50,000 industrial installations.
- Commercial Kitchens:Mid-capacity batch or continuous-flow systems installed in restaurants, hotels, and catering facilities with 50-500 meal equivalents daily. Demand concentrates in US hospitality corridors where EPA diversion guidelines shape procurement specifications and operational permitting.
- Food Processing Units:Engineered high-capacity configurations with customized grinding ring geometries and corrosion-resistant alloys for meat, dairy, and produce waste streams. Japanese and Australian food manufacturers drive specification innovation for water-scarce operating environments.
- Hospitality:Compact under-counter units prioritizing acoustic dampening and space efficiency for front-of-house aesthetic constraints.
- Institutional Canteens:Heavy-duty systems with redundant motor configurations ensuring operational continuity for military, prison, and university feeding operations.
- Catering Services:Mobile or skid-mounted equipment for off-site event waste processing with temporary utility connections.
Commercial kitchens represent the volume anchor. Food processing units are climbing the fastest.
Technology:
Customer type splits between price-sensitive residential buyers favoring manual and batch systems, and commercial operators specifying automatic and high-efficiency configurations to reduce labor and utility exposure.
- Batch Processing:Lidded chamber systems with interlocked safety mechanisms processing discrete waste loads of 2-5 kg, dominant in European residential markets with strict water authority discharge standards.
- Continuous Flow:Open-throat designs with water injection allowing uninterrupted feeding, standard in US commercial installations where throughput velocity outweighs water consumption concerns.
- Manual Operation:Basic electromechanical units requiring user activation and water control, occupying economy pricing tiers in emerging markets with BIS certification barriers.
- Automatic Sensor-Based:Infrared or load-cell activation with optimized water dosing reducing consumption 30-40% versus manual equivalents, commanding premium positioning in Australian drought-prone municipalities and Southwestern US water districts.
- High-Efficiency Motors:Brushless DC and permanent magnet synchronous designs cutting energy draw 15-25% while enabling variable speed control for load-matched operation.
Continuous flow systems command the established base. Automatic sensor-based technology is gaining share fastest.
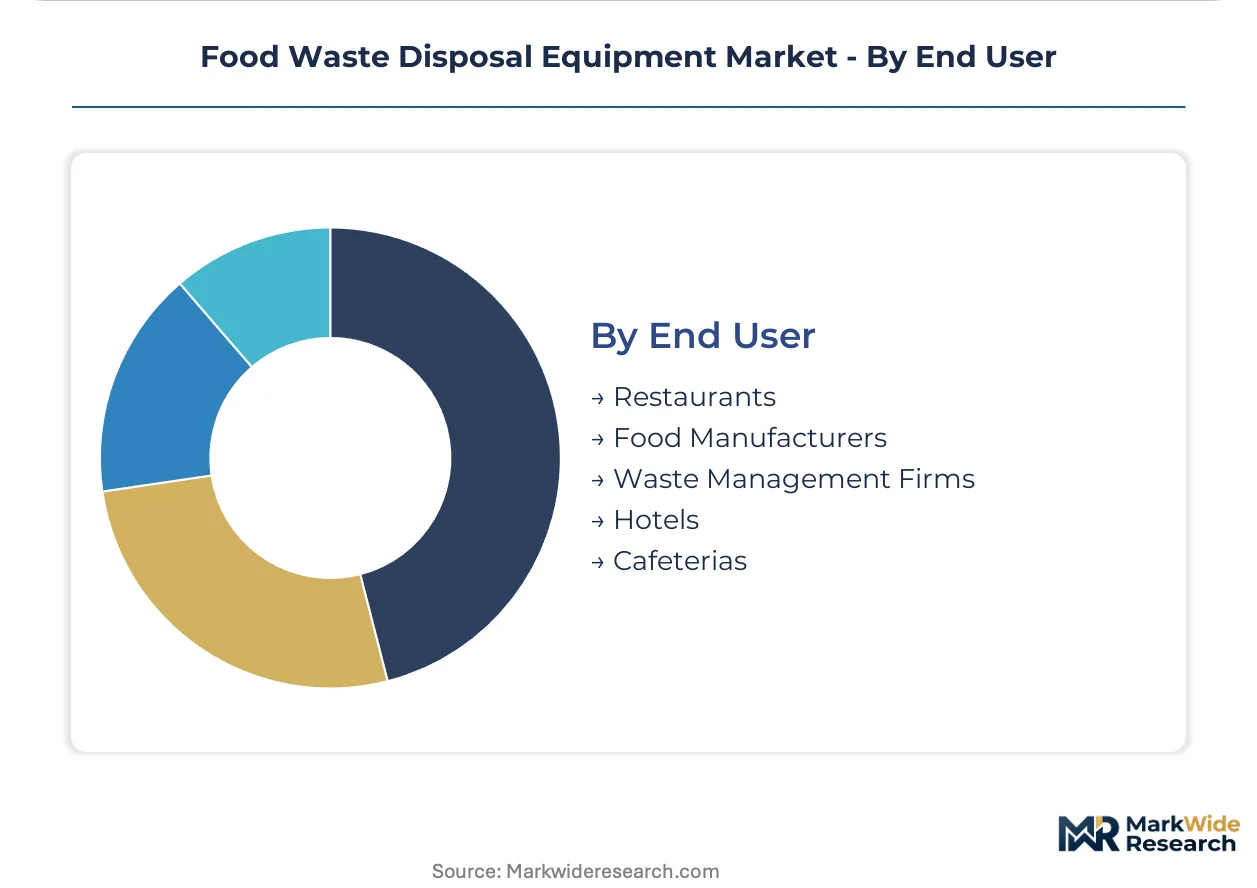
End User:
Supply concentration in motor and grinding component manufacturing creates tiered availability, with waste management firms and food manufacturers accessing specialized engineering while restaurants and hotels source through distribution channels.
- Restaurants:High-frequency users with 8-16 hour daily operation cycles driving replacement demand every 5-7 years in high-volume independent and chain establishments.
- Food Manufacturers:Engineering-intensive buyers specifying custom impeller geometries, alloy specifications, and integration with production line control systems for continuous waste extraction.
- Waste Management Firms:Fleet operators deploying mobile or centralized grinding assets for commercial organic waste collection and pre-processing ahead of composting or anaerobic digestion.
- Hotels:Procurement coordinated through corporate sustainability mandates with brand-level equipment standards and preferred vendor agreements.
- Cafeterias:Institutional buyers subject to federal or state procurement guidelines specifying certified equipment for schools, hospitals, and government facilities.
Restaurants command the established base. Waste management firms show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA diversion mandates and municipal organic waste ordinances are reshaping procurement patterns across key markets. Equipment specification now hinges on regulatory compliance timelines rather than operational preference alone.
United States
Commercial kitchen operators in Las Vegas and Atlantic City hospitality clusters are accelerating equipment replacement cycles ahead of EPA enforcement milestones. The EPA's food waste diversion guidelines compel institutional buyers to specify certified disposal systems in federal procurement contracts. Southwestern water districts in Arizona and California are prioritizing sensor-based units with reduced water consumption.
Germany
Municipal organic waste separation laws rank among Europe's strictest, driving demand for shredders with precise particle size control. CE marking under the EU Machinery Directive filters smaller exporters from market access, consolidating procurement around established suppliers. Bavarian food manufacturers and Baden-Württemberg processing facilities are upgrading to high-capacity configurations for anaerobic digestion feedstock preparation.
Japan
Apartment developers in Tokyo are specifying brushless DC motor disposers for high-density installations where electrical load management is critical. METI efficiency standards push manufacturers toward variable speed control and miniaturized motor housings. Osaka-based commercial kitchen operators are adopting standalone grinding systems decoupled from refrigeration-linked units.
Australia
Drought-prone municipalities in New South Wales and Victoria are capturing premium positioning for automatic sensor-based technology with 30-40% water reduction. The country's national environmental regulator is tightening discharge standards for commercial food service operators. Sydney and Melbourne hospitality clusters are shifting toward leasing models with bundled maintenance to guarantee operational continuity.
India
BIS certification mandates for electrical safety testing create compliance thresholds that domestic manufacturers exploit against smaller exporters. Maharashtra and Gujarat food processing units are driving specification innovation for water-scarce operating environments. The central government's PLI scheme for domestic manufacturing is incentivizing local assembly of mid-range residential disposers.
Food Waste Disposal Equipment Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with captive motor technology and specialized commercial kitchen equipment fabricators. The vendor base separates into three tiers: premium brands with century-long heritage, mid-range suppliers with distribution scale, and regional specialists with customization capabilities. Dominant competitive moves include backward integration into motor laminations and grinding component supply, plus geographic expansion through certification-first market entry strategies.
Within the heritage-brand tier, InSinkErator and Emerson Electric occupy positions shaped by decades of residential channel presence and industrial motor technology leadership respectively. Hobart Corporation sits within the heavy-duty commercial specialization vector, exemplifying the institutional canteen focus that separates food processing-grade suppliers from light commercial competitors. These three anchors represent distinct competitive archetypes: brand heritage, captive technology, and application-specific engineering.
| Leading Market Players |
|---|
| InSinkErator |
| Emerson Electric |
| Whirlpool Corporation |
| Waste King |
| GE Appliances |
| Moen |
| BioHiTech |
| Somat |
| Hobart Corporation |
| Others |
Supply & Pricing Matrix
Capacity utilization at motor lamination foundries in China and Germany shapes price floors across horsepower tiers, concentrating supply-side leverage with Emerson Electric and Hobart Corporation while squeezing mid-tier assemblers dependent on spot component markets.
Pricing Analysis
Certification level creates the primary spread across residential and commercial tiers, with CE-marked units commanding 15-25% premia over BIS-grade equivalents in Indian import channels. Three-tier pricing structure separates sensor-automated premium lines from standard continuous-flow systems and economy manual units. Pricing pressure stems from copper and electrical steel volatility compressing margins on ½ to 3 horsepower motors. Quick-service restaurants exhibit highest price sensitivity, while food processing manufacturers prioritize engineering customization over unit cost.
Supply Chain Analysis
Inventory cycles for grinding ring alloys extend 12-16 weeks, tethering production schedules to specialty steel mill capacity in Japan, Germany, and South Korea. Motor laminations draw from electrical steel rolling capacity concentrated in China and India, with winding copper sourced through Chilean and Indonesian smelter networks. Single-source vulnerability runs through rare-earth magnet supply for brushless DC motor programs. Distribution runs through HVAC and foodservice equipment wholesalers in North America, direct OEM relationships in Europe, and electrical goods importers in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized electromechanical repair capabilities are thinning across foodservice operator workforces, creating asset-availability risk that reshapes vendor selection criteria toward bundled maintenance contracts and equipment-as-a-service models.
For Market Incumbents: Consolidate grinding component supply through captive foundry investments or long-term offtake agreements with Japanese specialty steel producers. Deepen channel control in German and Australian markets where municipal organic waste ordinances are tightening fastest, preempting certification-first entrants from gaining specification footholds in institutional procurement.
For New Entrants and Emerging Players: Aftermarket service coverage gaps in Las Vegas and Atlantic City hospitality clusters present immediate white-space opportunity. Target water-scarce Australian municipalities with sensor-based rental offerings bypassing capital procurement cycles. Lead with leasing models that shift grinder replacement risk to vendor balance sheets, mirroring the equipment-as-a-service restructuring visible in North American casino kitchens.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors brushless DC motor specialists with miniaturization IP applicable to Tokyo and Singapore high-density installations. Long-term viability hinges on decoupling from refrigeration-integrated legacy architectures ahead of EU F-Gas Regulation enforcement milestones. Monitor BIS certification approval velocity in India as inflection indicator for domestic manufacturing scale-up feasibility under PLI scheme incentives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Laminations | Captive electrical steel supply insulates margin compression from commodity volatility in copper and alloy markets. |
| Sensor-Automation Product Line Expansion | Water conservation features capture premium positioning in EPA-mandated Southwestern US water districts and Australian drought zones. |
| Equipment-as-a-Service Leasing Model | Bundled maintenance contracts shift operational risk to vendors while guaranteeing uptime for high-volume hospitality operators. |
| CE Marking-First Market Entry | EU Machinery Directive compliance filters smaller exporters, consolidating procurement around certified suppliers in German organic waste compliance environments. |
| Brushless DC Motor Platform Development | METI efficiency standards in Japan and electrical load constraints in Singapore high-rises favor variable-speed miniaturized configurations. |
Research Methodology
The analysis maps garbage disposers, shredders, compactors, grinders, and pulverizers, each validated through interviews with foodservice equipment distributors, commercial kitchen maintenance directors, food processing plant engineers, and municipal waste authority procurement leads. Secondary validation draws from EPA diversion guideline documents, EU Machinery Directive technical files, BIS certification registries, and customs trade data for electromechanical waste equipment. Bottom-up unit economics triangulate against top-down market sizing across horsepower tiers and application intensity segments.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated product type, application intensity, technology tier, and end-user procurement sophistication. CAGRs were derived from replacement cycle analysis, regulatory compliance timeline mapping, and equipment-as-a-service adoption curves. Industry-specific forecast inputs included municipal organic waste ordinance enforcement schedules and brushless DC motor penetration rates in high-density residential developments.
Underlying assumptions cover copper and electrical steel price stability, CE marking regulatory continuity, and hospitality sector capital expenditure recovery, with deviation risk concentrated in tariff exposure for Chinese motor component imports and municipal budget constraints affecting institutional procurement timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Insect Protein Processing Equipment Market
Food Processing Equipment
Global Shawarma Machines Market
Food Processing Equipment
Continuous Fryer Machine Market
Food Processing Equipment
Countertop Blast Chiller Market
Food Processing Equipment
Deep Fryer Machine Market
Food Processing Equipment
Global Starch Recovery Systems Market
Food Processing Equipment
Nigeria Cocoa Processing Market
Food Processing Equipment
Multi Ovens Market
Food Processing Equipment
Global Food and Beverage Coding and Marking Equipment Market
Food Processing Equipment
Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Loss-In-Weight Feeder Market
Food Processing Equipment
Dehydrators Market
Food Processing Equipment
Food Automation Market
Food Processing Equipment
Dual-Ovenable Cook Trays Market
Food Processing Equipment
Deep Fryer Market
Food Processing Equipment
Food Processing and Handling Equipment Market