
 Countertop Convection Oven Market | 2026-2036
Countertop Convection Oven Market Size, Share, and Industry Trends Forecast 2026-2036
Countertop Convection Oven Market Outlook
Commercial food service operators is reorganizing countertop convection oven procurement away from casual home cooks toward professional kitchens with limited square footage. Breville Group leverages its premium product specialization to capture high-margin residential segments in Australia and North America. Hamilton Beach competes on manufacturing scale across mid-tier commercial and residential channels. De'Longhi sustains brand strength in European food service markets through programmable control interfaces.
A countertop convection oven circulates heated air via an internal fan to distribute temperature uniformly across the cooking chamber, typically operating between 150°F and 500°F with fan speeds engineered to reduce cooking times by 25% compared with conventional radiant ovens. The appliance serves commercial kitchens requiring accelerated throughput without permanent installation infrastructure. Digital and programmable control types command margin premiums as restaurants automate recipe consistency across shift workers. Portable units represent the fastest-growing product type as food trucks and pop-up catering operations expand mobility requirements. Built-in configurations remain mature in residential renovation cycles where permanent kitchen integration drives replacement demand.
FDA food-contact surface regulations and DOE appliance efficiency standards govern commercial and residential unit sales in the United States. EU Ecodesign requirements and CE marking obligations shape import compliance for manufacturers serving European restaurants and caterers. China's GB standards for household and similar electrical appliances establish safety benchmarks for products manufactured domestically. Stakeholders must monitor how regional energy efficiency thresholds evolve and whether programmable smart connectivity becomes a compliance-adjacent purchasing criterion.
Market Dynamics
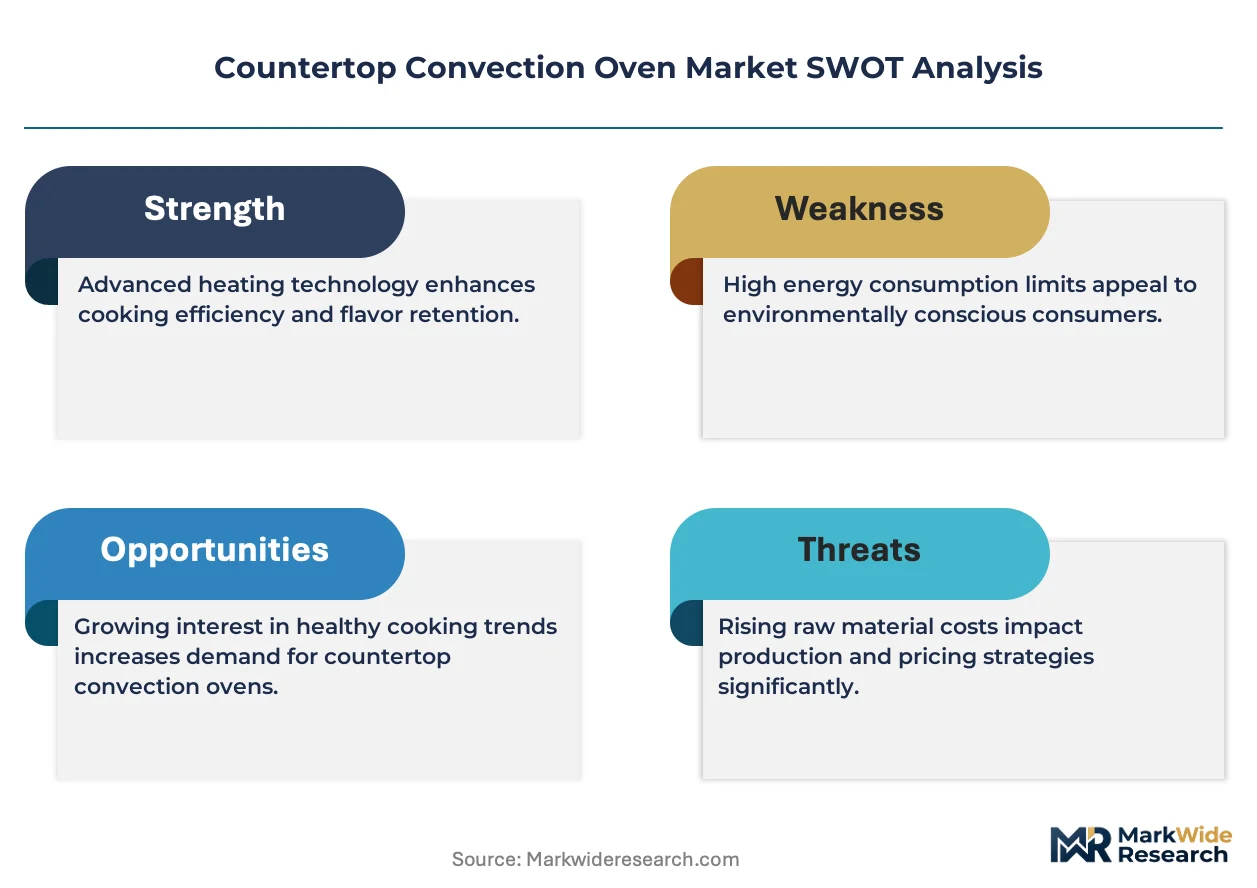
Commercial kitchen infrastructure constraints are compressing equipment footprints while operators demand throughput parity with full-size ovens, forcing manufacturers to engineer thermal efficiency into smaller cavities.
Growth Catalysts
- Cloud kitchen proliferation:Delivery-only food facilities in the United States and China require compact, high-output cooking equipment without ventilation hood dependencies.
- EU Ecodesign standards:Tightening efficiency thresholds for commercial cooking appliances create compliance-driven replacement cycles across German and French restaurant chains.
- Infrared-assisted convection:Hybrid heating technology reduces preheat times and energy draw, attracting independent operators seeking utility cost control.
Market Restraints
- Stainless steel price volatility:Chamber construction relies heavily on 304-grade stainless, exposing margins to commodity swings from East Asian mills.
- Fan motor supply concentration:High-RPM brushless DC motors for commercial units concentrate among Taiwanese and Japanese component suppliers.
- Induction oven substitution:Ventless induction ranges with comparable speed threaten countertop convection in front-of-house cooking stations.
Strategic Opportunities
- India's organized food service expansion:Quick-service restaurant chains in Mumbai and Bangalore seek standardized, programmable ovens for menu consistency.
- Smart connectivity integration:IoT-enabled recipe management and remote diagnostics open premium pricing in North American ghost kitchen networks.
- Energy Star certification tailwinds:US utility rebate programs for efficient commercial equipment accelerate upgrade decisions among independent operators.
Industry Challenges
- Controls engineering talent scarcity:Embedded systems developers capable of integrating programmable logic with food-safety protocols command premium compensation.
- Multi-certification timelines:Simultaneous UL, NSF, and CE marking requirements extend product launch cycles by 8-14 months.
- Legacy kitchen electrical infrastructure:Older buildings in dense urban cores lack 240V circuits required by high-wattage commercial units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Countertop Convection Oven Market |
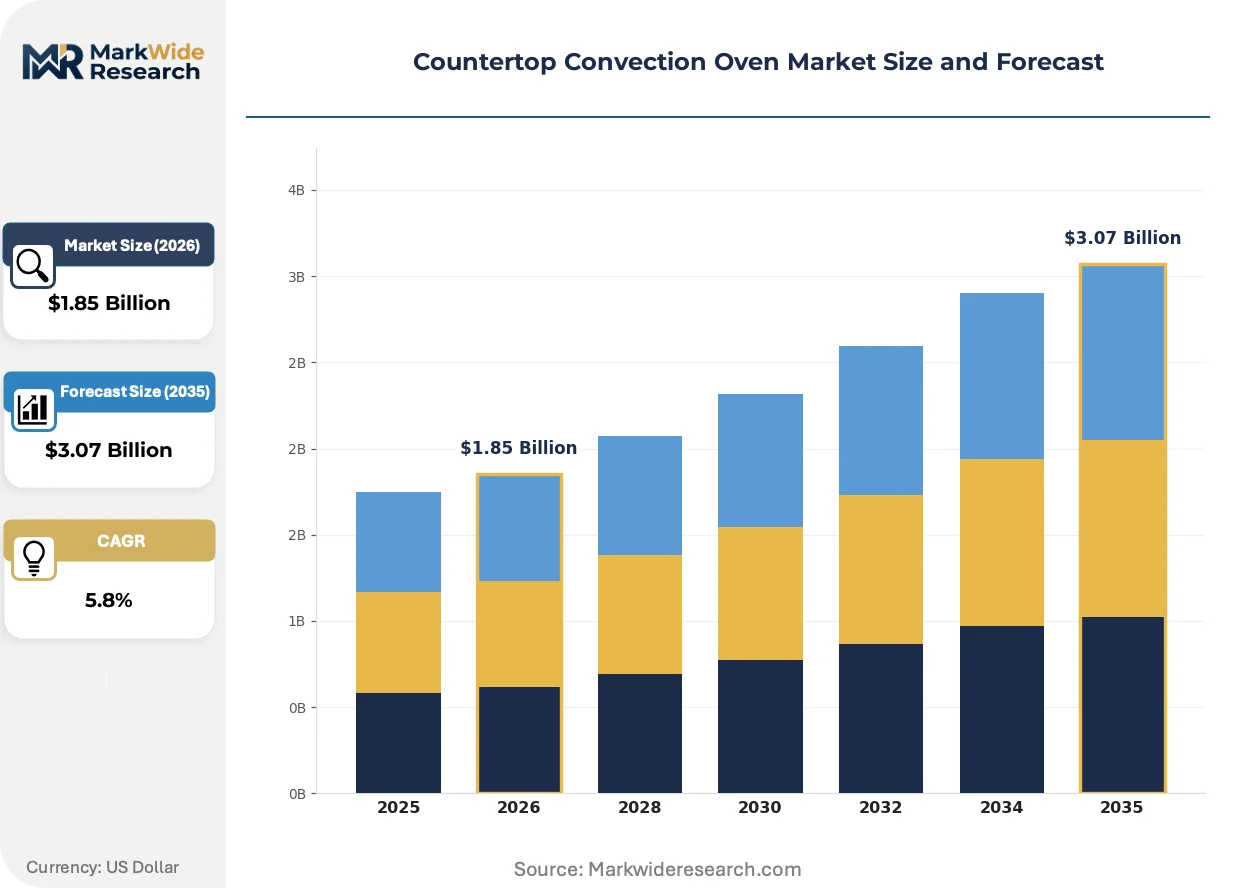
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.07 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Built-in, Portable, Commercial Power Rating: 1000W, 1500W, 1800W, 2000W Control Type: Mechanical, Digital, Programmable, Touchscreen End User: Residential, Restaurants, Catering, Food Trucks |
| Companies Covered | Breville Group, Whirlpool Corporation, Panasonic Corporation, Cuisinart, Hamilton Beach, De'Longhi, KitchenAid, Oster, SharkNinja Operating LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Countertop Convection Oven Market Strategic Shifts
Equipment intelligence and thermal engineering are converging to redefine what compact ovens can execute, with connectivity and precision controls becoming baseline expectations rather than premium differentiators.
Advanced cavity materials incorporating ceramic-coated aluminum alloys are bifurcating the product landscape. High-volume bakery chains adopt these surfaces for rapid thermal recovery and reduced sticking. The technology is compressing maintenance intervals and enabling smaller manufacturers to challenge incumbents on performance metrics previously gated by heavy-gauge stainless construction.
DOE commercial cooking equipment efficiency standards are tightening test procedures for idle energy consumption. Manufacturers must redesign insulation packages and control algorithms to maintain compliance. Full-service restaurants in California and New York face the steepest retrofit obligations as state-level mandates outpace federal minimums.
Equipment-as-a-service financing is displacing capital purchase models among multi-unit operators. Leasing providers bundle maintenance and software updates into per-hour usage fees. This shift concentrates most visibly in United Kingdom pub chains and US fast-casual rollouts where liquidity preservation drives procurement decisions.
Countertop Convection Oven Market Segmentation
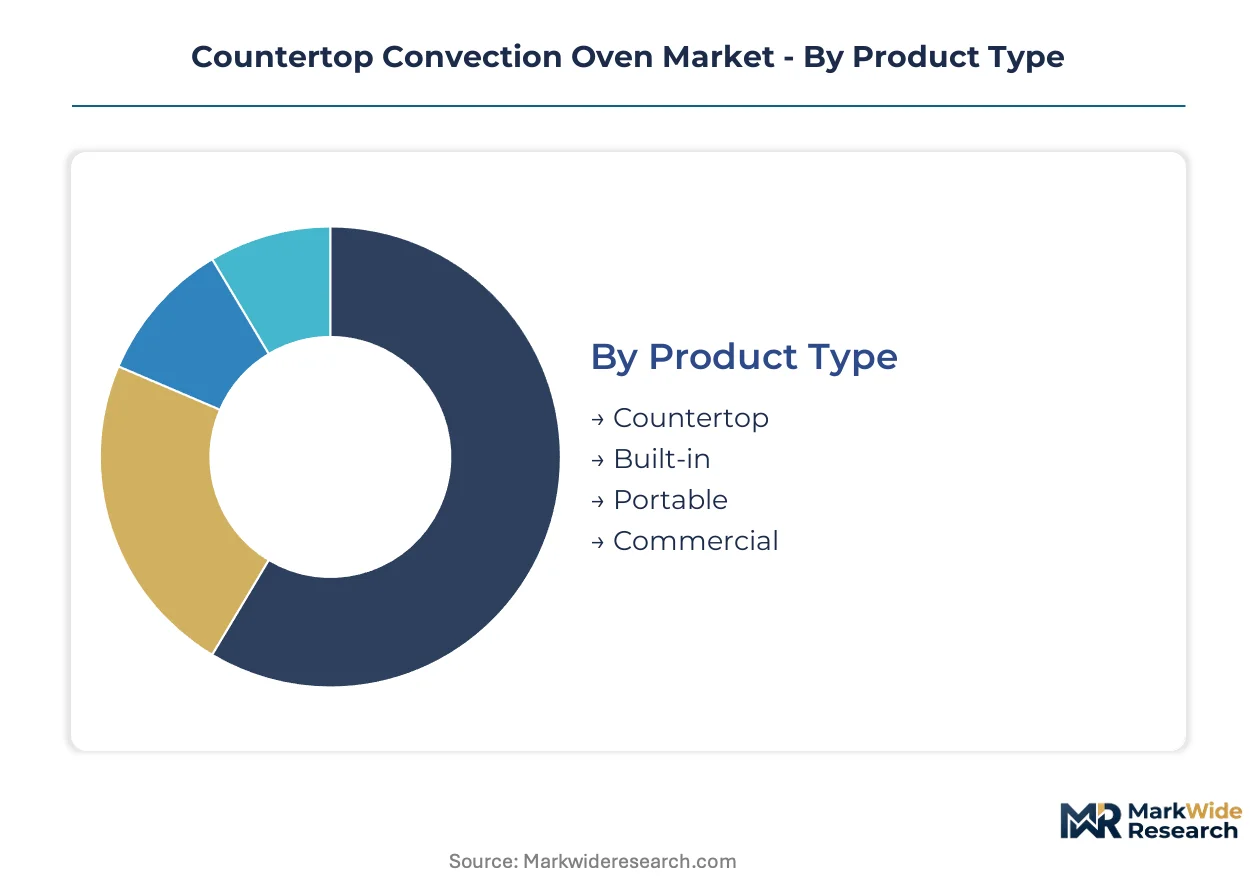
Countertop convection oven procurement channels diverge sharply across segments, with food service distributors dominating commercial-grade sales while retail and direct-to-consumer routes capture residential purchases. Understanding these channel dynamics enables manufacturers to align product specifications with buyer workflows and margin expectations.
Product Type:
Channel mix varies dramatically by installation requirements: portable and countertop units flow through food service equipment distributors and e-commerce platforms, while built-in configurations depend on kitchen design firms and renovation contractors.
- Countertop:Freestanding units with external housing designed for benchtop placement in commercial kitchens. Demand concentrates in United States cloud kitchen facilities and German independent restaurants seeking ventilation-hood-free alternatives. Operators prioritize rapid deployment without infrastructure modification.
- Portable:Lightweight chassis with carrying handles and 120V compatibility for mobile operations. Food trucks in Austin, Texas and pop-up catering operations across California represent the steepest expansion trajectory for this configuration. Mobility requirements override thermal capacity in purchase decisions.
- Built-in:Flush-mount designs integrating with cabinetry systems. Residential renovation cycles in suburban United States markets and custom kitchen projects in Italy sustain replacement demand.
- Commercial:Heavy-gauge construction with NSF certification and stackable configurations. Multi-unit restaurant chains in China and franchise operators in India standardize procurement through approved vendor programs.
By volume, countertop leads. By growth pace, portable is ahead.
Power Rating:
Cost tier alignment separates entry-level residential purchases from premium commercial installations, with electrical infrastructure requirements creating natural segmentation boundaries.
- 1000W:Compact residential units for apartment dwellers and secondary cooking applications. European households in France and Spain favor this tier for energy-conscious daily use.
- 1500W:Mid-range specification balancing preheat speed with standard 120V circuit compatibility. United States home cooks and small catering operations represent the core demand base.
- 1800W:Commercial entry point for independent restaurants requiring throughput without 240V infrastructure. Japanese ramen shops and Korean quick-service concepts adopt this specification widely.
- 2000W:High-output configuration demanding dedicated 240V circuits. Cloud kitchen networks in Shanghai and Dallas deploy these units for production-line cooking stations.
By installed base, 1500W dominates. By upgrade momentum, 2000W is climbing fastest.
Control Type:
Application sophistication drives specification divergence, with high-volume operators automating recipe consistency while cost-sensitive buyers accept manual interfaces.
- Programmable:Multi-stage cooking profiles with memory storage for standardized menu execution. Quick-service chains in Brazil and Saudi Arabia mandate this specification for franchise consistency across locations.
- Digital:Electronic temperature displays and timer functions without recipe storage. Mid-tier restaurants in Poland and residential buyers in Australia represent the primary adoption segments.
- Touchscreen:Capacitive interfaces with graphical menu navigation and connectivity readiness. Ghost kitchen operators in London and New York pilot these units for remote diagnostics integration.
- Mechanical:Rotary dial controls with minimal electronic components. Budget-conscious food trucks in Mexico and rural residential markets sustain this mature specification.
By shipment volume, digital leads. By technology transition, programmable is gaining share fastest.
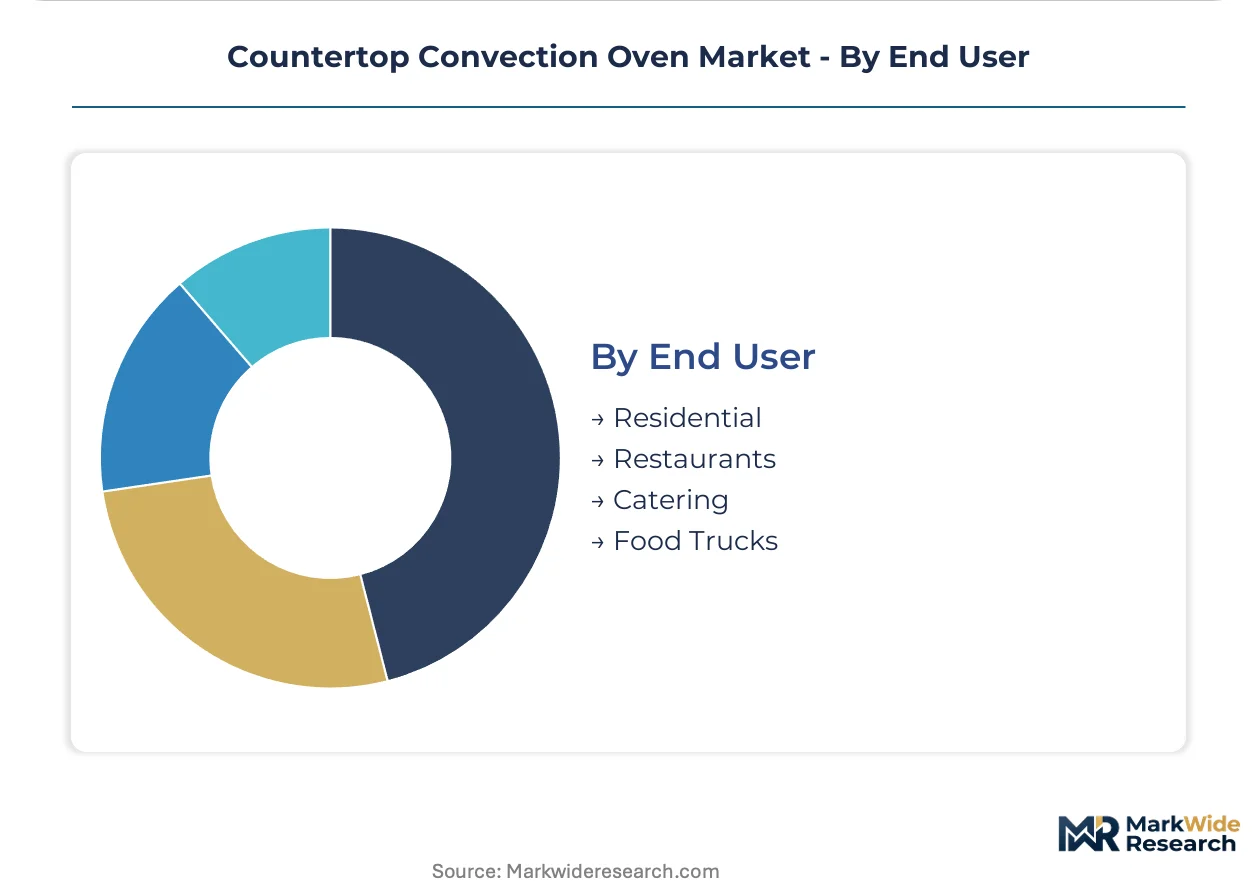
End User:
Customer type determines service expectations and lifecycle economics, with commercial operators demanding durability warranties and rapid parts availability that residential buyers rarely require.
- Restaurants:Full-service and fast-casual operators requiring NSF-listed equipment with 3-5 year service life. Independent operators in Chicago and Berlin represent concentrated procurement clusters.
- Food Trucks:Mobile operators prioritizing 120V compatibility, compact footprints, and vibration-resistant construction. Regulatory compliance with local fire codes in Los Angeles and Miami shapes product selection.
- Catering:Event-based operators needing rapid heat recovery and transport durability. Corporate catering services in Singapore and wedding specialists in Italy drive seasonal demand spikes.
- Residential:Home cooks seeking countertop convenience without permanent installation. Urban apartment dwellers in Toronto and Sydney represent the core demographic.
By absolute units, residential leads. By revenue per unit and replacement frequency, restaurants are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles handles the largest container volume of food service equipment imports into North America, underwriting California's central role in countertop convection oven distribution. Germany's Rhine-Alpine freight corridor channels commercial kitchen machinery from Dutch ports into Central European restaurant supply chains. China's Ningbo-Zhoushan port complex anchors Asia-Pacific manufacturing exports for cloud kitchen infrastructure.
United States
Cloud kitchen networks in Dallas and Austin deploy 2000W units for delivery-only production lines without ventilation hood retrofits. DOE commercial cooking equipment standards tighten idle energy consumption thresholds, forcing insulation redesigns. FDA food-contact surface regulations govern NSF certification requirements for multi-unit restaurant chains standardizing procurement through approved vendor programs.
Germany
Independent restaurants in Berlin and Munich seek ventilation-hood-free alternatives to bypass historic building infrastructure constraints. EU Ecodesign requirements for commercial cooking appliances accelerate compliance-driven replacement cycles across franchise operators. The Rhine-Main industrial cluster hosts distributors serving quick-service chains expanding standardized kitchen footprints into Eastern European markets.
China
Shanghai's cloud kitchen facilities upgrade electrical infrastructure to support high-wattage commercial units for production-line cooking stations. GB standards for household and similar electrical appliances establish safety benchmarks for domestically manufactured equipment. Ningbo-Zhoushan port throughput of food service machinery reflects sustained demand from delivery-only restaurant networks across the Yangtze River Delta.
India
Quick-service restaurant chains in Mumbai and Bangalore mandate programmable control interfaces for menu consistency across franchise locations. BIS certification requirements for commercial electrical appliances shape import compliance for European and East Asian manufacturers. The Maharashtra industrial corridor concentrates distributor networks serving organized food service expansion into tier-two cities.
United Kingdom
Pub chains and fast-casual rollouts adopt equipment-as-a-service financing to preserve liquidity in post-pandemic capital-constrained environments. CE marking obligations for commercial cooking equipment govern import compliance from EU suppliers following regulatory divergence. London's ghost kitchen operators pilot touchscreen-enabled units for remote diagnostics integration into centralized kitchen management platforms.
Countertop Convection Oven Market Competitive Environment
Listed leaders compete with private specialists across premium and volume-tier positioning in the countertop convection oven market. The vendor base fragments across residential appliance conglomerates, commercial food service specialists, and contract manufacturers serving private-label programs. Three archetypes dominate: premium-brand specialists commanding margin premiums through design differentiation; scale-driven manufacturers competing on production efficiency across mid-tier channels; and private-label fabricators supplying distributor-exclusive lines. Consolidation pressure concentrates among mid-tier players seeking geographic expansion, while technology licensing agreements proliferate around programmable control systems.
Within the premium-brand tier, Breville Group and De'Longhi occupy positions anchored by design-forward positioning in residential and European food service channels respectively. Hamilton Beach exemplifies scale-driven competition across mid-tier commercial and residential segments. These three entities represent distinct strategic postures: Australian-originated premium specialization, Italian-based European market strength through programmable interfaces, and broad manufacturing scale across multiple price tiers.
| Leading Market Players |
|---|
| Breville Group |
| Whirlpool Corporation |
| Panasonic Corporation |
| Cuisinart |
| Hamilton Beach |
| De'Longhi |
| KitchenAid |
| Oster |
| SharkNinja Operating LLC |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts with Taiwanese motor suppliers lock in both brushless DC fan motor access and eighteen-month price visibility for commercial oven manufacturers serving cloud kitchen networks in Texas and California. These arrangements insulate procurement teams from spot-market volatility in 304-grade stainless while committing volume thresholds that reshape working capital requirements.
Pricing Analysis
Volume-discount tiering structures stratify across premium NSF-certified commercial units, mid-tier digital-control models, and economy mechanical-dial configurations for food trucks. Price differentiation rests on certification grade and after-sales service bundling, with UL-listed units commanding substantial premiums over CE-marked equivalents in the United States. Pricing pressure stems from induction oven substitution in front-of-house installations, compressing margins for 1800W countertop configurations. Independent restaurants exhibit acute price sensitivity, while ghost kitchen operators prioritize throughput reliability over unit economics.
Supply Chain Analysis
Inbound logistics costs through the Port of Los Angeles and Ningbo-Zhoushan fluctuate with container availability on the transpacific trade lane, compressing landed cost predictability for stainless steel chamber components. Manufacturing concentration centers on China, Taiwan, and Italy, with brushless DC motors sourcing exclusively from East Asian component specialists. Supply chain risk hinges on single-source vulnerability for high-RPM fan assemblies. Distribution runs through food service equipment distributors in North America and specialized commercial kitchen dealers in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across control system architectures creates niche opportunities as programmable logic demands outpace embedded engineering supply, enabling specialist vendors to capture premium positioning in quick-service automation.
For Market Incumbents: Consolidate programmable control engineering capabilities through selective acquisition of embedded systems developers capable of integrating FDA food-safety protocols. Expand captive production of brushless DC motor assemblies to reduce Taiwanese supplier concentration. Channel control through exclusive distributor relationships in Germany's Rhine-Main cluster defends against mid-tier challengers.
For New Entrants and Emerging Players: Lead with ceramic-coated aluminum alloy cavity technology to challenge incumbents on thermal recovery metrics without heavy-gauge stainless capital intensity. India's organized quick-service expansion in Mumbai and Bangalore offers the most penetrable geography, with BIS certification compliance as the critical go-to-market hurdle. Target equipment-as-a-service financing partnerships with UK pub chains to bypass capital purchase barriers.
For Investors and Strategic Acquirers: Contract manufacturers with captive NSF certification capabilities and established relationships with cloud kitchen real estate operators represent the highest-conviction acquisition archetype. Long-term viability hinges on exposure to delivery-only food infrastructure buildout rather than cyclical residential renovation demand. Monitor Energy Star rebate program expansion across US utility territories as the primary demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Manufacturing | Captive brushless DC production reduces Taiwanese supplier concentration for commercial unit lines. |
| Smart Connectivity Platform Launch | IoT-enabled recipe management opens premium pricing in North American ghost kitchen networks. |
| NSF Certification Fast-Track Program | Accelerated compliance pathways capture replacement cycles from California's tightening idle-energy mandates. |
| Ceramic-Coated Cavity Technology Licensing | Technology transfer agreements enable smaller manufacturers to challenge stainless incumbents on performance. |
| Equipment-as-a-Service Financing Expansion | Per-hour usage models preserve liquidity for UK pub chains and US fast-casual rollouts. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, including cloud kitchen facility managers, commercial food service equipment distributors, NSF certification engineers, and embedded systems developers. Secondary validation drew from DOE appliance efficiency filings, EU Ecodesign regulatory databases, FDA food-contact surface guidance documents, and customs import records through the Port of Los Angeles. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
The projection horizon spans segmentation by product type, power rating, control interface sophistication, and end-user application intensity. CAGRs were derived from fitted growth curves calibrated to cloud kitchen facility expansion rates, EU Ecodesign compliance deadlines, and Energy Star rebate program adoption trajectories. Modeled outputs incorporate electrical infrastructure upgrade timelines in dense urban cores and food truck regulatory variance across municipal jurisdictions.
Forecasts assume regulatory continuity in US DOE efficiency standards and EU Ecodesign frameworks; material policy shifts would require re-modeling around accelerated replacement cycles or revised idle-energy test procedures. Stainless steel commodity volatility and fan motor supply concentration represent specific revision triggers. Recalibration cycles align with material shifts in cloud kitchen deployment rates and regional energy efficiency mandate adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Insect Protein Processing Equipment Market
Food Processing Equipment
Freeze-Drying Equipment Market
Food Processing Equipment
Milk Sterilizer Machine Market
Food Processing Equipment
Distillation Analyzer Market
Food Processing Equipment
Batter Mixer Machines Market
Food Processing Equipment
Contact and Convective Dryers Market
Food Processing Equipment
Bottling Line Machinery Market
Food Processing Equipment
Asia-Pacific Commercial Sous Vide Machine Market
Food Processing Equipment
Food and Beverages Air Filters Market
Food Processing Equipment
Pasta Machine Market
Food Processing Equipment
Mooncake Production Line Market
Food Processing Equipment
US Cold Storage Market
Food Processing Equipment
Brewing Equipment Market
Food Processing Equipment
North America Multi Cooker Market
Food Processing Equipment
Craft Beer Saccharification Equipment Market
Food Processing Equipment
Global Food and Beverage Processing Equipment Market