
 Automatic Evisceration System Market | 2026-2036
Automatic Evisceration System Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Evisceration System Market Analytics
Buyer concentration among top-tier poultry integrators is hardening across major protein-producing regions. Marel leverages its full-line automation portfolio to lock in multi-year service contracts with the largest processors. Meyn Food Processing Technology B.V. anchors European demand through localized engineering support and aftermarket parts density. Baader Group differentiates with species-flexible architectures that span poultry, fish, and red meat applications.
An automatic evisceration system is a mechanized line that removes internal organs from slaughtered birds using rotating spoons, vacuum extraction, and precision cutting tools operating at throughputs exceeding 13,500 birds per hour, designed to minimize carcass damage while ensuring food safety compliance. Electrical systems dominate installed capacity due to superior energy efficiency and programmable control precision, though pneumatic configurations retain share in facilities with legacy compressed-air infrastructure. Robotic automation segments attract the fastest upgrade cycles as computer vision-guided arms reduce manual rehang rates and improve yield recovery on variable bird sizes.
The USDA Food Safety and Inspection Service mandates zero-tolerance standards for fecal contamination, compelling processors toward vision-inspected evisceration modules. The EU Machinery Directive and CE marking requirements enforce guarded access points and emergency-stop architectures that lengthen equipment validation timelines. Stakeholders must weigh total cost of ownership against labor substitution rates when selecting between retrofit upgrades and greenfield automated lines.
Market Dynamics
USDA Food Safety and Inspection Service zero-tolerance mandates for fecal contamination are compressing upgrade cycles for vision-inspected evisceration modules across North American processing plants. Labor availability constraints in protein-producing regions are simultaneously accelerating capital deployment toward fully automated lines with reduced manual rehang requirements.
Growth Catalysts
- EU Machinery Directive compliance pressure:CE marking requirements for guarded access points and emergency-stop architectures are compelling European processors toward sensor-integrated equipment replacements.
- Computer vision-guided robotics:Vision systems that adjust cutting parameters to variable bird sizes are reducing yield loss and attracting upgrade investment from large-scale integrators.
- Brazilian integrator consolidation:Volume procurement concentration among top-tier Brazilian poultry processors is driving demand for high-throughput lines exceeding 13,500 birds per hour.
Market Restraints
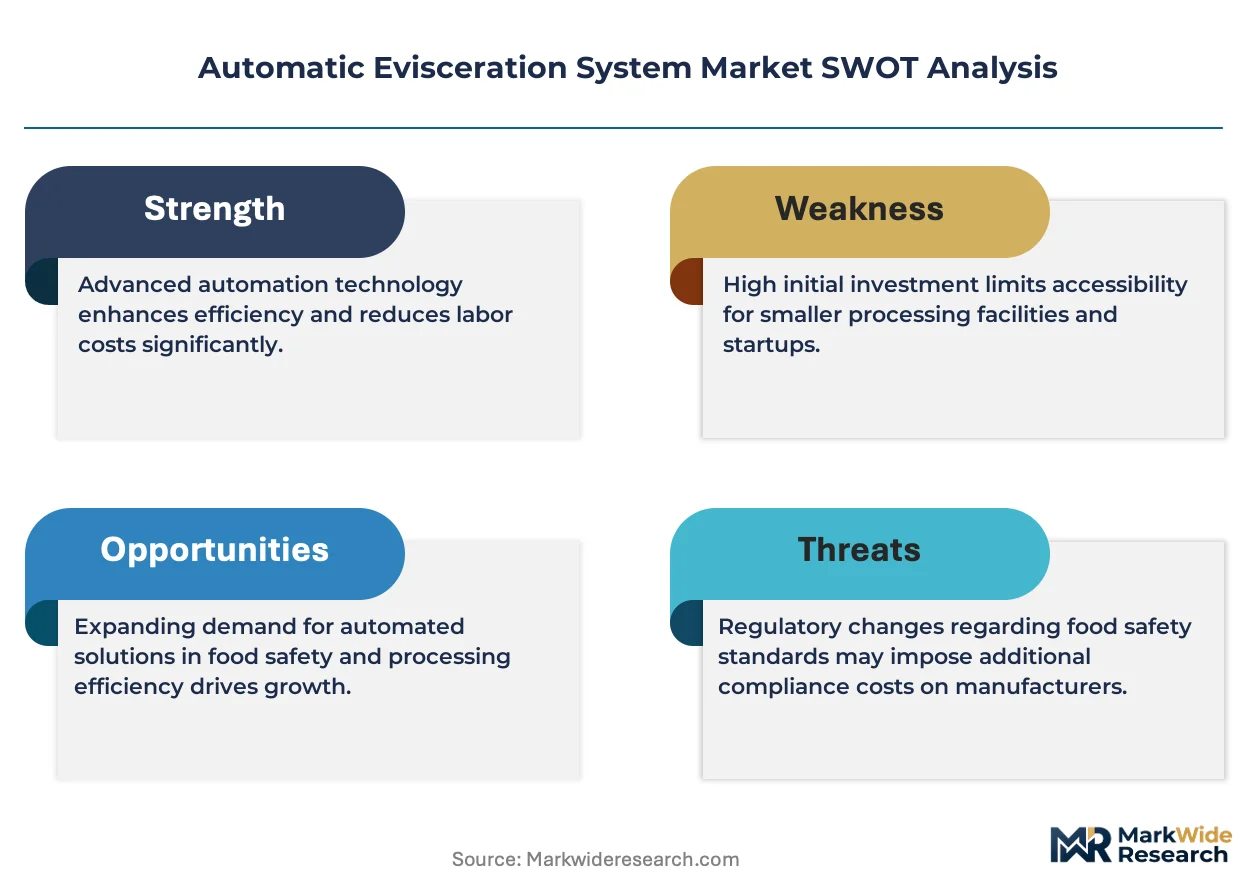
- Stainless steel input volatility:Equipment frames and contact surfaces rely heavily on food-grade stainless steel, exposing manufacturers to commodity price swings.
- Validation timeline friction:FDA HACCP equipment qualification and USDA acceptance testing extend deployment schedules by 8-14 months for greenfield installations.
- Legacy pneumatic infrastructure lock-in:Plants with substantial compressed-air capital resist full electrical conversion despite efficiency advantages.
Strategic Opportunities
- Species-flexible architecture demand:Equipment configurable across poultry, duck, and turkey applications opens procurement relationships with diversified protein processors.
- Aftermarket service unbundling:Independent spare parts and remote diagnostics channels are capturing margin from traditional OEM service contracts.
- Small-bird processing automation:Quail and Cornish hen lines remain underpenetrated by high-speed automation, creating white space for specialized equipment.
Industry Challenges
- Mechatronics technician scarcity:Maintenance of precision cutting tools and vacuum extraction systems requires hybrid mechanical-electrical skills that regional labor pools lack.
- Retrofit integration complexity:Older shackle systems and line configurations resist seamless integration with modern vision-guided modules without substantial infrastructure overhaul.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Evisceration System Market |
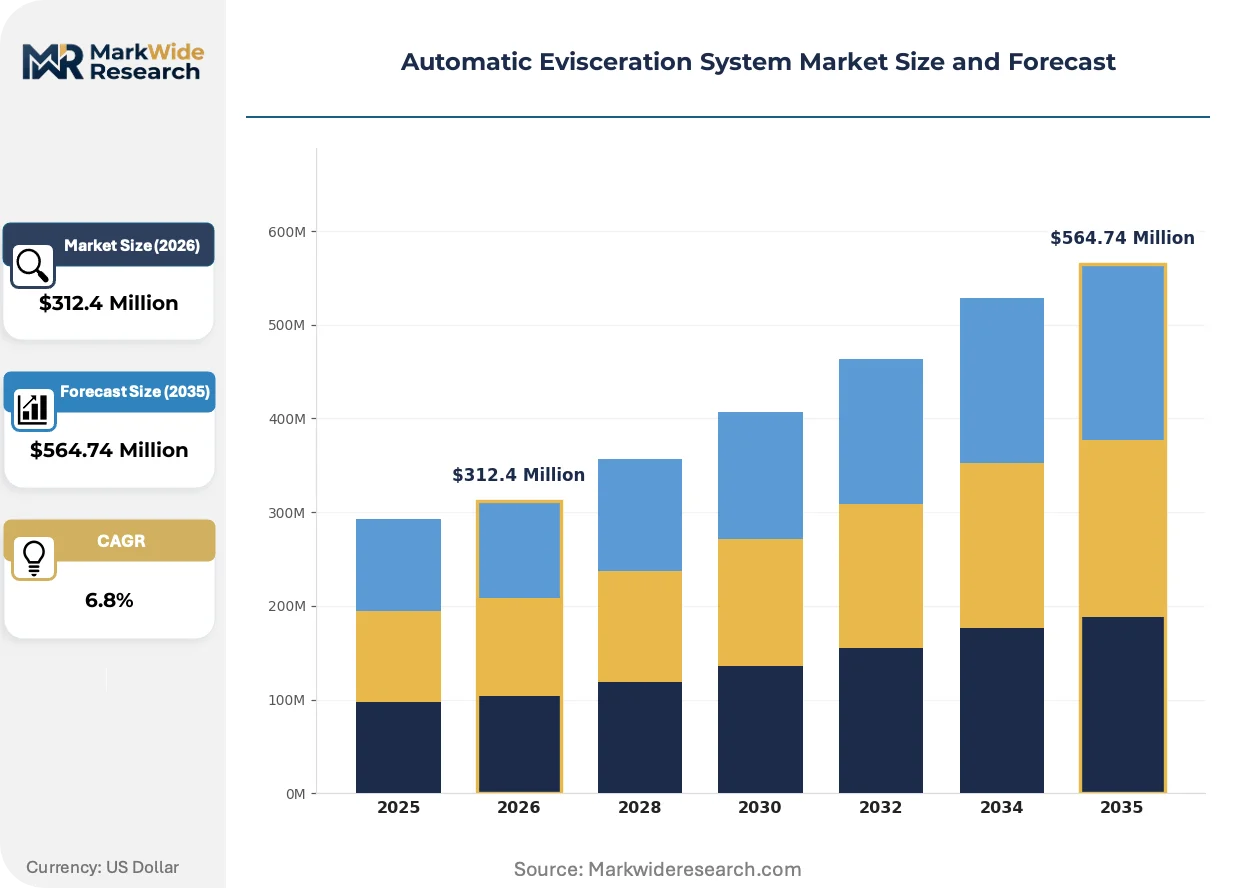
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrical Systems, Pneumatic Systems, Hydraulic Systems, Manual Systems Application: Poultry Processing, Seafood Processing, Meat Processing, Lab Processing End User: Commercial Farms, Processing Plants, Export Facilities, Research Institutions Technology: Robotic Automation, Computer Vision, Sensor Technology, Software Integration |
| Companies Covered | Marel, Meyn Food Processing Technology B.V., Baader Group, John Bean Technologies Corporation, CTB, Inc., Prime Equipment Group, Inc., GEA Group AG, Foodmate NL, Key Technology, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Evisceration System Market Evolving Landscape
Equipment architecture is pivoting from fixed mechanical designs toward adaptive systems that respond to real-time carcass variability. This shift is compressing the traditional trade-off between throughput speed and yield recovery.
Hyperspectral imaging is integrating into evisceration line quality control stations to detect fecal contamination and organ residue with greater precision than RGB camera systems. Large US integrators are deploying these modules at critical control points ahead of USDA inspection stations. The technology is integrating defect detection with automated diverting mechanisms that remove compromised carcasses without line stoppage.
REACH chemical safety restrictions on lubricants and cleaning agents used in food-contact equipment are forcing reformulation of bearing greases and conveyor coatings across European installations. Processors in Germany and the Netherlands face additional compliance verification steps before operational acceptance. Equipment manufacturers are responding with pre-certified component packages that streamline regulatory submission.
Buying committees at major integrators are consolidating vendor relationships around full-line automation partners rather than sourcing evisceration modules separately from cutting or packaging equipment. This pattern is displacing point-solution specialists from large capital projects. The shift is most visible in the United States, where Tyson Foods and Pilgrim's Pride procurement teams have standardized on single-source automation contracts for greenfield facilities.
Automatic Evisceration System Market Segmentation
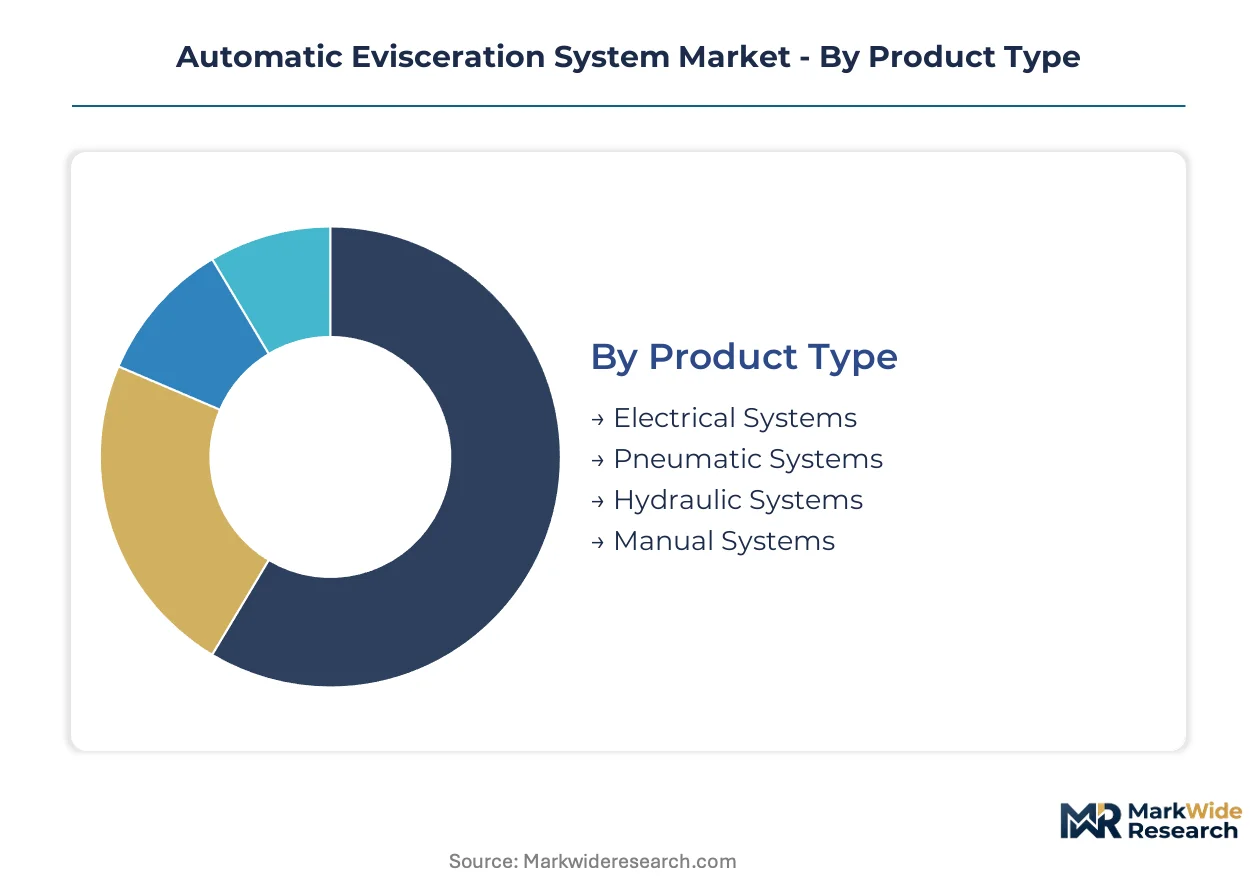
Segmentation in automatic evisceration systems reveals how regulatory requirements and operational scale reshape procurement patterns across protein processing. Each dimension carries distinct certification burdens and capital intensity thresholds that determine vendor selection criteria.
Product Type:
CE marking under the EU Machinery Directive applies differentially across power configurations, with electrical systems facing stricter electromagnetic compatibility testing than pneumatic alternatives. USDA acceptance protocols similarly vary by drive mechanism complexity.
- Electrical Systems:Servo-driven motors and programmable logic controllers deliver precision cutting parameters with energy efficiency advantages. Demand concentrates in greenfield US facilities where Tyson Foods and Pilgrim's Pride procurement teams prioritize full-line automation contracts with single-source vendors.
- Pneumatic Systems:Compressed-air actuation persists in legacy plants with substantial existing infrastructure investment. Brazilian integrators with established facilities resist full electrical conversion despite efficiency penalties, particularly in São Paulo and Paraná processing clusters.
- Hydraulic Systems:High-torque fluid power configurations retain niche deployment for heavy-bird species requiring greater cutting force.
- Manual Systems:Low-capital configurations serve small-scale processors in developing markets with limited automation budgets and relaxed regulatory timelines.
Leading the category by volume: Electrical Systems. Growing fastest: Robotic-augmented electrical configurations with integrated vision systems.
Application:
Species-specific carcass geometry drives fundamentally different equipment architectures, with poultry's standardized sizing enabling higher throughput automation than seafood's morphological variability.
- Poultry Processing:Chicken and turkey lines dominate capital deployment, with rotating spoon mechanisms and vacuum extraction modules calibrated to 13,500+ birds per hour. German and Dutch facilities under REACH chemical safety restrictions demand pre-certified lubricant packages.
- Meat Processing:Red meat applications require heavier-duty cutting tools and species-flexible architectures that Baader Group leverages across diversified protein portfolios.
- Seafood Processing:Fish evisceration demands adaptive gripping mechanisms for variable body shapes, limiting standardization and compressing throughput ceilings.
- Lab Processing:Small-batch research applications prioritize precision over speed, with FDA HACCP qualification timelines less critical than in commercial scale.
Volume concentration: Poultry Processing. Fastest expansion trajectory: Meat Processing as beef and pork integrators adopt poultry-derived automation architectures.
End User:
Facility scale determines whether procurement emphasizes throughput maximization or regulatory compliance flexibility, with export-facing operations facing the most stringent multi-jurisdiction certification requirements.
- Processing Plants:Large-scale integrators in the United States, Germany, and Brazil drive volume procurement, with Marel locking multi-year service contracts through full-line automation portfolios.
- Export Facilities:Dual USDA-EU compliance requirements extend validation timelines by 8-14 months, favoring vendors with established regulatory submission expertise.
- Commercial Farms:On-farm slaughter operations with limited capital budgets prioritize retrofit compatibility over greenfield automation.
- Research Institutions:Academic and regulatory laboratories demand configurable parameters for experimental protocols rather than production throughput.
Dominant by procurement value: Processing Plants. Expanding most quickly: Export Facilities as Brazilian and Thai integrators build EU-compliant capacity.
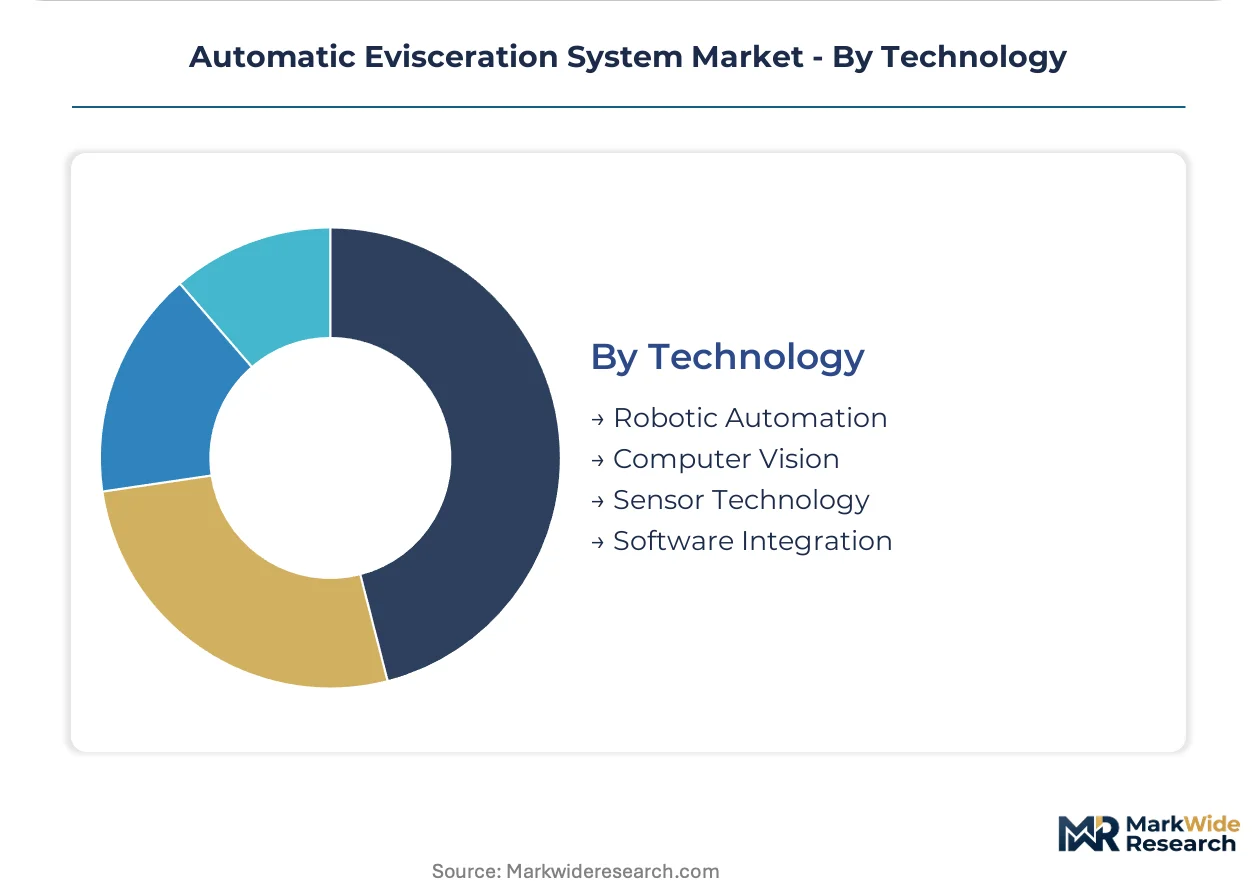
Technology:
Intellectual property concentration in machine learning algorithms and optical sensing creates vendor differentiation barriers that reshape competitive positioning in upgrade cycles.
- Computer Vision:RGB and hyperspectral imaging systems detect fecal contamination with precision exceeding manual inspection, with large US integrators deploying modules ahead of USDA inspection stations. Real-time parameter adjustment to variable bird sizes reduces yield loss and attracts capital from volume processors.
- Robotic Automation:Articulated arms with force feedback reduce manual rehang rates, though mechatronics technician scarcity constrains maintenance capacity in regional labor pools.
- Sensor Technology:Pressure, temperature, and position sensors enable predictive maintenance protocols that extend equipment uptime.
- Software Integration:Line control systems and data analytics platforms interface with plant-level MES and ERP architectures.
Highest installed base: Sensor Technology. Gaining share fastest: Computer Vision as hyperspectral modules displace conventional RGB systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentration among large-scale integrators drives capital deployment patterns across protein-producing regions. Facility upgrades cluster where labor availability constraints intersect with stringent food safety mandates.
United States
Tyson Foods and Pilgrim's Pride procurement teams standardize on single-source automation contracts for greenfield facilities. USDA Food Safety and Inspection Service zero-tolerance mandates for fecal contamination compress upgrade cycles for vision-inspected modules. Processing corridors in Arkansas, Georgia, and North Carolina attract the densest capital deployment.
Germany
REACH chemical safety restrictions on lubricants and cleaning agents force reformulation of bearing greases across European installations. The EU Machinery Directive enforces guarded access points and emergency-stop architectures that lengthen equipment validation timelines. Dutch-German border processing clusters around Oldenburg and Münster lead regional automation density.
Brazil
Volume procurement concentration among top-tier integrators drives demand for high-throughput lines exceeding 13,500 birds per hour. ANVISA compliance requirements for export-facing facilities extend qualification protocols. São Paulo and Paraná processing clusters resist full electrical conversion despite efficiency advantages, retaining substantial pneumatic infrastructure.
Netherlands
German and Dutch facilities face additional compliance verification steps before operational acceptance under REACH restrictions. Equipment manufacturers respond with pre-certified component packages that streamline regulatory submission. The Gelderland and Noord-Brabant poultry processing belts anchor European aftermarket parts density.
China
Domestic protein processors accelerate automation adoption as labor costs rise in coastal provinces. GB standards for food-contact equipment and SAMR oversight shape equipment qualification timelines. Yangtze River Delta processing hubs near Shanghai and Nantong concentrate imported European and US equipment deployment.
Automatic Evisceration System Market Competitive Landscape
European producers anchor the premium-tier equipment segment; North American fabricators hold scale-driven installation bases. The vendor base organizes around three strategic archetypes: full-line automation houses, species-flexible specialists, and point-solution module providers. Competitive moves center on multi-year service contract lock-ins and aftermarket parts channel control.
Among European full-line automation providers, Marel and Meyn Food Processing Technology B.V. exemplify the integrated-service archetype that dominates large capital projects. Baader Group occupies a position representing species-flexible architecture demand across diversified protein portfolios. These three entities anchor vendor consolidation patterns as buying committees at major integrators consolidate relationships around single-source contracts rather than sourcing evisceration modules separately from cutting or packaging equipment.
| Leading Market Players |
|---|
| Marel |
| Meyn Food Processing Technology B.V. |
| Baader Group |
| John Bean Technologies Corporation |
| CTB, Inc. |
| Prime Equipment Group, Inc. |
| GEA Group AG |
| Foodmate NL |
| Key Technology, Inc. |
| Others |
Value Network & Pricing Analysis
Buyer consolidation among Tyson Foods and Pilgrim's Pride procurement teams toward single-source automation contracts forces equipment manufacturers to absorb stainless steel commodity volatility into fixed-price multi-year agreements. This procurement concentration compresses margin buffers across the supply base while rewarding vendors with captive aftermarket service revenue streams.
Pricing Analysis
Volume procurement by large-scale integrators commands standard-tier pricing with service bundling, while smaller export facilities in Brazil and Thailand face premium tiers for dual USDA-ANVISA compliance modules. Price differentiation hinges on certification tier—CE-marked sensor-integrated configurations carry material premiums over pneumatic legacy alternatives—and geographic delivery cost differentials for European-engineered systems. Cost compression in standard electrical configurations is intensifying because Brazilian integrators resist full-line upgrades despite efficiency advantages. Small commercial farms with retrofit requirements exhibit highest price sensitivity; greenfield US facilities demonstrate lowest sensitivity due to total-cost-of-ownership procurement frameworks.
Supply Chain Analysis
Dual-sourcing requirements mandated by EU Machinery Directive compliance verification push European processors to qualify Danish and Dutch component suppliers alongside German engineering houses. Manufacturing concentration centers on Denmark, the Netherlands, and Germany for precision cutting tools and vision systems; stainless steel frames draw from Swedish and Finnish metallurgical suppliers. Supply chain risk rests on single-source vulnerability for hyperspectral imaging sensors sourced from specialized optical component manufacturers. Distribution runs through OEM-direct channels for large integrators, with aftermarket parts density anchoring regional service competitiveness in the Gelderland and Noord-Brabant belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment vendor consolidation is accelerating as buying committees eliminate point-solution specialists from large capital projects. Regulatory validation timeline friction and mechatronics technician scarcity are forcing weaker players toward exit or acquisition.
For Market Incumbents: Hedge against stainless steel input volatility through long-term metallurgical supply agreements with Nordic suppliers. Deepen vertical integration into remote diagnostics software to capture margin from unbundling aftermarket service channels. Lock multi-year service contracts with Brazilian integrators before ANVISA compliance requirements extend qualification protocols further. For New Entrants and Emerging Players: Begin with small-bird processing automation for quail and Cornish hen lines where high-speed equipment remains underpenetrated. Target research institutions and lab processing applications requiring configurable experimental parameters rather than throughput maximization. Pursue partnership-based go-to-market models with established European engineering houses to bypass validation timeline barriers. For Investors and Strategic Acquirers: The window for entry favors species-flexible architecture specialists with proven regulatory submission expertise across USDA and EU jurisdictions. Five-to-ten year viability hinges on computer vision algorithm differentiation and aftermarket parts channel control. Watch for inflection when Brazilian integrator consolidation triggers accelerated high-throughput line procurement exceeding current service capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Certification Investment | REACH-compliant lubricant packages streamline EU Machinery Directive acceptance timelines for German and Dutch facilities. |
| Vision System Algorithm Development | Hyperspectral imaging modules displace RGB systems at USDA inspection-critical control points for Tyson Foods and Pilgrim's Pride. |
| Aftermarket Service Channel Control | Remote diagnostics platforms capture margin from traditional OEM service contracts in North American processing corridors. |
| Species-Flexible Architecture Expansion | Multi-protein configurations open procurement relationships with Baader Group-style diversified processors. |
| Small-Bird Line Specialization | Quail and Cornish hen automation addresses white space untouched by standard 13,500 birds-per-hour equipment. |
Research Methodology
Independent corroboration across equipment procurement directors at large-scale integrators, maintenance directors at export-facing Brazilian facilities, and aftermarket service heads in the Benelux region underwrites the qualitative findings. Primary interviews with plant engineers, OEM technical sales leads, and regulatory compliance officers combined with secondary validation from USDA FSIS equipment qualification records, EU Machinery Directive CE marking databases, and ANVISA export facility registrations. Bottom-up installation base enumeration triangulates against top-down protein processing capacity estimates across the analysis window.
Rate-of-change decomposition separates volume effects from mix-shift contributions across power configuration, application species, facility scale tier, and technology generation segments. CAGRs derive from equipment replacement cycle analysis, regulatory mandate compliance deadlines, and labor substitution elasticity estimates. Hyperspectral imaging adoption curves and Brazilian integrator consolidation trajectories feed directly into forecast sensitivity testing.
Underlying measurement precision varies by segment; electrical systems with established installed bases carry tighter precision than emerging robotic-augmented configurations. Forecasts reflect assumptions regarding USDA zero-tolerance enforcement continuity, REACH chemical safety restriction stability, and stainless steel commodity price band persistence. Deviation in Brazilian labor availability or ANVISA-EU mutual recognition agreement timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Food Waste Disposers Market
Food Processing Equipment
Food Industry Vacuum Cooling Equipment Market
Food Processing Equipment
Food Sorting Machines Market
Food Processing Equipment
Cookie Dropper Machine Market
Food Processing Equipment
Clean in Place Market
Food Processing Equipment
Used Commercial Freezer Market
Food Processing Equipment
Countertop Convection Oven Market
Food Processing Equipment
Freeze-Drying Equipment Market
Food Processing Equipment
North America Cold Storage Market
Food Processing Equipment
Industrial Planetary Mixers Market
Food Processing Equipment
Bread Slicer Market
Food Processing Equipment
Refrigerated Vending Machines Market
Food Processing Equipment
Oceania Commercial Ice Machine Market
Food Processing Equipment
Europe Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Countertop Food Blenders Market
Food Processing Equipment
Plastic Processing Machinery Market