
 Salmon Fish Scaling Machine Market | 2026-2036
Salmon Fish Scaling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Salmon Fish Scaling Machine Market Insights
Buyer concentration among seafood processing plants is decoupling from traditional artisanal fishery networks as industrial salmon output scales in Norway and Chile. Marel leverages its integrated processing systems footprint to sustain service attach rates across Nordic installations. BAADER anchors its position through deep specialization in salmon-specific line equipment. Trifisk Manufacturing competes on compact system design for mid-volume processors seeking footprint efficiency.
A salmon fish scaling machine removes dermal denticles from salmonid species using rotating blade drums, water-assisted abrasion, or pneumatic scraper mechanisms operating at throughput rates from 20 to 200 fish per minute. The equipment serves commercial processors requiring HACCP-compliant surface preparation prior to filleting or smoking operations. Automatic scalers dominate volume deployment in industrial settings where labor cost arbitrage justifies capital intensity, while portable electric units capture fastest growth in remote aquaculture harvesting stations lacking fixed infrastructure. Pneumatic technology leads margin pools due to superior gentleness on skin-on product formats prized by premium smokehouse buyers.
EU hygiene regulation through EFSA guidelines and national food safety inspectorates mandates stainless-steel contact surfaces and clean-in-place capability, directly shaping equipment design specifications for machines sold into European processing plants. Norway's Seafood Research Fund and Chile's SUBPESCA aquaculture licensing framework both incentivize mechanization investments that reduce handling damage and improve yield recovery. Stakeholders must monitor evolving retailer certification schemes such as ASC and GlobalG.A.P. for equipment compliance requirements that increasingly dictate purchase specifications ahead of regulatory mandates.
Market Dynamics
EU hygiene mandates through EFSA guidelines are forcing stainless-steel contact surfaces and clean-in-place capability as baseline specifications, compressing equipment upgrade cycles across Nordic processing clusters.
Growth Catalysts
- Norway's Seafood Research Fund:Direct financing mechanisms reduce capital barriers for mechanization investments targeting yield recovery improvements in coastal aquaculture zones.
- Pneumatic scraper mechanisms:Premium smokehouse buyers prize skin-on product formats, driving specification upgrades from blade-drum legacy systems across filleting operations.
- Chile's SUBPESCA licensing framework:Aquaculture expansion permits mandate handling damage reduction protocols, accelerating replacement of manual scaling stations.
Market Restraints
- Stainless steel input volatility:Grade 316L price swings compress margin pools for equipment fabricators during contract bidding cycles.
- Component supplier concentration:Precision gearmotor production clusters in Germany create single-source vulnerability for mid-volume processor orders.
- Water-assisted abrasion limitations:High-volume throughput requirements exceed mechanical gentleness thresholds, constraining application in premium segments.
Strategic Opportunities
- Remote aquaculture harvesting stations:Portable electric units capture installation gaps where fixed infrastructure remains absent along Chilean fjord systems.
- ASC certification alignment:Equipment compliance pre-qualification creates specification lock-in ahead of retailer mandate timelines.
- Vision-guided blade positioning:Machine learning convergence with pneumatic systems enables real-time denticle density adaptation.
Industry Challenges
- Mechatronics technician scarcity:Servicing pneumatic-hydraulic hybrid systems requires cross-trained maintenance crews unavailable in peripheral processing regions.
- HACCP validation timelines:National food safety inspectorate approval cycles extend equipment commissioning by four to eight months.
- Legacy blade-drum integration:Retrofit compatibility with existing conveyor lines demands custom engineering for each plant configuration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Salmon Fish Scaling Machine Market |
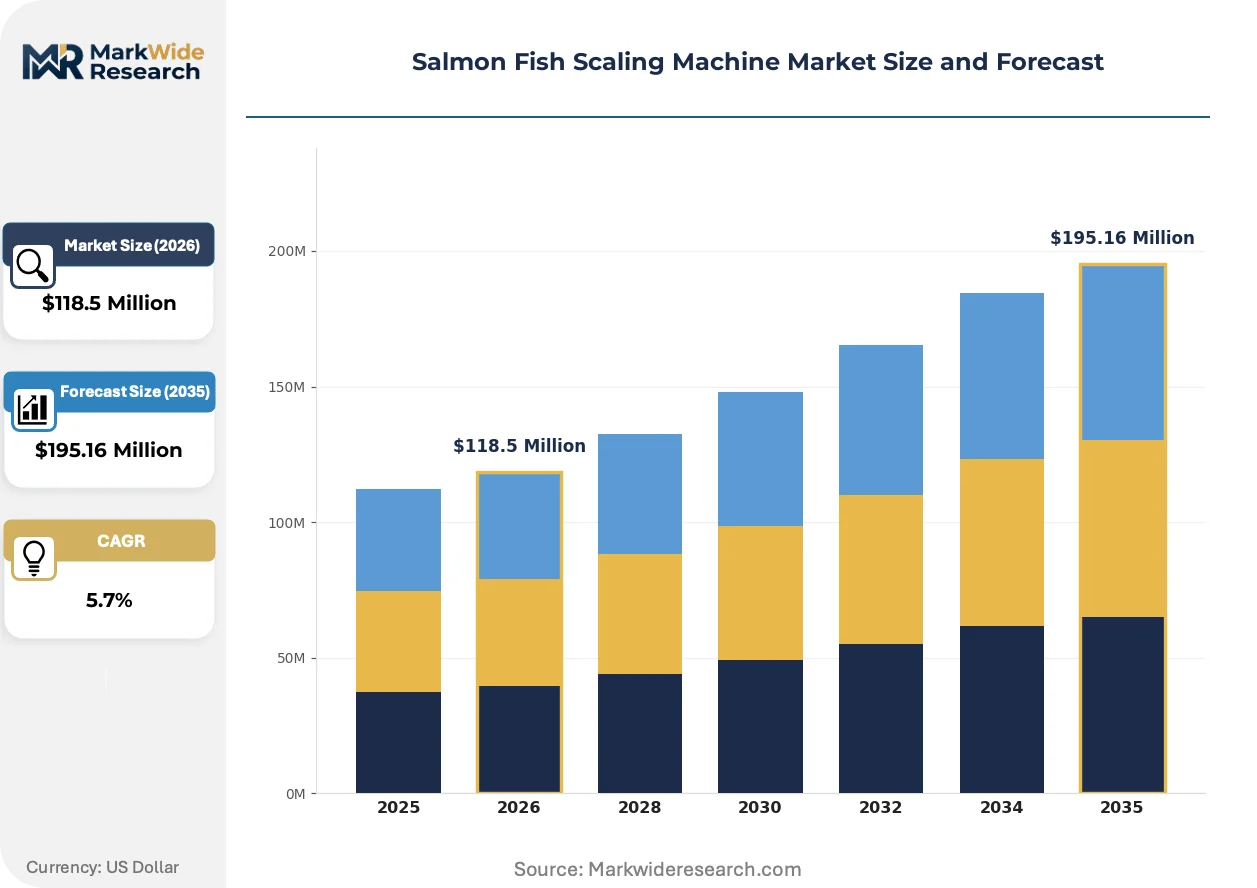
| Market Size in 2026 | $118.5 Million |
| Market Size in 2035 | $195.16 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Scalers, Automatic Scalers, Semi-Automatic Scalers, Portable Scalers End User: Commercial Fishery, Seafood Processing Plants, Retail Fish Markets, Home Users Technology: Electric, Pneumatic, Hydraulic, Mechanical Size: Small, Medium, Large, Custom Size |
| Companies Covered | Marel, BAADER, Trifisk Manufacturing, AGK, Varlet, STEEN, Kroma, RZPO, Pisces Fish Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Salmon Fish Scaling Machine Market Trends and Innovations
Automation architecture is pivoting toward modular subsystems that processors can reconfigure between species without full line replacement, reducing capital risk across volatile salmon harvest cycles.
Water-assisted abrasion systems with closed-loop filtration are expanding into industrial settings previously dominated by dry mechanical methods. Large-volume processors in Norway are retrofitting these units to meet discharge permit conditions. The technology is expanding into mid-tier facilities by compressing wastewater treatment capital requirements.
EFSA guidelines on stainless-steel surface roughness standards are tightening verification protocols for equipment sold into European processing plants. Third-party certification bodies now conduct unannounced factory audits. Nordic OEMs are responding by integrating laser profilometry documentation into standard delivery packages.
Buyer committees now specify outcome-based maintenance contracts where service payments tie to uptime guarantees rather than discrete repair events. Smokehouse cooperatives in Scotland are piloting these arrangements with equipment vendors. This restructuring shifts capital risk toward manufacturers while locking in long-term parts revenue streams.
Salmon Fish Scaling Machine Market Segmentation
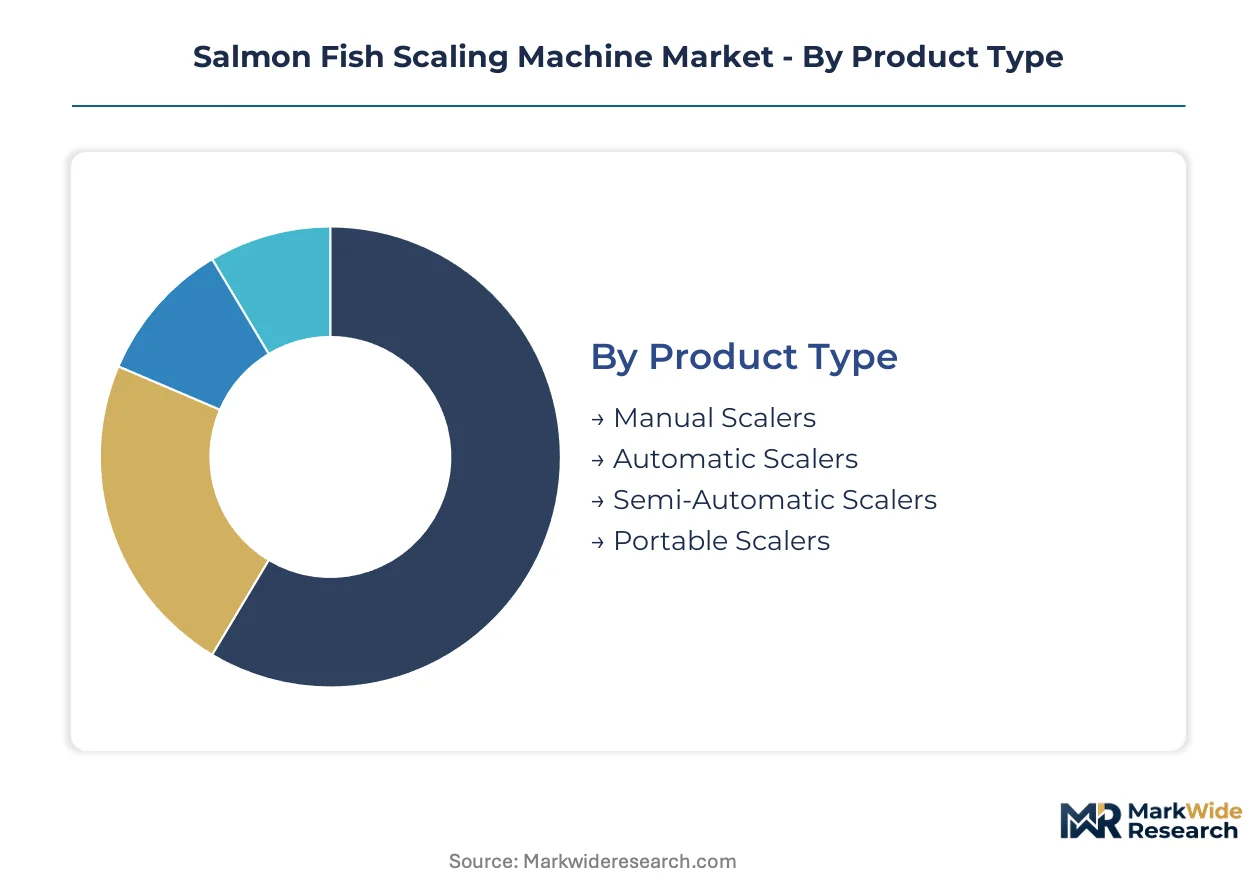
Segmentation in salmon scaling equipment reveals how capital intensity, hygiene mandates, and yield recovery priorities fragment procurement patterns across the value chain. Buyers optimize for throughput volume, skin integrity requirements, and facility infrastructure constraints when selecting machine configurations.
Product Type:
Procurement decisions pivot on labor cost arbitrage against capital deployment capacity, with volume scale dictating automation tier selection.
- Automatic Scalers:Rotating blade drums and water-assisted abrasion systems process 100-200 fish per minute with integrated clean-in-place protocols. Demand concentrates in Norwegian and Chilean seafood processing plants where EFSA hygiene mandates and SUBPESCA licensing frameworks justify capital intensity through yield recovery gains.
- Portable Scalers:Compact electric units weighing under 50 kilograms enable deployment at remote aquaculture harvesting stations lacking fixed infrastructure. Chilean fjord systems and Nordic coastal clusters drive adoption where seasonal harvest mobility outweighs throughput maximization.
- Manual Scalers:Handheld scraping tools persist in artisanal fishery networks and small-scale retail operations where capital constraints dominate procurement logic.
- Semi-Automatic Scalers:Hybrid configurations bridge throughput and flexibility for mid-volume processors upgrading from manual stations.
Automatic scalers lead on scale; portable scalers lead on momentum.
End User:
Facility certification requirements and product format specifications create divergent equipment performance thresholds across buyer categories.
- Seafood Processing Plants:Industrial installations demand HACCP-compliant stainless-steel contact surfaces with EFSA-mandated surface roughness verification. Norwegian plants prioritize pneumatic gentleness for skin-on smokehouse formats; Chilean facilities emphasize throughput density for export volume.
- Commercial Fishery:Vessel-deck and landing-site operations require corrosion-resistant enclosures and compact footprints for space-constrained environments.
- Retail Fish Markets:Low-volume intermittent use favors semi-automatic and manual configurations with minimal maintenance complexity.
- Home Users:Occasional consumption drives demand for handheld electric scalers through specialty equipment distributors.
Seafood processing plants anchor equipment revenue; commercial fishery operations show steepest expansion trajectory as fleet modernization accelerates.
Technology:
Skin integrity requirements and energy infrastructure availability determine power source selection across installation contexts.
- Pneumatic:Compressed air systems deliver superior gentleness on salmonid dermal layers, preserving skin-on product formats prized by premium smokehouse buyers. Nordic OEMs dominate specification-setting for this technology tier.
- Electric:Grid-dependent motors power the majority of industrial installations where three-phase supply reliability supports continuous operation.
- Hydraulic:High-torque applications in large-volume filleting lines utilize fluid power for blade drum actuation.
- Mechanical:Direct-drive legacy systems persist in retrofit contexts where pneumatic or electric conversion costs exceed replacement economics.
Pneumatic systems command premium positioning; electric configurations capture broadest installation base.
Size:
Facility footprint constraints and harvest volume volatility shape dimensional specifications across processor tiers.
- Large:Continuous-line systems exceeding five meters in length integrate with automated filleting and trimming stations for industrial-scale operations.
- Medium:Modular configurations occupy 2-4 meter footprints, enabling reconfiguration between species without full line replacement.
- Small:Benchtop and mobile units serve retail markets and research facilities with intermittent processing requirements.
- Custom Size:Engineered-to-order dimensions address legacy facility retrofit constraints and specialized product format demands.
Large systems dominate capital deployment value; custom sizing gains share fastest as retrofit activity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway deploys three times more automatic scaling capacity per processing plant than Chile, yet Chilean installations are expanding faster as SUBPESCA licensing accelerates mechanization mandates across fjord aquaculture zones.
Norway
Coastal processing clusters in Bergen and Ålesund drive equipment replacement cycles tied to salmon harvest volume volatility. The Norwegian Food Safety Authority enforces EFSA-compliant stainless-steel surface specifications through unannounced plant audits. Tromsø-based research facilities pilot vision-guided blade positioning systems for premium smokehouse supply chains.
Chile
Aquaculture expansion in Los Lagos and Aysén regions concentrates demand for portable electric units at remote harvesting stations. SUBPESCA licensing frameworks mandate handling damage reduction protocols that disqualify manual scaling operations. Puerto Montt fabricators retrofit legacy blade-drum lines with water-assisted abrasion systems to meet discharge permit conditions.
Scotland
Smokehouse cooperatives in the Highlands and Islands specify pneumatic gentleness for skin-on product formats bound for premium retail channels. Food Standards Scotland applies EFSA-derived hygiene verification protocols to processing equipment approvals. Aberdeen industrial zones test outcome-based maintenance contracts tying vendor payments to uptime guarantees.
Canada
British Columbia salmon processors face yield recovery pressure from Asian export contract specifications. Health Canada and CFIA coordinate HACCP validation timelines that extend equipment commissioning cycles. Vancouver Island installations prioritize modular subsystems enabling rapid reconfiguration between Pacific salmon species.
Iceland
Small-volume processors in Reykjanesbær and Akureyri adopt semi-automatic hybrid configurations bridging artisanal and industrial throughput tiers. The Icelandic Food and Veterinary Authority enforces EU-equivalent hygiene standards for equipment contact surfaces. Westfjords landing sites deploy compact electric scalers during seasonal Arctic char harvest windows.
Salmon Fish Scaling Machine Market Competitive Landscape
Nordic producers anchor the premium tier through integrated processing system footprints; Central European specialists hold mid-market positioning through component supply concentration. The vendor base separates into three strategic archetypes: full-line integrators commanding service attach rates, salmon-specific equipment specialists, and compact system fabricators targeting footprint-constrained facilities. Competitive moves concentrate on backward integration into precision gearmotor supply and geographic expansion through distributor partnerships in emerging aquaculture zones.
Within the full-line integrator tier, Marel and BAADER occupy positions defined by installed base density across Norwegian processing corridors. Trifisk Manufacturing exemplifies the compact system archetype, serving mid-volume processors seeking dimensional efficiency. These three entities represent divergent capital deployment strategies: integrated system lock-in versus specialized line equipment versus modular footprint optimization.
| Leading Market Players |
|---|
| Marel |
| BAADER |
| Trifisk Manufacturing |
| AGK |
| Varlet |
| STEEN |
| Kroma |
| RZPO |
| Pisces Fish Machinery |
| Others |
Pricing and Supply Chain Analysis
EFSA clean-in-place mandates gate qualified supply for premium-tier pricing access, as stainless-steel surface verification and third-party audit documentation separate certified OEMs from uncertified fabricators. Buyers in Norwegian and Chilean processing corridors pay structural premia for equipment packages bundling laser profilometry documentation and outcome-based maintenance contracts.
Pricing Analysis
Capacity additions in Chile are reshaping price floors for mid-volume automatic scalers, compressing regional premia that Norwegian OEMs historically commanded. Three-tier pricing structure across pneumatic premium, electric standard, and mechanical economy levels stratifies by skin-integrity performance and certification bundling. Pricing pressure stems from grade 316L stainless steel input volatility, which compresses fabricator margins during contract bidding cycles. Mid-volume processors in Nordic coastal clusters exhibit highest price sensitivity due to harvest volume volatility, while premium smokehouse cooperatives in Scotland show lowest sensitivity given yield recovery priorities.
Supply Chain Analysis
EFSA-compliant surface roughness certification gates supplier qualification, limiting precision gearmotor sourcing to German and Danish production clusters with verified cleanroom capabilities. Equipment fabrication draws from grade 316L stainless steel mills in Sweden and Finland, precision pneumatics from Germany, and control systems from Denmark. Single-source vulnerability concentrates in precision gearmotor supply, where mid-volume processor orders face allocation risk during capacity constraints. Distribution runs through OEM-direct service contracts for large installations and regional distributor networks for portable electric units in remote aquaculture zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Salmon scaling equipment functions as a regulatory compounder, where EFSA hygiene mandates and SUBPESCA licensing frameworks continuously upgrade equipment replacement cycles ahead of natural depreciation schedules.
For Market Incumbents: To counter portable electric unit entrants in Chilean fjord systems, Marel and BAADER should anchor service attach rates through outcome-based maintenance contracts while deepening backward integration into precision gearmotor supply. Certification pre-qualification for ASC and GlobalG.A.P. retailer schemes creates specification lock-in that delays competitive displacement. For New Entrants and Emerging Players: SUBPESCA licensing in Chile opens a window for compact system specialists targeting remote harvesting stations with portable electric configurations underserved by full-line integrators. White-space concentrates in mid-volume processors seeking modular subsystems for species reconfiguration, and in Icelandic semi-automatic hybrid demand bridging artisanal and industrial tiers. Go-to-market should route through Puerto Montt fabricator partnerships for retrofit credibility. For Investors and Strategic Acquirers: Roll-up economics work for pneumatic technology specialists because skin-on product format premia sustain margin pools resistant to electric commoditization. Long-term viability hinges on ASC certification alignment as retailer mandates accelerate. Acquisition targets should show installed base density across Norwegian processing corridors and documented clean-in-place validation. The signal to watch is unannounced EFSA factory audit failure rates as a leading indicator of vendor consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Gearmotors | German gearmotor supply concentration creates single-source vulnerability for mid-volume orders. |
| Outcome-Based Maintenance Contracts | Smokehouse cooperatives in Scotland pilot uptime-guaranteed payment structures shifting capital risk. |
| ASC Certification Pre-Qualification | Equipment compliance ahead of retailer mandate timelines creates specification lock-in. |
| Vision-Guided Blade Positioning Development | Tromsø research facilities pilot machine learning convergence for premium smokehouse supply chains. |
| Modular Subsystem Architecture | Processors reconfigure between species without full line replacement, reducing capital risk. |
Research Methodology
Coverage spans Nordic coastal clusters, Chilean fjord systems, Scottish smokehouse cooperatives, and Canadian Pacific processing corridors, with primary inputs from each. The analysis combines structured interviews with seafood processing plant maintenance directors, OEM aftermarket service heads, SUBPESCA licensing officials, and smokehouse cooperative procurement leads with secondary validation from EFSA guidance documents, Norwegian Food Safety Authority audit protocols, Chilean aquaculture expansion permit databases, and equipment customs records. Bottom-up installation counts triangulate against top-down aquaculture harvest volume projections.
Rate-of-change decomposition separates volume growth from mix-shift and pricing evolution across the projection horizon. Segmentation dimensions model equipment automation tier, technology type, end-user facility scale, and regional regulatory cluster intensity. CAGRs derive from equipment replacement cycle analysis against aquaculture licensing mandate timelines, with salmon harvest volume volatility and stainless-steel input cost indices as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EFSA guideline revisions or grade 316L price spike conditions. Forecasts reflect documented assumptions on mechanization subsidy continuity and retailer certification scheme evolution. A model refresh is warranted upon material change in SUBPESCA licensing enforcement intensity or ASC mandate adoption timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Sheet Metal Processing Equipment Market
Food Processing Equipment
Shawarma Grill Machine Market
Food Processing Equipment
Plastic Processing Machinery Market
Food Processing Equipment
Asia-Pacific Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Food Irradiation Equipment Market
Food Processing Equipment
Hand Blender Market
Food Processing Equipment
Brewing Thermometer Market
Food Processing Equipment
Food Waste Disposers Market
Food Processing Equipment
Aseptic Processing Market
Food Processing Equipment
Blast Chillers Market
Food Processing Equipment
Gas Convection Oven Market
Food Processing Equipment
Wine Processing Equipment Market
Food Processing Equipment
North America Ginger Processing Market
Food Processing Equipment
Automatic Grilling Machine Market
Food Processing Equipment
Industrial Planetary Mixers Market
Food Processing Equipment
Walk-In Refrigerator Market