
 Military Tactical Vest Market | 2026-2036
Military Tactical Vest Market Size, Share, and Industry Trends Forecast 2026-2036
Military Tactical Vest Market Foresight
Special operations procurement is shifting toward lightweight plate carriers with MOLLE compatibility as conventional military orders plateau. Point Blank Enterprises sustains dominance in U.S. military contracts through vertically integrated armor manufacturing. Safariland differentiates via law enforcement channel control across North American agencies. 5.11 Tactical competes in the commercial and security contractor segment with rapid product refresh cycles.
A military tactical vest is a load-carrying garment engineered from aramid fibers such as Kevlar or woven nylon, designed to distribute equipment weight across the torso while accommodating hard armor plates rated for specific ballistic threats. Its primary purpose centers on enhancing soldier survivability and operational endurance during dismounted combat or tactical entry operations. Plate carriers command the fastest-growing product category as militaries prioritize mobility over full-coverage ballistic protection. Kevlar-reinforced panels retain the largest material share despite weight penalties, while Nomex blends gain share in aviation and vehicle crew applications where flame resistance governs selection.
The U.S. Department of Defense mandates NIJ Standard 0101.06 compliance for all acquired ballistic packages, while the EU Green Deal's fluorocarbon restrictions are forcing textile suppliers to reformulate water-resistant coatings. Procurement officers must weigh modularity against total system weight as distributed power and communications gear expand vest payload requirements.
Market Dynamics
Special operations units across NATO member states are driving procurement toward lightweight plate carriers with MOLLE compatibility, compressing demand for full-coverage ballistic vests as soldier mobility takes precedence over maximum protection.
Growth Catalysts
- NIJ Standard 0101.06:U.S. Department of Defense mandates for ballistic package compliance are forcing vest manufacturers to upgrade testing protocols and material specifications across military contracts.
- Aramid fiber innovation:Next-generation Kevlar composites with reduced weight penalties are enabling longer mission endurance without sacrificing threat-level ratings.
- Soldier modernization programs:Germany, Australia, and the United States are expanding defense budgets specifically for dismounted combat equipment upgrades.
Market Restraints
- Fluorocarbon coating restrictions:EU Green Deal regulations are forcing textile suppliers to reformulate water-resistant treatments, extending R&D timelines and certification costs.
- Hard armor plate weight:Ceramic and polyethylene plates rated for rifle threats add 4-8 pounds to system weight, limiting mobility gains from carrier lightweighting.
- Specialized manufacturing concentration:Ballistic weaving and armor plate production cluster in limited supplier bases, creating vulnerability to single-source disruption.
Strategic Opportunities
- Aviation and vehicle crew applications:Nomex-blend vests with flame-resistant properties are gaining specification in rotary-wing and armored vehicle programs where burn protection governs selection.
- Distributed power integration:Vest architectures accommodating batteries, communications gear, and wearable electronics represent unpenetrated configuration space beyond pure ballistic function.
- Security contractor segment:Private military and close protection details are creating secondary demand channels with faster refresh cycles and less stringent procurement bureaucracy.
Industry Challenges
- Ballistic testing bottlenecks:NIJ-certified laboratory capacity constraints are extending product validation timelines for new vest configurations.
- Legacy system interoperability:Modular plate carriers must interface with existing load-bearing equipment, creating integration complexity during platform transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Tactical Vest Market |
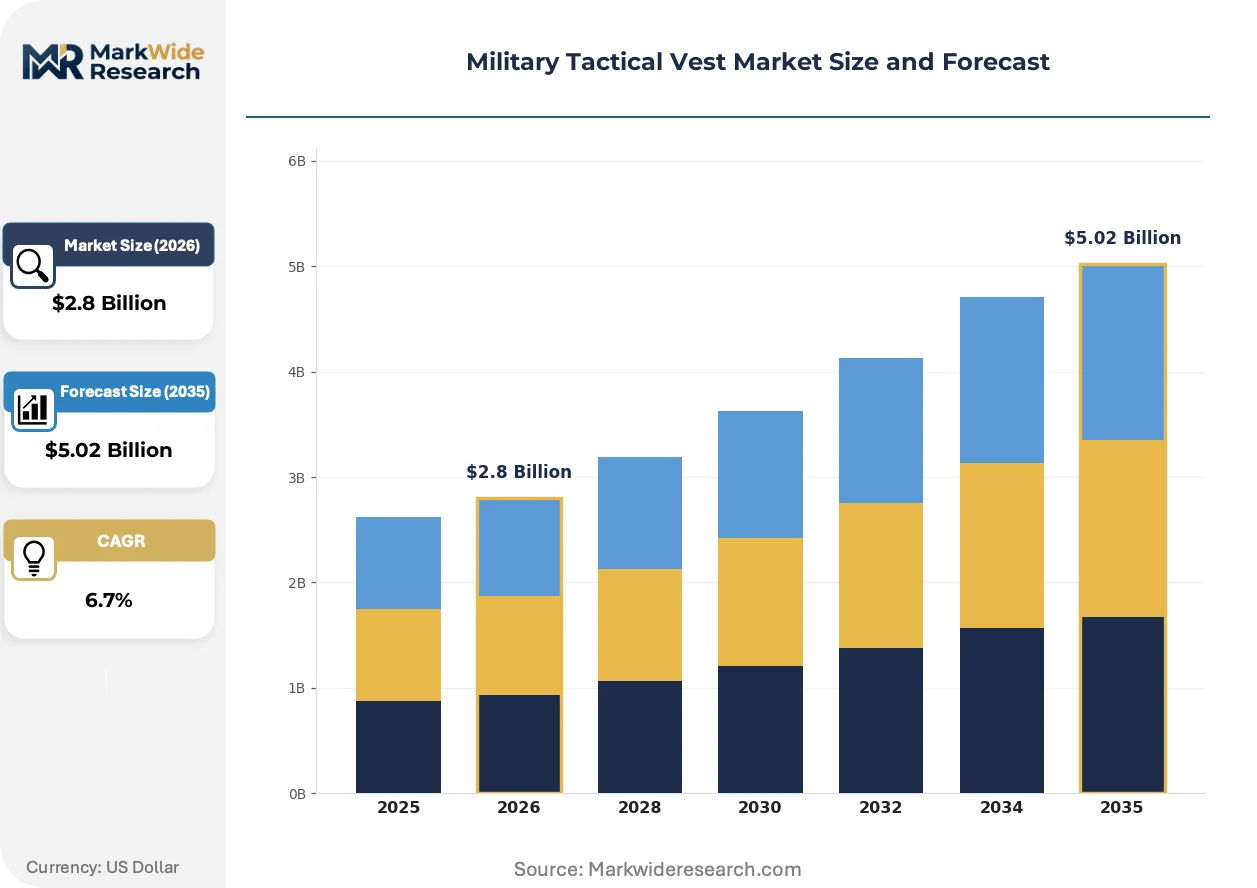
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ballistic Vest, Load Bearing Vest, Modular Vest, Plate Carrier Material: Nomex, Kevlar, Nylon, Polyester End User: Military Personnel, Law Enforcement, Security Contractors, Tactical Teams Feature: Water-Resistant, Lightweight, Modular Design, MOLLE Compatibility |
| Companies Covered | Condor Outdoor Products, Mil-Tec, 5.11 Tactical, Point Blank Enterprises, Safariland, Tactical Assault Gear, Helikon-Tex, Propper International, Blackhawk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Tactical Vest Market Shifts & Advancements
Active research into non-aramid ballistic materials and smart textile integration is reshaping how tactical vests balance protection, weight, and situational awareness capabilities.
Polyethylene-based hard armor plates are modularizing vest architecture by enabling rifle-rated protection at weights previously achievable only with soft armor. Special operations procurement teams are specifying these plates for direct action missions where speed and agility outweigh maximum coverage. This material shift is compressing the addressable market for traditional ceramic plate suppliers.
REACH regulations in Europe are restricting per- and polyfluoroalkyl substances in textile coatings, forcing manufacturers to validate alternative water-repellent chemistries. The industrial consequence extends beyond compliance costs to performance verification, as new formulations must demonstrate equivalent durability in field conditions. Aviation and maritime vest programs are most affected, with suppliers accelerating third-party testing to maintain certification continuity.
Unit-level procurement authority is fragmenting traditional centralized acquisition patterns as special operations commands gain budget autonomy for mission-specific equipment. Defense contractors accustomed to large-scale military tenders are establishing direct sales channels and rapid customization services to capture this demand. The United States and United Kingdom display the most pronounced shift, with squadron-level purchasing now common for plate carrier accessories and load-bearing components.
Military Tactical Vest Market Segmentation
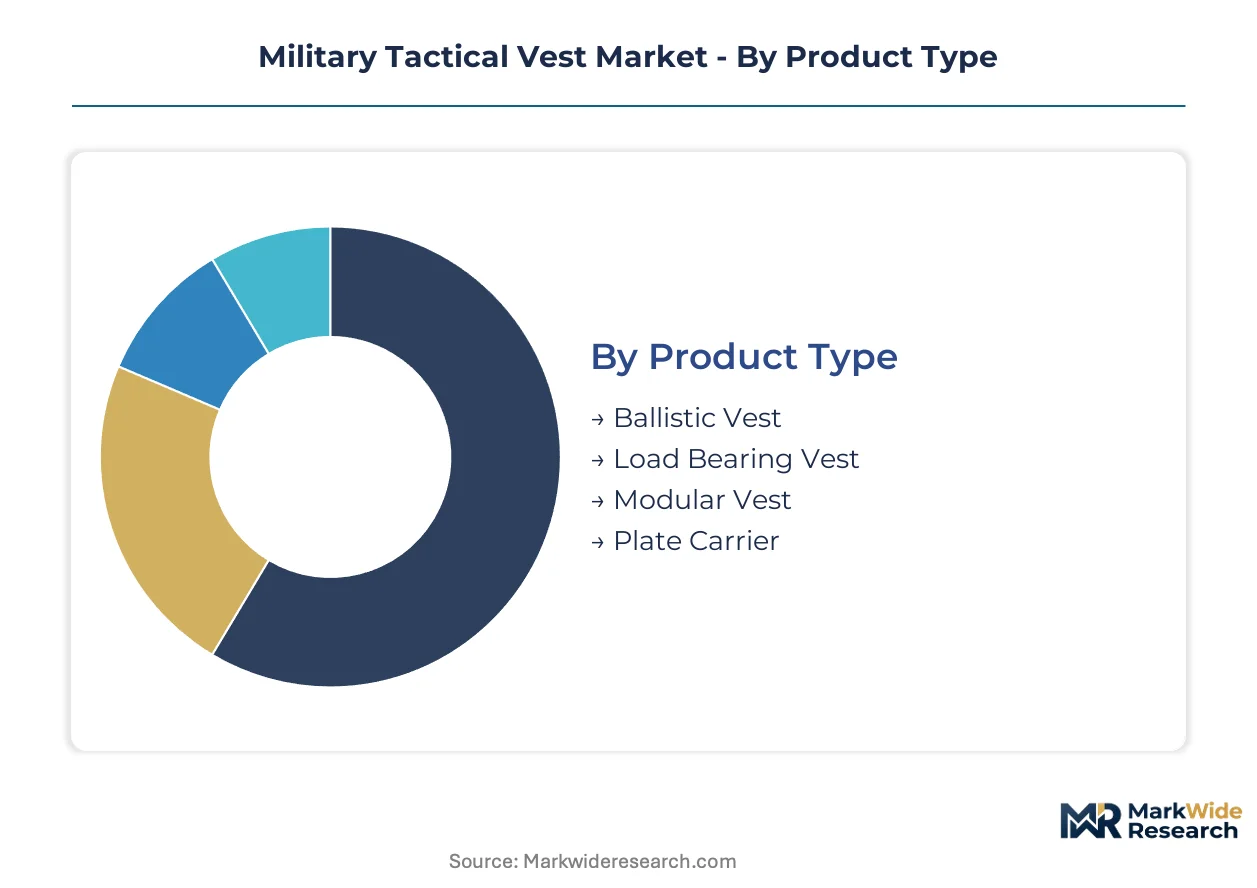
Tactical vest procurement follows distinct upgrade cycles across product categories, with military modernization programs driving systematic replacement of legacy systems. Material selection and feature prioritization vary sharply between institutional buyers and commercial security channels, creating parallel demand structures with different specification requirements.
Product Type:
Replacement cycles accelerate as NATO special operations units retire full-coverage ballistic systems in favor of mobility-optimized configurations.
- Ballistic Vest:Soft armor systems constructed from layered aramid fibers providing NIJ Level IIIA protection against handgun and fragmentation threats. Demand concentrates in domestic law enforcement agencies across the United States and Germany where patrol officer safety standards mandate comprehensive torso coverage.
- Plate Carrier:Minimalist platforms designed to accept hard armor plates while eliminating excess material weight. Special operations procurement teams in Australia and the United Kingdom specify these systems for direct action missions where speed and agility outweigh maximum protection.
- Load Bearing Vest:Equipment distribution systems without integrated ballistic protection, engineered for ammunition and utility carriage. Military support personnel and vehicle crews in conventional army units utilize these configurations.
- Modular Vest:Reconfigurable architectures enabling rapid attachment of pouches, panels, and protective elements. Security contractor segments in North America favor these systems for mission-adaptable flexibility.
Volume placements concentrate in Ballistic Vest configurations for institutional law enforcement; the faster expansion belongs to Plate Carrier systems driven by special operations mobility requirements.
Material:
Cost tiers separate premium aramid solutions from commodity synthetics, with specification authority residing in procurement officers who balance threat ratings against per-unit expenditure limits.
- Kevlar:DuPont's para-aramid fiber delivering exceptional strength-to-weight ratios for soft armor applications. Military contracts in the United States and Germany specify Kevlar-reinforced panels despite weight penalties, prioritizing proven ballistic performance over emerging alternatives.
- Nomex:Meta-aramid fiber engineered for flame resistance in aviation and armored vehicle crew applications. Rotary-wing programs in Australia and the United Kingdom mandate Nomex blends where burn protection governs selection criteria.
- Nylon:Woven synthetic base material for carrier shells and load-bearing components. Commercial security channels utilize nylon-dominant constructions for cost-controlled procurement.
- Polyester:Lower-cost synthetic alternative for training equipment and non-ballistic utility vests. Secondary markets in private security segments absorb polyester-based systems.
Institutional procurement favors Kevlar for threat-rated applications; Nomex blends gain share fastest in aviation and mechanized crew programs where thermal protection requirements intensify.
End User:
Customer type determines specification stringency, with military channels enforcing NIJ compliance while commercial buyers prioritize rapid availability and customization services.
- Military Personnel:National defense forces requiring NIJ Standard 0101.06 certified systems with documented ballistic performance. Procurement concentrates in the United States, Germany, and Australia as defense budgets prioritize soldier modernization programs.
- Law Enforcement:Domestic police agencies mandating comprehensive soft armor coverage for patrol officers. Municipal and state-level acquisition in the United States drives sustained replacement cycles for degraded vest panels.
- Security Contractors:Private military and close protection details operating with faster refresh cycles and reduced procurement bureaucracy. Direct sales channels serve this segment with rapid customization capabilities.
- Tactical Teams:Specialized law enforcement units including SWAT and counter-terrorism response elements. These operators specify plate carrier configurations optimized for dynamic entry operations.
Contract volume clusters with Military Personnel accounts; Security Contractors expand most quickly as geopolitical instability generates demand for protective services.
Feature:
Margin structures favor technically differentiated configurations, with MOLLE compatibility and modular architectures commanding pricing premiums over baseline utility designs.
- MOLLE Compatibility:Modular Lightweight Load-carrying Equipment interface standard enabling pouch attachment at standardized intervals. Special operations procurement across NATO member states mandates MOLLE integration as a baseline requirement.
- Modular Design:Reconfigurable architectures permitting rapid adaptation between mission profiles. United States and United Kingdom special operations commands specify these systems for squadron-level purchasing autonomy.
- Lightweight:Reduced system mass achieved through material optimization and component elimination. Mobility-focused users in direct action roles prioritize weight reduction.
- Water-Resistant:Protective treatments maintaining performance in maritime and adverse weather conditions. EU Green Deal fluorocarbon restrictions are forcing textile suppliers to reformulate these coatings.
Specification frequency runs highest for MOLLE Compatibility; Modular Design features climb fastest as unit-level procurement authority fragments traditional centralized acquisition patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foreign Trade Zones in the United States and bonded logistics parks in Germany concentrate ballistic textile finishing and armor plate integration. Special economic zones in Australia and free industrial zones in the United Kingdom host final assembly operations for NATO procurement.
United States
Defense Logistics Agency contracts drive sustained plate carrier procurement for Army and Marine Corps modernization. NIJ Standard 0101.06 mandates govern all ballistic package acquisitions through the Department of Defense. Manufacturing clusters in Florida and Tennessee host vertically integrated armor weaving and cut-and-sew operations serving military contracts.
Germany
Bundeswehr soldier modernization programs expand orders for modular vest systems compatible with existing load-bearing equipment. EU Green Deal fluorocarbon restrictions force textile suppliers in Bavaria to reformulate water-resistant coatings. Industrial concentration in North Rhine-Westphalia supplies Kevlar-reinforced panels for domestic and export military contracts.
Australia
Australian Defence Force special operations commands prioritize lightweight plate carriers for regional expeditionary missions. TGA-equivalent defense materiel certification requirements add validation layers for imported components. Manufacturing activity clusters in Victoria around ballistic testing facilities and textile research institutes.
United Kingdom
Ministry of Defence unit-level procurement autonomy fragments traditional centralized acquisition for special operations equipment. REACH regulations restrict per- and polyfluoroalkyl substances in vest coatings used by Royal Navy maritime programs. Industrial capacity concentrates in the Midlands around legacy defense textile suppliers.
Canada
Canadian Armed Forces NATO interoperability requirements drive specification alignment with U.S. plate carrier standards. Health Canada and PMRA oversight extends to chemical treatments in military textile imports. Quebec-based suppliers specialize in Nomex-blend aviation vest configurations for rotary-wing crews.
Military Tactical Vest Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with institutional military channels favoring established defense suppliers while commercial security segments absorb faster-refresh specialty brands. The vendor base clusters around three strategic archetypes: vertically integrated armor manufacturers controlling raw material through finished goods, channel-dominant law enforcement suppliers with agency certification relationships, and rapid-cycle commercial brands serving security contractors. Competitive positioning hardens through backward integration into ballistic weaving capacity and geographic expansion into NATO ally procurement offices.
Among U.S.-based defense contractors, Point Blank Enterprises and Safariland occupy positions within the institutional procurement tier, while 5.11 Tactical exemplifies the commercial-channel archetype with security contractor focus. These three entities represent contrasting strategic postures: captive manufacturing control, law enforcement agency relationship density, and product refresh velocity respectively.
| Leading Market Players |
|---|
| Condor Outdoor Products |
| Mil-Tec |
| 5.11 Tactical |
| Point Blank Enterprises |
| Safariland |
| Tactical Assault Gear |
| Helikon-Tex |
| Propper International |
| Blackhawk |
| Others |
Supply & Pricing Matrix
Polyethylene plate manufacturing scale-up in Tennessee and Bavaria is compressing per-unit armor costs while concentrating supply leverage among processors with captive polymer sourcing. This dual transformation rewards backward-integrated suppliers with testing protocol mastery and penalizes merchant-market buyers facing extended NIJ certification queues.
Pricing Analysis
Expedited delivery premiums for NIJ-certified plate carriers run 15-25 percent above standard lead-time contracts, while spot inventory of legacy Kevlar panels trades at distressed clearing rates. Three-tier pricing structure across premium, standard, and economy levels separates special operations specification-grade systems from municipal law enforcement procurement and commercial security training equipment. Cost compression in standard-tier soft armor is intensifying because REACH-compliant coating reformulations extended R&D amortization periods. Security contractors exhibit highest price elasticity, while U.S. Defense Logistics Agency contracts demonstrate lowest sensitivity due to mission-critical specification rigidity.
Supply Chain Analysis
Skilled ballistic-weaving technicians in South Carolina and North Rhine-Westphalia command wage premiums that constrain capacity expansion at Tier 2 cut-and-sew operations. Aramid fiber supply draws from DuPont facilities in Virginia and Teijin plants in Japan, while ceramic plate feedstocks source from alumina processors in Germany and silicon carbide refiners in China. Single-source vulnerability concentrates in NIJ-certified laboratory capacity, where backlog extends validation timelines. Distribution runs through defense logistics primes holding DLA contracts, with secondary channels serving commercial security via direct manufacturer portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Military Tactical Vest Market functions as a cost-of-compliance story where NIJ Standard 0101.06 certification creates a barrier-to-entry moat that protects incumbent positions against commodity competition.
For Market Incumbents: Acquire NIJ-certified testing laboratory capacity to compress product validation cycles and deny queue position to emerging competitors. Consolidate backward integration into aramid fiber weaving to secure supply continuity against Teijin and DuPont allocation decisions. Threat displacement from polyethylene plate suppliers demands captive polymer compounding expertise or exclusive offtake arrangements with Honeywell and DSM. For New Entrants and Emerging Players: Direct-to-contractor digital channels bypass Defense Logistics Agency procurement bureaucracy and capture security contractor demand with 90-day refresh cycles. White-space concentration in Nomex-blend aviation vest configurations for Canadian and Australian rotary-wing programs offers specification entry points absent entrenched incumbent relationships. Go-to-market leverage rests on rapid customization portals enabling squadron-level pouch configuration. For Investors and Strategic Acquirers: Exit pathways concentrate in defense prime acquisition of modular plate carrier specialists with established NATO special operations relationships. Long-term viability favors suppliers with dual-use textile capabilities spanning military ballistic and industrial flame-resistant applications. Signal to watch is Bundeswehr soldier modernization program award timing, which will indicate procurement velocity for European NATO alignment.| Strategic Initiative | Industry Significance |
|---|---|
| NIJ Laboratory Capacity Acquisition | Certification queue control locks out competitors from DLA contract eligibility windows. |
| Polyethylene Plate Manufacturing Scale-Up | Honeywell Spectra fiber integration enables rifle-rated protection at soft armor weights. |
| REACH-Compliant Coating Reformulation | ECHA-validated water-repellent chemistry preserves EU market access against fluorocarbon bans. |
| Security Contractor Direct Channel Launch | Bypassing DLA procurement cycles captures faster-refresh demand from private military details. |
| Nomex-Blend Aviation Vest Development | Rotary-wing crew specifications in Canada and Australia open non-ballistic protective equipment segments. |
Research Methodology
Multi-period observation of NATO special operations procurement awards, NIJ certification timelines, and defense budget appropriation patterns anchored the trend analysis, supplemented by interviews with program executive officers at U.S. Army PEO Soldier, Bundeswehr equipment procurement leads, and Australian Defence Force materiel directors. Secondary validation drew from U.S. Department of Defense contract announcements, EU Green Deal regulatory filings, and TGA defense materiel certification records. Bottom-up demand modeling across plate carrier, ballistic vest, and load-bearing equipment categories triangulated against top-down defense expenditure allocation analysis.
Segment-weighting applied product-type, material composition, end-user classification, and feature specification dimensions across the modeling period. CAGRs derived from unit shipment trajectories by NATO member state, adjusted for modernization program phase-in schedules and legacy system retirement curves. Forecast inputs incorporated polyethylene plate adoption rates and REACH compliance transition costs for EU-market suppliers.
The model holds under sustained defense budget prioritization for soldier modernization; deviation in congressional appropriation delays or Bundeswehr program cancellations would shift volume trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Cargo Security Seals Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Emergency Stop Switches Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Seat Belt System Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Fall Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Surface Protection Services Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Premium High Security Doors Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Anti-Vibration Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Safety Motion Control Market
Safety Equipment and Personal Protective Equipment (PPE)
Supplementary Protectors Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Radiation Protection Apron Market
Safety Equipment and Personal Protective Equipment (PPE)
FFP2 Grade Medical Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Gloves Market