
 FFP2 Grade Medical Protective Mask Market | 2026-2036
FFP2 Grade Medical Protective Mask Market Size, Share, and Industry Trends Forecast 2026-2036
FFP2 Grade Medical Protective Mask Market Insights
Hospital procurement channels across Europe is narrowing as group purchasing organizations consolidate supplier lists. 3M Company leverages its vertical integration in meltblown media to sustain price stability during raw material volatility. Shanghai Dasheng Health Products Manufacture Co. Ltd. anchors volume production for European private-label distributors. Moldex-Metric differentiates through German-engineered valve technology that competes on comfort metrics in extended-wear clinical environments.
FFP2 grade medical protective masks are tight-fitting respirators filtering at least 94% of airborne particles down to 0.3 microns, constructed from multi-layer polypropylene with electrostatically charged meltblown filtration media and designed to protect healthcare workers from infectious aerosols in clinical settings. The disposable product type dominates hospital procurement due to infection control protocols, while the reusable segment grows fastest among industrial safety buyers seeking total cost reduction. CE Marked certification commands premium positioning in European tenders, whereas NIOSH Approved variants occupy parallel demand channels in North American healthcare systems.
EU PPE Regulation 2016/425 and EN 149:2001+A1:2009 standards govern market access, with ECHA oversight of chemical compliance in mask components and REACH restrictions affecting additive formulations in polypropylene feedstock. FDA emergency use authorizations and NIOSH 42 CFR 84 classifications shape parallel demand in the United States, where hospital systems maintain dual-source strategies across regulatory jurisdictions. Stakeholders must monitor evolving harmonization between EU and US test protocols as divergent standards fragment supplier qualification costs.
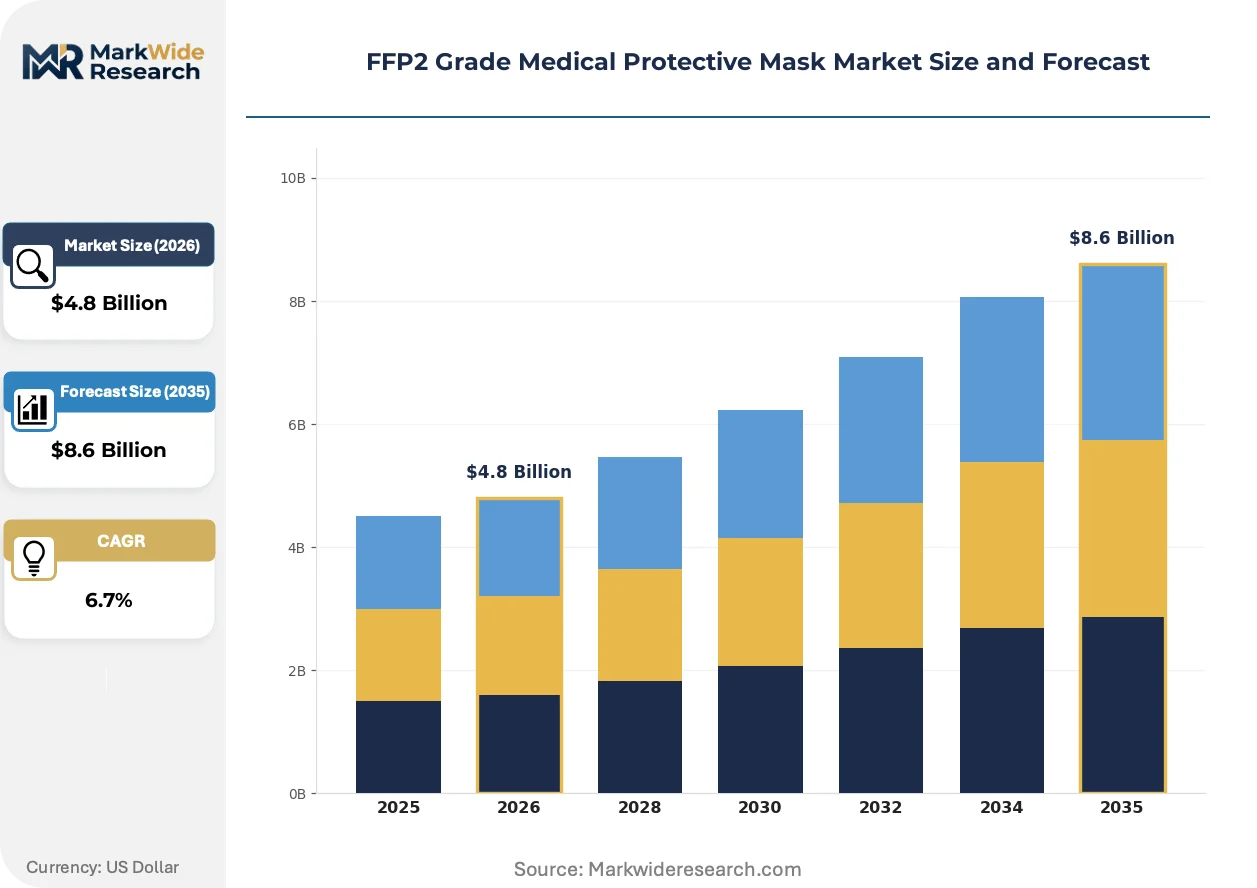
Market Dynamics
Hospital procurement consolidation across Western Europe is compressing supplier margins while simultaneously elevating certification requirements under the EU PPE Regulation framework, forcing manufacturers to absorb compliance costs or exit tender pools entirely.
Growth Catalysts
- EU PPE Regulation 2016/425:Mandatory CE marking for all respiratory protective equipment entering European healthcare channels creates a compliance moat that filters out uncertified competitors and stabilizes pricing for qualified suppliers.
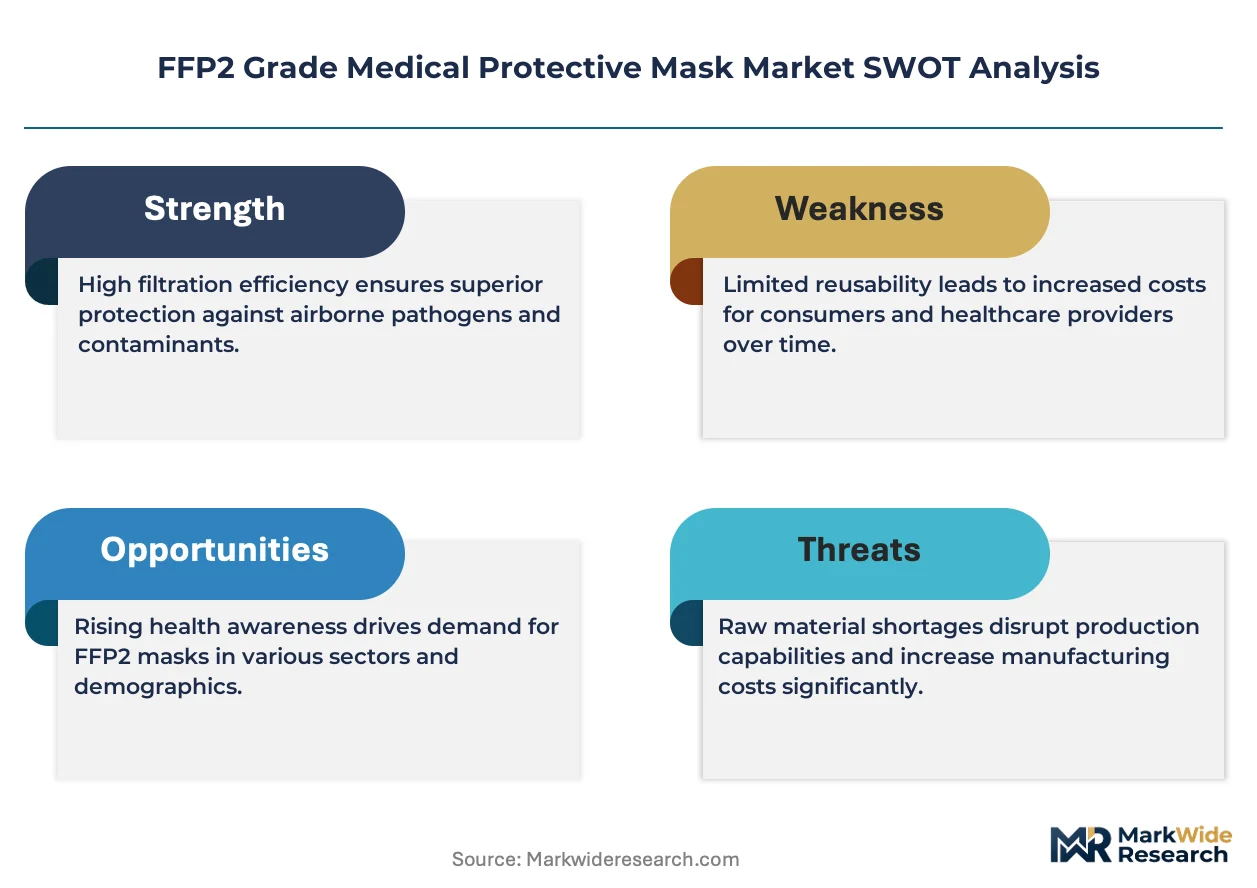
- Meltblown filtration advances:Electrostatic charging improvements in polypropylene media now achieve 94% particle retention at lower breathing resistance, extending comfortable wear time for clinical staff in high-intensity settings.
- German hospital networks:Group purchasing organizations representing university hospitals in Bavaria and North Rhine-Westphalia have standardized FFP2 specifications across procurement frameworks, generating predictable volume commitments.
Market Restraints
- Polypropylene feedstock volatility:Propylene monomer prices fluctuate with naphtha cracking margins, compressing gross margins for non-integrated converters during petrochemical upcycles.
- East Asian supply concentration:Over 70% of meltblown capacity sits within 200 kilometers of Shanghai, exposing European distributors to shipping rate spikes and customs clearance delays.
- Reusable elastomeric alternatives:Industrial safety buyers in automotive manufacturing are piloting half-mask respirators with P100 cartridges, threatening disposable FFP2 volumes in non-clinical segments.
Strategic Opportunities
- Eastern European hospital modernization:Polish and Romanian health ministries are allocating cohesion funds to upgrade infectious disease wards, creating first-mover advantages for certified suppliers establishing local distribution.
- EU Green Deal procurement criteria:Emerging tender specifications reward masks with recycled polypropylene content and biodegradable packaging, opening premium positioning for sustainability-invested manufacturers.
- Direct-to-clinic e-procurement platforms:Specialized medical supply marketplaces in France and Italy are disintermediating traditional distributor markups, enabling margin capture by manufacturers with logistics capabilities.
Industry Challenges
- Notified Body bottleneck:CE certification queues at EU PPE Regulation-designated entities stretch 8-14 months, delaying market entry for new product variants and trapping R&D investment in regulatory limbo.
- Electrostatic decay management:Maintaining filtration efficiency across 3-year shelf lives requires humidity-controlled warehousing and specialized polymer stabilizers, adding complexity to inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FFP2 Grade Medical Protective Mask Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Surgical, Consumer Application: Personal Use, Healthcare Facilities, Industrial Safety, Emergency Services Material: Polypropylene, PVC, Fabric, Meltblown Certification: CE Marked, NIOSH Approved, ISO Compliant, Others |
| Companies Covered | 3M Company, Honeywell International Inc., Kimberly-Clark Corporation, Ansell Limited, CM Mask, DACH Schutzbekleidung GmbH & Co. KG, Shanghai Dasheng Health Products Manufacture Co. Ltd., Cardinal Health, Inc., Moldex-Metric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FFP2 Grade Medical Protective Mask Market Trends and Innovations
Respiratory protection is undergoing material science transformation as electrostatic filtration performance converges with sustainability mandates, while procurement digitization reconfigures traditional channel economics.
Biodegradable meltblown media derived from polylactic acid blends is collapsing the historical trade-off between single-use infection control and waste reduction targets. German university hospitals in Berlin and Munich are piloting these materials in non-critical wards, pressuring incumbent polypropylene suppliers to accelerate compostable formulations or surrender sustainability-driven tenders.
ECHA enforcement of REACH restrictions on phthalate plasticizers in mask components is forcing reformulation of nose bridge wires and elastic ear loops. Manufacturers substituting bio-based alternatives face 6-12 month requalification timelines, with Italian converters absorbing the bulk of compliance costs to maintain access to Lombardy hospital procurement networks.
Hospital pharmacy departments are consolidating mask purchasing through integrated supply chain platforms that bundle respiratory protection with surgical gowns and examination gloves. French public hospital groups in the Île-de-France region have migrated 60% of FFP2 volume to these consolidated e-procurement channels, squeezing standalone distributors and rewarding manufacturers with broad personal protective equipment portfolios.
FFP2 Grade Medical Protective Mask Market Segmentation
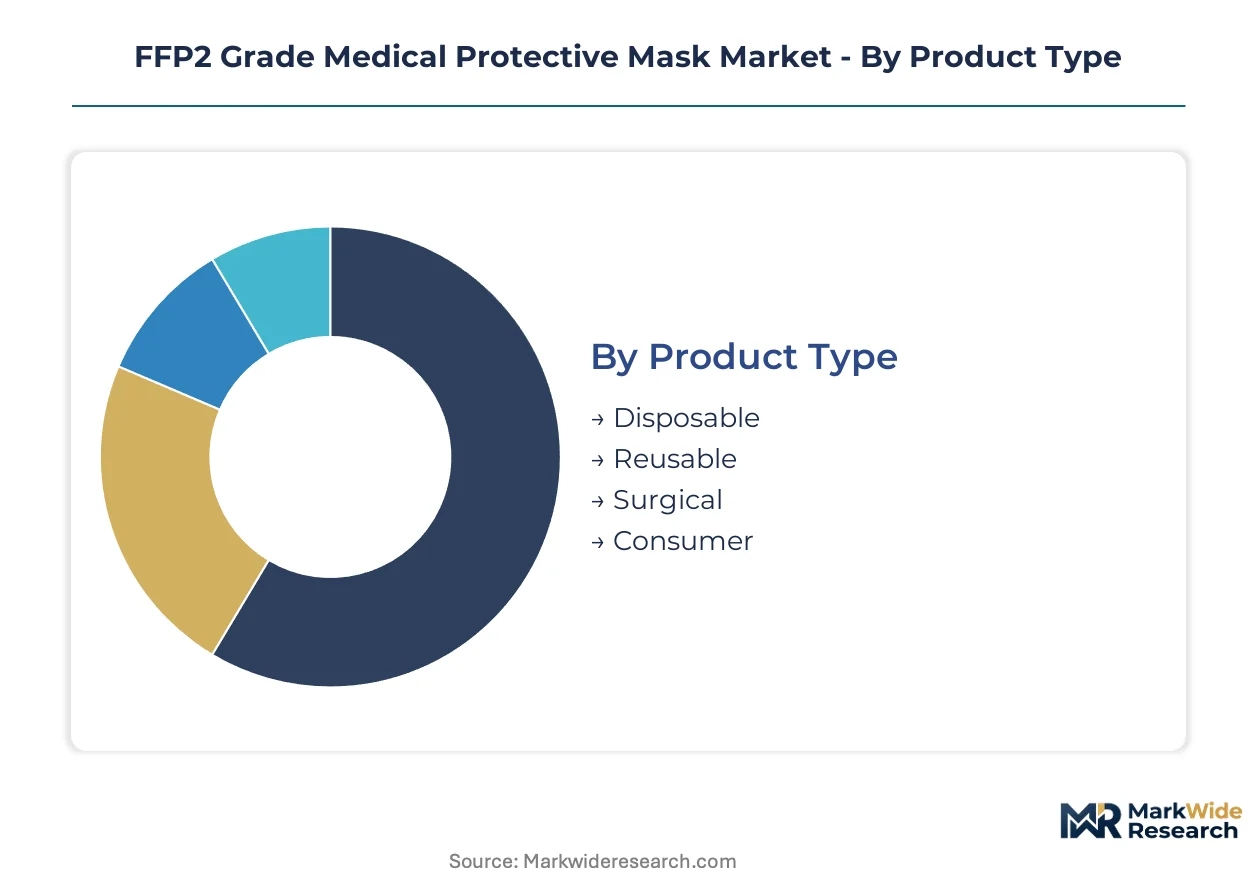
FFP2 mask segmentation reveals how procurement priorities split between infection control imperatives in hospitals and total cost pressures in industrial settings. Material choices and certification tiers further stratify supplier positioning across European tenders.
Product Type:
Use-case spectrum spans single-use clinical protocols through extended-wear industrial applications, with each tier demanding distinct manufacturing economics.
- Disposable:Multi-layer polypropylene construction with electrostatically charged meltblown filtration media meets EN 149 breathability standards. Hospital procurement in Germany and France concentrates here due to strict infection control protocols that mandate single-patient use. The dominant share belongs to Disposable, while Reusable is closing the gap fastest.
- Reusable:Elastomeric facepiece designs with replaceable filter cartridges target automotive and chemical manufacturing sectors in Bavaria and North Rhine-Westphalia seeking per-use cost reduction.
- Surgical:Sterile packaging and fluid resistance specifications align with operating theater requirements in Italian university hospitals.
- Consumer:Retail-packaged variants with simplified fit testing address pharmacy channel demand in France and Belgium.
Disposable configurations capture hospital volume, though Reusable designs are gaining traction in industrial safety budgets.
Application:
End-user concentration varies sharply by regulatory environment and exposure risk assessment protocols.
- Healthcare Facilities:Tertiary hospitals in Berlin, Munich, and Milan drive specification standards through group purchasing organization frameworks. EU PPE Regulation compliance is non-negotiable, with CE marking mandatory for all respiratory protective equipment entering procurement channels.
- Personal Use:Pharmacy retail and e-commerce distribution in France and Italy serve individuals with respiratory risk factors.
- Industrial Safety:Chemical processing and automotive assembly plants in Germany pilot half-mask respirators as disposable alternatives face cost scrutiny.
- Emergency Services:Fire departments and ambulance crews require rapid donning designs with speech diaphragms for field communication.
Healthcare Facilities command the largest procurement volumes, yet Industrial Safety applications are expanding most quickly as manufacturing employers reassess respiratory programs.
Material:
Feedstock selection determines filtration efficiency, breathability, and compliance with emerging sustainability mandates.
- Meltblown:Electrostatically charged polypropylene microfibers achieve 94% particle retention at 0.3 microns while maintaining pressure drop below EN 149 limits. Production concentrates within 200 kilometers of Shanghai, exposing European distributors to shipping volatility.
- Polypropylene:Spunbond outer layers provide structural integrity and splash resistance for clinical environments.
- Fabric:Woven textile alternatives address consumer comfort preferences in retail channels.
- PVC:Molded valve components and facepiece seals in reusable respirators.
Meltblown media anchors filtration performance, though biodegradable polylactic acid blends are capturing sustainability-focused tenders.
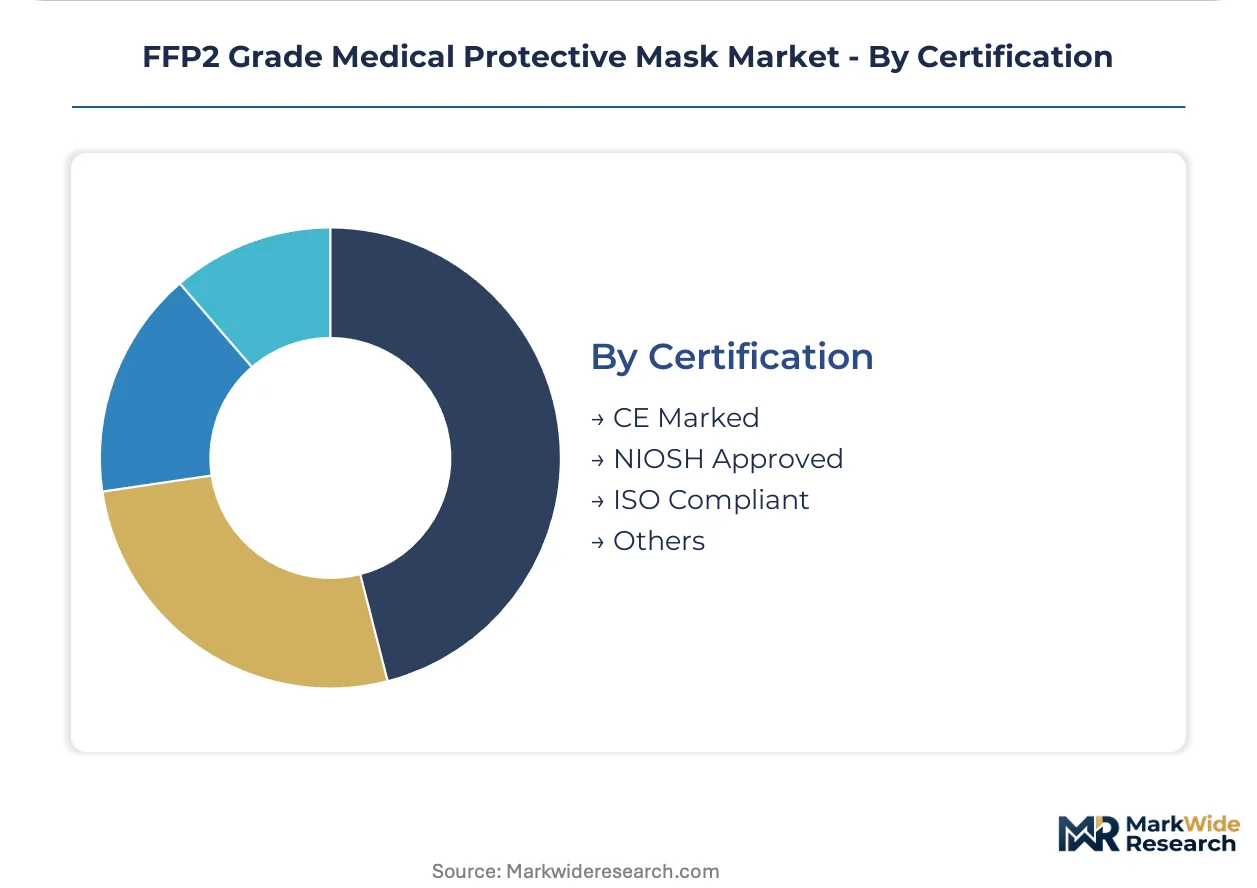
Certification:
Regulatory tier creates market access barriers and pricing stratification across parallel demand channels.
- CE Marked:Mandatory under EU PPE Regulation 2016/425 for all respiratory protective equipment entering European healthcare channels. ECHA oversight of REACH chemical compliance adds formulation constraints on polymer stabilizers and plasticizer alternatives.
- NIOSH Approved:42 CFR 84 classifications serve North American healthcare systems maintaining dual-source qualification strategies.
- ISO Compliant:ISO 9001 quality management and ISO 13485 medical device standards support private-label manufacturing for European distributors.
- Others:National certifications for specific Middle Eastern and Asian markets outside core European demand.
CE Marked certification holds premium positioning in European tenders, while NIOSH variants occupy parallel channels without direct competition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospital networks wield outsized pricing leverage over Italian distributors due to consolidated group purchasing organization frameworks, while East Asian manufacturing clusters supply volume without capturing equivalent margin premiums.
Germany
University hospital networks in Bavaria and North Rhine-Westphalia drive standardized FFP2 specifications through group purchasing organizations. The EU PPE Regulation 2016/425 mandates CE marking for all respiratory protective equipment entering procurement channels. Berlin-based distributors are expanding warehousing capacity to buffer against shipping volatility from Shanghai manufacturing clusters.
France
Public hospital groups in the Île-de-France region have migrated the majority of FFP2 volume to consolidated e-procurement platforms bundling respiratory protection with broader personal protective equipment portfolios. ANSM oversight of medical device quality adds compliance layers beyond baseline CE requirements. Lyon and Marseille hospital systems are piloting biodegradable mask variants in non-critical wards.
Italy
Lombardy hospital procurement networks anchor national demand, with Milan-based university hospitals setting filtration performance benchmarks. ECHA enforcement of REACH restrictions on phthalate plasticizers is forcing reformulation of nose bridge wires and elastic components. Turin and Bologna manufacturing converters are absorbing requalification costs to maintain access to regional tender pools.
United States
Hospital systems maintain dual-source qualification strategies across CE-marked and NIOSH-approved regulatory jurisdictions to mitigate supply disruption risk. FDA emergency use authorizations and NIOSH 42 CFR 84 classifications shape procurement specifications for acute care facilities. The Boston and New York metro hospital networks are standardizing fit-testing protocols for extended-wear clinical environments.
China
Over seventy percent of meltblown polypropylene capacity sits within two hundred kilometers of Shanghai, exposing European distributors to shipping rate spikes and customs clearance delays. NMPA oversight of medical device exports adds documentation requirements for manufacturers serving EU channels. The Yangtze River Delta manufacturing cluster is upgrading electrostatic charging equipment to meet revised EN 149 breathability standards.
FFP2 Grade Medical Protective Mask Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The FFP2 grade medical protective mask market structures around three distinct player tiers: diversified multinational conglomerates with captive meltblown capacity, regional fabricators serving private-label distributors, and specialized valve technology engineers. Competitive dynamics center on backward integration into filtration media production and strategic partnerships with hospital procurement platforms to secure volume commitments.
Among diversified industrial conglomerates, 3M Company and Honeywell International Inc. exemplify the integrated archetype combining upstream filtration media production with downstream hospital channel access. Shanghai Dasheng Health Products Manufacture Co. Ltd. anchors the volume-production tier for European private-label distributors. Moldex-Metric occupies a position within the specialized engineering segment, with German-engineered valve technology differentiating on comfort metrics in extended-wear clinical environments.
| Leading Market Players |
|---|
| 3M Company |
| Honeywell International Inc. |
| Kimberly-Clark Corporation |
| Ansell Limited |
| CM Mask |
| DACH Schutzbekleidung GmbH & Co. KG |
| Shanghai Dasheng Health Products Manufacture Co. Ltd. |
| Cardinal Health, Inc. |
| Moldex-Metric |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta manufacturing cluster concentrates over seventy percent of meltblown polypropylene capacity within two hundred kilometers of Shanghai, granting East Asian producers outsized leverage over European distributor pricing during petrochemical upcycles. German hospital group purchasing organizations exploit this concentration by consolidating tender volumes to extract volume discounts, while smaller Italian distributors absorb margin compression from freight rate volatility and customs clearance delays.
Pricing Analysis
The customization-premium spread separates configured-to-order valve-equipped designs from standard flat-fold configurations across European procurement channels. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking tier, breathability performance, and after-sales technical support bundling. Cost compression in standard disposable tiers is intensifying because propylene monomer prices track naphtha cracking margins. Industrial safety buyers in automotive manufacturing exhibit highest price sensitivity, while German university hospital networks prioritize filtration performance over unit cost.
Supply Chain Analysis
Upstream propylene monomer and specialized electrostatic charging equipment anchor raw material dependencies for filtration media production. Manufacturing concentrates in China, Germany, and Italy, with meltblown capacity clustered near Shanghai and conversion facilities distributed across Bavaria and Lombardy. Single-source vulnerability runs through Shanghai-area meltblown suppliers exposed to shipping chokepoints and NMPA export documentation delays. Distribution runs through group purchasing organization frameworks in Germany, consolidated e-procurement platforms in France, and traditional medical distributors in Italy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reusable elastomeric respirators with P100 cartridges threaten disposable FFP2 volumes in industrial segments, forcing incumbents to defend clinical channel positioning while new entrants exploit sustainability-driven tender openings.
For Market Incumbents: Build certification moats by accelerating CE marking pathways for biodegradable polylactic acid formulations before EU Green Deal procurement criteria harden. Deepen backward integration into meltblown media production to buffer propylene price volatility, or risk margin erosion during petrochemical upcycles. Secure multi-year volume commitments with Bavarian and North Rhine-Westphalian hospital networks before group purchasing organization consolidation narrows supplier pools further. For New Entrants and Emerging Players: Pursue Eastern European hospital modernization opportunities in Poland and Romania where cohesion fund allocations are upgrading infectious disease wards without entrenched incumbent relationships. Target sustainability-certified tenders in French public hospital groups piloting biodegradable variants in non-critical wards. Establish direct-to-clinic e-procurement partnerships with Italian pharmacy platforms to bypass traditional distributor markups. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because CE certification queues stretching 8-14 months trap competitor R&D investment in regulatory limbo while rewarding qualified incumbents with pricing stability. Acquisition candidates include Italian converters with REACH-compliant reformulation capabilities and German valve technology engineers serving extended-wear clinical environments. Watch electrostatic decay rates in humidity-stressed warehousing as a signal of inventory quality risk and working capital pressure.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU PPE Regulation 2016/425 compliance filters uncertified competitors from German hospital tenders. |
| Backward Integration | Captive meltblown capacity insulates 3M and Honeywell from propylene monomer price spikes. |
| Hospital System Partnership | Bavarian university hospital networks generate predictable volume through standardized specifications. |
| Sustainability Repositioning | Polylactic acid blends capture EU Green Deal procurement criteria in French pilot wards. |
| Distribution Channel Expansion | Direct-to-clinic e-procurement platforms in Italy disintermediate traditional medical distributor markups. |
Research Methodology
A spread of perspectives from hospital procurement managers, group purchasing organization contract directors, biomedical engineers, and meltblown media technical specialists converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against EN 149:2001+A1:2009 technical documentation, ECHA REACH restriction updates, and hospital tender databases from Germany, France, and Italy. Bottom-up volume estimates from end-use segmentation triangulated against top-down capacity assessments from Yangtze River Delta manufacturing clusters.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling hospital procurement consolidation against meltblown capacity expansion and electrostatic charging equipment upgrades. Segmentation dimensions included product type, application, material composition, and certification tier alongside regional regulatory cluster variations. CAGRs were derived from volume trajectory analysis incorporating propylene feedstock cost assumptions and group purchasing organization pricing leverage. Forecast inputs incorporated EU PPE Regulation enforcement intensity and REACH plasticizer reformulation timelines.
Macroeconomic conditions sit as an overlay; deviation in propylene monomer prices, shipping rate volatility, or euro-yuan exchange rates would shift the trajectory. Cross-checking against hospital procurement database benchmarks and notified body certification queue reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Portable Gas Detection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Safety Goggles Market
Safety Equipment and Personal Protective Equipment (PPE)
Household Smart Safe Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Radar Speed Gun Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Radiation Protection Apron Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Steel Smart Locker Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Rodent Control Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Machine Guarding Fence Market
Safety Equipment and Personal Protective Equipment (PPE)
Body Armor Accessories Market
Safety Equipment and Personal Protective Equipment (PPE)
Spill Kits Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Personal Protective Equipment Kit Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Solutions Market