
 North America Fall Protection Market | 2026-2036
North America Fall Protection Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fall Protection Market Analytics
Mexico is tilting toward expanded fall protection manufacturing capacity as nearshoring accelerates. 3M leverages its integrated respiratory and fall protection portfolio to anchor premium positioning across industrial accounts. MSA Safety sustains technology leadership through advanced self-retracting lifeline designs. Honeywell International competes on scale, controlling broad distribution channels throughout the United States and Canada.
North America fall protection encompasses engineered systems, personal equipment, and anchorages designed to arrest falls from elevated work surfaces, typically rated for forces not exceeding 1,800 pounds and incorporating energy-absorbing components to limit worker deceleration. These systems serve the essential commercial purpose of eliminating fatalities and compliance penalties in height-exposed occupations. Harnesses and lanyards dominate product-type revenue, while safety nets occupy a mature niche with stable replacement cycles. Construction leads end-user demand, though oil and gas applications command higher per-worker spend due to specialized anchorage requirements. Direct sales channels capture institutional volume, whereas distributors serve fragmented contractor bases with faster turnaround needs.
OSHA enforces 29 CFR 1926 Subpart M for construction and 1910.28 for general industry, mandating fall protection at elevations of six feet and four feet respectively, while CSA Z259 standards govern Canadian provincial enforcement. ANSI Z359 voluntary consensus standards further shape product design benchmarks that major buyers specify in procurement. The US EPA and state environmental agencies in Texas and Louisiana increasingly scrutinize disposal of synthetic harness materials, adding compliance layers to equipment lifecycle management. Stakeholders must monitor how California's Division of Occupational Safety and Health interprets emerging rope-access protocols, as this will determine certification requirements for a growing segment of wind turbine and tower maintenance crews.
Market Dynamics
OSHA's updated Walking-Working Surfaces standard is forcing systematic equipment replacement across United States industrial facilities, compressing replacement cycles from seven years to four years for legacy harness systems.
Growth Catalysts
- 29 CFR 1926 Subpart M enforcement:Construction employers face six-foot elevation mandates with escalating penalties, driving immediate procurement of self-retracting lanyards and engineered anchorages.
- Wind turbine maintenance expansion:Tower climbing crews in Texas and Iowa require certified rope-access protocols, creating specialized demand for lightweight full-body harnesses with integrated tool tethers.
- Synthetic material advances:Ultra-high-molecular-weight polyethylene webbing reduces harness weight by forty percent versus nylon, improving worker mobility in sustained elevated operations.
Market Restraints
- Petrochemical input volatility:Nylon 6,6 and polyester resin prices fluctuate with Gulf Coast refinery output, compressing margin stability for domestic harness manufacturers.
- Canadian provincial fragmentation:CSA Z259 adoption varies between Ontario, Alberta, and British Columbia, forcing manufacturers to maintain multiple certification SKUs for a single national market.
- Inspection burden accumulation:Pre-use harness checks and documented annual recertification consume supervisor hours, creating operational drag for small contractor fleets.
Strategic Opportunities
- Mexico nearshoring corridor:Querétaro and Nuevo León industrial zones lack established fall protection supply chains, opening first-mover positioning for integrated system providers.
- Connected safety convergence:Integration of RFID-equipped harnesses with building information modeling platforms enables real-time worker location tracking during complex construction phases.
- California scaffold safety mandates:Cal/OSHA's elevated work platform rules exceed federal baselines, creating premium-tier demand for engineered systems with redundant arrest mechanisms.
Industry Challenges
- Competent person certification scarcity:OSHA requires trained inspectors on every site, yet community college programs produce insufficient qualified graduates for Gulf Coast energy construction demand.
- Legacy anchorage incompatibility:Pre-2012 installed tie-off points lack load-rating documentation, forcing costly structural engineering assessments before equipment deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fall Protection Market |
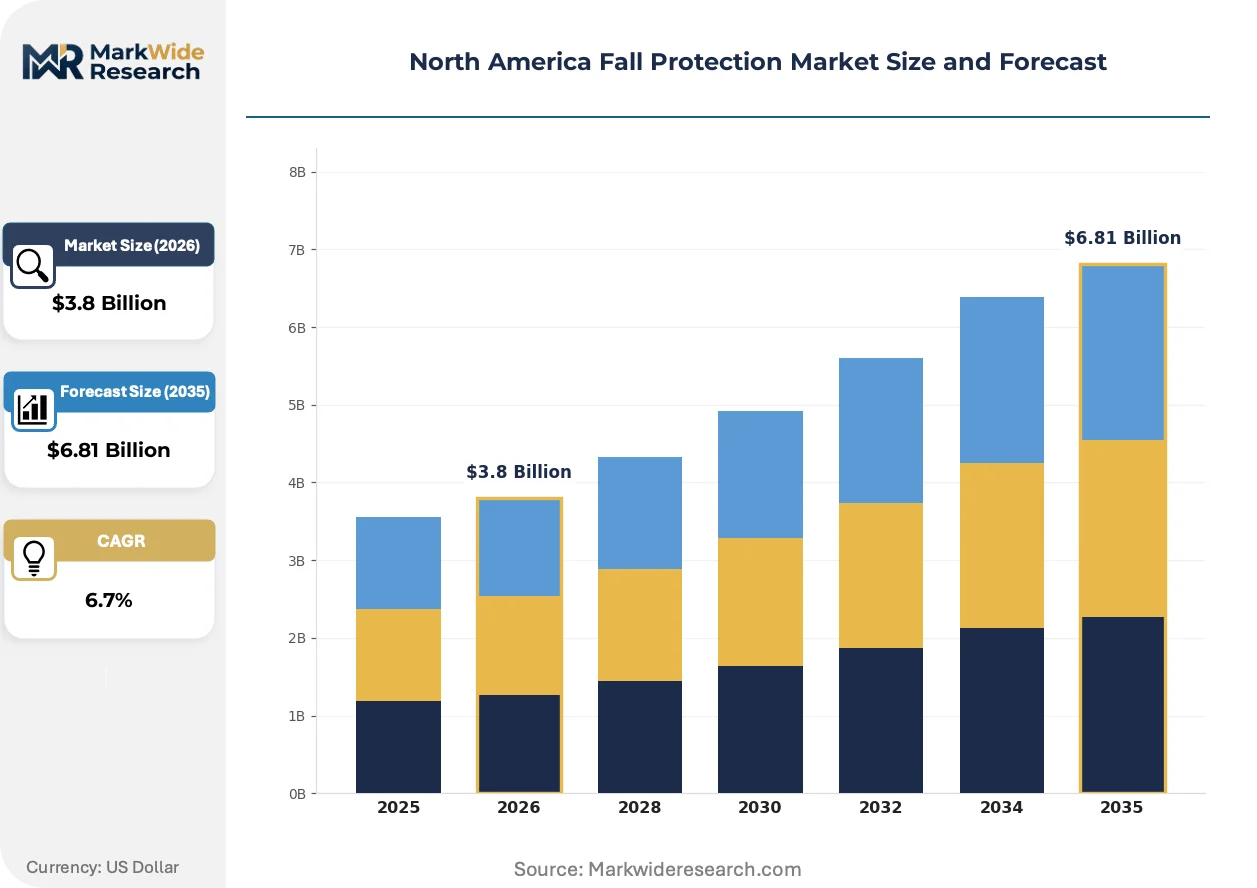
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Harnesses, Lanyards, Anchorage Connectors, Safety Nets End User: Construction, Oil & Gas, Mining, Transportation Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers Application: Industrial Applications, Residential Use, Commercial Projects, Government Contracts |
| Companies Covered | 3M, Honeywell International, MSA Safety, Guardian Fall, FallTech, Werner Co., SKYLOTEC, Kee Safety, Petzl, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fall Protection Market Evolving Landscape
Equipment intelligence and material science are converging to redefine how fall protection systems communicate, perform, and integrate with broader site safety architectures across North American job sites.
Self-retracting lifeline technology is migrating from steel cable to synthetic rope constructions. Wind farm operators in the Great Plains are adopting these lighter units to reduce climber fatigue during hundred-meter tower ascents. The shift is compressing equipment specification differentiation between premium and mid-tier suppliers.
California's Division of Occupational Safety and Health is interpreting rope-access protocols more stringently than federal counterparts. Tower maintenance contractors must now demonstrate dual-certification for technicians, elevating training costs but creating barrier-to-entry protection for qualified providers. Wind and solar installation sectors bear the highest compliance burden under these evolving state-level interpretations.
Equipment-as-service models are gaining traction among mid-size general contractors. Distributors are replacing outright sales with monthly subscription arrangements covering inspection, recertification, and rapid replacement. The Pacific Northwest infrastructure corridor shows the fastest uptake, where project-based contracting makes capital avoidance attractive.
North America Fall Protection Market Segmentation
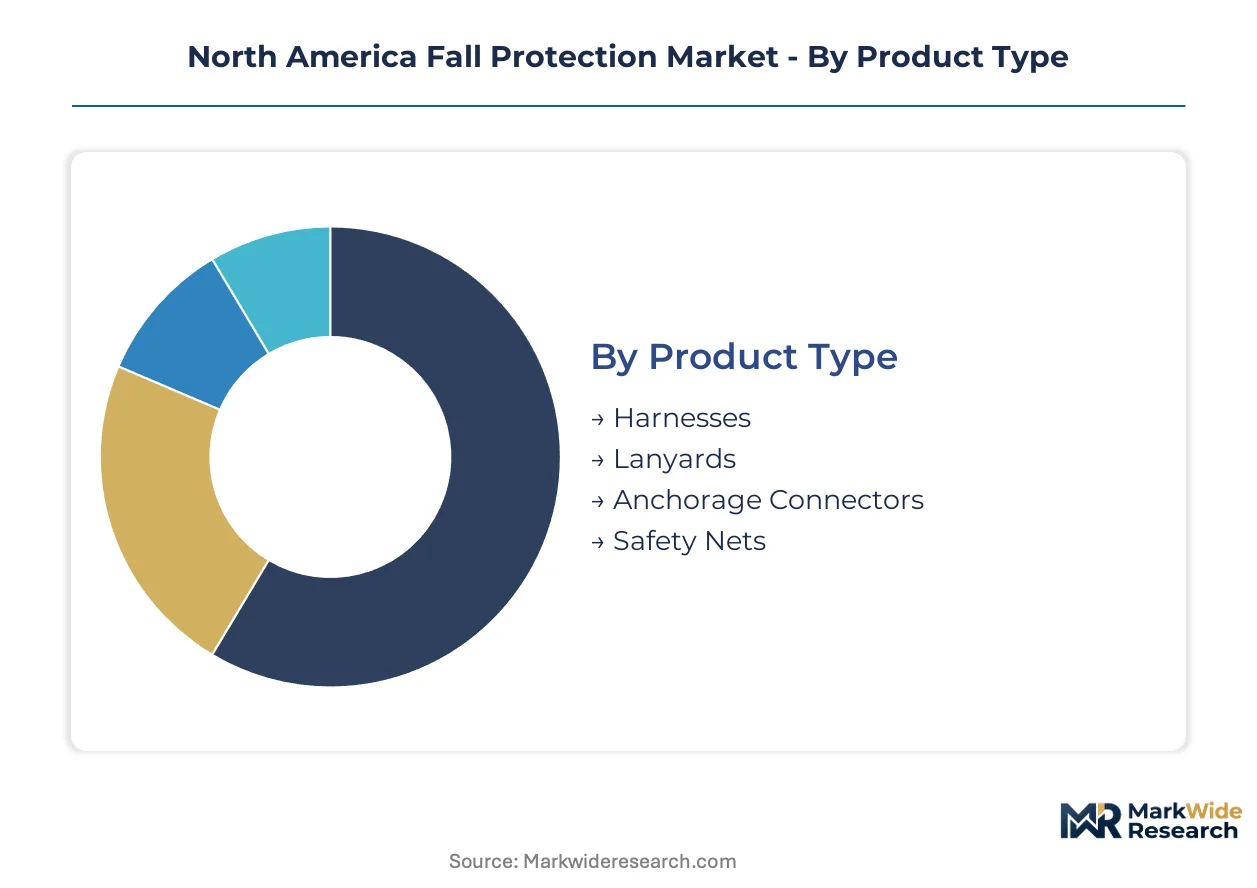
Fall protection procurement patterns diverge sharply across product categories, end-use sectors, and channel structures. Understanding these splits reveals where compliance pressure concentrates versus where discretionary upgrade cycles dominate purchasing behavior.
Product Type:
Maturity varies dramatically across this category, with established hardware categories facing displacement from integrated system approaches.
- Harnesses:Full-body designs incorporating dorsal D-rings and quick-connect buckles constitute the foundational personal protective equipment category. Construction sector procurement across the United States Gulf Coast energy corridor and Pacific Northwest infrastructure zones drives volume, with OSHA's updated Walking-Working Surfaces standard compressing replacement cycles from seven years to four years.
- Lanyards:Self-retracting variants are displacing traditional shock-absorbing webbing designs in elevated work applications. Wind turbine maintenance crews in Texas and Iowa require certified rope-access protocols, creating specialized demand for lightweight units with integrated tool tethers and synthetic rope constructions that reduce climber fatigue during hundred-meter tower ascents.
- Anchorage Connectors:Engineered systems rated for 5,000-pound minimum tensile strength serve permanent installation applications.
- Safety Nets:Passive fall arrest systems occupy a mature niche with stable replacement cycles in bridge construction and building demolition.
Harnesses retain volume leadership; lanyards hold the steepest expansion curve.
End User:
Cost tier stratification separates commodity procurement from specialized system integration across vertical markets.
- Construction:General contractors and specialty trades constitute the largest addressable base, with six-foot elevation mandates under 29 CFR 1926 Subpart M driving immediate procurement of self-retracting lanyards and engineered anchorages. State-level scaffold safety mandates in California and New York compel employers to upgrade legacy equipment beyond federal baselines.
- Oil & Gas:Offshore platforms and refinery turnarounds command the highest per-worker spend due to specialized anchorage requirements and corrosive environment specifications. The US Gulf Coast energy corridor concentrates demand for stainless steel hardware and flame-resistant harness materials.
- Mining:Underground operations require MSHA-compliant equipment with enhanced visibility features and chemical resistance.
- Transportation:Bridge maintenance and rail yard applications drive seasonal procurement patterns tied to federal infrastructure spending cycles.
Construction dominates absolute volume; oil and gas generates the highest revenue per deployed worker.
Distribution Channel:
Customer type and purchase urgency dictate channel selection across fragmented versus institutional buyer bases.
- Direct Sales:National accounts and multi-site industrial operators negotiate enterprise agreements with manufacturers. Equipment-as-service models are gaining traction among mid-size general contractors, with distributors replacing outright sales with monthly subscription arrangements covering inspection, recertification, and rapid replacement.
- Distributors:Independent and national distributors serve fragmented contractor bases with faster turnaround needs. The Pacific Northwest infrastructure corridor shows the fastest uptake of rental and subscription models, where project-based contracting makes capital avoidance attractive.
- Online Retail:Small contractors and individual tradespeople purchase standard SKU items through e-commerce platforms.
- Wholesalers:Bulk procurement channels serve regional safety equipment dealers and construction supply houses.
Direct sales capture institutional volume; distributors address the fastest-expanding contractor segment.
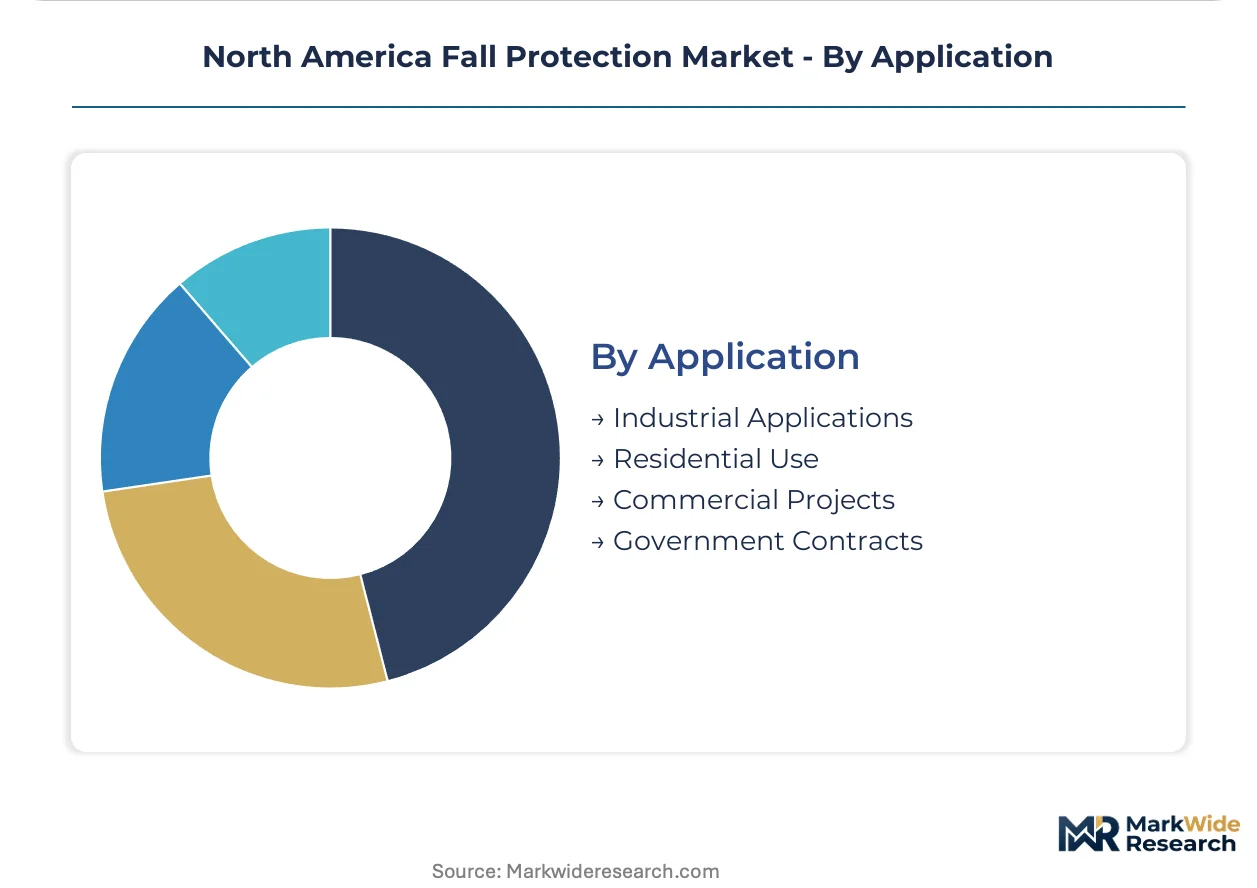
Application:
Geographic concentration of project types shapes specification requirements and compliance layering.
- Industrial Applications:Manufacturing facilities and processing plants require integration with lockout-tagout protocols and confined space entry procedures. EPA scrutiny of synthetic harness material disposal in Texas and Louisiana adds compliance layers to equipment lifecycle management.
- Commercial Projects:High-rise construction and facility maintenance drive demand for temporary engineered systems.
- Government Contracts:Federal and state procurement mandates domestic content requirements and certified small business participation.
- Residential Use:Roofing and home improvement applications represent a price-sensitive segment with limited specification rigor.
Industrial applications anchor revenue stability; commercial projects provide the most volatile expansion opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic harness manufacturing concentrates in the United States industrial belt, with Mexican assembly operations expanding to serve nearshoring demand. Canadian distribution networks anchor cross-border supply chains. Sub-regional specialization shapes procurement patterns across North American job sites.
United States
Construction sector procurement drives volume across the Gulf Coast energy corridor and Pacific Northwest infrastructure zones. OSHA enforces 29 CFR 1926 Subpart M with escalating penalties for six-foot elevation violations, compelling systematic equipment upgrades. Texas wind farms and Louisiana petrochemical facilities command specialized stainless steel hardware and flame-resistant harness materials.
Canada
Provincial adoption of CSA Z259 standards varies between Ontario, Alberta, and British Columbia, forcing manufacturers to maintain multiple certification SKUs. Ontario's manufacturing base and Alberta's oil sands operations generate concentrated demand for cold-weather-rated equipment. British Columbia's hydroelectric and mining sectors drive seasonal procurement tied to federal infrastructure spending cycles.
Mexico
Nearshoring accelerates fall protection manufacturing capacity expansion in Querétaro and Nuevo León industrial zones. These regions lack established supply chains, opening first-mover positioning for integrated system providers. Mexican assembly operations increasingly serve United States contractor demand through streamlined cross-border logistics.
California
Cal/OSHA interprets rope-access protocols more stringently than federal counterparts, elevating training costs for wind turbine and tower maintenance crews. State-level scaffold safety mandates exceed federal baselines, creating premium-tier demand for engineered systems with redundant arrest mechanisms. Los Angeles and San Francisco construction markets drive compliance-focused procurement.
New York
Metropolitan high-rise construction and bridge maintenance enforce strict local fall protection ordinances beyond OSHA minimums. State-level scaffold safety mandates compel employers to upgrade legacy equipment. New York City tower crane operations and Hudson Valley infrastructure projects concentrate demand for temporary engineered systems.
North America Fall Protection Market Competitive Landscape
Integrated safety conglomerates and specialized fall protection manufacturers split the market across premium and mid-tier positioning. The vendor base clusters around three strategic archetypes: diversified industrial safety suppliers with respiratory and hearing protection portfolios; dedicated fall protection specialists with deep anchorage engineering expertise; and construction equipment distributors with private-label harness lines. Competitive moves center on Mexico manufacturing expansion and connected safety technology licensing.
Among diversified industrial safety suppliers, 3M and Honeywell International exemplify scale-driven positioning through broad distribution channel control. MSA Safety occupies a position within the specialized technology tier, anchoring premium market segments through advanced self-retracting lifeline designs. These three companies represent the dominant competitive anchors shaping procurement specifications across institutional accounts.
| Leading Market Players |
|---|
| 3M |
| Honeywell International |
| MSA Safety |
| Guardian Fall |
| FallTech |
| Werner Co. |
| SKYLOTEC |
| Kee Safety |
| Petzl |
| Others |
Value Network & Pricing Analysis
Overcapacity in Mexican harness assembly operations is compressing supplier pricing power and accelerating migration of mid-tier production toward Querétaro and Nuevo León. This utilization dynamic simultaneously rewards buyers with sourcing flexibility while pressuring domestic United States manufacturers to defend margin through certification tiering.
Pricing Analysis
OSHA's updated Walking-Working Surfaces standard dictates the pricing tier structure across the North American fall protection market. Three-tier pricing structure across premium, standard, and economy levels separates ANSI Z359-certified systems with documented load ratings from basic compliance-grade equipment and disposable contractor-grade units. Price differentiation hinges on certification level and after-sales service bundling. Cost compression in the standard tier is intensifying because of Mexican nearshoring capacity expansion. Small roofing contractors exhibit the highest price sensitivity, while oil and gas operators prioritize performance specifications over unit cost.
Supply Chain Analysis
Tariff exposure between Mexico and the United States dominates supply chain risk assessment for fall protection equipment sourcing. Manufacturing concentrates in Mexico, China, and domestic United States industrial belt facilities. Nylon 6,6 webbing, polyester resin, and ultra-high-molecular-weight polyethylene fibers serve as critical raw material inputs. Single-source vulnerability in Gulf Coast petrochemical feedstock supply creates concentration risk for synthetic harness production. Distribution runs through national safety distributors and direct manufacturer sales to institutional accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from connected safety platforms integrating RFID-equipped harnesses with building information modeling systems. Equipment-as-service subscription models threaten traditional transactional revenue capture.
For Market Incumbents: Build certification moats around ANSI Z359.11 and CSA Z259 dual-compliance to lock out mid-tier competitors. Deepen vertical integration into synthetic rope manufacturing to secure margin against petrochemical input volatility. Anchor enterprise accounts with integrated inspection and recertification service bundles that raise switching costs for contractors. For New Entrants and Emerging Players: Pursue white-space positioning in Mexico's nearshoring corridor where established supply chains remain underdeveloped. Target Querétaro and Nuevo León industrial zones with equipment-as-service offerings tailored to project-based contractors seeking capital avoidance. Lead with rapid-turnaround distribution partnerships rather than manufacturing scale. For Investors and Strategic Acquirers: Capital is best deployed toward specialized fall protection engineering firms with deep anchorage system expertise and regulatory certification depth. Long-term viability rests on consolidation of fragmented mid-tier suppliers as compliance complexity escalates. Monitor Cal/OSHA rope-access protocol interpretations as the inflection signal for premium-tier demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Webbing | Captures margin from nylon and UHMWPE supply volatility affecting harness manufacturers. |
| Equipment-as-Service Subscription Launch | Aligns revenue model with Pacific Northwest contractor preference for capital avoidance. |
| Dual Certification Investment | Secures barrier-to-entry protection against Mexican competitors lacking ANSI and CSA compliance. |
| Connected Safety Platform Development | Integrates RFID harness tracking with building information modeling for real-time worker location. |
| Nearshoring Manufacturing Expansion | Positions capacity in Querétaro to serve United States demand through streamlined cross-border logistics. |
Research Methodology
The analysis maps harness systems, lanyard configurations, anchorage connectors, and safety net deployments, each validated through safety directors at construction firms, procurement managers at oil and gas operators, and distribution executives at industrial supply houses. Primary interview data draws from OSHA compliance officers and Cal/OSHA regulatory specialists. Secondary validation incorporates OSHA enforcement databases, ANSI Z359 standards documentation, SEC 10-K filings from listed safety equipment manufacturers, and customs trade records for synthetic fiber imports. Bottom-up equipment unit demand estimates triangulate against top-down construction spending and energy sector capital expenditure allocations.
Assumptions held fixed include prevailing OSHA and CSA enforcement intensity, current tariff structures between Mexico and the United States, and synthetic material technology trajectories. Variables modeled across the analysis window encompass wind turbine installation growth rates, nearshoring velocity, and state-level scaffold safety mandate expansion. Segmentation dimensions include product type, end-user industry vertical, distribution channel structure, and application environment. CAGRs derive from regression analysis of historical procurement cycles against compliance-driven replacement triggers. Industry-specific forecast inputs incorporate Gulf Coast energy construction backlog data and Iowa-Texas wind farm maintenance crew expansion plans.
Sensitivities concentrate around OSHA penalty escalation schedules, Mexican peso exchange rate volatility affecting nearshoring economics, and breakthroughs in connected safety technology adoption rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Tourniquet Market
Safety Equipment and Personal Protective Equipment (PPE)
Latin America Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Face Shield Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Tourniquet Cuffs Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Eyewear Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Technologies Market
Safety Equipment and Personal Protective Equipment (PPE)
Biometric Gun Safe Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Hazmat Suits Market
Safety Equipment and Personal Protective Equipment (PPE)
Bulletproof Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Laser Safety Glasses Market
Safety Equipment and Personal Protective Equipment (PPE)
Alarm Management System Market