
 Disposable Protective Clothing Market | 2026-2036
Disposable Protective Clothing Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Protective Clothing Market Intelligence
ISO 16603 certification for blood-borne pathogen resistance is unwinding competitive access for suppliers lacking accredited testing infrastructure. DuPont de Nemours, Inc. leverages its Tyvek manufacturing scale to dominate flash-spun polyethylene coveralls for hazardous material handling. Kimberly-Clark Corporation anchors hospital supply contracts through direct distribution networks across North American health systems. Ansell Limited specializes in chemical splash protection garments for European industrial clients.
Disposable protective clothing denotes single-use garments engineered from nonwoven synthetic substrates—typically polypropylene spunbond, SMS laminates, or microporous polyethylene film—designed to barrier against biological fluids, chemical splashes, or particulate contamination in controlled environments. These garments achieve protection through material density measured in grams per square meter and seam construction, with taped seams providing higher integrity than serged seams for blood-borne pathogen applications. Coveralls command the largest product category volume, driven by oil and gas maintenance turnarounds and pharmaceutical cleanroom protocols. Microporous film laminates represent the fastest-expanding material segment, as semiconductor fabs in South Korea and Taiwan adopt stricter particulate controls below ISO Class 5 thresholds. Food processing applications generate premium pricing for blue-detectable polyethylene aprons that satisfy BRC and SQF audit requirements.
OSHA's 29 CFR 1910.132 personal protective equipment standard and the EU's PPE Regulation (EU) 2016/425 together shape product design, testing protocols, and market entry documentation for suppliers serving transatlantic industrial buyers. China's GB 24539-2021 standard for chemical protective clothing and Japan's JIS T 8115 specifications for disposable cleanroom garments add compliance layers for Asia-Pacific market participation. FDA enforcement of 21 CFR 878.4040 for surgical isolation gowns continues to filter out non-medical-grade suppliers from U.S. healthcare procurement channels. Stakeholders must monitor evolving state-level extended producer responsibility legislation in California and New York that could mandate recyclable or compostable end-of-life pathways for single-use garments.
Market Dynamics
Post-pandemic infection control mandates from the CDC, ECDC, and Japan's MHLW are permanently elevating baseline demand for single-use isolation gowns while flash-spun polyethylene innovations displace woven reusable alternatives in chemical processing and semiconductor cleanrooms.
Growth Catalysts
- ISO 16603 certification requirements:Blood-borne pathogen resistance testing mandates are filtering out non-accredited suppliers and consolidating procurement toward certified manufacturers in United States hospital systems.
- Semiconductor cleanroom expansion:South Korean and Taiwanese fabs are adopting stricter particulate controls below ISO Class 5 thresholds, driving specification upgrades for microporous film laminate garments.
- Flash-spun polyethylene scale:DuPont's Tyvek manufacturing infrastructure enables cost-competitive hazardous material handling coveralls that penetrate oil and gas maintenance turnarounds previously served by reusable woven alternatives.
Market Restraints
- Polypropylene feedstock volatility:Spunbond nonwoven production depends on propylene monomer pricing tied to naphtha cracking economics, compressing margin stability for mid-tier converters.
- China supply concentration:Yangtze River Delta manufacturing clusters control 60-70% of global SMS laminate capacity, creating single-point vulnerability for European and North American distributors.
- Woven reusable substitution:Industrial laundries in Germany and Japan are marketing multi-use chemical protective garments with lower lifetime cost positioning for solvent-exposure applications.
Strategic Opportunities
- India industrial safety programs:BIS certification requirements under IS 15151 are creating first-mover advantage for suppliers establishing local testing partnerships before full enforcement.
- Extended producer responsibility legislation:California and New York state-level mandates for recyclable or compostable end-of-life pathways will reward bio-based polyethylene film development.
- Blue-detectable food processing aprons:BRC and SQF audit requirements are generating premium pricing for visual contamination detection in poultry and ready-to-eat manufacturing.
Industry Challenges
- ISO 17025 laboratory accreditation timelines:Blood-borne pathogen testing infrastructure expansion requires 18-24 month validation cycles that delay market entry for new garment suppliers.
- Seam taping automation capex:Taped seam construction for high-integrity blood-borne pathogen protection demands specialized hot-air welding equipment with 3-4 year payback periods.
- Multi-standard compliance complexity:Simultaneous adherence to OSHA 29 CFR 1910.132, EU PPE Regulation 2016/425, and China's GB 24539-2021 fragments quality management system requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Protective Clothing Market |
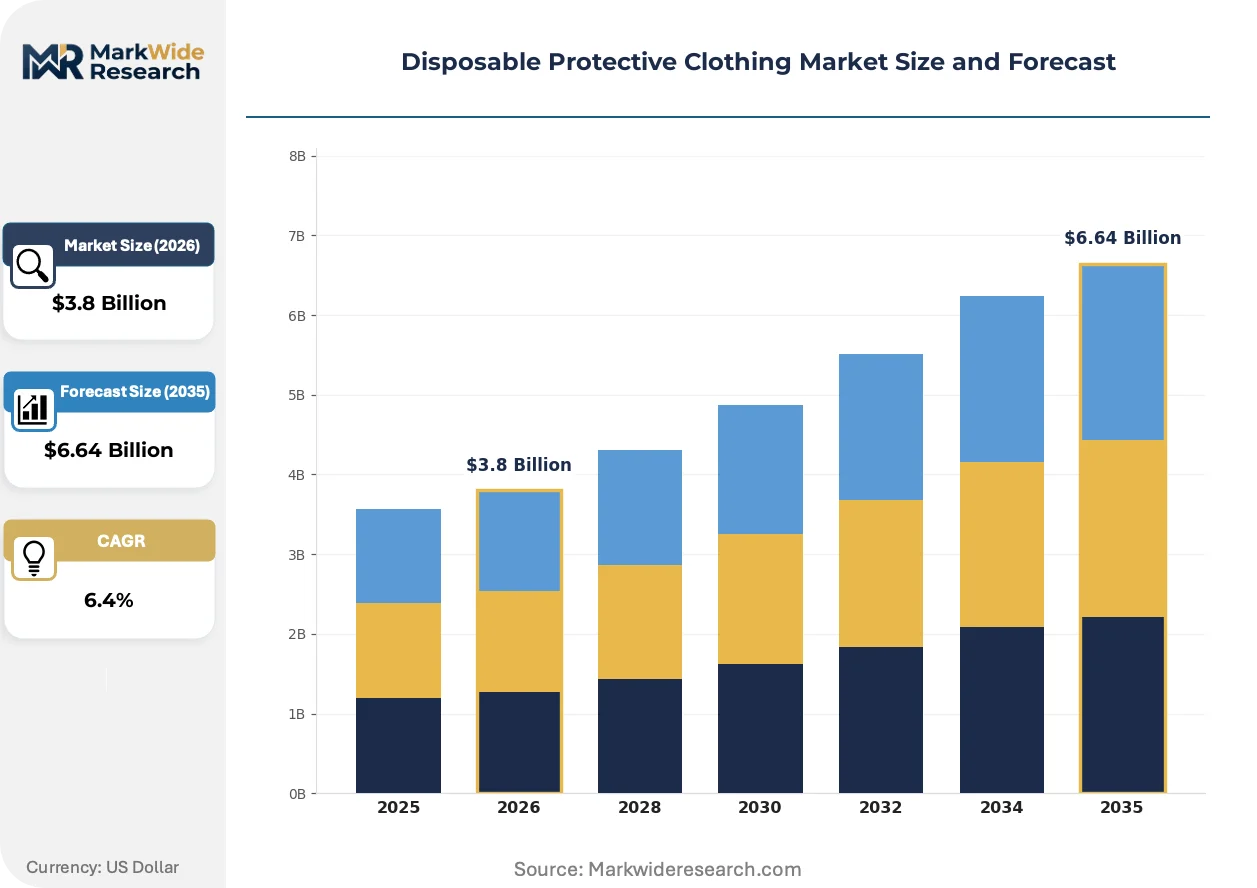
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coveralls, Gowns, Aprons, Sleeves Material: Polyethylene, Polypropylene, SMS, Microporous Film End User: Healthcare, Industrial, Chemical, Food Processing Application: Infection Control, Hazardous Material Handling, Cleanrooms, Food Hygiene |
| Companies Covered | Lakeland Industries, Inc., Honeywell International Inc., 3M Company, Alpha Pro Tech, Ltd., Medline Industries, L.P., DuPont de Nemours, Inc., Ansell Limited, International Enviroguard, Kimberly-Clark Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Protective Clothing Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory harmonization pressures are compressing product development cycles while reshaping competitive differentiation from commodity scale toward certified performance tiers.
Microporous polyethylene film laminates are miniaturizing barrier pore structures to sub-micron dimensions without sacrificing breathability metrics. Semiconductor fabs in Taiwan and South Korea are specifying these materials for ISO Class 3-4 environments previously requiring reusable garments. This technology is miniaturizing the performance gap between single-use disposables and multi-use cleanroom apparel, enabling volume expansion in premium contamination control segments.
EU PPE Regulation 2016/425 module B+C2 conformity assessment routes are extending notified body involvement from design review through production surveillance. Industrial buyers in Germany and France now require CE marking with module D quality assurance for chemical splash protection categories. Coverall suppliers serving European petrochemical maintenance are responding by consolidating testing partnerships with fewer notified bodies to streamline technical file management.
Hospital supply chain rationalization is compressing vendor panels from 15-20 disposable garment suppliers toward 3-5 strategic partners with direct distribution infrastructure. Group purchasing organizations in the United States are unbundling isolation gown contracts from broader infection control bundles to negotiate material-specific pricing. This concentration is most visible in Midwest health systems where regional distribution center proximity determines contract awards regardless of national brand recognition.
Disposable Protective Clothing Market Segmentation
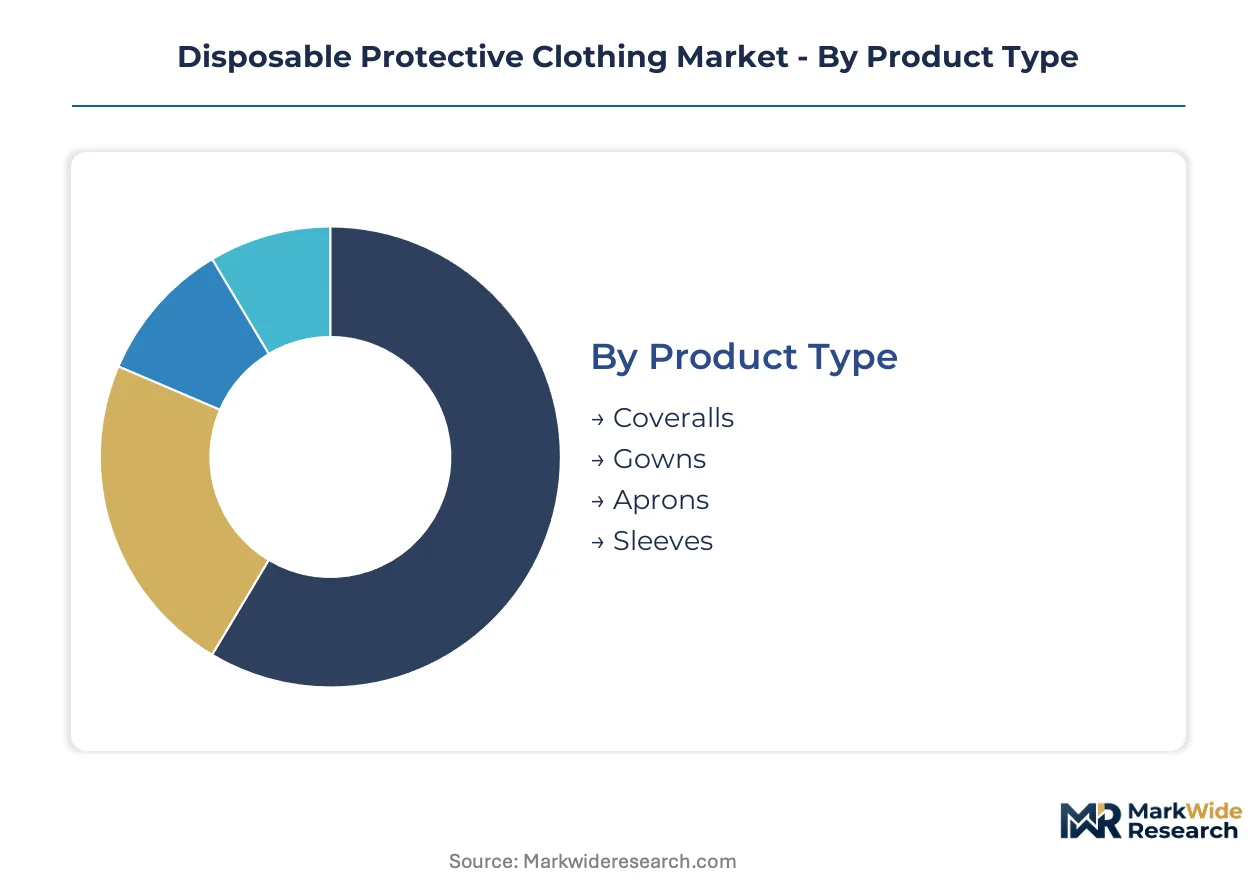
Disposable protective clothing procurement patterns diverge sharply between domestically consumed hospital supplies and export-oriented industrial safety garments. Understanding these segment boundaries clarifies why material specifications, certification requirements, and distribution channels rarely overlap across end-use categories.
Product Type:
Coveralls and gowns anchor export manufacturing from China's Yangtze River Delta, while aprons and sleeves serve predominantly domestic food processing and light industrial markets in North America and Europe.
- Coveralls:Full-body garments constructed from flash-spun polyethylene or SMS laminates with taped seam options for blood-borne pathogen resistance. Demand concentrates in United States oil and gas maintenance turnarounds and German chemical processing facilities where OSHA 29 CFR 1910.132 and EU PPE Regulation 2016/425 compliance is mandatory.
- Gowns:Single-use isolation garments engineered from polypropylene spunbond or SMS fabrics with ASTM F1670/F1671 fluid resistance ratings. Hospital systems in the United States, Germany, and Japan are expanding procurement following CDC, ECDC, and MHLW post-pandemic infection control mandates.
- Aprons:Front-protection polyethylene garments for food processing and light chemical splash applications.
- Sleeves:Arm-covering disposables used in poultry processing and semiconductor component handling.
Coveralls command the established base. The steepest expansion runs through gowns.
Material:
Cost tier stratification separates premium microporous film from commodity polypropylene, with SMS laminates occupying the mid-tier position across healthcare and industrial procurement.
- Polyethylene:Flash-spun high-density polyethylene (Tyvek-grade) delivers particulate and chemical splash protection through continuous fiber matrices without binders. Semiconductor fabs in Taiwan and South Korea specify these materials for ISO Class 3-4 cleanrooms previously requiring reusable garments.
- Microporous Film:Breathable polyethylene laminates with sub-micron pore structures blocking liquids while permitting moisture vapor transmission. Taiwan and South Korean semiconductor manufacturers are driving specification upgrades below ISO Class 5 thresholds as fab construction accelerates.
- Polypropylene:Spunbond nonwoven base material for cost-sensitive isolation gowns and basic protective aprons.
- SMS:Spunbond-meltblown-spunbond tri-laminate combining strength, filtration, and fluid resistance in mid-tier coveralls and surgical gowns.
Polyethylene anchors the established base. Microporous film is climbing the fastest.
End User:
Customer type determines certification burden intensity, with healthcare and chemical processing imposing the most stringent notified body involvement under FDA and EU PPE frameworks.
- Healthcare:Hospital systems and long-term care facilities requiring FDA 21 CFR 878.4040 compliant isolation gowns with ASTM F1670 blood penetration resistance. United States group purchasing organizations are consolidating vendor panels from 15-20 suppliers toward 3-5 strategic partners with direct distribution infrastructure.
- Chemical:Petrochemical maintenance, pharmaceutical manufacturing, and hazardous waste operations requiring CE Category III chemical splash protection. European industrial buyers in Germany and France now mandate module D quality assurance for production surveillance beyond basic CE marking.
- Industrial:General manufacturing, automotive assembly, and construction applications with lower certification thresholds.
- Food Processing:Poultry, red meat, and ready-to-eat manufacturing requiring blue-detectable polyethylene for visual contamination identification under BRC and SQF audit protocols.
Healthcare commands the established base. Chemical end-use is gaining share fastest.
Application:
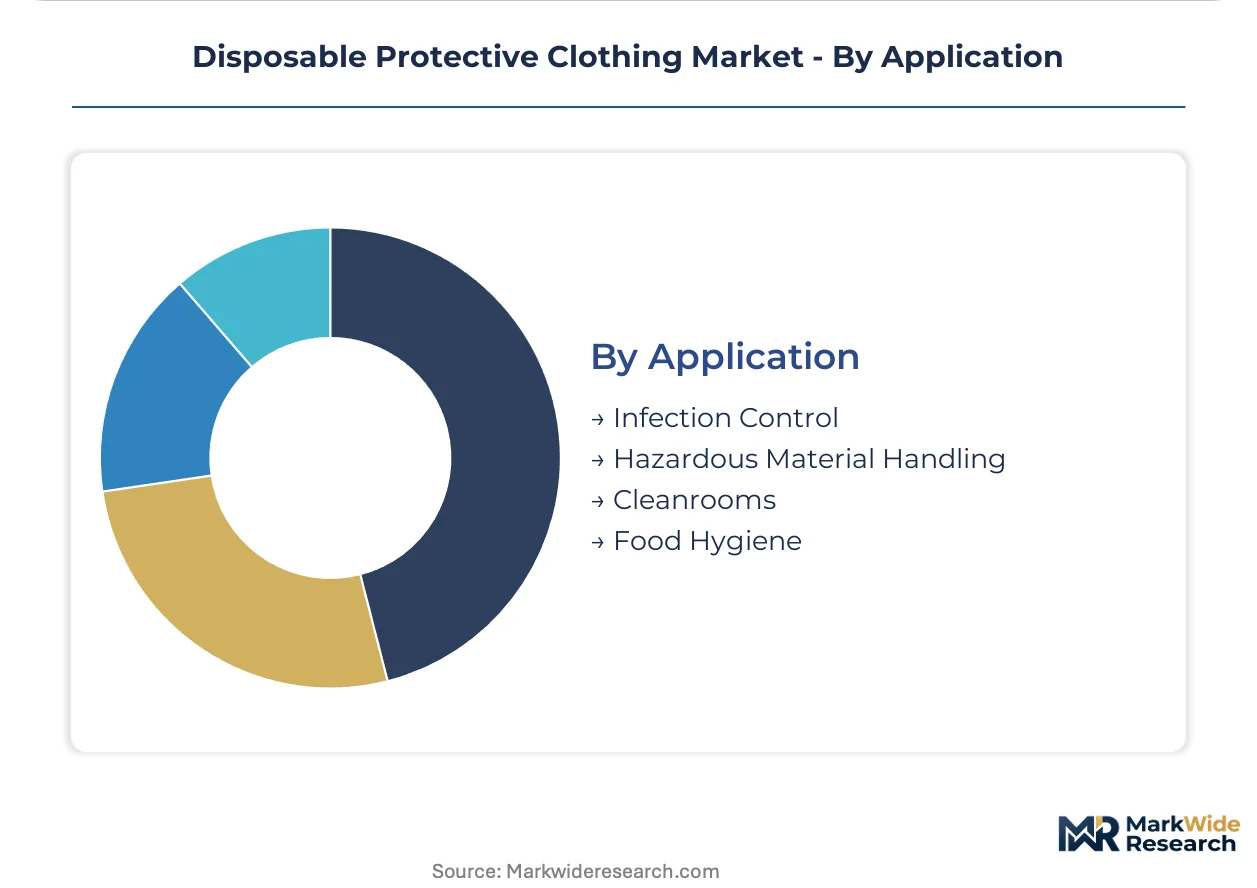
Volume concentration varies by regulatory trigger—CDC mandates for infection control versus OSHA enforcement for hazardous material handling versus ISO cleanroom standards for semiconductor contamination protocols.
- Infection Control:Isolation gown deployment in hospital isolation rooms and emergency departments governed by CDC Guideline for Isolation Precautions. United States health systems are unbundling gown contracts from broader infection control bundles to negotiate material-specific pricing.
- Cleanrooms:Particulate-controlled garment specifications for semiconductor, pharmaceutical, and aerospace manufacturing. Taiwan and South Korean fabs are miniaturizing barrier requirements to ISO Class 3-4 levels, displacing reusable apparel with advanced single-use alternatives.
- Hazardous Material Handling:Chemical splash and toxic particulate protection for petrochemical turnarounds and remediation sites.
- Food Hygiene:Color-coded disposable systems preventing cross-contamination in HACCP-compliant processing environments.
Infection control commands the established base. Cleanroom applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Post-pandemic infection control mandates from the CDC, ECDC, and Japan's MHLW are permanently elevating baseline demand for single-use isolation gowns across healthcare systems. Flash-spun polyethylene innovations are displacing woven reusable alternatives in chemical processing and semiconductor cleanrooms. Procurement patterns now concentrate around manufacturing clusters with accredited testing infrastructure.
United States
Hospital systems are consolidating vendor panels from 15-20 suppliers toward 3-5 strategic partners with direct distribution infrastructure. FDA enforcement of 21 CFR 878.4040 for surgical isolation gowns filters non-medical-grade suppliers from healthcare procurement channels. Midwest health systems award contracts based on regional distribution center proximity regardless of national brand recognition.
Germany
Industrial laundries market multi-use chemical protective garments with lower lifetime cost positioning for solvent-exposure applications. EU PPE Regulation 2016/425 module B+C2 conformity assessment routes extend notified body involvement from design review through production surveillance. Petrochemical maintenance buyers now mandate module D quality assurance for chemical splash protection categories.
China
Yangtze River Delta manufacturing clusters control 60-70% of global SMS laminate capacity, creating single-point vulnerability for European and North American distributors. GB 24539-2021 standard for chemical protective clothing adds compliance layers for Asia-Pacific market participation. Domestic producers serve both export markets and local industrial safety programs under national standards.
Japan
Semiconductor fabs adopt stricter particulate controls below ISO Class 5 thresholds, driving specification upgrades for microporous film laminate garments. JIS T 8115 specifications for disposable cleanroom garments shape procurement requirements for contamination-controlled environments. Tokyo and Osaka metropolitan areas concentrate demand from pharmaceutical manufacturing and electronics assembly operations.
South Korea
Semiconductor cleanroom expansion accelerates demand for sub-micron barrier pore structures without sacrificing breathability metrics. Taiwan and South Korean fabs miniaturize barrier requirements to ISO Class 3-4 levels, displacing reusable apparel with advanced single-use alternatives. Seoul Capital Area and Busan-Ulsan industrial corridors anchor premium contamination control garment consumption.
Disposable Protective Clothing Market Key Industry Players
Player mix skews toward diversified industrial conglomerates with polymer science capabilities and specialized protective equipment pure-plays. Market structure exhibits tiered consolidation with three to five strategic partners dominating hospital supply contracts while mid-tier converters compete on material cost. Archetypes include flash-spun polyethylene specialists, SMS laminate fabricators, and direct-distribution healthcare suppliers. Dominant competitive moves encompass capacity expansion in Yangtze River Delta manufacturing clusters and strategic partnerships with ISO 17025 accredited testing laboratories.
Within the diversified conglomerate tier, 3M Company and Honeywell International Inc. occupy positions spanning multiple protective equipment categories. DuPont de Nemours, Inc. anchors the flash-spun polyethylene segment through Tyvek manufacturing scale. Kimberly-Clark Corporation exemplifies the healthcare-direct archetype with established distribution networks across North American health systems. These three companies represent distinct competitive vectors: materials science depth, industrial safety breadth, and healthcare supply chain integration respectively.
| Leading Market Players |
|---|
| Lakeland Industries, Inc. |
| Honeywell International Inc. |
| 3M Company |
| Alpha Pro Tech, Ltd. |
| Medline Industries, L.P. |
| DuPont de Nemours, Inc. |
| Ansell Limited |
| International Enviroguard |
| Kimberly-Clark Corporation |
| Others |
Cost & Logistics Intelligence
ISO 16603 certification requirements simultaneously gate supply qualification and price differentiation, filtering non-accredited suppliers from United States hospital procurement while creating measurable spreads between certified and uncertified garment tiers. Buyers in Midwest health systems now weight regional distribution center proximity as heavily as unit price, compressing margin capture for distant manufacturers regardless of material cost advantages.
Pricing Analysis
Certification level creates the primary spread between ISO 16603-accredited blood-borne pathogen garments and basic fluid-resistant alternatives. Three-tier pricing structure across premium microporous film, mid-grade SMS laminates, and commodity polypropylene spunbond reflects performance differentiation. Cost compression in the polypropylene tier is intensifying because propylene monomer volatility feeds directly through naphtha cracking economics. Hospital group purchasing organizations exhibit lowest price sensitivity for taped-seam isolation gowns with direct distribution infrastructure, while industrial laundries in Germany drive substitution pressure through multi-use garment lifetime cost positioning.
Supply Chain Analysis
Inventory lead times for flash-spun polyethylene coveralls stretch 8-12 weeks due to DuPont's concentrated Tyvek manufacturing footprint. Supply concentrates in China's Yangtze River Delta for SMS laminates, South Korea for microporous film conversion, and the United States for flash-spun polyethylene. Raw material flows draw from Saudi Arabian petrochemical feedstocks for polypropylene, Japanese catalyst systems for polymerization, and German hot-air welding equipment for seam taping. Single-source vulnerability around Yangtze River Delta SMS capacity creates exposure for European distributors. Distribution runs through hospital supply direct networks in North America, industrial safety distributors in Europe, and integrated trading houses in Asia-Pacific.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Post-pandemic infection control mandates have reset baseline procurement standards, creating early-cycle expansion tailwinds as healthcare systems rebuild strategic supplier panels from fragmented pre-pandemic bases.
For Market Incumbents: Consolidate testing infrastructure partnerships to defend ISO 17025 accreditation moats against mid-tier converters. Add captive SMS laminate capacity in Yangtze River Delta clusters to offset raw material volatility exposure. Lock hospital system contracts through direct distribution center proximity rather than brand premium positioning. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for surgical isolation gowns open procurement access to United States health systems unbundling gown contracts from broader infection control bundles. Target India's BIS certification window before IS 15151 full enforcement creates first-mover positioning in industrial safety programs. Pursue blue-detectable food processing apron specialization to capture BRC/SQF audit-driven premium pricing in poultry manufacturing. For Investors and Strategic Acquirers: California extended producer responsibility legislation reshapes the acquisition landscape toward bio-based polyethylene film developers with recyclable end-of-life pathways. Five-to-ten year viability favors vertically integrated converters with captive testing laboratories and regional distribution infrastructure. Watch ISO 17025 laboratory accreditation queue lengths as inflection signal for supply-constrained pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Laboratory Accreditation | Blood-borne pathogen testing infrastructure gates hospital supply contracts under CDC mandates. |
| Backward Integration into SMS Laminate Production | Captive capacity in Yangtze River Delta clusters insulates margin from propylene volatility. |
| Blue-Detectable Food Processing Apron Development | BRC and SQF audit requirements generate premium pricing in poultry manufacturing segments. |
| Direct Distribution Network Expansion | Regional distribution center proximity determines contract awards in Midwest health systems. |
| Bio-Based Polyethylene Film R&D Partnership | California EPR legislation rewards compostable end-of-life pathways for single-use garments. |
Research Approach
Operator-level perspectives from infection control officers, hospital procurement managers, industrial safety directors, and nonwoven fabric technical specialists anchored the qualitative base. Primary fieldwork combined structured interviews with supply chain validation against customs records, OSHA enforcement databases, FDA 510(k) filings, and EU notified body CE marking registries. Bottom-up demand modeling triangulated against top-down macroeconomic indicators across healthcare capital expenditure and industrial safety spending.
Sensitivity analysis tested forecast robustness across propylene price volatility scenarios, accreditation timeline delays, and substitution elasticity for reusable garments. Segmentation modeling captured product type, material grade, end-user certification burden, and application regulatory trigger dimensions. CAGRs derived from weighted average of historical trajectory and penetration-adjusted saturation curves, with semiconductor cleanroom expansion and infection control mandate permanence as key demand drivers.
The analysis sits within stated boundaries; outcomes outside sustained CDC/ECDC mandate enforcement or accelerated Yangtze River Delta supply disruption would require recalibration. Forecasts reflect documented assumptions around regulatory permanence and raw material cost pass-through mechanisms. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Bulletproof Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Collision Avoidance System Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Emergency Stop Switches Market
Safety Equipment and Personal Protective Equipment (PPE)
US Industrial Barrier Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Guns Safes Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Solutions Market
Safety Equipment and Personal Protective Equipment (PPE)
Radar Speed Gun Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Seat Belt System Market
Safety Equipment and Personal Protective Equipment (PPE)
Self-Contained Breathing Apparatus (SCBA) Cylinders Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Power Air Purifying Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
South America Protective Coating Market
Safety Equipment and Personal Protective Equipment (PPE)
Surface Protection Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Healthcare Personal Protective Equipment (PPE) Market