
 US Safety Gloves Market | 2026-2036
US Safety Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
US Safety Gloves Market Intelligence
Modular glove systems that pair interchangeable liners with task-specific outer shells is restructuring how industrial buyers configure their PPE programs. Ansell leverages its polymer science portfolio to sustain premium positioning in chemical-resistant configurations. Honeywell anchors its distribution through integrated safety catalogs that bundle gloves with respiratory and eye protection. MCR Safety differentiates through vertical manufacturing control from yarn spinning to finished goods.
US safety gloves are engineered barrier devices constructed from woven, knitted, or dipped materials meeting ANSI/ISEA 105 mechanical performance benchmarks, designed to isolate human hands from thermal, chemical, cut, or impact hazards during industrial operations. Nitrile formulations dominate laboratory and food processing channels due to latex-allergy mitigation and chemical permeation resistance, while cut-resistant gloves integrating high-performance polyethylene yarns capture premium placement in metal fabrication and glass handling. Disposable nitrile and vinyl categories command volume leadership across healthcare-adjacent laboratory work, whereas heat-resistant and impact-resistant segments extract higher per-unit margins from oil and gas and mining end user industries where failure consequences escalate.
OSHA maintains enforceable hand-protection requirements under 29 CFR 1910.138, compelling employers to assess tasks and specify appropriate glove performance characteristics. ANSI/ISEA 105 revision cycles and FDA oversight of medical-grade disposable gloves further stratify product certification tiers and channel access. Stakeholders must track NIOSH research on emerging nanomaterial barriers and state-level California OSHA amendments that frequently prefigure federal rulemaking.
Market Dynamics
OSHA's accelerated enforcement of 29 CFR 1910.138 hand-protection standards is compressing compliance timelines and forcing industrial buyers to requalify their entire glove portfolios. ANSI/ISEA 105 revision cycles now drive specification rewrite frequency.
Growth Catalysts
- Texas Gulf Coast petrochemical expansion:Refinery and LNG terminal construction is generating concentrated demand for chemical-resistant and heat-resistant glove configurations across Beaumont-Port Arthur and Corpus Christi corridors.
- ANSI/ISEA 105-2016 cut-level standardization:Unified mechanical performance benchmarks enable procurement teams to specify A1-A9 ratings with confidence, reducing qualification friction in metal fabrication and glass handling.
- High-performance polyethylene yarn integration:Advanced fiber spinning techniques are lowering unit costs for cut-resistant gloves while maintaining A6-A9 protection levels.
Market Restraints
- Acrylonitrile price volatility:Nitrile glove feedstock costs fluctuate with crude oil derivatives and Asian spot market conditions, compressing margins for domestic formulators.
- Single-source dipping line concentration:Southeast Asian coating equipment suppliers control 70% of global capacity for multilayer chemical-resistant glove production.
- Permeation testing bottleneck:Finite NIOSH and third-party laboratory capacity extends certification timelines for novel barrier materials.
Strategic Opportunities
- Appalachian shale gas corridor:Pennsylvania and Ohio fracking operations remain underpenetrated for impact-resistant glove programs relative to Texas and North Dakota basins.
- Modular glove system adoption:Interchangeable liner-shell configurations allow safety managers to reduce SKU counts while maintaining task-specific protection.
- California OSHA Title 8 Section 3380 amendments:State-level heat illness prevention rules are expanding hand-cooling liner requirements in outdoor construction.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists with nitrile-Neoprene-PVC blending expertise command premium compensation and extended recruitment cycles.
- Legacy distributor ERP integration:Industrial supply houses struggle to map ANSI/ISEA performance codes to existing product master databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Safety Gloves Market |
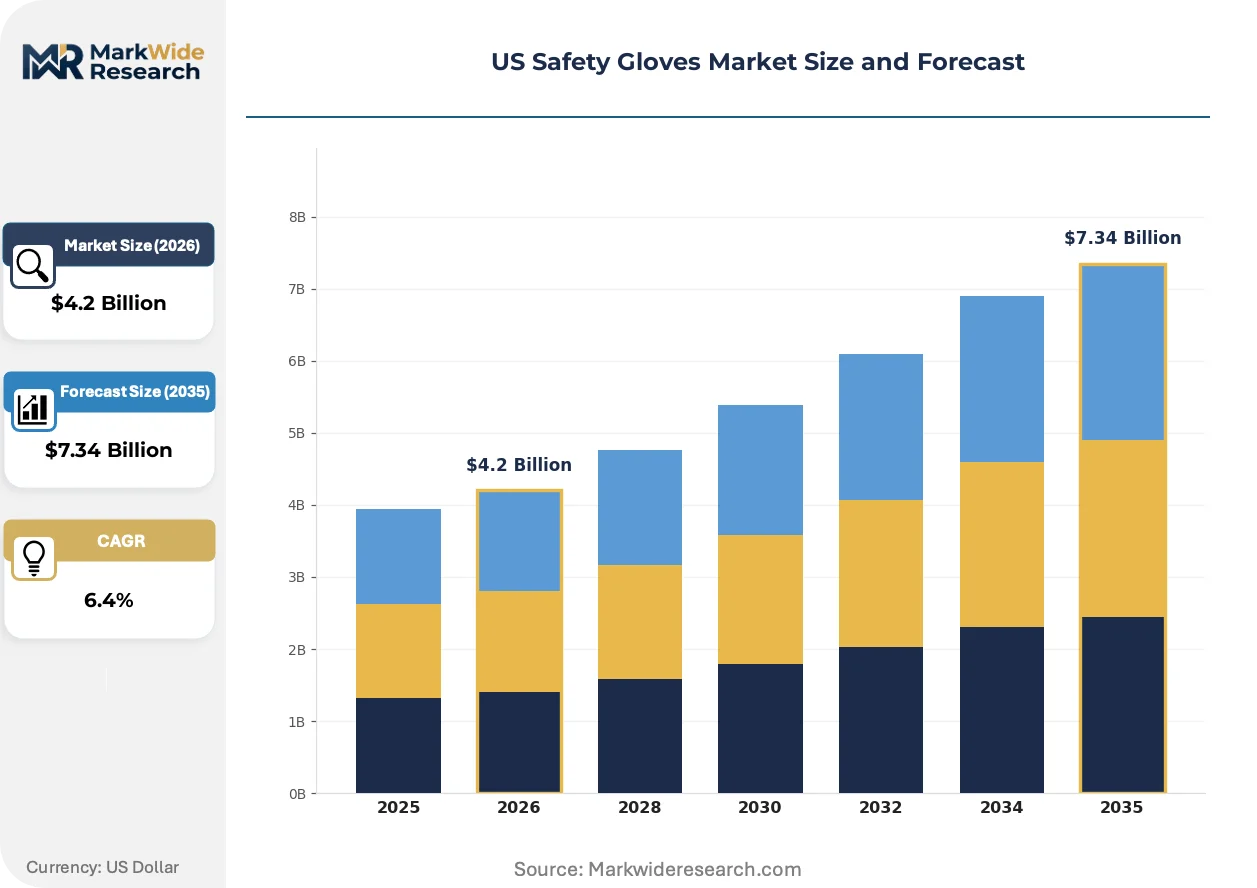
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $7.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Gloves, Cut-Resistant Gloves, Chemical-Resistant Gloves, Heat-Resistant Gloves, Impact-Resistant Gloves Material: Latex, Nitrile, Vinyl, Neoprene, Polyurethane, Synthetic Leather Application: Construction, Food Processing, Laboratory Work, Manufacturing, Electrical Work End User Industry: Oil & Gas, Pharmaceuticals, Agriculture, Automotive Suppliers, Mining |
| Companies Covered | W.W. Grainger, MCR Safety, 3M, Lakeland Industries, Honeywell, Ansell, Carolina Glove & Safety Company, SHOWA GROUP, Protective Industrial Products, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Safety Gloves Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory precision are converging to redefine barrier performance expectations. Buyers now demand validated protection metrics rather than generic durability claims.
Smart glove sensor integration is expanding into high-risk industrial environments. Embedded force and temperature monitors track hand exposure in real time during forging and foundry operations. Honeywell and MSA Safety pilot programs in Gulf Coast refineries demonstrate measurable reduction in thermal contact injuries. The technology is expanding into insurance-linked safety incentive programs where underwriters price premiums based on verified PPE utilization data.
OSHA's 2024 National Emphasis Program on heat hazards extends hand-protection requirements to outdoor construction crews. Employers must now assess evaporative cooling liner effectiveness alongside traditional mechanical performance. California OSHA's Title 8 amendments prefigure federal rulemaking, with Arizona and Nevada contractors already adopting compliant specifications. Roofing and masonry segments face the steepest compliance curve.
Specification-driven procurement now dominates enterprise accounts. Safety managers consolidate vendor lists to three approved suppliers with full ANSI/ISEA 105 test documentation. Group purchasing organizations negotiate master agreements bundling gloves with respiratory and fall protection. This consolidation is most visible in Texas and Louisiana petrochemical complexes where integrated safety catalogs displace spot-buying from industrial distributors.
US Safety Gloves Market Segmentation
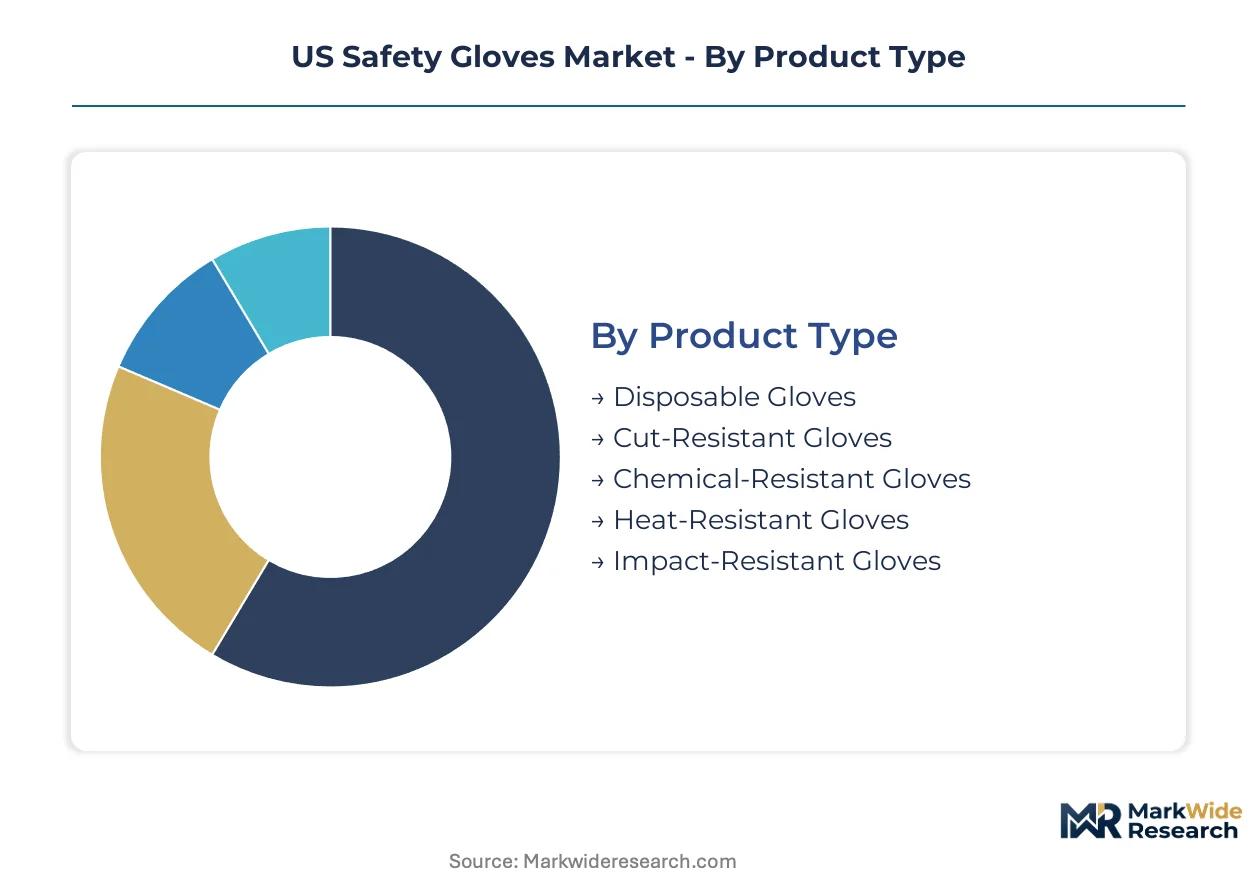
US safety gloves segment along four critical dimensions that dictate certification requirements and procurement workflows. Product type determines ANSI/ISEA 105 mechanical ratings and OSHA 29 CFR 1910.138 compliance burdens. Material selection drives FDA food-contact approvals or chemical permeation testing protocols.
Product Type:
Certification intensity varies sharply across glove categories, with chemical-resistant and cut-resistant configurations demanding the most extensive ANSI/ISEA 105 and ASTM F739 documentation.
- Disposable Gloves:Single-use nitrile and vinyl barriers dominate laboratory and food processing channels. FDA food-contact approvals and latex-allergy mitigation protocols drive specification in pharmaceutical cleanrooms across New Jersey and North Carolina research corridors.
- Cut-Resistant Gloves:High-performance polyethylene yarns deliver A6-A9 protection levels for metal fabrication. Texas and Louisiana petrochemical maintenance crews specify these for sheet metal handling during turnaround seasons.
- Chemical-Resistant Gloves:Multilayer nitrile-Neoprene-PVC blends isolate hands from solvents and caustics. Gulf Coast refineries mandate ASTM F739 permeation data for every SKU entering Beaumont-Port Arthur facilities.
- Heat-Resistant Gloves:Aramid and leather composites protect against thermal contact in foundry and forging operations. Ohio and Pennsylvania steel mills concentrate demand for aluminized outer shell configurations.
- Impact-Resistant Gloves:Thermoplastic rubber guards shield knuckles and fingers in oilfield and mining environments. North Dakota Bakken shale operations and West Virginia underground coal sites drive specification of ANSI/ISEA 138 impact-rated models.
Leading the category by volume: Disposable Gloves. Growing fastest: Cut-Resistant Gloves.
Material:
Raw material selection locks in cost tiers and performance ceilings, with petroleum-derived synthetics facing price volatility that reshapes margin structures.
- Nitrile:Acrylonitrile-butadiene formulations balance chemical permeation resistance with tactile sensitivity. Medical-grade variants require FDA 510(k) clearance, constraining supplier pools.
- Latex:Natural rubber delivers superior elasticity and grip in precision assembly tasks. Hospital procurement bans have collapsed demand outside niche industrial applications.
- Vinyl:Polyvinyl chloride offers lowest-cost barrier protection for short-duration tasks. California Prop 65 phthalate restrictions limit formulation flexibility.
- Neoprene:Chloroprene rubber resists oils, acids, and caustics across broad temperature ranges. Chemical-resistant glove premiums reflect chloroprene monomer cost volatility.
- Polyurethane:Thin, abrasion-resistant coatings enhance dexterity in electronics assembly. Cleanroom-grade versions command pricing multiples over standard industrial formulations.
- Synthetic Leather:Polyurethane-impregnated fabrics replace natural leather in welding and material handling. Heat-resistant variants incorporate aluminized backing for foundry proximity work.
Highest volume position: Nitrile. Steepest expansion trajectory: Polyurethane.
Application:
Task-specific hazard profiles determine glove replacement frequency and SKU complexity within customer safety programs.
- Construction:ANSI/ISEA 105 A4-A6 cut ratings and impact protection dominate roofing and framing specifications. California OSHA heat illness rules now mandate cooling liner compatibility.
- Food Processing:FDA Title 21 CFR compliance and HACCP program alignment drive disposable nitrile procurement. USDA-inspected poultry and beef plants in Georgia and Arkansas enforce color-coded glove protocols.
- Laboratory Work:Chemical permeation resistance per ASTM F739 and powder-free surfaces protect researchers. NIH-funded facilities require lot traceability and sterility documentation.
- Manufacturing:Task-specific mechanical protection spans assembly, material handling, and finishing operations. Michigan and Ohio automotive suppliers consolidate vendors to reduce qualification overhead.
- Electrical Work:ASTM D120 dielectric testing certifies voltage-rated rubber insulating gloves. Lineworkers in Texas ERCOT territory and California ISO zones require Class 00 through Class 4 ratings.
Dominant application by unit volume: Food Processing. Fastest specification growth: Electrical Work.
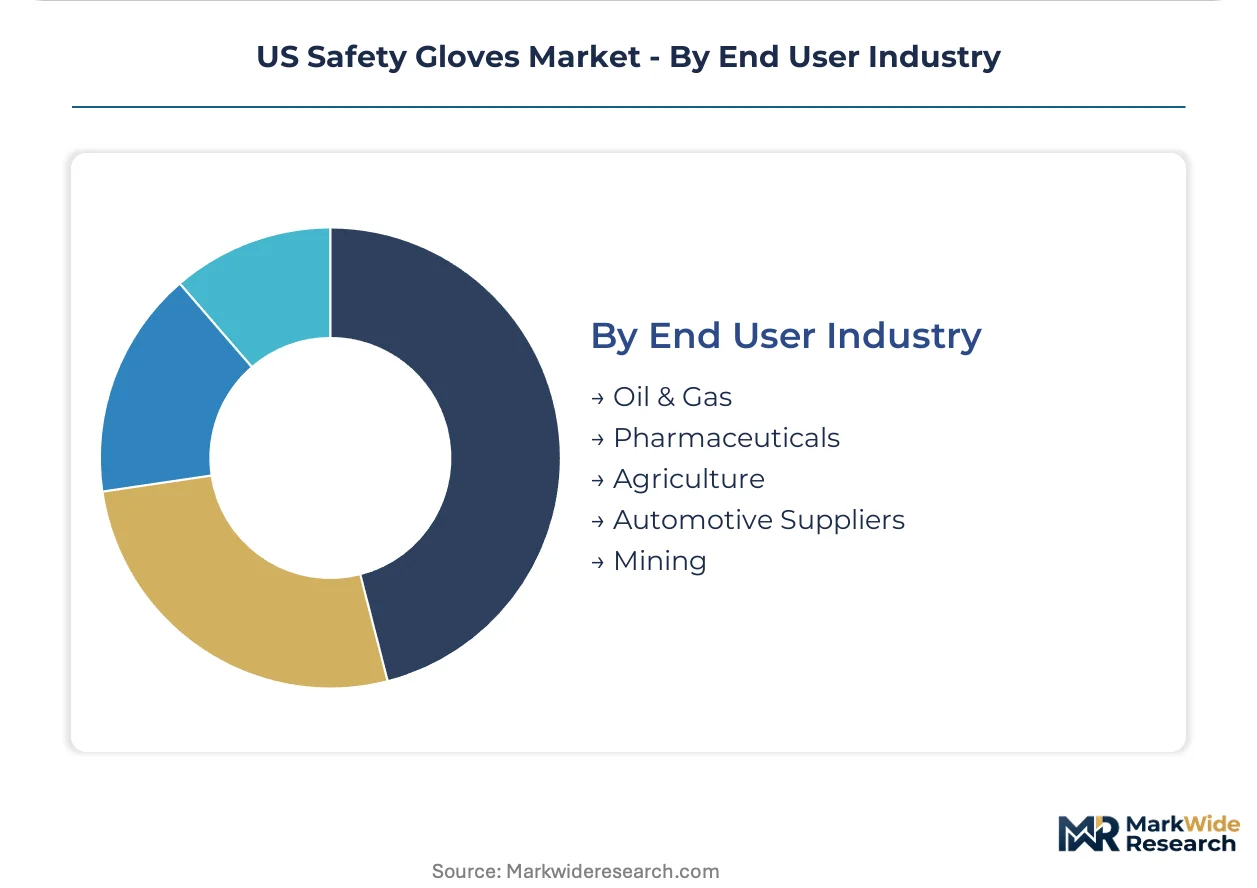
End User Industry:
Industry-specific failure consequences dictate pricing tolerance and performance validation requirements.
- Oil & Gas:Integrated operators specify impact-resistant and chemical-resistant configurations for upstream and downstream operations. ExxonMobil and Chevron master agreements bundle gloves with respiratory protection in Gulf Coast complexes.
- Pharmaceuticals:FDA-regulated manufacturing demands sterile, powder-free disposable gloves with extractables testing. New Jersey and Massachusetts biotech clusters enforce vendor lock-in through qualification protocols.
- Agriculture:Pesticide handling drives chemical-resistant nitrile and neoprene adoption in California Central Valley and Iowa corn belt operations. EPA Worker Protection Standard compliance audits intensify glove specification rigor.
- Automotive Suppliers:Tier 1 stamping and assembly plants specify cut-resistant and general-purpose mechanical gloves. Detroit Three supplier consolidation programs reduce approved vendor lists to three sources.
- Mining:MSHA enforcement drives impact-resistant and cut-resistant glove programs in underground coal and surface metal operations. Arizona copper and Nevada gold extraction sites concentrate demand for ANSI/ISEA 138-rated knuckle protection.
Volume leadership: Oil & Gas. Quickest specification expansion: Pharmaceuticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US safety glove production concentrates in Southeast textile corridors while consumption clusters in Gulf Coast petrochemical zones and Midwest manufacturing belts. This geographic mismatch shapes distribution networks and inventory positioning strategies across domestic supply chains.
Texas Gulf Coast
Refinery maintenance turnarounds and LNG terminal construction generate concentrated demand for chemical-resistant and heat-resistant configurations. OSHA enforcement of 29 CFR 1910.138 intensifies specification rigor across Beaumont-Port Arthur and Corpus Christi industrial complexes. ExxonMobil and Chevron master agreements bundle gloves with respiratory protection, consolidating vendor relationships.
Southeast Manufacturing Belt
North Carolina and Georgia textile infrastructure supports domestic glove fabrication from yarn spinning through finished goods. Georgia poultry processing plants enforce USDA color-coded disposable nitrile protocols. Charlotte and Greensboro distribution hubs serve automotive suppliers across the regional manufacturing corridor.
Midwest Industrial Core
Ohio and Michigan automotive stamping plants specify cut-resistant gloves for sheet metal handling. Detroit Three supplier consolidation programs reduce approved vendor lists to three sources. Cleveland and Toledo steel mills concentrate demand for aluminized heat-resistant outer shell configurations.
California
OSHA Title 8 Section 3380 heat illness prevention rules expand hand-cooling liner requirements in outdoor construction. Central Valley agriculture drives chemical-resistant nitrile adoption for pesticide handling under EPA Worker Protection Standard audits. Los Angeles and San Diego biotech clusters enforce FDA sterile glove qualification protocols.
Appalachian Shale Corridor
Pennsylvania and Ohio fracking operations remain underpenetrated for impact-resistant glove programs relative to Texas and North Dakota basins. Marcellus and Utica shale drilling activity concentrates around Pittsburgh and Youngstown metropolitan areas. MSHA enforcement drives specification of ANSI/ISEA 138-rated knuckle protection in underground operations.
US Safety Gloves Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Conglomerates leverage integrated safety catalogs that bundle gloves with respiratory and eye protection. Specialists exploit vertical manufacturing control from raw material processing through finished goods. Consolidation pressure intensifies as enterprise accounts reduce approved supplier lists to three sources. Capacity expansion and strategic partnerships represent the dominant competitive moves.
Among diversified industrial suppliers, W.W. Grainger and Honeywell occupy positions anchoring distribution through integrated safety catalogs. MCR Safety exemplifies the specialist archetype with manufacturing control spanning yarn spinning to finished goods. These three entities represent distinct strategic postures within a market where specification-driven procurement favors documented ANSI/ISEA 105 test compliance.
| Leading Market Players |
|---|
| W.W. Grainger |
| MCR Safety |
| 3M |
| Lakeland Industries |
| Honeywell |
| Ansell |
| Carolina Glove & Safety Company |
| SHOWA GROUP |
| Protective Industrial Products |
| Others |
Cost & Logistics Intelligence
Polymer formulation chemists concentrated in Southeast textile corridors command premium compensation that widens spreads between ANSI/ISEA 105-certified premium tiers and uncertified economy alternatives. Labor-cost differentials between domestic yarn-spinning operations and offshore dipping facilities feed directly into three-tier pricing structures across chemical-resistant glove categories.
Pricing Analysis
Margin tightening in disposable nitrile categories reflects acrylonitrile feedstock volatility tied to crude oil derivatives and Asian spot market conditions. Three-tier pricing structure across premium, standard, and economy levels stratifies by ANSI/ISEA 105 certification grade and ASTM F739 permeation documentation depth. Price differentiation hinges on NIOSH validation status and brand equity among Gulf Coast petrochemical buyers. Spot-buying distributors show highest price sensitivity, while integrated safety catalog purchasers accept premiums for bundled respiratory and fall protection programs.
Supply Chain Analysis
Direct-to-refinery channels handle ExxonMobil and Chevron master agreement volumes across Beaumont-Port Arthur and Corpus Christi corridors. Raw material supply draws from Southeast Asian acrylonitrile producers, domestic high-performance polyethylene yarn spinners in North Carolina, and chloroprene monomer facilities in Louisiana. Southeast Asian coating equipment suppliers control multilayer chemical-resistant glove production capacity, creating single-source vulnerability for domestic formulators. Distribution runs through industrial supply houses, group purchasing organizations, and integrated safety catalogs serving Texas and Louisiana petrochemical complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSHA's 29 CFR 1910.138 hand-protection standards erect a compliance moat that rewards incumbents with documented ANSI/ISEA 105 test portfolios while filtering out undercapitalized entrants lacking NIOSH relationship access.
For Market Incumbents: To counter modular glove system disruption from Ansell and Honeywell, deepen backward integration into high-performance polyethylene yarn spinning and expand captive coating capacity in Georgia textile corridors. Anchor distribution through integrated safety catalogs that bundle gloves with respiratory protection to lock in Chevron and ExxonMobil master agreements. For New Entrants and Emerging Players: Enter via Pennsylvania and Ohio fracking operations where impact-resistant glove penetration lags Texas and North Dakota basins. Target MSHA-regulated underground coal sites in West Virginia and Arizona copper extraction facilities with ANSI/ISEA 138-rated knuckle protection. Pursue private-label partnerships with Charlotte and Greensboro distribution hubs serving automotive supplier consolidation programs. For Investors and Strategic Acquirers: The window for entry favors vertically integrated specialists with polymer science R&D capabilities and existing NIOSH testing relationships. Acquire mid-cap manufacturers with in-house yarn spinning through finished goods control and established Gulf Coast petrochemical customer access. Watch California OSHA Title 8 Section 3380 amendment adoption rates in Arizona and Nevada as signal for federal heat illness rulemaking timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Yarn Spinning | Captive high-performance polyethylene supply secures A6-A9 cut-level rating consistency for metal fabrication customers. |
| NIOSH Partnership Expansion | Preferred permeation testing access compresses ASTM F739 certification timelines for novel barrier materials. |
| Modular Glove System Launch | Interchangeable liner-shell configurations reduce SKU counts for safety managers at Texas Gulf Coast refineries. |
| Integrated Safety Catalog Bundling | Respiratory and fall protection pairing locks in multi-year master agreements with Chevron and ExxonMobil. |
| Appalachian Shale Corridor Penetration | Impact-resistant glove programs capture underpenetrated Marcellus and Utica drilling operations around Pittsburgh. |
Research Approach
OSHA enforcement bulletins, ANSI/ISEA 105 revision documentation, and NIOSH permeation research databases formed the secondary backbone for this analysis. Primary interviews with safety procurement managers at Gulf Coast petrochemical complexes, polymer formulation chemists in Southeast textile corridors, and distribution channel partners in Charlotte and Greensboro validated segment sizing assumptions. Bottom-up SKU-level demand modeling triangulated against top-down end-use industry expenditure analysis across construction, oil and gas, and automotive supplier verticals.
Historical trendline analysis of glove procurement volumes tracked specification shifts following ANSI/ISEA 105-2016 standardization and OSHA National Emphasis Program expansions. Segmentation modeling spanned product type, material formulation, application task profile, and end-use industry failure-consequence tier. CAGRs were derived from regression analysis against petrochemical capital expenditure cycles, automotive production forecasts, and MSHA enforcement intensity patterns. Feedstock cost indices for acrylonitrile and chloroprene monomer informed margin trajectory assumptions.
Revisions become necessary when OSHA rulemaking accelerates beyond current enforcement timelines, when Southeast Asian coating equipment capacity constraints deepen, or when California OSHA amendments trigger federal preemption challenges. Periodic stress-testing of base assumptions against NIOSH research publication schedules and state-level regulatory adoption curves is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Global above the Waist PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Explosion-Proof Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Machine Guarding Fence Market
Safety Equipment and Personal Protective Equipment (PPE)
Isolation Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Seat Belt System Market
Safety Equipment and Personal Protective Equipment (PPE)
Eye Wash Stations Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Light Curtains Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Scuba Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Motorcycle Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Technologies Market
Safety Equipment and Personal Protective Equipment (PPE)
Spill Kits Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Protection Glasses Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Protection System Market