
 Supplementary Protectors Market | 2026-2036
Supplementary Protectors Market Size, Share, and Industry Trends Forecast 2026-2036
Supplementary Protectors Market Analytics
Modular breaker configurations is repositioning how facility managers specify overcurrent protection, moving from standalone units to integrated panel systems. Eaton leverages its circuit protection portfolio to anchor North American industrial accounts. Siemens differentiates through IEC-certified product lines that dominate European infrastructure retrofits. Schneider Electric extends its footprint via channel partnerships in commercial building automation.
Supplementary protectors are electromechanical devices designed to open a circuit automatically on overcurrent conditions, typically rated below branch-circuit protection thresholds with trip characteristics calibrated to 1.15 to 1.45 times rated current. They safeguard control circuits, appliances, and industrial equipment where standard breakers would permit damaging current levels to persist. Polycarbonate-housed units lead in medical device applications due to sterilization compatibility and dielectric strength, while nylon variants occupy the automotive segment where cost-efficient vibration resistance matters. Foam and rubber configurations remain niche, serving sports gear and portable electronics where impact absorption rather than thermal protection drives specification.
UL 1077 governs supplementary protector construction and performance in the United States, while IEC 60947-2 shapes European product acceptance and the CCC mark controls market entry in China. These frameworks elevate testing costs but create barriers against uncertified imports, concentrating procurement among validated suppliers. Stakeholders must monitor evolving harmonization between UL and IEC trip curves, as divergence in standards continues to fragment global product platforms and complicate inventory strategies.
Market Dynamics
Industrial automation adoption across automotive assembly lines is compressing trip response requirements and forcing recalibration of protector sensitivity curves. Facility managers now specify integrated panel systems rather than standalone units, restructuring procurement relationships and technical validation workflows.
Growth Catalysts
- Automotive electrification:EV powertrain manufacturing in Germany's Stuttgart-Munich corridor demands precision overcurrent protection for battery management systems. Assembly line automation requires supplementary protectors with faster trip characteristics.
- UL 1077 harmonization pressure:US electrical safety tightening elevates certified product demand. Industrial accounts now mandate third-party validation for control circuit protection.
- Polycarbonate housing penetration:Medical device sterilization protocols favor dielectric-stable materials. Surgical equipment OEMs specify these variants for autoclave compatibility.
Market Restraints
- Copper and silver contact volatility:Raw material price swings compress margin predictability for electromechanical assembly. Suppliers face hedging complexity.
- Testing laboratory concentration:UL and IEC certification dependence on limited accredited facilities creates queue bottlenecks. Validation timelines extend unpredictably.
- Solid-state circuit breaker substitution:Silicon carbide-based alternatives threaten traditional electromechanical protector relevance in high-frequency applications.
Strategic Opportunities
- India manufacturing expansion:PLI scheme incentives for industrial automation create fresh demand for IEC-compliant control circuit protection. Domestic production waivers reduce import duty exposure.
- Building automation convergence:Integration of fire safety, HVAC, and electrical monitoring systems creates specification pull for multi-function panel-mounted protectors.
- CSRD disclosure mandates:European corporate sustainability reporting requirements elevate energy-efficient protection device preference. Lifecycle carbon footprint now factors in procurement scoring.
Industry Challenges
- Trip curve calibration expertise scarcity:Field engineers with UL 1077 and IEC 60947-2 dual competency command premium compensation. Training pipelines lag automation deployment speed.
- Legacy panel retrofit friction:Existing MCC infrastructure uses incompatible mounting standards. Upgrade projects stall on physical dimension mismatches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Supplementary Protectors Market |
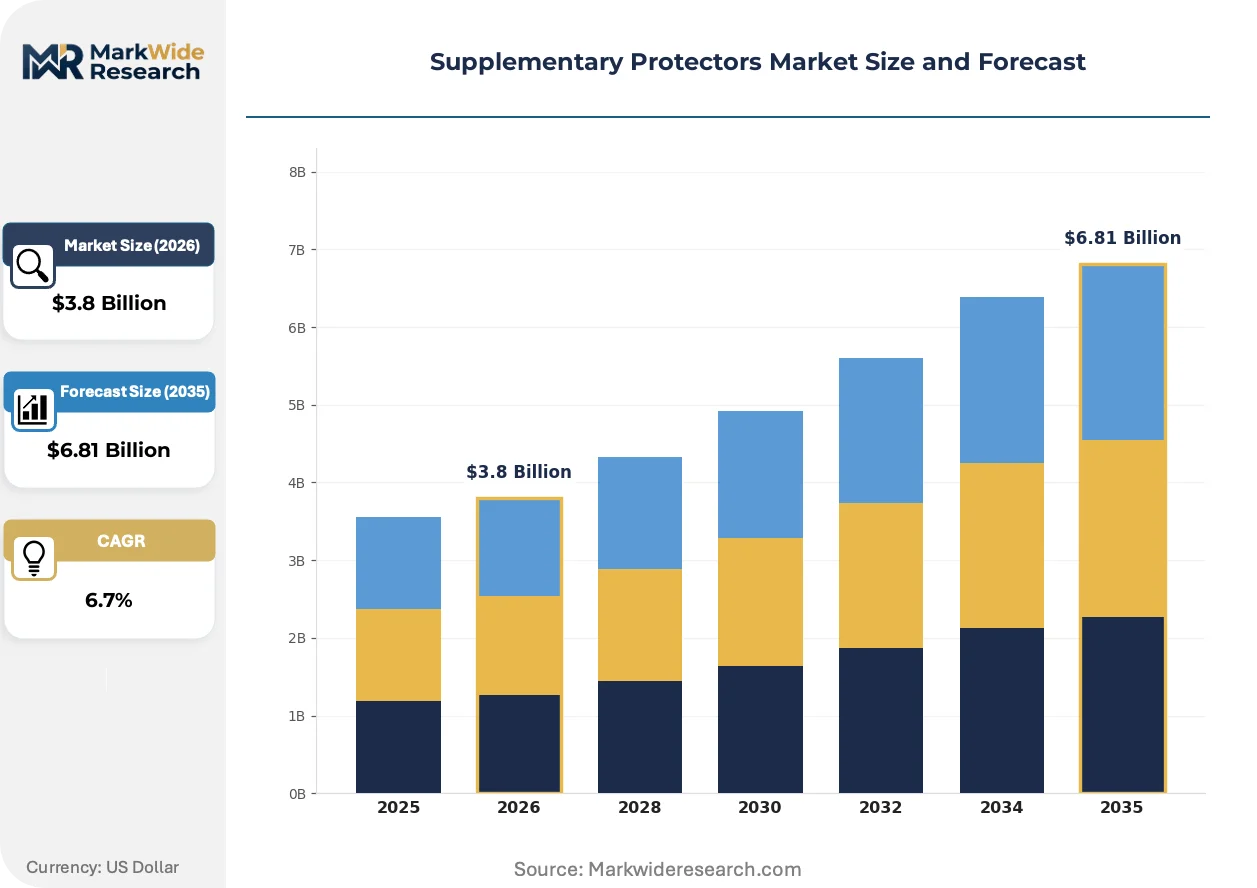
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shields, Covers, Pads, Guards Material: Polycarbonate, Nylon, Rubber, Foam Application: Medical Devices, Electronics, Sports Gear, Automotive End User: Consumers, Manufacturers, Healthcare Providers, Distributors |
| Companies Covered | Eaton, Rockwell Automation, General Electric, Siemens, Schneider Electric, ABB, Sprecher + Schuh, OMEGA Engineering, CG Power, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Supplementary Protectors Market Evolving Landscape
Digital trip units and communication-enabled protection devices are redefining how facility operators monitor and respond to electrical faults. Real-time data streams now supplement electromechanical interruption with predictive analytics.
Smart supplementary protectors with embedded current sensors and Modbus connectivity are integrating into building management system architectures. Automotive OEMs in Germany specify these for assembly line predictive maintenance programs. The technology is integrating operational technology and information technology domains, compressing response times from minutes to milliseconds.
REACH substance restrictions on halogenated flame retardants are forcing housing material reformulation. European manufacturers now validate phosphorus-based alternatives for polycarbonate grades. Medical device exporters to the EU face supply chain recertification costs.
Specification authority is migrating from electrical contractors to facility energy managers. Centralized procurement teams now mandate standardized trip curves across multi-site portfolios. This concentration is most visible in German automotive supplier networks, where tier-one manufacturers enforce uniform protection standards on subordinate equipment vendors.
Supplementary Protectors Market Segmentation
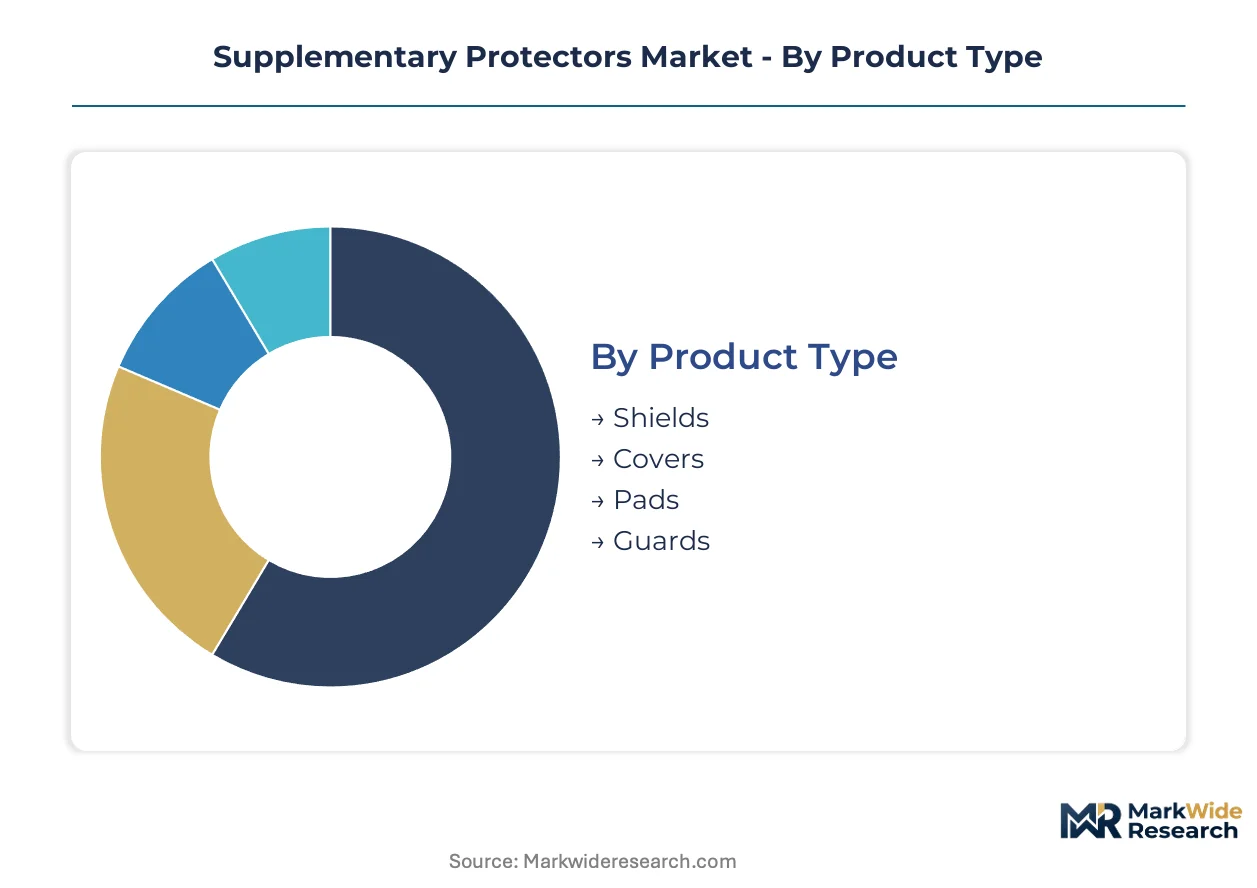
Segmentation in supplementary protectors reveals divergent specification logics across electromechanical and passive protection applications. Product architecture, material science, and end-use certification requirements create distinct procurement channels with incompatible technical validation workflows.
Product Type:
Standalone shielding components dominate replacement markets, while embedded configurations anchor OEM supply agreements with longer validation cycles.
- Shields:Rigid barriers engineered from dielectric-grade polymers that isolate live conductors in control panels. Demand clusters in German automotive supplier networks where IEC 60947-2 compliance is mandatory for tier-one vendor qualification.
- Covers:Molded housings that enclose terminal blocks and breaker mechanisms, rated for IP40-IP65 ingress protection. Medical device OEMs in Stuttgart specify autoclavable variants for surgical equipment integration.
- Pads:Compressible interface layers that damp vibration in mobile equipment. Construction machinery accounts in Bavaria drive specification for these accessories.
- Guards:Mechanical interlocks preventing accidental contact with trip mechanisms. Industrial automation retrofits across Munich manufacturing corridors absorb volume.
Volume placements concentrate in Shields; the faster expansion belongs to Covers.
Material:
Cost tier stratification separates medical-grade certified supply from commodity automotive sourcing, with housing material selection driving 40-60% of unit economics variance.
- Polycarbonate:Amorphous thermoplastic with dielectric strength exceeding 15 kV/mm and gamma sterilization stability. Surgical equipment manufacturers in Germany's medical technology cluster specify these for reusable device housings facing REACH flame-retardant compliance.
- Nylon:Semi-crystalline polyamide offering cost-efficient vibration damping and fuel resistance. Stuttgart-area EV powertrain assemblers favor these for under-hood control circuit protection.
- Rubber:Elastomeric compounds providing impact absorption and environmental sealing. Sports equipment OEMs specify these for portable electronics protection.
- Foam:Lightweight cellular structures for energy dissipation in consumer applications. Niche demand from fitness device manufacturers persists.
Polycarbonate commands the premium tier; nylon captures the steepest expansion trajectory as automotive electrification accelerates.
Application:
Certification intensity varies sharply across end-use segments, with medical and automotive applications imposing 3-5x longer validation timelines than consumer electronics.
- Medical Devices:Autoclave-compatible supplementary protectors for diagnostic and surgical equipment. German hospital procurement consortia now mandate CSRD-aligned lifecycle carbon disclosure for device suppliers.
- Electronics:Circuit board-mounted protection for consumer and industrial control systems. Volume concentrates in contract manufacturing serving building automation integrators.
- Sports Gear:Impact-resistant housings for wearable fitness technology. Specification authority sits with brand owners rather than electrical engineers.
- Automotive:Battery management system protection for EV powertrains. Stuttgart-Munich corridor assemblers specify IEC 60947-2 certified variants with sub-10ms trip characteristics.
Automotive applications are gaining share fastest; medical devices retain the highest margin structure.
End User:
Procurement concentration distinguishes centralized industrial buyers from fragmented consumer channels, with distributor intermediation varying by technical complexity.
- Consumers:Retail purchasers of replacement protectors for residential appliances. Price sensitivity drives private-label penetration in this channel.
- Manufacturers:OEMs integrating supplementary protectors into finished equipment. German automotive and medical device producers enforce supplier consolidation programs.
- Healthcare Providers:Hospital procurement departments specifying certified protection for clinical equipment. Biomedical engineering departments now control technical validation.
- Distributors:Electrical wholesalers and industrial supply houses managing inventory for contractor accounts. Channel partners in Bavaria report lengthening lead times for IEC-certified stock.
Manufacturer direct procurement dominates value capture; healthcare provider specification authority is expanding most quickly as centralized purchasing matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing clusters in Germany and the United States generate concentrated demand for IEC and UL-certified supplementary protectors, while assembly operations in China and Mexico absorb volume for export-oriented electronics and automotive production.
United States
Industrial automation retrofits across Michigan and Ohio automotive plants drive specification of UL 1077-certified control circuit protection. OSHA electrical safety enforcement tightens validation requirements for panel-mounted devices. Chicago-area electrical distributors report lengthening lead times for certified stock serving the Midwest manufacturing belt.
Germany
EV powertrain assembly in the Stuttgart-Munich corridor demands supplementary protectors with sub-10ms trip characteristics for battery management systems. REACH substance restrictions on halogenated flame retardants force polycarbonate housing reformulation. Bavarian medical device OEMs specify autoclave-compatible variants for surgical equipment integration.
China
Export-oriented electronics contract manufacturers in the Pearl River Delta absorb volume for circuit board-mounted protection devices. CCC mark requirements control market entry for imported supplementary protectors. Shenzhen-based industrial automation integrators specify IEC-compliant variants for regional infrastructure projects.
India
PLI scheme incentives for industrial automation create fresh demand for IEC-compliant control circuit protection in Maharashtra and Gujarat manufacturing zones. BIS certification requirements elevate testing costs for electromechanical assembly imports. Tamil Nadu automotive suppliers specify supplementary protectors for EV component production lines.
Japan
Precision equipment manufacturers in the Nagoya industrial corridor specify high-sensitivity supplementary protectors for semiconductor fabrication tools. METI energy efficiency standards elevate preference for low-power-consumption protection devices. Osaka-area electrical component distributors consolidate procurement around validated IEC-certified suppliers.
Supplementary Protectors Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across certification-intensive segments. The vendor base stratifies into three tiers: global electrical equipment conglomerates with circuit protection portfolios, regional specialists concentrated in single certification regimes, and contract manufacturers serving private-label demand. Dominant competitive moves include channel partnership expansion in building automation and backward integration into contact material processing.
Among diversified electrical equipment conglomerates, Eaton, Siemens, and Schneider Electric exemplify archetype positioning. Eaton anchors North American industrial accounts through circuit protection portfolio breadth. Siemens occupies a position calibrated to European infrastructure retrofit demand via IEC-certified product lines. Schneider Electric represents channel partnership strategies in commercial building automation convergence. These three entities sit within the tier where certification breadth and geographic coverage determine procurement eligibility.
| Leading Market Players |
|---|
| Eaton |
| Rockwell Automation |
| General Electric |
| Siemens |
| Schneider Electric |
| ABB |
| Sprecher + Schuh |
| OMEGA Engineering |
| CG Power |
| Others |
Value Network & Pricing Analysis
Dual-competency field engineers in Germany's Stuttgart-Munich corridor command premium compensation, widening spreads between UL 1077 and IEC 60947-2 certified product tiers as labor-cost differentials transmit directly into specification premiums.
Pricing Analysis
Margin tightening in standard-grade polycarbonate units reflects REACH-driven flame-retardant reformulation costs. Three-tier pricing structure across premium, standard, and economy levels separates autoclave-validated medical variants from automotive nylon grades and commodity foam configurations. Price differentiation hinges on certification tier and volume scale, with healthcare procurement consortia showing lowest sensitivity and consumer replacement channels most responsive to cost-down pressure.
Supply Chain Analysis
Workforce scarcity in electromechanical assembly clusters across Germany, China, and Mexico constrains contact material processing capacity. Copper and silver contact sourcing draws from concentrated mining jurisdictions, while polycarbonate resin supply rests on petrochemical feedstock availability. Single-source vulnerability in UL and IEC testing laboratory accreditation creates validation queue bottlenecks. Distribution runs through electrical wholesalers and industrial supply houses serving contractor accounts in regional manufacturing belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Testing laboratory capacity constraints prop pricing power for validated suppliers, as IEC and UL accreditation queues extend validation timelines unpredictably.
For Market Incumbents: Extend certification breadth into dual UL 1077 and IEC 60947-2 product platforms to capture cross-border procurement consolidation. Solid-state circuit breaker substitution threatens traditional electromechanical relevance; backward integration into silver contact material processing defends margin position against raw material volatility. For New Entrants and Emerging Players: Launch via private-label supply to electrical distributors in India's Maharashtra and Gujarat manufacturing zones, where PLI scheme automation incentives outpace domestic certified supplier capacity. Building automation convergence creates specification pull for communication-enabled protection devices with Modbus connectivity. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap specialists holding captive IEC testing relationships given harmonization pressure between UL and IEC trip curve standards. Long-term viability favors suppliers with validated phosphorus-based flame-retardant formulations aligned with REACH substance restrictions. Watch for BIS certification timeline compression in India as inflection signal for regional manufacturing shift.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | UL 1077 and IEC 60947-2 validation unlocks cross-border procurement eligibility for German automotive supplier networks. |
| Backward Integration into Contact Materials | Captive copper and silver contact processing hedges raw material price swings compressing electromechanical assembly margins. |
| Smart Protection Device Launch | Embedded current sensors with Modbus connectivity integrate into building management system architectures for predictive maintenance. |
| Regional Manufacturing Expansion | PLI scheme incentives in India reduce import duty exposure for IEC-compliant control circuit protection devices. |
| Phosphorus-Based Flame-Retardant Reformulation | REACH-compliant polycarbonate grades preserve EU market access for medical device sterilization applications. |
Research Methodology
Trade databases, regulatory filing repositories, and industry association technical standards formed the secondary backbone. Primary interviews with facility energy managers, electrical contractor procurement leads, OEM specification engineers, and testing laboratory accreditation officers combined with customs records and SEC 10-K segment disclosures. Bottom-up unit shipment estimates and top-down manufacturing value-added analysis underwent triangulation validation.
Historical trendline analysis of polycarbonate and nylon resin pricing, contact material cost structures, and certification timeline patterns informed projection parameters. Segmentation modeling spanned product architecture, housing material grade, end-use application intensity, and regional regulatory cluster. CAGRs derived from curve-fitting against automation deployment rates and electrification capital expenditure trajectories. Forecast inputs included EV powertrain assembly line counts and hospital procurement consortium standardization mandates.
Copper price volatility, testing laboratory queue extensions, and solid-state circuit breaker substitution acceleration are the dominant revision risks. Forecasts reflect assumptions around harmonization pace between UL and IEC standards. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Smart PPE Technology Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Explosion Proof Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Explosion Proof Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Public Address and Voice Alarm Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Machine Guarding Fence Market
Safety Equipment and Personal Protective Equipment (PPE)
Germany Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Global above-The-Neck PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Laser Safety Glasses Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Protective Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Armoured Thermocouple Market
Safety Equipment and Personal Protective Equipment (PPE)
Head Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Welding Helmets Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Prefilled Safety Device Market