
 Global Emergency Stop Switches Market | 2026-2036
Global Emergency Stop Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Global Emergency Stop Switches Market Intelligence
The integration of software-defined safety logic into control systems is recalibrating the value proposition beyond the physical switch. Siemens AG leverages its extensive automation portfolio to embed these features, linking switches to its broader digital factory ecosystem. Schneider Electric differentiates through its EcoStruxure platform by offering connected safety solutions. Omron Corporation specializes in advanced sensing and control technologies that complement its safety switch offerings in automated manufacturing.
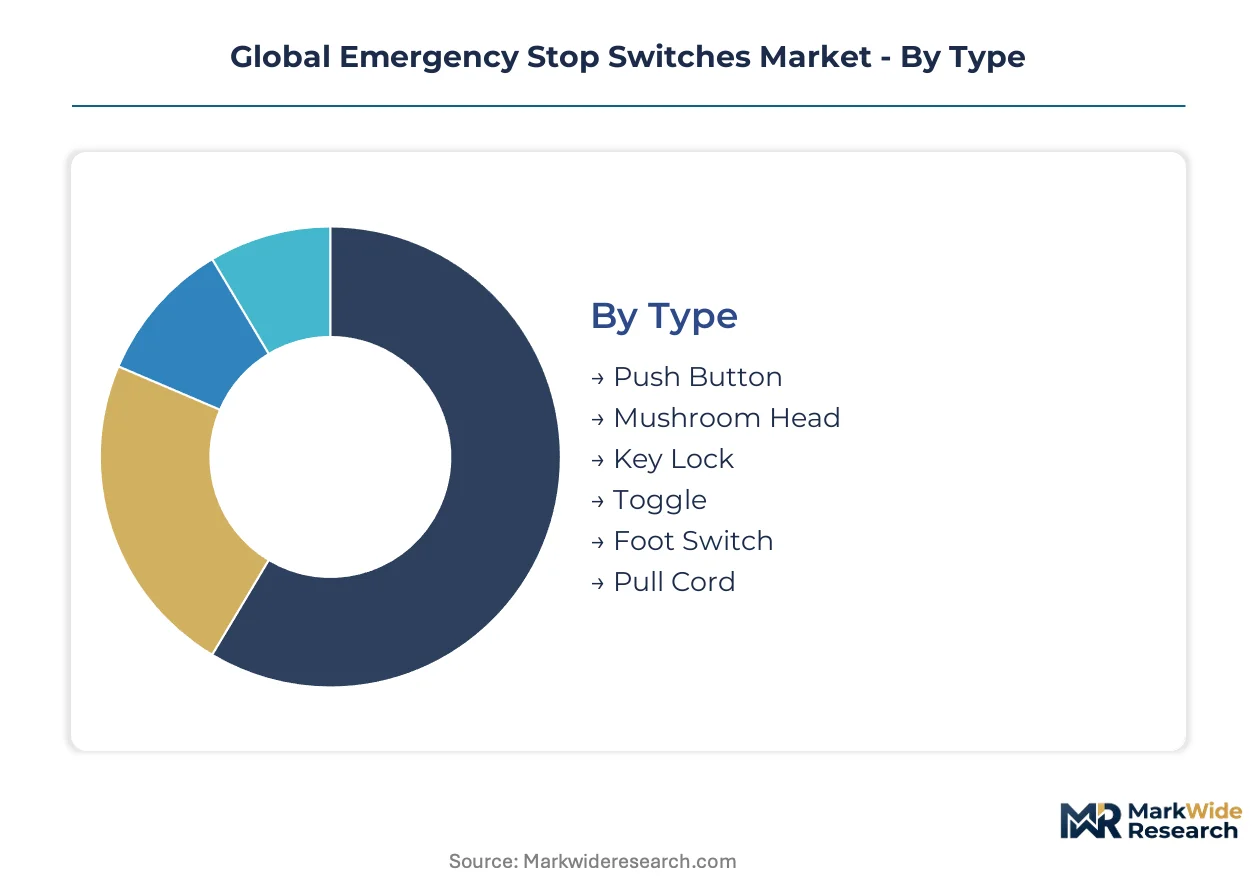
An emergency stop switch is a fail-safe control mechanism designed to halt machinery function during a hazardous event. These devices are engineered with a positive opening operation, forcing electrical contacts apart upon activation to guarantee a stop command. Mushroom head push buttons dominate the market by type, favored for their high visibility in busy manufacturing plants. Pull cord switches serve critical applications like long conveyor lines found in mining operations and large-scale packaging facilities.
Global standards, particularly ISO 13850, define the functional requirements and design principles for emergency stop equipment. Regional compliance, such as UL 508 in the United States and the EU Machinery Directive's CE marking, is mandatory for market access and dictates product testing protocols. Stakeholders must monitor the evolution of wireless safety protocols and their integration into existing machine control architectures.
Market Dynamics
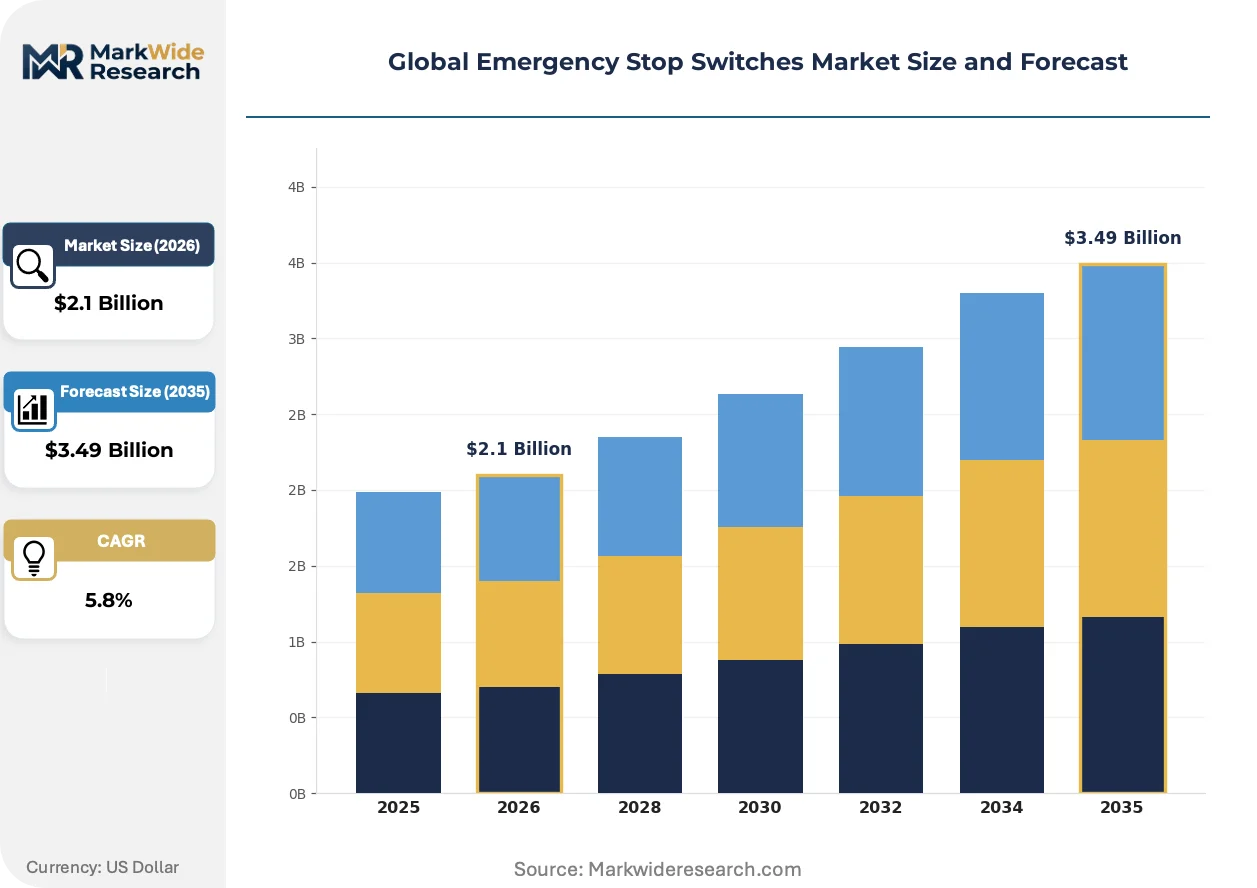
The market's fundamental dynamic is the shift from viewing emergency stop switches as standalone hardware to integrating them as data-rich nodes within software-defined industrial safety networks, driven by automation complexity and stringent functional safety mandates.
Growth Catalysts
- Regulatory Compliance:Mandates including ISO 13850 and the EU Machinery Directive make certified emergency stop devices a prerequisite for machine operation and market access.
- Automation in Logistics:The expansion of automated warehousing and conveyor systems requires extensive safety stop integration to protect workers interacting with equipment.
- Modernization in China:Government-led upgrades to China’s manufacturing sector, emphasizing worker safety, create substantial and consistent demand for safety components.
Market Restraints
- Substitution by Software:Integrated safety functions in motor drives, such as Safe Torque Off, can fulfill certain risk reduction tasks, though not fully replace physical E-stops.
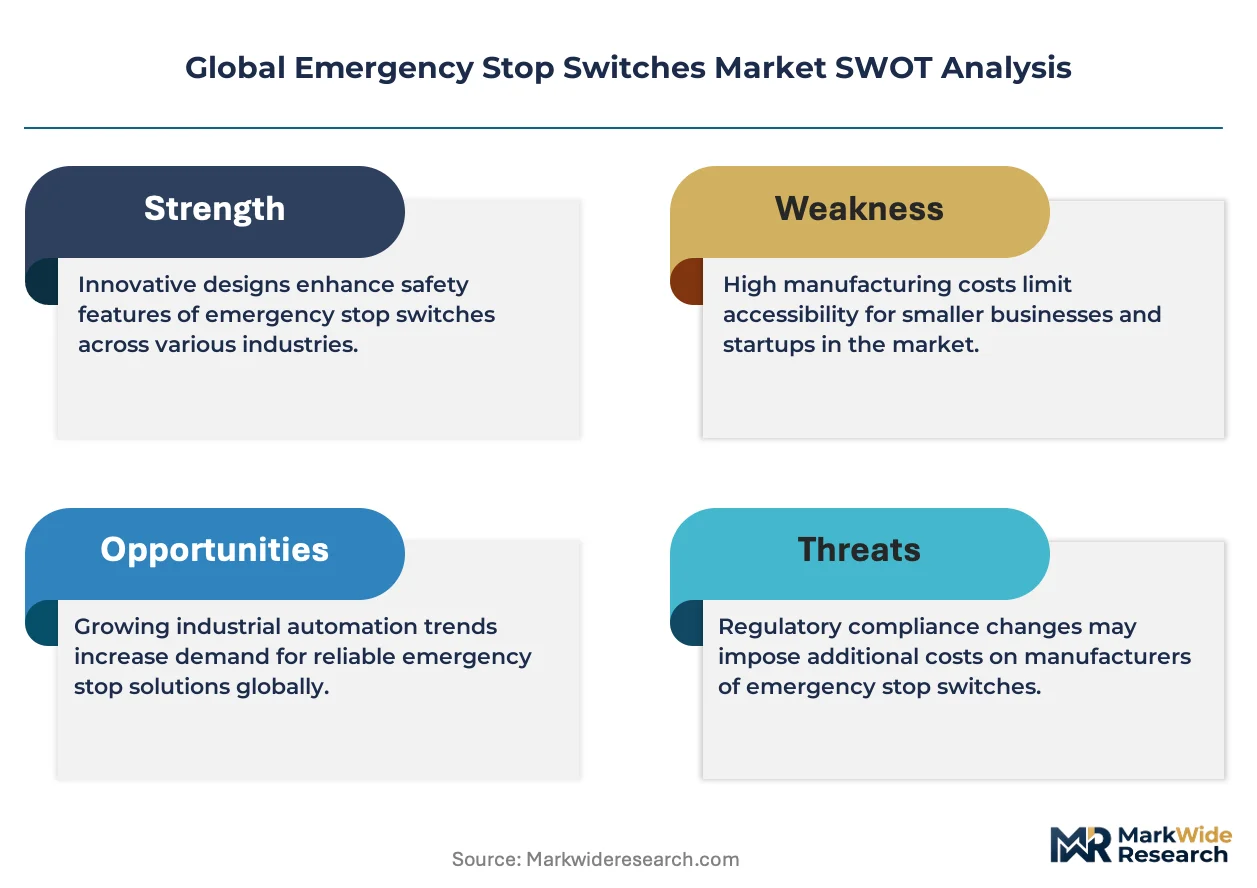
- Certification Costs:High costs and long lead times for achieving multiple regional certifications like UL and CE create significant barriers for smaller component suppliers.
- Legacy System Integration:Integrating modern networked safety devices with older hardwired machine controls is expensive and complex, often delaying necessary safety upgrades.
Strategic Opportunities
- Wireless Technology:Certified wireless E-stops can serve mobile robotics and modular production lines where cabling is impractical, creating new application areas.
- Industrializing Economies:Markets in Southeast Asia and Latin America represent growth frontiers as their industrial bases expand and safety standard adoption accelerates.
- Smart Diagnostics:Integrating diagnostics via IO-Link to predict switch wear or tampering offers a value-added service beyond basic stop functionality.
Industry Challenges
- Counterfeit Components:The proliferation of non-certified and counterfeit safety switches, particularly through online marketplaces, poses significant liability and safety risks to end-users and machine builders.
- Harmonization of Standards:Navigating subtle differences between regional safety standards, such as those from UL in the US and CE marking requirements in Europe, complicates product design and testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Emergency Stop Switches Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Push Button, Mushroom Head, Key Lock, Toggle, Foot Switch, Pull Cord Technology: Mechanical, Electrical, Pneumatic, Magnetic, Electronic, Hydraulic Application: Manufacturing Plants, Construction Sites, Mining Operations, Food Processing, Packaging Lines, Chemical Processing End User: Heavy Machinery Operators, Industrial Automation, Facility Management, Safety Inspection Teams |
| Companies Covered | ABB, EAO Corporation, Eaton Corporation, Honeywell International Inc., Schneider Electric, Siemens AG, Omron Corporation, REMA Group, REES Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Emergency Stop Switches Market Strategic Shifts & Innovations
The evolution from standalone electromechanical devices to intelligent, network-aware safety components is the defining trend. This shift prioritizes system-level integration, data generation, and compliance with performance-based safety standards over simple hardware specifications.
Wireless safety communication is emerging as a critical enabling technology. These systems use secure, low-latency protocols to connect emergency stop devices without physical wiring, a key advantage for mobile equipment. The packaging and intralogistics sectors are early adopters for flexible conveyor lines, and this technology is converging with industrial 5G networks to enable large-scale, dynamic safety zones.
Performance-based safety standards are becoming more stringent and quantitative. Regulations like Europe's IEC 62061 require machine builders to calculate and document the Safety Integrity Level (SIL) for their entire safety function. This affects component selection profoundly, as switch manufacturers must now provide certified reliability data to support these system-level calculations.
Ecosystem-based purchasing now influences component selection significantly. End-users favor safety switches that integrate seamlessly into a single vendor's automation platform, simplifying programming, diagnostics, and maintenance. This procurement trend is most visible in Germany's advanced manufacturing sector, where holistic system integration is a core competitive factor.
Global Emergency Stop Switches Market Segmentation
Market segmentation provides a granular understanding of how emergency stop switches are adopted across diverse industrial settings. This analysis helps stakeholders identify specific demand patterns and technology preferences, crucial for product development and market penetration strategies. Understanding these distinct segments illuminates pathways for innovation and compliance within the safety component sector.
Type:
The upgrade and replacement cycles for emergency stop switches often depend on the specific physical design and operational context of the machinery. Older installations frequently rely on basic electromechanical types, while modern automated systems integrate more advanced variants. Regulatory updates also drive transitions to newer, certified switch types.
- Mushroom Head:These highly visible, large-actuator switches are designed for immediate, unambiguous activation in critical situations. Demand concentrates in manufacturing plants, driven by stringent worker safety regulations and the need for quick access.
- Pull Cord:Utilized for extended machinery or conveyor lines, these switches allow activation from any point along their length. Mining operations and large-scale logistics facilities represent significant demand, requiring continuous safety coverage across long distances.
- Push Button:Standard, compact switches often integrated into control panels for localized machine shutdown.
- Key Lock:These switches prevent unauthorized reset, ensuring machinery remains stopped until a supervisor intervenes.
- Toggle:Less common for primary emergency stops, these are sometimes used for auxiliary or maintenance-specific lockout functions.
- Foot Switch:Offers hands-free operation, valuable in applications where operators' hands are occupied.
Mushroom Head switches sit at the top of the volume ranking, with Pull Cord switches climbing the fastest in specific high-volume applications.
Technology:
The choice of emergency stop switch technology is heavily influenced by the existing control architecture and the required Safety Integrity Level (SIL). Integration into modern control systems favors electronic and electrical solutions. Legacy systems often retain mechanical or pneumatic options due to cost and simplicity.
- Electrical:These switches directly interrupt electrical circuits to cut power, forming the backbone of most industrial safety systems. Manufacturing plants and automated assembly lines drive substantial demand, requiring reliable power interruption.
- Electronic:Integrating with programmable logic controllers (PLCs) and safety relays, these switches provide diagnostic capabilities and advanced functional safety. Industrial automation applications represent a key growth area, driven by the need for data-rich safety networks.
- Mechanical:Simple, robust switches that physically break a circuit, often used in less complex or older machinery.
- Pneumatic:Utilized in hazardous environments where electrical sparking is a concern, relying on air pressure changes to signal a stop.
- Magnetic:Less common for primary emergency stops, sometimes used for interlock or position sensing functions.
- Hydraulic:Employed in heavy machinery where hydraulic power is the primary control medium, ensuring a fail-safe stop.
Electrical technology remains dominant due to its widespread applicability, while Electronic technology is gaining traction from advanced automation requirements.
Application:
Application segments dictate the specific environmental and operational demands placed on emergency stop switches. Each industry has unique safety protocols and machinery types, influencing the selection of robust and compliant devices. Modernization efforts across sectors are driving demand for integrated safety solutions.
- Manufacturing Plants:These facilities require comprehensive safety coverage across diverse machinery, from assembly lines to robotics. Stringent regulatory compliance under standards like ISO 13850 drives consistent demand for certified components.
- Packaging Lines:High-speed, automated packaging systems necessitate rapid-response emergency stops to prevent product damage and worker injury. The expansion of e-commerce logistics fuels demand for advanced safety switches in these environments.
- Construction Sites:Heavy equipment and temporary setups demand durable, weather-resistant switches for operator safety.
- Mining Operations:Harsh environments and extensive conveyor systems require robust, often pull-cord type, emergency stops.
- Food Processing:Hygiene requirements dictate corrosion-resistant and easily cleanable switch designs in these facilities.
- Chemical Processing:Hazardous material handling necessitates intrinsically safe or explosion-proof emergency stop switches.
Manufacturing Plants represent the largest application area, with Packaging Lines demonstrating significant expansion due to automation trends.
End User:
End-user segments reflect distinct purchasing behaviors and operational priorities, ranging from large industrial integrators to individual machine operators. Compliance with safety mandates and the need for operational continuity are central to procurement decisions. The complexity of machinery and the associated risk profiles shape specific demands.
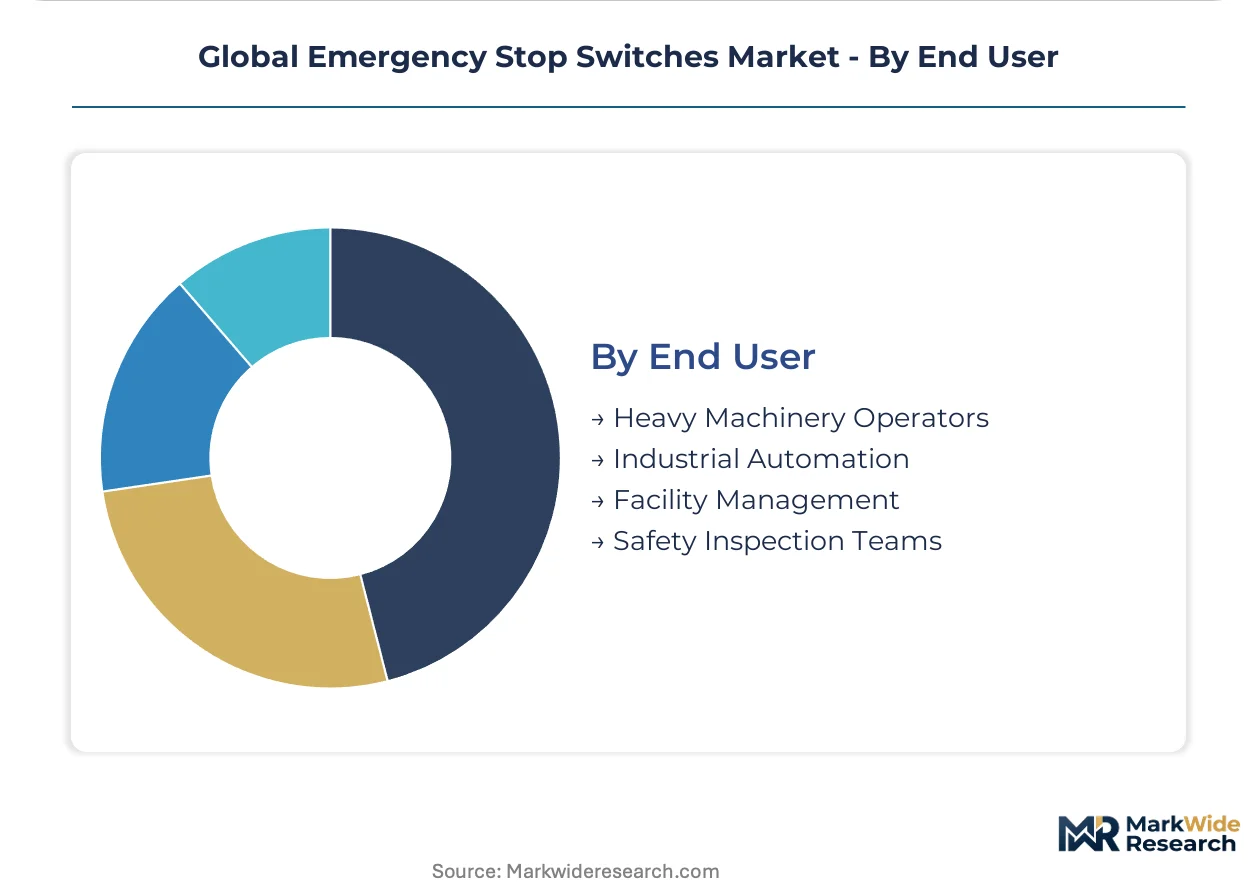
- Industrial Automation:These users integrate safety switches into complex, networked control systems, prioritizing data feedback and system-level diagnostics. The shift towards Industry 4.0 drives demand for smart, connected safety devices.
- Heavy Machinery Operators:This segment requires robust, easily accessible emergency stops for large, powerful equipment in demanding environments. Worker safety regulations, such as those from OSHA in the United States, mandate reliable emergency functions.
- Facility Management:Responsible for maintaining safety across diverse equipment within buildings, often requiring a mix of switch types.
- Safety Inspection Teams:These teams influence procurement through compliance audits and recommendations for certified safety components.
Industrial Automation end users are driving significant innovation in safety switch technology, while Heavy Machinery Operators focus on durability and immediate functionality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage, where production migrates due to cost-of-compliance differentials, influences the global distribution of emergency stop switch manufacturing. Countries with well-established industrial bases and stringent safety regulations drive demand for advanced, certified components. Conversely, emerging economies with expanding manufacturing sectors represent significant growth frontiers as safety standards accelerate.
China
China's extensive manufacturing sector upgrades drive substantial demand for emergency stop switches, emphasizing worker safety across its industrial base. The government's focus on modernizing factories, often guided by GB standards, mandates certified safety components. Industrial clusters in the Yangtze River Delta are integrating advanced safety systems into new production lines.
Germany
Germany's advanced manufacturing sector, characterized by high automation complexity, requires sophisticated emergency stop solutions. The EU Machinery Directive and IEC 62061 standards mandate stringent functional safety levels for machinery operating within the country. Bavaria's industrial heartland, home to numerous automation companies, prioritizes holistic system integration for safety.
United States
The United States sees consistent demand for emergency stop switches, particularly in automated warehousing and conveyor systems. OSHA regulations enforce workplace safety, making reliable emergency stop functions a prerequisite for machinery operation. The Midwest's industrial heartland, with its strong manufacturing presence, continually upgrades safety infrastructure.
India
India's expanding industrial base and accelerating adoption of safety standards create a significant growth frontier for emergency stop switches. BIS standards are increasingly influencing the selection of certified safety components in new and retrofitted machinery. Maharashtra's industrial zones are implementing modern safety solutions as automation grows.
Brazil
Brazil's industrial growth and focus on worker protection drive demand for robust emergency stop switches across its manufacturing and mining sectors. National safety standard NR-12 mandates specific requirements for machinery safety, including emergency stop provisions. São Paulo's manufacturing sector is a key consumer, integrating safety devices into diverse industrial applications.
Global Emergency Stop Switches Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, influencing market dynamics. The emergency stop switch market features a tiered structure, with global automation technology providers at the premium end and numerous regional component manufacturers. Strategic archetypes include integrated automation solution providers, specialized safety component manufacturers, and cost-focused regional suppliers. Portfolio diversification into smart safety features and strategic partnerships for ecosystem integration are dominant competitive moves.
Global automation technology providers like Siemens AG and Schneider Electric exemplify the integration of emergency stop switches into broader digital factory ecosystems, leveraging their extensive portfolios. Omron Corporation, a specialist in advanced sensing and control technologies, complements its safety switch offerings with robust automation solutions for manufacturing. These companies focus on providing certified reliability data to support system-level calculations required by performance-based safety standards.
| Leading Market Players |
|---|
| ABB |
| EAO Corporation |
| Eaton Corporation |
| Honeywell International Inc. |
| Schneider Electric |
| Siemens AG |
| Omron Corporation |
| REMA Group |
| REES Inc. |
| Others |
Cost & Logistics Intelligence
The certification-driven premium tier for emergency stop switches creates a distinct pricing structure, influencing specialized component sourcing and distribution channels. This divergence manifests in both the cost of compliance and the complexity of supply networks for advanced safety solutions.
Pricing Analysis
Distributor margins for certified emergency stop switches reflect the value added through local inventory and technical support. Per-unit transactional pricing dominates for standard components, while project-based pricing applies to integrated safety systems. Price differentiation stems from the Safety Integrity Level (SIL) certification and the level of integration with automation platforms. Pricing softness for basic electromechanical switches reflects intense competition from regional suppliers. Industrial Automation end-users are less price-sensitive for advanced, integrated solutions, prioritizing functional safety, while Heavy Machinery Operators are more sensitive to the initial cost of robust, standalone units.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand, especially for integrated safety solutions. Geographic supply concentration centers on China for basic components and Germany for advanced safety electronics. Raw material dependencies include copper for wiring, specialized plastics for enclosures, and microcontrollers for smart switches. Single-source vulnerability for certified safety relays presents a structural risk. Distribution runs through a mix of direct sales teams for large industrial integrators and a broad network of electrical distributors for smaller machine builders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The emergency stop switch market presents a margin-expansion story, driven by the premiumization of smart diagnostics and integrated safety features.
For Market Incumbents: Lock in existing customer bases through ecosystem integration, bundling emergency stop switches with broader automation platforms. Deepen vertical integration into specialized component manufacturing to mitigate supply chain risks from counterfeit components. This defends against emerging software-only safety solutions and cost-focused regional suppliers, leveraging certified reliability data as a competitive lever.
For New Entrants and Emerging Players: Online marketplaces offer a direct route to market for certified, cost-effective emergency stop switches, bypassing traditional distribution. Target industrializing economies in Southeast Asia with standard, compliant devices for new factory builds. Focus on smart diagnostics via IO-Link as a go-to-market angle, providing value beyond basic functionality for small to medium-sized enterprises.
For Investors and Strategic Acquirers: Consolidation pressure builds where regional compliance requirements create market fragmentation and certification costs are high. The market offers long-term viability over the next decade, supported by ongoing automation and worker safety mandates. Seek specialist safety component manufacturers with strong intellectual property in wireless safety protocols or advanced diagnostic capabilities as acquisition targets. A signal to watch is the widespread adoption of industrial 5G networks enabling dynamic safety zones.
| Strategic Initiative | Industry Significance |
|---|---|
| Ecosystem Integration | Siemens AG strengthens its digital factory ecosystem by linking safety switches. |
| Wireless Safety Development | Omron Corporation expands its offerings for mobile robotics and modular production lines. |
| Certification Portfolio Expansion | Schneider Electric ensures market access across diverse regulatory regions like the EU and US. |
| Smart Diagnostics Integration | Manufacturers provide predictive maintenance capabilities for industrial automation users. |
| Regional Manufacturing Hubs | Companies mitigate supply chain risks and serve growing demand in China. |
Research Approach
Direct dialogue with plant engineers, safety managers, OEM procurement teams, and distribution channel partners informed the primary research. This qualitative insight was validated through secondary sources including ISO standards documents, UL 508 and CE marking guidelines, and industrial automation trade publications. A comprehensive bottom-up and top-down triangulation approach ensured data consistency and accuracy across all market segments.
The quantitative model generated volume and value outputs for emergency stop switches, derived from a robust analytical framework. Segmentation dimensions included type, technology, application, end-user, and regional regulatory clusters. Compound annual growth rates were calculated using a weighted average of historical trends and projected market dynamics over the projection horizon. Key inputs included industrial automation spending and worker safety regulation enforcement.
The model assumes a particular technology adoption path for wireless safety protocols; alternative pathways for industrial 5G integration would alter the outlook. Forecasts reflect underlying assumptions about global manufacturing output and regulatory stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Global Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia Pacific Gas Detector Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Face Shield Market
Safety Equipment and Personal Protective Equipment (PPE)
China Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety IO Modules Market
Safety Equipment and Personal Protective Equipment (PPE)
Edge Protector Market
Safety Equipment and Personal Protective Equipment (PPE)
Road Flares Market
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Static Safety Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
APAC Safety Instrumented Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Self-Contained Breathing Apparatus (SCBA) Cylinders Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Emergency Lighting Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Analyzers Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Fall Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Flammable Storage Cabinets Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Safety Goggles Market