
 Premium High Security Doors Market | 2026-2036
Premium High Security Doors Market Size, Share, and Industry Trends Forecast 2026-2036
Premium High Security Doors Market Analysis
Composite fiber-reinforced panels is repositioning traditional steel as the dominant core material in premium security door manufacturing, reducing weight while maintaining UL 752 ballistic ratings. ASSA ABLOY leverages its electromechanical lock portfolio to bundle smart access with door assemblies across European commercial contracts. dormakaba anchors its position through in-house production of certified hardware systems that integrate with its door frames. Wangli Security Doors dominates residential retrofit channels across East Asian markets with fire-rated steel designs.
Premium high security doors are engineered entry assemblies combining forced-entry resistance, ballistic protection, and fire containment typically rated to UL 752, EN 1627, or equivalent standards, manufactured with steel, composite, or reinforced wood cores bonded to anti-drill face sheets. Steel doors sustain the largest volume share due to established certification paths and lower per-unit cost in institutional procurement, while composite doors represent the fastest-expanding category as weight reduction becomes critical for high-rise retrofits. Smart lock technology integration concentrates margin pools at the premium tier, with biometric systems commanding specification priority in data center and embassy applications where multi-factor authentication is mandatory.
UL certification requirements in North America, EN 1627-1630 resistance classes in Europe, and China's GB 17565-2007 national standard collectively shape product development cycles and market access barriers for manufacturers seeking cross-border contracts. EMA and national building safety regulators across EU member states are tightening material traceability rules under the Construction Products Regulation, forcing suppliers to document supply chain provenance for steel and composite inputs. Stakeholders must monitor evolving harmonization gaps between regional certification regimes as specification divergence creates compliance cost fragmentation for multinational projects.
Market Dynamics
Composite fiber-reinforced core technology is compressing established steel supply chains while biometric authentication mandates from data center operators are rewriting specification requirements for entry system assemblies.
Growth Catalysts
- Data center security mandates:Hyperscale facility operators in the United States and Germany now require UL 752 ballistic ratings paired with multi-factor biometric access for all perimeter entry points.
- EU Construction Products Regulation:Material traceability rules are elevating certified door assemblies over uncertified alternatives in public procurement across France, Italy, and Spain.
- Composite panel adoption:Weight reduction imperatives in high-rise retrofits across Singapore and the United Arab Emirates are accelerating specification of fiber-reinforced cores over traditional steel.
Market Restraints
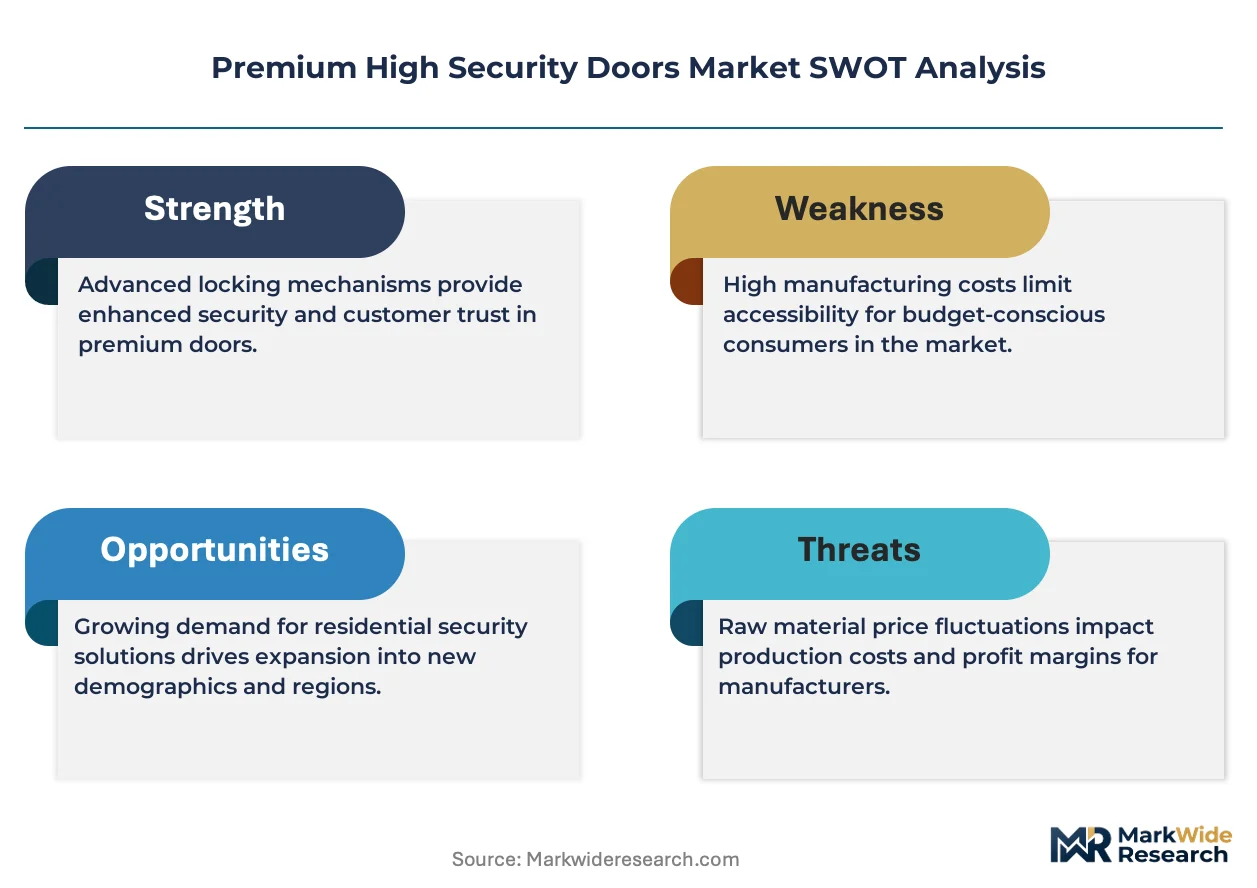
- Steel input cost volatility:Cold-rolled steel price fluctuations tied to energy costs in Germany and Japan are compressing margins for manufacturers without captive metallurgical supply.
- Certification timeline friction:UL 752 testing protocols in the United States require 12-18 month validation cycles that delay product launches and lock working capital in inventory.
- Technical weight-floor limits:Composite cores cannot yet achieve RC6 forced-entry ratings without steel reinforcement, capping addressable share in maximum-security embassy and military applications.
Strategic Opportunities
- India infrastructure buildout:Smart city initiatives and commercial data center construction in Mumbai and Hyderabad are creating first-mover openings for certified security door suppliers.
- Biometric-electromechanical convergence:Integration of facial recognition with electromechanical locking hardware is enabling premium pricing in embassy and financial institution verticals.
- Fire-security bundling:Combined fire-rated and ballistic-rated assemblies are capturing specification priority in hospital and research laboratory construction across Canada and Australia.
Industry Challenges
- Certification engineer scarcity:Qualified testing personnel familiar with both UL 752 and EN 1627 protocols are concentrated in Germany and the United States, creating bottlenecks for Asian manufacturers seeking dual-market entry.
- Legacy access system integration:Retrofit projects in institutional buildings require custom bridging hardware to connect new door assemblies with existing building management systems, extending project timelines and eroding contract profitability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Premium High Security Doors Market |
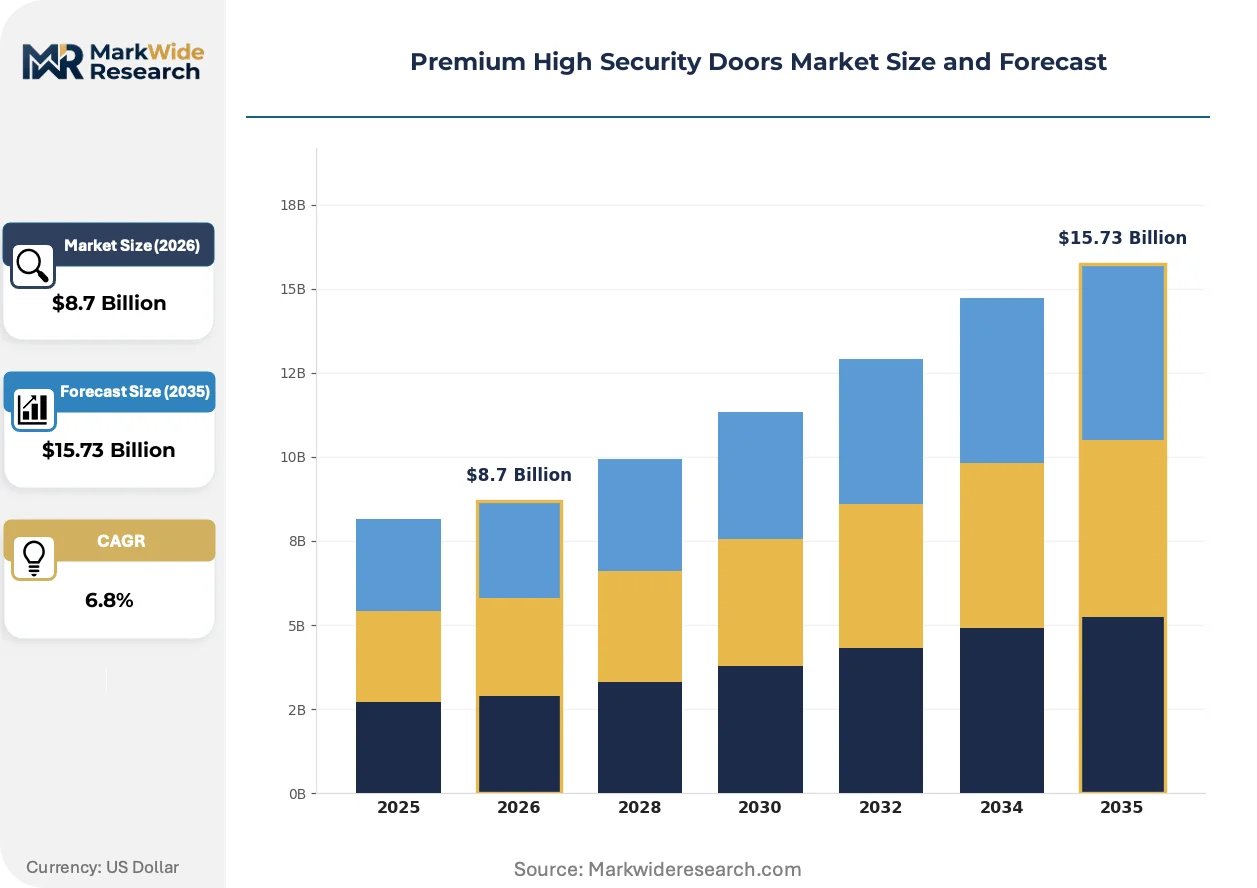
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Doors, Composite Doors, Wood Doors, Reinforced Doors Technology: Smart Locks, Electronic Keypads, Biometric Systems, Magnetic Locks End User: Residential, Commercial, Industrial, Institutional Installation Type: New Construction, Retrofit, DIY, Professional Installation |
| Companies Covered | Armortex, Mexin Group, ASSA ABLOY, Buyang Group, Simto Group, Fichet Group, Wangli Security Doors, Vallisco, dormakaba, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Premium High Security Doors Market Emerging Trajectories
Material science breakthroughs and regulatory harmonization pressures are compressing product development cycles while authentication technology is migrating from peripheral add-on to core door specification.
Modular composite core systems are decentralizing the traditional steel-dominated supply structure for high-rise security door installations. Facility managers in Singapore and Dubai are specifying these assemblies to reduce structural load requirements. The shift is compressing established foundry relationships and enabling regional fabricators to capture share previously held by integrated steel door manufacturers.
REACH material disclosure requirements in Europe are forcing reformulation of bonding agents and face sheet coatings used in composite door manufacturing. Suppliers must now document full chemical provenance through supply chains or face exclusion from public sector tenders. German and French manufacturers with captive laboratory testing capacity are accelerating compliance documentation while smaller competitors face 18-24 month backlog at external certification bodies.
Specification authority is migrating from general contractors to specialized security consultants who bundle door assemblies with access control and surveillance systems. Data center operators in Virginia and Frankfurt are consolidating vendor relationships around integrated security packages rather than discrete component procurement. This consolidation favors suppliers with in-house electromechanical lock production and certified integration capabilities over pure-play door fabricators.
Premium High Security Doors Market Segmentation
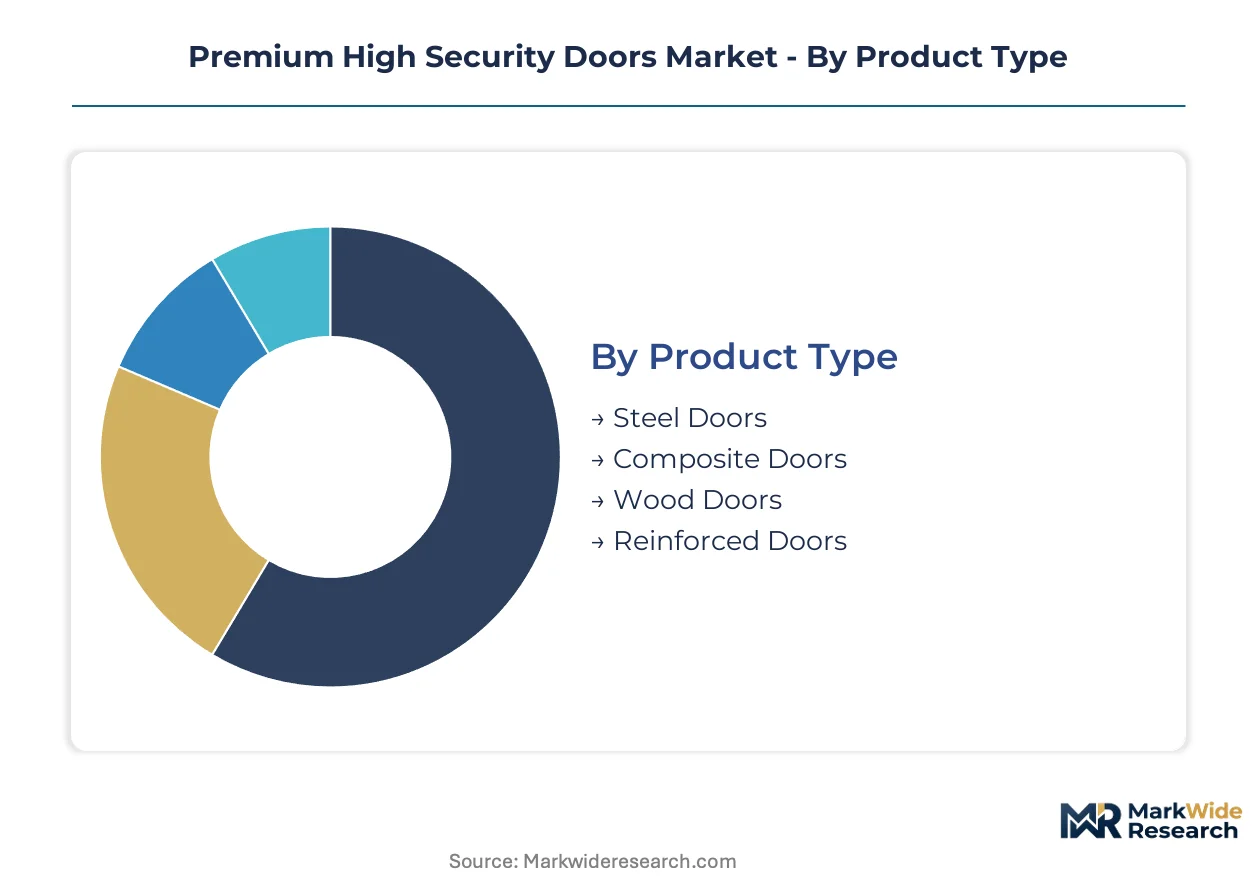
Specification authority in premium high security doors fragments across material performance tiers, authentication technology bundles, and installation complexity thresholds. Procurement patterns diverge sharply between institutional buyers demanding certified assemblies and residential channels prioritizing retrofit compatibility.
Product Type:
Material selection pivots on the forced-entry rating versus weight trade-off, with certification path availability determining specification feasibility across verticals.
- Steel Doors:Cold-rolled steel cores bonded to anti-drill face sheets deliver UL 752 ballistic ratings and RC4-RC6 forced-entry resistance. Data center operators in the United States and Germany specify these assemblies for perimeter hardening despite structural load penalties. Mature deployment sits with Steel Doors.
- Composite Doors:Fiber-reinforced polymer cores reduce weight by 40-60% versus steel equivalents while maintaining mid-tier ballistic ratings. Facility managers in Singapore and Dubai specify these for high-rise retrofits where floor loading limits constrain traditional steel. Newer deployment is concentrated in Composite Doors.
- Wood Doors:Reinforced timber cores with steel face sheets serve heritage building renovations and embassy residential quarters requiring aesthetic conformity with historical facades.
- Reinforced Doors:Hybrid steel-composite constructions target mid-market commercial applications balancing cost containment with moderate security ratings.
Steel maintains specification dominance where maximum forced-entry resistance is non-negotiable; composite gains ground fastest where weight reduction unlocks retrofit feasibility.
Technology:
Authentication hardware integration now determines margin capture, with biometric-electromechanical convergence commanding premium positioning in institutional procurement.
- Smart Locks:Electromechanical locking systems with remote credential management and audit trail logging. ASSA ABLOY bundles these with door assemblies across European commercial contracts, displacing standalone mechanical hardware.
- Biometric Systems:Fingerprint and facial recognition modules integrated into door frame assemblies. Hyperscale data centers in Virginia and Frankfurt mandate multi-factor biometric access for all perimeter entry points, creating specification priority for integrated suppliers. Biometric Systems are climbing the fastest.
- Electronic Keypads:PIN-based credential systems serving mid-tier commercial and light industrial applications where cost sensitivity limits biometric adoption.
- Magnetic Locks:Electromagnetic holding force systems for controlled egress applications in healthcare and research laboratory construction across Canada.
Biometric integration concentrates margin pools at the premium tier; keypad and magnetic configurations serve price-sensitive segments with thinner hardware margins.
End User:
Procurement sophistication varies dramatically across buyer categories, with institutional mandates driving certification complexity and residential channels prioritizing installation speed.
- Institutional:Government, defense, and critical infrastructure facilities requiring certified assemblies to UL 752 or EN 1627 standards. EU public procurement rules under the Construction Products Regulation elevate certified door assemblies over uncertified alternatives in France, Italy, and Spain.
- Commercial:Corporate headquarters, financial institutions, and data center facilities. Smart city initiatives in Mumbai and Hyderabad are creating first-mover openings for certified security door suppliers in this segment.
- Industrial:Manufacturing facilities and logistics hubs requiring forced-entry resistance with less stringent ballistic specifications than institutional counterparts.
- Residential:Single-family and multi-family dwellings, primarily retrofit channels. Wangli Security Doors dominates this category across East Asian markets with fire-rated steel designs.
Institutional buyers drive specification complexity and certification investment; residential channels reward speed-to-install and distributor availability.
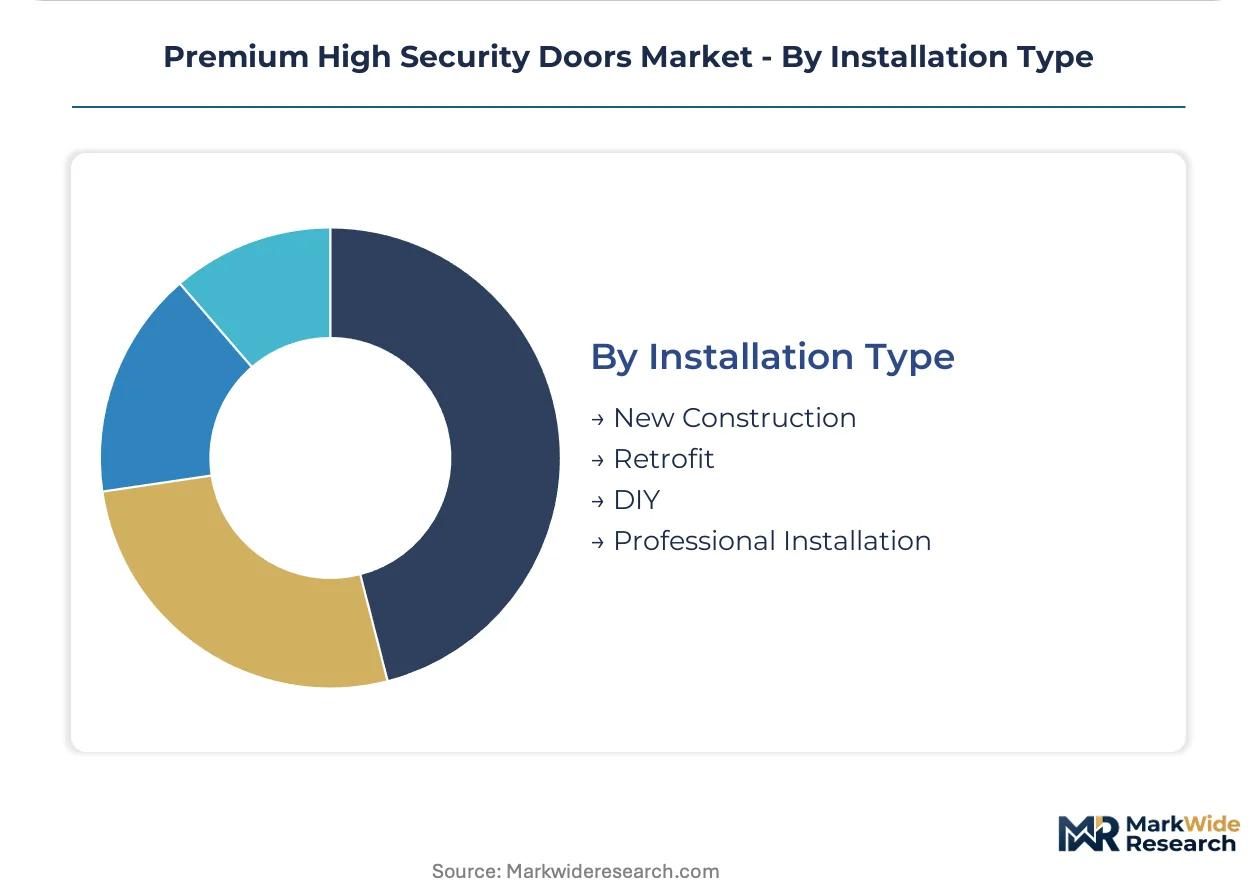
Installation Type:
Project delivery mode shapes supplier economics, with retrofit complexity eroding margins through custom bridging hardware requirements.
- New Construction:Greenfield projects allowing integrated door-frame-hardware specification during architectural design phase. General contractors in commercial and institutional verticals consolidate procurement around certified assembly suppliers.
- Retrofit:Replacement of existing door assemblies in operational buildings. Projects in institutional buildings require custom bridging hardware to connect new door assemblies with existing building management systems, extending timelines and compressing contract profitability. Retrofit is expanding most quickly.
- Professional Installation:Certified technician deployment ensuring warranty validity and code compliance, mandatory for institutional and commercial specifications.
- DIY:Self-installation channels serving residential retrofit markets with pre-hung assemblies and simplified hardware kits.
New construction rewards early supplier engagement and design-phase specification capture; retrofit demands flexible integration capabilities and field engineering bandwidth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale data center construction concentrates procurement authority in specific metropolitan clusters across Germany, the United States, Singapore, and the United Arab Emirates. Facility operators in these markets mandate certified ballistic-rated assemblies with integrated biometric access. National building safety regulators in each jurisdiction enforce divergent certification timelines that fragment supplier economics.
Germany
Frankfurt's data center corridor drives specification of EN 1627 RC6-rated assemblies with multi-factor authentication. EMA and federal building regulators enforce material traceability under the Construction Products Regulation. Bavarian manufacturers with captive testing laboratories accelerate compliance documentation while competitors face external certification bottlenecks.
United States
Northern Virginia's hyperscale cluster demands UL 752 ballistic ratings paired with biometric-electromechanical convergence. Virginia and California state procurement codes elevate certified assemblies in public infrastructure tenders. Dallas-Fort Worth metroplex contractors consolidate vendor relationships around integrated security packages rather than discrete components.
Singapore
High-rise commercial retrofits prioritize composite fiber-reinforced cores to reduce structural load penalties. The national building authority enforces fire-bundled security specifications for financial district renovations. Marina Bay and Raffles Place facility managers specify modular assemblies from regional fabricators capturing share from integrated steel manufacturers.
United Arab Emirates
Dubai's smart city infrastructure mandates forced-entry-resistant entry systems for critical government and commercial facilities. MOHAP and federal construction regulators align procurement with Gulf-standard certification harmonization initiatives. Jebel Ali industrial zone fabricators supply composite-core assemblies across Middle East retrofit projects.
India
Mumbai and Hyderabad data center construction creates first-mover openings for certified security door suppliers. BIS and state urban development authorities tighten material standards for smart city infrastructure. Maharashtra and Telangana industrial corridors attract regional fabricators establishing captive hardware integration capabilities.
Premium High Security Doors Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated electromechanical lock producers capturing premium-tier margin pools while regional fabricators compete on retrofit speed. The vendor base organizes around three strategic archetypes: European electromechanical integrators, East Asian volume fabricators, and North American ballistic specialists. Capacity expansion and backward integration into captive hardware production represent the dominant competitive moves as specification authority migrates toward bundled security packages.
Among European electromechanical integrators, ASSA ABLOY and dormakaba occupy positions exemplifying the convergence of lock hardware with certified door assemblies. Wangli Security Doors anchors the East Asian volume-fabricator archetype. These three entities represent distinct strategic postures: bundled smart access integration, in-house certified hardware production, and residential retrofit channel dominance respectively.
| Leading Market Players |
|---|
| Armortex |
| Mexin Group |
| ASSA ABLOY |
| Buyang Group |
| Simto Group |
| Fichet Group |
| Wangli Security Doors |
| Vallisco |
| dormakaba |
| Others |
Supply Flow & Price Mechanics
Composite fiber-reinforced core manufacturing is compressing traditional foundry economics while redistributing value capture toward regional fabricators with modular assembly capabilities. Cold-rolled steel price volatility tied to energy costs in Germany and Japan simultaneously erodes margin stability for integrated steel door producers and creates procurement arbitrage opportunities for composite specialists.
Pricing Analysis
Volume concentrates in steel door assemblies where per-unit margins compress under cold-rolled steel input volatility, while biometric-integrated premium tiers capture expanded margin pools through specification bundling. Three-tier pricing structure across premium, standard, and economy levels separates UL 752-certified assemblies with multi-factor authentication from mid-tier EN 1627-compliant offerings and uncertified commercial alternatives. Pricing pressure stems from certification timeline friction that locks working capital in 12-18 month UL validation cycles. Residential retrofit channels exhibit highest price sensitivity, while data center operators in Virginia and Frankfurt demonstrate lowest sensitivity due to security mandate compliance requirements.
Supply Chain Analysis
Freight cost escalation for cold-rolled steel slabs from Germany and Japan is accelerating regionalization of composite panel sourcing. Manufacturing concentrates in China, Germany, and the United Arab Emirates, with raw material dependencies spanning fiber-reinforced polymers, cold-rolled steel, and electromechanical locking hardware. Supply chain risk centers on single-source vulnerability for UL-certified testing capacity concentrated in German and American laboratories. Distribution runs through security consultants bundling door assemblies with access control systems rather than discrete component procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where the EU Construction Products Regulation's material traceability mandates erect barrier-to-entry moats favoring certified incumbents with captive laboratory capacity.
For Market Incumbents: Hedge against composite substitution by securing captive fiber-reinforced polymer supply agreements in Singapore and Dubai. Steel input volatility threatens margin stability; backward integration into certified hardware production defends specification authority as security consultants consolidate vendor relationships around bundled packages. For New Entrants and Emerging Players: Launch via regional fabricator partnerships targeting Mumbai and Hyderabad data center construction where BIS standards tightening creates first-mover openings. Composite-core retrofit channels in Singapore high-rises represent the most penetrable segment. Go-to-market leverage rests on modular assembly speed versus integrated steel manufacturer lead times. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by electromechanical lock specialists seeking door assembly integration. Long-term viability favors suppliers with dual UL 752 and EN 1627 certification capabilities across the analysis window. Acquisition target archetype: regional fabricators with captive composite panel production and pending certification backlog. Watch certification engineer scarcity as inflection signal—bottleneck intensity predicts margin expansion for compliant players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hardware Production | dormakaba's captive certified systems demonstrate margin defense against pure-play fabricators. |
| Biometric-Electromechanical Convergence | ASSA ABLOY bundles facial recognition with door assemblies for Virginia data center mandates. |
| Regional Fabricator Capacity Expansion | Singapore and Dubai modular assembly sites capture high-rise retrofit share from steel incumbents. |
| Dual Certification Investment | Simultaneous UL 752 and EN 1627 validation unlocks cross-border procurement in Germany and United States. |
| Composite Core Supply Agreement | Fiber-reinforced polymer sourcing partnerships in UAE reduce structural load penalties for Marina Bay projects. |
Methodological Framework
Multi-period observation of certification timeline data, material input cost indices, and specification authority migration anchored the trend analysis, supplemented by interviews with security consultants, facility managers at hyperscale data centers, electromechanical lock product directors, and certified testing laboratory engineers. Secondary validation drew from UL certification registries, EN 1627 test reports, EU Construction Products Regulation compliance databases, and customs trade data for cold-rolled steel and fiber-reinforced polymer imports. Bottom-up segment sizing triangulated against top-down construction spending forecasts for critical infrastructure verticals.
Input-output matrices modeled relationships between material cost drivers, certification capacity constraints, and specification bundling trends across the projection horizon. Segmentation dimensions included core material type, authentication technology tier, end-user vertical, and installation complexity. CAGRs derived from regression analysis of historical procurement patterns against regulatory mandate implementation schedules. Industry-specific forecast inputs incorporated data center construction pipelines in Northern Virginia and Frankfurt, plus smart city infrastructure budgets in Mumbai and Hyderabad.
Steel price volatility, certification backlog duration, and regulatory harmonization gaps between UL and EN protocols are the dominant revision risks that could alter trajectory assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Tube and Dressing Securement Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Germany Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Intrinsically Safe Lighting Market
Safety Equipment and Personal Protective Equipment (PPE)
Security System Tester Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Face Shield Market
Safety Equipment and Personal Protective Equipment (PPE)
Biodegradable Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Goggles Market
Safety Equipment and Personal Protective Equipment (PPE)
Cargo Security Seals Market
Safety Equipment and Personal Protective Equipment (PPE)
Hand Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Premium Motorcycle Helmets Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Surgical Mask and Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Detection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Splash Shield Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Respirators Market