
 UK Real Estate Hospitality Market | 2026-2036
UK Real Estate Hospitality Market Size, Share, and Industry Trends Forecast 2026-2036
UK Real Estate Hospitality Market Insights
Cross-laminated timber is hardening as the structural material of choice for new hospitality developments, cutting embodied carbon by roughly one-third against traditional steel frames. InterContinental Hotels Group PLC leverages its scale to specify mass timber across premium urban sites, while Travelodge anchors its cost-led model through standardized concrete modular construction. Covivio differentiates via mixed-use hospitality-residential schemes in regeneration zones.
The UK Real Estate Hospitality sector comprises income-generating physical assets—freehold or leasehold buildings and land—designed to accommodate transient guests through lodging, food service, and ancillary amenities, typically yielding returns via operational cash flows or capital appreciation over holding periods of five to fifteen years. Hotels dominate transaction volumes, though extended-stay properties capture widening margin pools as average guest durations lengthen. Boutique and limited-service models lead new supply pipelines, while full-service assets in secondary cities face yield compression from rising operating cost bases.
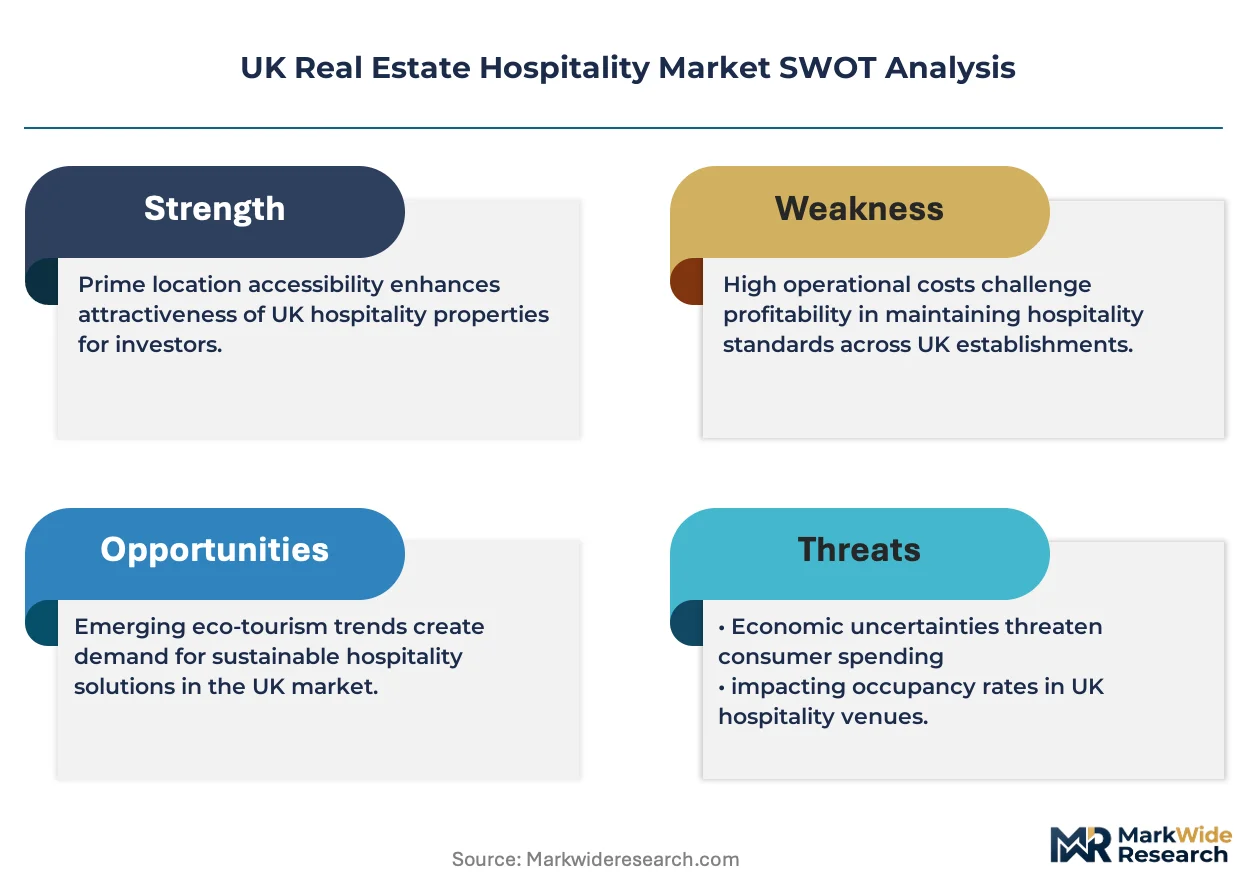
MHCLG enforces Building Regulations Part L and Part F standards that mandate fabric efficiency and ventilation performance in new hospitality construction, directly shaping developer specifications and refurbishment timelines. The Health and Safety Executive's fire safety regime, tightened post-Grenfell through the Building Safety Act, imposes gateway compliance obligations that extend project durations and elevate professional indemnity requirements. Stakeholders must weigh regulatory carrying costs against locational premiums when underwriting development feasibility in constrained planning environments.
Market Dynamics
The Building Safety Act's gateway compliance regime is extending project timelines across UK hospitality developments, forcing capital providers to restructure underwriting assumptions around extended holding periods and elevated professional indemnity costs.
Growth Catalysts
- Building Regulations Part L:Fabric efficiency mandates are accelerating deep retrofit pipelines across aging provincial hotel stock, unlocking trapped value in secondary city assets.
- Extended-stay demand:Corporate relocation pattern shifts are concentrating demand in London's serviced apartment segment, compressing lease-up risk for purpose-built product.
- Cross-laminated timber:Structural timber specification is cutting embodied carbon in new developments, aligning institutional capital allocation with net-zero fund mandates.
Market Restraints
- Professional indemnity cost inflation:Post-Grenfell liability regimes have tripled insurance premiums for fire safety consultants, elevating soft costs across refurbishment schemes.
- Skilled labour scarcity:Specialist M&E contractors capable of Part F ventilation compliance are concentrated in London and Manchester corridors, constraining regional deployment velocity.
- Debt cost volatility:Sterling base rate movements are compressing development yield spreads, freezing speculative starts outside prime locations.
Strategic Opportunities
- Manchester corridor expansion:Boutique operators are capturing undersupplied corporate demand in regenerated city fringe zones, ahead of national brand pipeline delivery.
- Mixed-use hospitality-residential:Planning authorities in Birmingham and Leeds are permitting denser floorplates where residential cross-subsidises amenity provision.
- Heat pump integration:Non-domestic building efficiency incentives are offsetting capex premiums for low-carbon plant in new-build schemes.
Industry Challenges
- Gateway 2 compliance timelines:Building Safety Regulator sign-off requirements are inserting 4-6 month delays between structural completion and operational handover.
- Legacy stock retrofit complexity:Post-war concrete frame hotels face fabric upgrade challenges that Part L fabric efficiency targets cannot accommodate without demolition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Real Estate Hospitality Market |
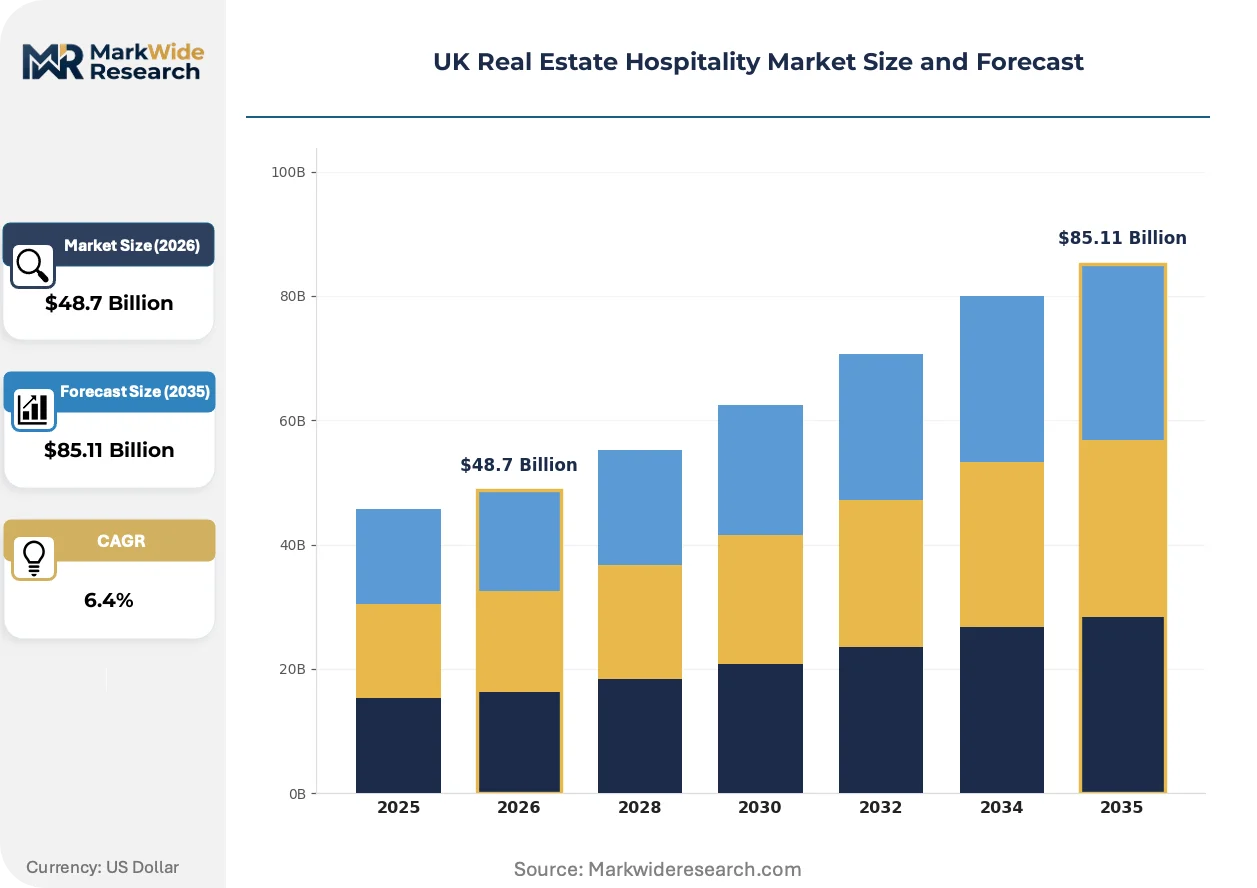
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $85.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Hotels, Motels, Resorts, Bed & Breakfasts Service Model: Full-Service, Limited-Service, Boutique, Extended-Stay Target Segment: Business Travelers, Leisure Tourists, Conference Attendees, Family Vacationers Booking Channel: Online Travel Agencies, Direct Booking, Travel Agents, Corporate Accounts |
| Companies Covered | InterContinental Hotels Group PLC, Travelodge, Britannia Hotels, Choice Hotels International Inc., Accor SA, Hilton Hotels & Resorts, Covivio, London & Regional Properties, LRC Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Real Estate Hospitality Market Trends and Innovations
Operational technology deployment and structural material substitution are compressing carbon intensity across UK hospitality development, while procurement models adapt to extended asset holding periods.
Mass timber structural systems are electrifying design specifications for premium urban hospitality assets. Boutique developers in Edinburgh and Manchester corridors are specifying glulam frames for 50-100 key properties, cutting site construction duration by one-third against steel alternatives. This acceleration is compressing capital deployment timelines and enabling earlier operational cash flow capture.
MHCLG's Part L conservation of fuel and power standards are mandating 31% carbon reduction against 2013 baselines for new non-domestic buildings. Developers are responding with fabric-first envelope strategies that eliminate thermal bridging at balcony junctions and window reveals. Full-service assets in secondary cities face the steepest compliance cost escalation, diverting capital toward limited-service models with simpler servicing requirements.
Corporate accommodation buyers are consolidating procurement through serviced apartment platforms, displacing traditional hotel negotiated rate agreements. Extended-stay operators in London's Canary Wharf and South Bank clusters are capturing multi-month assignments from financial and professional services relocations. This concentration is visible across technology and consulting verticals, where project-based staffing drives predictable occupancy patterns.
UK Real Estate Hospitality Market Segmentation
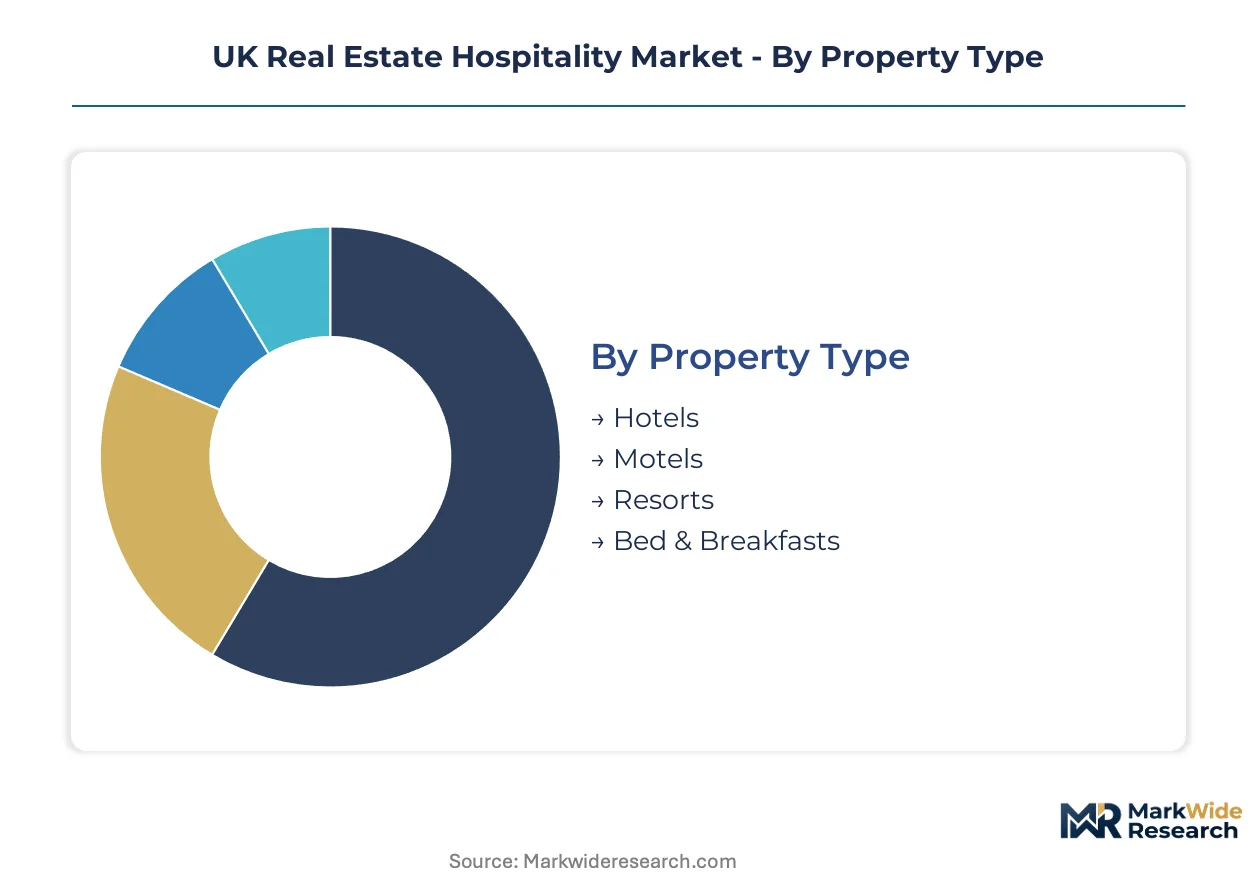
Segmentation reveals where capital deployment concentrates and where yield compression threatens. Investors targeting the UK Real Estate Hospitality Market must align property type and service model selections with regulatory timelines and demand migration patterns.
Property Type:
Hotels dominate transaction liquidity, yet supply concentration varies sharply by asset vintage and location.
- Hotels:Purpose-built lodging assets with centralized food and beverage operations. Investment concentrates in London's extended-stay conversions and Manchester's boutique pipeline, driven by corporate relocation demand and Part L retrofit economics.
- Motels:Low-rise roadside properties with surface parking and limited amenities. Highway corridor assets in the Midlands face obsolescence pressure from changing domestic travel patterns and electrification infrastructure gaps.
- Resorts:Destination assets integrating accommodation with leisure facilities. Coastal and rural holdings in Cornwall and the Scottish Highlands capture premium pricing from international leisure recovery.
- Bed & Breakfasts:Small-scale owner-operated properties, typically under 10 keys. Heritage stock in Edinburgh and Bath corridors trades on locational scarcity despite operational inefficiency.
Today's leader: Hotels. Tomorrow's challenger: Extended-stay conversions within hotel stock.
Service Model:
Operating cost structures and staffing intensity create three distinct margin tiers across UK hospitality assets.
- Full-Service:Properties with restaurants, bars, meeting space, and concierge operations. Secondary city assets face yield compression from rising wage and utility costs, diverting capital toward lighter models.
- Limited-Service:Accommodation-focused properties with minimal F&B and no meeting facilities. Standardized concrete modular construction anchors Travelodge's cost-led expansion in regional transport hubs.
- Boutique:Design-led properties emphasizing localized experience and smaller room counts. Operators are expanding across Manchester and Edinburgh corridors ahead of national brand pipeline delivery.
- Extended-Stay:Serviced apartment products with kitchen facilities and multi-week stay positioning. London's Canary Wharf and South Bank clusters capture technology and consulting vertical relocations.
Capital currently favors limited-service velocity. Extended-stay margins are climbing the fastest as average guest durations lengthen.
Target Segment:
Demand composition determines pricing power and occupancy resilience through economic cycles.
- Business Travelers:Corporate account demand concentrated in London's financial districts and regenerated regional business parks. Procurement consolidation through serviced apartment platforms is displacing traditional negotiated rate agreements.
- Leisure Tourists:Domestic and international discretionary travel driving seasonal pricing in heritage and coastal locations. Sterling volatility shapes international booking patterns.
- Conference Attendees:Event-driven demand requiring dedicated meeting space and group accommodation blocks. Post-pandemic hybrid work patterns have permanently reduced mid-week corporate event frequency.
- Family Vacationers:Multi-room demand seeking connecting configurations and leisure amenities. Regional resort assets capture this segment during school holiday windows.
Business travel anchors revenue stability. Extended-stay corporate demand is gaining share fastest as project-based staffing patterns normalize.
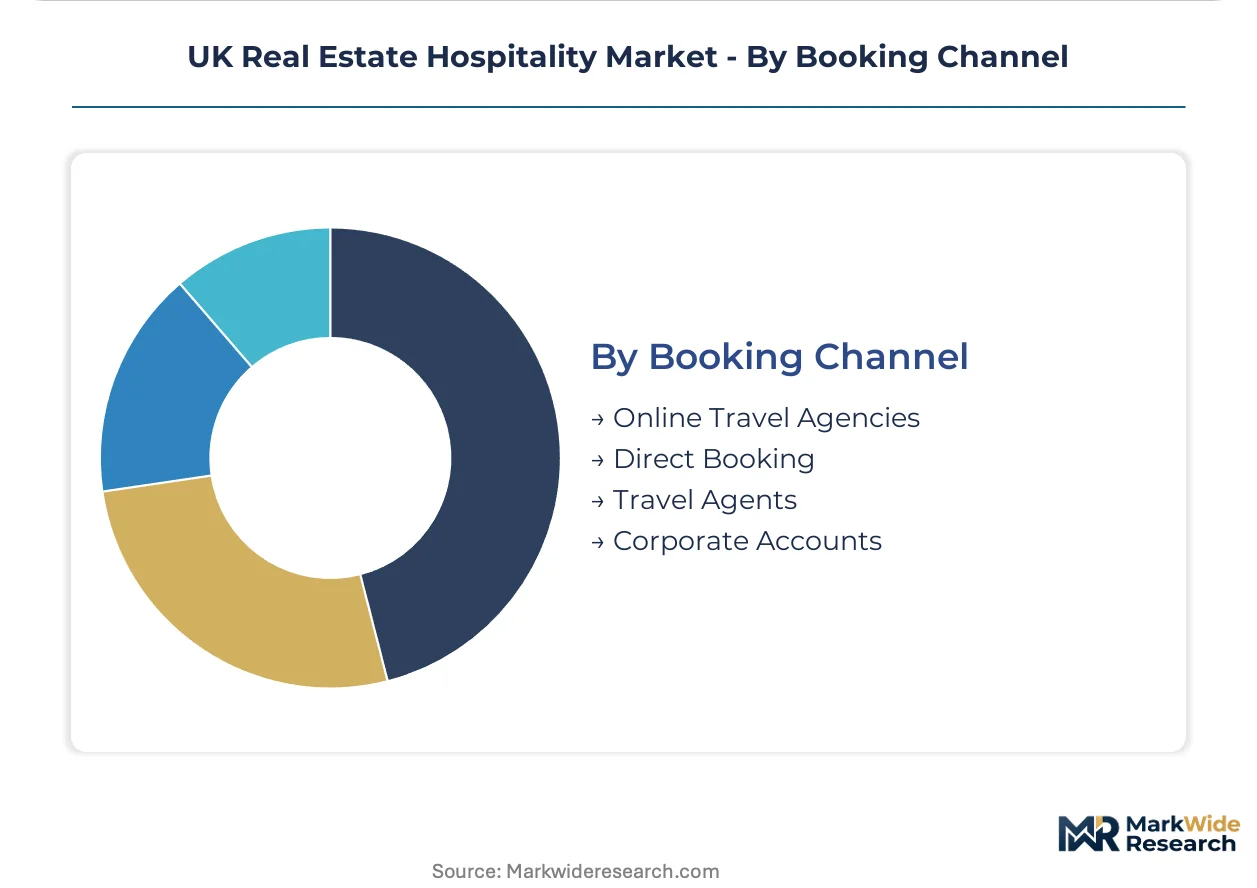
Booking Channel:
Distribution economics are restructuring operator margin capture and customer acquisition costs.
- Online Travel Agencies:Third-party platforms aggregating inventory with commission-based revenue models. Booking.com and Expedia dominate visibility but erode net operating income through 15-25% take rates.
- Direct Booking:Proprietary websites and loyalty programs capturing margin otherwise lost to intermediaries. Investment in digital infrastructure and member pricing is accelerating across mid-market operators.
- Travel Agents:Traditional intermediaries serving package holiday and complex itinerary segments. Corporate travel management companies retain relevance for negotiated rate administration.
- Corporate Accounts:Direct contractual relationships with employers for employee accommodation. Extended-stay operators are consolidating procurement relationships with financial and professional services relocations.
Direct booking commands strategic priority. Corporate account pipelines offer the steepest expansion trajectory as serviced apartment procurement centralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London and the Southeast corridor concentrate investment velocity and regulatory complexity. Capital deployment patterns diverge sharply between the capital's extended-stay conversions and provincial retrofit pipelines.
London and Southeast
Corporate relocation demand from financial and professional services firms is concentrating in Canary Wharf and South Bank clusters. MHCLG's Building Regulations Part L mandates 31% carbon reduction against 2013 baselines for new non-domestic buildings. Developers in the Thames Gateway are specifying cross-laminated timber frames to accelerate construction timelines and capture earlier operational cash flows.
Midlands
Transport hub adjacency is driving limited-service expansion across Birmingham and Leicester corridors. The Building Safety Act's gateway compliance regime extends project timelines and elevates professional indemnity costs for refurbishment schemes. Mixed-use hospitality-residential schemes in Birmingham's regeneration zones capture planning permissions for denser floorplates.
North England
Boutique operators are expanding across Manchester ahead of national brand pipeline delivery. Part F ventilation compliance requirements concentrate specialist M&E contractors in Manchester corridors, constraining regional deployment velocity. The city's regenerated fringe zones capture undersupplied corporate demand from technology and consulting verticals.
Scotland
Heritage stock in Edinburgh trades on locational scarcity despite operational inefficiency. The Scottish Government's energy efficiency standards accelerate deep retrofit pipelines across aging provincial hotel stock. Boutique developers in Edinburgh specify glulam frames for 50-100 key properties, cutting site construction duration against steel alternatives.
Wales and Northern Ireland
Coastal resort assets in Wales capture premium pricing from domestic leisure recovery. Post-Grenfell liability regimes have elevated insurance premiums for fire safety consultants across refurbishment schemes. Limited new supply pipelines in Belfast and Cardiff reflect debt cost volatility compressing development yield spreads.
UK Real Estate Hospitality Market Competitive Landscape
Global majors compete with regional champions across development scale and service model positioning. The market structure fragments between premium urban developers, cost-led regional operators, and mixed-use regeneration specialists. Three archetypes dominate: institutional-scale hotel groups, standardized limited-service chains, and boutique design-led independents. Competitive moves concentrate on portfolio diversification into extended-stay formats and strategic partnerships for mixed-use scheme delivery.
Within the institutional-scale tier, InterContinental Hotels Group PLC and Hilton Hotels & Resorts exemplify global operators leveraging specification power across premium urban sites. Among European-headquartered groups, Accor SA occupies a position spanning luxury through economy positioning. Covivio represents the mixed-use regeneration archetype, anchoring hospitality-residential schemes in secondary city zones. These three sit within distinct competitive vectors—global scale, continental reach, and asset-light regeneration—each responding differently to Part L compliance timelines and extended-stay demand migration.
| Leading Market Players |
|---|
| InterContinental Hotels Group PLC |
| Travelodge |
| Britannia Hotels |
| Choice Hotels International Inc. |
| Accor SA |
| Hilton Hotels & Resorts |
| Covivio |
| London & Regional Properties |
| LRC Group |
| Others |
Pricing and Supply Chain Analysis
Specialist M&E contractors concentrated in London and Manchester corridors create labor-cost differentials that widen pricing spreads between premium urban developments and provincial retrofit schemes. Part F ventilation compliance requirements tether regional project viability to these concentrated skill pools, forcing developers to absorb elevated soft costs or accept extended timelines.
Pricing Analysis
Input-cost pass-through dominates pricing dynamics as cross-laminated timber premiums and professional indemnity inflation reshape development economics. Three-tier pricing structure across premium mass-timber urban assets, standard concrete-framed limited-service properties, and economy-grade legacy stock reflects specification grade and compliance burden differentiation. Pricing pressure stems from Gateway 2 compliance delays extending capital deployment horizons. Corporate buyers in London's extended-stay segment demonstrate lowest price sensitivity, while regional limited-service operators face acute margin compression from debt cost volatility.
Supply Chain Analysis
Single-source vulnerability sits with Austrian and German glulam suppliers dominating cross-laminated timber specifications for UK boutique developments. Fabric-first envelope systems draw from Belgian insulation manufacturers and Scandinavian window fabricators, creating tariff-exposed dependencies. Supply chain risk centers on regulatory restriction as MHCLG's Building Regulations Part L tightens import specification requirements for non-domestic building components. Distribution runs through specialist timber engineering contractors and regional M&E integrators rather than merchant builders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK Real Estate Hospitality Market represents a late-cycle quality story as institutional capital migrates toward mass-timber premium specifications that satisfy net-zero fund mandates. Corporate relocation demand toward serviced apartment formats reinforces this shift toward higher-specification, lower-carbon assets.
For Market Incumbents: Cement market position through captive control over specialist M&E contractor relationships in Manchester and Edinburgh corridors, insulating pipeline velocity against regional labor scarcity. Accelerate backward integration into cross-laminated timber supply agreements to lock in specification premiums before Gateway 2 compliance extends competitor timelines. Fire safety consultant liability inflation threatens margin structures; vertical integration into in-house compliance capabilities defends against this pressure point.
For New Entrants and Emerging Players: Technology-first mass timber specification offers entry into boutique segments where InterContinental Hotels Group PLC and Covivio have established premium positioning. Target Birmingham and Leeds mixed-use regeneration zones where planning permissions for denser hospitality-residential floorplates remain undersupplied. White-space concentration exists in heat pump-integrated new-build schemes capturing non-domestic building efficiency incentives. Go-to-market angle: partner with regional authorities ahead of national brand pipeline delivery.
For Investors and Strategic Acquirers: Institutional pension funds and sovereign wealth vehicles are the most active acquirer in this space, drawn by inflation-linked lease structures and operational cash flow visibility. Long-term viability frames around holding periods that capture full Part L compliance value accretion in secondary city retrofits. Acquisition target archetype: extended-stay conversions within hotel stock with kitchen infrastructure and multi-week stay positioning. Signal to watch: Building Safety Regulator staffing levels as indicator of Gateway 2 timeline compression or extension.
| Strategic Initiative | Industry Significance |
|---|---|
| Mass Timber Specification | Cross-laminated timber cuts embodied carbon one-third against steel, unlocking institutional capital. |
| Extended-Stay Conversion | Serviced apartment repositioning captures corporate relocation demand from financial services relocations. |
| Heat Pump Integration | Non-domestic building efficiency incentives offset capex premiums in new-build schemes. |
| Mixed-Use Regeneration | Residential cross-subsidy enables denser floorplates in Birmingham and Leeds planning environments. |
| Gateway 2 Compliance Capability | In-house Building Safety Regulator navigation compresses 4-6 month structural-to-operational handover delays. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with hospitality developers, fire safety consultants, M&E contractors, and institutional investment officers with secondary validation. MHCLG regulatory filings, Building Safety Regulator gateway compliance databases, and local authority planning portals anchored supply-side assessment. Operator transaction data, serviced apartment platform procurement disclosures, and cross-laminated timber import records informed demand calibration. Bottom-up project pipeline enumeration triangulated against top-down sector capital flow estimates.
Comparable-period anchoring linked the projection horizon to historical development completion cycles and regulatory implementation phases. Segmentation modeling spanned property type, service model intensity, target guest segment, and booking channel economics, with regional regulatory cluster as an additional hospitality-specific dimension. CAGRs derived from fitted trend extrapolation moderated by supply constraint factors including skilled labor availability and professional indemnity market capacity. Forecast inputs incorporated Part L compliance cost curves and extended-stay demand migration patterns from corporate procurement platforms.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to sterling base rate movements, Building Safety Act enforcement intensity, and mass timber supply chain expansion. Assumptions reflect current regulatory trajectories and capital allocation preferences documented across institutional investor disclosures. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Africa Cotton Market
Others
North America Automotive LED Lighting Market
Others
Insoluble Sulfur Market
Others
Global Geotechnical Instrumentation and Monitoring Market
Others
Security Envelopes Market
Others
Managed Testing Services Market
Others
Enterprise Video Content Management Market
Others
US Quantum Computing Market
Others
Mobile Retina Services Market
Others
Disposable Non Woven Sponge Market
Others
Griffin Beaker Market
Others
Europe Medical Simulation Market
Others
Global Car Wax Market
Others
Global Recruitment and Staffing Market
Others
Language Translation Device Market
Others
Latin America IT Device Market