
 Ultra Mobile Devices (UMD) Market | 2026-2036
Ultra Mobile Devices (UMD) Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra Mobile Devices (UMD) Market Analytics
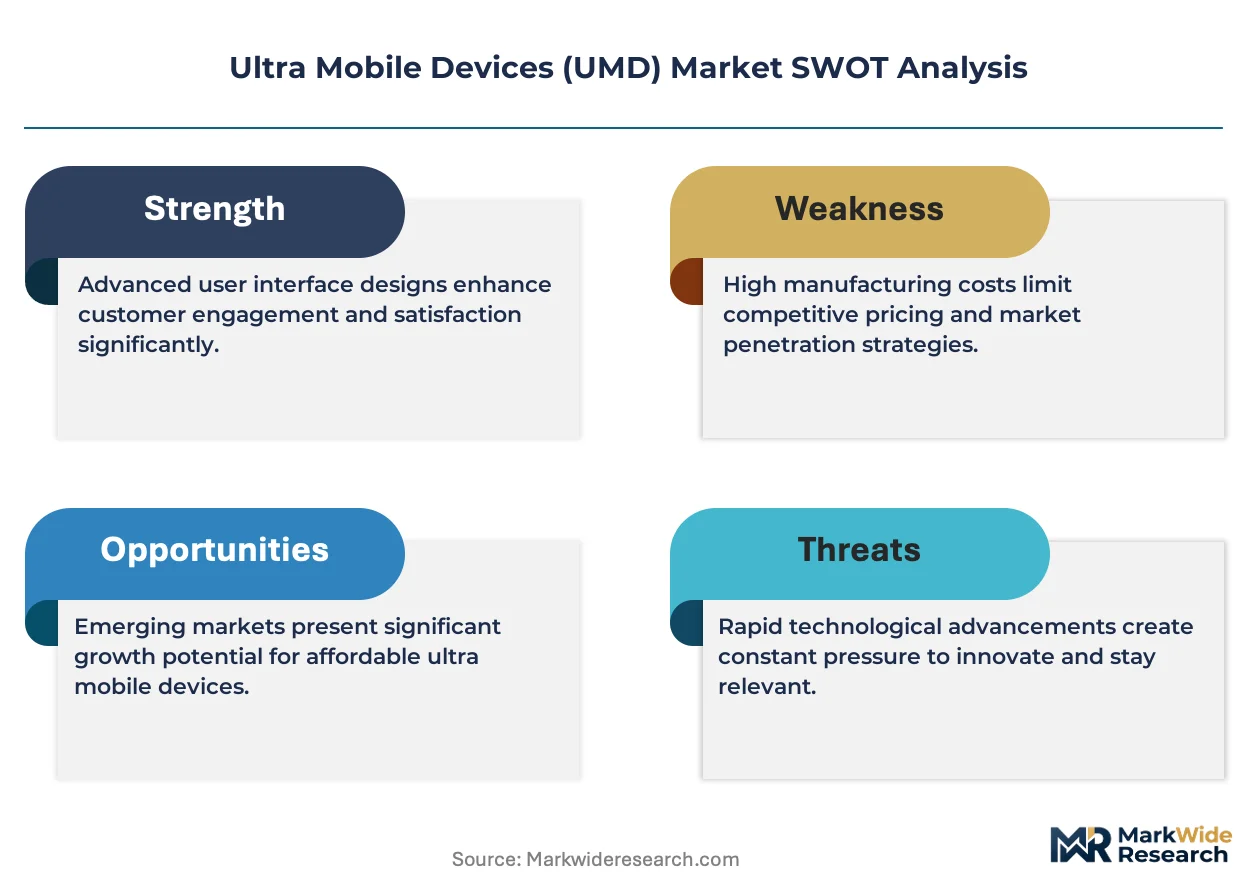
Enterprise buyer concentration is shifting from fragmented departmental purchases toward centralized procurement frameworks managed by IT governance teams. Samsung Electronics Co., Ltd. leverages its vertical integration in display and semiconductor manufacturing to control component costs across premium and mid-tier UMD portfolios. Apple Inc. differentiates through proprietary silicon architecture and tightly integrated software-hardware ecosystems that sustain premium pricing power. Microsoft Corporation anchors its position in enterprise-grade tablets and 2-in-1 convertibles where Windows compatibility drives replacement decisions.
Ultra Mobile Devices encompass portable computing and communication equipment weighing under two kilograms, typically featuring solid-state storage, low-power processors, and wireless connectivity modules designed for mobility-centric workflows. The category spans smartphones, tablets, wearables, and laptops, with wearables representing the fastest-expanding margin pool as health-monitoring sensors and extended battery chemistries attract premium positioning. 5G-enabled UMDs command structural priority in enterprise segments where low-latency connectivity supports field-service and logistics applications, while Wi-Fi 6 dominates educational institution deployments balancing performance against infrastructure upgrade costs.
The Federal Communications Commission (FCC) in the United States governs spectrum allocation and device certification, directly shaping which connectivity configurations manufacturers prioritize for North American market access. The European Union's Radio Equipment Directive (RED) and CE marking requirements enforce electromagnetic compatibility and safety standards that filter non-compliant imports from Asian manufacturing hubs. China's Ministry of Industry and Information Technology (MIIT) mandates network access licenses and GB standards compliance for devices operating on domestic cellular bands. Stakeholders must monitor divergent national certification timelines and spectrum auction outcomes when allocating R&D budgets across regional product variants.
Market Dynamics
Enterprise procurement centralization is colliding with distributed departmental budgets, creating a structural tension that reshapes vendor engagement models and contract negotiation leverage across the Ultra Mobile Devices ecosystem.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:Material disclosure mandates accelerate circular economy investments, compelling manufacturers to redesign supply chains for traceability compliance across member states.
- 5G network densification:Field-service and logistics operators in India deploy low-latency UMDs to replace legacy ruggedized equipment, compressing replacement cycles in enterprise verticals.
- Solid-state battery chemistry advances:Extended cycle life and reduced thermal management requirements enable thinner form factors that penetrate healthcare wearable segments previously constrained by power density.
Market Restraints
- Rare earth element concentration:Neodymium and dysprosium processing capacity clusters in China's Jiangxi province, exposing non-Chinese OEMs to export quota volatility and forced technology transfer pressures.
- Electromagnetic compatibility certification fragmentation:Divergent FCC, RED, and MIIT testing protocols extend time-to-market by 8-14 weeks for multi-region product variants.
- ARM architecture licensing costs:Per-unit royalty structures compress margin pools in sub-$300 device tiers where Android OEMs compete primarily on price.
Strategic Opportunities
- India's tier-2 city expansion:Mobile-first internet penetration in Surat, Indore, and Coimbatore drives replacement demand for aging 4G smartphone fleets ahead of 5G spectrum auctions.
- Windows-on-ARM convergence:Snapdragon X Elite platforms enable all-day battery performance in enterprise tablets, displacing x86 dominance in mobile productivity segments.
- EU Digital Product Passport mandate:Blockchain-enabled provenance tracking creates service revenue streams for compliance-as-a-service providers managing material disclosure workflows.
Industry Challenges
- RF front-end integration complexity:Millimeter-wave antenna module design requires specialized electromagnetic simulation talent scarce outside Taiwan and South Korea.
- Legacy enterprise software compatibility:Windows 10 migration deadlines force IT departments to evaluate UMD refresh cycles against application virtualization costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra Mobile Devices (UMD) Market |
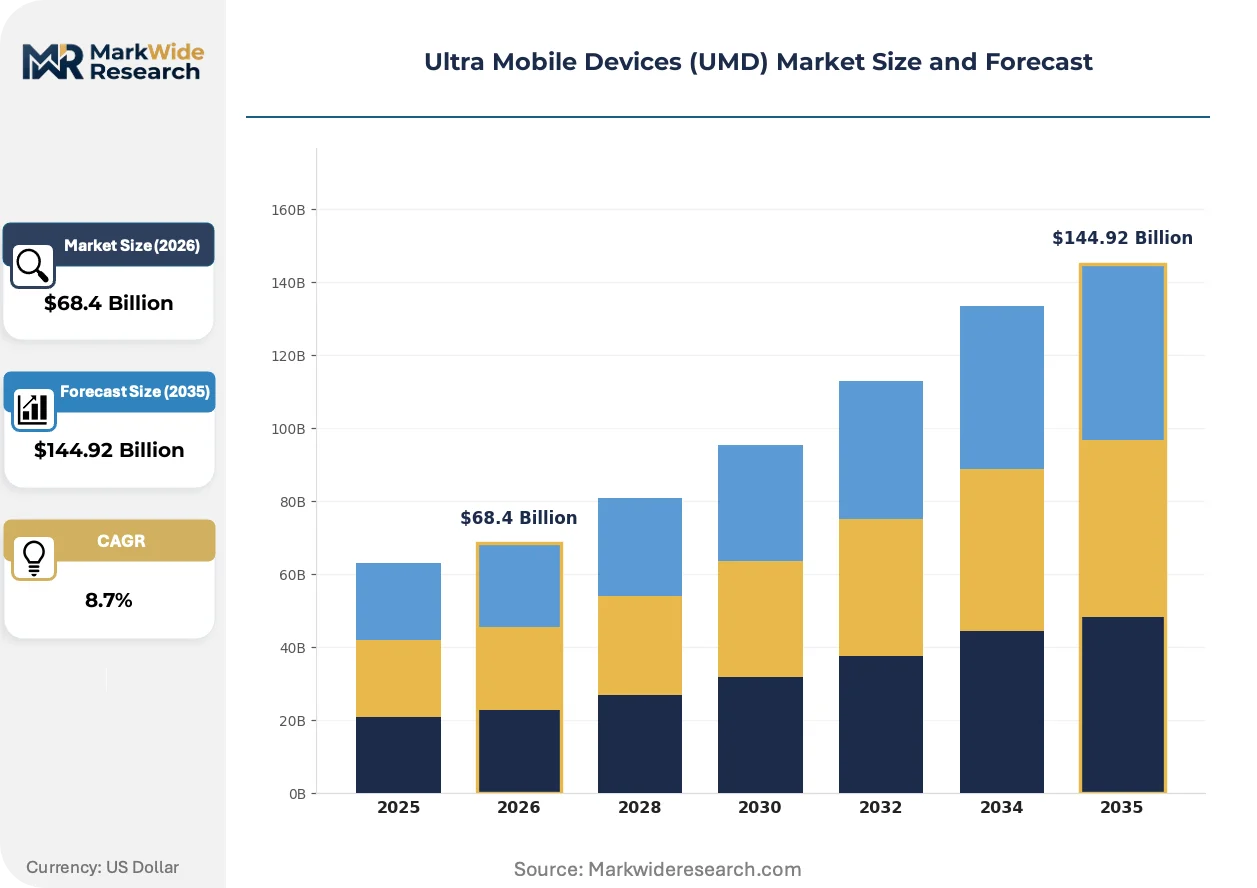
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Tablets, Wearables, Laptops Technology: 5G, Wi-Fi 6, Bluetooth, NFC End User: Consumers, Enterprises, Educational Institutions, Government Agencies Distribution Channel: Online Retail, Physical Stores, Telecom Operators, Direct Sales |
| Companies Covered | Samsung Electronics Co., Ltd., Apple Inc., Microsoft Corporation, Lenovo Group Limited, Google LLC, Huawei Technologies Co., Ltd., ASUSTeK Computer Inc., Dell Inc., HP Development Company L.P., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra Mobile Devices (UMD) Market Evolving Landscape
Computational photography and on-device machine learning are compressing the functional gap between dedicated imaging hardware and integrated smartphone sensors, redirecting R&D investment toward software-defined experiences.
On-device neural processing units are automating real-time video enhancement and computational photography workflows previously requiring cloud offload, enabling content creators and field journalists to produce broadcast-grade material without external equipment. Media production houses in Germany and Japan accelerate adoption of Snapdragon 8 Gen 3 and Apple A17 Pro platforms. This capability compression threatens standalone action camera and entry-level mirrorless camera segments by collapsing multiple device categories into single UMD form factors.
REACH substance restrictions and RoHS amendments tighten thresholds for cadmium and lead in solder alloys, forcing EMS providers to qualify lead-free alternatives with inferior thermal fatigue characteristics. European OEMs absorb 12-18 month qualification cycles for new interconnect materials. Medical-grade tablet manufacturers face the steepest compliance burden as MDR device classification rules overlap with environmental material mandates.
Departmental IT budget autonomy is fragmenting enterprise purchasing authority, with line-of-business managers in healthcare and logistics bypassing centralized procurement to acquire specialized UMDs through cloud marketplaces and direct vendor portals. This channel shift concentrates in United States mid-market enterprises with 500-5,000 employees. Hardware vendors respond with usage-based financing and embedded device management subscriptions that bypass traditional IT asset disposition workflows.
Ultra Mobile Devices (UMD) Market Segmentation
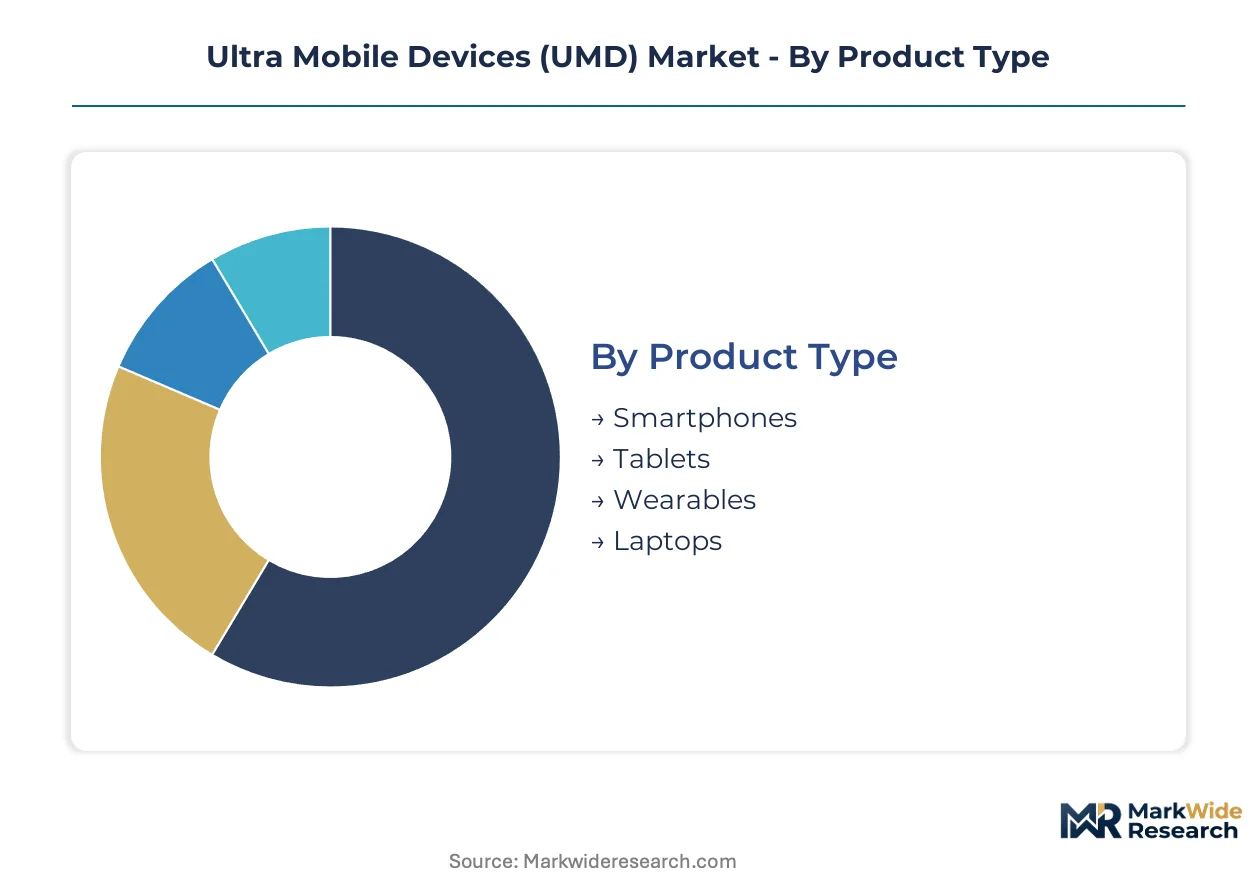
Ultra Mobile Devices fragment across four distinct dimensions that reshape how vendors allocate R&D, pricing power, and channel investment. Product type determines margin architecture and replacement cadence. Technology choices lock in connectivity partnerships and spectrum licensing costs. End-user concentration shifts procurement authority between centralized IT and distributed departmental budgets. Distribution channel selection governs working capital intensity and post-sale service attachment rates.
Product Type:
Volume concentrates in pocket-sized form factors while premium margin pools accumulate on wrist-worn health monitors and ultra-portable compute devices.
- Smartphones:Glass-and-aluminum slabs with OLED panels and multi-lens camera arrays dominate unit shipments across India, Indonesia, and Brazil. Replacement cycles in India's tier-2 cities compress as mobile-first internet access renders aging 4G fleets functionally obsolete ahead of 5G spectrum auctions.
- Wearables:Health-monitoring sensors, extended battery chemistries, and FDA-cleared ECG algorithms position wrist-worn devices as the fastest-climbing margin segment. Solid-state battery advances enable thinner form factors that penetrate medical-grade monitoring applications previously constrained by power density limitations.
- Tablets:Enterprise-grade slates with active stylus support and Windows-on-ARM compatibility anchor field-service workflows in logistics and healthcare verticals.
- Laptops:Sub-kilogram clamshells with Snapdragon X Elite or Apple Silicon architectures displace x86 dominance in mobile productivity segments where all-day battery performance drives refresh decisions.
Today's leader: Smartphones. Tomorrow's challenger: Wearables.
Technology:
Connectivity modules differentiate through latency profiles, spectrum licensing complexity, and infrastructure upgrade dependencies that segment customer budgets.
- 5G:Millimeter-wave and sub-6 GHz modems command structural priority in enterprise field-service deployments where low-latency connectivity supports real-time asset tracking and remote diagnostics. India's logistics operators accelerate replacement of legacy ruggedized equipment as network densification proceeds.
- Wi-Fi 6:Educational institutions in the United States and Germany balance performance requirements against infrastructure upgrade costs, favoring Wi-Fi 6 tablets over cellular-enabled alternatives for campus-bound deployments.
- Bluetooth:Low-energy protocols enable wearable-to-smartphone tethering and hearing-aid compatibility mandated by FCC regulations.
- NFC:Contactless payment and physical access control integration concentrates in European enterprise deployments where GDPR-compliant credential management drives hardware refresh cycles.
Enterprise 5G deployments expand most quickly. Wi-Fi 6 retains educational dominance.
End User:
Procurement authority fragments as departmental budgets bypass centralized IT governance, reshaping vendor engagement models and contract structures.
- Enterprises:Hybrid workforce management drives procurement of 2-in-1 convertibles and 5G-enabled tablets through cloud marketplaces and direct vendor portals. Mid-market firms with 500-5,000 employees concentrate this channel shift in the United States.
- Consumers:Brand loyalty and ecosystem lock-in sustain replacement cycles for premium smartphones and wearables in developed markets.
- Educational Institutions:Bulk purchasing agreements and Chromebook compatibility dominate K-12 deployments, while higher education prioritizes Windows and macOS ecosystems.
- Government Agencies:FIPS 140-2 encryption mandates and FedRAMP certification requirements filter vendor eligibility for federal procurement in the United States.
Enterprise procurement gains negotiating leverage fastest. Government compliance barriers protect incumbent positions.
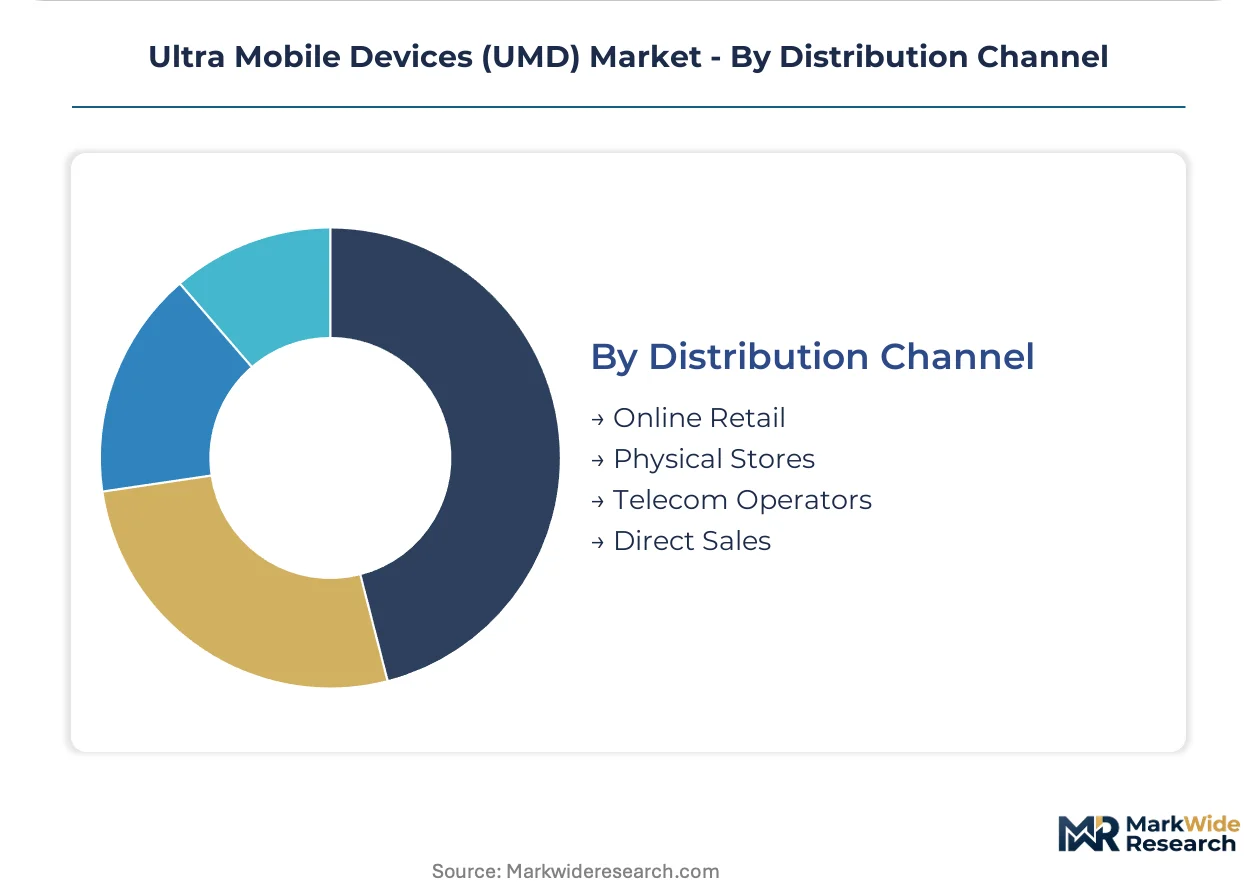
Distribution Channel:
Working capital intensity and service attachment rates diverge sharply between inventory-heavy retail and asset-light direct models.
- Telecom Operators:Subsidized handset financing and bundled data plans concentrate smartphone volume in India, where Reliance Jio and Bharti Airtel control subscriber acquisition costs.
- Online Retail:Amazon and Flipkart marketplaces aggregate comparison shopping for mid-tier Android devices, compressing margin pools through price transparency.
- Physical Stores:Experiential retail with on-site repair and trade-in services sustains premium positioning for Apple and Samsung flagship launches.
- Direct Sales:Usage-based financing and embedded device management subscriptions bypass traditional IT asset disposition workflows for enterprise accounts.
Telecom bundling anchors consumer volume. Direct sales capture enterprise lifetime value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's tier-2 city expansion outpaces Germany's enterprise refresh cycles in absolute volume, though Berlin's procurement frameworks command higher per-unit value capture across the Ultra Mobile Devices landscape.
United States
Mid-market enterprises with 500-5,000 employees fragment procurement authority through cloud marketplaces and direct vendor portals. FCC spectrum allocation and device certification govern North American market access for 5G-enabled field-service deployments. Austin and Seattle clusters concentrate Windows-on-ARM development talent for enterprise tablet platforms.
India
Mobile-first internet penetration in Surat, Indore, and Coimbatore compresses replacement cycles for aging 4G smartphone fleets ahead of 5G spectrum auctions. TRAI mandates network access licenses that filter non-compliant imports from Asian manufacturing hubs. Bengaluru's electronics manufacturing corridor anchors assembly capacity for sub-$300 Android device tiers.
Germany
Media production houses accelerate adoption of on-device neural processing units for broadcast-grade content creation. REACH substance restrictions and RoHS amendments tighten thresholds for cadmium and lead in solder alloys. Stuttgart's automotive electronics cluster drives demand for ruggedized tablets in logistics and field-service verticals.
China
MIIT mandates network access licenses and GB standards compliance for devices operating on domestic cellular bands. Rare earth element processing capacity clusters in Jiangxi province, exposing non-Chinese OEMs to export quota volatility. Shenzhen's Pearl River Delta ecosystem integrates millimeter-wave antenna module design with specialized electromagnetic simulation talent.
Japan
Content creators and field journalists leverage computational photography workflows on Snapdragon and Apple Silicon platforms. METI standards govern battery chemistry safety for wearable health-monitoring devices. Tokyo-Kanto region concentrates R&D investment for solid-state battery advances enabling thinner medical-grade tablet form factors.
Ultra Mobile Devices (UMD) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a tiered structure where premium ecosystem lock-in, mid-tier price compression, and enterprise service attachment define three distinct competitive vectors. Consolidation pressure concentrates in the sub-$300 Android segment where margin pools erode under ARM royalty burdens and price-transparent online retail. Strategic moves cluster around vertical integration into display and semiconductor manufacturing, plus usage-based financing models that bypass traditional IT asset disposition workflows.
Within the premium ecosystem tier, Apple Inc. and Samsung Electronics Co., Ltd. exemplify divergent approaches to silicon architecture and supply chain control. Microsoft Corporation anchors enterprise-grade positioning where Windows compatibility drives replacement decisions. Among Asia-Pacific-based fabricators, Huawei Technologies Co., Ltd. and Lenovo Group Limited occupy positions shaped by domestic regulatory frameworks and regional procurement preferences.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| Apple Inc. |
| Microsoft Corporation |
| Lenovo Group Limited |
| Google LLC |
| Huawei Technologies Co., Ltd. |
| ASUSTeK Computer Inc. |
| Dell Inc. |
| HP Development Company L.P. |
| Others |
Value Network & Pricing Analysis
Solid-state battery chemistry transitions are compressing thermal management costs while concentrating manufacturing expertise in Japan and South Korea, simultaneously enabling premium pricing for medical-grade wearables and tightening supply security around specialized electrolyte formulations. This dual effect reshapes procurement economics across enterprise and consumer tiers as vendors absorb extended qualification cycles against margin expansion in healthcare applications.
Pricing Analysis
Capacity additions in China's Jiangxi province are reshaping price floors for rare earth-dependent magnet assemblies, intensifying cost competition in sub-$300 Android tiers where ARM per-unit royalties already compress margins. Three-tier pricing structure across premium, standard, and economy levels separates Apple-Samsung ecosystem lock-in from mid-tier spec competition and entry-level carrier-subsidized volume. Price differentiation hinges on FDA-cleared health sensor certification and millimeter-wave antenna integration. Margins are tightening due to online retail price transparency, with Indian tier-2 city buyers exhibiting highest sensitivity while German media production houses show lowest.
Supply Chain Analysis
Electromagnetic simulation talent shortages in Taiwan and South Korea constrain millimeter-wave module design capacity, forcing OEMs to prioritize R&D allocation toward qualified foundry partnerships. Component sourcing draws from China's Pearl River Delta for final assembly, South Korea for OLED panels, and Taiwan for advanced semiconductor fabrication. Critical dependencies include neodymium-dysprosium magnets, solid-state electrolytes, and sub-6 GHz RF filters. Single-source vulnerability concentrates in Taiwan's specialized antenna design houses. Distribution runs through telecom operator bundling in India, direct enterprise portals in the United States, and experiential retail in developed Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Ultra Mobile Devices market functions as a regulatory compounder where the EU Digital Product Passport mandate accelerates compliance-as-a-service demand and reshapes vendor investment priorities toward traceability infrastructure.
For Market Incumbents: Cement ecosystem lock-in through proprietary silicon architecture investments that sustain premium positioning against Windows-on-ARM convergence threats. Deepen backward integration into display and battery cell manufacturing to defend margin pools against rare earth price volatility. Prioritize FDA and CE certification portfolios for health-monitoring wearables before MDR device classification rules tighten.
For New Entrants and Emerging Players: Cloud marketplace aggregators represent the most penetrable channel for bypassing traditional IT procurement in United States mid-market enterprises. Target India's tier-2 city replacement cycles ahead of 5G spectrum auctions with localized service networks. Pursue usage-based financing models that embed device management subscriptions to capture enterprise lifetime value.
For Investors and Strategic Acquirers: Valuations sit cheapest among vertically integrated component suppliers with captive rare earth processing and electromagnetic simulation capabilities. Long-term viability centers on five-to-ten year windows for solid-state battery chemistry commercialization and regulatory compliance platform consolidation. Watch EU Ecodesign enforcement intensity as the primary inflection signal for circular economy investment returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Windows-on-ARM Platform Convergence | Snapdragon X Elite compatibility displaces x86 dominance in enterprise tablets requiring all-day battery performance. |
| Solid-State Battery Manufacturing Scale-Up | Extended cycle life enables FDA-cleared medical wearables previously constrained by power density limitations. |
| EU Digital Product Passport Compliance | Blockchain-enabled provenance tracking creates service revenue streams for material disclosure workflow management. |
| Millimeter-Wave Antenna Module Integration | Taiwan and South Korea electromagnetic simulation talent scarcity limits qualified supplier pools for 5G enterprise deployments. |
| Direct Enterprise Portal Channel Expansion | Cloud marketplace aggregation bypasses traditional IT asset disposition workflows for 500-5,000 employee mid-market firms. |
Research Methodology
Direct dialogue with procurement officers at logistics operators, biomedical engineers at healthcare systems, platform architects at enterprise software vendors, and channel managers at telecom operators grounded qualitative insights in operational reality. Secondary validation drew from FCC device certification databases, EU RED compliance filings, TRAI network access license records, MIIT GB standards documentation, and customs trade flow data. Bottom-up shipment modeling and top-down spending pattern analysis were triangulated against vendor-reported segment performance.
Top-down macroeconomic framing anchored demand projections across the analysis window, while bottom-up unit economics modeled replacement cycles by product type, connectivity technology, end-user concentration, and distribution channel. Segmentation dimensions included form factor portability tiers, spectrum licensing requirements, procurement authority centralization, and service attachment rates. CAGRs were derived from logistic curve fitting to 5G network densification timelines and solid-state battery commercialization trajectories. Industry-specific inputs incorporated Windows-on-ARM enterprise adoption rates and EU Ecodesign compliance cost curves.
Revisions become necessary when FCC spectrum auction outcomes diverge from modeled allocations, EU material disclosure thresholds tighten beyond REACH baseline assumptions, or China's rare earth export quota volatility exceeds historical bands. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Cryogenic Storage Tanks Market
Others
Mobile Social Networks Market
Others
Thermal Insulation Solution for LNG and LPG Market
Others
Global Contactless Biometrics Technology Market
Others
Asia Pacific Automotive LED Lighting Market
Others
Powder Coating Equipment Market
Others
PC As a Service Market
Others
Global Electronic Filters Market
Others
5G Edge Computing Market
Others
Server Market
Others
Deep Sea Mining Market
Others
Rotary Union Market
Others
Aircraft Lighting Market
Others
Fluorite Market
Others
Global Smart Devices Market
Others
North America Luxury Car Market