
 Military Biometrics Market | 2026-2036
Military Biometrics Market Size, Share, and Industry Trends Forecast 2026-2036
Military Biometrics Market Analysis
Border security applications is expanding within the military biometrics landscape as cross-border threat detection priorities shift. Thales Group leverages its European defense electronics heritage to anchor multimodal biometric contracts with NATO-aligned agencies. IDEMIA sustains competitive positioning through deep specialization in large-scale fingerprint and iris enrollment systems for national security programs. NEC Corporation dominates high-performance facial recognition algorithm development, particularly for surveillance integration in contested environments.
Military biometrics encompasses the automated measurement and statistical analysis of physiological and behavioral characteristics—fingerprint minutiae, iris patterns, facial geometry, and voiceprints—to verify or establish the identity of personnel in defense and security operations. Systems typically operate with false acceptance rates below 0.001% and integrate with hardened command-and-control networks for real-time battlefield identity assurance. Fingerprint recognition occupies the most mature technology tier, with established supply chains and standardized interoperability protocols across allied forces. Facial recognition represents the fastest-expanding segment, driven by advances in edge-computing deployment and thermal-imaging compatibility for nighttime operations. Cloud-based and hybrid deployment modes are capturing growing share as defense agencies seek federated identity databases without sacrificing operational security.
The U.S. National Institute of Standards and Technology (NIST) and the European Union AI Act collectively shape algorithmic testing mandates, data governance requirements, and cross-border information sharing protocols for military biometric systems. Compliance with these frameworks determines market access for vendors and influences procurement specifications across defense ministries. Stakeholders must monitor evolving export control classifications for biometric AI software, as regulatory fragmentation between Washington and Brussels threatens to complicate multinational program integration and supplier qualification pathways.
Market Dynamics
NATO border security agencies are consolidating procurement around multimodal biometric screening systems that fuse fingerprint, iris, and facial recognition into single enrollment workflows, compressing vendor qualification timelines and reshaping competitive positioning around algorithmic accuracy certifications.
Growth Catalysts
- EU AI Act compliance mandates:Defense ministries across Europe are accelerating biometric system upgrades to meet algorithmic accuracy thresholds for facial recognition in high-risk security contexts.
- Cross-border threat detection prioritization:Border security applications are absorbing elevated procurement budgets as NATO member states harden perimeter identity verification infrastructure.
- Edge-computing deployment:Thermal-imaging compatible facial recognition systems are enabling real-time battlefield identity assurance without cloud dependency.
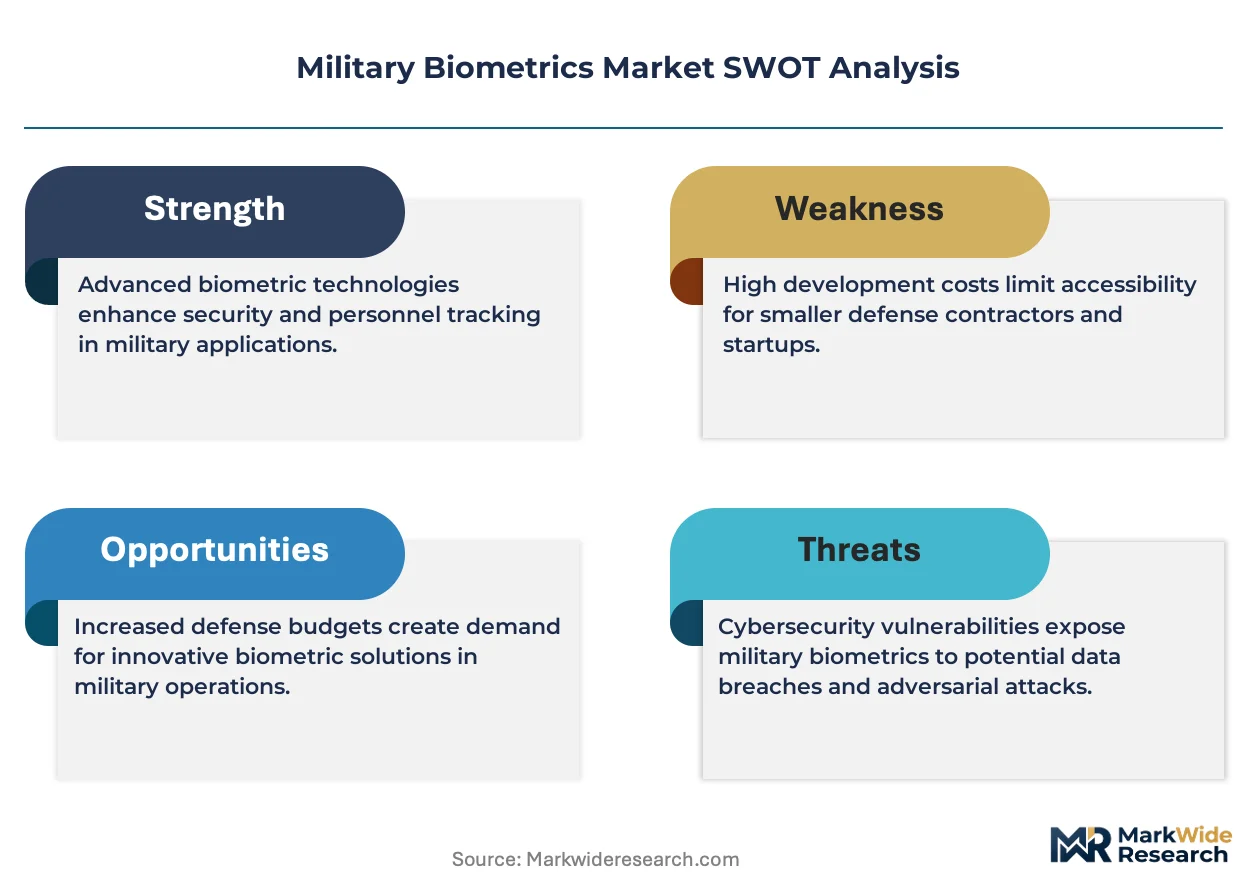
Market Restraints
- Export control fragmentation:Divergent Washington-Brussels classifications for biometric AI software are complicating multinational program integration and supplier qualification pathways.
- Algorithmic retraining costs:Continuous model updates to maintain NIST Face Recognition Vendor Test compliance impose recurring operational expenditure burdens on defense contractors.
- Data governance friction:GDPR-mandated consent frameworks conflict with military intelligence collection requirements, constraining cross-border biometric database federation.
Strategic Opportunities
- Contested environment surveillance:Denied-area operations are creating demand for passive biometric collection systems that operate without subject cooperation.
- Behavioral biometrics convergence:Gait analysis and keystroke dynamics are merging with physiological modalities to enable continuous authentication in command-and-control networks.
- Cloud-hybrid architectures:Federated identity databases with tactical edge nodes are opening procurement channels for vendors with zero-trust security clearances.
Industry Challenges
- Adversarial attack resilience:Deepfake injection and presentation attacks are forcing continuous algorithmic hardening, stretching research and development timelines.
- Interoperability certification delays:Allied force biometric data exchange protocols remain fragmented across national standards, impeding coalition operational readiness.
- Specialized workforce scarcity:Cleared machine learning engineers with biometric system deployment experience command premium compensation, constraining program scale-up velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Biometrics Market |
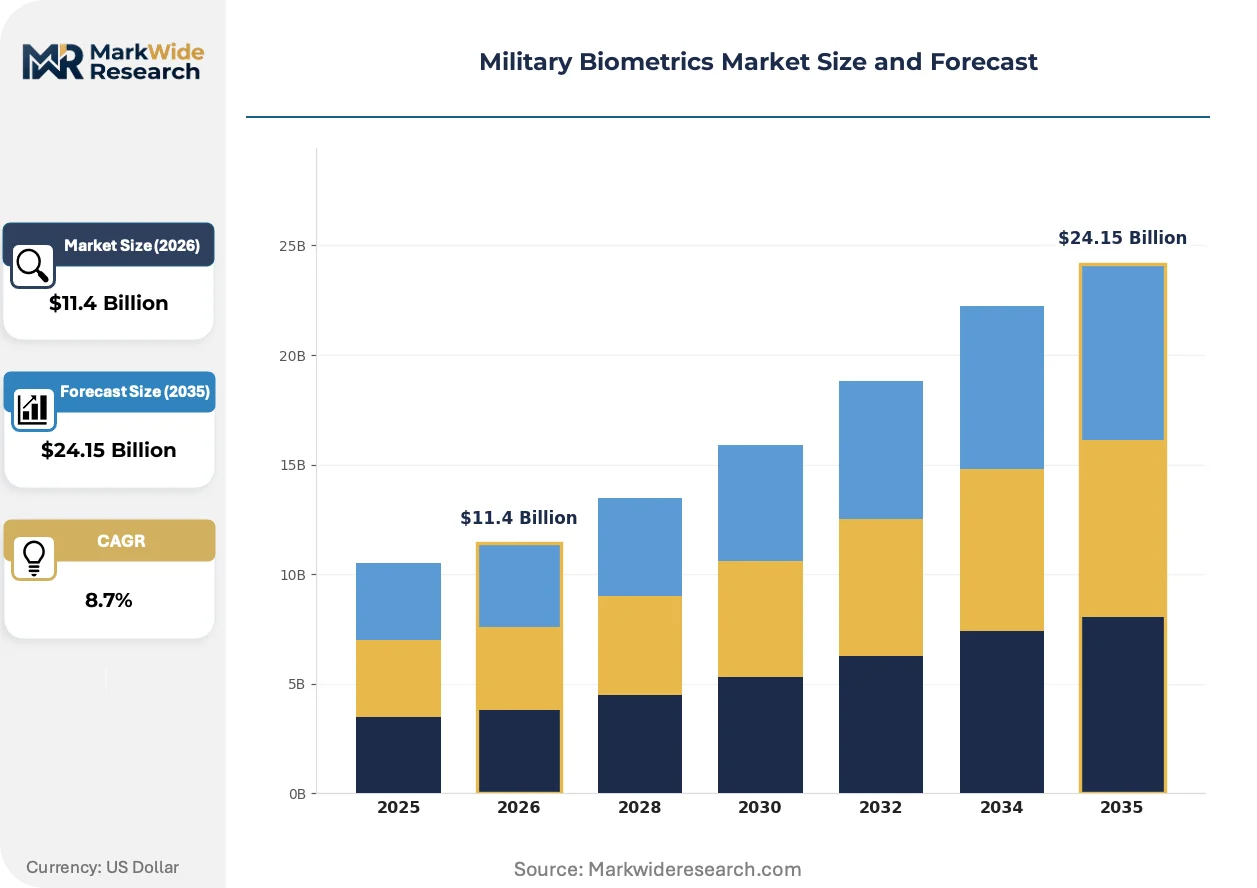
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $24.15 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fingerprint Recognition, Iris Recognition, Facial Recognition, Voice Recognition Application: Access Control, Surveillance Systems, Identification Verification, Border Security End User: Defense Organizations, Government Agencies, Security Firms, Military Contractors Deployment Mode: On-Premises, Cloud-Based, Hybrid, Mobile Solutions |
| Companies Covered | Leidos, Safran, Thales Group, M2SYS Technology, Aware, IDEMIA, HID Global, Fulcrum Biometrics, NEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Biometrics Market Emerging Trajectories
Thermal-imaging compatible facial recognition is compressing operational constraints for nighttime and obscured-conditions identity verification. Algorithmic testing mandates from Brussels and Washington are rewriting procurement specifications. Defense agencies are reconfiguring deployment architectures around federated data models.
Edge-deployed neural inference engines are electrifying biometric processing latency in tactical environments. Special operations units across NATO forces are fielding palm-sized enrollment devices that perform full multimodal capture and matching within thirty seconds. This capability compression is eliminating the gap between strategic intelligence databases and point-of-contact identity verification.
The EU AI Act's high-risk system classification is mandating conformity assessment procedures for biometric identification in defense contexts. European defense ministries are embedding algorithmic impact documentation into tender specifications. Vendors lacking established European Economic Area presence are facing extended qualification timelines relative to incumbents with Brussels regulatory affairs capabilities.
Buyer concentration around national identity intelligence platforms is consolidating vendor relationships toward multi-year enterprise agreements. The United States Department of Defense is displacing point-solution procurement with integrated identity-as-a-service frameworks. This contractual evolution favors systems integrators with existing classified infrastructure clearances over specialized biometric hardware suppliers.
Military Biometrics Market Segmentation
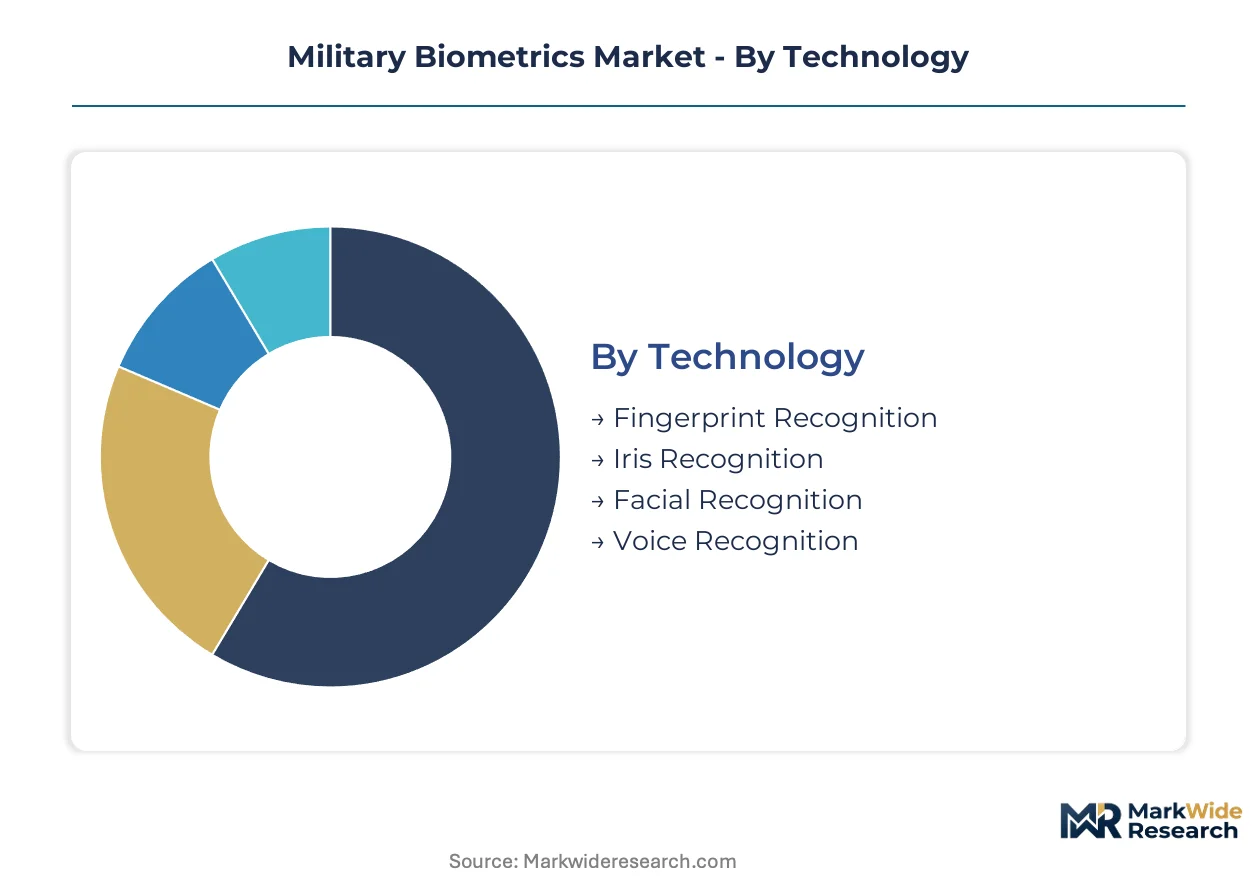
Segmentation in military biometrics reveals distinct procurement patterns across technology maturity tiers and operational security requirements. Defense agencies calibrate investments between proven fingerprint infrastructure and emerging facial recognition capabilities while navigating deployment constraints from battlefield edge nodes to federated cloud architectures.
Technology:
Standardized interoperability protocols dominate fingerprint and iris systems, while facial and voice recognition demand extensive algorithmic customization for contested environment performance.
- Fingerprint Recognition:Mature minutiae-matching algorithms operate with false acceptance rates below 0.001% across hardened NATO command networks. Defense ministries in the United States and Germany prioritize this modality for base access control and personnel enrollment, driven by established supply chains and cross-allied data exchange compatibility.
- Facial Recognition:Thermal-imaging compatible neural networks enable real-time identity verification in nighttime and obscured conditions without cloud dependency. Special operations units across NATO forces are absorbing the steepest procurement volume gains as edge-computing deployment eliminates latency between tactical capture and strategic database matching.
- Iris Recognition:Pattern-matching accuracy at distance remains the technical benchmark for high-security checkpoint applications.
- Voice Recognition:Behavioral biometric analysis for continuous authentication in command-and-control networks is gaining traction among signals intelligence units.
Leading the category by volume: Fingerprint Recognition. Growing fastest: Facial Recognition.
Application:
Cost tier stratification separates perimeter infrastructure investments from portable field deployment systems.
- Border Security:Multimodal screening fusion—combining fingerprint, iris, and facial capture into single enrollment workflows—commands premium procurement budgets across NATO member states. Agencies in Poland and Estonia are accelerating hardened checkpoint installations as cross-border threat detection priorities intensify.
- Surveillance Systems:Passive biometric collection in denied-area operations requires specialized hardware with adversarial attack resilience against deepfake injection. United States Special Operations Command and British Army Intelligence Corps are driving demand for palm-sized enrollment devices performing full multimodal matching within thirty seconds.
- Access Control:Base and facility perimeter systems represent the standardized procurement tier with established vendor relationships.
- Identification Verification:Point-of-contact identity assurance for detainee processing and personnel recovery operations occupies the mid-tier investment band.
Highest absolute spending: Border Security. Steepest budget acceleration: Surveillance Systems.
End User:
Customer type determines security clearance requirements and contract vehicle complexity.
- Defense Organizations:National military services with classified infrastructure clearances consolidate procurement around multi-year enterprise agreements. The United States Department of Defense is displacing point-solution purchasing with integrated identity-as-a-service frameworks that favor systems integrators over specialized hardware vendors.
- Government Agencies:Border control and homeland security ministries operate under distinct budget authorities with faster vendor qualification timelines.
- Security Firms:Private contractors supporting coalition logistics and facility protection represent fragmented demand with limited standardization.
- Military Contractors:Prime defense suppliers integrating biometric subsystems into broader platform deliveries face extended supply chain certification requirements.
Contract concentration centers on Defense Organizations. Procurement velocity favors Government Agencies.
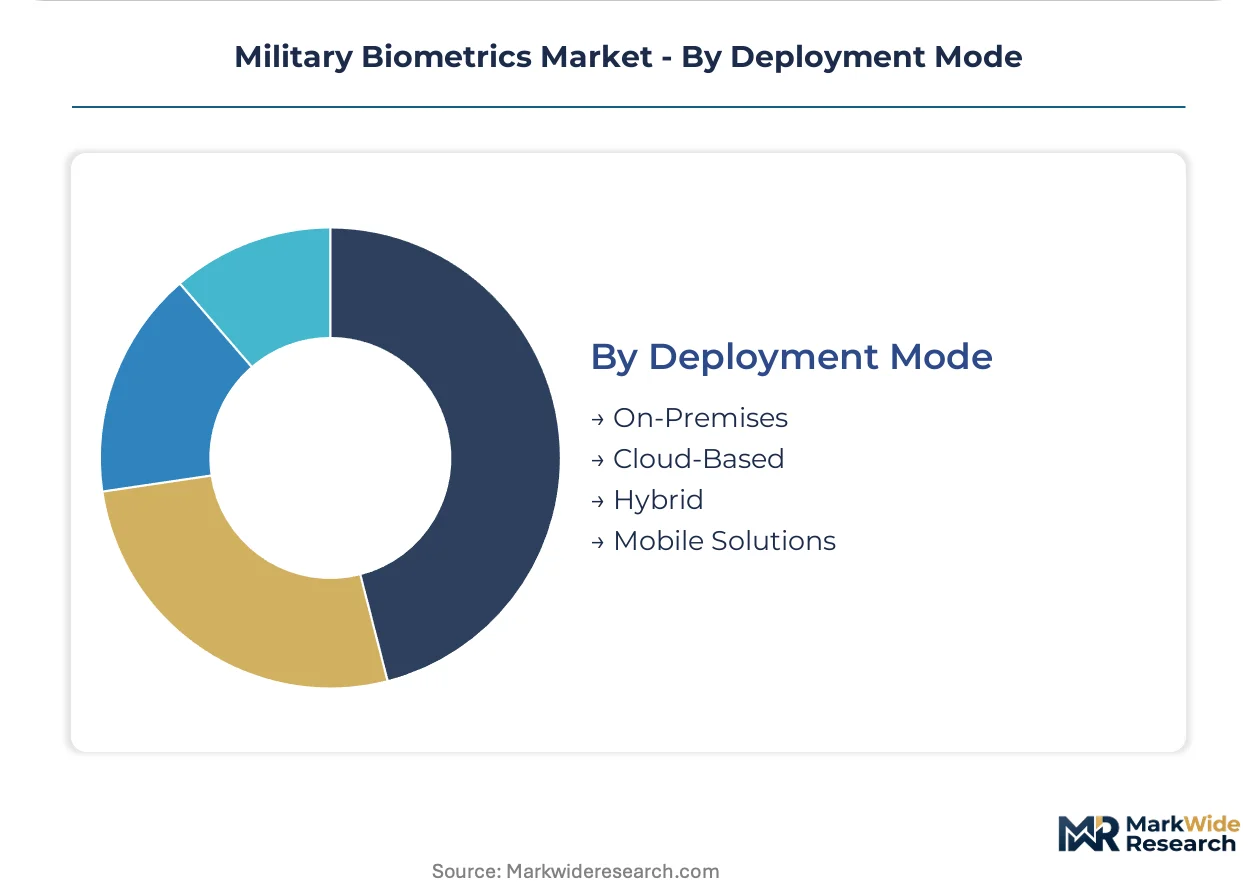
Deployment Mode:
Maturity gradient runs from hardened on-premises installations to experimental mobile field systems.
- Hybrid:Federated identity databases with tactical edge nodes are capturing growing share as defense agencies seek centralized intelligence fusion without sacrificing operational security. Zero-trust architecture mandates from United States Cyber Command and NATO Communications and Information Agency are opening procurement channels for vendors with appropriate security clearances.
- Cloud-Based:Strategic intelligence platforms require continuous algorithmic retraining to maintain NIST Face Recognition Vendor Test compliance, imposing recurring operational expenditure burdens that favor vendors with established European Economic Area regulatory affairs capabilities.
- On-Premises:Air-gapped installations for highest-sensitivity facilities remain the conservative procurement default.
- Mobile Solutions:Disconnected operation in contested environments is driving rapid capability compression into palm-sized form factors.
Widest installed base: On-Premises. Fastest architectural shift: Hybrid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of biometric hardware concentrates in established defense electronics clusters, while procurement demand distributes across NATO allied nations with varying security clearance infrastructures and regulatory compliance timelines.
United States
The Department of Defense funds next-generation identity intelligence platforms through consolidated enterprise agreements. NIST Face Recognition Vendor Test compliance mandates algorithmic accuracy thresholds for vendors seeking federal contracts. Defense contractors in the Washington DC metropolitan area and Boston corridor anchor multimodal system integration for special operations units.
Germany
Bundeswehr modernization programs prioritize fingerprint and iris enrollment infrastructure for base access control networks. EU AI Act high-risk system classifications impose conformity assessment procedures on facial recognition procurement. Industrial clusters in Bavaria and Baden-Württemberg host subsystem suppliers for NATO interoperable biometric data exchange protocols.
United Kingdom
British Army Intelligence Corps drives demand for palm-sized enrollment devices capable of contested-environment operation. Ministry of Defence procurement specifications align with GDPR-mandated data governance frameworks for cross-border database federation. London and Southeast England concentrate systems integrators with classified infrastructure clearances.
Poland
Eastern flank NATO positioning accelerates hardened checkpoint installations with multimodal screening fusion capabilities. National security agencies align biometric upgrades with EU AI Act algorithmic transparency requirements. Warsaw and Tri-City metropolitan areas anchor border security infrastructure deployment along external Schengen boundaries.
France
DGA procurement channels favor vendors with established European Economic Area regulatory affairs capabilities for defense biometric systems. Thales Group leverages domestic defense electronics heritage for multimodal contracts with NATO-aligned agencies. Paris-Saclay and Toulouse clusters concentrate algorithm development for thermal-imaging compatible facial recognition.
Military Biometrics Market Vendor Landscape
Top-tier vendors anchor multimodal system integration, while specialized biometric hardware suppliers occupy mid-tier procurement channels. The vendor base stratifies across three tiers: systems integrators with classified infrastructure clearances, algorithm developers with NIST certification track records, and point-solution hardware manufacturers. Strategic archetypes include European defense electronics conglomerates, Japanese precision technology groups, and American identity intelligence platforms. Competitive moves concentrate on multi-year enterprise agreement consolidation and zero-trust security clearance acquisition.
Within the European defense electronics tier, Thales Group and Safran exemplify vendors leveraging regulatory proximity to Brussels for EU AI Act compliance positioning. IDEMIA and NEC Corporation anchor specialized algorithm development, with the former representing fingerprint and iris enrollment heritage and the latter exemplifying high-performance facial recognition neural network capabilities. Leidos occupies a position among American systems integrators displacing point-solution procurement with integrated identity-as-a-service frameworks for Department of Defense programs.
| Leading Market Players |
|---|
| Leidos |
| Safran |
| Thales Group |
| M2SYS Technology |
| Aware |
| IDEMIA |
| HID Global |
| Fulcrum Biometrics |
| NEC Corporation |
| Others |
Supply Flow & Price Mechanics
NATO procurement consolidation around multimodal biometric screening systems is compressing vendor qualification timelines and forcing supply chains to absorb algorithmic retraining costs, which in turn stratifies pricing across certification tiers.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as defense ministries accelerate EU AI Act compliance upgrades. Three-tier pricing structure across premium, standard, and economy levels separates NIST-certified algorithm developers from uncertified hardware suppliers. Pricing pressure stems from continuous model retraining burdens for FRVT compliance. Government agencies exhibit highest price sensitivity due to fixed budget authorities, while defense organizations prioritize performance over cost.
Supply Chain Analysis
NIST certification and EU AI Act conformity assessment procedures gate supplier entry, elongating qualification timelines for vendors lacking established European Economic Area presence. Hardware production concentrates in the United States, Germany, and Japan, drawing from specialized image sensor foundries, neural inference chip fabricators, and hardened enclosure manufacturers. Single-source vulnerability runs through thermal-imaging sensor suppliers. Distribution runs through systems integrators with classified infrastructure clearances rather than direct vendor-to-buyer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cleared machine learning engineers with biometric deployment experience represent the binding capacity constraint, propping pricing power for vendors with established security clearance pipelines.
For Market Incumbents: Lock in multi-year enterprise agreements with United States Department of Defense identity-as-a-service frameworks before procurement consolidation hardens. Deepen backward integration into neural inference chip design to capture margin from edge-computing deployment acceleration. Counter emerging entrant pressure by accelerating EU AI Act regulatory affairs capabilities in Brussels. For New Entrants and Emerging Players: Security firms supporting coalition logistics represent the most penetrable buyer archetype, as these fragmented customers lack standardized vendor relationships and move faster than defense organization procurement channels. Target palm-sized enrollment device contracts for special operations units where incumbent systems integrators lack tactical field experience. Pursue zero-trust security clearance acquisition as the primary go-to-market enabler. For Investors and Strategic Acquirers: The window for entry favors algorithm developers with NIST FRVT certification track records and established European regulatory affairs infrastructure. Long-term viability hinges on federated identity database architecture capabilities as hybrid deployment modes capture growing share. Watch for Department of Defense displacement of point-solution procurement toward integrated frameworks as the inflection signal for consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| NIST FRVT Certification Investment | Algorithm developers with established test track records capture federal contract eligibility. |
| EU AI Act Regulatory Affairs Expansion | Brussels-based compliance capabilities compress vendor qualification timelines for European defense ministries. |
| Edge-Computing Hardware Miniaturization | Palm-sized multimodal enrollment devices unlock special operations procurement channels. |
| Zero-Trust Security Clearance Acquisition | Cleared personnel pipelines enable hybrid federated identity database deployments. |
| Backward Integration into Neural Inference | In-house chip design captures margin from thermal-imaging compatible facial recognition demand. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with defense procurement officers, biometric system engineers, regulatory affairs specialists at European defense ministries, and cleared systems integrators. NIST technical reports, EU AI Act implementation guidance, NATO standardization agreements, and Department of Defense budget justification documents provided validation layers. Bottom-up segment sizing triangulated against top-down defense expenditure allocation models.
Granularity-level modeling operated at technology-modality, application-use-case, and deployment-architecture intersections across the projection horizon. Fingerprint, facial, iris, and voice recognition modalities were sized separately with distinct maturity-adjusted growth parameters. Border security, surveillance, access control, and identification verification applications carried differential security-clearance and procurement-timeline assumptions. CAGRs derived from defense budget trajectory analysis and algorithmic accuracy improvement curves.
Revisions become necessary when NIST FRVT accuracy thresholds tighten, EU AI Act enforcement interpretations shift, or export control classifications fragment further between Washington and Brussels. Forecasts reflect assumptions about NATO interoperability protocol adoption rates and coalition operational readiness requirements. A model refresh is warranted upon material change in Department of Defense identity-as-a-service procurement velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Global Authentication Services Market
Biometrics & Identity Management
China Mobile Biometrics Market
Biometrics & Identity Management
Biometric ATM Market
Biometrics & Identity Management
Biometric Passport Market
Biometrics & Identity Management
Global Authentication and Brand Protection Market
Biometrics & Identity Management
Identity Theft Protection Services Market
Biometrics & Identity Management
E-Government Identity Management Market
Biometrics & Identity Management
Global Behavioral Biometrics Market
Biometrics & Identity Management
United States Facial Recognition Market
Biometrics & Identity Management
United States Biometrics Market
Biometrics & Identity Management
Voice Biometric Solutions Market
Biometrics & Identity Management
Gait Biometrics Market
Biometrics & Identity Management
Europe Government and Security Biometrics Market
Biometrics & Identity Management
Global Biometric Systems Market
Biometrics & Identity Management
Password Management Market
Biometrics & Identity Management
Mobile Devices User Authentication Services Market