
 City Surveillance Market | 2026-2036
City Surveillance Market Size, Share, and Industry Trends Forecast 2026-2036
City Surveillance Market Outlook
GDPR's Article 35 data protection impact assessments is restructuring vendor qualification protocols across European city procurement offices. Hangzhou Hikvision Digital Technology Co., Ltd. leverages in-house sensor fabrication to sustain cost leadership in high-density camera deployments. Axis Communications AB differentiates through open-platform architecture that navigates interoperability mandates in multi-vendor municipal ecosystems. Bosch Security and Safety Systems anchors European market presence with cybersecurity-certified hardware lines that satisfy EN 62676 standards.
City surveillance encompasses networked visual monitoring infrastructure combining fixed and pan-tilt-zoom cameras with centralized video management platforms, typically operating across IP-based architectures with latency thresholds below 150 milliseconds for real-time analytics. The primary purpose involves automated detection of security incidents, traffic anomalies, and crowd behavior patterns to enable rapid response coordination by municipal authorities. IP Cameras now dominate new installations as municipalities phase out analog CCTV legacy networks that lack edge-computing capability. Video Analytics represents the fastest-expanding technology layer, with motion detection algorithms migrating from rule-based to deep-learning architectures that reduce false-positive rates. Government Agencies absorb the majority of capital expenditure, though Commercial Spaces are emerging as a distinct procurement segment with cloud-native deployment preferences.
The EU AI Act imposes conformity obligations on biometric identification systems that reshape product development timelines for vendors serving European cities. China's GB standards for intelligent video surveillance, administered by SAMR, mandate domestic encryption protocols that influence component sourcing decisions. India's CEA guidelines for critical infrastructure protection are expanding the regulated perimeter of surveillance deployments beyond traditional police jurisdictions. Stakeholders must monitor how divergent data localization requirements between jurisdictions affect cloud architecture choices and cross-border service delivery models.
Market Dynamics
The EU AI Act's high-risk classification of biometric surveillance systems is forcing vendors to redesign product architectures and compliance protocols, compressing development timelines while expanding certification costs across European municipal procurement cycles.
Growth Catalysts
- Smart city transit modernization:Metropolitan authorities in China are accelerating integrated video analytics procurement for subway and bus networks. Edge-computing camera density targets now exceed legacy analog replacement rates.
- GB standards mandate:China's SAMR-administered encryption protocols for intelligent video surveillance are driving domestic component sourcing and creating captive supply chains for local vendors.
- Critical infrastructure expansion:India's CEA guidelines are extending regulated surveillance perimeters beyond police jurisdictions into power grids and transportation nodes.
Market Restraints
- Semiconductor input volatility:Image sensor and SoC pricing fluctuations compress hardware margins for camera OEMs dependent on foundry capacity allocation.
- Regulatory fragmentation:Divergent data localization requirements between EU GDPR, China GB standards, and India CEA guidelines fragment cloud architecture roadmaps and inflate compliance overhead.
- Technical latency thresholds:Sub-150 millisecond real-time analytics requirements constrain edge-processing hardware choices and limit software optimization flexibility.
Strategic Opportunities
- Cloud-native commercial deployment:Retail and logistics facilities in Germany and France are adopting subscription-based video management platforms, displacing capital-heavy government procurement models.
- Multi-vendor interoperability:Open-platform architecture demand from Dutch and Swedish municipal IT departments creates white space for middleware specialists bridging proprietary camera protocols.
- Deep-learning analytics convergence:Fusion of computer vision with lidar and thermal sensors is opening perimeter security applications for critical infrastructure operators in Japan and South Korea.
Industry Challenges
- Edge-AI engineering scarcity:Municipal system integrators in Italy and Spain face acute shortages of firmware developers capable of optimizing neural network inference on resource-constrained camera SoCs.
- Legacy analog migration complexity:Hybrid IP-analog transition projects in Poland and Czech Republic municipalities suffer integration failures where coaxial infrastructure cannot support Power-over-Ethernet retrofit requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | City Surveillance Market |
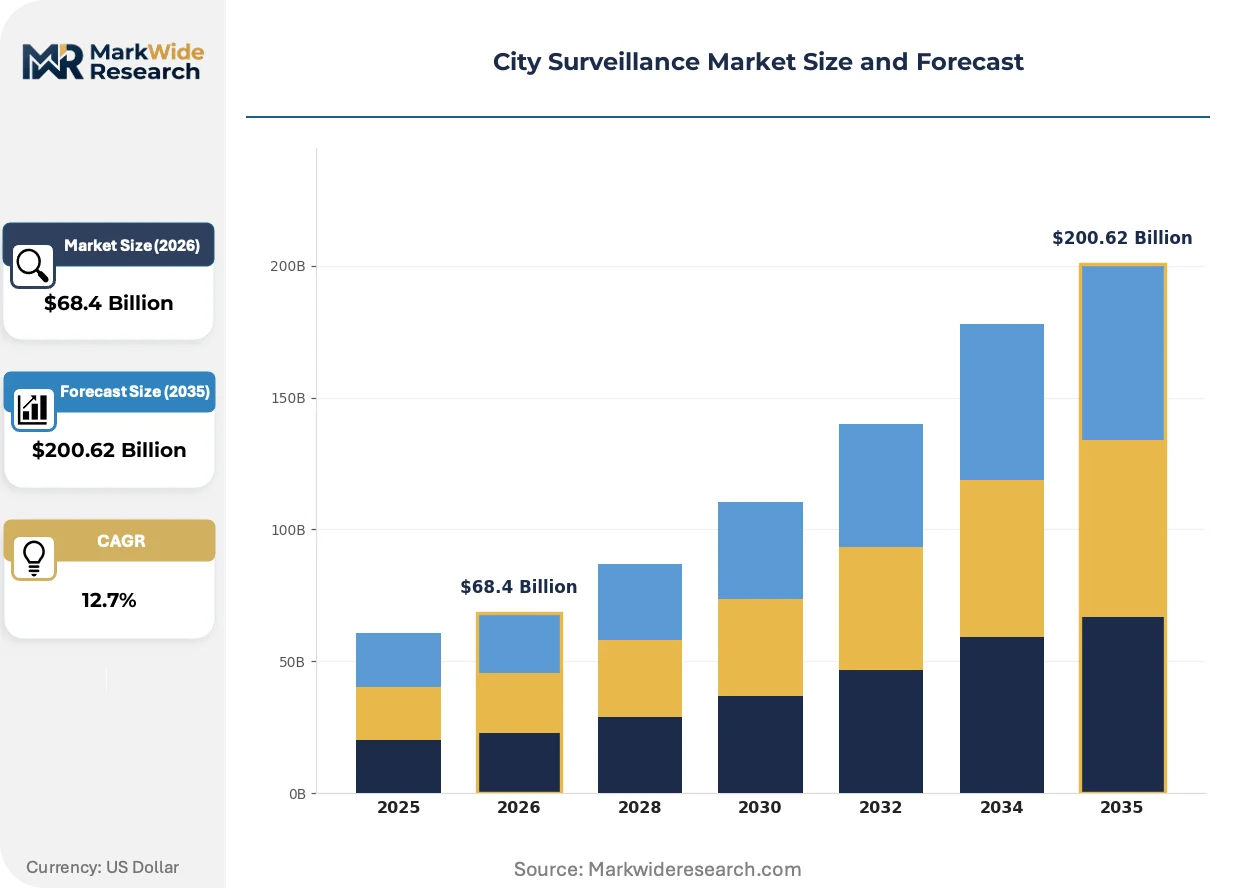
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $200.62 Billion |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Analog CCTV, IP Cameras, Thermal Cameras, Dome Cameras Application: Traffic Monitoring, Public Safety, Crime Prevention, Retail Security End User: Government Agencies, Commercial Spaces, Residential Areas, Educational Institutions Technology: Wireless Communication, Video Analytics, Cloud Storage, Motion Detection |
| Companies Covered | Hangzhou Hikvision Digital Technology Co., Ltd., Zhejiang Dahua Technology Co., Ltd., Axis Communications AB, Bosch Security and Safety Systems, Motorola Solutions, Inc., Hanwha Vision, Honeywell International Inc., Genetec Inc., NEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
City Surveillance Market Strategic Shifts
Deep-learning video analytics is compressing false-positive rates and enabling predictive incident detection, while regulatory pressure on biometric systems accelerates privacy-preserving computer vision alternatives.
Edge-deployed transformer-based object detection is electrifying real-time threat classification in high-density urban deployments. Dutch and Singaporean transit authorities are adopting these models for platform safety monitoring. The technology is electrifying competitive differentiation around inference latency rather than camera hardware specifications.
The EU AI Act's conformity obligations for biometric identification systems are restructuring vendor product roadmaps serving European cities. Development timelines now embed third-party audit checkpoints before market release. High-risk system vendors are responding by bifurcating European and non-European product lines to isolate compliance scope.
Municipal procurement offices are consolidating vendor qualification around cybersecurity certification tiers rather than unit cost metrics. French and German city authorities now require EN 62676-compliant hardware as a baseline eligibility filter. This behavioral shift is most visible in RFP evaluation scoring where certification weighting now exceeds price-point differentials.
City Surveillance Market Segmentation
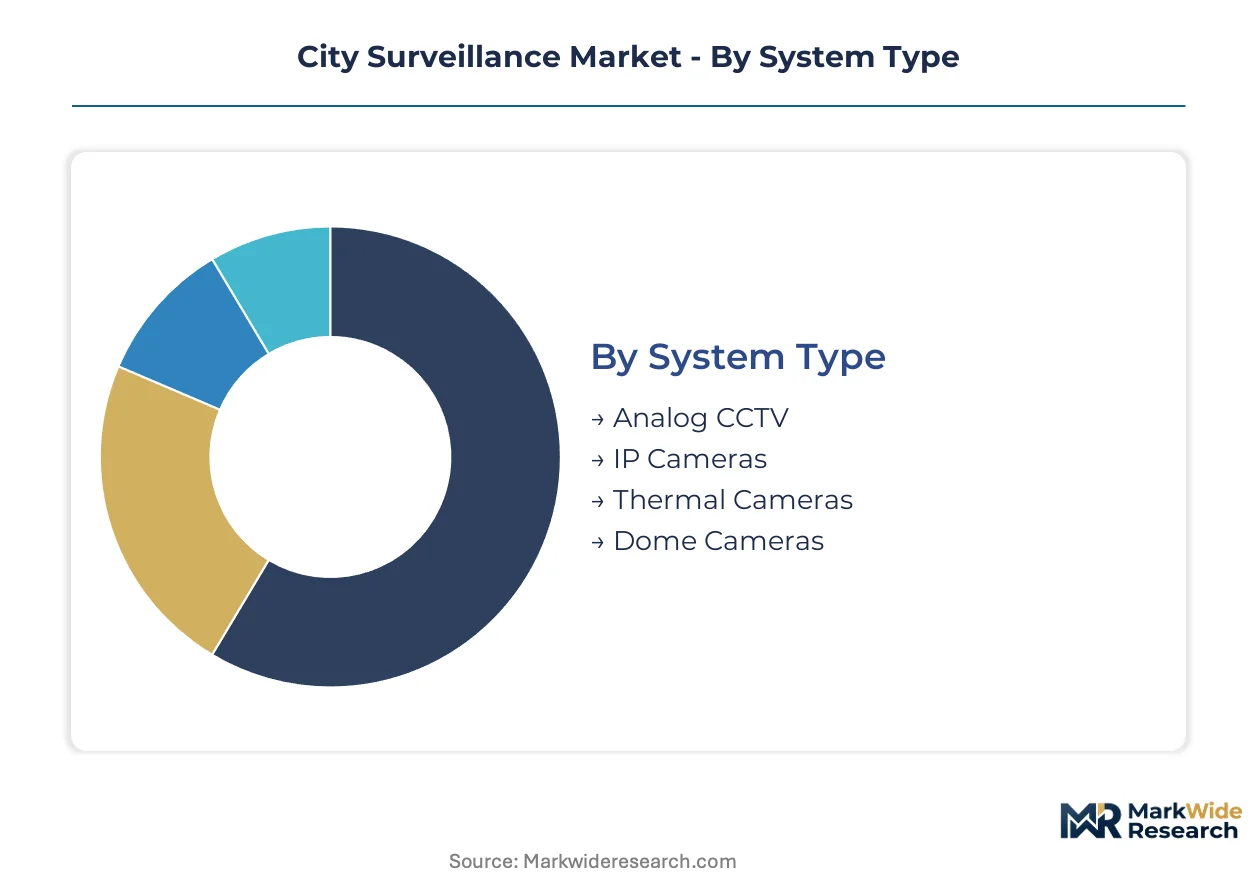
Procurement patterns in city surveillance diverge sharply across hardware generations, software intelligence layers, and operational mandates. Municipal buyers prioritize interoperability and edge-computing capability while commercial adopters emphasize cloud-native architectures. Understanding these fault lines enables vendors to align R&D roadmaps with divergent buyer workflows and compliance requirements.
System Type:
Hardware specifications determine infrastructure lifecycle costs and analytics capability ceilings for municipal buyers.
- IP Cameras:Network-addressable devices with Power-over-Ethernet capability and embedded edge-computing processors. Demand concentrates in China's tier-one municipal clusters where public safety budgets prioritize AI-enabled camera networks and real-time inference requirements.
- Thermal Cameras:Uncooled microbolometer sensors detecting infrared emissions for perimeter security and low-visibility operations. European critical infrastructure operators in France and Germany are expanding procurement for nuclear facilities and airport perimeters under tightened CEA and national security guidelines.
- Analog CCTV:Coaxial-based closed-circuit systems lacking digital addressing and edge analytics capability. Legacy deployments persist in Eastern European municipalities with constrained capital replacement cycles.
- Dome Cameras:Vandal-resistant housings with pan-tilt-zoom mechanisms for indoor public spaces. Shopping malls and transit stations in Japan specify these for discrete positioning and 360-degree coverage.
Mature deployment sits with Analog CCTV. Newer deployment is concentrated in IP Cameras.
Application:
Operational use cases impose distinct latency thresholds, storage architectures, and integration requirements on surveillance infrastructure.
- Public Safety:Crowd behavior analysis and emergency response coordination across municipal command centers. Police jurisdictions in India's tier-one cities are expanding procurement under CEA guidelines that extend regulated surveillance perimeters beyond traditional boundaries.
- Traffic Monitoring:Automated license plate recognition and intersection flow optimization. Metropolitan transit authorities in China are accelerating integrated video analytics procurement for subway and bus networks with edge-computing density targets exceeding legacy replacement rates.
- Crime Prevention:Predictive incident detection and forensic evidence capture for judicial proceedings. UK municipal authorities require GDPR Article 35 data protection impact assessments for biometric deployment in this application.
- Retail Security:Loss prevention and customer flow analysis in commercial environments. Retail and logistics facilities in Germany and France are adopting subscription-based video management platforms, displacing capital-heavy government procurement models.
Public Safety commands the steepest expansion trajectory as regulatory mandates widen surveillance perimeters. Retail Security offers the most pronounced shift toward operational expenditure models.
End User:
Buyer categories separate by procurement methodology, cybersecurity certification requirements, and cloud architecture preferences.
- Government Agencies:Municipal police, transit authorities, and critical infrastructure operators with capital expenditure cycles and EN 62676 certification mandates. French and German city authorities now require compliant hardware as baseline eligibility, with certification weighting exceeding price-point differentials in RFP evaluation.
- Commercial Spaces:Retail chains, logistics hubs, and corporate campuses favoring subscription-based video management. Cloud-native deployment preferences in this segment are creating white space for software vendors unencumbered by legacy hardware margins.
- Educational Institutions:Universities and K-12 districts with constrained IT budgets and hybrid security requirements. Campus police departments in the US specify integration with existing access control systems.
- Residential Areas:Gated communities and apartment complexes with consumer-grade expectations and limited technical integration. Neighborhood associations in South Korea are adopting AI-enabled doorbell cameras with facial recognition for visitor management.
Government Agencies absorb the majority of capital expenditure. Commercial Spaces are gaining share fastest through subscription monetization models.
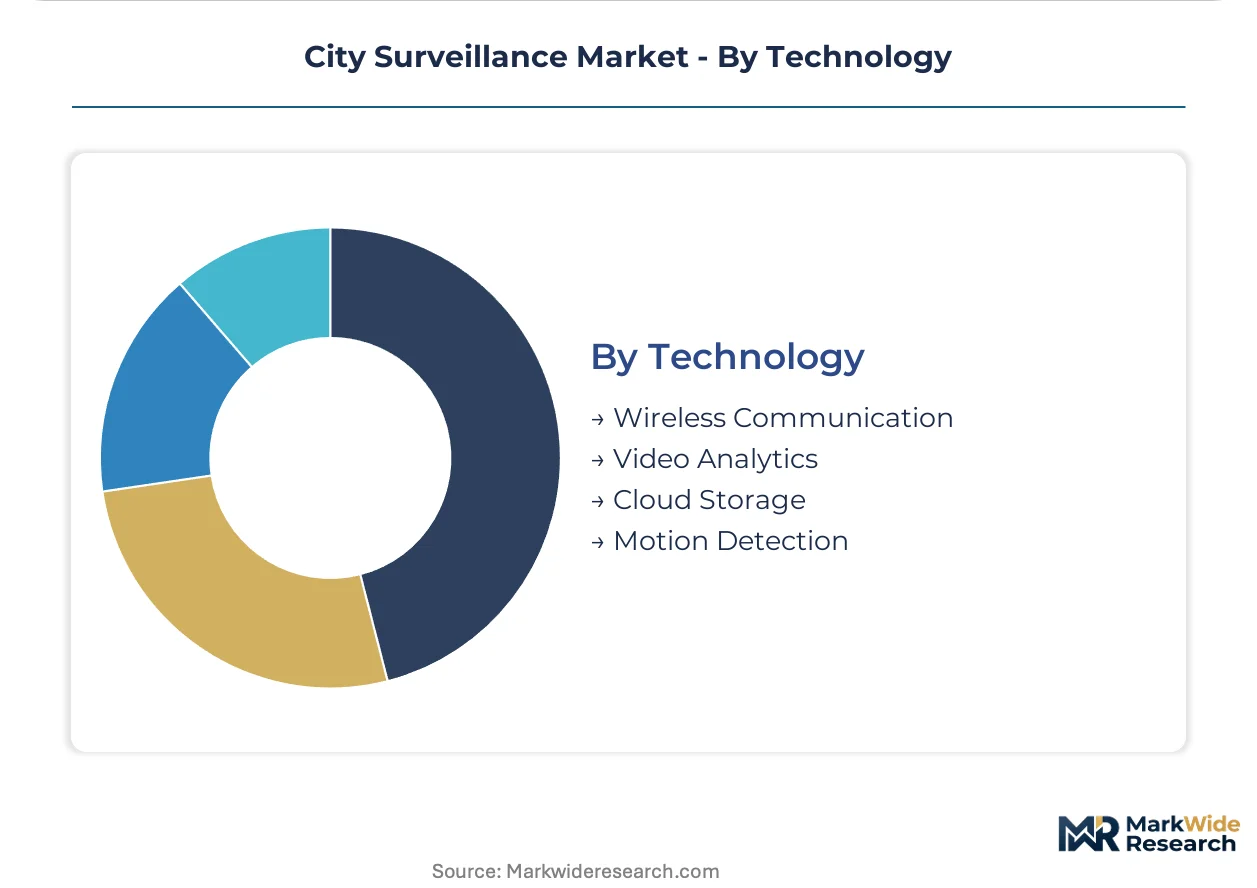
Technology:
Software and connectivity layers determine analytics sophistication, data sovereignty compliance, and total cost of ownership.
- Video Analytics:Deep-learning architectures for object detection, behavior classification, and predictive incident identification. Dutch and Singaporean transit authorities are adopting transformer-based models for platform safety monitoring, electrifying competitive differentiation around inference latency.
- Cloud Storage:Distributed data architectures enabling remote access and elastic compute scaling. Divergent data localization requirements between EU GDPR, China GB standards, and India CEA guidelines fragment cloud architecture roadmaps and inflate compliance overhead.
- Wireless Communication:4G/5G and Wi-Fi 6 backhaul for camera deployments lacking fiber infrastructure. Brazilian favela upgrading programs specify these for rapid deployment without trenching requirements.
- Motion Detection:Rule-based and neural network algorithms triggering recording and alert generation. Basic implementations persist in cost-constrained residential and small commercial installations.
Motion Detection represents mature, commoditized deployment. Video Analytics is concentrating newer procurement as municipalities phase out rule-based systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in China's tier-one municipal clusters where public safety budgets prioritize AI-enabled camera networks. European procurement offices restructure vendor qualification around GDPR Article 35 assessments. India's CEA guidelines extend regulated surveillance perimeters into transportation and power infrastructure.
China
Metropolitan transit authorities in Beijing and Shanghai accelerate integrated video analytics procurement for subway networks. SAMR-administered GB standards mandate domestic encryption protocols that reshape component sourcing decisions. Shenzhen's technology corridor anchors captive supply chains for local vendors serving municipal AI-camera deployments.
Germany
French and German city authorities require EN 62676-compliant hardware as baseline eligibility in RFP evaluations. GDPR Article 35 data protection impact assessments restructure vendor qualification protocols across municipal procurement offices. The Rhine-Ruhr metropolitan region concentrates demand for cybersecurity-certified camera lines in critical infrastructure applications.
India
Police jurisdictions in Mumbai and Delhi expand procurement under CEA guidelines extending regulated surveillance beyond traditional boundaries. The central government's critical infrastructure protection mandates widen procurement to power grids and transportation nodes. Karnataka's technology corridor hosts system integrators optimizing edge-AI firmware for resource-constrained municipal deployments.
United States
Campus police departments specify integration with existing access control systems across educational institutions. Municipal transit authorities in major metros adopt edge-computing camera density targets exceeding legacy analog replacement rates. The Northeast Corridor concentrates cloud-native deployment preferences among commercial retail and logistics facilities.
Japan
Transit stations and shopping malls specify vandal-resistant dome cameras with 360-degree coverage for discrete positioning. Critical infrastructure operators fuse computer vision with lidar and thermal sensors for perimeter security applications. The Kanto region around Tokyo anchors adoption of transformer-based object detection models for platform safety monitoring.
City Surveillance Market Competitive Environment
Chinese producers anchor the scale-driven tier; European specialists hold the certification-premium segment. The vendor base separates into three strategic layers: integrated hardware-software conglomerates with captive component sourcing, open-platform middleware specialists navigating multi-vendor interoperability mandates, and cybersecurity-certified hardware fabricators satisfying EN standards. Competitive moves concentrate on backward integration into sensor fabrication and geographic bifurcation of product lines to isolate compliance scope.
Within the integrated conglomerate tier, Hangzhou Hikvision Digital Technology Co., Ltd. and Zhejiang Dahua Technology Co., Ltd. represent Chinese-origin limited companies with in-house production capabilities. Axis Communications AB exemplifies the open-platform specialist archetype among European Aktiebolag structures. Bosch Security and Safety Systems occupies a position within the cybersecurity-certified hardware tier serving municipal procurement offices with EN-compliant product lines.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Zhejiang Dahua Technology Co., Ltd. |
| Axis Communications AB |
| Bosch Security and Safety Systems |
| Motorola Solutions, Inc. |
| Hanwha Vision |
| Honeywell International Inc. |
| Genetec Inc. |
| NEC Corporation |
| Others |
Value Chain & Pricing Dynamics
Firmware engineering talent pools in Karnataka and Shenzhen anchor labor-cost differentials that widen pricing spreads between premium cybersecurity-certified hardware tiers and commoditized edge-AI camera modules. Municipal procurement offices in France and Germany absorb EN 62676 compliance premiums while Eastern European buyers prioritize unit economics over certification depth.
Pricing Analysis
Volume concentration in high-density municipal deployments compresses per-unit margins while cybersecurity certification tiers command premium spreads. Pricing stratifies across EN 62676-compliant hardware, open-platform middleware, and economy-grade edge-AI modules without third-party audit validation. Cost compression in the economy tier intensifies because foundry capacity allocation favors automotive and smartphone sensor demand. Government agencies exhibit lowest price sensitivity given capital expenditure cycles and regulatory mandates; residential buyers and small commercial installers show highest elasticity.
Supply Chain Analysis
China's GB standards for intelligent video surveillance reshape component sourcing toward domestic encryption protocol vendors and captive sensor fabrication facilities. Image sensor and SoC supply concentrates in Taiwan, South Korea, and China with secondary packaging and assembly in Vietnam and Mexico. Raw material dependencies span silicon wafers, rare-earth elements for thermal imaging microbolometers, and specialized optical glass. Single-source vulnerability around advanced node semiconductor fabrication creates chokepoint exposure. Distribution runs through municipal system integrators in Europe and direct OEM relationships in China's tier-one municipal clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's high-risk classification of biometric surveillance erects a compliance moat that favors incumbents with established third-party audit infrastructure and bifurcated product line capabilities.
For Market Incumbents: Deploy certification investment as a barrier-to-entry lever against emerging cloud-native software vendors lacking hardware audit trails. Deepen backward integration into edge-AI SoC design to secure foundry allocation priority during semiconductor input volatility. Municipal procurement consolidation around EN 62676 baselines threatens margin compression for non-compliant product lines. For New Entrants and Emerging Players: Municipal IT departments in the Netherlands and Sweden present white-space targets for middleware specialists bridging proprietary camera protocols in multi-vendor ecosystems. Cloud-native subscription platforms for German and French retail logistics facilities offer the most penetrable segment given displacement of capital-heavy government procurement models. Channel partnerships with regional system integrators accelerate qualification timelines without direct certification burden. For Investors and Strategic Acquirers: Re-rating potential sits with cybersecurity-certified hardware fabricators given EN 62676 mandate expansion across European municipal RFP evaluations. Long-term viability favors vendors with geographic product line bifurcation capabilities isolating compliance scope. Signal to watch: CEA guideline expansion beyond police jurisdictions into Indian power grid and transportation infrastructure procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Fabrication | Hangzhou Hikvision's in-house production sustains cost leadership in high-density municipal deployments. |
| EN 62676 Certification Investment | Bosch Security's hardware lines satisfy baseline eligibility filters in French and German RFP scoring. |
| Open-Platform Architecture Development | Axis Communications navigates interoperability mandates in Dutch and Swedish multi-vendor ecosystems. |
| Geographic Product Line Bifurcation | Vendors isolate EU AI Act compliance scope by separating European and non-European hardware roadmaps. |
| Cloud-Native Video Management Launch | Subscription platforms displace capital-heavy procurement in German retail and logistics facilities. |
Study Parameters
Document review covered customs trade databases, municipal procurement registries, and regulatory filings from SAMR and CEA, complemented by interviews with municipal system integrators, transit authority procurement officers, edge-AI firmware engineers, and cybersecurity certification auditors. Secondary validation drew from SEC filings of listed surveillance vendors, EN standards documentation, and EU AI Act implementation guidance. Bottom-up deployment volume estimates triangulated against top-down public safety budget allocations across analyzed geographies.
Segmented outputs across hardware generation, software intelligence layer, operational mandate, and regional regulatory cluster fed into analytical framework spanning the projection horizon. CAGRs derived from weighted average of historical procurement velocity and policy-mandated replacement cycle acceleration. Industry-specific inputs included edge-computing camera density targets in Chinese transit authorities and GDPR Article 35 assessment completion rates across European municipal offices.
Several conditions sit outside the modeled scope, including black-market surveillance equipment flows, military-intelligence procurement channels, and consumer-grade residential camera networks without municipal integration. Forecasts reflect documented assumptions around regulatory implementation timelines and foundry capacity allocation continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Canada Surveillance Camera Market
Video Surveillance Systems
Smart Doorbell Camera Market
Video Surveillance Systems
Concealed Weapon Detection Systems Market
Video Surveillance Systems
United States Surveillance Camera Market
Video Surveillance Systems
Canada Surveillance IP Camera Market
Video Surveillance Systems
Brazil Video Surveillance Market
Video Surveillance Systems
United Kingdom Surveillance Camera Market
Video Surveillance Systems
Wearable and Body-Worn Cameras Market
Video Surveillance Systems
US Video Surveillance Market
Video Surveillance Systems
Global GCC Video Surveillance Storage Market
Video Surveillance Systems
Night Vision (IR) Surveillance Cameras Market
Video Surveillance Systems
Europe Video Surveillance As a Service Market
Video Surveillance Systems
AI Surveillance Camera Market
Video Surveillance Systems
Germany Surveillance IP Camera Market
Video Surveillance Systems
Smart Home Security Camera Market
Video Surveillance Systems
Japan Surveillance IP Cameras Market