
 E-Government Identity Management Market | 2026-2036
E-Government Identity Management Market Size, Share, and Industry Trends Forecast 2026-2036
E-Government Identity Management Market Analysis
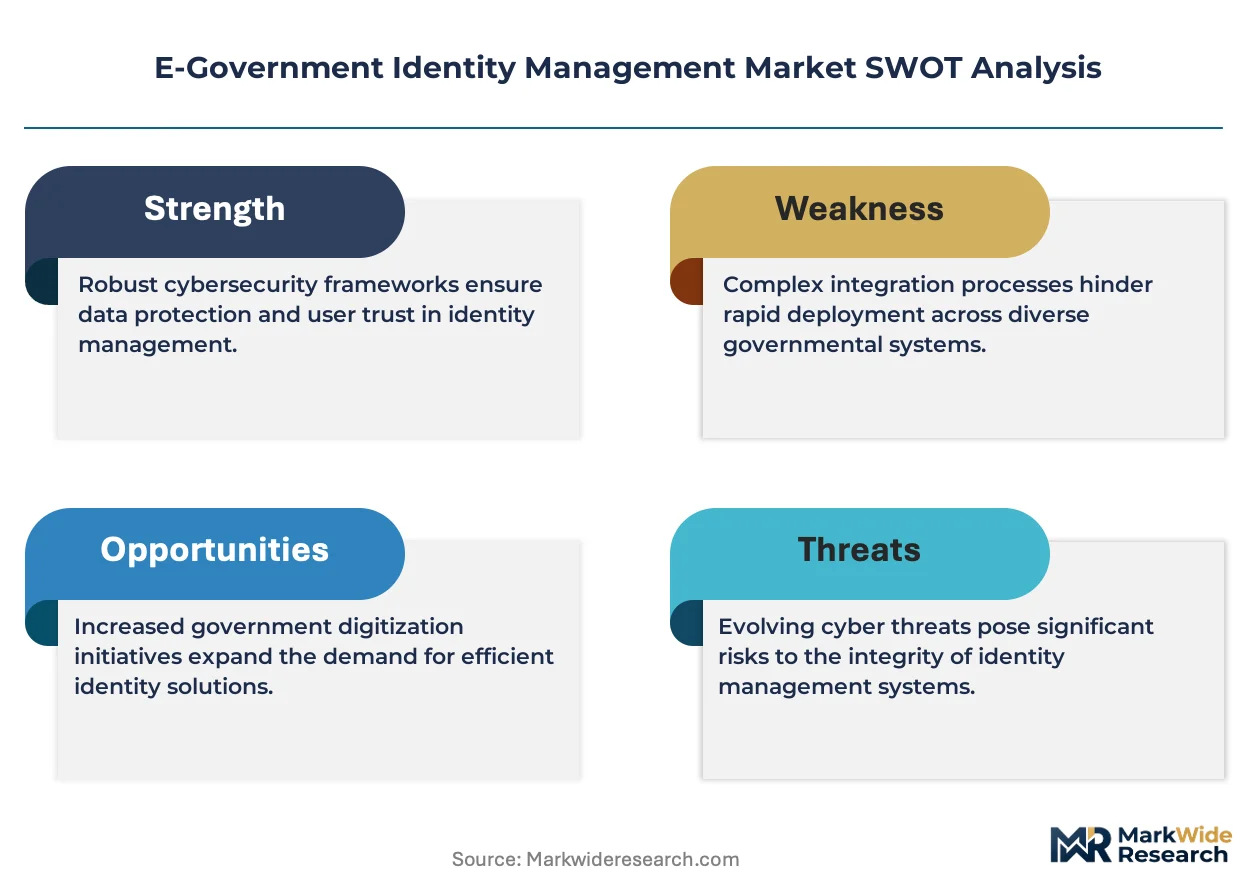
GDPR is consolidating the cost-of-entry calculus for vendors serving European public-sector clients, forcing compliance investments that smaller competitors cannot absorb. Oracle Corporation leverages its installed base in legacy government databases to sustain renewal cycles across federal agencies. Microsoft Corporation anchors cloud identity workloads through Azure Active Directory deployments in municipal and regional governments. IBM Corporation competes on mainframe-integrated credentialing systems that dominate tax and social security administrations.
E-Government Identity Management encompasses the technical systems, protocols, and infrastructure that authenticate citizens and public employees across digital government services, typically operating through PKI certificates, biometric matching engines, and federated identity protocols with 99.9% uptime service-level agreements. Biometric Verification leads solution spending as border and immigration agencies deploy facial recognition and fingerprint enrollment at scale. Access Management captures expanding budget share as zero-trust architectures replace perimeter-based security in inter-agency data exchanges. Cloud-Based deployment is outpacing on-premises installations where sovereign data requirements permit external hosting.
The EU Digital Identity Framework, NIST 800-63 digital identity guidelines in the United States, and India's Aadhaar Act collectively shape product standards, interoperability mandates, and liability frameworks for vendors. EMA and national data protection authorities enforce cross-border data residency rules that constrain cloud architecture choices for European health and tax platforms. Stakeholders must monitor which jurisdictions will mandate in-country key escrow for biometric templates, as this technical requirement would fragment vendor roadmaps and procurement specifications.
Market Dynamics
The EU Digital Identity Framework is compressing procurement timelines across European public-sector agencies while mandating interoperable authentication stacks that legacy vendors struggle to retrofit.
Growth Catalysts
- Biometric enrollment mandates:India's Aadhaar Act compels facial recognition and fingerprint capture for welfare distribution, forcing state governments to expand identity infrastructure.
- Zero-trust architecture adoption:NIST 800-63 guidelines in the United States are accelerating passwordless authentication deployments across federal cloud migrations.
- Cross-border service integration:The EU Digital Identity Framework enables portable digital wallets, driving demand for federated identity protocols that authenticate citizens across member-state boundaries.
Market Restraints
- Biometric template storage costs:Sovereign data requirements in Germany and France mandate in-country key escrow, fragmenting cloud economics and inflating infrastructure spend.
- Legacy system entrenchment:Mainframe-integrated credentialing systems at tax and social security administrations create switching friction that extends replacement cycles.
- GDPR compliance burden:European data protection authorities enforce cross-border data residency rules that constrain architecture choices and disqualify non-compliant vendors.
Strategic Opportunities
- Brazil's digital ID expansion:The national civil identification program is enrolling 100 million citizens, creating procurement windows for biometric matching engines and mobile authentication platforms.
- Health credential convergence:Post-pandemic digital health passes are integrating with national ID systems, opening adjacent revenue streams for identity vendors with vaccination verification capabilities.
- Mobile-first enrollment:Smartphone-based identity verification is displacing physical document checks at municipal service counters, enabling self-service onboarding that reduces agency staffing costs.
Industry Challenges
- PKI certificate lifecycle management:Government agencies lack internal expertise to rotate encryption keys at scale, creating operational risk and service continuity exposure.
- Interoperability testing delays:Vendor implementations must pass conformance certification against national standards bodies before production deployment, extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Government Identity Management Market |
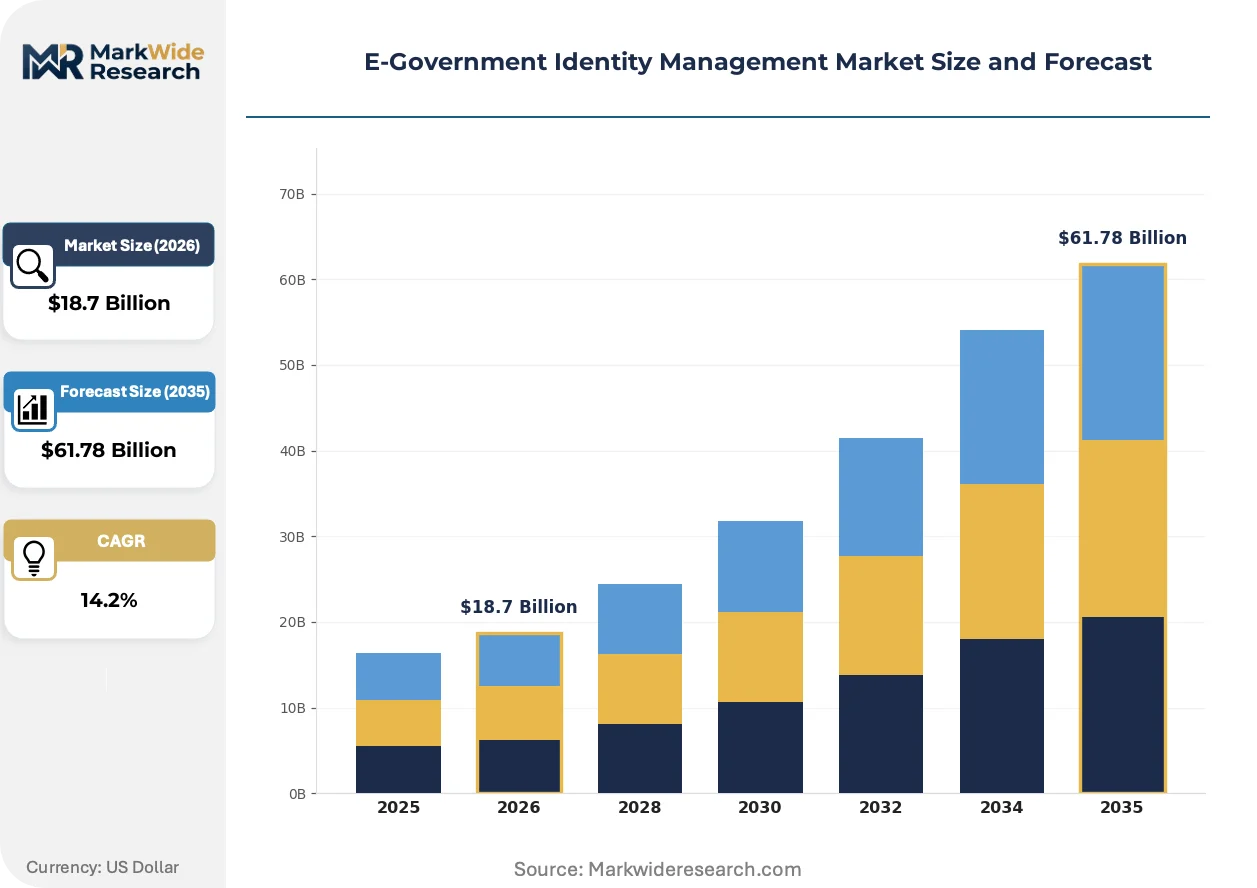
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Biometric Verification, Digital Signatures, Identity Verification, Access Management End User: Government Entities, Citizens, Private Sector, Non-Governmental Organizations Deployment: Cloud-Based, On-Premises, Hybrid, Mobile Technology: Blockchain, AI Solutions, Secure Protocols, Multi-Factor Authentication |
| Companies Covered | Oracle Corporation, AWS, Microsoft Corporation, Saviynt, Google LLC, IBM Corporation, SAP SE, Okta, SailPoint Technologies Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Government Identity Management Market Emerging Trajectories
Artificial intelligence and decentralized identity protocols are restructuring how governments authenticate citizens, shifting verification from centralized databases to edge-computing architectures that preserve privacy.
Facial recognition with liveness detection is automating border crossing authentication at immigration checkpoints in Australia and Singapore. Customs agencies are deploying passive biometric capture that eliminates document presentation, compressing processing time from minutes to seconds. This automation is reducing staffing requirements at ports of entry while improving accuracy against watchlist databases.
GDPR's data minimization principles are forcing identity vendors to redesign systems that process biometric templates within European borders. EMA and national data protection authorities are rejecting cloud architectures that route authentication through non-EU data centers. Health and tax platforms in France and Germany are selecting vendors with sovereign hosting guarantees, fragmenting procurement specifications.
Subscription-based identity verification is displacing perpetual license purchases at municipal governments with constrained capital budgets. Brazilian and Indian city agencies are adopting pay-per-authentication models that align costs with citizen service volumes. This consumption shift favors vendors with elastic cloud infrastructure over on-premises appliance providers.
E-Government Identity Management Market Segmentation
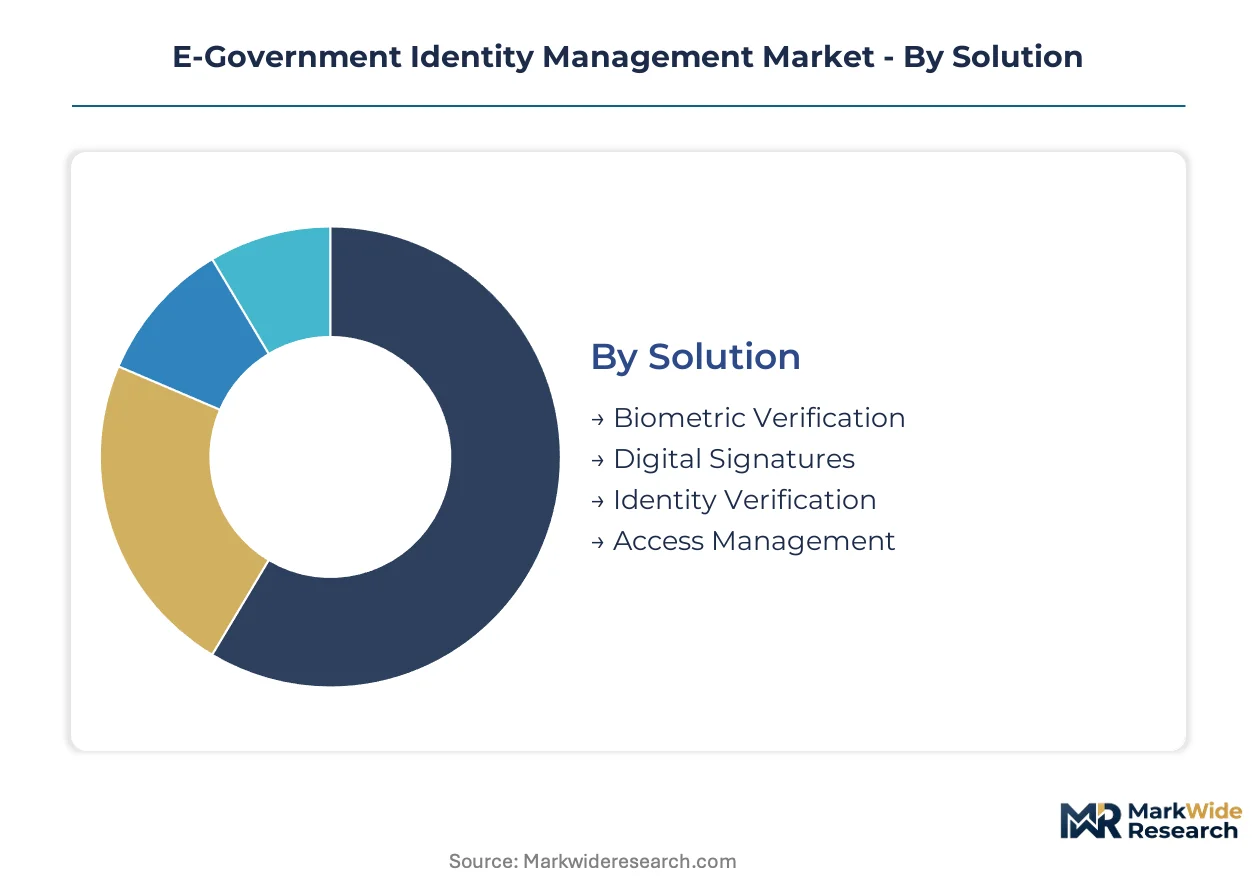
E-Government identity management segments diverge sharply by technical sophistication, data sovereignty requirements, and procurement authority. Solution architecture and deployment topology determine vendor selection criteria more than end-user type, as agencies prioritize interoperability mandates over user-facing features.
Solution:
Technical capabilities within this axis separate credential issuance from verification workflows, with biometric engines commanding premium procurement cycles due to hardware integration complexity.
- Biometric Verification:Facial recognition and fingerprint matching engines process citizen enrollment at border checkpoints and welfare distribution points. India's Aadhaar Act compels state governments to deploy multi-modal capture systems, creating sustained demand for liveness detection and template encryption modules.
- Access Management:Zero-trust architectures replace perimeter-based security in inter-agency data exchanges, with NIST 800-63 guidelines accelerating passwordless authentication deployments across federal cloud migrations. Municipal governments prioritize this segment for cross-departmental resource sharing.
- Identity Verification:Document authentication and credential validation systems anchor citizen onboarding workflows for tax and licensing portals.
- Digital Signatures:PKI certificate lifecycle management supports legally binding transactions in procurement and judicial filings.
Mature deployment sits with Digital Signatures in established tax and legal frameworks. Newer deployment is concentrated in Biometric Verification as welfare agencies mandate physical identity confirmation.
End User:
Procurement authority and budget scale vary dramatically across this axis, with central government agencies dictating technical standards that cascade to subordinate entities.
- Government Entities:Federal and state agencies drive platform standardization through sovereign procurement frameworks. Brazil's national civil identification program exemplifies concentrated demand, enrolling 100 million citizens through centralized biometric infrastructure.
- Citizens:Individual service consumption patterns shape mobile-first authentication requirements, with smartphone-based verification displacing physical document checks at municipal counters. Self-service onboarding reduces agency staffing costs.
- Private Sector:Government-contracted service providers require federated identity access to tax and licensing databases.
- Non-Governmental Organizations:Humanitarian and development agencies need portable credential verification for beneficiary tracking.
Volume concentration rests with Government Entities. Usage intensity is climbing fastest among Citizens as digital wallet adoption accelerates.
Deployment:
Sovereign data requirements and capital budget constraints create divergent infrastructure strategies across this axis, with cloud economics fragmenting under residency mandates.
- Cloud-Based:Elastic infrastructure supports pay-per-authentication models that align costs with citizen service volumes. Brazilian and Indian city agencies favor this approach, though GDPR enforcement constrains European adoption.
- On-Premises:Hardware appliances maintain air-gapped environments for classified systems and biometric template storage. Germany and France mandate in-country key escrow, fragmenting procurement specifications.
- Hybrid:Split architectures route sensitive operations to sovereign data centers while leveraging cloud scale for public-facing services.
- Mobile:Smartphone-native verification enables offline credential presentation in remote or bandwidth-constrained environments.
Capital deployment favors On-Premises in defense and classified tax systems. Cloud-Based configurations are expanding most quickly where data residency rules permit external hosting.
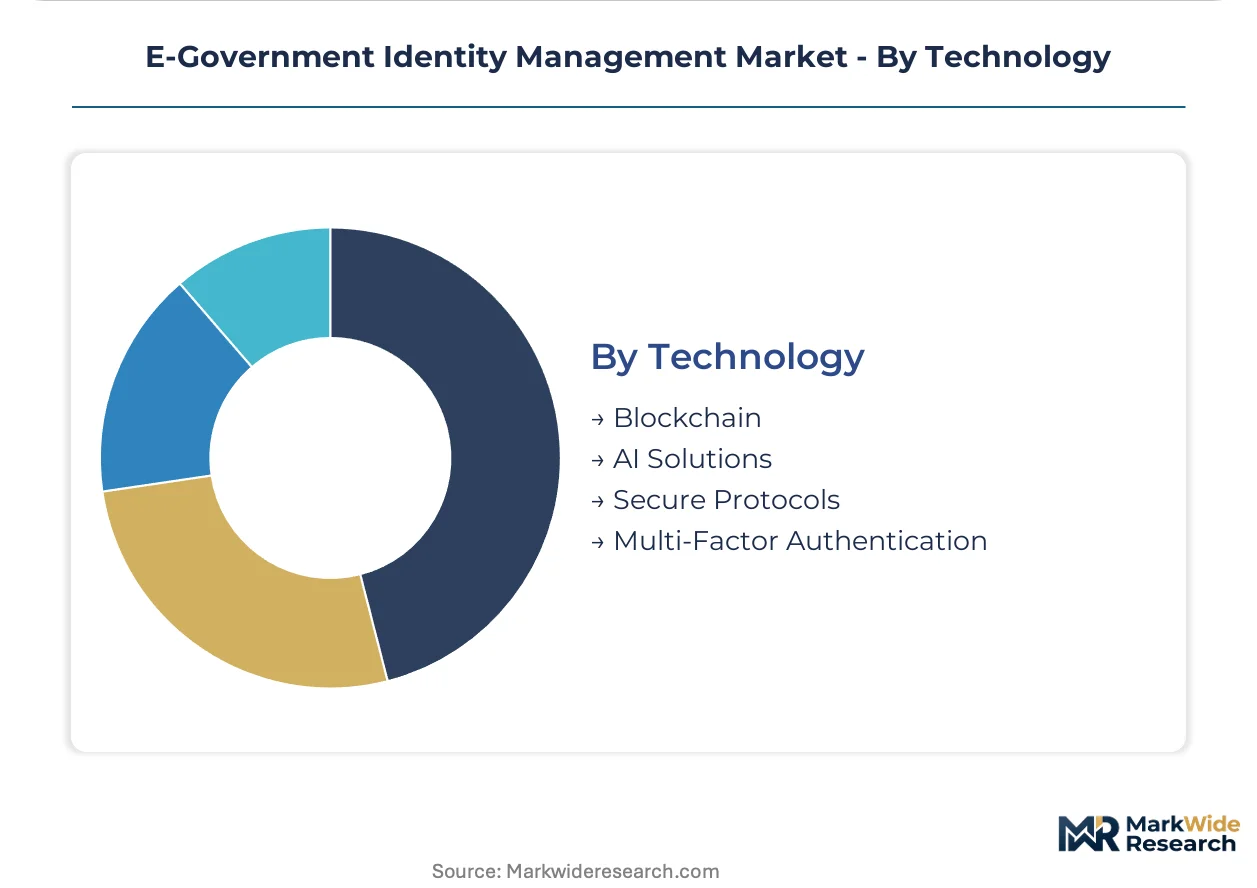
Technology:
Innovation velocity and integration risk separate emerging protocols from established authentication stacks, with AI and decentralized architectures reshaping vendor roadmaps.
- AI Solutions:Machine learning models automate liveness detection and anomaly scoring in biometric workflows. Australian and Singapore immigration checkpoints deploy passive capture that eliminates document presentation, compressing processing from minutes to seconds.
- Secure Protocols:FIDO2 and OIDC standards enable passwordless authentication across federated government services. Federal cloud migrations in the United States prioritize this foundation.
- Multi-Factor Authentication:Layered verification combining possession, knowledge, and inherence factors protects high-risk transactions in financial and health portals.
- Blockchain:Distributed ledger architectures for self-sovereign identity remain experimental in pilot programs, with scalability and governance questions limiting production deployment.
Production maturity concentrates in Secure Protocols. Steepest expansion trajectory belongs to AI Solutions as border agencies automate passenger processing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India anchors procurement volume through its Aadhaar biometric enrollment infrastructure, while Germany and Brazil concentrate sovereign data investments. Jurisdictions with active national digital ID programs command vendor attention and compress deployment timelines.
United States
Federal cloud migrations and zero-trust mandates drive agency procurement cycles. NIST 800-63 guidelines accelerate passwordless authentication deployments across civilian and defense departments. Washington DC and Northern Virginia host concentrated identity workload deployments for federal clients.
Germany
In-country key escrow requirements for biometric templates inflate infrastructure spend for welfare and tax platforms. GDPR enforcement by CNIL-equivalent state authorities constrains cloud architecture choices. Berlin and Munich anchor procurement clusters for federal and state-level credentialing systems.
India
Aadhaar Act mandates compel state governments to expand multi-modal biometric capture for welfare distribution. The Unique Identification Authority of India sets technical standards that cascade to vendor specifications. Bangalore and Hyderabad concentrate system integrators supporting national enrollment platforms.
Brazil
The national civil identification program is enrolling 100 million citizens through centralized biometric infrastructure. ANVISA and national data protection frameworks shape procurement specifications for health-credential convergence. São Paulo and Brasília anchor demand for mobile authentication and matching engine deployments.
Australia
Border automation programs deploy passive biometric capture at immigration checkpoints, eliminating document presentation. The country's digital transformation agency sets interoperability standards for federated citizen services. Sydney and Melbourne concentrate vendor delivery teams for Asia-Pacific government clients.
E-Government Identity Management Market Vendor Landscape
United States technology conglomerates anchor the premium tier through cloud-native identity stacks; European specialists hold positions in sovereign-compliant credentialing systems. Market structure consolidates around three strategic layers: hyperscale platform providers, legacy mainframe integrators, and emerging cloud-native specialists. Competitive positioning depends on compliance certification breadth and existing public-sector installed base. Dominant moves include strategic partnerships with national standards bodies and geographic expansion through local system integrator alliances.
Within the hyperscale platform tier, Oracle Corporation and Microsoft Corporation exemplify divergent approaches to public-sector retention. Oracle leverages legacy database relationships to sustain renewal cycles across federal tax and social security administrations. Microsoft anchors cloud identity workloads through municipal and regional government deployments. IBM Corporation occupies a position within the mainframe-integrated credentialing segment, serving agencies with entrenched legacy infrastructure.
| Leading Market Players |
|---|
| Oracle Corporation |
| AWS |
| Microsoft Corporation |
| Saviynt |
| Google LLC |
| IBM Corporation |
| SAP SE |
| Okta |
| SailPoint Technologies Holdings |
| Others |
Supply Flow & Price Mechanics
GDPR data minimization mandates gate qualified supply for European public-sector identity platforms, restricting vendor eligibility to providers with sovereign hosting guarantees and fragmenting procurement specifications across premium-tier compliance investments and economy-tier exclusion.
Pricing Analysis
Short lead-time premiums for biometric hardware integration compress margins for urgent deployments, while spot inventory discounts emerge for standardized PKI certificate modules. Subscription-based SaaS tiers dominate municipal procurement, with price differentiation hinging on certification depth (FIPS 140-2 versus baseline encryption) and after-sales service bundling. Pricing pressure stems from pay-per-authentication models displacing perpetual licenses in Brazilian and Indian city agencies. Government entities exhibit lowest price sensitivity due to sovereign budget allocations, whereas municipal governments with constrained capital reserves drive hardest bargain.
Supply Chain Analysis
Domestic-content mandates in India's Aadhaar procurement specifications and Germany's biometric template escrow requirements reshape sourcing toward local system integrators. Component concentration centers on Taiwan for secure element manufacturing, the United States for facial recognition algorithm licensing, and Israel for liveness detection modules. Raw material dependencies include specialized CMOS sensors, cryptographic processors, and edge-computing chipsets. Single-source vulnerability runs through Taiwan's semiconductor foundry capacity. Distribution runs through national standards bodies that enforce conformance certification before production deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around compliance-certified incumbents as GDPR enforcement and biometric escrow mandates force smaller competitors toward exit or acquisition.
For Market Incumbents: Deploy certification depth as the primary defensive lever. Oracle and Microsoft should accelerate FIPS 140-2 and Common Criteria investments to disqualify emerging cloud-native challengers from federal procurement cycles. Capacity addition in Germany and France addresses sovereign data requirements that fragment cloud economics. Channel control through exclusive partnerships with national enrollment authorities extends replacement friction against mainframe displacement. For New Entrants and Emerging Players: The premium-economy price-point gap in municipal pay-per-authentication models creates entry space for elastic infrastructure specialists. Brazilian state-level enrollment platforms and Indian city agency digitization programs represent the most penetrable geographies. Mobile-first enrollment workflows targeting bandwidth-constrained environments offer a differentiated go-to-market angle against legacy appliance vendors. For Investors and Strategic Acquirers: ANVISA health-credential convergence with Brazil's civil identification program is the leading indicator that adjacent revenue streams will accrue to identity vendors with vaccination verification capabilities. Long-term viability favors platform plays with cross-jurisdictional compliance certification breadth. Acquisition targets should display sovereign hosting guarantees and established national standards body relationships. The signal to monitor is which jurisdictions mandate in-country biometric key escrow, as this technical requirement fragments vendor roadmaps and creates distressed asset opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | GDPR enforcement by EMA and national data protection authorities disqualifies non-compliant vendors from European health and tax platforms. |
| Biometric Hardware Integration | India's Aadhaar Act compels multi-modal capture systems that sustain demand for liveness detection and template encryption modules. |
| Mobile-First Enrollment Platform | Smartphone-based verification displaces physical document checks at municipal counters, reducing agency staffing costs. |
| Federated Identity Partnership | The EU Digital Identity Framework enables portable digital wallets that authenticate citizens across member-state boundaries. |
| Health Credential Convergence | Post-pandemic digital health passes integrate with national ID systems, opening adjacent revenue streams for vaccination verification capabilities. |
Methodological Framework
Document review covered NIST 800-63 guidelines, EU Digital Identity Framework specifications, and India's Aadhaar technical standards, complemented by interviews with government CIOs, biometric system integrators, national data protection authority officials, and municipal procurement officers. Secondary validation drew from SEC filings of listed identity vendors, hyperscaler cloud infrastructure disclosures, and national enrollment program procurement databases. Bottom-up deployment estimates triangulated against top-down public-sector IT spending forecasts.
Model outputs project biometric verification, access management, and digital signature segments across cloud, on-premises, hybrid, and mobile deployment topologies over the projection horizon. CAGRs derive from enrollment velocity assumptions tied to national ID program mandates, zero-trust architecture adoption curves, and sovereign data residency rule expansion. Industry-specific inputs include Aadhaar Act enrollment targets, EU Digital Identity Wallet rollout schedules, and NIST guideline revision cycles.
Inputs from Unique Identification Authority of India procurement records and ANVISA health-credential specifications were available through the study window; gaps in classified defense authentication system deployments introduce uncertainty bands around federal security segment estimates. Forecasts reflect assumptions regarding interoperability certification timelines and biometric template storage cost trajectories. Regulatory fragmentation risk, cloud residency mandate expansion, and legacy mainframe replacement friction could revise projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Asia Pacific Biometrics in Government Market
Biometrics & Identity Management
Asia-Pacific Government and Security Biometrics Market
Biometrics & Identity Management
Next Generation Biometric Market
Biometrics & Identity Management
Global Human Identification Market
Biometrics & Identity Management
Global Voice Biometrics Market
Biometrics & Identity Management
Biometric Services Platform (Biosp) Market
Biometrics & Identity Management
FIDO Authentication Market
Biometrics & Identity Management
Iris Recognition Market
Biometrics & Identity Management
United States Biometrics Market
Biometrics & Identity Management
Biometric Passport Market
Biometrics & Identity Management
North America Government and Security Biometrics Market
Biometrics & Identity Management
Mobile Devices User Authentication Services Market
Biometrics & Identity Management
Voice Biometric Solutions Market
Biometrics & Identity Management
Global Phone Based Authentication Solution Market
Biometrics & Identity Management
AI-Enabled Biometrics Market
Biometrics & Identity Management
Italy Mobile Biometrics Market