
 Password Management Market | 2026-2036
Password Management Market Size, Share, and Industry Trends Forecast 2026-2036
Password Management Market Intelligence
Shift from single-vendor credential vaults toward multi-source identity architectures is hardening as enterprises diversify supplier risk. CyberArk anchors the privileged-access tier with deep mainframe and DevSecOps integration. Okta extends cloud-native single sign-on across hybrid workforce deployments. Bitwarden competes on open-source transparency and self-hosting flexibility for privacy-conscious organizations.
Password management encompasses cryptographic credential vaulting, policy-enforced rotation protocols, and breach-monitoring analytics that secure authentication flows across distributed IT environments. AES-256 encryption, zero-knowledge architectures, and FIDO2/WebAuthn interoperability define baseline technical specifications for commercial-grade solutions. Cloud-Based deployment leads volume adoption as SaaS delivery eliminates infrastructure overhead for mid-market buyers, while Identity & Access Management integration captures the deepest enterprise wallet share by embedding credentials within broader governance frameworks. Enterprise Security application segments sustain premium pricing through compliance-driven procurement cycles in regulated industries.
FDA cybersecurity guidance for medical devices, HIPAA administrative safeguards, and the EU NIS2 Directive collectively mandate auditable access controls that expand addressable demand for password management platforms. FERC standards for critical energy infrastructure and Japan's METI cybersecurity framework impose comparable requirements on operational technology environments. Stakeholders must monitor convergence between password vaulting and post-quantum cryptographic standards as NIST finalizes migration timelines for public-key algorithms.
Market Dynamics
Zero-trust architecture migration is compressing procurement cycles for credential security platforms as enterprises dismantle perimeter-based trust models. HIPAA administrative safeguards, EU NIS2 mandates, and FDA medical-device guidance collectively force healthcare and critical infrastructure operators toward auditable privileged-access controls.
Growth Catalysts
- HIPAA Enforcement:US healthcare providers face escalating audit scrutiny over patient-record access logs. Privileged-access tools now anchor compliance budgets for hospital networks and telehealth platforms.
- Operational Technology Convergence:Energy utilities under FERC cybersecurity standards extend password vaulting into SCADA and industrial control environments. Critical infrastructure operators treat credential rotation as operational safety.
- Japan:METI cybersecurity framework revisions mandate access-control documentation for supply-chain resilience. Domestic manufacturers accelerate privileged-access deployments to satisfy customer audit requirements.
Market Restraints
- Quantum Vulnerability:Current RSA and ECC implementations face obsolescence as NIST post-quantum algorithms mature. Migration timelines create procurement paralysis among risk-averse buyers.
- Input Concentration:FIDO2 hardware authenticator supply chains concentrate in Taiwan and South Korea. Geopolitical friction threatens token availability for enterprise rollout schedules.
- Legacy Integration Friction:Mainframe credential vaulting demands specialized protocol adapters. Deep integration costs deter mid-market buyers from replacing incumbent single-vendor architectures.
Strategic Opportunities
- Germany:NIS2 implementation deadlines create immediate demand for compliant privileged-access platforms. Mittelstand manufacturers represent an underpenetrated segment with limited incumbent saturation.
- Post-Quantum Convergence:Lattice-based cryptography integration with existing vault architectures opens differentiation for early movers. Hybrid certificate management bridges current and future algorithm standards.
- DevSecOps Channel:Infrastructure-as-code credential injection via CI/CD pipelines displaces manual vault administration. Platform engineering teams emerge as new procurement influencers outside traditional IT security.
Industry Challenges
- Cryptographic Talent Scarcity:Zero-knowledge architecture implementation demands rare expertise in secure multiparty computation. Vendors compete for engineers capable of auditing side-channel resistance.
- Certification Latency:Common Criteria EAL4+ evaluation timelines extend 18-24 months for privileged-access modules. Product roadmaps misalign with federal procurement windows.
- Interoperability Complexity:WebAuthn implementation varies across browser and mobile platforms. Customer support burdens escalate from fragmented FIDO2 behavior.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Password Management Market |
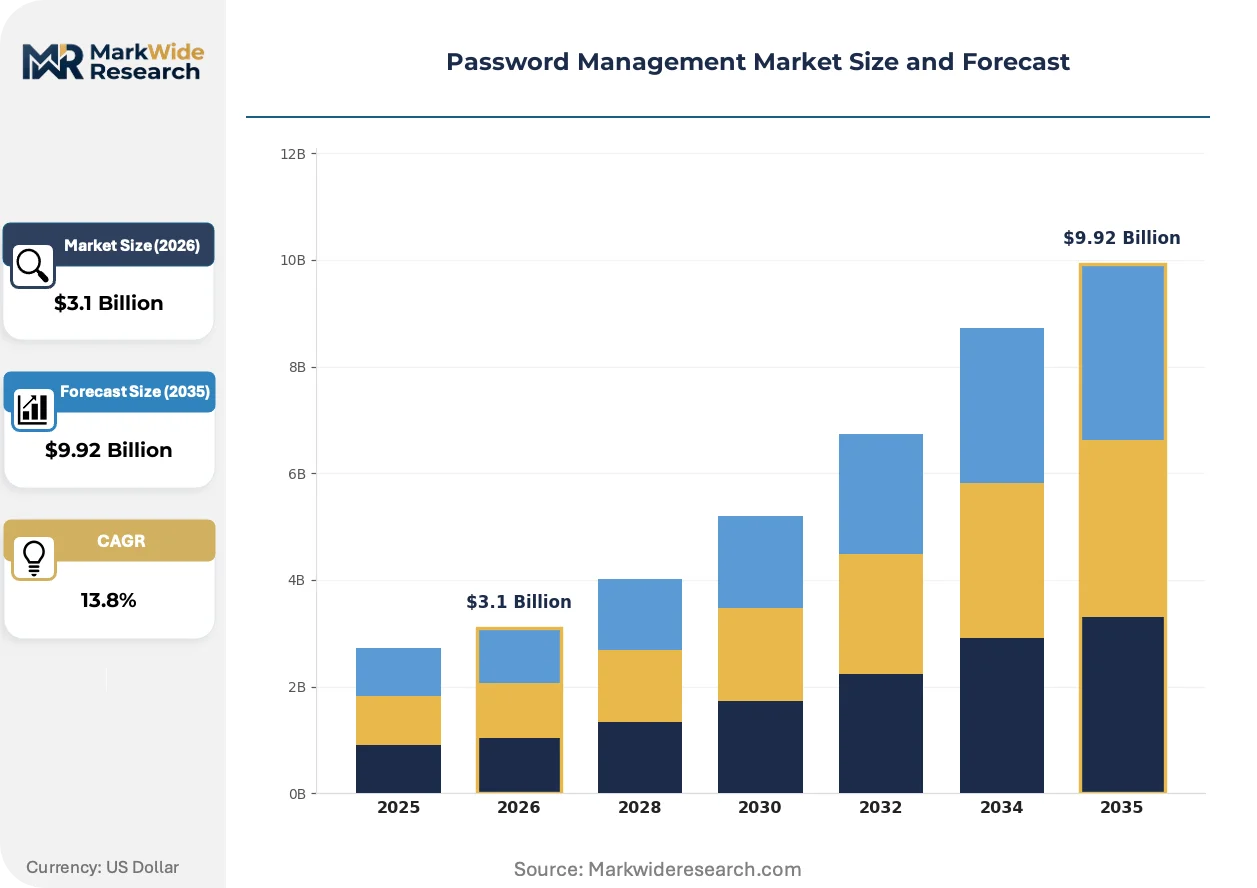
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $9.92 Billion |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Managed Service Solution Type: Standalone Password Manager, Identity & Access Management, Single Sign-On, Multi-Factor Authentication Application: Enterprise Security, Small & Medium Business Security, Personal Use, Government Compliance End User: IT Administrators, Corporate Employees, Individual Consumers, Regulatory Authorities |
| Companies Covered | 1Password, LastPass, Bitwarden, Keeper Security, Dashlane, Microsoft, CyberArk, Delinea, Okta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Password Management Market Strategic Shifts & Innovations
Passwordless authentication architectures are absorbing capital and engineering resources as vendors reposition beyond credential vaulting. Technical roadmaps converge on FIDO2, passkeys, and continuous authentication signals.
Passkey technology is absorbing enterprise authentication budgets previously allocated to hardware tokens and SMS one-time passwords. Financial services and SaaS providers deploy WebAuthn credentials at scale to reduce phishing exposure. The shift is absorbing help-desk password-reset volume and compressing operational overhead for identity operations teams.
EU NIS2 Directive enforcement is mandating incident-response capabilities and access-log retention across critical infrastructure operators. Member states transpose the framework into national law through 2024-2025, creating synchronized procurement waves. German energy distributors and Dutch healthcare networks represent the most advanced implementation timelines, with contract awards concentrating among vendors with EU-sovereign data residency.
Self-hosted deployment preferences harden among privacy-conscious organizations seeking data-sovereignty guarantees. European public-sector buyers and German automotive suppliers prioritize on-premise vaulting over SaaS delivery to satisfy GDPR Article 44 transfer restrictions. Procurement evaluation criteria now weight deployment flexibility above feature breadth in regulated verticals.
Password Management Market Segmentation
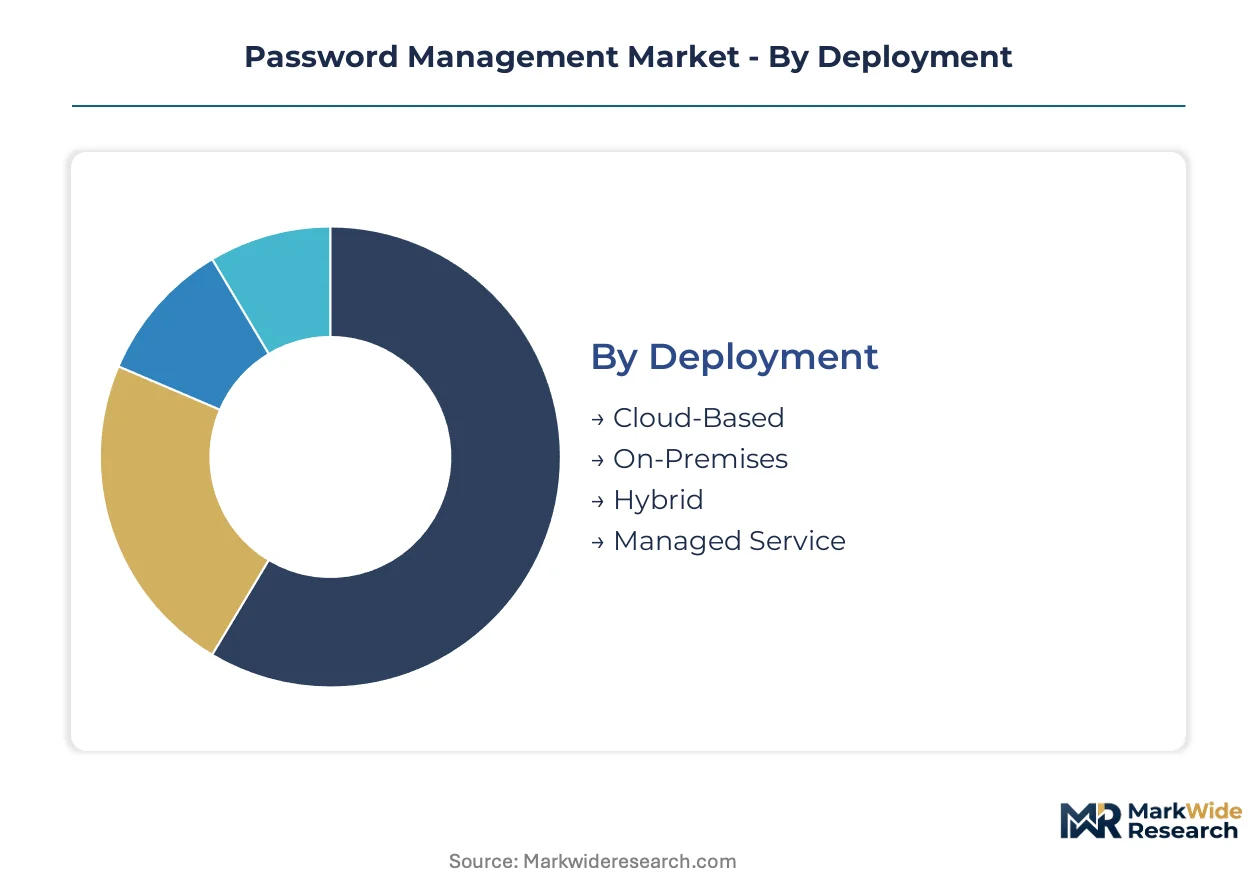
Credential security platforms fragment across deployment architectures, solution types, and compliance mandates. Each segmentation axis reveals distinct procurement patterns and technical requirements that shape vendor positioning.
Deployment:
Upgrade cycles accelerate as enterprises dismantle perimeter-based trust models and reassess infrastructure ownership economics.
- Cloud-Based:SaaS delivery eliminates infrastructure overhead through browser-accessible vaults with automatic encryption key rotation. Mid-market buyers in the United States favor this model for HIPAA-aligned patient-record protection without capital expenditure.
- On-Premises:Self-hosted vaulting maintains complete data sovereignty through localized AES-256 encryption and air-gapped key storage. German automotive suppliers and European public-sector agencies prioritize this deployment to satisfy GDPR Article 44 cross-border transfer restrictions.
- Hybrid:Split-credential architectures separate high-value privileged accounts on-premise while pushing standard workforce credentials to cloud instances.
- Managed Service:Third-party administration of vault operations appeals to resource-constrained organizations lacking dedicated cryptographic talent.
Cloud-Based sits at the top of the volume ranking, with Hybrid climbing the fastest as regulated industries seek compromise between agility and sovereignty.
Solution Type:
Procurement budgets consolidate around platforms that embed credential vaulting within broader identity governance frameworks rather than isolated tools.
- Identity & Access Management:Unified policy engines orchestrate privileged-access workflows, entitlement reviews, and session recording across hybrid IT estates. Healthcare networks under FDA cybersecurity guidance deploy these integrated stacks for auditable medical-device access controls.
- Standalone Password Manager:Lightweight vaulting for individual or small-team credential storage with limited policy enforcement capabilities. Privacy-conscious organizations in Japan favor open-source variants for supply-chain audit transparency under METI framework requirements.
- Single Sign-On:Federated authentication portals reduce credential sprawl through SAML and OIDC protocol standardization.
- Multi-Factor Authentication:FIDO2 hardware tokens and biometric overlays harden vault access against phishing and credential stuffing attacks.
Identity & Access Management commands the dominant revenue share, while Single Sign-On expands most quickly through SaaS provider integrations.
Application:
Compliance-driven procurement cycles concentrate spending in regulated verticals where breach-notification mandates impose immediate procurement deadlines.
- Enterprise Security:Tier-one deployments span thousands of privileged accounts across mainframe, cloud, and operational technology environments. FERC-regulated energy utilities extend these controls into SCADA systems where credential rotation equals operational safety.
- Government Compliance:Sovereign data residency and Common Criteria certification anchor public-sector evaluations. EU NIS2 implementation across German and Dutch critical infrastructure operators creates synchronized demand waves through national transposition deadlines.
- Small & Medium Business Security:Simplified SaaS vaulting with pre-configured policy templates reduces administrative burden for lean IT teams.
- Personal Use:Consumer-grade managers secure individual digital identities across personal and professional account portfolios.
Enterprise Security leads absolute spending, with Government Compliance gaining share fastest as NIS2 deadlines approach.
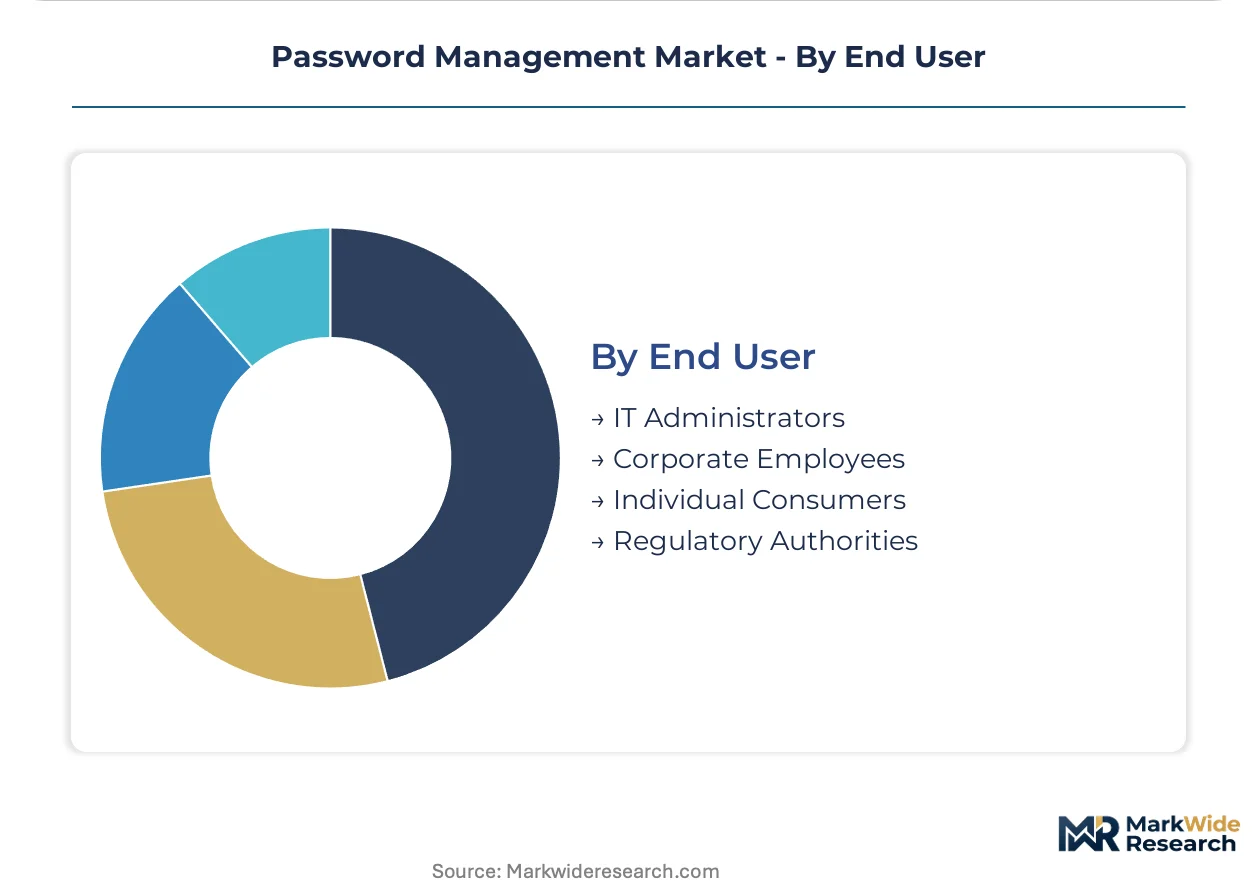
End User:
Platform engineering teams emerge as new procurement influencers outside traditional IT security hierarchies.
- IT Administrators:Vault operators manage credential lifecycle, rotation schedules, and access certification campaigns across distributed infrastructure. Their workflows demand granular audit logs and automated policy enforcement for HIPAA and NIS2 evidentiary requirements.
- Corporate Employees:Workforce authentication experiences determine help-desk ticket volume and productivity friction. Financial services firms deploy WebAuthn passkeys to eliminate password-reset overhead for this population.
- Individual Consumers:Personal cybersecurity awareness drives freemium-to-paid conversion in password manager subscriptions.
- Regulatory Authorities:Audit and inspection functions mandate read-only access to credential access logs for compliance verification.
IT Administrators anchor platform selection decisions, with Corporate Employees representing the steepest expansion trajectory as hybrid workforces scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compliance cost differentials between jurisdictions are redirecting procurement budgets toward markets with harmonized breach-notification frameworks. Enterprises locate credential security operations where regulatory clarity reduces implementation risk.
United States
HIPAA enforcement escalation drives hospital network spending on privileged-access audit trails. FDA cybersecurity guidance for connected medical devices mandates access-log retention periods. Healthcare clusters in Boston and the Research Triangle accelerate deployments to satisfy federal inspection protocols.
Germany
NIS2 transposition deadlines synchronize demand across energy distributors and automotive suppliers. GDPR Article 44 cross-border transfer restrictions favor sovereign data residency solutions. Mittelstand manufacturers in Baden-Württemberg and Bavaria prioritize on-premise vaulting for supply-chain audit documentation.
Japan
METI cybersecurity framework revisions impose access-control documentation requirements on domestic manufacturers. Critical infrastructure operators under the country's central bank oversight extend credential rotation into operational technology environments. Manufacturing hubs in Aichi and Osaka prefectures deploy privileged-access tools to satisfy customer audit demands.
United Kingdom
Post-Brexit data protection alignment creates procurement uncertainty for financial services firms. The country's national cybersecurity center guidance pushes toward zero-trust architecture adoption. London-based fintech clusters invest in FIDO2 passkey infrastructure to reduce phishing exposure for hybrid workforces.
Netherlands
EU NIS2 early transposition creates immediate demand for incident-response capabilities among healthcare networks. The country's data protection authority enforces strict breach-notification timelines. Dutch healthcare operators in Utrecht and Rotterdam lead European deployment schedules for compliant privileged-access platforms.
Password Management Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue passwordless authentication and post-quantum cryptographic integration. The vendor base stratifies across three maturity levels: heritage credential vaulting specialists, cloud-native identity platforms, and open-source transparency advocates. Consolidation pressure intensifies as enterprise buyers demand unified policy engines spanning privileged access and workforce authentication. Dominant competitive moves include strategic partnerships for DevSecOps pipeline integration and geographic expansion into NIS2-compliant European markets.
Within the heritage privileged-access tier, CyberArk and Delinea occupy positions anchored by deep mainframe and operational technology integration capabilities. Cloud-native platforms exemplified by Okta sit within the workforce authentication vector, extending single sign-on across hybrid deployments. Open-source transparency advocates represented by Bitwarden capture privacy-conscious organizations seeking self-hosting flexibility under GDPR and METI framework requirements.
| Leading Market Players |
|---|
| 1Password |
| LastPass |
| Bitwarden |
| Keeper Security |
| Dashlane |
| Microsoft |
| CyberArk |
| Delinea |
| Okta |
| Others |
Cost & Logistics Intelligence
AES-256 encryption chip spot prices from Taiwan semiconductor foundries cascade through credential security platform tiers, compressing margins for SaaS-native vendors while hardening pricing power for self-hosted solution providers serving German automotive suppliers under GDPR Article 44 constraints.
Pricing Analysis
Input-cost pass-through from FIDO2 hardware authenticator shortages concentrates pricing pressure on mid-market SaaS tiers. Subscription models stratify across enterprise-grade IAM integration, standalone vaulting, and freemium consumer tiers. Price differentiation hinges on Common Criteria EAL4+ certification status and sovereign data residency guarantees. Healthcare networks under HIPAA enforcement show lowest price sensitivity due to compliance-driven procurement mandates, while SMB segments face acute cost compression from competing open-source alternatives.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific semiconductor lanes disrupts FIDO2 token availability for enterprise rollout schedules. Hardware security module manufacturing concentrates in Taiwan, South Korea, and Japan. Component dependencies span lattice-based cryptographic processors, secure enclave chips, and tamper-resistant packaging. Single-source vulnerability around Taiwan Strait logistics threatens token procurement timelines. Distribution runs through direct enterprise sales, channel partners, and hyperscaler marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as post-quantum cryptographic migration forces buyers toward premium vault architectures with hybrid certificate management capabilities.
For Market Incumbents: Extend zero-knowledge architecture roadmaps to encompass NIST post-quantum algorithm integration before certification latency widens competitive gaps. Defend against open-source displacement by deepening mainframe protocol adapter coverage for healthcare and energy utility incumbents. Prioritize EU-sovereign data residency certifications to capture NIS2 implementation waves.
For New Entrants and Emerging Players: The premium-to-economy price gap in German Mittelstand manufacturing offers white-space entry through DevSecOps-native credential injection tools. Target platform engineering teams outside traditional IT security hierarchies with infrastructure-as-code vaulting solutions. Pursue channel partnerships with CI/CD pipeline vendors to bypass incumbent sales cycles.
For Investors and Strategic Acquirers: Consolidation pressure builds where cryptographic talent scarcity constrains zero-knowledge implementation velocity. Long-term viability favors platforms with post-quantum migration roadmaps and EU data sovereignty positioning. Acquisition target archetypes include lattice-based cryptography specialists and DevSecOps tooling vendors. Monitor NIST algorithm finalization timelines as inflection indicator for procurement cycle reactivation.
| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Cryptography Integration | Hybrid certificate management bridges RSA/ECC standards with NIST lattice-based algorithms for future-proof vaulting. |
| EU Sovereign Data Residency Certification | GDPR Article 44 compliance unlocks German automotive and Dutch healthcare procurement under NIS2 deadlines. |
| DevSecOps Pipeline Partnership | CI/CD credential injection displaces manual vault administration among platform engineering teams. |
| SCADA/OT Protocol Adapter Development | FERC-regulated energy utilities require specialized adapters for critical infrastructure credential rotation. |
| Open-Source Transparency Program | Public codebase audits satisfy METI framework requirements for Japanese manufacturing supply-chain resilience. |
Research Approach
Direct dialogue with CISOs, identity operations directors, platform engineers, and healthcare compliance officers grounded qualitative findings, validated against secondary sources including FDA cybersecurity guidance documents, EU NIS2 transposition notices, FERC reliability standards, and METI framework revisions. Bottom-up and top-down triangulation reconciled vendor shipment data with enterprise procurement pipeline disclosures.
Analytical lenses alternated between bottom-up credential volume modeling and top-down IT security budget allocation analysis across the projection horizon. Segmentation dimensions spanned deployment architecture, solution type, compliance mandate tier, and regional regulatory cluster. CAGRs derived from logarithmic trend fitting of historical adoption curves, with forecast inputs incorporating HIPAA enforcement intensity scores and NIS2 national transposition timelines.
The model assumes a particular technology adoption path; alternative pathways for post-quantum cryptographic migration would alter the outlook. Forecasts reflect assumptions around NIST algorithm standardization schedules and hardware authenticator supply chain stabilization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Global Behavioral Biometrics Market
Biometrics & Identity Management
Europe Decentralized Identity Market
Biometrics & Identity Management
Fingerprint Biometrics Market
Biometrics & Identity Management
Europe Enterprise Biometrics Market
Biometrics & Identity Management
Biometric Services Platform (Biosp) Market
Biometrics & Identity Management
Global Multifactor Authentication Market
Biometrics & Identity Management
Italy Mobile Biometrics Market
Biometrics & Identity Management
Spain Mobile Biometrics Market
Biometrics & Identity Management
Germany Identity Verification and Authentication Market
Biometrics & Identity Management
Latin America Biometrics Market
Biometrics & Identity Management
Biometrics As a Service in Healthcare Market
Biometrics & Identity Management
Out-Of-Band Authentication Market
Biometrics & Identity Management
Global Authentication Services Market
Biometrics & Identity Management
Consumer Biometrics Market
Biometrics & Identity Management
Identity Theft Protection Services Market
Biometrics & Identity Management
Global Personal Identity Management Market