
 Gait Biometrics Market | 2026-2036
Gait Biometrics Market Size, Share, and Industry Trends Forecast 2026-2036
Gait Biometrics Market Analysis
A shift from single-source sensor procurement to multi-source component sourcing is recalibrating how gait biometrics vendors secure hardware supply. BioSensics leverages its wearable sensor specialization to anchor clinical trial partnerships across rehabilitation centers. NEC Corporation dominates computer vision deployments for security applications, while Fujitsu Limited extends its pressure mat manufacturing scale into athletic performance facilities.
Gait biometrics identifies individuals through distinctive locomotion patterns captured via kinematic, kinetic, or spatiotemporal measurements, typically requiring sampling rates above 100 Hz for clinical-grade precision and employing machine learning classifiers trained on multi-joint trajectory data. The technology serves primary commercial purposes spanning patient fall-risk assessment, forensic identification, and athletic biomechanics optimization. Computer vision solutions occupy the largest installed base due to minimal hardware requirements, though wearable sensors represent the fastest-expanding segment as MEMS accelerometer costs decline and battery efficiency improves. Healthcare monitoring applications sustain the deepest margin pools because reimbursement codes in Germany and Japan validate clinical utility, while security systems compete primarily on price per monitored access point.
The FDA regulates gait biometrics software as AI-enabled medical devices when deployed for diagnostic purposes, requiring 510(k) premarket notification or De Novo classification based on predicate availability. The EU AI Act classifies biometric identification systems as high-risk, mandating conformity assessment through notified bodies before CE marking and market entry. ISO 13485 quality management systems and IEC 62304 software lifecycle standards govern manufacturing processes for regulated healthcare deployments. Stakeholders must monitor evolving harmonization between FDA software-as-medical-device guidance and EU AI Act implementing acts to avoid fragmented compliance architectures.
Market Dynamics
The gait biometrics market is restructuring around regulatory bifurcation between medical device pathways and security system exemptions, with the EU AI Act high-risk classification forcing vendors to maintain dual compliance architectures for cross-border deployments.
Growth Catalysts
- Clinical reimbursement validation:Germany's statutory health insurance system and Japan's long-term care insurance programs now recognize gait analysis for fall-risk assessment, creating predictable payment streams for healthcare providers deploying these systems.
- MEMS accelerometer cost compression:Wearable sensor hardware economics have crossed critical thresholds where battery-efficient, high-sampling-rate devices achieve price points viable for mass rehabilitation center deployment.
- EU AI Act conformity infrastructure:The high-risk classification mandate for biometric identification systems is accelerating notified body capacity expansion across France, Germany, and the Netherlands, reducing CE marking timelines for compliant vendors.
Market Restraints
- Silicon supply concentration:Advanced MEMS fabrication for clinical-grade inertial measurement units depends on Taiwanese and South Korean foundry capacity, exposing sensor vendors to geopolitical supply disruptions.
- FDA predicate scarcity:The De Novo classification pathway for novel gait diagnostic algorithms extends premarket timelines substantially when no substantially equivalent device exists for 510(k) submission.
- Computer vision substitution pressure:Markerless video-based gait analysis from smartphone cameras and standard security infrastructure threatens wearable sensor volumes in non-clinical applications where sub-100 Hz sampling suffices.
Strategic Opportunities
- Athletic performance facilities:Pressure mat and force plate integration into professional sports training centers in the United States represents an underpenetrated vertical with direct procurement budgets outside insurance reimbursement constraints.
- ISO 13485 certification arbitrage:Vendors holding both FDA QSR compliance and EU MDR quality system certification can access dual markets with unified manufacturing audits, compressing regulatory overhead per geography.
- Edge AI convergence:On-device neural network inference for real-time gait classification is absorbing microcontroller advances from adjacent IoT sectors, enabling ambulatory monitoring without cloud connectivity dependencies.
Industry Challenges
- Biomechanical data science talent scarcity:The intersection of kinesiology domain expertise and machine learning engineering remains shallow, forcing vendors to train interdisciplinary teams internally or compete for rare hybrid profiles.
- Legacy electronic health record integration:Healthcare providers require HL7 FHIR-compliant data exchange architectures that most gait analysis platforms lack, extending sales cycles and implementation costs.
- Multi-site clinical validation requirements:Payers and regulators demand reproducibility across diverse patient populations and facility types, necessitating expensive multi-center trials for algorithm generalization claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gait Biometrics Market |
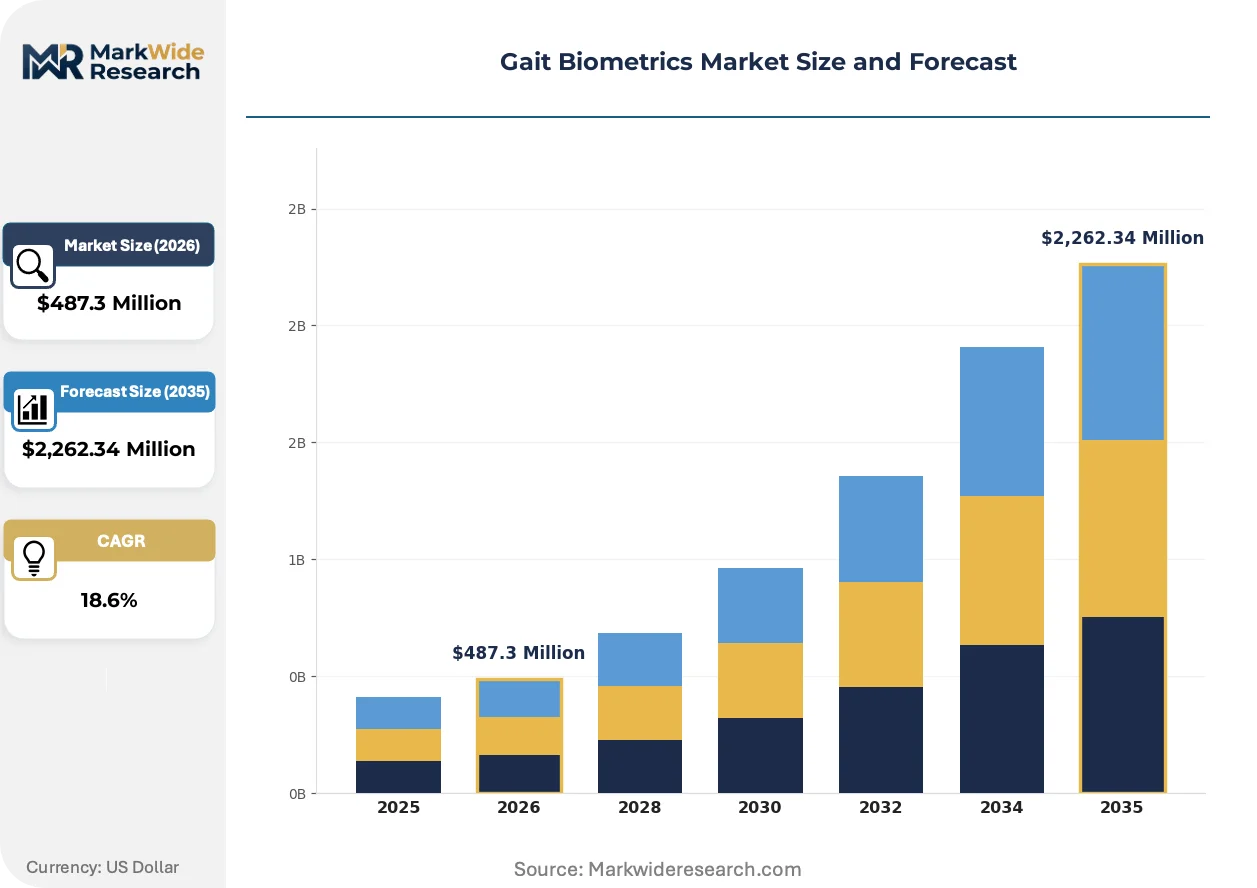
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $2,262.34 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Computer Vision, Wearable Sensors, Pressure Sensors, Smartphone-based Solutions Application: Healthcare Monitoring, Security Systems, Sports Analytics, Rehabilitation End User: Healthcare Providers, Athletic Organizations, Educational Institutions, Law Enforcement Delivery Mode: Cloud-based, On-premises, Hybrid, Mobile Applications |
| Companies Covered | BioSensics, Motek Medical BV, NEC Corporation, CIR Systems Inc., Noraxon USA Inc., Intel Corporation, MindMaze SA, Tekscan Inc., Fujitsu Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gait Biometrics Market Emerging Trajectories
Sensor fusion architectures and on-device inference capabilities are compressing the hardware-software boundary in gait biometrics, while regulatory frameworks on both sides of the Atlantic harden compliance requirements for biometric identification deployments.
Multi-modal sensor fusion combining inertial measurement units with pressure-sensitive insoles is absorbing microcontroller advances from industrial IoT applications, enabling sub-10 millisecond synchronization between kinematic and kinetic data streams. Rehabilitation centers in Germany and Japan are adopting these integrated platforms for comprehensive gait lab functionality at one-fifth the footprint of traditional camera-based systems. The technology is absorbing price compression from consumer electronics supply chains, forcing standalone component vendors to bundle software analytics or face margin erosion.
The EU AI Act's high-risk classification for biometric identification systems mandates conformity assessment through notified bodies before CE marking, creating a two-tier market where medical device vendors with existing ISO 13485 infrastructure absorb compliance costs more efficiently than security-focused entrants. This regulatory architecture is fragmenting product development roadmaps, as vendors must maintain separate algorithm validation dossiers for clinical diagnostic claims versus security identification applications. France's CNIL and Germany's regional data protection authorities are issuing supplementary guidance on lawful basis for biometric processing that extends implementation timelines for multi-country deployments.
Hospital procurement departments are consolidating gait analysis purchasing under broader digital health platform contracts, displacing standalone sensor vendors who lack electronic health record integration capabilities. United States health systems participating in Medicare accountable care organizations are prioritizing remote patient monitoring vendors with established reimbursement coding expertise, filtering hardware-only suppliers from preferred vendor lists. This concentration is most visible in the Veterans Health Administration network, where centralized contracting for telehealth infrastructure bundles gait monitoring into multi-condition chronic disease management platforms.
Gait Biometrics Market Segmentation
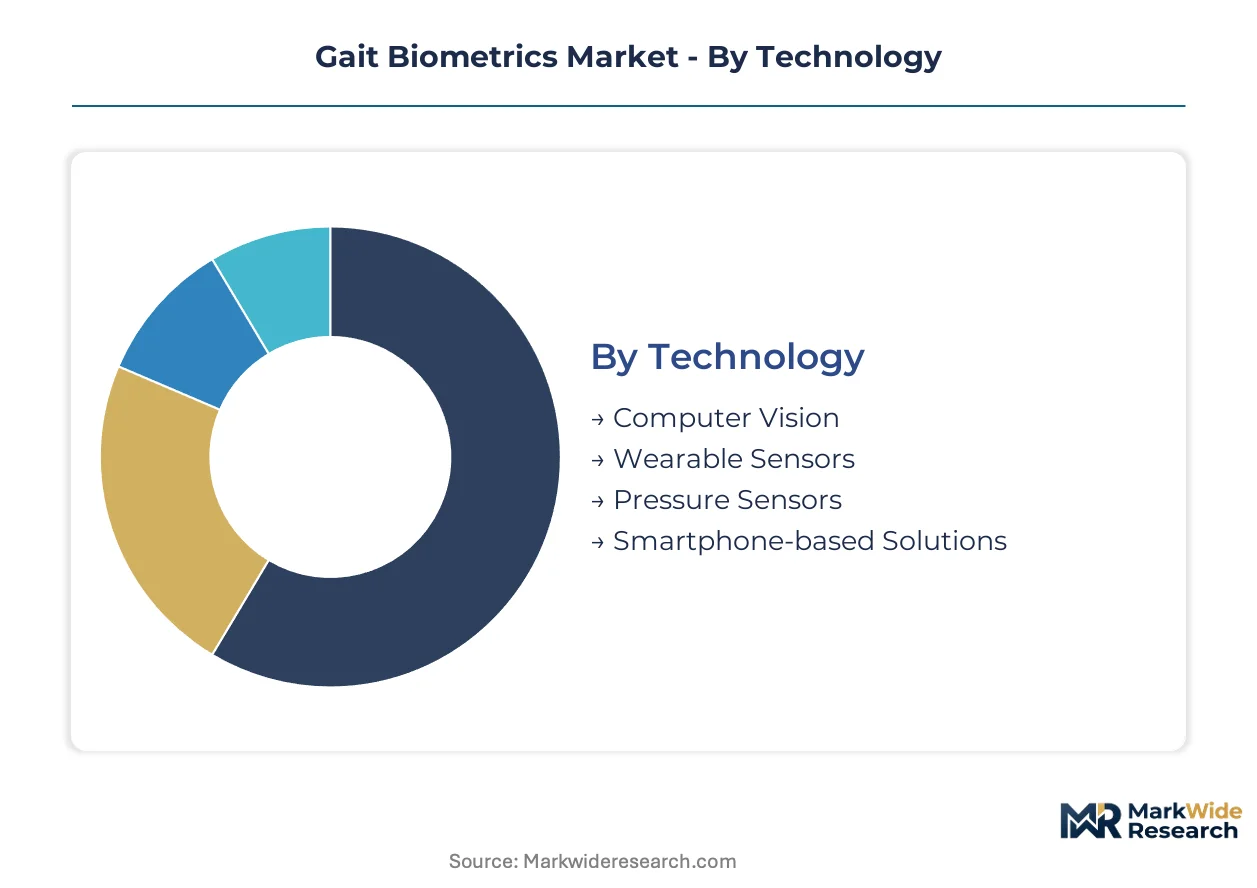
Segmentation in gait biometrics reveals how hardware economics and regulatory pathways fragment vendor strategies across deployment contexts. Technology choices determine compliance architecture, while application focus dictates reimbursement access and procurement timelines.
Technology:
Upgrade cycles in this category accelerate where MEMS cost curves and edge AI capabilities create replacement pressure against legacy camera installations.
- Computer Vision:Markerless video analysis extracts kinematic parameters from standard camera feeds at 30-60 Hz sampling rates. Demand concentrates in United States security infrastructure where existing CCTV networks minimize incremental hardware spend, though sub-clinical precision limits diagnostic reimbursement eligibility.
- Wearable Sensors:Inertial measurement units combining accelerometers and gyroscopes capture 100+ Hz multi-axis motion data with Bluetooth Low Energy transmission. Germany and Japan rehabilitation centers drive procurement volume as statutory insurance validates fall-risk assessment claims, while battery efficiency improvements compress replacement intervals to 18-24 months.
- Pressure Sensors:Force plate and insole mat configurations measure ground reaction forces and center-of-pressure trajectories.
- Smartphone-based Solutions:Embedded IMUs and camera arrays leverage consumer device ubiquity for decentralized gait screening.
Volume placements concentrate in Computer Vision; the faster expansion belongs to Wearable Sensors.
Application:
Cost tier differentiation separates reimbursed clinical workflows from self-funded security and athletic deployments.
- Healthcare Monitoring:Continuous ambulatory assessment for fall-risk stratification, medication efficacy tracking, and neurodegenerative progression monitoring. United States accountable care organizations and German statutory insurers validate payment codes, creating predictable procurement budgets that absorb premium sensor pricing.
- Security Systems:Forensic identification and access control via gait signatures captured at facility perimeters. Price competition per monitored access point dominates vendor selection, compressing margins unless computer vision solutions eliminate hardware costs entirely.
- Sports Analytics:Biomechanical optimization for injury prevention and performance enhancement in professional training facilities.
- Rehabilitation:Post-surgical and stroke recovery protocols requiring quantified mobility metrics for discharge planning.
Revenue concentration sits with Healthcare Monitoring; Sports Analytics climbs fastest as direct athletic organization budgets bypass insurance constraints.
End User:
Customer type determines integration complexity and sales cycle duration across procurement methodologies.
- Healthcare Providers:Hospitals and outpatient clinics requiring HL7 FHIR-compliant electronic health record integration and FDA 510(k) or EU MDR device certification. Multi-site health systems in the United States consolidate gait analysis purchasing under broader digital health platform contracts, filtering standalone vendors.
- Athletic Organizations:Professional sports franchises and Olympic training centers with direct capital expenditure authority and performance-focused evaluation criteria.
- Educational Institutions:University biomechanics laboratories and kinesiology departments with research-oriented procurement and grant-dependent budgets.
- Law Enforcement:Forensic units deploying gait analysis for suspect identification from surveillance footage.
Procurement volume aggregates at Healthcare Providers; Athletic Organizations expand most quickly outside reimbursement-dependent sales cycles.
Delivery Mode:
Maturity gradients separate established on-premises installations from emerging cloud-native architectures.
- Cloud-based:Centralized data storage and algorithm updates with subscription pricing models. Germany's CNIL and France's data protection authorities impose supplementary biometric processing constraints that extend implementation timelines for multi-country deployments.
- On-premises:Local server installations satisfying healthcare provider data residency requirements and air-gapped security mandates.
- Hybrid:Edge inference with cloud analytics partitioning sensitive raw data from processed biomarker outputs.
- Mobile Applications:Smartphone-native deployments leveraging on-device neural network inference without connectivity dependencies.
Installed base dominance remains with On-premises; Hybrid architectures gain share fastest as edge AI convergence enables compliance-flexible configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon foundry capacity in Taiwan and South Korea anchors sensor hardware supply for gait biometrics deployments, while regulatory validation pathways in Germany, Japan, and the United States determine software commercialization timelines.
United States
The Veterans Health Administration and Medicare accountable care organizations drive procurement volume for remote patient monitoring platforms. FDA 510(k) and De Novo classification pathways govern AI-enabled diagnostic algorithms, extending premarket timelines for novel gait analysis claims. Boston and San Francisco Bay Area clusters concentrate digital health vendors integrating gait biomarkers into chronic disease management contracts.
Germany
Statutory health insurance reimbursement codes validate gait analysis for fall-risk assessment, creating predictable payment streams for rehabilitation centers. The EU AI Act high-risk classification for biometric identification mandates conformity assessment through notified bodies in Berlin and Munich. Bavaria and North Rhine-Westphalia host the deepest concentration of clinical trial sites validating multi-site algorithm reproducibility.
Japan
Long-term care insurance programs recognize gait monitoring for elderly fall prevention, sustaining premium sensor pricing in institutional settings. METI and PMDA coordinate on AI-enabled medical device guidance harmonization with international standards. Tokyo and Osaka metropolitan areas concentrate rehabilitation facility networks deploying integrated pressure mat and inertial measurement unit platforms.
United Kingdom
NHS integrated care systems are consolidating digital health procurement under platform contracts that filter standalone gait sensor vendors. MHRA operates the EU AI Act conformity assessment designation process for post-Brexit market access, creating dual regulatory exposure for cross-border deployments. London and Cambridge clusters concentrate biomechanical data science talent bridging kinesiology and machine learning engineering.
South Korea
Advanced MEMS foundry capacity in Gyeonggi Province supplies clinical-grade inertial measurement units to global gait biometrics vendors. MFDS medical device registration and data localization requirements under the Personal Information Protection Act shape cloud deployment architectures. Seoul Capital Area rehabilitation centers are piloting edge AI-enabled wearable sensors for ambulatory monitoring without connectivity dependencies.
Gait Biometrics Market Vendor Landscape
Global majors compete with regional champions across regulatory certification and reimbursement expertise, producing a tiered structure where medical device incumbents absorb compliance costs more efficiently than security-focused entrants. The vendor base separates into three archetypes: wearable sensor specialists with clinical trial partnerships, computer vision platforms leveraging existing security infrastructure, and pressure mat manufacturers extending from industrial measurement into athletic facilities. Dominant competitive moves include ISO 13485 certification arbitrage for dual FDA-EU market access and edge AI capability acquisition from adjacent IoT semiconductor supply chains.
Within the wearable sensor tier, BioSensics and Noraxon USA Inc. exemplify vendors anchoring clinical validation partnerships across rehabilitation networks. NEC Corporation occupies a position representing computer vision deployments for security applications where minimal hardware requirements drive price competition per monitored access point. Fujitsu Limited sits within the pressure sensor manufacturing archetype, extending industrial measurement scale into athletic performance facilities with direct procurement budgets outside insurance reimbursement constraints.
| Leading Market Players |
|---|
| BioSensics |
| Motek Medical BV |
| NEC Corporation |
| CIR Systems Inc. |
| Noraxon USA Inc. |
| Intel Corporation |
| MindMaze SA |
| Tekscan Inc. |
| Fujitsu Limited |
| Others |
Supply Flow & Price Mechanics
Hospital procurement consolidation under digital health platform contracts in the United States and Germany is compressing standalone sensor vendor margins and forcing component suppliers to bundle software analytics or absorb price erosion. This buyer-side concentration shifts supply chain leverage toward integrated platform vendors with ISO 13485 certification and electronic health record integration capabilities.
Pricing Analysis
Warranty and calibration service bundling separates premium-tier wearable sensor vendors from unbundled hardware competitors in rehabilitation center procurement. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) certification status and HL7 FHIR integration depth as primary differentiation drivers. Pricing pressure stems from MEMS accelerometer cost compression and smartphone-based markerless video substitution in non-clinical applications. Security system integrators exhibit highest price sensitivity per monitored access point, while German statutory insurers absorb premium pricing for validated fall-risk assessment platforms.
Supply Chain Analysis
Microelectromechanical systems engineering talent scarcity in Taiwan and South Korea constrains foundry expansion for clinical-grade inertial measurement units despite automated fabrication lines. Advanced MEMS fabrication draws from Taiwanese and South Korean wafer capacity, with raw material dependencies spanning silicon wafers, rare earth magnets, and lithium-polymer battery cells. Single-source vulnerability concentrates in TSMC and Samsung foundry allocations for sub-100-micron precision accelerometers. Distribution runs through medical device distributors in Germany, direct hospital procurement in the United States, and rehabilitation equipment specialists in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edge AI inference capabilities on microcontroller platforms are displacing cloud-dependent gait analysis architectures, compressing hardware-software boundaries and rewriting vendor competitive requirements.
For Market Incumbents: Acquire edge AI semiconductor design teams to embed real-time classification on battery-efficient wearables before smartphone-based markerless video captures non-clinical volume. Reinforce ISO 13485 certification moats through unified FDA-EU quality system audits that fragment compliance costs for security-focused entrants. Defend against computer vision substitution by locking rehabilitation center partnerships with HL7 FHIR-integrated platforms.
For New Entrants and Emerging Players: Capture athletic performance facility procurement in the United States where direct capital expenditure authority bypasses insurance reimbursement constraints and six-month sales cycles. Target pressure mat and force plate integration for professional sports training centers as the most penetrable vertical outside healthcare regulatory pathways. Lead with on-device neural network demonstrations that eliminate cloud connectivity dependencies and data residency complications.
For Investors and Strategic Acquirers: Re-rating potential sits with wearable sensor specialists holding dual FDA-EU certification and established German statutory insurance reimbursement codes given EU AI Act high-risk classification barriers. Long-term viability favors vendors with captive edge AI capability and multi-site clinical validation dossiers rather than hardware-only suppliers. Watch notified body capacity expansion timelines in France and Germany as inflection indicators for CE marking velocity and market entry speed.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Arbitrage | Unified manufacturing audits compress regulatory overhead for FDA and EU MDR dual market access. |
| Edge AI Capability Acquisition | On-device inference absorbs microcontroller advances from industrial IoT for ambulatory monitoring. |
| HL7 FHIR Integration Development | Electronic health record compliance filters standalone vendors from hospital procurement consolidation. |
| Multi-Site Clinical Validation | Bavaria and North Rhine-Westphalia trial sites validate algorithm reproducibility for payer acceptance. |
| Athletic Facility Direct Sales | Professional sports training centers offer procurement budgets outside insurance reimbursement constraints. |
Methodological Framework
Document review covered FDA 510(k) filings, EU MDR notified body guidance, and German statutory insurance reimbursement codes, complemented by interviews with rehabilitation center biomedical engineers, hospital GPO contracts managers, MEMS foundry procurement leads, and athletic facility performance directors. Secondary validation drew from CMS Medicare remote patient monitoring data, Japanese long-term care insurance program documentation, and Taiwan Semiconductor Industry Association capacity reports. Bottom-up sensor shipment estimates and top-down healthcare IT spending analysis provided triangulation anchors.
Historical volume trajectories were cross-referenced against expert panel inputs on MEMS cost curves and edge AI adoption timelines. The analytical framework modeled technology segmentation across computer vision, wearable sensors, pressure mats, and smartphone-based solutions; application segmentation spanning healthcare monitoring, security systems, sports analytics, and rehabilitation; and delivery mode segmentation across cloud, on-premises, hybrid, and mobile architectures. CAGRs were derived from regression analysis of reimbursement code expansion and sensor hardware economics across the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act implementing acts, FDA software-as-medical-device guidance harmonization, and MEMS foundry allocation shifts. Forecasts reflect assumptions on regulatory timeline stability and reimbursement code persistence. Material deviation in notified body capacity expansion or Taiwan semiconductor export controls warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Biometric Authentication Solution Market
Biometrics & Identity Management
Biometrics As a Service in Healthcare Market
Biometrics & Identity Management
Automated Fingerprint Identification Systems (AFIS) Market
Biometrics & Identity Management
United States Facial Recognition Market
Biometrics & Identity Management
Latin America Government & Security Biometrics Market
Biometrics & Identity Management
Global Authentication Services Market
Biometrics & Identity Management
Biometric Bike Locks Market
Biometrics & Identity Management
Biometric Smart Cards Market
Biometrics & Identity Management
Biometric Lockers Market
Biometrics & Identity Management
Passive Authentication Market
Biometrics & Identity Management
North America Enterprise Biometrics Market
Biometrics & Identity Management
Mobile Biometrics Market
Biometrics & Identity Management
Mobile Biometric Security and Services Market
Biometrics & Identity Management
Biometrics Banking Market
Biometrics & Identity Management
Mobile Devices User Authentication Services Market
Biometrics & Identity Management
Germany Identity Verification and Authentication Market