
 United States Biometrics Market | 2026-2036
United States Biometrics Market Size, Share, and Industry Trends Forecast 2026-2036
United States Biometrics Market Intelligence
Buyer concentration among federal agencies and large enterprise security departments is expanding as procurement consolidates under fewer prime contractors with cleared facility status. HID Global Corporation leverages its established government channel relationships to sustain recurring revenue from federal identity credentialing programs. IDEMIA anchors its position through manufacturing scale and domestic production facilities serving DHS and DoD contracts. Princeton Identity differentiates via specialized iris recognition systems deployed at high-security research installations.
United States biometrics encompasses automated methods for measuring and analyzing unique physiological or behavioral characteristics—fingerprint minutiae, facial geometry, iris patterns, or voiceprints—for identification and verification purposes. These systems typically operate through sensor capture, template extraction, and matching algorithms against enrolled databases, with accuracy thresholds measured by false acceptance and false rejection rates. Fingerprint recognition occupies the largest installed base due to legacy access control infrastructure and mobile device integration, while facial recognition represents the fastest-expanding segment driven by touchless authentication demand in healthcare and transportation settings. Voice recognition sits at a more nascent stage, with margin pools concentrated in call center fraud prevention and remote banking verification workflows.
The National Institute of Standards and Technology (NIST) establishes biometric performance testing protocols that determine vendor eligibility for federal procurement, while the Department of Homeland Security (DHS) mandates specific interoperability standards for border and credentialing applications. FDA oversight applies where biometric systems integrate with medical device authentication or patient identification workflows in healthcare settings. Stakeholders must monitor evolving NIST test criteria and state-level biometric privacy legislation to anticipate compliance costs and market access barriers.
Market Dynamics
Federal procurement consolidation around cleared facility contractors is compressing vendor access to DHS and DoD identity credentialing programs, privileging primes with established security clearances and domestic manufacturing footprints.
Growth Catalysts
- NIST FRVT Testing Protocols:Updated facial recognition vendor test benchmarks accelerate federal agency adoption of qualified multimodal systems for border and credentialing applications.
- Touchless Authentication Surge:Healthcare facilities and airport authorities deploy iris and facial recognition to replace fingerprint contact points in high-throughput security lanes.
- California-Texas Infrastructure Clustering:Defense contractor concentration and border technology investments in these states concentrate demand for biometric integration services.
Market Restraints
- Silicon Sensor Supply Concentration:Fingerprint and iris capture module production concentrates among East Asian foundries, exposing integrators to geopolitical supply disruptions.
- Template Storage Cost Structure:Large-scale biometric database operations face escalating cloud infrastructure and encryption compliance expenditures under federal data protection mandates.
- State Privacy Law Fragmentation:Illinois BIPA and emerging California biometric privacy statutes impose inconsistent consent and retention requirements across multi-state deployments.
Strategic Opportunities
- Veterans Health Administration Expansion:VA medical centers present underpenetrated demand for patient identification systems integrating with existing electronic health record infrastructure.
- Behavioral Biometric Convergence:Keystroke dynamics and gait analysis fusion with physiological modalities opens fraud prevention applications in remote banking and call center workflows.
- Buy American Procurement Preference:DHS and DoD domestic content mandates create competitive openings for vendors with US-based manufacturing and assembly operations.
Industry Challenges
- Algorithm Bias Mitigation Expertise:Vendors face acute shortage of machine learning engineers specializing in demographic parity testing and NIST-compliant fairness validation.
- Legacy Physical Access Control Integration:Federal facilities require backward compatibility with decades-old card reader infrastructure during multimodal system upgrades.
- Continuous Certification Timelines:NIST evaluation cycles and DHS SAFETY Act qualification processes extend sales-to-revenue recognition periods by 18-24 months.
Report Scope
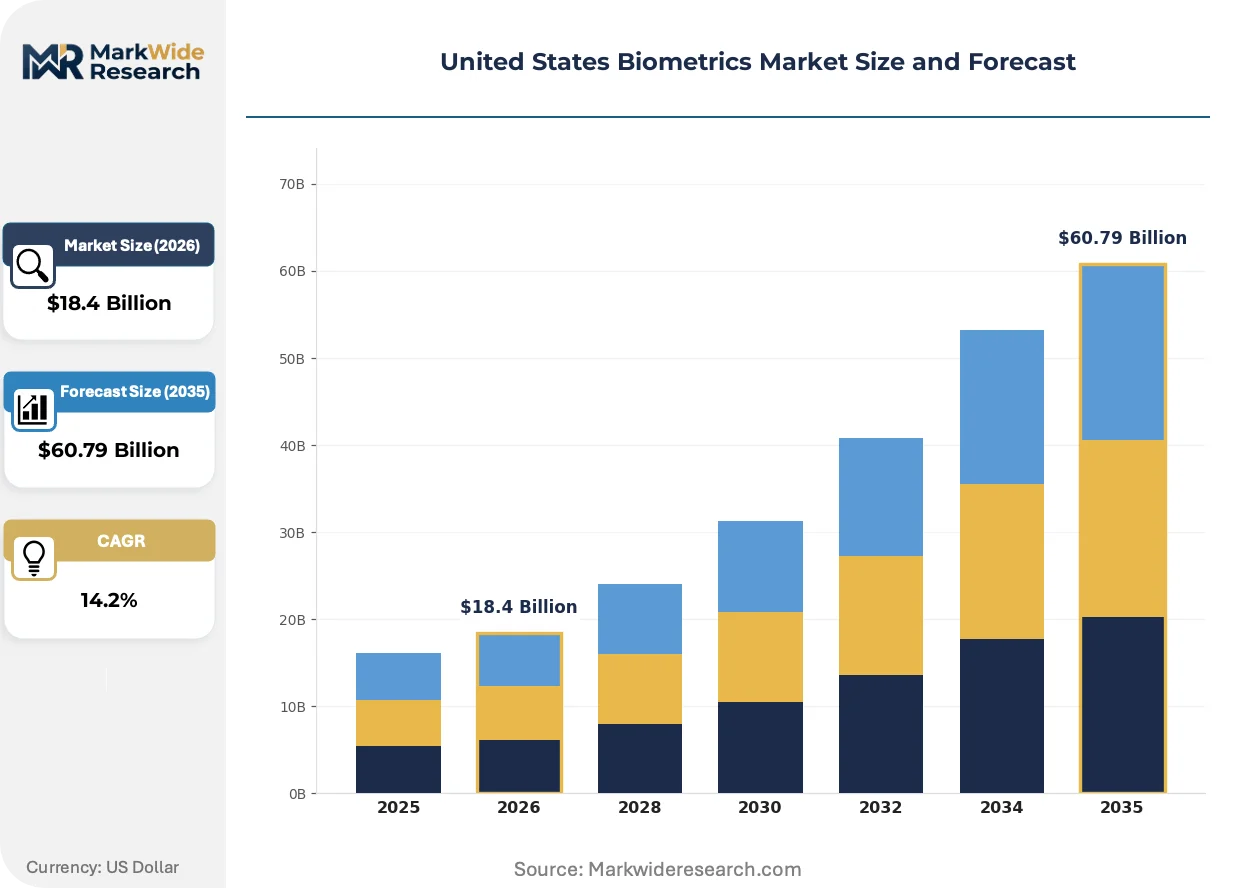
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Biometrics Market |
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $60.79 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fingerprint Recognition, Facial Recognition, Iris Recognition, Voice Recognition Application: Identity Verification, Access Control, Time & Attendance, Law Enforcement End User: Government, Healthcare, Banking, Retail Deployment: On-premises, Cloud-based, Hybrid, Embedded |
| Companies Covered | HID Global Corporation, Biofire Technologies Inc., Synaptics Incorporated, Redrock Biometrics, TwoSense AI, Qualcomm Incorporated, Aware Inc., Princeton Identity, IDEMIA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Biometrics Market Strategic Shifts & Innovations
Edge computing architectures and on-device template processing are redistributing biometric matching workloads away from centralized databases toward sensor-integrated chipsets, altering system design priorities and vendor capability requirements.
Contactless fingerprint capture using high-resolution ultrasonic and optical sensors is rewriting physical access control deployment economics. Corporate security departments and critical infrastructure operators accelerate replacement of legacy contact-based readers. This compression of hardware refresh cycles is squeezing margins for traditional capacitive sensor manufacturers while rewarding semiconductor firms with advanced imaging intellectual property.
The FDA's evolving guidance on biometric-enabled medical device authentication is tightening validation requirements for patient identification systems deployed in hospital settings. Device manufacturers must now demonstrate clinical-grade accuracy thresholds and interoperability with electronic health record platforms. Healthcare IT procurement committees in Texas and California medical center networks are prioritizing vendors with existing FDA 510(k) clearances.
Airport authorities and federal tenant agencies are consolidating biometric service contracts under multi-year performance-based agreements that bundle hardware, software, and operational support. Traditional equipment purchase models are losing share to integrated service offerings where vendors assume template management and system uptime liability. This restructuring is most advanced at DHS-sponsored installations along the southwest border corridor.
United States Biometrics Market Segmentation
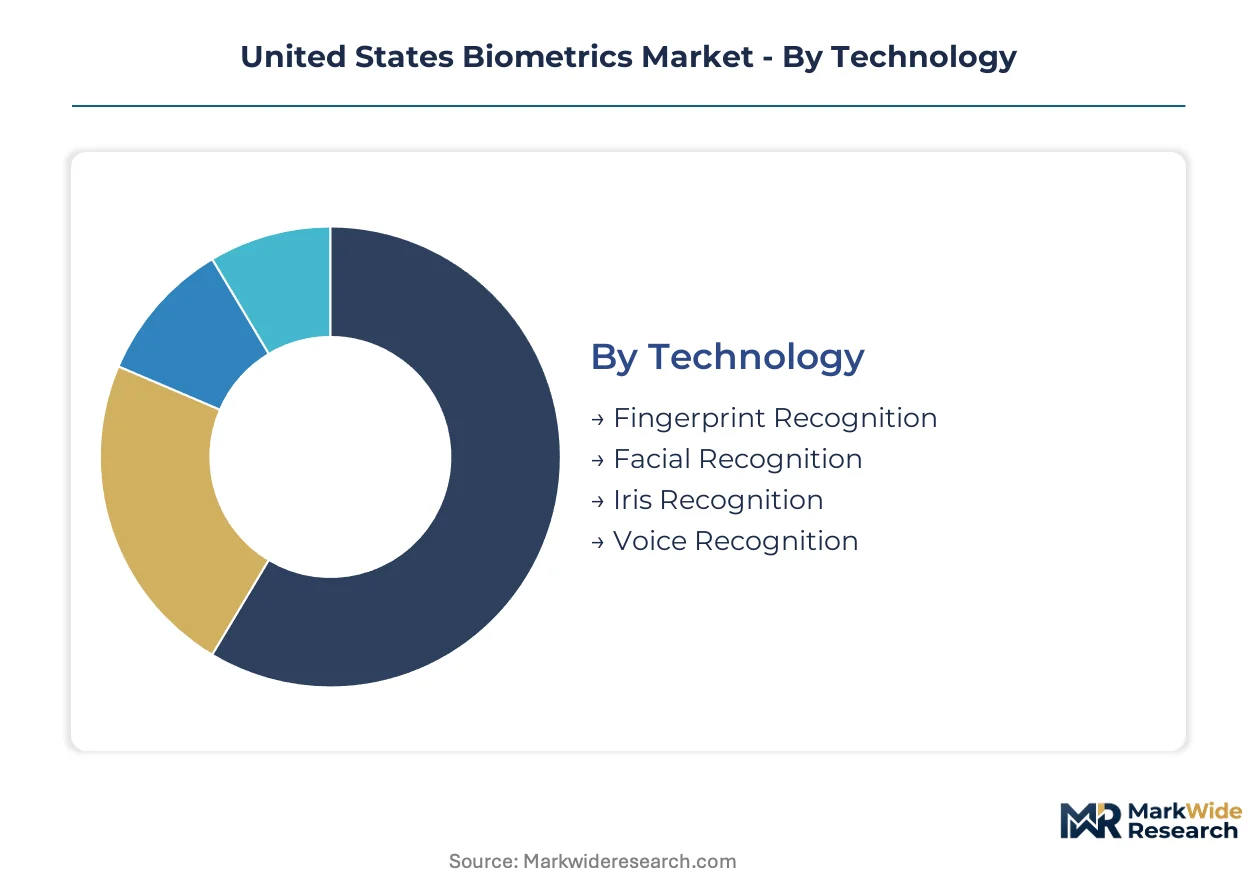
Biometric procurement patterns diverge sharply across federal, enterprise, and consumer contexts, with technology selection driven by accuracy thresholds, throughput requirements, and regulatory compliance burdens rather than cost alone. Vendors must align product architectures to distinct operational constraints spanning cleared facility networks, HIPAA-regulated healthcare workflows, and frictionless retail authentication.
Technology:
Federal buyers prioritize modalities with NIST-certified accuracy metrics, while healthcare and transportation sectors weight touchless operation and user throughput more heavily.
- Facial Recognition:Algorithms match facial geometry against enrolled templates using visible or infrared spectrum capture. Touchless deployment at DHS border crossings and VA medical centers accelerates as agencies replace fingerprint contact points. NIST FRVT qualification gates federal eligibility.
- Fingerprint Recognition:Minutiae extraction from ridge patterns dominates legacy physical access control infrastructure and mobile device integration. Capacitive sensors face replacement pressure from ultrasonic contactless alternatives at federal facilities and corporate campuses.
- Iris Recognition:Pattern analysis of the colored stroma offers high accuracy at distance. Princeton Identity and IDEMIA compete for high-security research installation contracts where false acceptance rates must approach zero.
- Voice Recognition:Spectral and behavioral analysis of speech patterns remains concentrated in call center fraud prevention and remote banking verification workflows with limited federal adoption.
Fingerprint recognition leads volumes today; facial recognition is gaining share fastest.
Application:
Deployment economics vary by whether the biometric system authenticates against a watchlist, verifies claimed identity, or tracks presence over time.
- Identity Verification:One-to-one matching confirms that a live sample matches a claimed enrolled template. State DMVs and airport credentialing authorities drive demand for ICAO-compliant document authentication systems.
- Access Control:Physical entry authorization at federal facilities and critical infrastructure sites requires PIV card compatibility and multimodal fallback options. DHS mandates shape procurement specifications for southwest border infrastructure.
- Time & Attendance:Workforce presence tracking in manufacturing and logistics environments favors low-cost fingerprint terminals, though Illinois BIPA litigation has shifted some buyers toward facial alternatives.
- Law Enforcement:Forensic identification against criminal databases demands latent print capability and rapid mobile enrollment. FBI NGI interoperability requirements constrain vendor selection.
Access control leads volumes today; identity verification is climbing the fastest.
End User:
Budget cycles, security clearance requirements, and data handling protocols segment buyer behavior across institutional categories.
- Government:Federal agencies concentrate procurement among cleared facility primes with domestic manufacturing. DHS and DoD identity credentialing programs represent the largest revenue pool, with SAFETY Act qualification extending sales cycles.
- Healthcare:HIPAA-covered entities and FDA-regulated device authentication drive demand for patient identification systems. Texas and California medical center networks prioritize vendors with existing 510(k) clearances.
- Banking:Remote account opening and call center fraud prevention deploy voice and facial verification. Behavioral biometric fusion with keystroke dynamics opens new authentication layers.
- Retail:Frictionless checkout and loyalty program authentication remain experimental, with privacy litigation risk constraining deployment scale.
Government leads volumes today; healthcare shows the steepest expansion trajectory.
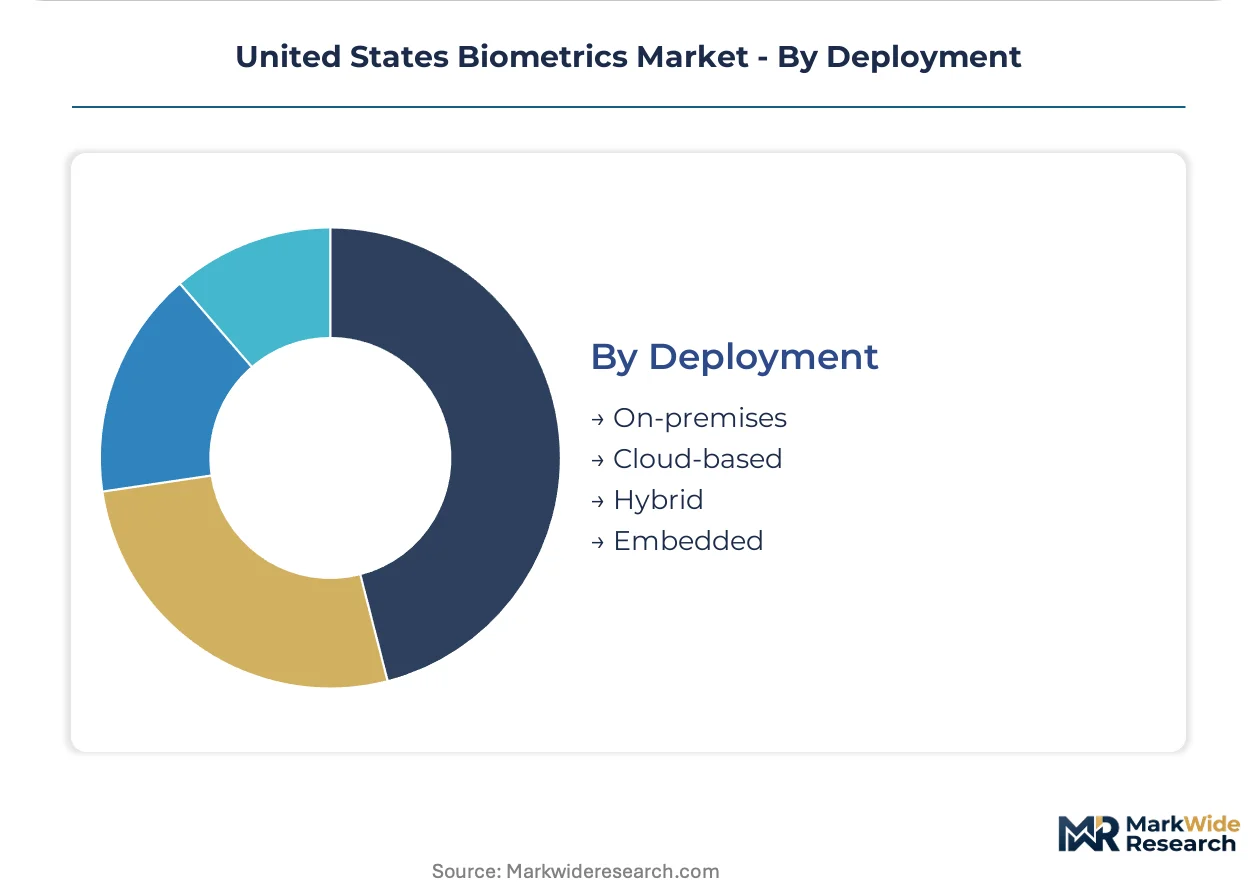
Deployment:
Architecture selection trades off latency, data sovereignty, and operational control against capital expenditure and internal IT burden.
- On-premises:Template storage and matching execute within agency-controlled data centers. Federal classified networks and critical infrastructure operators mandate this architecture for sensitive biometric databases.
- Cloud-based:Managed service delivery reduces capital burden for state and municipal buyers. Escalating encryption compliance expenditures and state privacy law fragmentation constrain multi-tenant deployments.
- Hybrid:Edge capture with centralized enrollment and audit logging balances latency and scalability. Airport authorities and large healthcare networks favor this model for distributed facility footprints.
- Embedded:On-device template processing in smartphones and specialized terminals redistributes matching workloads. Semiconductor firms with advanced imaging IP capture margin from this architectural shift.
On-premises leads volumes today; hybrid is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense contractors and cleared facility engineers cluster in California and Texas, anchoring federal biometric procurement concentration. State-level privacy statutes create compliance patchwork that fragments deployment economics across jurisdictions.
California
Silicon Valley semiconductor firms and Los Angeles defense contractors drive multimodal system integration demand. The California Consumer Privacy Act and emerging biometric privacy statutes impose consent and retention requirements that constrain multi-tenant cloud deployments. San Diego's military research corridor hosts iris recognition pilots at high-security federal installations.
Texas
Austin semiconductor design houses and Dallas-Fort Worth systems integrators concentrate DHS border infrastructure contracting. State procurement codes align with federal Buy American mandates, privileging domestic assembly operations. Houston's medical center networks prioritize FDA-cleared patient identification systems for Veterans Health Administration facilities.
Virginia
Northern Virginia's cleared facility corridor anchors federal identity credentialing program execution. NIST Gaithersburg proximity accelerates vendor participation in FRVT qualification cycles. Fairfax County primes manage SAFETY Act procurement for southwest border biometric deployments.
Illinois
Chicago financial services firms deploy voice and behavioral biometrics for call center fraud prevention under BIPA litigation pressure. The state's biometric privacy statute drives enterprise buyers toward facial recognition alternatives to fingerprint systems. Downstate manufacturing plants adopt touchless authentication for workforce time tracking.
Florida
Miami international airport authorities and Orlando federal tenant agencies consolidate biometric service contracts under performance-based agreements. State procurement favors vendors with existing DHS interoperability certifications. Tampa Bay healthcare networks pilot FDA-regulated patient identification for VA medical center integration.
United States Biometrics Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across federal, enterprise, and consumer authentication segments. The vendor base stratifies around cleared facility status, domestic manufacturing footprints, and NIST certification timelines. Three archetypes dominate: semiconductor firms with imaging intellectual property, systems integrators with federal channel relationships, and modality specialists with research-grade accuracy. Competitive dynamics center on strategic partnerships for algorithm licensing and capacity expansion for domestic assembly operations.
Among federal-channel specialists, HID Global Corporation and Princeton Identity occupy positions tied to government credentialing programs and high-security research installations respectively. IDEMIA anchors the manufacturing-scale tier with domestic production facilities serving DHS and DoD contracts. Semiconductor players including Synaptics Incorporated and Qualcomm Incorporated exemplify the imaging-IP archetype capturing margin from edge computing architectural shifts.
| Leading Market Players |
|---|
| HID Global Corporation |
| Biofire Technologies Inc. |
| Synaptics Incorporated |
| Redrock Biometrics |
| TwoSense AI |
| Qualcomm Incorporated |
| Aware Inc. |
| Princeton Identity |
| IDEMIA |
| Others |
Cost & Logistics Intelligence
Contactless fingerprint capture using ultrasonic and optical sensors is redistributing manufacturing value from legacy capacitive sensor producers toward semiconductor firms with advanced imaging intellectual property, simultaneously compressing hardware refresh cycles and concentrating supply leverage among East Asian foundries with high-resolution sensor fabrication capability.
Pricing Analysis
Bundled service contracts that merge hardware, software, and operational support are displacing traditional equipment purchase models at DHS-sponsored installations and airport authorities. Price differentiation hinges on NIST FRVT certification tier and domestic assembly qualification under Buy American mandates. Pricing pressure stems from federal procurement consolidation around cleared facility primes, squeezing margins for non-cleared vendors. State and municipal buyers exhibit highest price sensitivity due to budget cycle constraints, while federal agencies prioritize certification compliance over unit cost.
Supply Chain Analysis
Reverse-logistics flows for biometric hardware remain underdeveloped, with limited refurbishment channels for decommissioned fingerprint and iris capture modules outside federal surplus programs. Sensor production concentrates in Taiwan, South Korea, and China, drawing from silicon wafer and specialized optical component inputs. Supply chain risk centers on single-source vulnerability for high-resolution imaging chipsets subject to export control restrictions. Distribution runs through systems integrators with cleared facility status and established DHS channel relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Federal demand is shifting toward multimodal systems with NIST-certified accuracy thresholds, elevating premium specifications over cost-minimization in procurement evaluations.
For Market Incumbents: Lock in cleared facility status and SAFETY Act qualification to defend against emerging semiconductor firms seeking direct federal channel access. Prioritize backward integration into domestic sensor assembly operations to satisfy DHS and DoD domestic content mandates. Channel control through prime contractor relationships remains the critical defensive lever against modality specialists with research-grade accuracy. For New Entrants and Emerging Players: Launch via cloud-based managed service offerings targeting state and municipal buyers constrained by capital expenditure limitations. Veterans Health Administration medical centers present the most penetrable segment, with patient identification systems integrating electronic health record infrastructure representing underserved demand. A go-to-market angle emphasizing FDA 510(k) clearance status accelerates access to Texas and California healthcare networks. For Investors and Strategic Acquirers: Valuations sit cheapest among semiconductor firms with imaging intellectual property positioned to capture margin from edge computing architectural shifts. Long-term viability favors vendors with NIST certification pipelines and domestic manufacturing footprints aligned to federal procurement consolidation. The signal to watch is DHS procurement timeline acceleration or deceleration as an inflection indicator for revenue recognition periods.| Strategic Initiative | Industry Significance |
|---|---|
| NIST FRVT Certification Investment | Federal eligibility gates vendor access to DHS and DoD identity credentialing programs. |
| Domestic Manufacturing Scale-Up | Buy American procurement preference privileges US-based assembly operations for border infrastructure. |
| Behavioral Biometric Platform Integration | Keystroke dynamics fusion with physiological modalities opens remote banking fraud prevention applications. |
| Healthcare IT Partnership Development | FDA-cleared patient identification systems integrate with Veterans Health Administration electronic health records. |
| Edge Computing Chipset Licensing | On-device template processing redistributes matching workloads toward sensor-integrated semiconductor architectures. |
Research Approach
Direct dialogue with federal procurement officers, cleared facility prime contractors, healthcare IT directors, and semiconductor supply chain managers grounded qualitative assessments in operational constraints. Secondary validation drew from NIST FRVT test reports, DHS procurement databases, FDA 510(k) filings, and SEC disclosures from imaging semiconductor firms. Bottom-up and top-down triangulation reconciled vendor shipment data with federal budget appropriations for identity credentialing programs.
Bottom-up modeling aggregated modality-specific deployment volumes across government, healthcare, banking, and retail end-use segments. Top-down verification cross-checked aggregate market scale against federal IT spending patterns and DHS infrastructure appropriations. Segmentation dimensions spanned technology type, application purpose, end-user category, and deployment architecture. CAGR derivation incorporated NIST evaluation cycle timelines, SAFETY Act qualification durations, and sensor technology refresh rates as industry-specific forecast inputs across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export control expansion or state privacy law fragmentation scenarios. Practitioners should monitor NIST FRVT protocol updates and DHS procurement timeline shifts for early signals of vendor eligibility and revenue recognition acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Mobile Biometrics Market
Biometrics & Identity Management
Fingerprint Biometrics Market
Biometrics & Identity Management
Global Authentication and Brand Protection Market
Biometrics & Identity Management
Automated Fingerprint Identification Systems (AFIS) Market
Biometrics & Identity Management
Flash Calling Authentication Market
Biometrics & Identity Management
Global Personal Identity Management Market
Biometrics & Identity Management
Mobile Devices User Authentication Services Market
Biometrics & Identity Management
Vein Recognition Biometrics Market
Biometrics & Identity Management
Biometrics Banking Market
Biometrics & Identity Management
Global Biometric Card Market
Biometrics & Identity Management
Global Mobile User Authentication Market
Biometrics & Identity Management
Identity Theft Protection Services Market
Biometrics & Identity Management
Biometric Point-Of-Sale Terminals Market
Biometrics & Identity Management
Europe Government and Security Biometrics Market
Biometrics & Identity Management
Palm Vein Biometrics Market
Biometrics & Identity Management
Consumer Biometrics Market