
 China Mobile Biometrics Market | 2026-2036
China Mobile Biometrics Market Size, Share, and Industry Trends Forecast 2026-2036
China Mobile Biometrics Market Insights
Modular sensor-software bundling is pivoting as the dominant procurement pattern in China's mobile biometrics sector. Goodix Technology Inc. leverages its Shenzhen-based semiconductor fabrication to dominate fingerprint module supply for domestic handset OEMs. IDEMIA anchors its position through deep partnerships with state-owned financial institutions requiring certified identity verification stacks. NEC Corporation competes by specializing in multimodal algorithms that combine facial and iris recognition for high-security government contracts.
China mobile biometrics encompasses portable authentication systems integrating physiological trait capture—minimum 500 dpi resolution for fingerprint sensors, infrared dot-projector arrays for 3D facial mapping, and near-infrared illumination for iris pattern extraction—with onboard template matching and encrypted transmission protocols. These systems enable real-time identity verification without dedicated fixed infrastructure. Fingerprint recognition leads in transaction volume due to mature sensor economics and integration into budget smartphones, while facial recognition captures expanding margin pools as payment platforms mandate liveness detection. Cloud-based deployment grows fastest among retail chains seeking centralized biometric template management across franchise networks, though hybrid architectures retain dominance in banking where data sovereignty requirements fragment storage between edge devices and private servers.
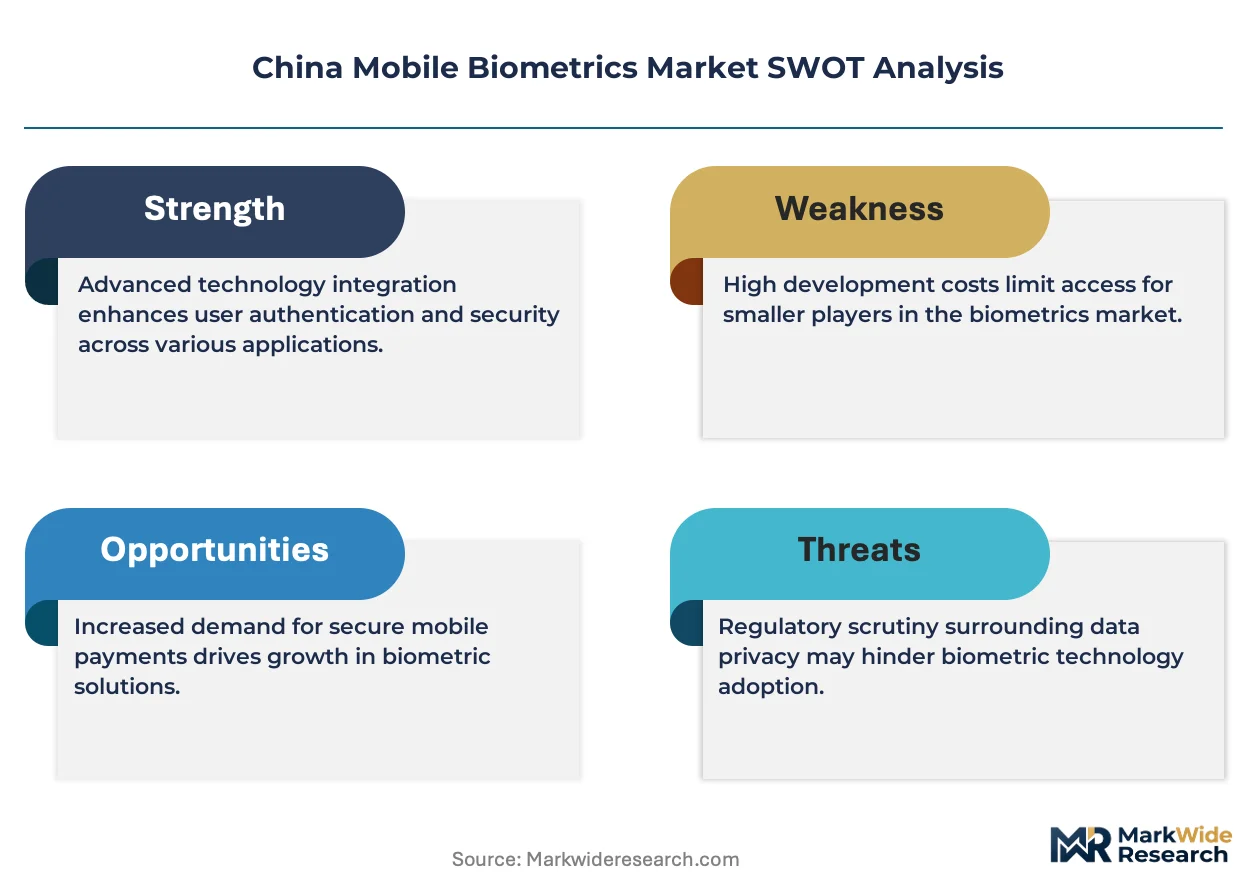
SAMR enforces national standards for biometric information collection under personal information protection rules, compelling vendors to obtain security certification before commercial deployment. The MIIT cybersecurity review framework mandates source-code audits and data-localization commitments for cloud-based biometric services processing Chinese citizen data. GB standards specify interoperability requirements for fingerprint templates across payment networks, reducing vendor lock-in but raising compliance costs for foreign suppliers. Stakeholders must monitor evolving certification timelines and assess whether edge-computing architectures can satisfy localization mandates without sacrificing real-time performance.
Market Dynamics
MIIT cybersecurity review framework is forcing biometric vendors to rearchitect data flows around edge-computing localization mandates. Shenzhen's hardware manufacturing corridor concentrates sensor supply, creating procurement bottlenecks for non-domestic OEMs seeking certified fingerprint modules.
Growth Catalysts
- State-owned bank mandates:Chinese financial institutions require certified identity verification stacks for mobile payment authentication, pulling multimodal algorithm demand from domestic vendors.
- GB standard interoperability:National fingerprint template specifications reduce vendor lock-in across payment networks, expanding addressable hardware replacement cycles.
- Shenzhen fabrication cluster:Proximity of semiconductor foundries to handset OEM assembly lines compresses module integration lead times below offshore alternatives.
Market Restraints
- Source-code audit requirements:MIIT cybersecurity review framework demands full disclosure of biometric processing algorithms, creating IP exposure risks for foreign suppliers.
- Near-infrared component concentration:Iris recognition module supply depends on limited domestic emitter diode manufacturers, constraining multimodal system scaling.
- Data-localization infrastructure costs:Cloud-based biometric services must deploy private server farms within Chinese borders, raising fixed cost thresholds for SaaS entrants.
Strategic Opportunities
- Franchise retail networks:Centralized biometric template management across dispersed store locations creates demand for hybrid edge-cloud architectures in tier-two cities.
- Liveness detection mandates:Payment platform requirements for 3D facial mapping with infrared dot-projector arrays open premium sensor upgrade cycles.
- Automotive cabin integration:Driver identity verification for personalized settings and payment authorization represents an emerging application beyond handsets.
Industry Challenges
- Certification timeline compression:SAMR security certification queues for biometric information collection systems extend commercial deployment schedules by six to nine months.
- Legacy template migration:Banks must reconcile existing fingerprint databases with new GB interoperability standards without disrupting active transaction flows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Mobile Biometrics Market |
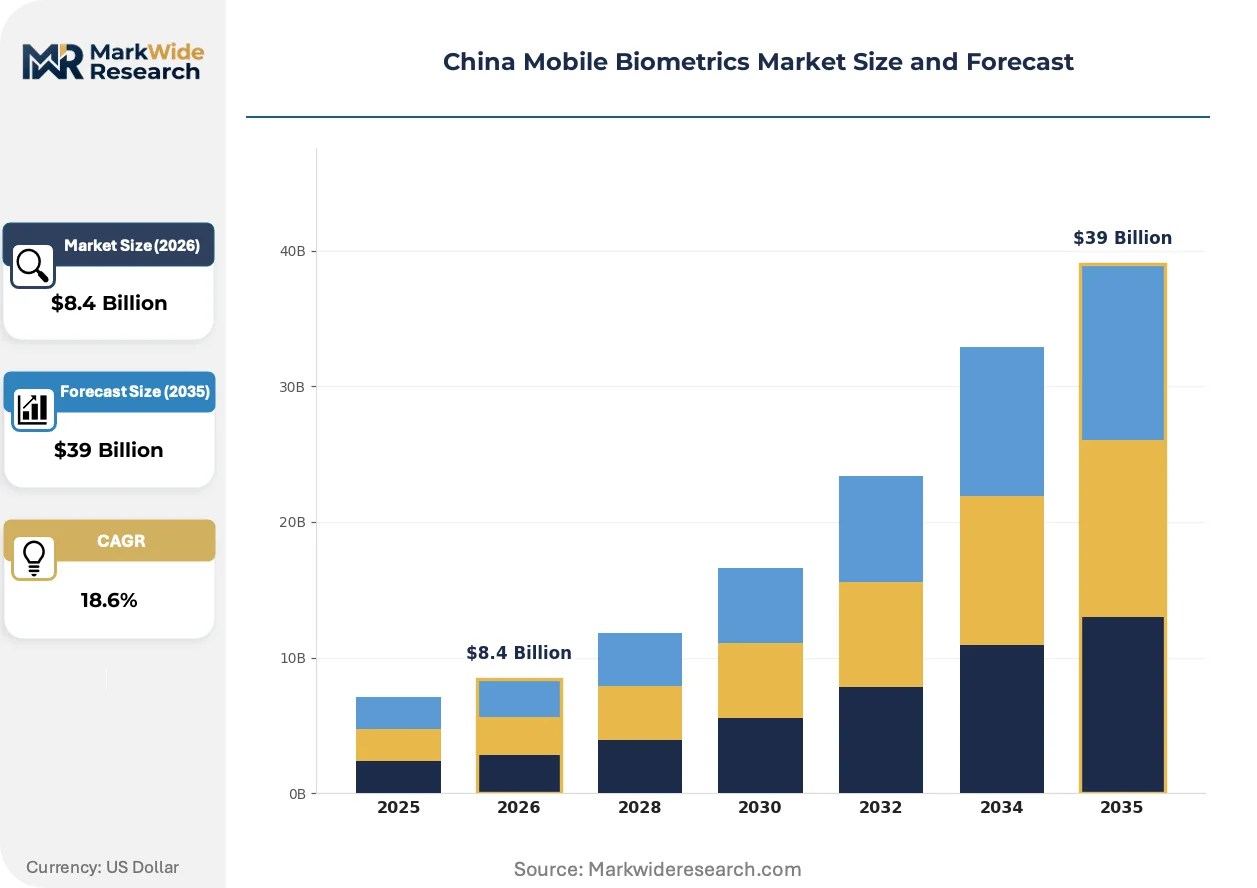
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $39 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fingerprint Recognition, Facial Recognition, Iris Recognition, Voice Recognition Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing End User: Banking, Retail, Healthcare, Government Application: Mobile Payments, Access Control, Identity Verification, Time Tracking |
| Companies Covered | NEC Corporation, Goodix Technology Inc., Aware Inc., HID Global Corporation, IDEMIA, Thales, Precise Biometrics AB, M2SYS Technology, Safran Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Mobile Biometrics Market Trends and Innovations
Hardware-software bundling contracts are restructuring vendor relationships around modular sensor procurement with algorithm licensing. This shift favors domestic semiconductor fabricators with captive template-matching IP over pure-play software licensors.
Ultrasonic fingerprint sensing is absorbing capacitive dominance in premium handset segments. Xiaomi and Oppo integrate Qualcomm's 3D Sonic sensors for under-display placement. The technology is absorbing margin pools previously captured by optical module suppliers as liveness detection requirements harden.
SAMR personal information protection rules are tightening consent mechanisms for biometric data collection. Retail chains must deploy granular opt-in interfaces before template capture. Food delivery platforms and ride-hailing apps face the steepest compliance reconfiguration as they process millions of daily facial verification events.
State-owned banks are consolidating vendor relationships around certified identity verification stacks. Procurement teams now require pre-integrated sensor-algorithm bundles with MIIT audit completion. Guangdong province leads this concentration as its regional banks pilot centralized biometric authentication for cross-branch account access.
China Mobile Biometrics Market Segmentation
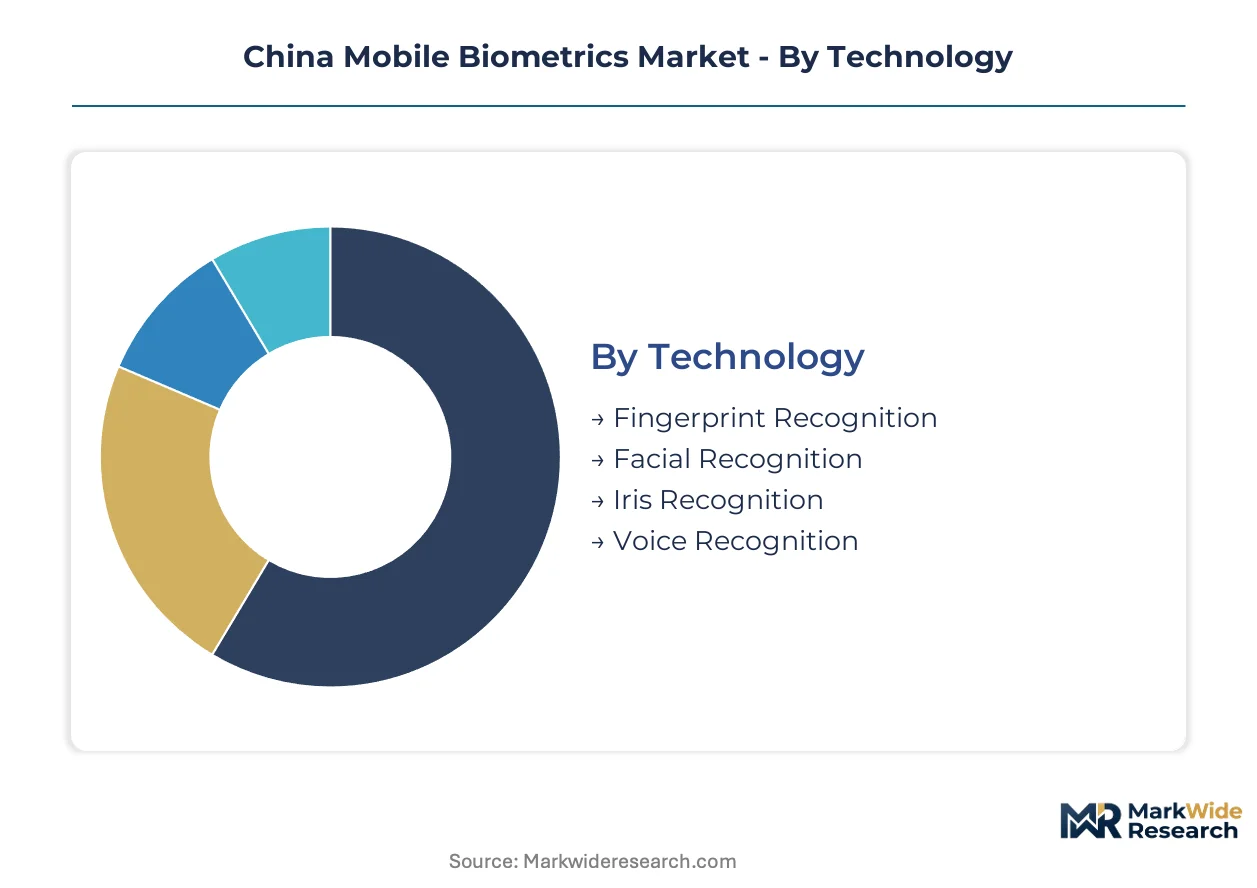
Technology choices in China's mobile biometrics sector cascade through deployment architectures and end-use procurement patterns. Each segmentation layer reveals distinct compliance thresholds and margin structures that vendors must navigate.
Technology:
Shenzhen's semiconductor fabrication corridor concentrates sensor supply for each modality, creating divergent cost curves and certification pathways.
- Fingerprint Recognition:Capacitive and ultrasonic sensors capture ridge patterns at 500+ dpi resolution for template generation. Banking networks in Guangdong province drive procurement volumes as state-owned institutions mandate certified modules for mobile payment authentication.
- Facial Recognition:Infrared dot-projector arrays construct 3D depth maps while liveness detection algorithms combat presentation attacks. Payment platforms in tier-one cities are mandating these premium sensor configurations, compressing upgrade cycles for handset OEMs.
- Iris Recognition:Near-infrared illumination reveals unique stromal patterns for high-security government contracts.
- Voice Recognition:Spectral analysis of vocal tract characteristics enables hands-free authentication in automotive cabin applications.
Today's leader: Fingerprint Recognition. Tomorrow's challenger: Facial Recognition.
Deployment:
Cost tier differentiation separates enterprise-grade infrastructure from mass-market handset integration.
- On-Premise:Dedicated servers within institutional firewalls process biometric matching without external data transmission. State-owned banks favor this architecture to satisfy SAMR data sovereignty requirements for core transaction systems.
- Cloud-Based:Centralized template storage enables franchise retail networks to synchronize authentication across dispersed locations. Retail chains in tier-two cities are adopting this model fastest as they scale biometric payment terminals.
- Hybrid:Edge devices perform initial matching while cloud systems handle template synchronization and audit logging.
- Edge Computing:Onboard processors execute complete authentication pipelines without network dependency. Automotive OEMs exploring driver identity verification are piloting this architecture for cabin-integrated systems.
Hybrid architectures currently dominate banking procurement. Cloud-Based deployment is climbing the fastest among retail franchises.
End User:
Application maturity varies sharply across sectors, with financial services setting the compliance baseline that other industries must follow.
- Banking:Mobile payment authentication requires MIIT-certified identity verification stacks with multimodal fallback options. Guangdong regional banks are consolidating vendor relationships around pre-integrated sensor-algorithm bundles.
- Retail:Franchise networks deploy biometric terminals for customer loyalty linkage and payment authorization. Food delivery platforms face steep SAMR consent mechanism reconfiguration as they process millions of daily facial verification events.
- Healthcare:Patient identity verification for mobile health record access demands enhanced encryption protocols.
- Government:High-security contracts for border control and civil ID systems specify iris and facial multimodal combinations.
Banking commands premium pricing through certification requirements. Retail is gaining share fastest as franchise networks expand biometric payment coverage.
Application:
Volume concentration in consumer-facing transactions creates economies of scale that subsidize specialized enterprise deployments.
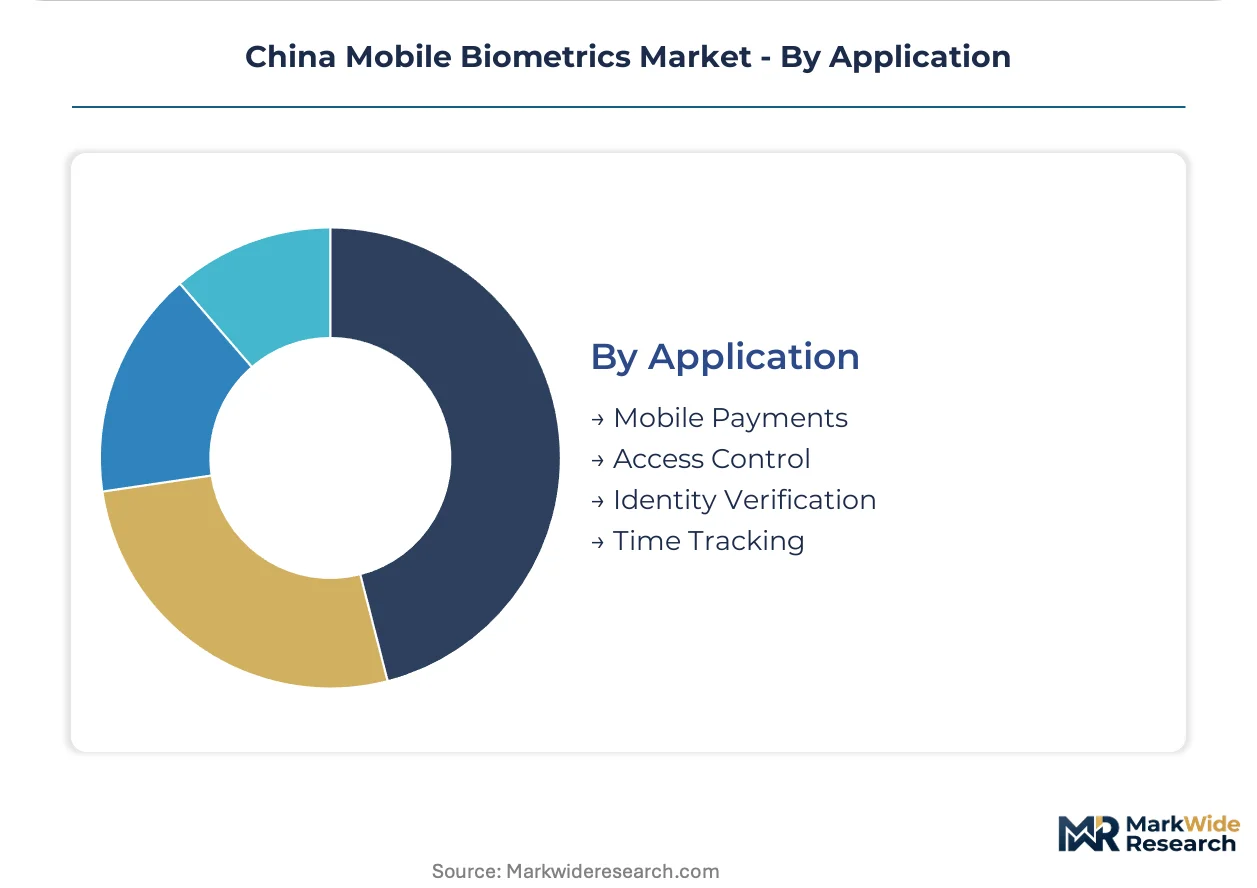
- Mobile Payments:Real-time authentication for transaction authorization integrates fingerprint or facial matching with tokenized credential exchange. Chinese banks are expanding fingerprint-based mobile payment adoption through certified module mandates.
- Access Control:Enterprise building entry and device unlock scenarios prioritize speed over liveness detection rigor.
- Identity Verification:Account onboarding and KYC processes require higher assurance levels with audit trail documentation.
- Time Tracking:Workforce management applications in manufacturing facilities use biometric clock-in to prevent buddy punching.
Mobile Payments anchors current revenue. Identity Verification shows steepest expansion trajectory as remote onboarding requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's mobile biometrics industry traces its commercial scale-up to Shenzhen's electronics manufacturing boom of the 2000s, when semiconductor foundries began integrating fingerprint sensors into domestic handset production. The sector now distributes capability across coastal manufacturing belts and inland technology corridors.
Guangdong Province
Shenzhen's semiconductor fabrication cluster supplies certified fingerprint modules to domestic handset OEMs. SAMR enforces personal information protection rules that mandate security certification before commercial biometric deployment. State-owned banks in Guangzhou pilot centralized authentication for cross-branch account access.
Beijing-Tianjin-Hebei
MIIT cybersecurity review framework mandates source-code audits for cloud-based biometric services processing citizen data. Government contracts for high-security identity verification concentrate in the capital's technology procurement corridors. Edge-computing architectures are being tested to satisfy data-localization mandates.
Jiangsu Province
Nanjing and Suzhou host R&D centers developing multimodal algorithms combining facial and iris recognition. The province's banking sector requires certified identity verification stacks for mobile payment authentication. Hardware-software bundling contracts favor domestic vendors with captive template-matching IP.
Zhejiang Province
Hangzhou's payment platforms mandate liveness detection requirements for 3D facial mapping with infrared dot-projector arrays. Food delivery platforms face SAMR consent mechanism reconfiguration for millions of daily facial verification events. Retail franchise networks adopt hybrid edge-cloud architectures for biometric payment terminals.
Sichuan-Chongqing
Western China's automotive OEMs explore driver identity verification for cabin-integrated biometric systems. Local manufacturers pilot edge-computing architectures that execute complete authentication pipelines without network dependency. Tier-two city retail chains drive demand for centralized biometric template management.
China Mobile Biometrics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-tier and sensor-modality dimensions. The market structures around three tiers: domestic semiconductor fabricators with captive algorithm IP, multinational specialists in multimodal systems, and modular software licensors. Competitive moves center on hardware-software bundling contracts and MIIT audit completion to secure state-owned bank procurement.
Among Japan-based technology conglomerates, NEC Corporation exemplifies the multimodal specialist archetype combining facial and iris recognition. Shenzhen-based Goodix Technology Inc. represents domestic semiconductor fabricators leveraging proximity to handset OEM assembly lines. IDEMIA anchors the multinational tier through positioning within certified identity verification stacks for financial institutions.
| Leading Market Players |
|---|
| NEC Corporation |
| Goodix Technology Inc. |
| Aware Inc. |
| HID Global Corporation |
| IDEMIA |
| Thales |
| Precise Biometrics AB |
| M2SYS Technology |
| Safran Inc |
| Others |
Pricing and Supply Chain Analysis
Captive semiconductor fabrication in Shenzhen anchors both supply security and pricing power for domestic sensor vendors serving China's mobile biometrics sector. Goodix Technology and comparable fabricators leverage in-house foundry capacity to undercut offshore module suppliers while capturing margin pools that pure-play algorithm licensors cannot access. MIIT cybersecurity review requirements compound this advantage by forcing foreign competitors into costly data-localization infrastructure that domestic players avoid.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and liveness detection capability. Premium tiers command substantial markups for MIIT-audited sensor-algorithm bundles with multimodal fallback, while economy tiers face cost compression from Shenzhen's fabrication cluster oversupply. State-owned banks show lowest price sensitivity due to compliance mandates, whereas tier-two retail franchises drive hardest bargain on per-terminal pricing.
Supply Chain Analysis
Domestic-content mandates under MIIT cybersecurity review framework are reshaping sourcing patterns toward certified local suppliers. Sensor module supply concentrates in China, Taiwan, and South Korea, with near-infrared emitter diodes drawing from limited Japanese and Korean component specialists. Single-source vulnerability in iris recognition illumination components threatens multimodal system scaling. Distribution runs through handset OEM direct procurement and state-owned bank certified vendor lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's mobile biometrics market compounds steadily as state-mandated authentication infrastructure penetrates tier-two cities and automotive applications. Regulatory certification requirements create durable competitive moats around incumbent positions.
For Market Incumbents: Cement dominance by completing MIIT source-code audits ahead of foreign competitors and securing exclusive sensor-algorithm bundling contracts with Guangdong regional banks. Threat of emerging domestic algorithm specialists demands accelerated R&D investment in ultrasonic fingerprint liveness detection. Backward integration into near-infrared emitter diode supply reduces exposure to Japanese component bottlenecks. For New Entrants and Emerging Players: Tier-two city retail franchises represent the most penetrable buyer archetype, as these operators lack technical procurement sophistication of state-owned banks and prioritize cost over multimodal redundancy. White-space exists in automotive cabin integration for driver identity verification, where edge-computing architectures bypass cloud-localization mandates. Go-to-market through Tier 1 automotive electronics suppliers accelerates pilot deployment without direct MIIT certification burden. For Investors and Strategic Acquirers: Roll-up economics work for domestic semiconductor fabricators with captive algorithm IP because certification timelines and MIIT audit completion create artificial scarcity of investable assets. Five-to-ten year viability rests on continued state-mandated biometric authentication expansion beyond financial services into healthcare and government sectors. Watch SAMR personal information protection rule enforcement intensity as inflection signal for compliance-cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Security Certification Completion | Unlocks procurement eligibility for state-owned bank identity verification stacks. |
| Ultrasonic Sensor Module Launch | Captures premium handset upgrade cycles as liveness detection requirements harden. |
| Edge-Computing Architecture Deployment | Satisfies data-localization mandates without sacrificing real-time authentication performance. |
| Automotive Tier 1 Partnership | Secures pilot positioning for driver identity verification in cabin-integrated systems. |
| Near-Infrared Component Backward Integration | Reduces supply risk for iris recognition modules in high-security government contracts. |
Research Methodology
Coverage spans China's coastal manufacturing belts and inland technology corridors, with primary inputs from each. Semiconductor fabrication executives, state-owned bank procurement directors, MIIT certification specialists, and automotive Tier 1 electronics engineers provided structured interviews. Secondary validation drew from SAMR regulatory filings, MIIT cybersecurity framework documentation, GB standard interoperability specifications, and handset OEM supply chain disclosures. Bottom-up module shipment analysis triangulated against top-down payment transaction authentication volume estimates.
Rate-of-change decomposition structured the analytical framework across the projection horizon. Segmentation dimensions modeled include biometric modality, deployment architecture, end-use sector, and application type, with regional regulatory cluster as an additional cross-cutting variable. CAGRs derived from installed base growth curves, replacement cycle compression, and penetration rate assumptions for emerging automotive and healthcare applications. Specific inputs included SAMR certification queue timelines and GB standard implementation schedules.
Underlying measurement precision varies by segment; banking and government procurement carry tighter precision than emerging automotive applications. Forecasts reflect assumptions around MIIT audit completion rates, SAMR enforcement intensity, and near-infrared component supply expansion. A small set of regulatory trigger events warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Global Phone Based Authentication Solution Market
Biometrics & Identity Management
Fingerprint Biometrics Market
Biometrics & Identity Management
Signature Verification Market
Biometrics & Identity Management
GCC Biometrics Market
Biometrics & Identity Management
E-Government Identity Management Market
Biometrics & Identity Management
Global Behavioral Biometrics Market
Biometrics & Identity Management
Middle East and Africa Biometrics in Government Market
Biometrics & Identity Management
Biometrics Banking Market
Biometrics & Identity Management
Biometric Point-Of-Sale Terminals Market
Biometrics & Identity Management
Healthcare Biometrics Market
Biometrics & Identity Management
Europe Enterprise Biometrics Market
Biometrics & Identity Management
FIDO Authentication Market
Biometrics & Identity Management
Authentication Solution Market
Biometrics & Identity Management
Physical Identity and Access Management (PIAM) Market
Biometrics & Identity Management
Biometric Scan Software Market
Biometrics & Identity Management
Military Biometrics Market