
 Mass Transit Security Market | 2026-2036
Mass Transit Security Market Size, Share, and Industry Trends Forecast 2026-2036
Mass Transit Security Market Intelligence
China's metro expansion is tilting procurement volumes toward integrated platform-screening systems. Siemens sustains engineering depth in rail signaling security across European corridors. Honeywell dominates building-management integration for transit hubs in North America. Smiths Detection specializes in chemical trace detection for high-throughput station environments.
Mass transit security encompasses layered protection of passenger rail, bus, and multimodal infrastructure through video surveillance, access control, explosives screening, and cyber-physical monitoring. Systems typically operate on redundant networks with sub-100-millisecond latency requirements for real-time threat response. Surveillance systems anchor capital spending as cities retrofit analog camera networks with AI-enabled analytics platforms. Incident management software represents the fastest-expanding segment as operators unify dispatch, communication, and forensic review into single-pane workflows. Cloud-based deployment lags in this sector due to stringent data sovereignty requirements for critical infrastructure.
The U.S. Transportation Security Administration mandates baseline security assessments for surface transit agencies receiving federal grants. The EU's NIS2 Directive extends cybersecurity reporting obligations to metro operators and rail infrastructure managers. India's CEA guidelines enforce redundant power and communication standards for metro rail operations. Stakeholders must weigh sovereign data requirements against the operational flexibility of hybrid architectures as procurement cycles lengthen.
Market Dynamics
Urban rail operators are consolidating fragmented surveillance estates into unified AI-native platforms, compressing procurement cycles from multi-year capital projects to modular software subscriptions. This architectural shift is redrawing vendor relationships and technical staffing models across metropolitan networks.
Growth Catalysts
- EU NIS2 Directive:Cybersecurity reporting mandates for metro operators and rail infrastructure managers are accelerating investment in unified threat detection platforms across European corridors.
- India's metro construction pipeline:Hundreds of kilometers of new track deployment in cities including Delhi, Mumbai, and Bangalore are generating concentrated demand for integrated screening and access control systems.
- AI-enabled video analytics:Behavioral recognition and anomaly detection algorithms are replacing rule-based surveillance, enabling real-time incident response in high-throughput station environments.
Market Restraints
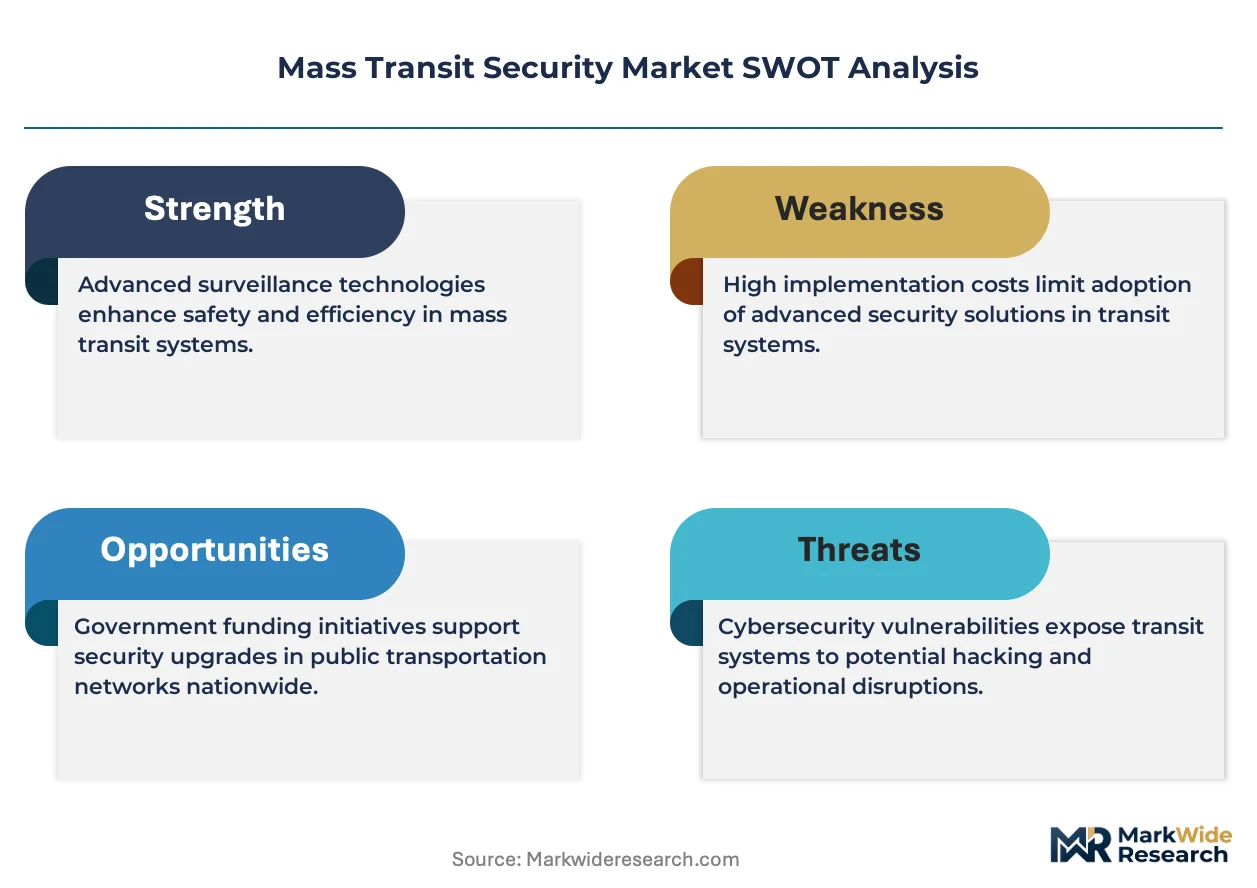
- Semiconductor supply concentration:Specialized image processing chips for thermal and multispectral cameras remain concentrated among Taiwanese and South Korean foundries, creating procurement vulnerability.
- Data sovereignty requirements:Critical infrastructure classifications in Germany, France, and India mandate on-premise storage, blocking cloud-native architectures and inflating total cost of ownership.
- Legacy analog infrastructure:Decades of sunk investment in coaxial cable networks and proprietary recording formats impose steep retrofit costs for system-wide analytics deployment.
Strategic Opportunities
- Underpenetrated African urban rail:Cairo, Lagos, and Addis Ababa are initiating metro expansions with greenfield security specifications, bypassing legacy integration constraints.
- Convergence of physical and cyber monitoring:Integrated security operations centers combining SCADA anomaly detection with perimeter surveillance are emerging as differentiated procurement bundles.
- Outcome-based maintenance contracts:Performance-guaranteed service agreements for screening equipment uptime are displacing traditional break-fix arrangements in North American transit authorities.
Industry Challenges
- Multi-vendor system integration:Interoperability gaps between access control, video management, and explosives detection platforms from different suppliers complicate unified command center deployment.
- Cyber-physical certification timelines:Dual safety and security approvals for rail signaling modifications under EU and Indian frameworks extend product qualification cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mass Transit Security Market |
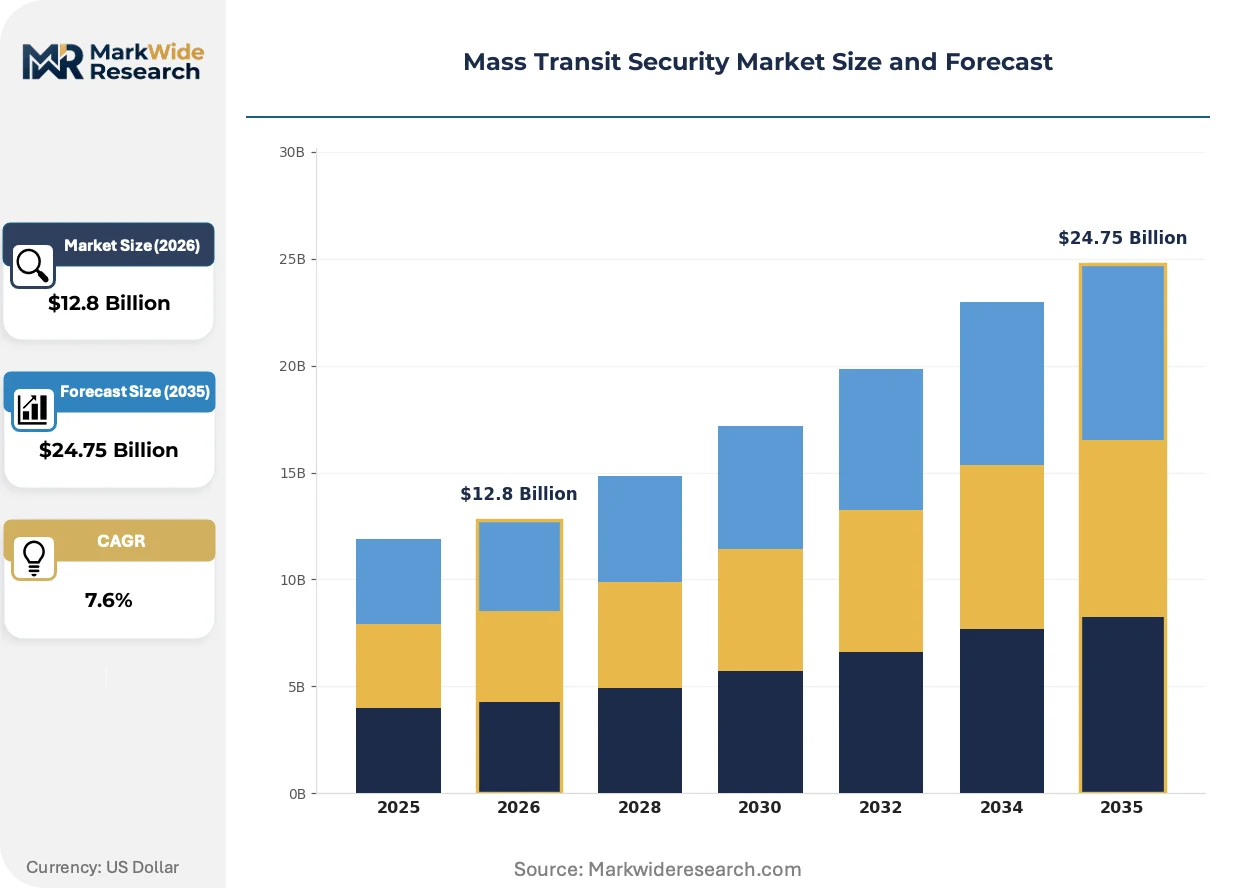
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $24.75 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Surveillance Systems, Access Control, Incident Management, Bomb Detection Application: Subways, Buses, Trains, Airports End User: Government Agencies, Transportation Authorities, Security Service Providers, Private Operators Deployment: On-premises, Cloud-based, Hybrid, Mobile |
| Companies Covered | Bosch Security Systems, Axis Communications, Siemens, Honeywell, Thales Group, Smiths Detection, Genetec, Panasonic Corporation, Cisco Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mass Transit Security Market Strategic Shifts & Innovations
Edge computing architectures are redistributing processing load from centralized data centers to station-level nodes, enabling sub-100-millisecond response times for automated threat response. This infrastructure evolution is compressing the technical stack and reshaping vendor competitive boundaries.
Multispectral imaging arrays combining visible, thermal, and near-infrared sensors are rendering obsolete single-spectrum camera deployments in platform and tunnel monitoring applications. Transit operators in Singapore and Dubai are adopting these fused-sensor platforms for 24-hour perimeter coverage without artificial lighting infrastructure. The technology is compressing equipment counts and simplifying cabling topologies across new-build metro lines.
EU AI Act risk classifications are imposing documentation and human-oversight requirements on biometric identification systems deployed in public transit environments. Rail operators in France and Germany are restructuring procurement specifications to exclude prohibited AI practices and ensure conformity assessment traceability. The regulation is accelerating demand for explainable analytics platforms that provide audit trails for automated alerting decisions.
Consolidated security-as-a-service models are displacing capital-intensive equipment ownership among mid-sized transit agencies. Municipal operators in Spain and Italy are subscribing to managed detection and response packages that bundle hardware, software, and analyst staffing. This consumption shift is visible most acutely in regions with constrained municipal borrowing capacity and shorter political budget cycles.
Mass Transit Security Market Segmentation
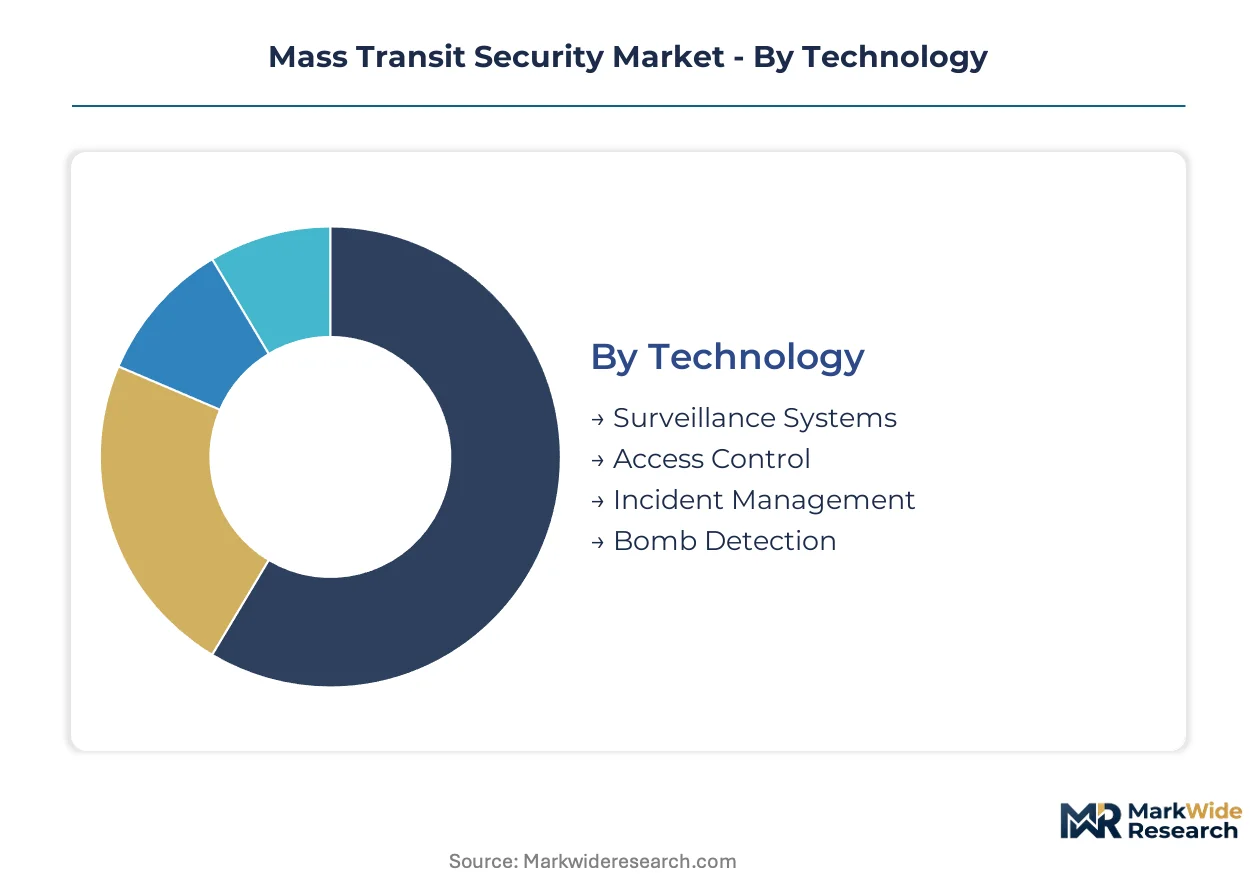
Mass transit security procurement cycles vary dramatically by technology layer, with software platforms refreshing every 2-3 years while physical infrastructure endures 10-15 year depreciation schedules. Understanding these temporal patterns helps vendors align R&D pipelines with actual replacement demand rather than assumed upgrade cycles.
Technology:
Surveillance systems turn over fastest as AI-native platforms displace legacy analog estates, while bomb detection hardware operates on decade-long certification cycles that resist rapid substitution.
- Surveillance Systems:AI-enabled video analytics platforms process behavioral recognition and anomaly detection at station-level edge nodes. Delhi Metro and Singapore's Land Transport Authority are consolidating fragmented camera estates into unified neural-network architectures with sub-100-millisecond latency. Procurement is compressing from capital projects to modular software subscriptions.
- Incident Management:Unified dispatch platforms integrate communication, forensic review, and automated alerting into single-pane workflows. European operators under NIS2 Directive mandates are accelerating deployment of these systems to satisfy unified threat detection reporting requirements. This segment is expanding most quickly as operators seek operational consolidation.
- Access Control:Biometric and credential-based entry systems for staff zones and passenger flow management.
- Bomb Detection:Chemical trace and explosives screening equipment with extended certification timelines under EU and Indian safety frameworks.
Surveillance systems anchor the volume base while incident management gains share at the steepest rate.
Application:
Subway environments concentrate security spending due to enclosed platforms and high passenger density, whereas bus networks spread equivalent protection across dispersed stop infrastructure with lower per-node investment.
- Subways:Enclosed station environments with platform screen doors, tunnel networks, and centralized command centers demand layered physical-cyber protection. China's metro expansion is driving integrated platform-screening procurement at scale. Underground infrastructure creates unique perimeter challenges requiring 24-hour multispectral monitoring without artificial lighting.
- Trains:Intercity and commuter rail corridors with distributed trackside assets and signaling infrastructure. The EU's revised Rail Safety Directive tightens cybersecurity mandates for signaling systems across European corridors, accelerating SCADA anomaly detection investment.
- Buses:Distributed stop networks and vehicle-mounted surveillance with lower capital intensity per protected node.
- Airports:Multimodal transit connections requiring integration with aviation security protocols and passenger screening standards.
Subway deployments command the highest per-node security investment while train corridors show the strongest regulatory tailwind.
End User:
Government agencies maintain longest procurement cycles with multi-year capital appropriations, while private operators exhibit greater flexibility in adopting subscription-based security-as-a-service models.
- Transportation Authorities:Municipal and regional operators managing integrated multimodal networks with consolidated security operations centers. Spain and Italy's municipal agencies are subscribing to managed detection packages bundling hardware, software, and analyst staffing due to constrained borrowing capacity.
- Security Service Providers:Third-party contractors delivering outsourced monitoring, maintenance, and incident response. Performance-guaranteed uptime contracts are displacing break-fix arrangements in North American transit authorities.
- Government Agencies:National regulators and federal grant recipients with extended procurement timelines and stringent compliance requirements.
- Private Operators:Concession-holders and outsourced facility managers with operational flexibility in contracting models.
Transportation authorities concentrate absolute spending while security service providers capture expanding share through outcome-based contracting.
Deployment:
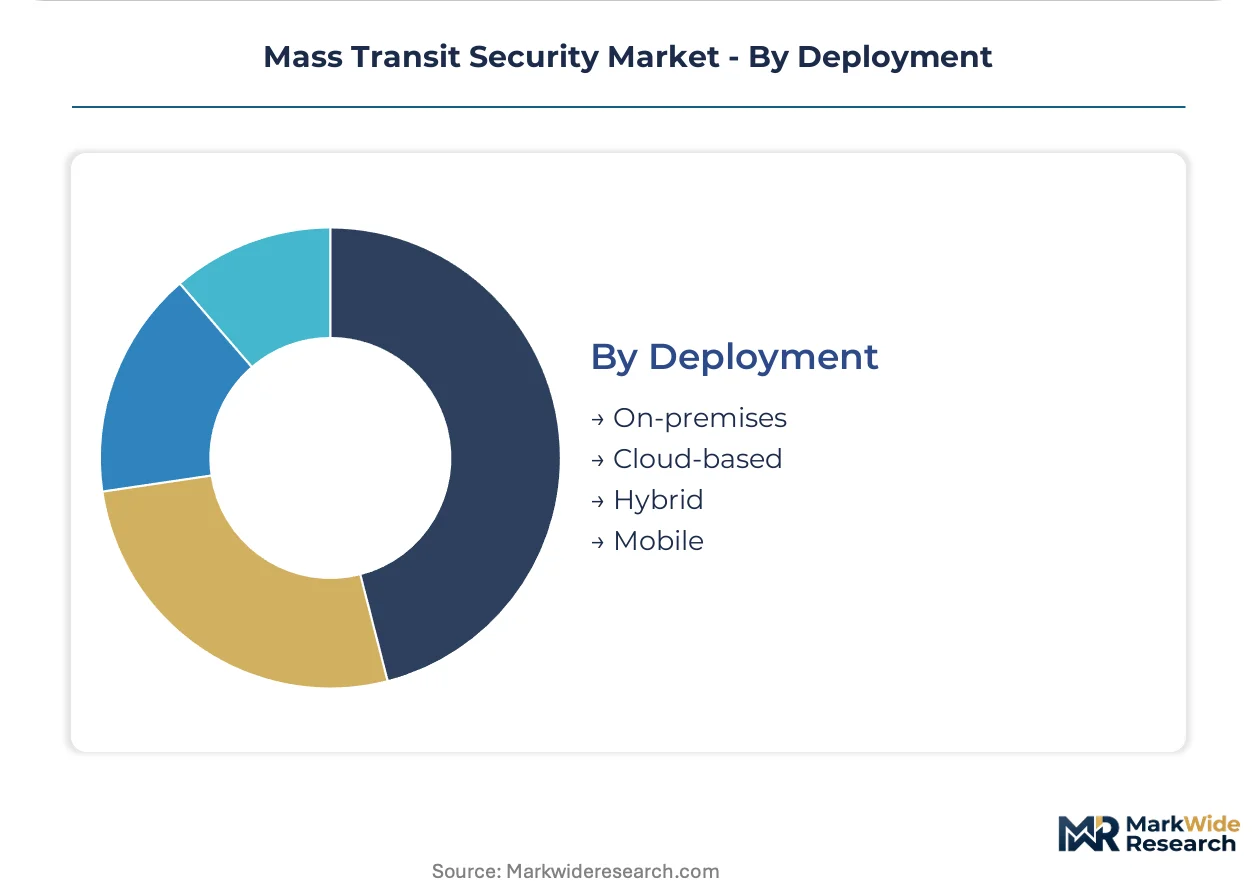
On-premise architectures dominate where data sovereignty requirements block cloud migration, while hybrid models emerge as a compliance-compatible compromise for analytics-intensive workloads.
- On-premises:Critical infrastructure classifications in Germany, France, and India mandate local storage for surveillance and signaling data. Redundant power and communication standards under India's CEA guidelines reinforce on-premise hardware requirements. Total cost of ownership runs higher due to dedicated facility and staffing overhead.
- Hybrid:Edge-computing nodes at station level combined with centralized data aggregation for non-sensitive analytics. This architecture satisfies sovereign data requirements while enabling cloud-based software updates and AI model training.
- Cloud-based:Software and storage delivered remotely, currently limited by critical infrastructure data localization mandates.
- Mobile:Vehicle-mounted and portable security assets for flexible deployment across distributed transit networks.
On-premises deployment retains dominant installed base while hybrid architectures climb fastest as operators seek compliance-compatible modernization paths.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Transportation Security Administration mandates baseline security assessments for surface transit agencies receiving federal grants. India's Central Electricity Authority enforces redundant power and communication standards for metro rail operations. Germany's Federal Office for Information Security certifies rail signaling cybersecurity under tightened EU frameworks.
United States
The Transportation Security Administration's surface transit grant programs drive procurement of explosives screening and video analytics platforms. Federal transit law requires security assessments for agencies receiving capital investment grants. New York's Metropolitan Transportation Authority and Washington Metro anchor demand for integrated command center deployments across legacy rail networks.
Germany
The Federal Office for Information Security certifies SCADA anomaly detection systems under the EU's revised Rail Safety Directive. NIS2 reporting mandates accelerate unified threat detection investment across Deutsche Bahn corridors. Berlin and Munich metro operators consolidate fragmented surveillance estates into AI-native platforms with sovereign data compliance.
India
The Central Electricity Authority mandates redundant power and communication standards for metro rail operations under statutory guidelines. Metro construction pipelines in Delhi, Mumbai, and Bangalore generate concentrated demand for integrated screening and access control systems. The Delhi Metro Rail Corporation leads deployment of platform-screening systems across hundreds of kilometers of new track.
China
The Ministry of Transport oversees cybersecurity classification for critical rail infrastructure under national security frameworks. Metro expansion in Shanghai, Beijing, and Shenzhen tilts procurement toward integrated platform-screening systems. State-owned rail operators mandate domestic supplier qualification for signaling security components.
United Arab Emirates
The National Electronic Security Authority sets critical infrastructure protection standards for transport operators. Dubai's Roads and Transport Authority deploys multispectral imaging arrays for 24-hour perimeter coverage without artificial lighting. Abu Dhabi's Department of Municipalities and Transport adopts managed security service models for metro and bus networks.
Mass Transit Security Market Key Industry Players
Capability concentration sits with engineering-intensive specialists; scale advantage sits with diversified industrial conglomerates. The market exhibits tiered structure with signaling security, surveillance hardware, and detection equipment each dominated by distinct player sets. Three archetypes prevail: integrated platform providers, component specialists, and security-as-a-service operators. Consolidation pressure manifests through strategic partnerships for cyber-physical system integration and geographic expansion into greenfield metro markets.
Among diversified industrial conglomerates, Siemens and Honeywell occupy positions spanning rail signaling and building management integration. Bosch Security Systems and Axis Communications exemplify the surveillance hardware specialist tier with deep camera and analytics portfolios. Smiths Detection anchors the explosives and chemical trace detection segment with certification-heavy product cycles.
| Leading Market Players |
|---|
| Bosch Security Systems |
| Axis Communications |
| Siemens |
| Honeywell |
| Thales Group |
| Smiths Detection |
| Genetec |
| Panasonic Corporation |
| Cisco Systems |
| Others |
Cost & Logistics Intelligence
Taipei and Hsinchu anchor specialized image processing capacity for thermal and multispectral camera sensors, concentrating procurement leverage among Taiwanese foundries and compressing margin flexibility for downstream security system integrators facing sovereign data localization mandates.
Pricing Analysis
Price spreads between European and Asian procurement markets widen where NIS2 compliance bundling inflates total cost of ownership. Three-tier pricing structure across premium certified, standard integrated, and economy unbundled levels separates Siemens and Thales signaling platforms from regional competitors. Cost compression in mid-tier video analytics stems from modular software subscriptions displacing capital-heavy hardware refresh cycles. Municipal transportation authorities in Southern Europe exhibit highest price sensitivity due to constrained borrowing capacity, while Gulf state operators prioritize performance guarantees over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates component sourcing strategies for edge computing nodes and neural network accelerators. Manufacturing concentration rests on Taiwan, South Korea, and mainland China for CMOS sensors, thermal imaging arrays, and specialized AI inference chips. German and French system integrators draw from these hubs while maintaining redundant inventory buffers against logistics chokepoints at Rotterdam and Singapore transshipment nodes. Distribution runs through authorized channel partners with certification maintenance obligations rather than direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mass transit security hardware commoditizes faster than service layers, positioning managed detection and response subscriptions as the fastest-expanding recurring revenue stream outpacing equipment sales across European municipal operators.
For Market Incumbents: Entrench platform-screening system dominance through backward integration into edge computing hardware production, insulating margin structures against semiconductor supply volatility. Deepen certification investment under EU AI Act conformity assessment pathways to extend product qualification timelines that deter emerging competitors. Consolidate fragmented surveillance estates through unified AI-native architectures that compress customer switching flexibility. For New Entrants and Emerging Players: Establish a beachhead in African greenfield metro markets where Cairo, Lagos, and Addis Ababa bypass legacy analog integration constraints entirely. Target security-as-a-service bundling for mid-sized transit agencies in Spain and Italy facing municipal borrowing limitations. Deploy hybrid cloud-edge architectures that satisfy Indian CEA data localization requirements while enabling SaaS delivery models. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component specialists with deep certification moats over diversified industrial conglomerates exposed to signaling commoditization. Long-term viability hinges on cyber-physical convergence capabilities spanning SCADA anomaly detection and perimeter surveillance integration. Monitor EU AI Act enforcement intensity as the inflection signal for biometric identification system demand trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies dispatch, communication, and forensic review into single-pane workflows for NIS2 compliance. |
| Backward Integration | Captures edge computing node production to reduce dependency on Taiwanese foundry allocation cycles. |
| Geographic Expansion | Targets African greenfield metro specifications in Cairo and Lagos without legacy retrofit burdens. |
| Strategic Partnership | Combines SCADA anomaly detection with perimeter surveillance for differentiated procurement bundles. |
| Acquisition of Specialist Firm | Absorbs chemical trace detection expertise to complete layered screening portfolios for high-throughput stations. |
Research Approach
The analysis maps surveillance systems, incident management platforms, access control infrastructure, and explosives detection equipment, each validated through transit authority procurement directors, rail signaling engineers, security operations center managers, and municipal finance officers. Primary fieldwork combined structured interviews with secondary validation against EU NIS2 implementation guidance, Indian CEA statutory standards, U.S. TSA surface transit grant documentation, and customs records for thermal imaging component trade flows. Bottom-up equipment shipment tracking and top-down infrastructure investment pipelines were triangulated to anchor volume estimates.
Assumptions held fixed include prevailing data sovereignty classifications in Germany, France, and India, while regulatory enforcement intensity and semiconductor supply normalization were varied across sensitivity scenarios. Segmentation dimensions modeled encompass technology layer, application environment, end-user contracting model, and deployment architecture. CAGRs were derived from replacement cycle analysis and greenfield construction pipelines rather than extrapolated trend fitting. Industry-specific inputs included metro rail kilometer addition schedules and AI-enabled video analytics refresh rates.
Stress conditions across foundry capacity allocation, EU AI Act risk classification expansion, and sovereign data localization mandate tightening were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about procurement cycle compression and subscription model penetration trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Global Contraband Detector Market
Security and Surveillance
Resale Authentication Services Market
Security and Surveillance
Sirens Market
Security and Surveillance
Global Container Security Market
Security and Surveillance
Full Body Scanner Market
Security and Surveillance
Threat Detection Systems Market
Security and Surveillance
Security Product Integration Services Market
Security and Surveillance
Security Holograms Market
Security and Surveillance
Global Security Policy Management Market
Security and Surveillance
Explosive Vapour Detector Market
Security and Surveillance
Smart Home Security Market
Security and Surveillance
Europe Security Services Market
Security and Surveillance
Home Security Market
Security and Surveillance
Proactive Security Market
Security and Surveillance
Airport Security Market
Security and Surveillance
Europe Urban Security Screening Market