
 Laxatives Market | 2026-2036
Laxatives Market Size, Share, and Industry Trends Forecast 2026-2036
Laxatives Market Outlook
India is tilting toward bulk-forming laxative production as contract manufacturing capacity expands across Gujarat and Hyderabad clusters. Johnson & Johnson leverages its consumer health division to sustain shelf dominance in North American pharmacy chains. Bayer AG anchors European market presence through its Bepanthen gastrointestinal portfolio, while Takeda Pharmaceutical Company Limited competes in prescription-strength osmotic segments across Asia-Pacific markets.
Laxatives comprise pharmacological agents that promote bowel evacuation through osmotic water retention, intestinal nerve stimulation, or stool softening via surfactant action on fecal matter, with primary commercial purpose spanning constipation relief, pre-procedural bowel preparation, and opioid-induced bowel dysfunction management. Osmotic variants lead value generation due to polyethylene glycol formulations commanding premium positioning in hospital procurement, while bulk-forming fiber types capture expanding self-directed consumer channels through powder and tablet formats. E-commerce distribution is accelerating fastest as direct-to-patient platforms bypass traditional pharmacy intermediaries.
FDA OTC monograph reform and EMA pharmacovigilance frameworks govern active ingredient concentrations and labeling claims, with FDA's ongoing reclassification of phenolphthalein-containing stimulants demonstrating how safety-driven withdrawals reshape product portfolios. India's CDSCO imposes bioequivalence requirements on bulk-forming generics entering institutional tenders. Stakeholders must monitor evolving monograph statuses and channel migration patterns to align formulation investments with shifting regulatory and purchasing pathways.
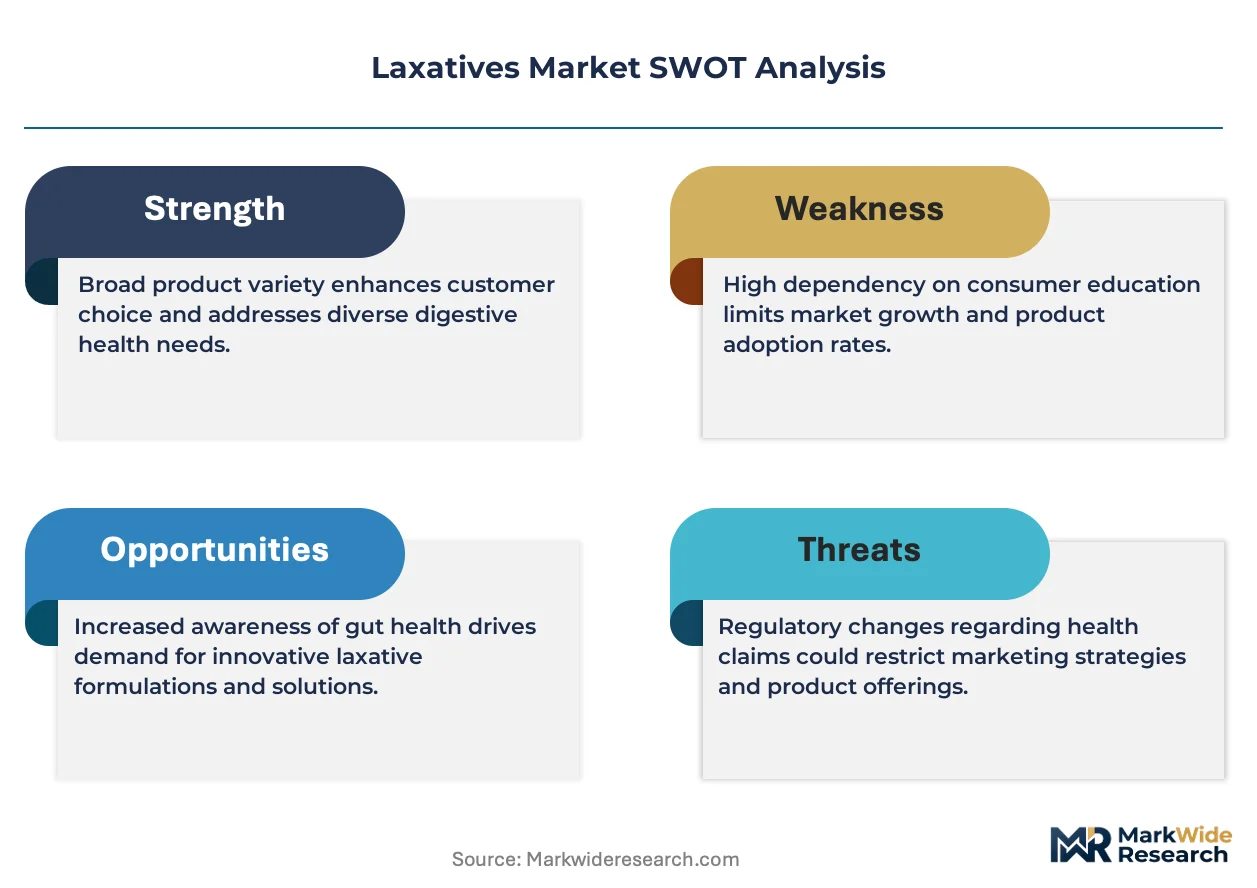
Market Dynamics
FDA OTC monograph reform is compressing product lifecycles for stimulant laxatives while polyethylene glycol formulations capture institutional procurement preference through superior safety profiles in geriatric populations.
Growth Catalysts
- Aging Demographics:United States census projections show expanding 65-plus populations driving sustained volume in self-medication channels. Geriatric care facilities now represent the fastest-expanding end-use setting for laxative procurement.
- CDSCO Bioequivalence Standards:India's tightening institutional tender requirements for bulk-forming generics is professionalizing contract manufacturing quality across Gujarat and Hyderabad production clusters.
- E-Commerce Channel Expansion:Direct-to-patient platforms are bypassing traditional pharmacy intermediaries, accelerating distribution velocity for powder and tablet format laxatives.
Market Restraints
- Active Ingredient Withdrawals:FDA reclassification of phenolphthalein-containing stimulants has forced portfolio restructuring and stranded inventory across multiple manufacturers.
- Supply Concentration in PEG Feedstocks:Polyethylene glycol precursor supply clusters in select Asian chemical hubs create input cost volatility exposure for osmotic formulation producers.
- Substitution by Probiotic Interventions:Microbiome-targeted digestive health products are capturing preventive-oriented consumers in wellness-focused retail channels.
Strategic Opportunities
- Underpenetrated Indian Institutional Market:Hospital and long-term care procurement standardization creates white space for CDSCO-compliant bulk-forming entrants.
- EMA Pharmacovigilance Alignment:Harmonized safety documentation requirements across European markets reward early compliance investment with accelerated market access.
- Opioid-Induced Bowel Dysfunction Indication:Expanding prescription-strength osmotic demand in pain management protocols creates specialized formulation opportunities.
Industry Challenges
- Monograph Status Uncertainty:FDA ongoing OTC reform timeline ambiguity complicates multi-year formulation investment planning and pipeline prioritization.
- Legacy System Integration:Established manufacturers face friction adapting quality management systems to evolving bioequivalence documentation requirements across multiple regulatory jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laxatives Market |
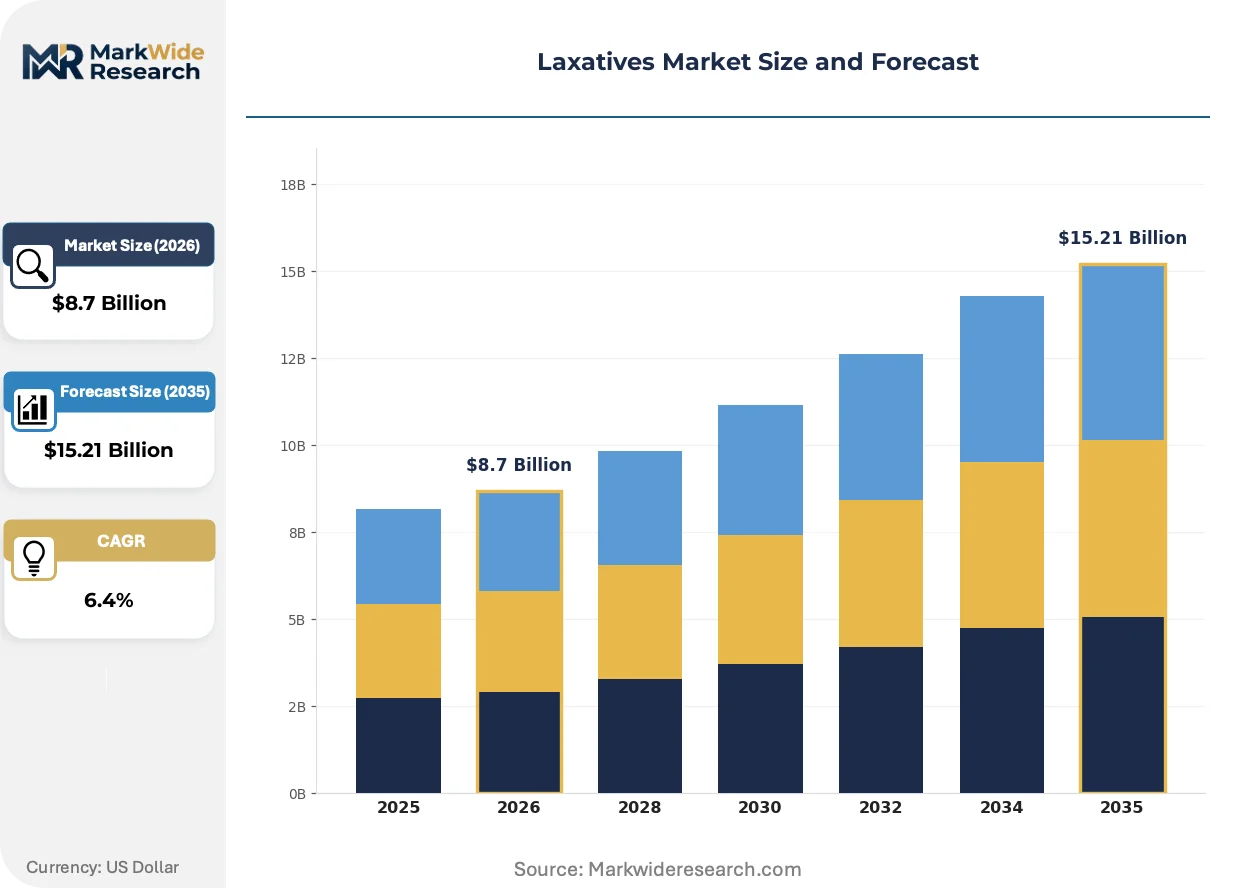
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stool Softeners, Bulk Forming, Osmotic, Stimulant End User: Pharmacies, Hospitals, Online Stores, Supermarkets Formulation: Tablet, Liquid, Powder, Gel Distribution Channel: Retail, Direct Sales, E-commerce, Wholesalers |
| Companies Covered | Johnson & Johnson, Abbott Laboratories, Bayer AG, Takeda Pharmaceutical Company Limited, Teva Pharmaceutical Industries Ltd., Pfizer Inc., GlaxoSmithKline plc, Procter & Gamble Co., Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laxatives Market Strategic Shifts
Digital health integration and regulatory safety recalibration are restructuring how laxative products reach end-users, with channel disintermediation and formulation science advancing in parallel.
Smart packaging embedded with adherence-tracking sensors is digitizing patient compliance monitoring for chronic constipation management. Geriatric care facilities are piloting connected dispenser systems that transmit consumption data to nursing station dashboards. This connectivity infrastructure is digitizing reimbursement documentation and enabling outcome-based formulary negotiations with pharmacy benefit managers.
EMA pharmacovigilance frameworks are tightening active ingredient concentration thresholds for stimulant laxatives across European markets. Manufacturers must now submit enhanced cardiovascular safety data for senna-derived formulations seeking renewal approvals. This regulatory recalibration is compressing stimulant variant portfolios while elevating osmotic and bulk-forming alternatives in hospital procurement guidelines.
Self-directed consumers are migrating from pharmacy counter purchases to subscription-based direct delivery platforms. Wellness-oriented buyers now research ingredient transparency and third-party testing certifications before committing to recurring orders. This behavioral shift is most visible in United States urban markets where same-day delivery infrastructure supports impulse-to-habit conversion for fiber supplement regimens.
Laxatives Market Segmentation
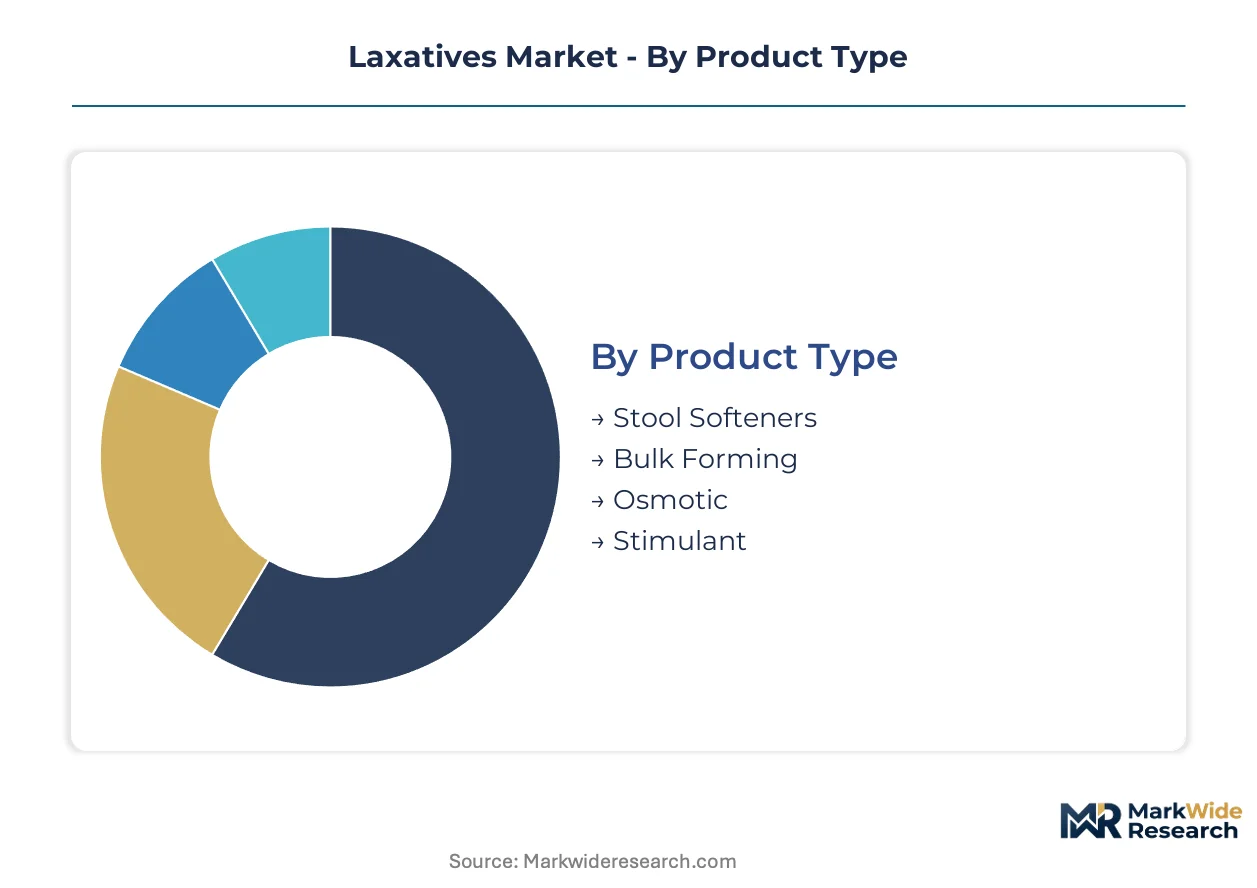
Laxative segmentation reveals how formulation science, procurement channels, and patient self-direction intersect to create distinct competitive arenas. Each category maps to divergent margin profiles and regulatory exposure, requiring targeted portfolio architecture rather than uniform market approaches.
Product Type:
Use-case spectrum spans acute relief through chronic management, with mechanism of action determining reimbursement tier and prescriber channel.
- Osmotic:Polyethylene glycol formulations draw water into intestinal lumen through osmotic pressure, producing predictable evacuation without cramping. Hospital procurement in the United States favors these agents for pre-procedural bowel preparation and geriatric populations, with FDA monograph stability supporting long-term formulary placement against stimulant volatility.
- Bulk Forming:Psyllium and methylcellulose derivatives absorb water to increase stool mass and trigger peristalsis. India's CDSCO-compliant contract manufacturers in Gujarat and Hyderabad clusters are expanding capacity to serve institutional tenders, though bioequivalence documentation requirements compress margins for generic entrants.
- Stimulant:Senna and bisacodyl compounds activate colonic nerve plexuses to accelerate transit. FDA phenolphthalein withdrawals have forced portfolio consolidation, leaving established brands to defend shelf position against safety-conscious pharmacy benefit manager exclusion.
- Stool Softeners:Docusate sodium surfactants reduce fecal surface tension for post-surgical or opioid-induced constipation. Limited differentiation confines these agents to narrow acute-care protocols and pediatric niches.
Established volume favors osmotic formulations; emerging adoption favors bulk-forming fiber supplements in direct-to-consumer channels.
End User:
Procurement authority concentrates in divergent institutional and self-directed settings, with reimbursement status dictating price realization.
- Hospitals:Formulary committees prioritize osmotic agents for inpatient bowel preparation and opioid-induced dysfunction protocols. Geriatric care facilities within this channel represent the steepest expansion trajectory as census growth outpaces acute-care admission rates.
- Pharmacies:Community and chain dispensaries capture recurring prescriptions for chronic constipation management, with pharmacist counseling influencing brand substitution patterns. Shelf placement fees and generic substitution pressure compress branded margins.
- Online Stores:Subscription platforms bypass pharmacy intermediaries to capture wellness-oriented consumers researching ingredient transparency. Same-day delivery infrastructure in dense United States urban markets supports habit formation for fiber supplement regimens.
- Supermarkets:Mass-market retail positions laxatives adjacent to digestive wellness aisles, with private-label fiber supplements capturing price-sensitive shoppers. Limited pharmacist interaction restricts prescription-strength placement.
Institutional procurement concentrates in hospitals; patient-directed volume is shifting fastest into online stores.
Formulation:
Patient compliance and administration setting determine format preference, with portability and taste masking driving innovation investment.
- Powder:Bulk-forming psyllium and methylcellulose variants dominate this format, with single-serve sachets penetrating travel and workplace consumption occasions. Gujarat-based contract manufacturers are scaling powder filling lines to serve export demand.
- Tablet:Osmotic and stimulant agents compress into coated tablets for discreet chronic use. Hospital formulary preference for unit-dose packaging supports this format's institutional defense.
- Liquid:Pediatric and geriatric populations favor liquid osmotic solutions for dose titration flexibility. Polyethylene glycol 3350 solutions command premium positioning in pre-procedural preparation kits.
- Gel:Rectal delivery formats serve acute obstruction rescue scenarios and patients with swallowing difficulties. Limited addressable market constrains manufacturer investment in formulation refinement.
Tablet formats anchor chronic-use prescriptions; powder formulations are gaining share fastest in subscription wellness channels.
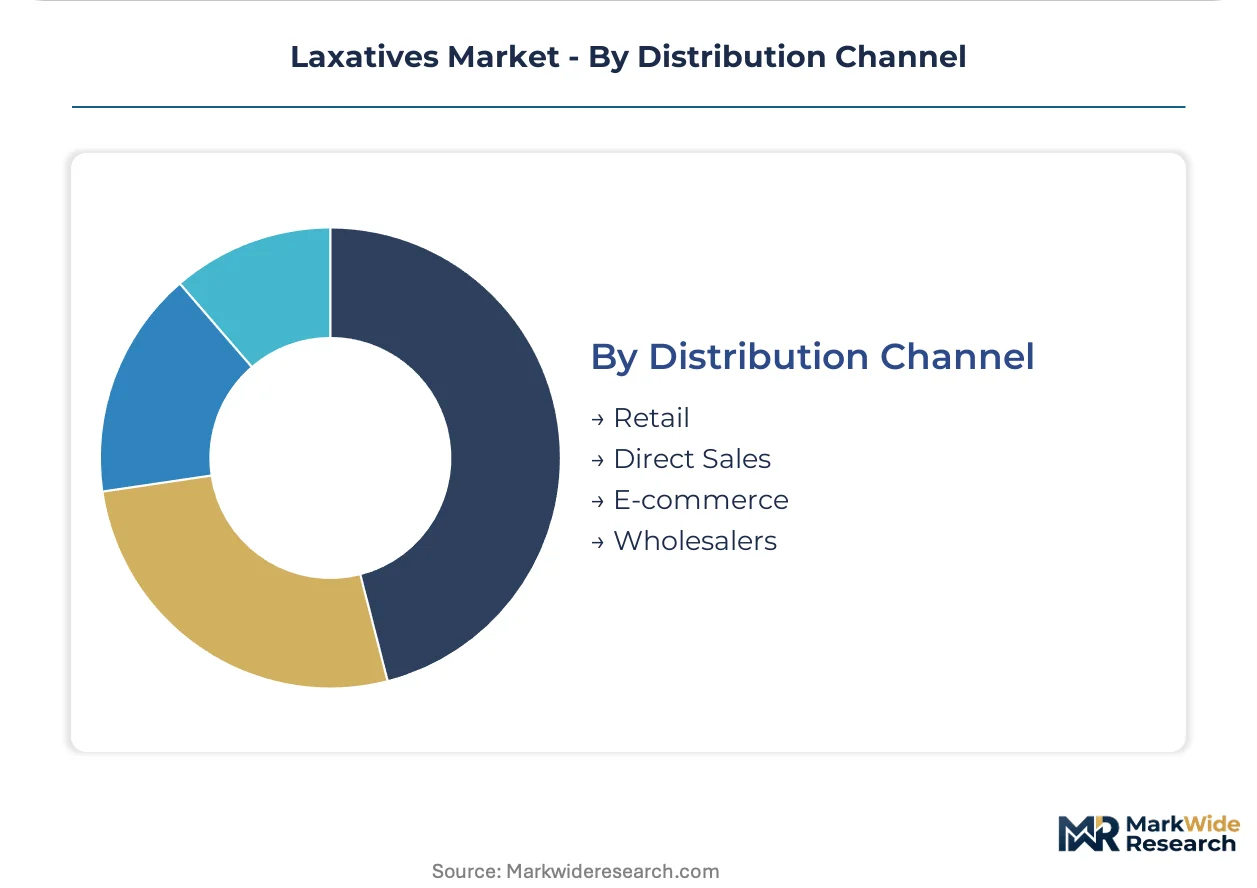
Distribution Channel:
Channel economics fragment across intermediated and disintermediated pathways, with inventory carrying cost and patient data ownership determining strategic priority.
- E-commerce:Direct-to-patient platforms capture recurring revenue through subscription fiber programs, with third-party testing certifications and ingredient transparency influencing conversion. United States urban same-day delivery infrastructure supports impulse-to-habit conversion.
- Retail:Pharmacy and supermarket storefronts provide immediate availability for acute need states, with planogram placement fees and pharmacist recommendation programs defending incumbent brand position.
- Direct Sales:Institutional contracting teams serve hospital purchasing consortia and long-term care group purchasing organizations, with outcome-based formulary negotiations emerging in geriatric care networks.
- Wholesalers:McKesson and Cardinal Health-type distributors maintain inventory buffers for pharmacy chains, with generic bulk-forming laxatives flowing through this channel to minimize manufacturer working capital exposure.
Wholesalers and retail intermediaries still handle majority volume; e-commerce direct channels are climbing the fastest as patient data monetization opportunities attract platform investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA OTC monograph reform anchors the United States as the dominant geography, with aging demographics and self-medication trends sustaining volume leadership across institutional and direct-to-consumer channels.
United States
Geriatric care facilities drive the fastest-expanding procurement segment as census growth outpaces acute-care admissions. FDA's ongoing reclassification of phenolphthalein-containing stimulants compresses product lifecycles and forces portfolio restructuring. Polyethylene glycol formulation clusters in New Jersey and Illinois chemical corridors supply hospital procurement networks.
Germany
EMA pharmacovigilance frameworks tighten active ingredient thresholds for senna-derived stimulants seeking renewal approvals. Enhanced cardiovascular safety documentation requirements compress stimulant portfolios while elevating osmotic alternatives. Baden-Württemberg and Bavaria host pharmaceutical manufacturing hubs serving European hospital formulary committees.
India
CDSCO bioequivalence requirements professionalize contract manufacturing quality for bulk-forming generics entering institutional tenders. Hospital and long-term care procurement standardization creates white space for compliant entrants. Gujarat and Hyderabad production clusters expand powder filling capacity to serve export demand.
Japan
PMDA safety guidelines influence regional formulation preferences toward gentle-acting osmotic agents in aging populations. Kanto and Kansai metropolitan areas concentrate pharmaceutical distribution infrastructure. Tokyo-based purchasing consortia negotiate outcome-based formulary placement for chronic constipation management protocols.
United Kingdom
NHS procurement frameworks favor unit-dose tablet formats for institutional cost containment. London and Southeast England anchor pharmacy chain headquarters influencing shelf placement negotiations. MHRA alignment with EMA pharmacovigilance standards streamlines renewal documentation for osmotic formulation portfolios.
Laxatives Market Competitive Environment
Capability concentration sits with prescription-strength specialists; scale advantage sits with diversified consumer health conglomerates. The market structures around three tiers: hospital formulary incumbents with regulatory dossier depth, pharmacy shelf dominators with trade spend scale, and contract manufacturers with bioequivalence documentation agility. Two competitive moves define positioning: M&A to capture opioid-induced bowel dysfunction indications, and backward integration into polyethylene glycol feedstock supply.
Among diversified consumer health conglomerates, Johnson & Johnson and Procter & Gamble Co. exemplify scale-driven pharmacy shelf defense. Bayer AG occupies a position within European prescription-strength portfolios. Takeda Pharmaceutical Company Limited anchors Asia-Pacific osmotic specialization. These named entities represent archetype positioning rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Abbott Laboratories |
| Bayer AG |
| Takeda Pharmaceutical Company Limited |
| Teva Pharmaceutical Industries Ltd. |
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Procter & Gamble Co. |
| Sanofi |
| Others |
Value Chain & Pricing Dynamics
Shanghai-Ningbo port freight corridors govern polyethylene glycol feedstock import economics, compressing margins for Indian osmotic formulation producers while amplifying price spreads between hospital-grade and retail-tier laxative products across United States and European markets.
Pricing Analysis
United States pharmacy chains command 40-60% discounts below German hospital procurement rates for equivalent polyethylene glycol formulations. Three-tier pricing structure across premium, standard, and economy levels separates FDA-monograph-certified hospital supplies from subscription wellness powders and mass-market private-label tablets. Price differentiation hinges on bioequivalence documentation burden and brand heritage in pharmacy benefit manager negotiations. Pricing pressure stems from CDSCO-compliant Indian generics entering institutional tenders at compressed margins. Supermarket private-label shoppers exhibit highest price sensitivity; geriatric care facility group purchasing organizations demonstrate lowest.
Supply Chain Analysis
Tariff exposure between China and India dominates supply chain risk calculations for polyethylene glycol precursor procurement. Active pharmaceutical ingredient synthesis concentrates in China, India, and select New Jersey chemical corridors. Formulation depends on polyethylene glycol 3350, psyllium husk, and senna extract as core inputs. Single-source vulnerability pervades PEG feedstock supply clusters in Zhejiang province. Distribution runs through McKesson-type wholesalers for pharmacy chains, with direct-to-patient platforms bypassing intermediaries fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating through hospital purchasing consortia and long-term care group purchasing organizations, fragmenting pricing leverage across legacy branded manufacturers.
For Market Incumbents: Entrench formulary position through backward integration into polyethylene glycol feedstock supply and accelerated CDSCO bioequivalence dossier completion for Indian institutional tenders. Probiotic substitution threats in wellness channels demand fiber-plus-microbiome hybrid R&D investment. Channel control through smart packaging adherence data strengthens pharmacy benefit manager negotiation leverage.
For New Entrants and Emerging Players: Underpenetrated Indian hospital and long-term care procurement standardization represents the most penetrable entry point for CDSCO-compliant bulk-forming generics. Subscription-based direct-to-patient platforms in United States urban markets offer second white-space avenue for transparency-certified fiber supplements. Go-to-market angle: third-party testing certification and same-day delivery infrastructure partnerships.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical parents with neglected prescription-strength osmotic portfolios lacking opioid-induced bowel dysfunction indication focus. Long-term viability frames around regulatory dossier depth rather than brand equity. Signal to watch: FDA OTC monograph reform timeline clarity as inflection indicator for stimulant laxative portfolio valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PEG Feedstock | Captive supply of polyethylene glycol 3350 insulates osmotic formulation margins from Zhejiang supply shocks. |
| CDSCO Bioequivalence Certification | Documentation compliance unlocks institutional tender access across Gujarat and Hyderabad manufacturing clusters. |
| Smart Packaging Adherence Systems | Connected dispenser data enables outcome-based formulary negotiations with geriatric care purchasing consortia. |
| Opioid-Indicated Formulation Development | Specialized osmotic protocols capture prescription-strength demand from pain management clinical pathways. |
| Direct-to-Patient Subscription Launch | Recurring revenue platforms bypass pharmacy intermediaries in United States urban same-day delivery corridors. |
Study Parameters
The analysis maps osmotic, bulk-forming, stimulant, and stool softener sub-sectors, each validated through hospital formulary directors, pharmacy procurement managers, contract manufacturing executives, and regulatory affairs leads. Primary interviews with these stakeholders combined with secondary validation against FDA OTC monograph filings, CDSCO tender databases, EMA pharmacovigilance reports, and hospital procurement contract repositories. Bottom-up volume triangulation across formulation types and top-down value reconciliation against end-use procurement channels anchored market sizing.
Assumption sets held FDA monograph reform timeline and polyethylene glycol feedstock cost curves fixed while varying geriatric care facility census growth and e-commerce penetration rates. Segmentation dimensions modeled span mechanism of action, end-user procurement authority, formulation format, and distribution channel structure. CAGRs derived from logistic adoption curves fitted to institutional procurement standardization timelines and self-medication channel migration patterns. Opioid-induced bowel dysfunction protocol expansion and probiotic substitution elasticity served as scenario-variant inputs.
Practitioners should monitor FDA monograph reform announcements, CDSCO tender specification changes, and PEG feedstock tariff adjustments for early signals necessitating forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Ocular Drug Delivery System Market
Pharmaceuticals
Repurposed Human Immunosuppressants Market
Pharmaceuticals
Nucleic Acid Therapeutics Contract Development and Manufacturing Organization Market
Pharmaceuticals
Selective Serotonin Reuptake Inhibitors Market
Pharmaceuticals
Sustained Release Drugs Market
Pharmaceuticals
Isoflurane Market
Pharmaceuticals
Large Volume Parenteral (LVP) Market
Pharmaceuticals
Global Anesthesia Drugs Market
Pharmaceuticals
Canada Specialty Pharmacy Market
Pharmaceuticals
Angiogenesis Inhibitors and Stimulators Market
Pharmaceuticals
Paracetamol IV Market
Pharmaceuticals
Warts Therapeutics Market
Pharmaceuticals
Tuberculosis Therapeutics Market
Pharmaceuticals
Global Cytotoxic Drugs Market
Pharmaceuticals
Unit-Dose Respiratory Medications Market
Pharmaceuticals
Italy Healthcare Market