
 Meperidine Drugs Market | 2026-2036
Meperidine Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Meperidine Drugs Market Foresight
Pain management centers are redrawing procurement priorities as hospital formularies tighten opioid stewardship. Mallinckrodt Pharmaceuticals anchors North American manufacturing capacity for injectable meperidine. Hikma Pharmaceuticals PLC competes through generic tablet supply across European and Middle Eastern markets. Teva Pharmaceutical Industries Ltd. extends its position with diversified dosage forms including oral solutions.
Meperidine drugs are synthetic opioid analgesics derived from phenylpiperidine, typically formulated as hydrochloride salts with parenteral bioavailability exceeding 80 percent, primarily indicated for moderate to severe acute pain relief in perioperative and obstetric settings. The injection segment dominates hospital procurement due to rapid onset requirements in surgical recovery, while the tablet format serves declining outpatient chronic pain prescriptions amid safety concerns. Intravenous delivery mode captures the largest volume share in anesthesia applications, though subcutaneous administration grows in palliative care settings where patient-controlled analgesia pumps reduce nursing burden.
FDA scheduling under Controlled Substances Act Schedule II shapes manufacturing quotas, distribution tracking, and prescribing limits across the United States. DEA production limits and state-level prescription monitoring programs constrain volume expansion regardless of clinical demand fluctuations. Stakeholders must monitor evolving CDC opioid prescribing guidelines and institutional formulary restrictions that directly determine meperidine's competitive standing against morphine and hydromorphone alternatives.
Market Dynamics
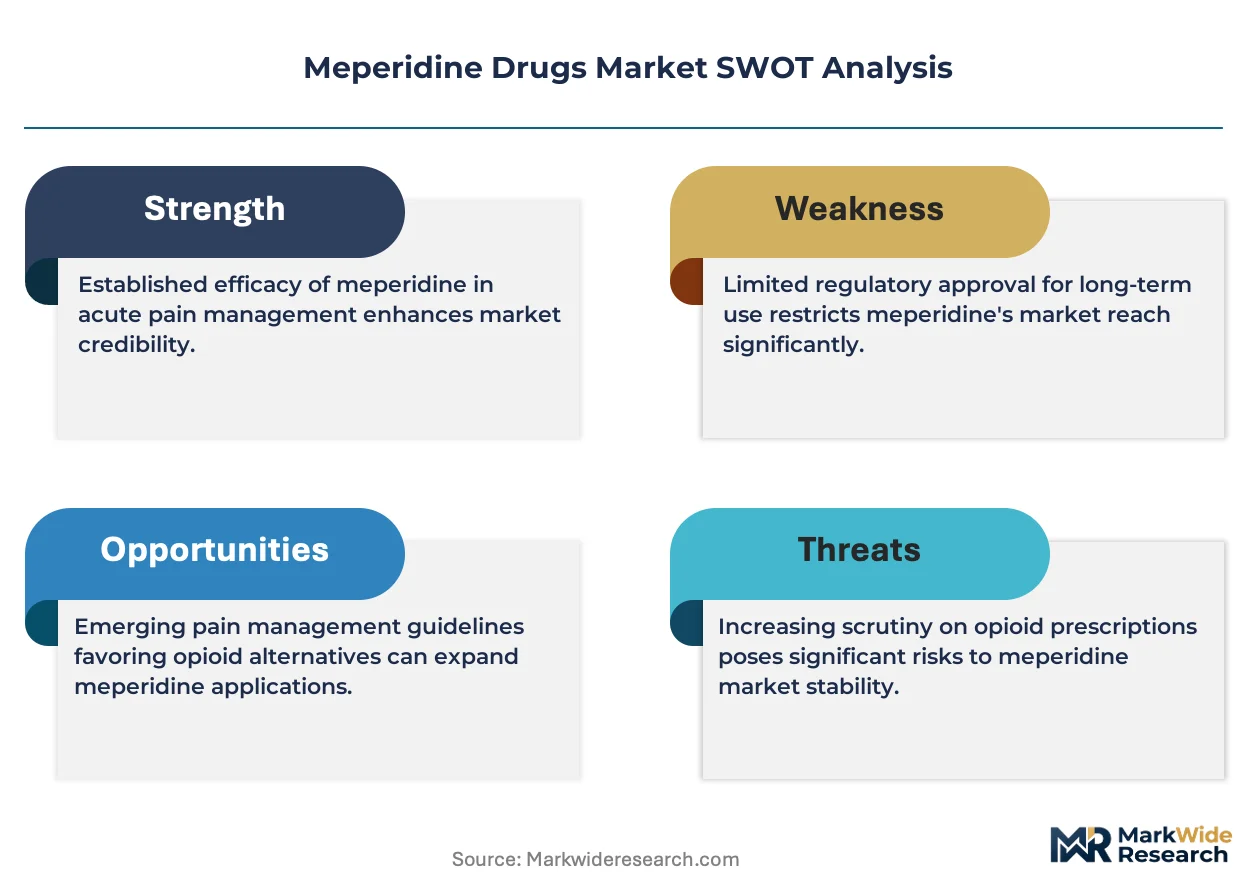
FDA Schedule II classification and DEA production quotas impose rigid supply ceilings that disconnect manufacturing capacity from clinical demand fluctuations in acute care settings. Hospital formularies are systematically deprioritizing meperidine amid institutional opioid stewardship mandates.
Growth Catalysts
- Perioperative pain protocols:Surgical units maintain meperidine in multimodal analgesia regimens for patients with morphine intolerance. Post-operative recovery floors specify parenteral delivery for rapid onset control.
- Obstetric analgesia demand:Labor and delivery departments preserve meperidine for parturients requiring short-acting opioid relief without prolonged neonatal depression. Maternity wards in tertiary hospitals anchor consistent procurement volumes.
- Controlled Substances Act framework:DEA quota allocations create predictable competitive boundaries that protect incumbent manufacturers from capacity-driven price erosion. Established suppliers benefit from regulatory moats around production licensing.
Market Restraints
- Active pharmaceutical ingredient concentration:Phenylpiperidine precursor supply concentrates among specialty chemical manufacturers in Germany and Switzerland, exposing formulators to single-source dependency risk.
- Serotonin syndrome liability:Meperidine's interaction profile with monoamine oxidase inhibitors creates prescribing friction that hydromorphone and fentanyl alternatives avoid. Clinical safety databases document adverse event patterns that inform formulary exclusions.
- Morphine equivalence conversion:Standardized opioid conversion tables in electronic health records nudge prescribers toward alternatives with cleaner pharmacokinetic profiles. Clinical decision support systems embed institutional preferences that disadvantage meperidine.
Strategic Opportunities
- Palliative care pump integration:Patient-controlled analgesia device manufacturers are certifying meperidine compatibility for home hospice settings. Subcutaneous delivery protocols expand addressable use cases beyond hospital walls.
- EMA centralized procedure alignment:European manufacturers pursuing mutual recognition can streamline multi-country market access through single regulatory submission. Harmonized labeling reduces national variation barriers.
- Hospital-at-home expansion:Acute care delivery models shifting to residential settings create demand for short-acting parenteral opioids with established nursing protocols. Home infusion services require analgesics with predictable duration profiles.
Industry Challenges
- DEA quota forecasting precision:Manufacturers must project annual production needs twelve months in advance against volatile hospital purchasing patterns. Misalignment between quota requests and actual demand creates inventory shortages or carrying cost penalties.
- Legacy EHR integration:Electronic prescribing systems require manual workaround configurations for Schedule II substances that slow clinical workflow. Pharmacy information technology teams face upgrade backlogs that delay automated compliance reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meperidine Drugs Market |
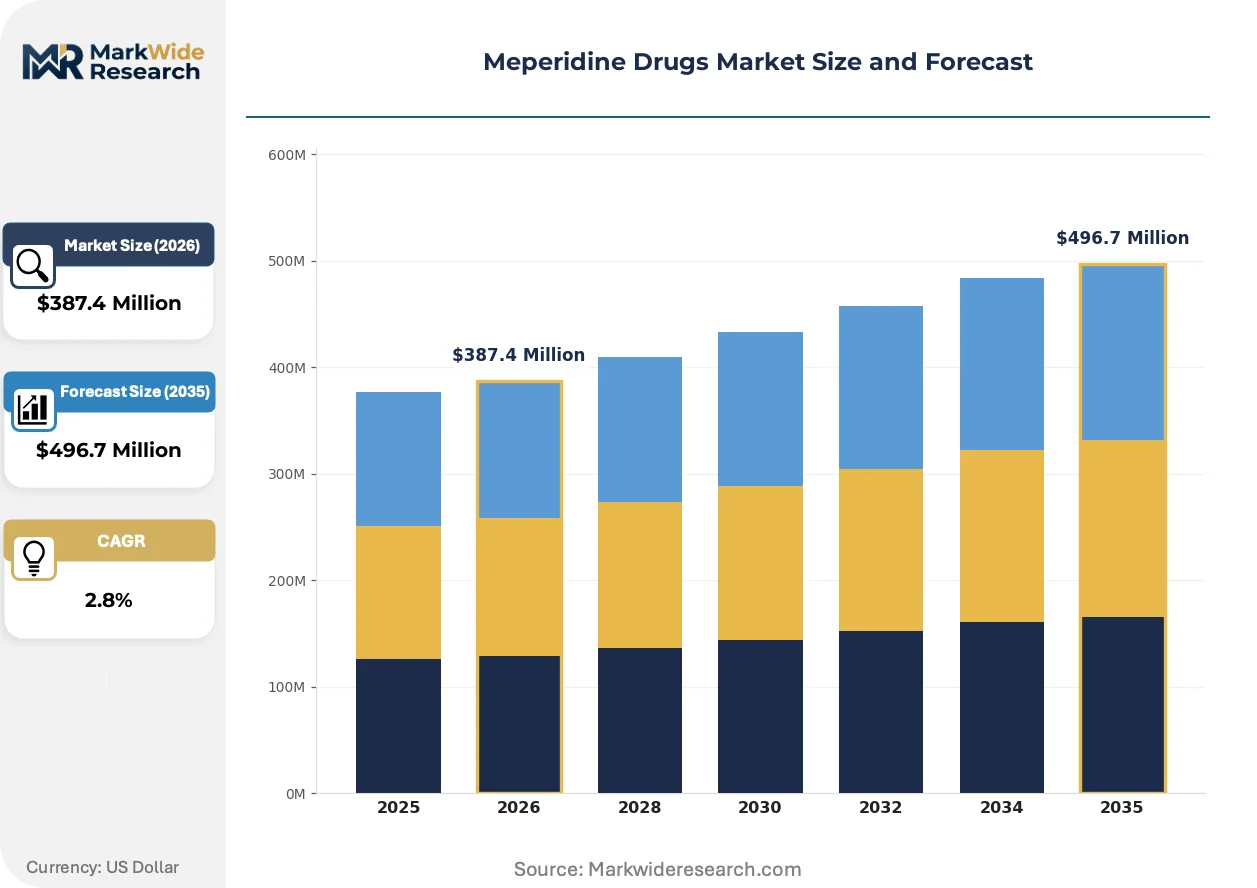
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $496.7 Million |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection, Tablet, Solution, Syrup End User: Hospitals, Clinics, Pain Management Centers, Home Care Therapy Area: Anesthesia, Palliative Care, Acute Pain Management, Chronic Pain Treatment Delivery Mode: Intravenous, Intramuscular, Oral, Subcutaneous |
| Companies Covered | Pfizer Inc., Mallinckrodt Pharmaceuticals, Sandoz (Novartis AG), Epic Pharma LLC, Sanofi S.A., Hikma Pharmaceuticals PLC, Teva Pharmaceutical Industries Ltd., Boehringer Ingelheim International GmbH, Sun Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meperidine Drugs Market Shifts & Advancements
Formulary automation and clinical decision support are actively compressing prescriber discretion for legacy opioids while opening technical pathways for targeted analgesic delivery systems. Three convergent developments are restructuring competitive positioning.
Extended-release local anesthetic formulations combined with liposomal encapsulation technology are supplanting short-acting parenteral opioids in select ambulatory surgical protocols. Outpatient arthroscopy centers are adopting these alternatives for same-day discharge cases. The shift is compressing meperidine volume in orthopedic day surgery while preserving its role in inpatient recovery.
CDC opioid prescribing guidelines are tightening perioperative quantity limits and mandatory prescription monitoring program checks across US hospital systems. The 2022 guideline updates extended duration thresholds that trigger automated pharmacy alerts. Surgical departments in California and New York are responding with pre-emptive multimodal protocols that reduce meperidine line items.
Consolidated purchasing organizations are centralizing analgesic contracts under single-source agreements that bundle multiple opioid SKUs. Three-hospital systems in Texas and Florida are displacing fragmented pharmacy committee decisions with standardized formularies. The behavioral shift concentrates volume with manufacturers offering full-spectrum opioid portfolios rather than meperidine-only suppliers.
Meperidine Drugs Market Segmentation
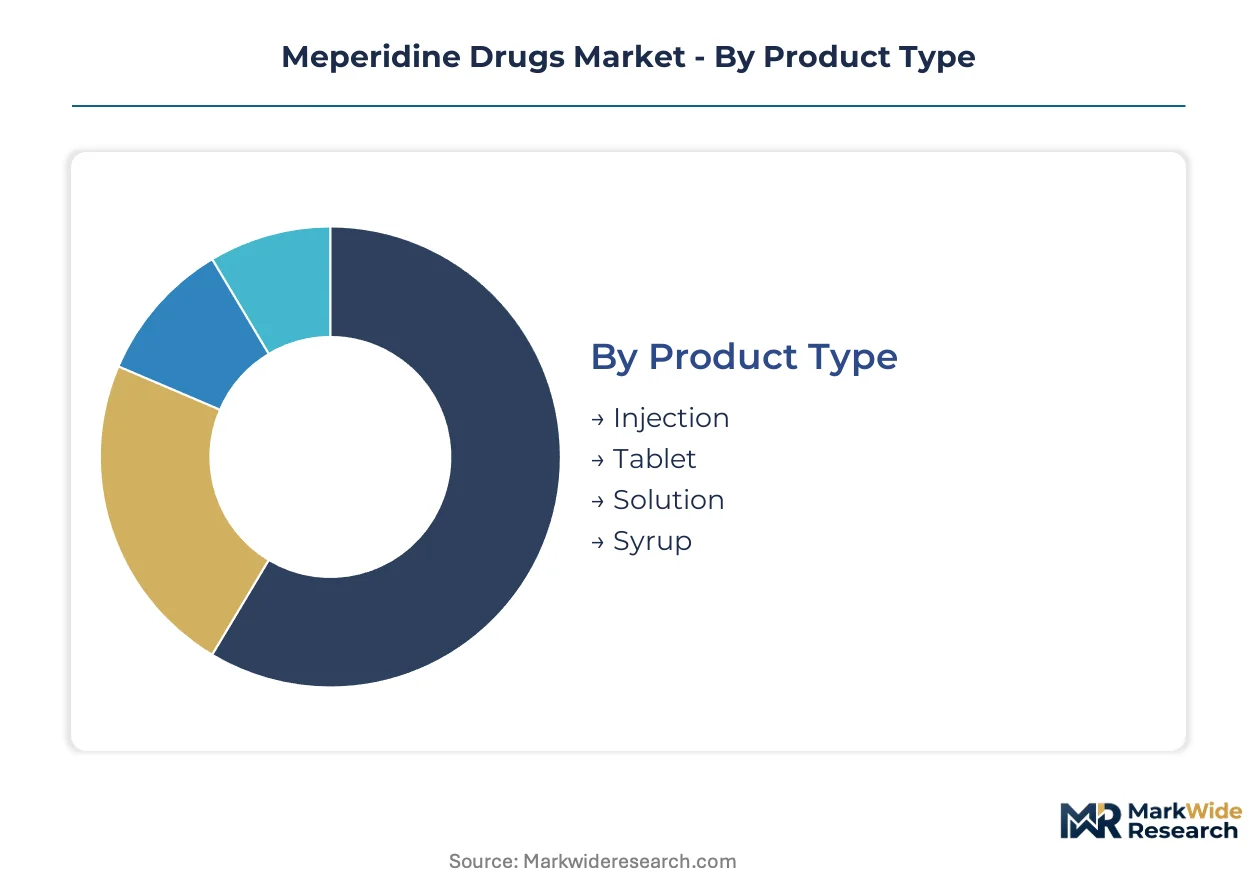
Meperidine's synthetic opioid classification under Schedule II controls creates divergent compliance burdens across dosage forms and delivery settings. Segmentation reveals how regulatory friction reshapes procurement patterns between hospital systems and outpatient channels.
Product Type:
FDA DEA quotas apply differentially to parenteral versus oral formulations, with injectable production tracked through separate manufacturing batch records.
- Injection:Hydrochloride salt formulations achieve bioavailability exceeding 80 percent through intramuscular or intravenous routes. Hospital surgical units and labor-and-delivery departments anchor procurement volumes for rapid-onset perioperative protocols.
- Tablet:Oral solid dosage forms face steeper prescribing scrutiny under CDC opioid guidelines and state prescription monitoring programs. Chronic pain outpatient prescriptions are declining amid institutional formulary restrictions.
- Solution:Liquid concentrates support compounding pharmacies and specialized pediatric dosing requirements.
- Syrup:Flavored oral suspensions serve limited geriatric and pediatric populations with swallowing difficulties.
Established volume favors Injection; emerging adoption favors Solution in compounding channels.
End User:
Procurement authority concentrates with pharmacy-and-therapeutics committees that apply uniform opioid stewardship standards across facility types.
- Hospitals:Tertiary academic medical centers and community hospital systems maintain meperidine in multimodal anesthesia protocols. Surgical volume and obstetric admissions determine annual purchasing contracts.
- Clinics:Ambulatory surgical centers and urgent care facilities stock limited quantities for same-day procedure recovery.
- Pain Management Centers:Specialized interventional practices are deprioritizing meperidine in favor of hydromorphone and fentanyl alternatives with cleaner drug interaction profiles.
- Home Care:Hospice agencies and home infusion services are expanding subcutaneous patient-controlled analgesia pump applications.
Contract concentration favors Hospitals; service expansion favors Home Care.
Therapy Area:
Clinical decision support systems embed therapy-specific alerts that reshape prescriber behavior across acute versus chronic indications.
- Anesthesia:Perioperative protocols specify meperidine for patients with documented morphine intolerance or rigidity syndromes.
- Palliative Care:Hospice settings value the short duration of action for breakthrough pain management without prolonged sedation.
- Acute Pain Management:Emergency departments and trauma centers maintain parenteral stock for rapid titration in hemodynamically unstable patients.
- Chronic Pain Treatment:Long-term prescribing faces institutional exclusion due to serotonin syndrome risk and active metabolite accumulation.
Protocol preservation favors Anesthesia; clinical displacement favors Chronic Pain Treatment.
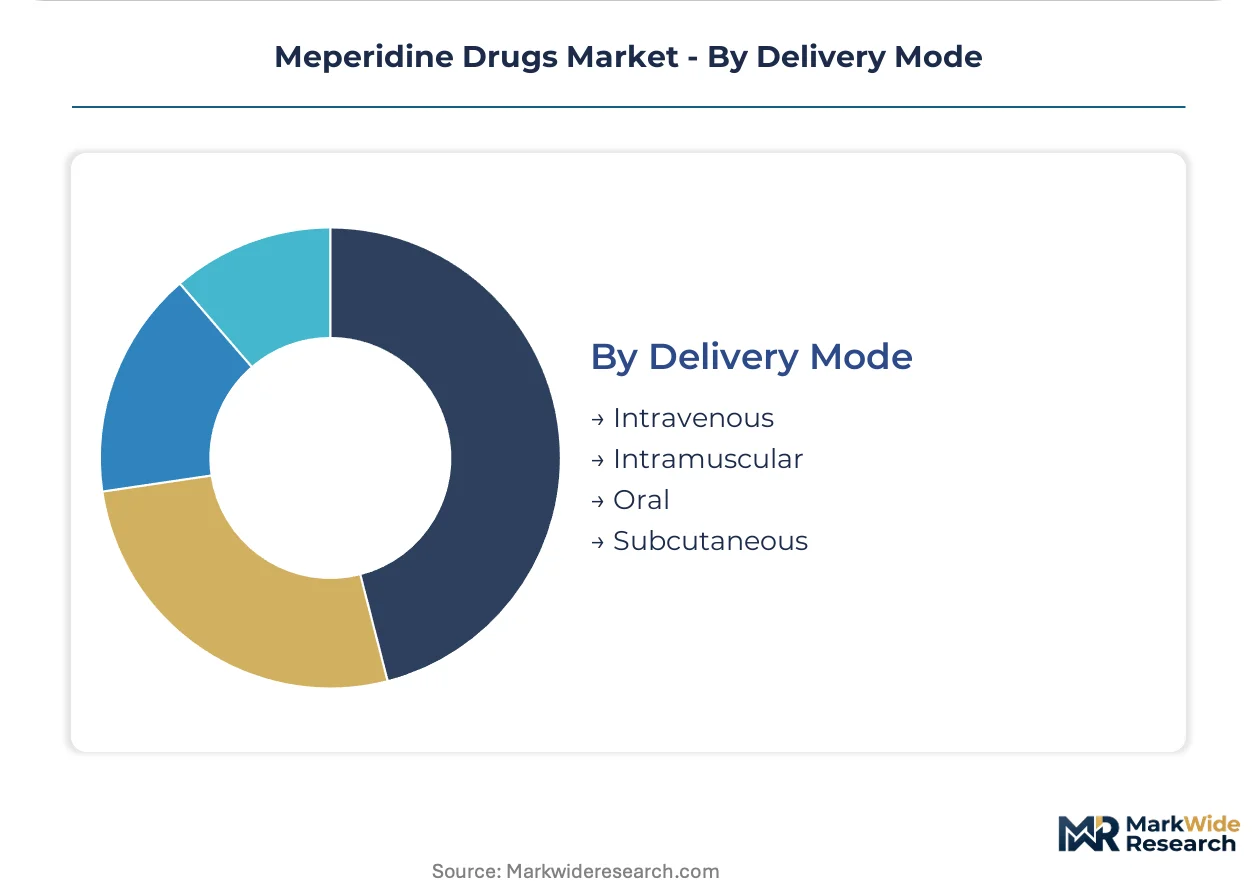
Delivery Mode:
Route selection determines DEA distribution tracking requirements and nursing workflow integration costs.
- Intravenous:Direct vascular administration achieves peak plasma concentration within 5-10 minutes. Operating rooms and post-anesthesia care units specify IV delivery for immediate effect.
- Intramuscular:Slower absorption kinetics suit patients without vascular access, though injection site pain limits patient acceptance.
- Oral:First-pass hepatic metabolism reduces bioavailability and delays onset, restricting use to step-down analgesia.
- Subcutaneous:Patient-controlled analgesia pumps enable continuous infusion in palliative home care, reducing nursing administration burden.
Institutional standardization favors Intravenous; technology integration favors Subcutaneous.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital systems and surgical networks concentrate purchasing authority across distinct national regulatory environments. Each geography presents unique DEA, FDA, or EMA compliance burdens that reshape procurement patterns for Schedule II synthetic opioids.
United States
Tertiary academic medical centers in Boston, Houston, and Los Angeles anchor meperidine demand through perioperative protocols and obstetric units. DEA production quotas under the Controlled Substances Act impose rigid annual manufacturing ceilings that disconnect supply from clinical demand fluctuations. Mallinckrodt Pharmaceuticals maintains concentrated production capacity in Missouri and Illinois, serving hospital networks under long-term supply agreements.
Germany
Specialty chemical manufacturers in Ludwigshafen and Leverkusen supply phenylpiperidine precursors to European formulators. EMA centralized procedures streamline multi-country market access, though national pricing boards in Berlin and Munich impose reference-based reimbursement limits. German hospital federations are systematically deprioritizing meperidine in favor of hydromorphone through formulary standardization.
United Kingdom
NHS England's opioid stewardship mandates have compressed meperidine prescribing in London and Manchester hospital trusts. The Medicines and Healthcare products Regulatory Agency tracks Schedule II distribution through centralized pharmacy reporting. Palliative care networks in Liverpool and Glasgow preserve limited subcutaneous pump applications for home hospice settings.
India
CDSCO manufacturing licenses for Schedule II opioids concentrate among Mumbai and Hyderabad-based formulators serving domestic hospital chains. Export-oriented production from Gujarat and Maharashtra supplies Middle Eastern and African markets under bilateral regulatory recognition agreements. Indian pharmaceutical exporters face EMA and FDA inspection backlogs that delay European and North American market access.
Switzerland
Swissmedic's stringent batch certification requirements protect domestic manufacturers in Basel and Bern from price-driven import competition. Specialized chemical synthesis capabilities in the Rhine corridor support high-purity phenylpiperidine production for global API supply. Swiss hospital procurement cooperatives in Zurich and Geneva maintain limited meperidine stocks for documented morphine intolerance cases.
Meperidine Drugs Market Competitive Landscape
Player mix skews toward diversified pharmaceutical conglomerates with established controlled-substance manufacturing infrastructure. The competitive structure concentrates around three to four incumbent suppliers protected by DEA quota allocations and specialized production licensing. Strategic archetypes include vertically integrated API-to-dosage-form manufacturers, regional generic specialists with EMA mutual recognition, and hospital-contract aggregators bundling full opioid portfolios. Dominant competitive moves center on quota defense through regulatory relationship maintenance and formulary lock-in via diversified analgesic portfolios.
Among North American-based manufacturers, Mallinckrodt Pharmaceuticals anchors the injectable segment through Missouri production facilities. Hikma Pharmaceuticals PLC occupies a position exemplifying Middle Eastern-European supply bridge strategies, while Teva Pharmaceutical Industries Ltd. represents the diversified dosage-form archetype spanning oral solutions and tablets. These three entities collectively illustrate how regulatory moats around Schedule II licensing create durable competitive positioning against new market entrants lacking established DEA relationships and quota histories.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Mallinckrodt Pharmaceuticals |
| Sandoz (Novartis AG) |
| Epic Pharma LLC |
| Sanofi S.A. |
| Hikma Pharmaceuticals PLC |
| Teva Pharmaceutical Industries Ltd. |
| Boehringer Ingelheim International GmbH |
| Sun Pharmaceutical Industries |
| Others |
Supply & Pricing Matrix
Phenylpiperidine precursor substitution from German and Swiss specialty chemical suppliers to Indian API manufacturers is simultaneously redrawing supply geography toward South Asia and compressing intermediate pricing through volume-scale chemistry capabilities. This geographic shift feeds back into formulation economics as hospital procurement committees negotiate against landed-cost alternatives.
Pricing Analysis
Prior-generation parenteral vial pricing faces compression from next-generation liposomal local anesthetic bundles that displace meperidine in ambulatory protocols. Three-tier pricing structure across DEA-quota-protected, standard generic, and economy contract-manufactured tiers dominates hospital GPO negotiations. Price differentiation hinges on FDA establishment inspection history and vertical integration into phenylpiperidine synthesis. Cost compression in the economy tier intensifies because Indian exporters undercut European incumbents on API conversion costs. Ambulatory surgical centers exhibit highest price sensitivity; tertiary academic medical centers with obstetric units show lowest.
Supply Chain Analysis
DEA quota allocation cycles create twelve-month inventory lead-time rigidities that prevent demand-responsive production adjustments. Phenylpiperidine API concentrates in Germany, Switzerland, and India; finished dosage form manufacturing clusters in Missouri, Illinois, and Gujarat. Raw material dependencies include 4-piperidone hydrochloride, benzyl cyanide, and specialized hydrogenation catalysts. Single-source vulnerability runs through Swiss-German precursor supply for high-purity grades. Distribution runs through DEA-registered wholesale distributors with Schedule II vault infrastructure before hospital pharmacy receiving.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patient-controlled analgesia pump interoperability standards are creating platform-economics inflection as device manufacturers certify multi-opioid compatibility, eroding single-molecule lock-in and enabling formulary substitution at the point of care.
For Market Incumbents: Consolidate DEA quota allocations through multi-year production forecasts that align with hospital system contracting cycles. Backward integration into phenylpiperidine precursor synthesis in Basel or Ludwigshafen protects margin structure against Indian API import competition. Mallinckrodt's Missouri infrastructure exemplifies capacity concentration that new entrants cannot replicate without quota history.
For New Entrants and Emerging Players: CDSCO Schedule II manufacturing license fast-track through Hyderabad or Mumbai regulatory consulting relationships opens white-space access. Target home hospice subcutaneous pump services in Texas and Florida where nursing protocol flexibility exceeds hospital formulary rigidity. Pursue EMA centralized procedure alignment as the go-to-market angle for European hospital-at-home expansion.
For Investors and Strategic Acquirers: The market sits at a late-stage consolidation phase that favors diversified opioid portfolio owners over single-molecule specialists. Five-to-ten-year viability hinges on DEA relationship durability and hospital GPO contract concentration. Acquisition target archetype: regional generic injectable manufacturers with established quota history and underutilized Schedule II production lines. Watch FDA inspection observation trends as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| DEA Quota Defense and Expansion | Multi-year allocation requests secure manufacturing capacity against demand volatility in perioperative settings. |
| Palliative Care Pump Certification | Device compatibility agreements with PCA manufacturers extend addressable use beyond hospital walls. |
| EMA Centralized Procedure Filing | Single regulatory submission streamlines multi-country hospital access across European Union member states. |
| Backward Integration into Phenylpiperidine | Captive API production insulates margin from German-Swiss precursor pricing and supply interruption. |
| Hospital-at-Home Service Partnership | Home infusion network agreements create demand for subcutaneous delivery protocols in residential settings. |
Research Methodology
Operator-level perspectives from hospital pharmacy directors, DEA regulatory consultants, palliative care physicians, and medical device integration specialists anchored the qualitative base. Primary interviews combined with secondary validation against FDA 483 inspection databases, DEA aggregate production quota reports, CMS Medicare Part B claims data, and hospital GPO contract disclosures. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing triangulated segment-level estimates.
Sensitivity analysis across DEA quota allocation scenarios, hospital formulary exclusion probabilities, and liposomal anesthetic substitution rates shaped the analytical framework. Segmentation dimensions included dosage form, delivery mode, therapy area, and regional regulatory cluster. CAGRs were derived from trend-line extrapolation of historical prescription volumes adjusted for institutional stewardship impacts. Forecast inputs incorporated CDC guideline revision probabilities and EMA centralized procedure approval timelines.
Decision-makers should treat outputs as directional under stable DEA scheduling and stable hospital reimbursement assumptions; material deviation would warrant model refresh. Specific risk factors include sudden Schedule II rescheduling, mandatory prescription monitoring program expansion, and breakthrough local anesthetic formulations displacing short-acting opioids. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Europe Pharmaceutical Contract Manufacturing Market
Pharmaceuticals
Drug Designing Tools Market
Pharmaceuticals
Nuclear Medicines Radioisotopes Market
Pharmaceuticals
Topical Corticosteroids Market
Pharmaceuticals
Hyoscine-N-Butyl Bromide Market
Pharmaceuticals
Meglitinide Market
Pharmaceuticals
Acne Drugs Market
Pharmaceuticals
Global Nizatidine Market
Pharmaceuticals
Hospital Pharmaceuticals Market
Pharmaceuticals
2-Valent HPV Vaccine (2vHPV) Market
Pharmaceuticals
Cough and Cold Preparations Market
Pharmaceuticals
Bendamustin Market
Pharmaceuticals
Specialty Active Pharmaceutical Ingredients Market
Pharmaceuticals
Ophthalmic Drug Delivery Systems Market
Pharmaceuticals
Prescription Drugs Market
Pharmaceuticals
Hyperphosphatemia Drugs Market