
 Saudi Arabia Contract Logistics Market | 2026-2036
Saudi Arabia Contract Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Contract Logistics Market Insights
E-commerce retailers are unwinding reliance on in-house fulfillment, shifting volume toward outsourced contract logistics operators. Almajdouie Group anchors heavy-lift and project cargo capabilities across the kingdom's industrial corridors. DHL Supply Chain leverages multi-client campus models near King Abdullah Economic City. Agility Logistics competes through dedicated pharmaceutical and healthcare verticals.
Contract logistics denotes the comprehensive outsourcing of supply chain execution—including inventory management, order fulfillment, and distribution coordination—under long-term service agreements with measurable performance parameters. Temperature-controlled warehousing and real-time inventory visibility systems constitute core technical infrastructure for pharmaceutical and food-grade operations. Transportation services command the largest revenue share within service type segmentation, while last mile delivery exhibits the fastest structural expansion due to e-commerce proliferation. Within industry verticals, pharmaceutical logistics carries premium margin pools driven by serialization and cold-chain compliance requirements.
SFDA cold-chain regulations and SASO quality certification frameworks elevate operational barriers for contract logistics providers serving regulated sectors. The General Authority of Civil Aviation and Saudi Ports Authority coordinate customs modernization and air-freight clearance protocols that directly shape market access timelines. Stakeholders must monitor Vision 2030 industrial cluster development to align capacity investments with demand formation across NEOM, the Red Sea Project, and existing manufacturing zones.
Market Dynamics
E-commerce fulfillment outsourcing is compressing contract logistics timelines across Saudi Arabia, forcing operators to deploy real-time inventory systems and same-day delivery networks to capture volume from digital retailers unwinding in-house operations.
Growth Catalysts
- SFDA cold-chain mandates:Pharmaceutical serialization and temperature-control requirements are pulling specialized warehousing investment into Riyadh and Jeddah industrial zones.
- Vision 2030 industrial clusters:NEOM and Red Sea Project developments are generating concentrated demand for project cargo and heavy-lift logistics capabilities.
- Warehouse automation:Automated storage and retrieval systems are reducing labor dependency and accelerating order fulfillment velocity for e-commerce clients.
Market Restraints
- Labor cost escalation:Expatriate visa restrictions and Saudization quotas are compressing margins for labor-intensive picking and packing operations.
- Real estate concentration:Premium warehousing stock clusters around King Abdullah Economic City and Dammam, limiting expansion options for secondary-market entrants.
- Technical infrastructure gaps:Real-time visibility platforms require redundant connectivity that remains inconsistent outside Riyadh and Jeddah corridors.
Strategic Opportunities
- Tabuk and Asir underpenetration:Northern and southern provinces lack temperature-controlled capacity for pharmaceutical distribution, creating first-mover positioning for compliant operators.
- Cross-border e-commerce integration:SASO quality certification alignment with GCC customs protocols enables unified fulfillment across Gulf markets from Saudi hubs.
- Blockchain-IoT convergence:Immutable chain-of-custody records combined with sensor telemetry are opening premium service tiers for high-value cargo segments.
Industry Challenges
- Specialized technician scarcity:Cold-chain equipment maintenance and WMS platform administration require skills that outpace local vocational pipeline output.
- Multi-client integration complexity:Shared warehouse management systems must reconcile incompatible ERP protocols from pharmaceutical, retail, and industrial clients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Contract Logistics Market |
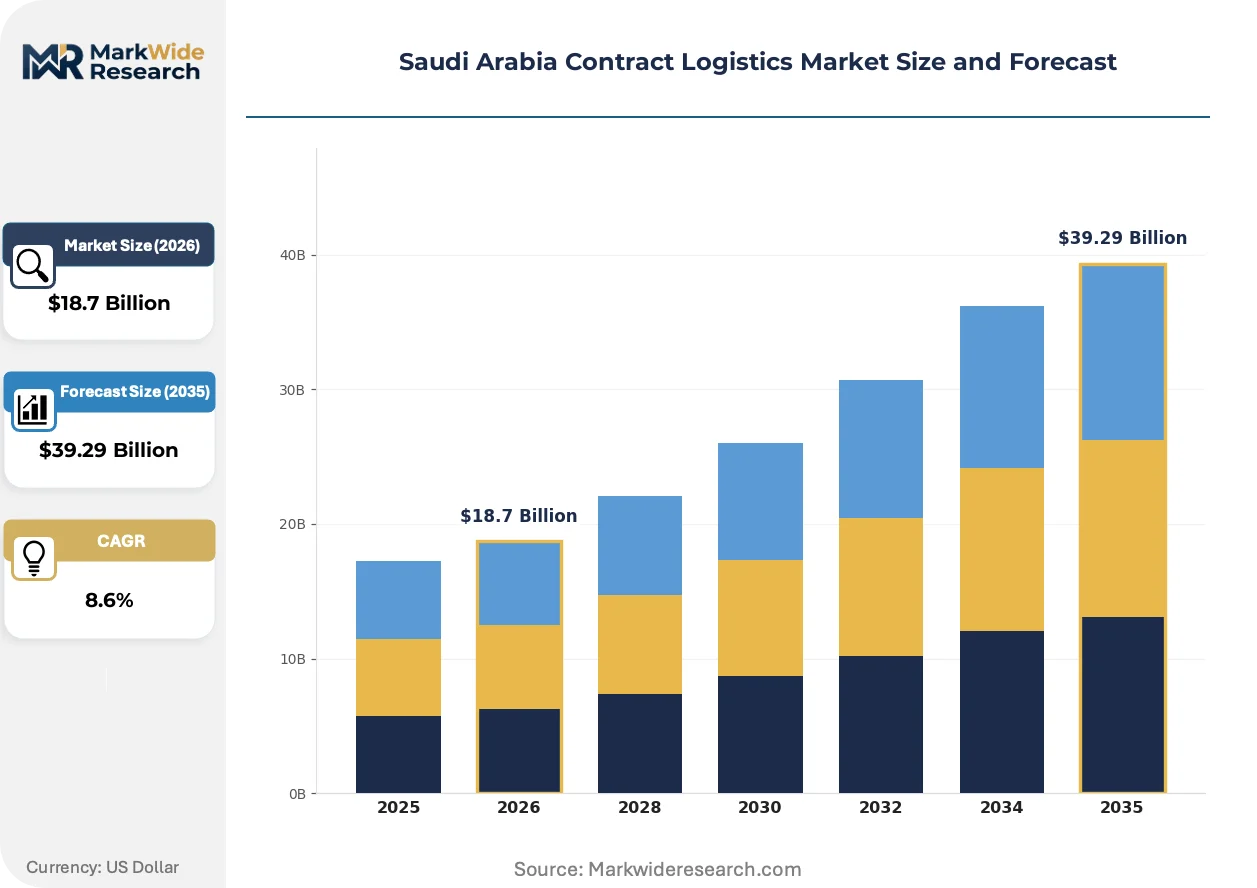
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Last Mile Delivery Industry Vertical: Retail, Automotive, Pharmaceutical, E-Commerce Delivery Model: Dedicated, Shared, Hybrid, Cross-Docking Client Type: SMEs, Corporates, Startups, Multinationals |
| Companies Covered | Wared Logistics, Kuehne + Nagel, Almajdouie Group, Agility Logistics, DSV, Aramex, GAC, DB Schenker, DHL Supply Chain, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Contract Logistics Market Trends and Innovations
Digital fulfillment infrastructure is rewiring competitive requirements across Saudi contract logistics, with automation, regulatory compliance technology, and buyer behavior shifts converging to redefine service differentiation.
Autonomous mobile robots are fragmenting traditional warehouse labor models in Saudi distribution centers. E-commerce retailers with volatile SKU proliferation are deploying AMR fleets for dynamic slotting and batch picking. This technology is fragmenting the historical dominance of fixed automation, enabling mid-scale operators to achieve throughput parity with capital-intensive campus models.
SFDA serialization mandates are forcing pharmaceutical supply chain transparency investments. Track-and-trace systems must capture unit-level movement from manufacturer to patient, elevating data infrastructure to core competitive capability. Cold-chain operators serving Riyadh's medical device clusters are consolidating compliance platforms to amortize certification costs across multiple client portfolios.
Consolidated buying by omnichannel retailers is compressing supplier rosters for fulfillment services. Department store chains and grocery conglomerates are bundling warehousing, transport, and last-mile under single-source agreements. This concentration is most visible in Jeddah, where port-adjacent logistics parks are capturing multi-year contracts from regional retail headquarters.
Saudi Arabia Contract Logistics Market Segmentation
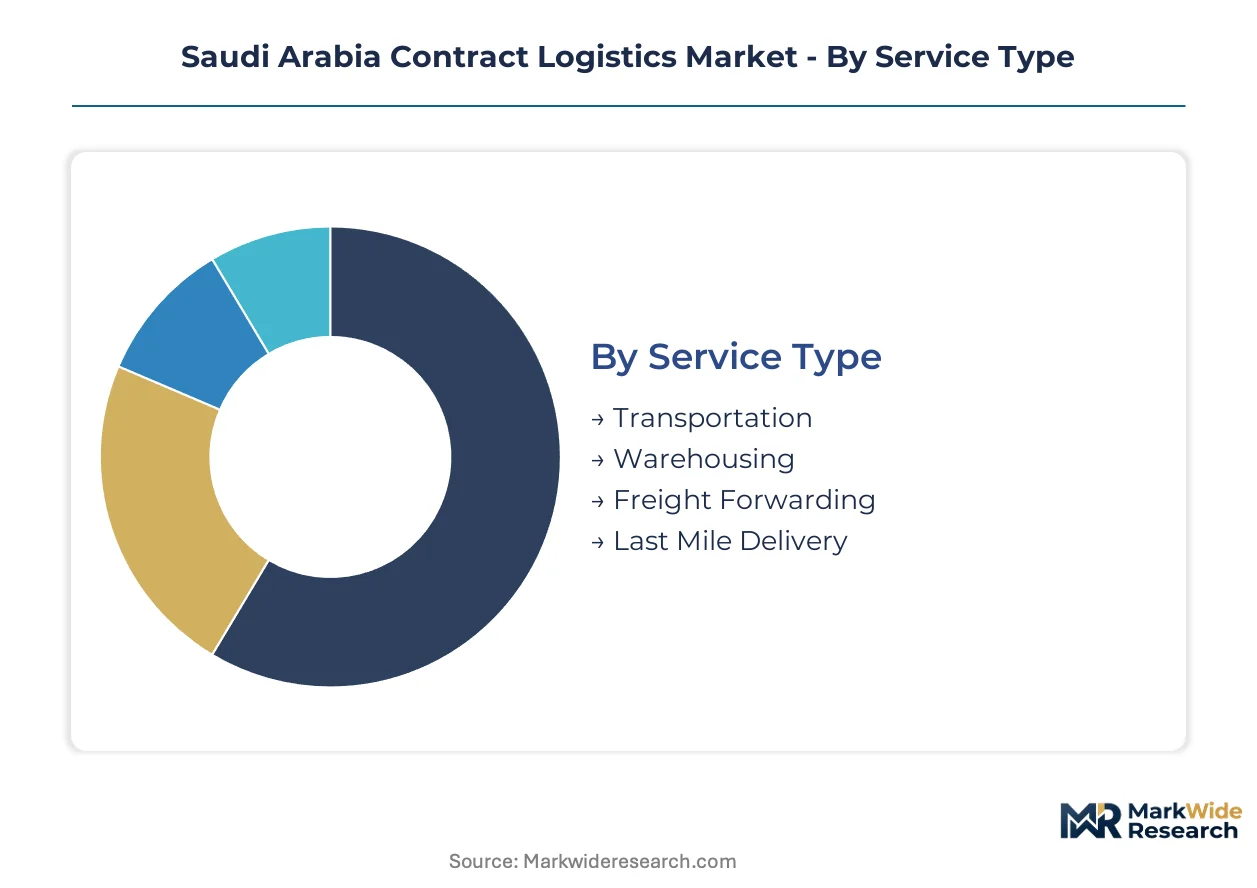
Service configuration across Saudi contract logistics channels determines which capabilities capture margin and which segments face commoditization pressure. Understanding how demand flows through dedicated versus shared infrastructure clarifies where operators should concentrate capital deployment.
Service Type:
Transportation and warehousing services flow through distinct commercial channels, with asset-heavy segments commanding long-term contracts and variable-cost services capturing spot-market volume.
- Transportation:Fleet-based road freight and intermodal services constitute the revenue foundation for most contract logistics operators. Riyadh-Jeddah corridor demand concentrates around automotive parts distribution and retail replenishment cycles. SFDA cold-chain mandates are pulling refrigerated fleet investment away from general cargo capacity.
- Warehousing:Temperature-controlled and ambient storage facilities anchor multi-year agreements with pharmaceutical and e-commerce clients. King Abdullah Economic City and Dammam industrial zones concentrate premium stock, forcing secondary-market operators toward Jazan and Tabuk for expansion.
- Freight Forwarding:Customs brokerage and air-ocean coordination services integrate with port modernization timelines at Jeddah Islamic Port and King Abdulaziz Port.
- Last Mile Delivery:Same-day and next-day networks are expanding most quickly as e-commerce retailers unwind in-house fulfillment operations.
By volume, Transportation leads. By growth pace, Last Mile Delivery is ahead.
Industry Vertical:
Margin concentration varies sharply across verticals, with compliance requirements and inventory velocity determining which sectors sustain premium pricing.
- Pharmaceutical:Serialization mandates and cold-chain integrity requirements elevate technical barriers. SFDA track-and-trace regulations force unit-level visibility investments that generalist operators cannot amortize.
- E-Commerce:Volatile SKU proliferation and returns processing complexity favor automated campuses over conventional warehousing. Jeddah and Riyadh fulfillment centers capture the bulk of digital retail volume.
- Retail:Omnichannel consolidation is bundling warehousing, transport, and last-mile under single-source agreements.
- Automotive:Just-in-sequence delivery to assembly plants and aftermarket parts distribution require specialized yard management and sequencing capabilities.
Pharmaceutical commands the steepest margin structure. E-Commerce is gaining share fastest.
Delivery Model:
Asset configuration determines cost flexibility, with dedicated infrastructure locking in volume commitments and shared models offering variable-cost alternatives.
- Dedicated:Single-client facilities and captive fleets serve high-volume pharmaceutical and automotive contracts with guaranteed throughput commitments.
- Shared:Multi-client campuses aggregate demand from SMEs and mid-market retailers, achieving scale economies that individual shippers cannot replicate.
- Hybrid:Segregated inventory zones within shared facilities balance dedicated service levels with pooled infrastructure costs.
- Cross-Docking:Flow-through facilities minimize inventory holding for time-definite retail and automotive replenishment.
Dedicated models dominate contract value. Shared infrastructure is expanding most quickly.
Client Type:
Procurement sophistication and contract duration separate client tiers, with multinationals demanding integrated solutions and startups prioritizing variable-cost flexibility.
- Multinationals:Global manufacturers and retailers mandate standardized KPI frameworks and multi-country service consistency.
- Corporates:Domestic conglomerates in retail and industrial sectors drive bundled logistics procurement across Vision 2030 project corridors.
- SMEs:Mid-sized manufacturers and distributors favor shared warehousing and freight consolidation to avoid fixed-cost exposure.
- Startups:E-commerce entrants and niche pharmaceutical distributors prioritize pay-per-use models and rapid scaling flexibility.
Corporates anchor contract value. Startups are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jeddah Islamic Port anchors Saudi Arabia's contract logistics infrastructure, handling over half the kingdom's maritime freight and feeding distribution corridors into Riyadh and the Eastern Province.
Riyadh
Automotive assembly plants and pharmaceutical manufacturing clusters drive warehousing demand in the capital region. SFDA serialization mandates force cold-chain operators to deploy track-and-trace infrastructure across King Salman Industrial City facilities. Almajdouie Group maintains heavy-lift yards near the Dry Port to serve machinery and project cargo flows.
Eastern Province
Petrochemical feedstock movements and industrial zone expansion around Jubail and Ras Al-Khair concentrate bulk logistics contracts. The Saudi Ports Authority's modernization of King Abdulaziz Port accelerates customs clearance timelines for containerized imports. Dammam's logistics parks capture automotive parts distribution contracts serving regional assembly plants.
Western Region
Pilgrimage traffic and Red Sea tourism development generate seasonal surges in freight forwarding and temporary warehousing demand. King Abdullah Economic City hosts multi-client campus models that aggregate e-commerce fulfillment volume. Port modernization at Jeddah Islamic Port enables direct vessel calls that bypass transshipment through regional hubs.
NEOM Northwest
The linear city development and associated industrial clusters are pulling project cargo and construction logistics capabilities northward from established bases. NEOM's regulatory sandbox framework permits pilot deployments of autonomous warehouse systems and drone delivery networks. Oxagon's industrial zone is pre-leasing dedicated logistics facilities to operators serving renewable energy and advanced manufacturing tenants.
Saudi Arabia Contract Logistics Market Competitive Landscape
Listed leaders compete with private specialists across capital access and operational flexibility. The Saudi market exhibits tiered concentration, with global integrators capturing multinational contracts while domestic groups defend local relationships. Three archetypes dominate: diversified conglomerates with captive logistics arms, pure-play contract operators with vertical specialization, and freight forwarders extending into value-added warehousing. Capacity expansion near King Abdullah Economic City and technology licensing partnerships for warehouse automation represent the primary competitive vectors.
Within the diversified conglomerate tier, Almajdouie Group exemplifies heavy-lift and project cargo capabilities anchored across industrial corridors. Among global integrators, DHL Supply Chain and Agility Logistics occupy positions defined by multi-client campus models and pharmaceutical vertical specialization respectively. These operators represent contrasting strategic postures: capital-intensive dedicated infrastructure versus shared-platform scale economics.
| Leading Market Players |
|---|
| Wared Logistics |
| Kuehne + Nagel |
| Almajdouie Group |
| Agility Logistics |
| DSV |
| Aramex |
| GAC |
| DB Schenker |
| DHL Supply Chain |
| Others |
Pricing and Supply Chain Analysis
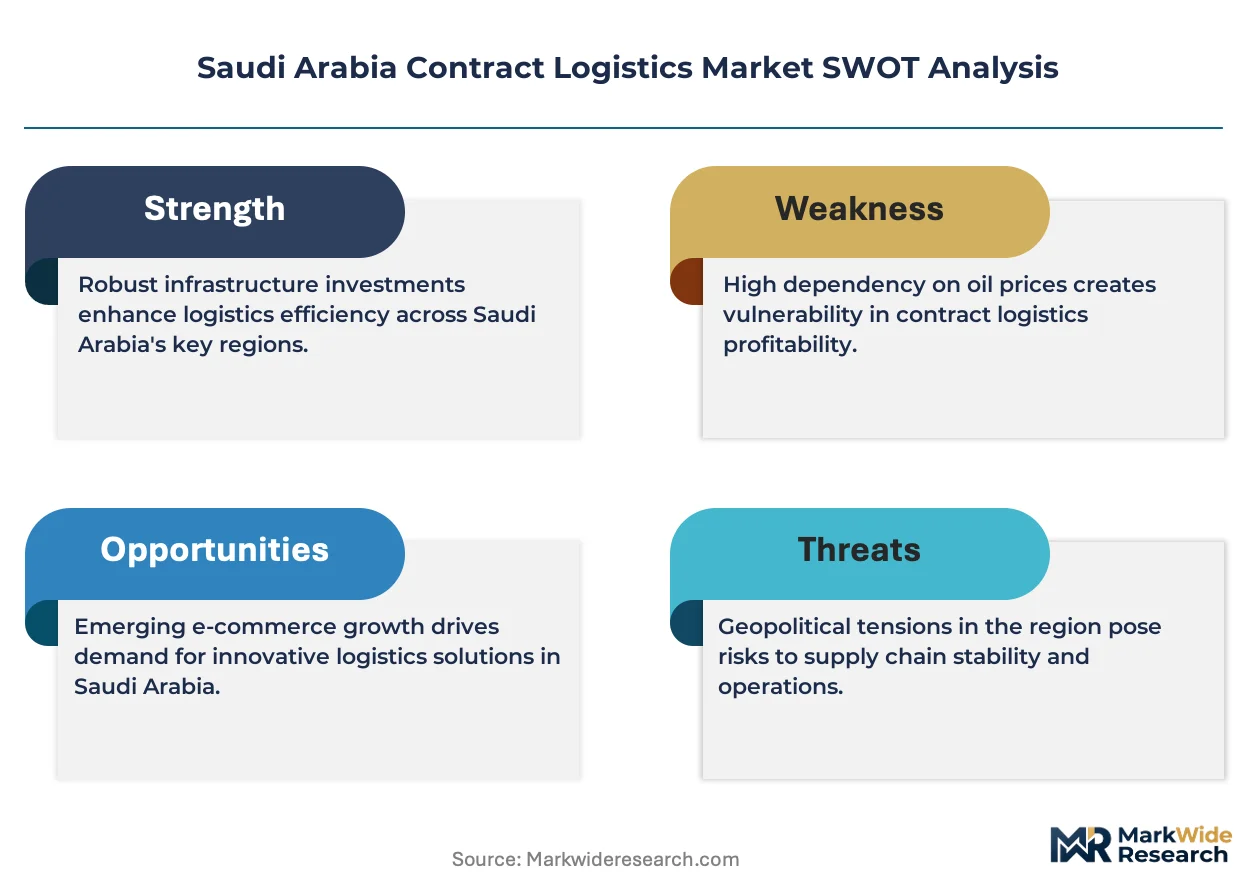
SFDA cold-chain certification gates both warehouse qualification and rate tiering simultaneously, forcing operators to amortize compliance investments across premium service tiers while excluding uncertified competitors from pharmaceutical margin pools.
Pricing Analysis
Volume-discount tiering structures separate dedicated contract rates from shared-facility spot pricing across Riyadh and Jeddah corridors. Three-tier pricing stratifies across certified cold-chain, ambient bonded warehousing, and unbonded general storage levels, with SFDA serialization compliance and automated inventory systems driving premium differentiation. Cost compression in shared warehousing intensifies because mid-scale operators deploy AMR fleets to match campus-model throughput. SME e-commerce entrants exhibit highest price sensitivity, while multinational pharmaceutical manufacturers accept rate premiums for guaranteed cold-chain integrity.
Supply Chain Analysis
Inbound logistics costs fluctuate with Jeddah Islamic Port container availability and Red Sea transshipment lane reliability, compressing margins for operators dependent on imported automation equipment and packaging materials. Warehouse construction materials draw from China, UAE, and Turkey, while cold-chain equipment rests on German and Japanese component sourcing. Single-source vulnerability concentrates in European refrigeration compressor supply, with limited qualified alternatives for SFDA-compliant pharmaceutical operations. Distribution runs through King Abdullah Economic City multi-client campuses feeding last-mile networks into Riyadh and Jeddah urban cores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi contract logistics represents a high-growth disruption as Vision 2030 industrial cluster formation and SFDA regulatory mandates simultaneously expand addressable demand and erect technical barriers to entry.
For Market Incumbents: Compound cold-chain certification advantages by extending track-and-trace infrastructure into Tabuk and Asir provinces before competitors achieve SFDA compliance. Defend against AMR-enabled mid-scale challengers through captive integration into automated storage and retrieval system maintenance capabilities. Lock in multi-year pharmaceutical contracts with guaranteed throughput commitments that amortize regulatory infrastructure across client portfolios. For New Entrants and Emerging Players: Anchor in temperature-controlled pharmaceutical distribution across northern and southern provinces where compliant capacity scarcity creates first-mover positioning. Target shared warehousing models for SME e-commerce retailers unwinding in-house fulfillment, offering pay-per-use flexibility that dedicated operators cannot match. Pursue SASO certification alignment with GCC customs protocols to enable cross-border fulfillment scale from Saudi hubs. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated warehouse infrastructure as AMR deployment and WMS platform investments displace labor-dependent models. Long-term viability favors operators with demonstrated SFDA compliance track records and established relationships with Vision 2030 project developers. Acquisition target archetype: mid-scale regional operators with underutilized warehouse licenses in secondary markets. Signal to watch: SFDA expansion of serialization mandates to medical devices, which would replicate pharmaceutical infrastructure requirements across adjacent verticals.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Cold-Chain Certification Investment | Pharmaceutical serialization mandates force unit-level visibility infrastructure that generalist operators cannot replicate. |
| AMR Fleet Deployment | Autonomous mobile robots enable mid-scale operators to achieve throughput parity with capital-intensive campus models. |
| Multi-Client Campus Expansion | King Abdullah Economic City aggregation models capture e-commerce volume from retailers unwinding in-house fulfillment. |
| Provincial Temperature-Controlled Buildout | Tabuk and Asir underpenetration creates first-mover positioning for compliant pharmaceutical distribution operators. |
| GCC Cross-Border Integration | SASO certification alignment with Gulf customs protocols enables unified fulfillment scale from Saudi logistics hubs. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Saudi Ports Authority modernization disclosures, SFDA regulatory filings, and Vision 2030 industrial cluster development timelines. Interviews with contract logistics operations directors, pharmaceutical supply chain managers, e-commerce fulfillment leads, and warehouse automation specialists combined with analysis of customs trade data, industrial zone lease records, and cold-chain equipment import statistics. Bottom-up facility capacity assessments triangulate against top-down market size estimates derived from service revenue aggregation.
Segmentation dimensions modeled include service type, industry vertical, delivery model, and client type across the projection horizon. CAGRs derive from weighted capacity expansion schedules, e-commerce penetration trajectories, and pharmaceutical regulatory compliance timelines. Forecast inputs incorporate Vision 2030 project cargo flow projections and SFDA serialization mandate implementation phases.
Material uncertainties — Red Sea shipping lane disruptions, expatriate visa policy shifts, and SFDA regulatory scope expansion — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained industrial zone development and cold-chain infrastructure investment continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Finished Vehicle Logistics Market
Logistics and Shipping
South Korea International Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Canada Road Freight Transport Market
Logistics and Shipping
Germany Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
US FTL Brokerage Market
Logistics and Shipping
North America Cross Border Road Freight Transport Market
Logistics and Shipping
Sweden Courier, Express, and Parcel Market
Logistics and Shipping
Liquid Chemical Tanker Shipping Market
Logistics and Shipping
Slovakia Freight and Logistics Market
Logistics and Shipping
Asean Freight Forwarding Market
Logistics and Shipping
Manufacturing Logistics Market
Logistics and Shipping
Europe Chemical Logistics Market
Logistics and Shipping
Germany Contract Logistics Market
Logistics and Shipping
Digital Freight Forwarding Market
Logistics and Shipping
China Cold Chain Logistics Market
Logistics and Shipping
North America Same Day Delivery Market