
 Spain 3PL Market | 2026-2036
Spain 3PL Market Size, Share, and Industry Trends Forecast 2026-2036
Spain 3PL Market Analytics
Buyer concentration among Spanish e-commerce platforms is rebalancing toward mid-market retailers seeking flexible fulfillment partnerships. DHL Supply Chain leverages its pan-European network to anchor large-scale warehousing contracts in the Madrid region. Naeko specializes in temperature-controlled logistics for pharmaceutical clients, occupying a defensible niche against generalist competitors. Kuehne + Nagel extends its digital freight platform to compete on visibility and rate transparency across Iberian trade lanes.
Third-party logistics (3PL) encompasses outsourced transportation, warehousing, and inventory management services performed under contract by external providers rather than in-house fleets or facilities. The sector operates through asset-light network orchestration, where providers coordinate owned and contracted capacity across road, rail, and short-sea modes to optimize cost per pallet-kilometer for shippers. Warehousing services lead current revenue pools due to sustained demand for bonded storage and e-commerce fulfillment centers near Barcelona and Valencia ports. Transportation segments face margin compression from fuel cost pass-through structures, while freight forwarding benefits from volatile capacity pricing on Asia-Europe routes. IoT Solutions within the technology segment is expanding fastest as shippers mandate real-time container tracking and predictive delay alerts.
Spain's logistics sector operates under EU Green Deal emissions targets enforced by national climate regulators, with truck fleet decarbonization timelines accelerating contract renewals toward electric and alternative-fuel vehicle operators. The country's national transport regulator enforces driver hour limits and cabotage rules that shape cross-border capacity allocation and subcontractor qualification standards. Stakeholders must monitor how Madrid's sustainable mobility ordinances and Barcelona's low-emission zone expansions will restrict diesel vehicle access to urban distribution nodes, forcing warehouse relocation or fleet replacement decisions before regulatory deadlines tighten.
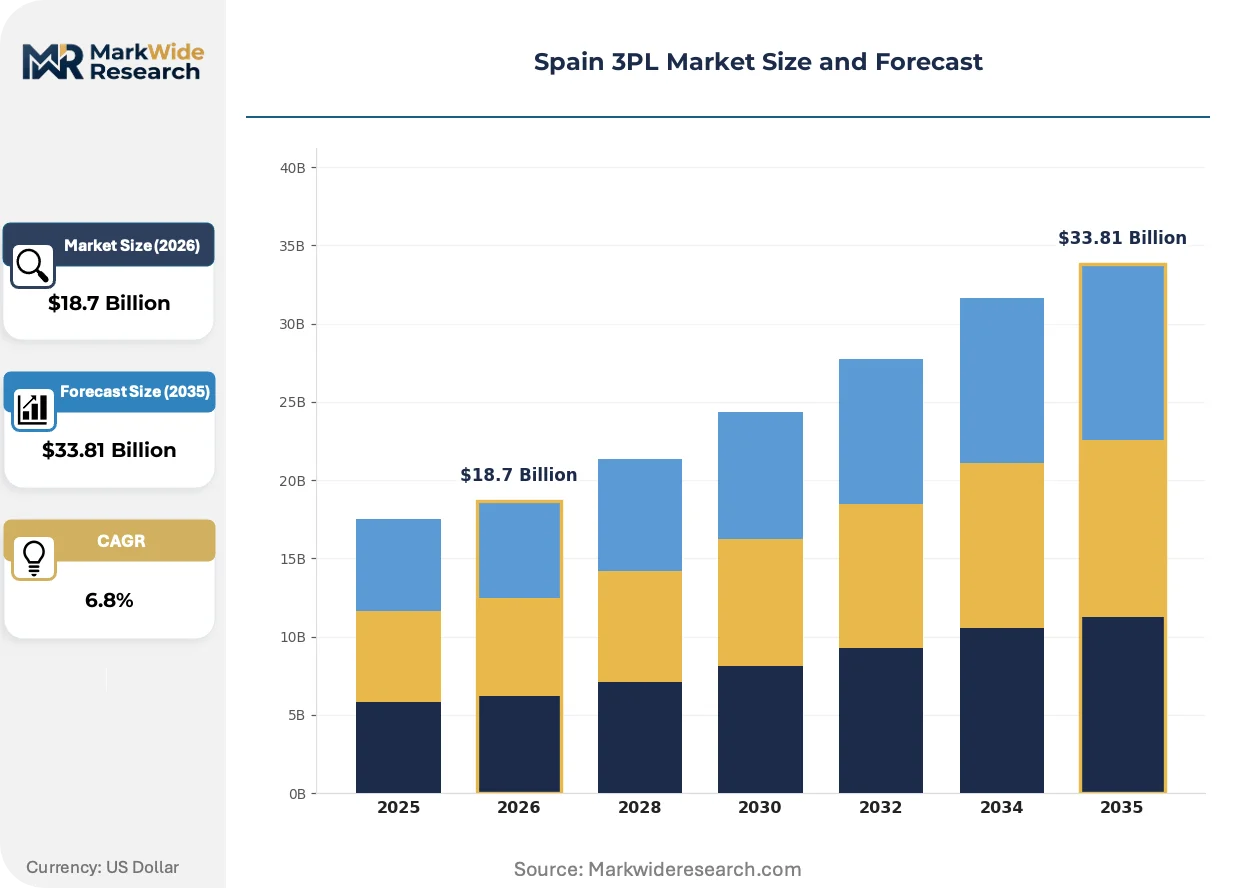
Market Dynamics
The EU Green Deal's tightening emissions standards are forcing Spanish 3PL providers to reconfigure fleet compositions and warehouse locations ahead of regulatory deadlines. This structural pressure is compressing contract renewal cycles and favoring operators with capital reserves for electric vehicle acquisition.
Growth Catalysts
- EU Green Deal compliance mandates:Truck fleet decarbonization timelines are accelerating demand for alternative-fuel logistics operators. Shippers now prioritize providers with certified low-emission vehicle fleets for long-term contracts.
- E-commerce fulfillment concentration:Mid-market Spanish retailers are consolidating outsourced logistics partnerships around flexible warehousing models. This demand pull concentrates investment in the Madrid-Barcelona corridor.
- IoT-enabled visibility platforms:Real-time container tracking and predictive delay alerts are becoming standard contract requirements. Pharmaceutical and perishable goods shippers mandate these capabilities for cold chain integrity.
Market Restraints
- Diesel fleet obsolescence risk:Madrid's sustainable mobility ordinances and Barcelona's low-emission zone expansions threaten asset values for conventional vehicle operators. Warehouse relocation costs compound this stranded asset exposure.
- Fuel cost pass-through compression:Transportation segments face margin erosion as fuel price volatility transfers directly to shippers through index-linked contracts. This limits pricing power during capacity shortages.
- Cross-border capacity fragmentation:National cabotage rules and driver hour limits restrict subcontractor qualification standards. Iberian operators struggle to optimize pan-European load consolidation.
Strategic Opportunities
- Andalusian port hub development:Valencia and Algeciras multimodal infrastructure investments create capacity for Asia-Europe freight forwarding expansion. Bonded storage demand concentrates near these gateway terminals.
- Temperature-controlled pharmaceutical logistics:Specialized cold chain capabilities remain underpenetrated relative to generic warehousing. Naeko's niche positioning demonstrates defensible margin potential.
- Rail-road intermodal integration:EU Green Deal subsidies for rail freight are expanding multimodal hub viability. Operators capturing this infrastructure access gain cost advantages on continental routes.
Industry Challenges
- Electric vehicle technician scarcity:Fleet electrification timelines outpace qualified maintenance workforce availability. Training pipelines for high-voltage systems remain underdeveloped across Iberian technical institutes.
- Legacy warehouse management system integration:Real-time IoT platform deployment requires costly retrofitting of existing facilities. Mid-tier operators face disproportionate capital burdens relative to scale economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain 3PL Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Distribution, Freight Forwarding End User: Retail, Automotive, Consumer Goods, Healthcare Delivery Model: Just-In-Time, Drop Shipping, Cross-Docking, Direct Shipping Technology: Warehouse Management Systems, Freight Management Software, Robotics, IoT Solutions |
| Companies Covered | FM Logistic, Naeko, Carcaba, DHL Supply Chain, Rhenus Logistics, CEVA Logistics, Groupe CAT, Kuehne + Nagel, DSV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain 3PL Market Evolving Landscape
Digital freight platforms and emissions tracking technologies are restructuring competitive differentiation in Spanish logistics. Providers now compete on data transparency rather than asset ownership alone.
Blockchain-enabled documentation systems are expanding into customs clearance and bonded warehouse operations. Pharmaceutical exporters and automotive manufacturers adopt these platforms for audit trail compliance. This technology is compressing administrative processing times and reducing documentation disputes at Valencia and Barcelona ports.
EU Green Deal enforcement by Spain's national climate regulators is mandating Scope 3 emissions disclosure across logistics contracts. Shippers now require verified carbon footprint reporting from 3PL partners. Heavy-haul and long-distance transportation segments face the steepest compliance cost escalations.
Mid-market e-commerce retailers are consolidating vendor relationships around integrated fulfillment partners. Small parcel specialists and pure-play transportation providers lose share to warehouse-capable operators. This concentration is most visible among Barcelona-based fashion and consumer electronics sellers seeking single-source logistics accountability.
Spain 3PL Market Segmentation
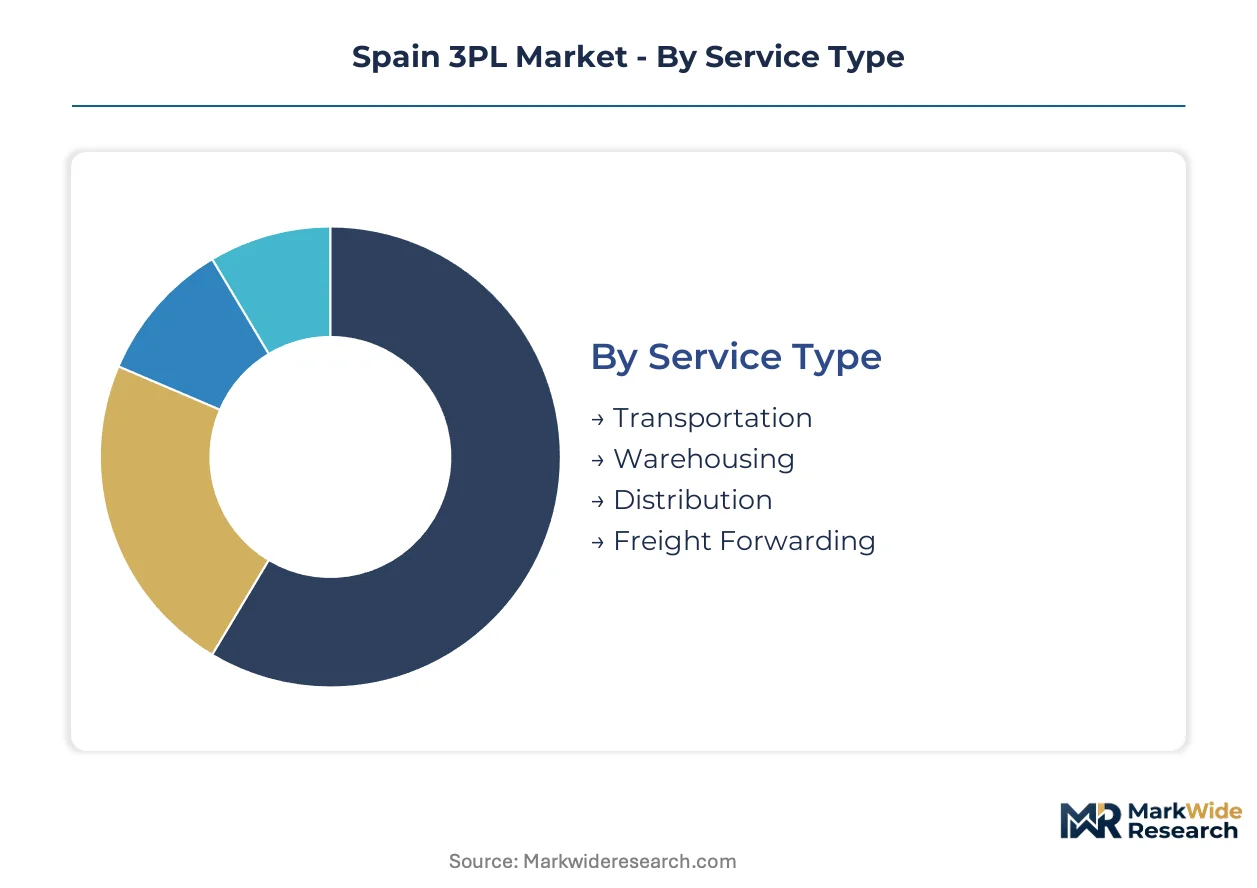
Spanish 3PL segmentation reflects divergent certification burdens across service types and end-use verticals. Pharmaceutical logistics demands GDP compliance, while automotive contracts require IATF quality management. Technology adoption varies sharply by segment, creating tiered competitive barriers.
Service Type:
Warehouse Management Systems and cold chain infrastructure require GDP certification for pharmaceutical clients, while bonded storage operations need AEO authorization from Spanish customs authorities. Transportation fleets face escalating EU Green Deal emissions verification.
- Transportation:Road, rail, and short-sea coordination under contract, with fleet operators now required to demonstrate EU Green Deal emissions compliance for contract renewal. Diesel vehicle operators face stranded asset risk as Madrid and Barcelona low-emission zones tighten access restrictions.
- Warehousing:Bonded storage and e-commerce fulfillment infrastructure, commanding premium rates near Valencia and Barcelona ports. AEO-certified facilities capture pharmaceutical and automotive contracts requiring customs-secure inventory segregation.
- Distribution:Last-mile and regional consolidation services, with urban access permits becoming critical as municipal sustainable mobility ordinances restrict conventional vehicle entry. Electric van adoption concentrates in Madrid-Barcelona corridor operations.
- Freight Forwarding:Multimodal documentation and customs brokerage, benefiting from volatile Asia-Europe capacity pricing. Blockchain-enabled documentation platforms are compressing administrative processing times at Iberian gateway terminals.
Warehousing sits at the top of the volume ranking, with Freight Forwarding climbing the fastest.
End User:
Customer concentration patterns split between high-certification healthcare logistics and volume-driven retail fulfillment. Margin structures diverge accordingly.
- Retail:E-commerce fulfillment dominates, with mid-market Spanish retailers consolidating around flexible warehouse partnerships. Seasonal demand spikes require surge capacity contracts near Barcelona fashion and consumer electronics clusters.
- Automotive:Just-in-time sequencing and sequenced parts delivery, mandating IATF quality management certification. Production line stoppage penalties enforce stringent service level agreements.
- Consumer Goods:High-volume, low-margin distribution requiring scale economies in pallet consolidation. Cross-docking efficiency determines contract awards from FMCG manufacturers.
- Healthcare:Temperature-controlled pharmaceutical logistics with GDP compliance mandatory. Naeko and specialized operators command defensible margins against generalist competitors in this underpenetrated niche.
Retail captures the largest revenue pool, while Healthcare delivers the steepest margin expansion.
Delivery Model:
Operational complexity and capital intensity separate models, with real-time visibility requirements escalating across all categories.
- Just-In-Time:Precision-scheduled inventory arrival synchronized to production or sales velocity. Automotive and industrial clients impose penalty clauses for delivery window failures.
- Drop Shipping:Direct vendor-to-consumer fulfillment without retailer inventory holding. E-commerce platforms favor this model for SKU breadth without warehouse capital commitment.
- Cross-Docking:Minimal dwell time consolidation, with goods flowing directly from inbound to outbound transport. FMCG and retail distributors optimize for pallet-level sorting velocity.
- Direct Shipping:Point-to-point transport bypassing intermediate handling, common in bulk industrial and project cargo movements.
Just-In-Time maintains the highest contract value concentration, with Drop Shipping expanding most quickly among digital-native retailers.
Technology:
Deployment costs and integration complexity create tiered adoption barriers, with mid-tier operators facing disproportionate capital burdens.
- Warehouse Management Systems:Core inventory control and order fulfillment orchestration platforms. Legacy system retrofitting for real-time IoT integration imposes heavy capital requirements on established operators.
- Freight Management Software:Digital platforms for rate transparency and load matching. Kuehne + Nagel extends these capabilities across Iberian trade lanes to compete on visibility.
- Robotics:Automated picking and sortation systems, concentrated in high-throughput e-commerce fulfillment centers near Madrid and Barcelona.
- IoT Solutions:Real-time container tracking and predictive delay alerts, now standard contract requirements for pharmaceutical and perishable goods shippers. This segment expands most quickly as cold chain integrity mandates tighten.
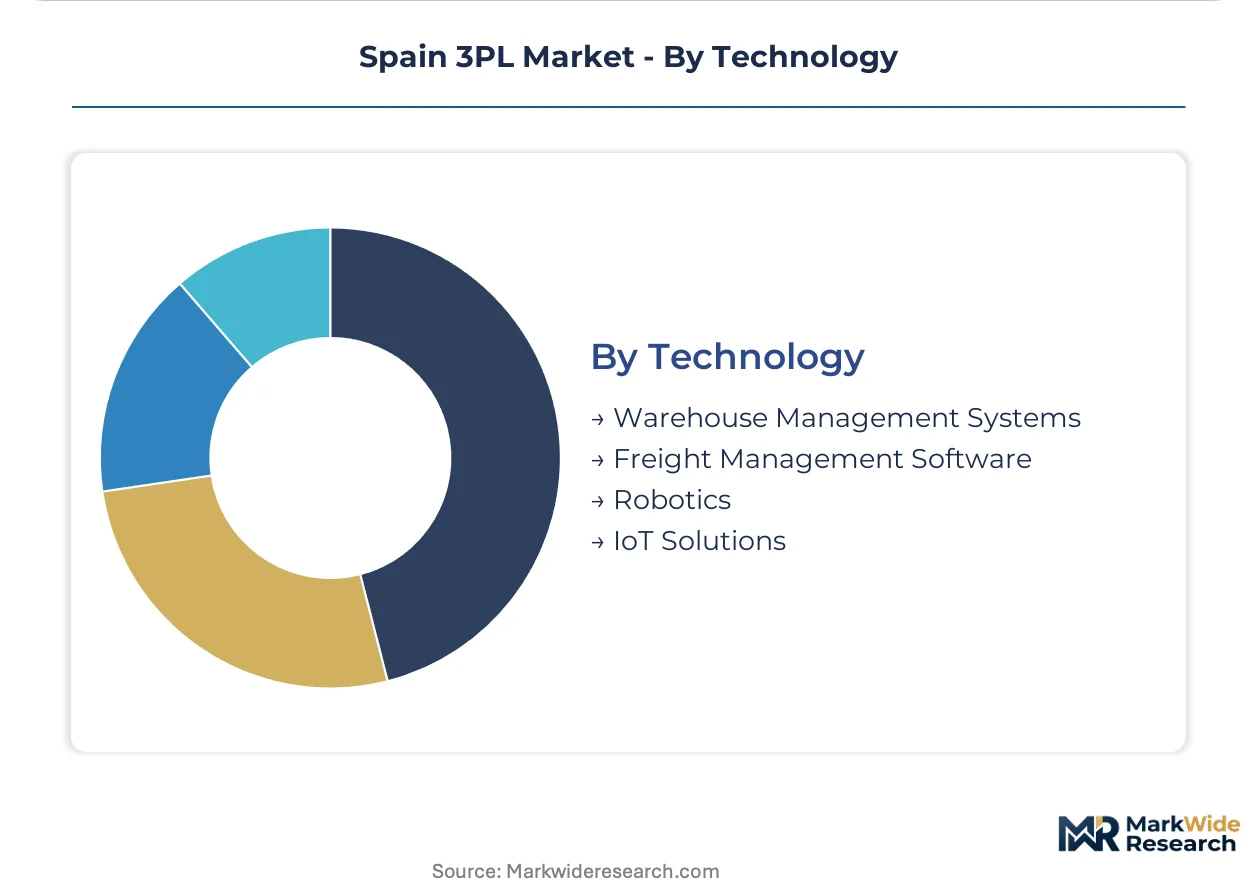
Warehouse Management Systems anchor current technology spending, with IoT Solutions gaining share fastest on shipper compliance demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
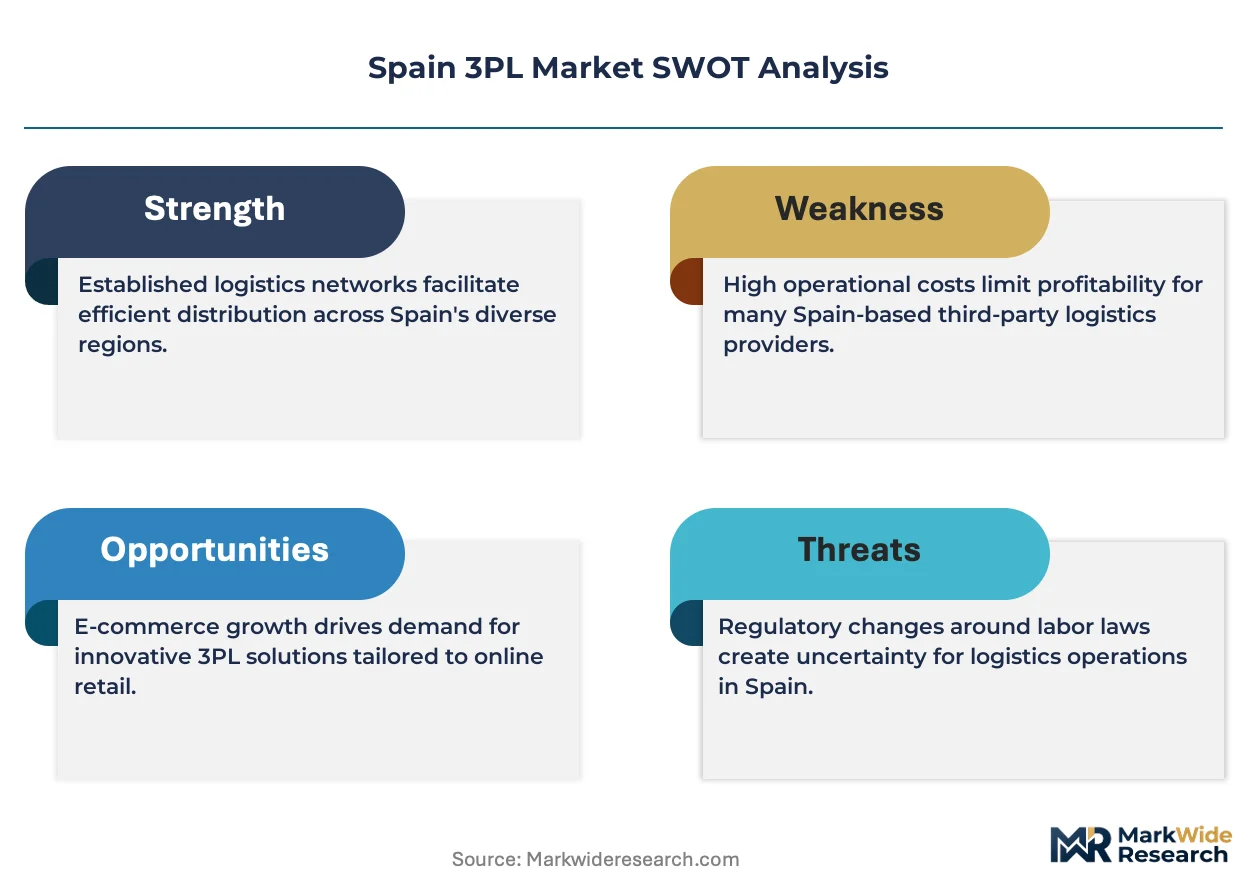
Germany and Spain operate divergent logistics models despite shared EU Green Deal obligations, with German operators leveraging rail density while Spanish providers confront Iberian peninsula isolation and stricter urban access restrictions.
Madrid
The capital anchors Spain's largest warehousing cluster, with e-commerce fulfillment demand driving speculative development in the Corredor del Henares logistics belt. Madrid's sustainable mobility ordinances restrict diesel vehicle access to urban distribution nodes, forcing fleet replacement timelines. Multimodal hubs in Coslada and San Fernando de Henares connect road networks to continental rail corridors.
Catalonia
Barcelona commands the second-largest logistics concentration, with port-linked bonded storage facilities serving automotive and pharmaceutical exporters. The city's low-emission zone expansion tightens conventional vehicle access to metropolitan distribution centers. Zona Franca industrial parks concentrate temperature-controlled warehousing for perishable goods trade.
Valencia
Spain's busiest container port drives freight forwarding and customs brokerage specialization along the Mediterranean corridor. EU Green Deal subsidies for rail freight are expanding intermodal connectivity to Madrid and Barcelona. Sagunto and Puerto de Valencia logistics zones attract Asia-Europe transshipment investment.
Andalusia
Algeciras Bay positions the region as a gateway for Atlantic and Mediterranean shipping routes, with bonded storage demand concentrating near the port complex. The Andalusian regional government promotes logistics park development to capture transshipment volume. Seville's river port adds multimodal capacity for agricultural and industrial bulk movements.
Basque Country
Bilbao's port infrastructure supports automotive and machinery exports to Northern European markets, with just-in-time sequencing contracts requiring stringent service level agreements. The Basque industrial cluster generates specialized project cargo and heavy-haul demand. EU emissions verification requirements shape contract renewal patterns among local fleet operators.
Spain 3PL Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Spain's 3PL sector, creating a tiered structure where scale advantages clash with niche certification depth. The market fragments between pan-European network operators and regional Iberian specialists. Three archetypes dominate: integrated global networks, temperature-controlled specialists, and port-centric forwarding agents. Capacity expansion and fleet electrification represent the dominant competitive moves as EU Green Deal deadlines approach.
Among global network operators, DHL Supply Chain and Kuehne + Nagel exemplify the integrated archetype, leveraging digital freight platforms and cross-border coordination capabilities. Naeko occupies a distinct position within the temperature-controlled tier, demonstrating how pharmaceutical logistics specialization commands defensible margins against generalist competitors.
| Leading Market Players |
|---|
| FM Logistic |
| Naeko |
| Carcaba |
| DHL Supply Chain |
| Rhenus Logistics |
| CEVA Logistics |
| Groupe CAT |
| Kuehne + Nagel |
| DSV |
| Others |
Value Network & Pricing Analysis
Diesel fuel price indices cascade through Spanish 3PL cost structures, compressing margins for conventional fleet operators while amplifying rate premiums for EU Green Deal-certified electric vehicle providers. This commodity pass-through mechanism stratifies pricing tiers across the Madrid-Barcelona logistics corridor.
Pricing Analysis
Capacity additions in electric vehicle fleets are reshaping price floors for transportation contracts, with certified low-emission operators commanding premium-mid-economy pricing differentiation based on emissions compliance tier. Price differentiation hinges on AEO certification status and GDP compliance for pharmaceutical handling, with fuel cost volatility exerting downward pressure on road freight margins. Mid-market e-commerce retailers exhibit highest price sensitivity, while healthcare shippers accept rate premiums for temperature-controlled integrity guarantees.
Supply Chain Analysis
Returns processing and reverse logistics flows concentrate in Barcelona and Madrid urban distribution nodes, where municipal low-emission zone restrictions constrain diesel vehicle access for refurbishment and remanufacturing movements. Spain's 3PL sector draws fleet assets from Germany, France, and domestic manufacturers, with battery supply for electric vehicles resting on Chinese and South Korean cell production. Single-source vulnerability permeates high-voltage technician training pipelines. Distribution runs through multimodal hubs at Valencia and Algeciras before final-mile consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's 3PL market offers geographic-arbitrage value against Northern European logistics costs, with Madrid warehouse rents trading at discounts to Rotterdam or Frankfurt while maintaining EU single-market access.
For Market Incumbents: Deepen electric vehicle fleet penetration ahead of Barcelona's low-emission zone expansion deadlines. Secure AEO-certified warehouse capacity near Valencia port to defend against port-centric forwarding specialists capturing Asia-Europe transshipment volume. Consolidate subcontractor networks under unified emissions reporting to reduce Scope 3 compliance fragmentation.
For New Entrants and Emerging Players: EU Green Deal subsidies for rail freight in Spain open a window for intermodal hub operators to capture infrastructure-access advantages on Madrid-Barcelona corridors. Target temperature-controlled pharmaceutical logistics as the most penetrable niche, where GDP compliance requirements deter generalist competition. Pursue direct contracting relationships with mid-market fashion and consumer electronics sellers seeking single-source fulfillment accountability.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized cold chain operators possessing GDP certification and established pharmaceutical client relationships. Five-to-ten-year viability favors asset-light platform orchestrators over heavy fleet owners facing diesel obsolescence risk. Monitor EU Green Deal enforcement intensity and Madrid sustainable mobility ordinance implementation timelines as inflection indicators for stranded asset exposure.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Conversion Program | EU Green Deal compliance secures contract renewals from emissions-conscious shippers in retail and automotive verticals. |
| Rail-Road Intermodal Hub Development | Coslada and San Fernando de Henares multimodal connectivity reduces cost per pallet-kilometer on continental routes. |
| GDP-Certified Cold Chain Expansion | Pharmaceutical logistics specialization commands defensible margins against generalist warehousing competitors near Barcelona. |
| Blockchain Documentation Platform Deployment | Valencia and Barcelona port authorities accelerate customs clearance for AEO-certified operators adopting audit-trail systems. |
| Warehouse Management System Modernization | Real-time IoT integration meets shipper mandates for predictive delay alerts in perishable goods transportation. |
Research Methodology
Coverage spans Iberian logistics clusters, Mediterranean port authorities, and continental European trade corridors, with primary inputs from each. The research combines interviews with fleet operations directors, warehouse facility managers, pharmaceutical supply chain executives, and customs brokerage specialists with secondary validation from Spanish customs AEO registries, EU transport emissions databases, and port authority throughput statistics. Bottom-up contract value analysis triangulates against top-down sector expenditure estimates from national logistics association reports.
Rate-of-change decomposition separates volume growth from pricing dynamics across service type, end-use vertical, and technology adoption segments. The analytical framework models transportation, warehousing, distribution, and freight forwarding segments alongside delivery model and certification tier dimensions throughout the forecast period. CAGRs derive from regression analysis against EU Green Deal implementation timelines and e-commerce fulfillment demand curves, with electric vehicle adoption rates and rail freight subsidy utilization serving as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU emissions enforcement or diesel vehicle ban preemptions. Forecasts reflect documented assumptions regarding regulatory implementation schedules and shipper contract renewal patterns. Practitioners should monitor Madrid and Barcelona municipal ordinance publication dates and EU Green Deal subsidy allocation announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
WAN Connected Returnable Transport Asset Tracking Market
Logistics and Shipping
Less-Than-Truckload Market
Logistics and Shipping
Colombia Freight and Logistics Market
Logistics and Shipping
Colombia Cold Chain Logistics Market
Logistics and Shipping
China Same Day Delivery Market
Logistics and Shipping
Saudi Arabia Contract Logistics Market
Logistics and Shipping
Germany Contract Logistics Market
Logistics and Shipping
Middle East and Africa Freight & Logistics Market
Logistics and Shipping
Sweden Courier, Express, and Parcel Market
Logistics and Shipping
India less than Truckload Road Freight Transport Market
Logistics and Shipping
Europe Refrigerated Container Shipping Market
Logistics and Shipping
North America Automotive Logistics Market
Logistics and Shipping
Peru Logistics Market
Logistics and Shipping
North America Freight and Logistics Market
Logistics and Shipping
Europe Chemical Logistics Market
Logistics and Shipping
Turkey Freight and Logistics Market