
 Florida Freight and Logistics Market | 2026-2036
Florida Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Florida Freight and Logistics Market Insights
FMCSA hours-of-service reform is shifting the cost-of-entry calculus for regional carriers entering Florida's drayage and long-haul markets. CSX Corporation leverages its Jacksonville headquarters to dominate intermodal rail connections linking Florida ports to southeastern distribution networks. Crowley Maritime Corporation anchors Caribbean and Central American trade lanes through integrated ocean-land service offerings. Landstar System, Inc. competes via its agent-based model, which sustains variable-cost capacity without fixed asset exposure.
Florida freight and logistics encompasses the planning, execution, and control of goods movement across road, rail, air, and ocean modes, typically involving containerized cargo, temperature-controlled shipments, and bulk commodities moving through temperatures ranging from subtropical humidity to hurricane-disrupted corridors. Its primary commercial purpose centers on connecting Florida's port gateways, agricultural heartland, and manufacturing zones to domestic and international consumption points. Road freight absorbs the dominant volume share given Florida's peninsula geography and limited rail penetration south of Orlando, while ocean freight commands premium margin pools tied to Caribbean and Latin American re-export trade. E-commerce end users are accelerating fastest within the demand mix, pressuring same-day and next-day delivery infrastructure across the I-4 corridor.
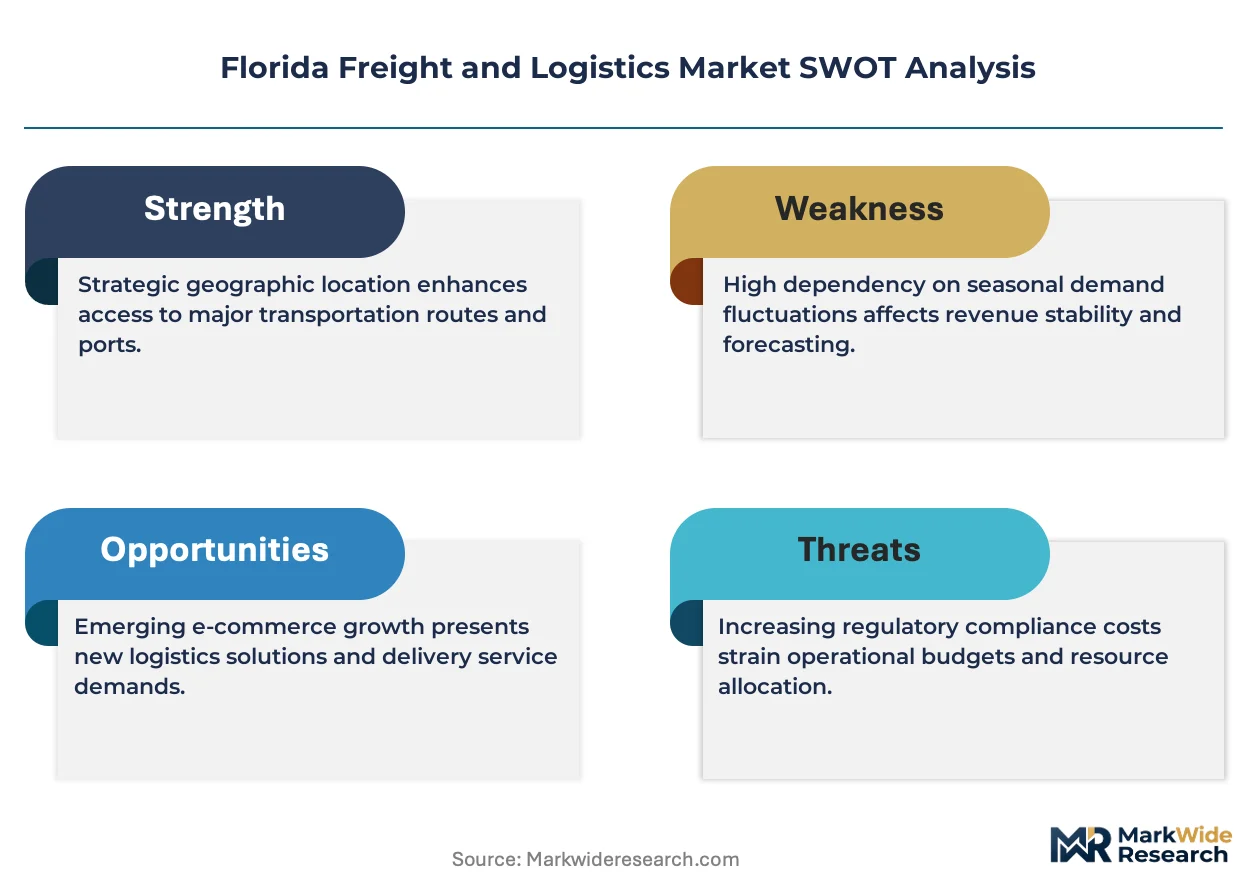
The Federal Motor Carrier Safety Administration shapes driver availability and safety compliance costs, while the Environmental Protection Agency's Phase 3 greenhouse gas standards for heavy-duty vehicles are elevating capital requirements for fleet modernization. The Florida Department of Transportation's Strategic Intermodal System directs public infrastructure spending toward designated freight corridors, influencing warehouse location decisions and last-mile network design. Stakeholders must monitor how port automation investments at PortMiami and Port Everglades interact with chassis pool shortages to determine whether container velocity gains offset rising inland transportation costs.
Market Dynamics
The FMCSA's electronic logging device mandate is compressing driver utilization rates across Florida's long-haul and drayage corridors, forcing carriers to restructure fleet deployment around tighter hours-of-service windows rather than traditional dispatch patterns.
Growth Catalysts
- E-commerce fulfillment density:Warehouse footprints along the Tampa-Orlando corridor are expanding to meet same-day delivery expectations from consumer platforms, pulling refrigerated and dry van capacity into the I-4 corridor.
- PortMiami automation investments:Terminal operating system upgrades and semi-automated gantry cranes are accelerating container velocity through Florida's densest throughput gateway, reducing vessel dwell times.
- Strategic Intermodal System designations:The Florida Department of Transportation's corridor prioritization directs infrastructure spending toward designated freight routes, influencing warehouse location decisions and last-mile network design.
Market Restraints
- Chassis pool fragmentation:Equipment imbalances between Port Everglades and inland depots create detention cost volatility for intermodal shippers moving Caribbean transshipment cargo.
- Driver qualification bottleneck:Entry-level driver training program completion timelines stretch carrier recruitment capacity, constraining fleet expansion regardless of equipment availability.
- Rail penetration limits:Florida's peninsula geography restricts Class I rail infrastructure south of Orlando, forcing road freight to absorb volume that would otherwise move on intermodal rail.
Strategic Opportunities
- Central Florida distribution clustering:Polk and Osceola counties offer undeveloped industrial land with Strategic Intermodal System access, positioning the region for temperature-controlled consolidation facilities serving the Southeast.
- EPA Phase 3 greenhouse gas standards:Fleet modernization mandates create first-mover advantage for carriers deploying battery-electric or hydrogen fuel cell tractors on predictable drayage circuits.
- Cross-border Caribbean integration:Free Trade Zone status at Port Everglades enables value-added logistics services for Central American assembly operations seeking US market access.
Industry Challenges
- Telematics integration complexity:Legacy dispatch systems at mid-sized carriers resist seamless data exchange with FMCSA-mandated electronic logging devices, forcing parallel workflow maintenance.
- Hurricane corridor disruption protocols:Seasonal shutdown procedures across South Florida's tri-county area require redundant inventory positioning that strains working capital during peak freight windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Florida Freight and Logistics Market |
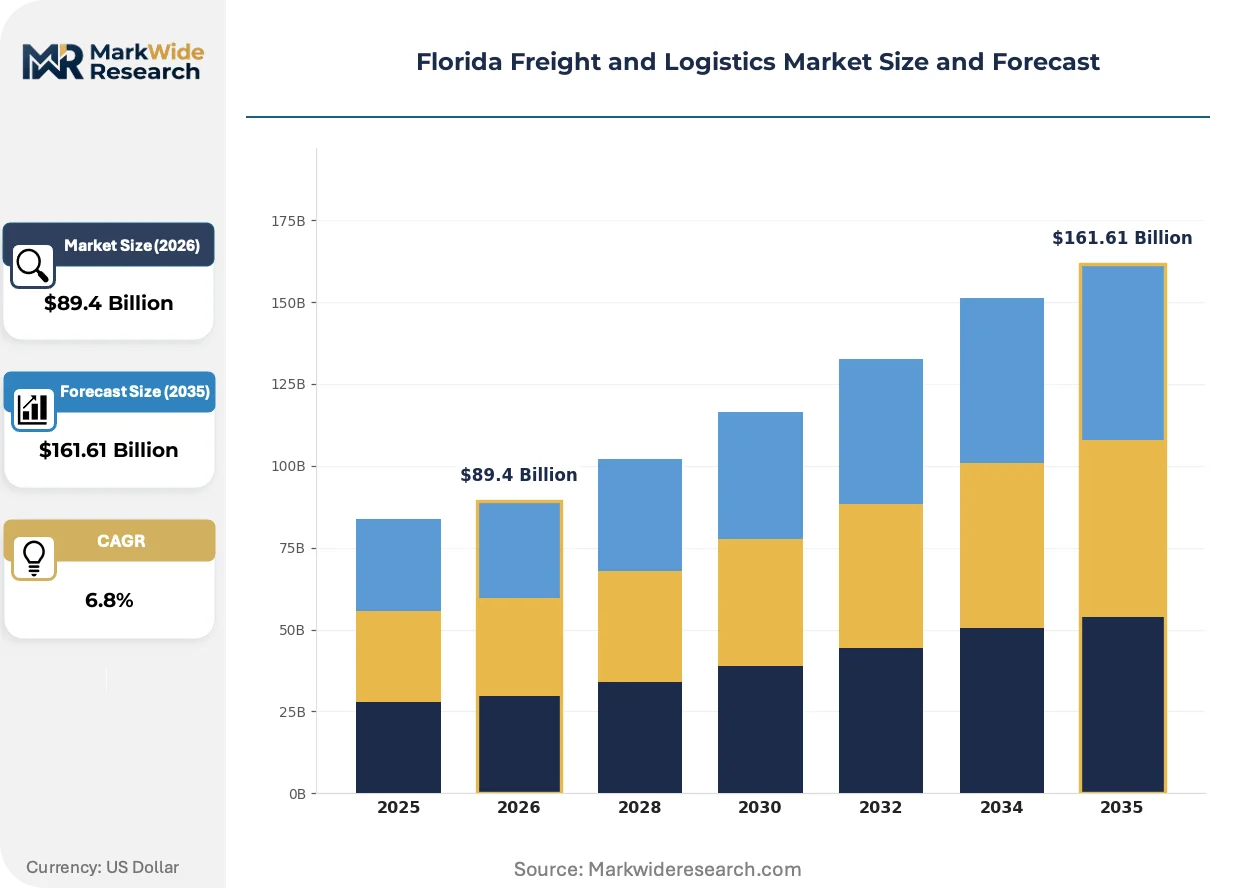
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $161.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Road Freight, Air Freight, Ocean Freight, Rail Freight End User: E-commerce, Manufacturing, Retail, Agriculture Technology: GPS Tracking, TMS, RFID, Blockchain Capacity: Small Scale, Medium Scale, Large Scale, Enterprise |
| Companies Covered | CSX Corporation, Crowley Maritime Corporation, Ryder System, Inc., Landstar System, Inc., BlueGrace Logistics, Go Freight Group, Direct Drive Logistics, Inland Transport Inc., Flagler Global Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Florida Freight and Logistics Market Trends and Innovations
Digital freight matching platforms and predictive cargo visibility tools are rewriting how Florida carriers allocate capacity across hurricane-season volatility and e-commerce surge patterns.
Telematics-enabled dynamic routing is rewriting dispatch economics for temperature-controlled fleets serving Central Florida's agricultural heartland. Shippers of perishable produce now demand real-time temperature and location verification, forcing carriers to retrofit refrigerated trailers with IoT sensors or lose contract renewals. The technology is rewriting margin structures by compressing empty miles through automated backhaul matching.
The Environmental Protection Agency's Phase 3 greenhouse gas standards for heavy-duty vehicles are elevating capital requirements for fleet operators running PortMiami drayage circuits. Engine and aerodynamic package upgrades now dominate procurement conversations, with larger carriers front-loading tractor replacements to capture early compliance credits. The regulation hits small fleet operators hardest, accelerating subcontracting relationships with asset-light brokers.
Consolidation among grocery and home improvement retailers is concentrating procurement leverage over Florida's less-than-truckload networks. Large shippers now demand unified billing across multiple modes and dedicated account management, displacing the transactional spot-market relationships that historically characterized regional freight. The shift is most visible across South Florida's tri-county area, where distribution center rationalization has reduced the number of delivery points while increasing drop size requirements.
Florida Freight and Logistics Market Segmentation
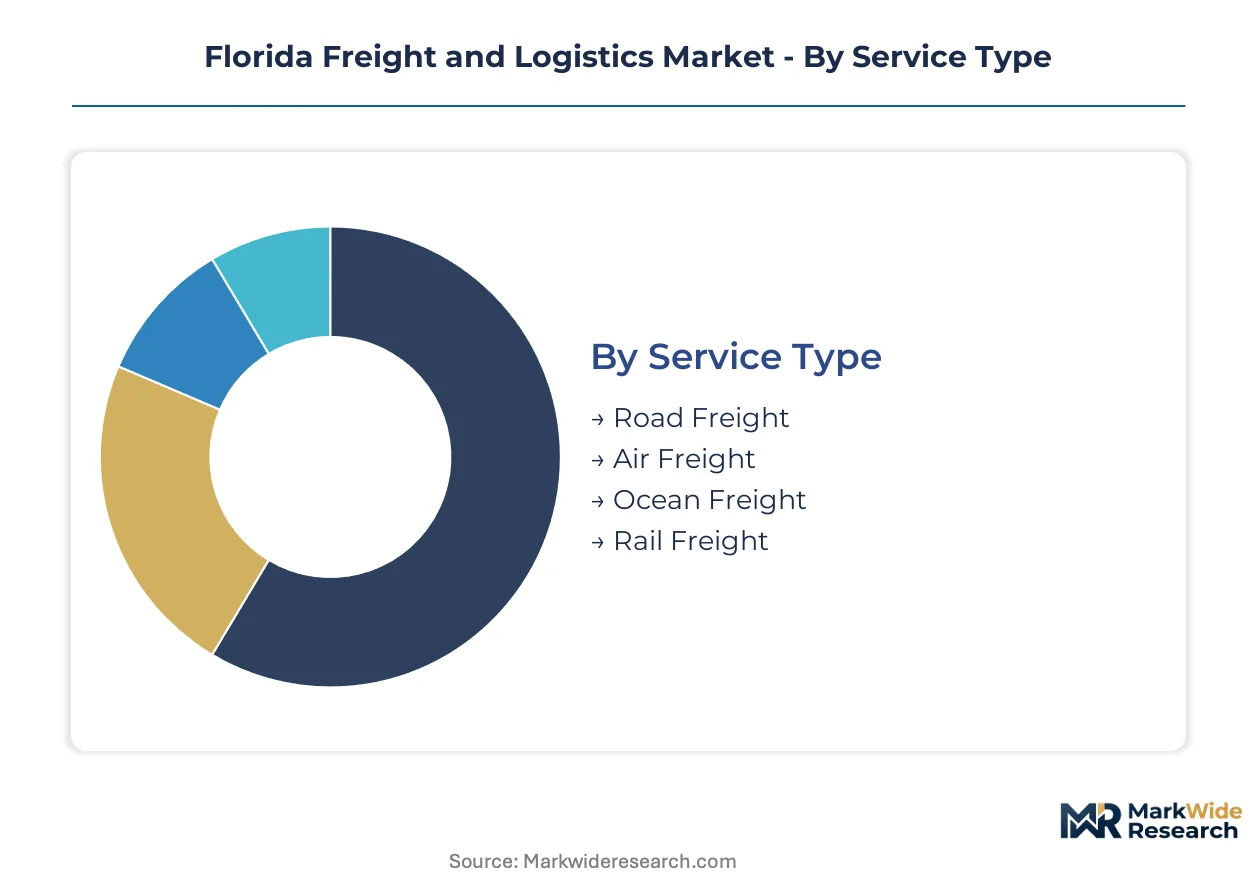
Segmentation reveals how Florida's peninsula geography and multi-modal infrastructure create distinct service economics across transportation modes, end-use demand patterns, and technology adoption curves. Understanding these divisions exposes where carrier margins concentrate and where capital deployment faces structural constraints.
Service Type:
Road freight dominates standardized, high-frequency movements across Florida's limited rail penetration south of Orlando, while ocean and air freight capture premium-priced specialized cargo requiring gateway access.
- Road Freight:Dry van and refrigerated trucking absorb the majority of intra-Florida volume given the state's peninsula geography and restricted Class I rail infrastructure south of Orlando. Demand concentrates along the I-4 corridor connecting Tampa distribution centers to Orlando's e-commerce fulfillment clusters, where same-day delivery expectations are compressing transit time windows.
- Ocean Freight:Containerized cargo moving through PortMiami and Port Everglades anchors Caribbean and Latin American re-export trade lanes, with specialized reefers handling Central American agricultural imports. South Florida's tri-county area generates the densest throughput, though chassis pool fragmentation between port terminals and inland depots creates equipment availability volatility.
- Air Freight:Temperature-controlled pharmaceutical and perishable shipments leverage Miami International Airport's cargo infrastructure for time-definite Latin American connectivity.
- Rail Freight:CSX intermodal corridors link Jacksonville to southeastern distribution networks, with limited penetration into Central Florida beyond bulk commodity movements.
Leading the category by volume: Road Freight. Growing fastest: Ocean Freight.
End User:
Customer scale and delivery velocity requirements segment procurement behavior, with large-volume shippers extracting dedicated capacity commitments while smaller users absorb spot-market volatility.
- E-commerce:Platform-driven fulfillment networks are restructuring warehouse location decisions across Polk and Osceola counties, pulling refrigerated and dry van capacity into the I-4 corridor as delivery density expectations intensify.
- Retail:Consolidated grocery and home improvement distribution centers now demand unified multi-modal billing and dedicated account management, displacing transactional spot relationships across South Florida's tri-county area.
- Manufacturing:Just-in-time assembly operations in Central Florida require predictable drayage circuits from Port Everglades Free Trade Zone facilities.
- Agriculture:Central Florida's produce shippers mandate real-time temperature verification through IoT-enabled trailers, forcing carrier technology retrofits or contract loss.
Volume leader: Retail. Steepest expansion trajectory: E-commerce.
Technology:
Adoption maturity splits between compliance-mandated systems and competitive-differentiation platforms, with FMCSA requirements forcing baseline investments while visibility tools capture premium pricing.
- GPS Tracking:Real-time location monitoring has become table stakes for temperature-controlled agricultural and pharmaceutical shipments, with shippers rejecting carriers lacking continuous visibility.
- TMS:Transportation management systems enable dynamic routing optimization that compresses empty miles for mid-sized carriers serving the I-4 corridor's fulfillment density.
- RFID:Automated cargo identification accelerates container velocity through PortMiami's semi-automated terminal infrastructure.
- Blockchain:Distributed ledger documentation remains experimental for Caribbean transshipment cargo, with adoption constrained by carrier IT integration costs.
Widest deployment: GPS Tracking. Gaining share fastest: TMS.
Capacity:
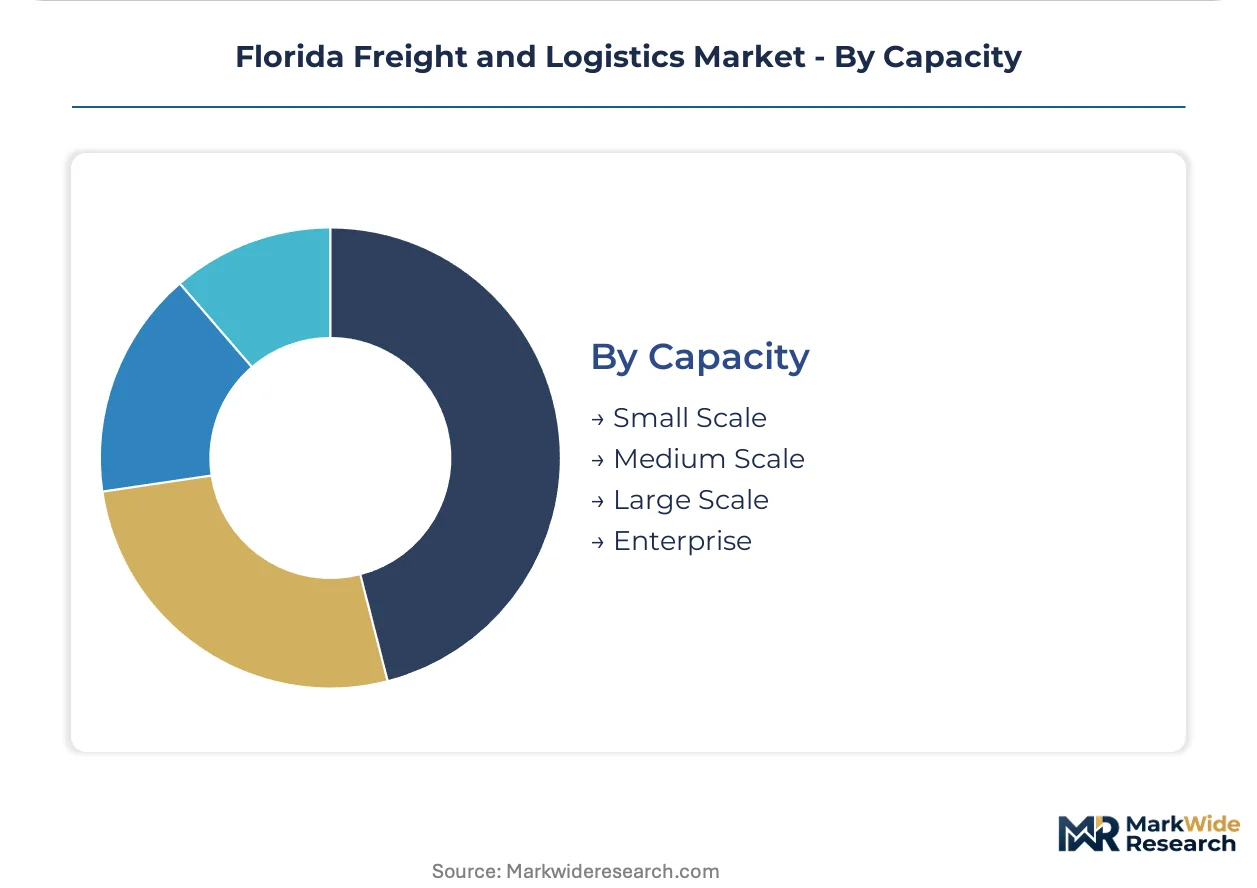
Asset scale determines regulatory exposure and modernization capital access, with EPA Phase 3 standards accelerating consolidation toward larger fleet operators.
- Enterprise:National carriers with 500+ tractors front-load replacement cycles to capture early EPA compliance credits, deploying battery-electric units on predictable PortMiami drayage circuits.
- Large Scale:Regional fleets of 100-499 units leverage subcontracting relationships with asset-light brokers to manage equipment utilization across hurricane-season volatility.
- Medium Scale:20-99 tractor operators face the steepest FMCSA telematics integration costs, maintaining parallel legacy and mandated electronic logging workflows.
- Small Scale:Owner-operators and micro-fleets under 20 units absorb spot-market rate pressure, with limited capital access for engine upgrades or aerodynamic package investments.
Revenue concentration: Enterprise. Most pressured segment: Small Scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates most visibly in South Florida's tri-county area, where PortMiami and Port Everglades handle the state's densest container throughput. The I-4 corridor connecting Tampa to Orlando anchors e-commerce fulfillment expansion, while Jacksonville's rail intermodal hub links Florida to southeastern distribution networks.
South Florida Tri-County Area
PortMiami and Port Everglades drive container throughput for Caribbean and Latin American re-export trade. The Federal Motor Carrier Safety Administration's electronic logging device mandate compresses driver utilization rates across local drayage circuits. Miami-Dade, Broward, and Palm Beach counties host temperature-controlled consolidation facilities serving pharmaceutical and perishable cargo flows.
Central Florida I-4 Corridor
E-commerce fulfillment centers in Polk and Osceola counties pull refrigerated and dry van capacity into same-day delivery networks. The Florida Department of Transportation's Strategic Intermodal System directs infrastructure spending toward designated freight routes. Orlando's warehouse clustering accelerates last-mile network design decisions for consumer platforms.
Tampa Bay Metro
Distribution centers leverage port access and interstate connectivity for agricultural exports and manufactured goods. The Environmental Protection Agency's Phase 3 greenhouse gas standards elevate capital requirements for fleet modernization. Hillsborough and Pinellas counties offer industrial land with multimodal access to Gulf Coast shipping lanes.
Jacksonville Northeast Florida
CSX Corporation's headquarters anchors intermodal rail connections to southeastern distribution networks. The Federal Motor Carrier Safety Administration shapes driver availability and safety compliance costs for regional carriers. Duval County's port and rail infrastructure supports bulk commodity movements and automotive logistics.
Northwest Florida Gulf Coast
Panhandle distribution networks serve military and aerospace supply chains with less congestion than peninsula corridors. The Florida Department of Transportation's corridor prioritization influences warehouse location decisions along Interstate 10. Escambia and Santa Rosa counties position for cross-Gulf trade with Texas and Mexico.
Florida Freight and Logistics Market Competitive Landscape
Southeastern rail intermodal operators anchor one tier; asset-light brokerage specialists hold variable-cost capacity without fixed asset exposure. The market exhibits tiered consolidation with national carriers, regional fleets, and owner-operator micro-fleets competing across distinct service economics. Three archetypes dominate: integrated rail-port operators, agent-based capacity networks, and technology-enabled freight brokers. Competitive moves center on fleet modernization for EPA compliance and strategic partnerships for chassis pool access.
Within the integrated rail-port tier, CSX Corporation and Crowley Maritime Corporation exemplify vertically structured operators combining intermodal rail, port terminal access, and ocean carrier relationships. Landstar System, Inc. occupies a position in the asset-light brokerage archetype, sustaining variable-cost capacity through independent agent networks. These three companies represent the dominant competitive positioning vectors across Florida's multimodal freight corridors.
| Leading Market Players |
|---|
| CSX Corporation |
| Crowley Maritime Corporation |
| Ryder System, Inc. |
| Landstar System, Inc. |
| BlueGrace Logistics |
| Go Freight Group |
| Direct Drive Logistics |
| Inland Transport Inc. |
| Flagler Global Logistics |
| Others |
Pricing and Supply Chain Analysis
Consolidated grocery and home improvement distribution centers across South Florida's tri-county area command unified multi-modal billing arrangements that compress margins for carriers lacking scale. Contract-based long-term offtake agreements dominate procurement relationships, displacing transactional spot-market dynamics that historically characterized regional freight.
Pricing Analysis
Volume-heavy drayage circuits absorb margin compression while specialized temperature-controlled lanes retain premium pricing power. Three-tier pricing structure across premium, standard, and economy levels separates enterprise carriers with EPA compliance credits from mid-scale fleets facing telematics integration costs. Cost compression in the small-scale owner-operator tier is intensifying because chassis pool fragmentation elevates equipment access uncertainty. E-commerce fulfillment platforms exhibit least price sensitivity given same-day delivery imperatives, while agricultural exporters show highest sensitivity to per-mile rate fluctuations.
Supply Chain Analysis
Direct-to-port channels handle hyperscale container throughput through PortMiami and Port Everglades, while agent-based networks sustain variable-cost capacity across hurricane-disrupted corridors. Manufacturing concentration rests on Mexico, China, and Vietnam for container chassis and refrigeration unit components. Diesel engine blocks, aerodynamic fairings, and IoT sensor arrays constitute critical input dependencies. Single-source vulnerability around semiconductor chips for electronic logging devices creates fleet modernization bottlenecks. Distribution runs through CSX intermodal terminals in Jacksonville and Crowley's integrated ocean-land corridors serving Caribbean assembly operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where EPA Phase 3 compliance costs and FMCSA telematics mandates force sub-scale operators into subcontracting relationships or exit.
For Market Incumbents: Cement chassis pool access partnerships with Port Everglades and PortMiami terminal operators to lock in equipment velocity advantages over emerging entrants. Deepen backward integration into refrigerated trailer asset pools serving Central Florida's agricultural heartland, countering the threat of asset-light brokerage platforms capturing temperature-controlled contract renewals through superior technology deployment. For New Entrants and Emerging Players: Capture white-space in Polk and Osceola county distribution clustering where Strategic Intermodal System designations attract e-commerce fulfillment investment but incumbent carrier density remains thin. Target battery-electric drayage circuits on predictable PortMiami routes, leveraging first-mover EPA compliance credit accumulation as a go-to-market wedge against legacy diesel fleets. For Investors and Strategic Acquirers: The window for entry favors mid-scale regional fleets with 100-499 tractor positions and established agent relationships, as these assets offer operational integration potential without enterprise-scale capital requirements. Acquisition focus should center on carriers with existing temperature-controlled certification and I-4 corridor warehouse proximity. Watch chassis pool utilization rates at Port Everglades as the inflection signal for inland transportation cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Partnership | Battery-electric tractor deployment on PortMiami drayage circuits captures early EPA Phase 3 compliance credits ahead of competitors. |
| Chassis Pool Integration Agreement | Direct equipment access contracts with port terminal operators reduce detention cost volatility for intermodal shippers. |
| Temperature-Controlled Certification Investment | IoT-enabled trailer retrofits satisfy Central Florida agricultural shipper mandates for real-time cargo verification. |
| Strategic Intermodal System Corridor Positioning | Polk and Osceola county facility placement aligns with Florida DOT infrastructure spending on designated freight routes. |
| Agent Network Expansion | Asset-light capacity aggregation sustains variable-cost operations without fixed tractor exposure during hurricane-season volatility. |
Research Methodology
FMCSA regulatory filings, Florida Department of Transportation Strategic Intermodal System documentation, and EPA Phase 3 greenhouse gas standard impact assessments formed the secondary backbone of this analysis. Primary interviews with fleet operations directors, port terminal managers, refrigerated carrier dispatch supervisors, and agricultural shipper logistics coordinators provided operational validation. Customs data on container movements through PortMiami and Port Everglades, alongside CSX intermodal volume disclosures, supplied demand-side calibration. Bottom-up carrier fleet composition analysis and top-down regional GDP-elasticity modeling were triangulated to cross-validate segment sizing.
Bottom-up modeling of tractor fleet deployment patterns by capacity tier and service type was reconciled against top-down freight demand projections tied to e-commerce fulfillment expansion and Caribbean trade lane volumes. Segmentation across service type, end user, technology adoption, and fleet capacity scale informed the analytical framework throughout the projection horizon. CAGRs were derived from regression analysis against historical freight tonnage correlations with retail sales and port throughput metrics. Forecast inputs incorporated hurricane disruption frequency patterns and driver training program completion timelines as industry-specific demand constraints.
The model holds under stable FMCSA enforcement intensity and continued EPA Phase 3 implementation timelines; deviation in regulatory delay or chassis pool restructuring would shift carrier cost structures and competitive positioning. Forecasts reflect documented assumptions around e-commerce penetration rates and port automation investment schedules. Periodic stress-testing of base assumptions is recommended given hurricane corridor disruption protocols and their working capital implications for inventory positioning strategies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Saudi Arabia Last Mile Delivery Market
Logistics and Shipping
Same Day Delivery Service Market
Logistics and Shipping
Unit Load Device Market
Logistics and Shipping
Europe Third Party Logistics Market
Logistics and Shipping
US Mexico Cross Border FTL Freight Transport Market
Logistics and Shipping
Roll Trailer Market
Logistics and Shipping
United Kingdom Contract Logistics Market
Logistics and Shipping
North America Cargo Handling Equipment Market
Logistics and Shipping
Poland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
ASEAN Chemical Logistics Market
Logistics and Shipping
Latin America Cold Chain Logistics Market
Logistics and Shipping
Australia Cold Chain Logistics Market
Logistics and Shipping
Middle East and Africa Courier Market
Logistics and Shipping
ASEAN Domestic Courier Market
Logistics and Shipping
Event Logistics Market
Logistics and Shipping
China Local Courier Market