
 Finished Vehicle Logistics Market | 2026-2036
Finished Vehicle Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Finished Vehicle Logistics Market Analysis
Finished vehicle distribution networks is rewriting how OEMs move cars from assembly plants to dealerships. DHL Supply Chain leverages its multi-modal platform to control high-volume corridors between European manufacturing hubs and Mediterranean ports. Wallenius Wilhelmsen anchors deep-sea ro-ro capacity on trans-Pacific and trans-Atlantic routes, sustaining its position in ocean-borne vehicle transport. Kuehne+Nagel competes through digital freight matching tools that reduce empty backhaul miles for truck carriers serving just-in-time delivery contracts.
Finished vehicle logistics encompasses the specialized handling, storage, and transport of completed automobiles from factory gates to final delivery points, requiring vehicle-specific carrier equipment with hydraulic lift decks and tie-down systems that prevent transit damage. The primary purpose is maintaining vehicle condition integrity while minimizing dwell time and inventory carrying costs across extended supply chains. Transportation services dominate value capture within the service type dimension, though warehousing and inventory management functions are deepening as OEMs buffer against semiconductor-driven production volatility. SUVs and trucks command disproportionate logistics complexity due to dimensional constraints on standard car carriers, while sedan volumes face structural pressure in North American and European markets.
EPA emissions regulations for heavy-duty trucks shape carrier fleet renewal timelines and alternative fuel investment decisions across US interstate corridors. EU Green Deal transport decarbonization targets and Germany's KBA vehicle type-approval requirements collectively push logistics providers toward electrified terminal equipment and low-emission last-mile configurations. Stakeholders must monitor how battery-electric vehicle weight premiums reshape carrier payload economics and whether port infrastructure investments keep pace with rising ro-ro vessel calls.
Market Dynamics
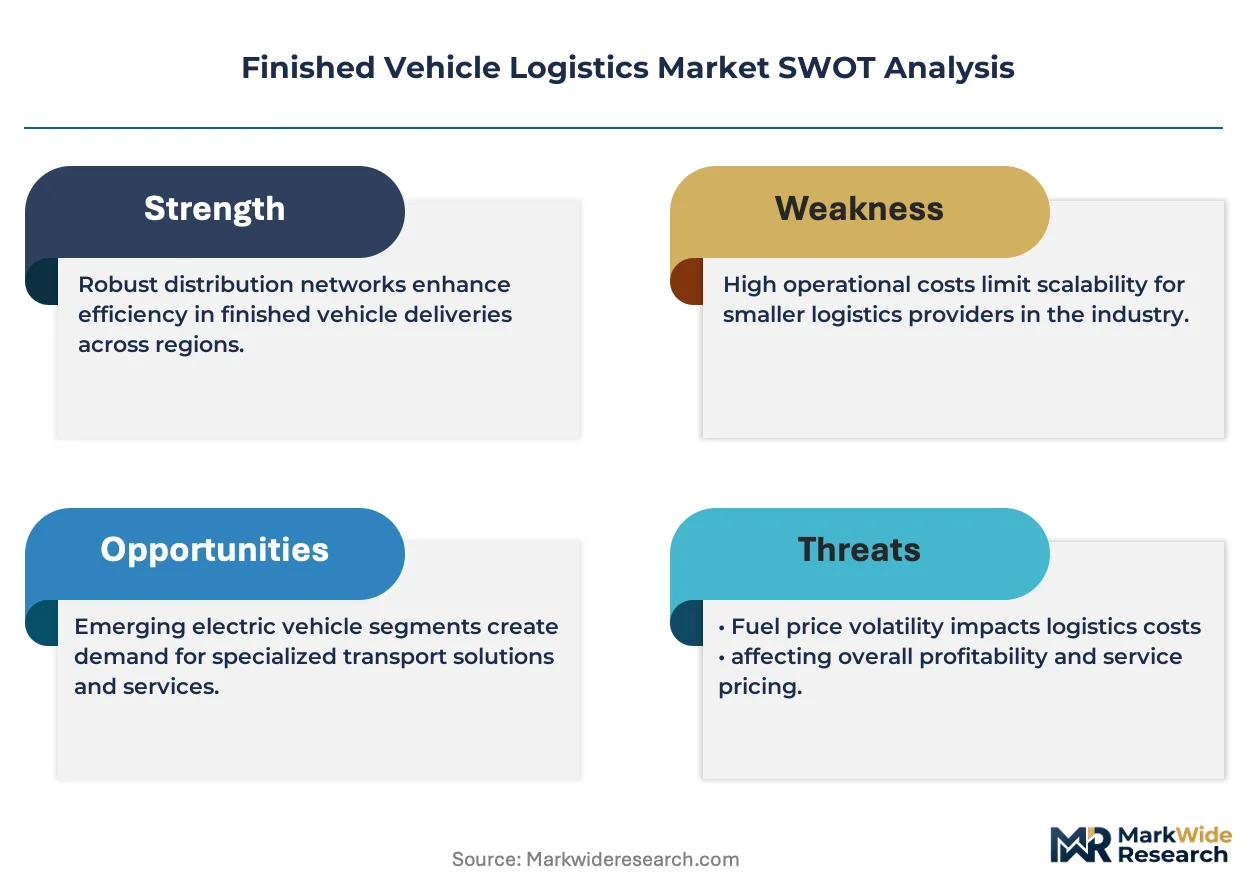
EU Green Deal transport decarbonization mandates are forcing logistics providers to reconfigure terminal operations and last-mile fleets while battery-electric vehicle weight premiums compress carrier payload economics across European corridors.
Growth Catalysts
- EU Green Deal Compliance:Transport fleet electrification mandates under the EU Green Deal accelerate investment in charging infrastructure and low-emission terminal equipment across German manufacturing clusters.
- Electric Vehicle Production Scaling:Rising EV manufacturing volumes from OEMs expand finished vehicle logistics requirements for specialized handling equipment and battery-safe transport protocols.
- Ro-Ro Port Expansion:Mediterranean port infrastructure investments in Barcelona, Valencia, and Piraeus accommodate rising deep-sea vessel calls for outbound vehicle distribution.
Market Restraints
- Semiconductor-Driven Production Volatility:Automotive manufacturing fluctuations force logistics providers to absorb higher warehousing costs and inventory buffering expenses.
- Carrier Fleet Renewal Capex:EPA emissions standards for heavy-duty trucks compress carrier margins as fleet operators face accelerated equipment replacement timelines.
- Dimensional Constraints on Standard Equipment:SUV and truck weight premiums reduce effective payload capacity on hydraulic lift-deck carriers, degrading route economics.
Strategic Opportunities
- Digital Freight Matching Platforms:Algorithmic load consolidation tools reduce empty backhaul miles for truck carriers serving just-in-time delivery contracts with German OEMs.
- Multi-Modal Corridor Control:Integrated rail-truck-sea platforms capture value from high-volume corridors between Czech and Slovak manufacturing hubs and Adriatic ports.
- Battery-Electric Vehicle Logistics Specialization:Hazardous-material-certified handling protocols and thermal-managed storage create service differentiation for EV-focused carriers.
Industry Challenges
- Driver Qualification Shortages:Specialized vehicle transport licensing requirements and hazardous materials certifications constrain qualified operator availability across EU member states.
- Legacy Terminal Electrification:Port and inland terminal infrastructure retrofitting for electric yard tractors and charging stations demands capital deployment without immediate volume guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Finished Vehicle Logistics Market |
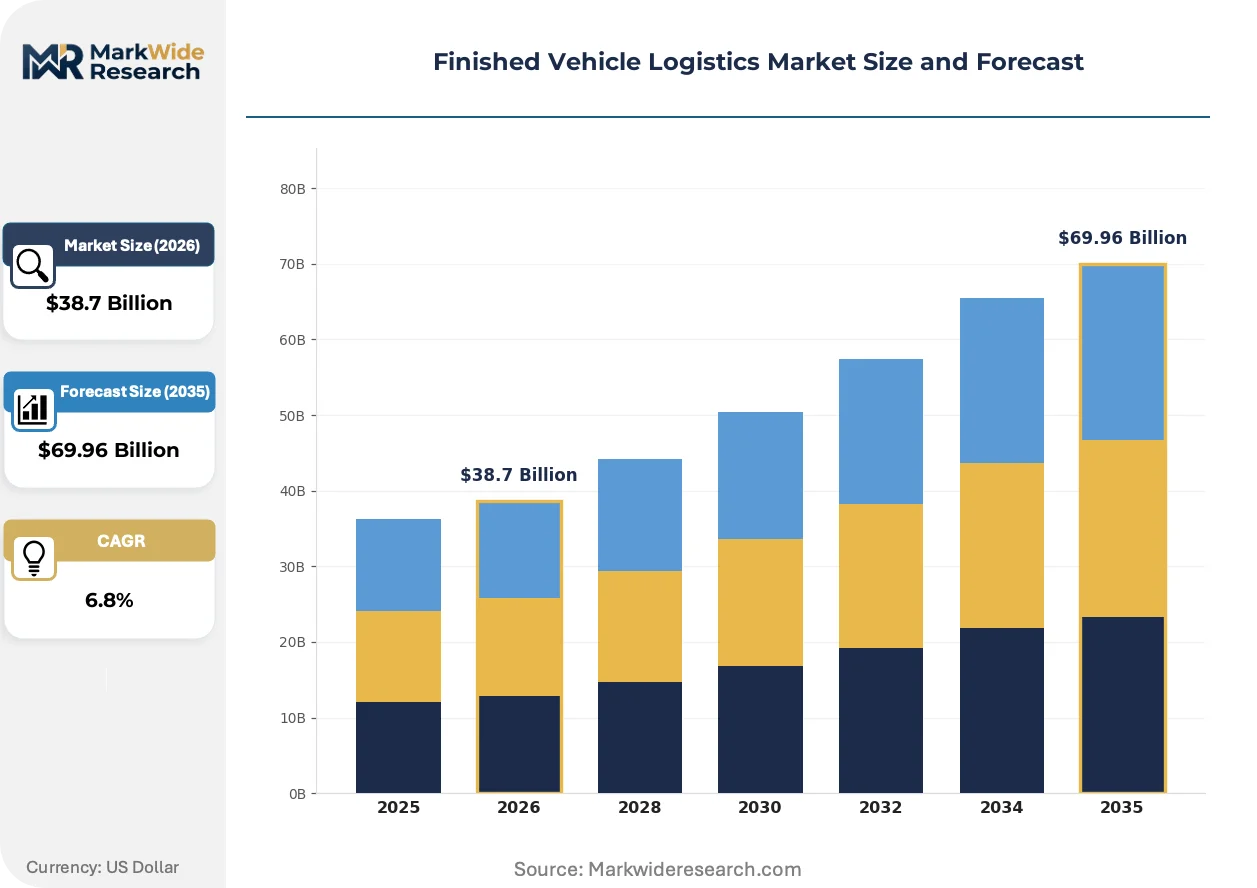
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trucks, Sedans, SUVs, Vans Service Type: Transportation, Warehousing, Inventory Management, Delivery End User: OEMs, Dealerships, Fleet Operators, Aftermarket Providers Distribution Channel: Direct Sales, Online Platforms, Auctions, Third-party Logistics |
| Companies Covered | Kuehne+Nagel, DSV, CEVA Logistics, NYK Line, Wallenius Wilhelmsen, DHL Supply Chain, Maersk, Deutsche Post DHL Group, DB Schenker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Finished Vehicle Logistics Market Emerging Trajectories
Digital orchestration platforms and alternative-fuel vehicle handling protocols are restructuring how finished vehicle logistics providers coordinate multi-modal movements and manage emissions compliance across European distribution networks.
Autonomous yard tractor technology is collapsing dwell times at vehicle processing centers. German terminal operators at Bremerhaven and Hamburg are piloting self-driving equipment for vehicle marshalling and vessel loading operations. This automation is collapsing labor cost structures while compressing vessel turnaround windows.
EU Green Deal transport decarbonization targets are mandating progressive emission reductions for logistics fleets serving automotive manufacturing corridors. Germany's KBA vehicle type-approval requirements now extend to terminal equipment certification, pushing providers toward electrified configurations. Heavy-duty truck carriers operating across the Rhine-Ruhr corridor face accelerated fleet renewal timelines to maintain OEM contract eligibility.
Buyer consolidation among European automotive OEMs is compressing logistics contract renewal cycles and unbundling service components. German and French manufacturers are separating transportation, warehousing, and final-mile delivery into discrete procurement lots, enabling specialized providers to capture niche segments. This fragmentation is most visible in the premium vehicle segment, where OEMs demand dedicated handling protocols for luxury marques.
Finished Vehicle Logistics Market Segmentation
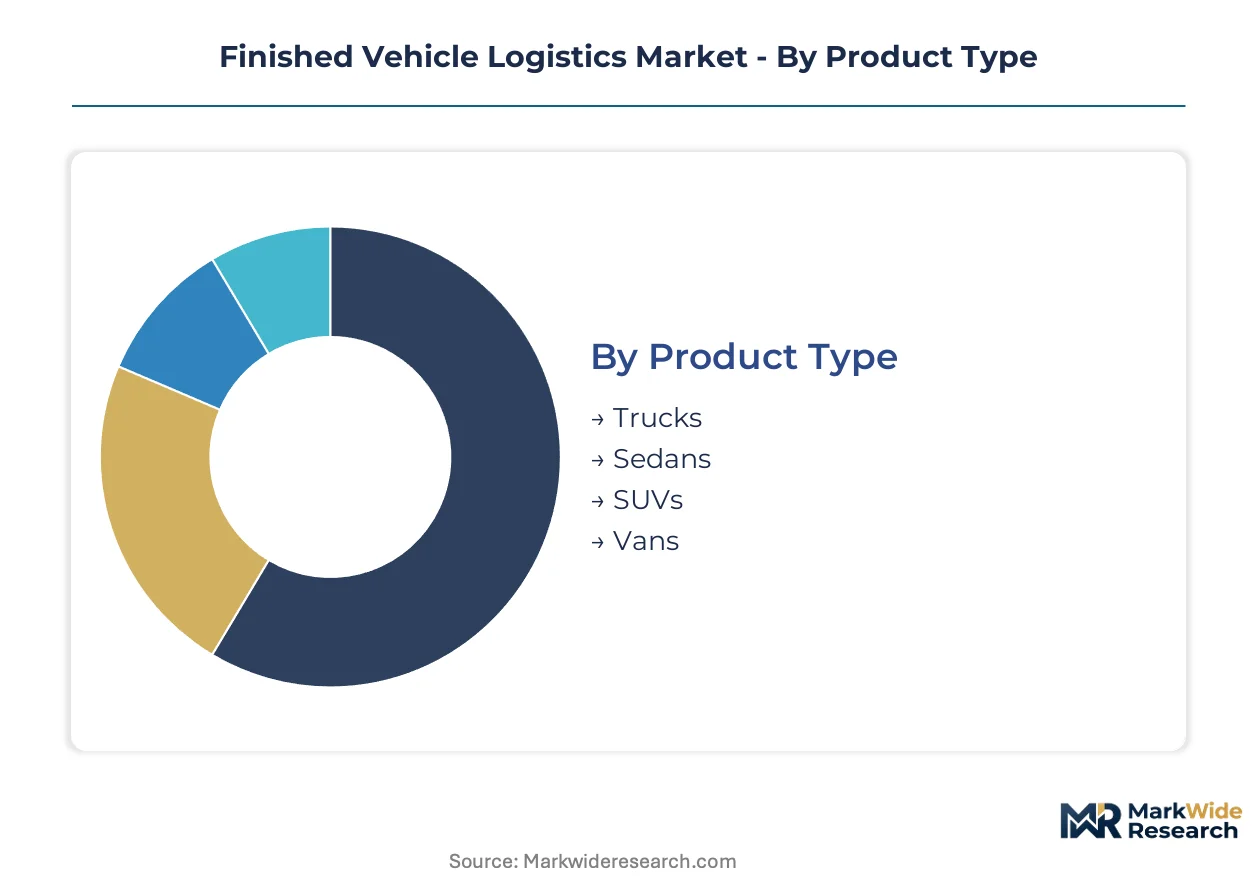
Segmentation in finished vehicle logistics reveals how equipment specifications, service intensity, and customer procurement patterns fragment value capture across the supply chain. Understanding these divisions exposes where carriers earn premiums versus where commoditization pressures concentrate.
Product Type:
Cycle times vary sharply across vehicle formats, with compact sedans turning through distribution networks fastest while heavy trucks dwell longest at processing terminals due to specialized handling requirements.
- SUVs:Dimensional bulk exceeding standard car carrier decks forces deployment of hydraulic lift systems with extended load beds. German OEMs in Bavaria and Baden-Württemberg drive disproportionate logistics complexity for premium SUV variants requiring enclosed transport.
- Trucks:Commercial vehicle weight classes demand reinforced tie-down systems and escort protocols for oversized loads. Fleet operators in the Rhine-Ruhr corridor generate concentrated demand for heavy-duty terminal equipment capable of handling 7.5-tonne plus configurations.
- Sedans:Standardized dimensions enable maximum payload density on multi-deck carriers.
- Vans:Light commercial configurations occupy intermediate handling tiers between passenger and heavy commercial segments.
Sedans anchor the volume base while SUVs gain share at the steepest rate.
Service Type:
Cost tiers separate commoditized movement from value-added services, with transportation commanding baseline rates while inventory management functions capture premiums through risk absorption.
- Transportation:Road, rail, and ocean modes constitute the foundational service layer with thin margins and high asset intensity. Czech and Slovak manufacturing clusters generate dense corridor demand for integrated multi-modal platforms serving Adriatic port connections.
- Inventory Management:Semiconductor-driven production volatility forces OEMs to outsource buffer stock positioning and demand forecasting. German manufacturers now contract separately for inventory optimization services distinct from physical transport execution.
- Warehousing:Vehicle processing centers provide staging, inspection, and minor reconfiguration services.
- Delivery:Final-mile execution to dealership lots requires specialized equipment for damage-free unloading.
Transportation anchors the volume base while inventory management gains share at the steepest rate.
End User:
Customer type determines contract structure, with OEMs demanding integrated solutions while aftermarket providers purchase discrete services on spot markets.
- OEMs:Original equipment manufacturers contract for end-to-end control from factory gate to dealership, requiring dedicated fleet allocation and real-time visibility systems. Volkswagen, BMW, and Mercedes-Benz operations in Germany drive the most sophisticated logistics procurement specifications in Europe.
- Dealerships:Franchise networks purchase delivery services and short-term storage through regional logistics aggregators.
- Fleet Operators:Commercial vehicle lessors and corporate fleet managers require bulk handling protocols for vehicle rotation and remarketing.
- Aftermarket Providers:Parts distributors and vehicle modification specialists generate fragmented demand for specialized transport of non-standard configurations.
OEMs anchor the volume base while fleet operators gain share at the steepest rate.
Distribution Channel:
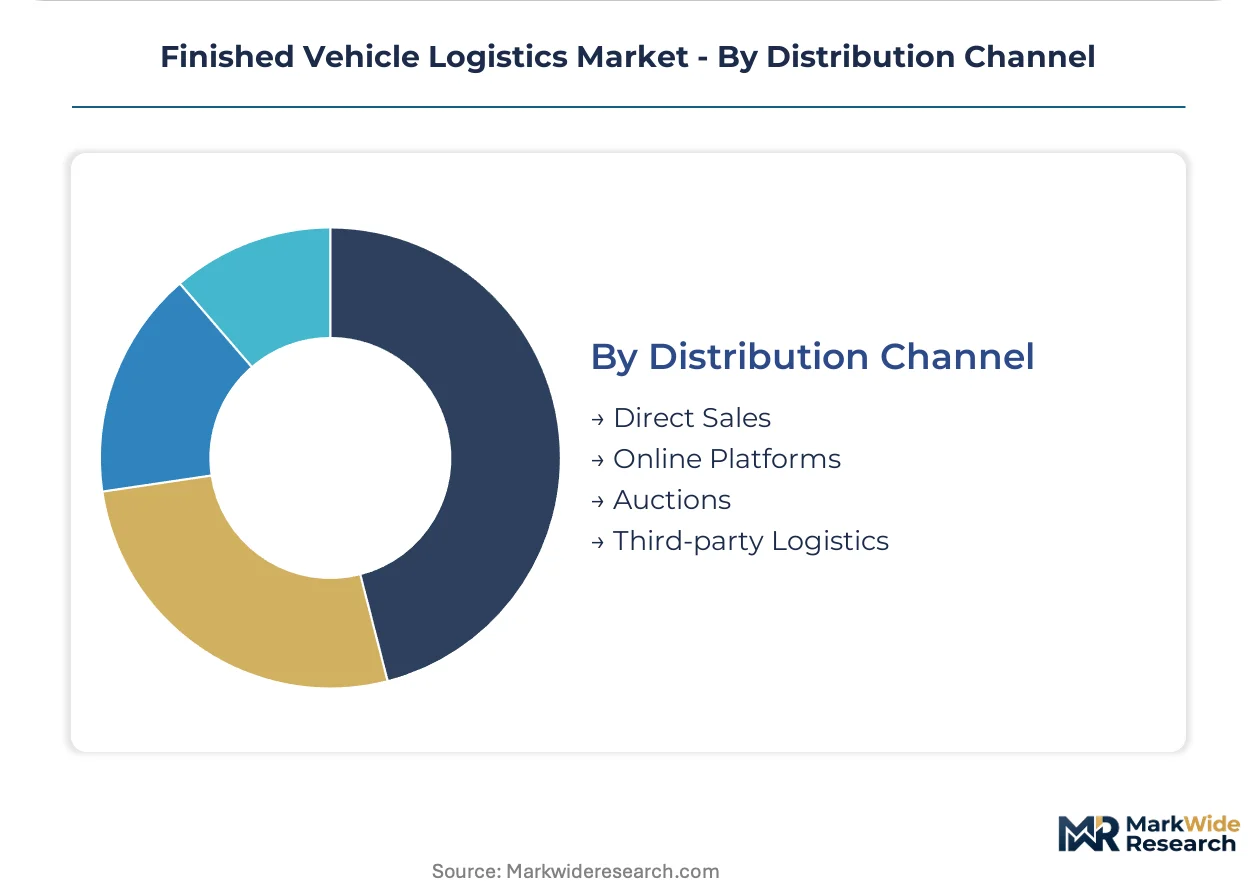
Channel maturity separates established direct sales networks from emerging digital platforms, with third-party logistics providers capturing value from channel fragmentation.
- Third-party Logistics:Specialized vehicle logistics providers aggregate demand across multiple OEMs to achieve equipment utilization rates unachievable by captive fleets. DHL Supply Chain and Kuehne+Nagel operations across German manufacturing corridors demonstrate how multi-client platforms achieve density economics.
- Direct Sales:OEM captive fleets serve dedicated routes with guaranteed capacity but limited flexibility.
- Online Platforms:Digital marketplaces for used and new vehicle transactions generate spot demand for transport services.
- Auctions:Remarketing channels for fleet vehicles and lease returns require rapid repositioning logistics.
Direct sales anchor the volume base while third-party logistics gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Bremerhaven's dedicated ro-ro terminals anchor Germany's dominance in European vehicle exports, handling over two million finished vehicles annually through specialized vessel-to-rail transfer facilities.
Germany
Volkswagen's Wolfsburg complex and BMW's Munich operations generate concentrated outbound logistics demand for premium sedans and SUVs. KBA certification requirements now extend to terminal equipment emissions standards, accelerating electrification of yard tractors at Bremerhaven and Hamburg vehicle processing centers.
United States
Detroit's automotive manufacturing corridor and Tesla's Austin assembly plant drive multi-modal distribution complexity across interstate highway networks. EPA heavy-duty truck emissions standards under Phase 2 regulations compress carrier fleet renewal timelines, pushing logistics providers toward alternative fuel investments at Gulf Coast and West Coast port gateways.
China
BYD's Shenzhen headquarters and NIO's Hefei manufacturing base expand finished vehicle logistics requirements for battery-electric export volumes. MIIT new energy vehicle mandates and dual carbon goals reshape port infrastructure investments at Shanghai and Ningbo, where dedicated EV handling terminals process rising ro-ro vessel calls.
Mexico
BMW's San Luis Potosí assembly plant and expanding Kia operations in Nuevo León generate cross-border trucking demand through Laredo and Eagle Pass corridors. USMCA rules of origin compliance requirements concentrate logistics investment at Monterrey vehicle processing centers serving North American distribution networks.
Japan
Toyota's Nagoya manufacturing cluster and Honda's Suzuka operations sustain deep-sea export volumes through Yokohama and Kobe port terminals. METI carbon neutrality roadmaps for transport sectors push terminal operators toward hydrogen fuel cell yard equipment pilots at major vehicle handling facilities.
Finished Vehicle Logistics Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in equipment and software layers. The vendor base organizes around three archetypes: multi-modal orchestrators managing end-to-end control towers, deep-sea ro-ro operators anchoring trans-oceanic capacity, and digital freight platforms consolidating fragmented truck capacity. Competitive moves concentrate on strategic partnerships between ocean carriers and terminal operators, plus technology licensing agreements for yard automation systems.
Among European-based multi-modal specialists, Kuehne+Nagel and DB Schenker represent the integrated platform archetype, while Wallenius Wilhelmsen occupies a position exemplifying deep-sea ro-ro concentration. These three entities anchor the competitive structure through contrasting scale and specialization profiles.
| Leading Market Players |
|---|
| Kuehne+Nagel |
| DSV |
| CEVA Logistics |
| NYK Line |
| Wallenius Wilhelmsen |
| DHL Supply Chain |
| Maersk |
| Deutsche Post DHL Group |
| DB Schenker |
| Others |
Supply Flow & Price Mechanics
German automotive manufacturing clusters concentrate OEM procurement power, compressing logistics provider margins while pushing contract value toward integrated multi-modal platforms that bundle transport, warehousing, and digital visibility services.
Pricing Analysis
Volume-discount tiering structures dominate OEM procurement, with German manufacturers leveraging annual contract minimums to extract rate concessions from carriers. Price differentiation hinges on service bundling depth and KBA emissions certification tiers for terminal equipment. Cost compression in standard transportation services is intensifying because OEMs unbundle warehousing and inventory management into separate procurement lots. Fleet operators exhibit highest price sensitivity due to thin commercial vehicle margins, while premium OEMs prioritize service reliability over rate competition.
Supply Chain Analysis
Contract-manufacturing concentration rests with specialized vehicle carriers operating dedicated equipment pools across Germany, Czech Republic, and Slovakia. Raw material dependencies span high-strength steel for reinforced decks, hydraulic lift systems, and lithium-ion batteries for electrified terminal tractors. Supply chain risk centers on single-source vulnerability for specialized car-carrier chassis production. Distribution runs through ro-ro port gateways at Bremerhaven, Hamburg, and Adriatic terminals with rail-truck intermodal connections.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where EU Green Deal compliance requirements and KBA certification standards create structural barriers that protect incumbent logistics providers with electrified fleet investments.
For Market Incumbents: Harden terminal electrification advantages by accelerating yard tractor fleet replacement ahead of EU Green Deal phase-in deadlines. Deepen backward integration into charging infrastructure at Bremerhaven and Hamburg processing centers to lock in OEM contract renewals against emerging digital freight platforms threatening margin compression in standard transport services. For New Entrants and Emerging Players: Establish a beachhead in battery-electric vehicle logistics specialization, where hazardous-material-certified handling protocols and thermal-managed storage create service differentiation gaps. Target aftermarket providers and fleet operators in the Rhine-Ruhr corridor with spot-market digital matching tools that exploit incumbent carriers' rigidity in just-in-time contract structures. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional carriers holding dense corridor positions between Czech manufacturing hubs and Adriatic ports. Long-term viability over a multi-year window favors platforms with integrated rail-truck-sea control towers. Monitor EU Green Deal enforcement intensity across German member states as the inflection signal for accelerated fleet renewal capex demands.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Modal Platform Integration | DHL Supply Chain and DB Schenker capture OEM contracts through unified rail-truck-sea control towers. |
| Terminal Electrification Investment | Bremerhaven and Hamburg operators deploy electric yard tractors to meet KBA emissions certification requirements. |
| Digital Freight Matching Deployment | Algorithmic load consolidation tools reduce empty backhaul miles for carriers serving German automotive clusters. |
| Battery-Electric Vehicle Handling Certification | Hazardous-material protocols differentiate carriers capturing rising EV production volumes from BYD and NIO. |
| Ro-Ro Port Capacity Expansion | Barcelona, Valencia, and Piraeus infrastructure investments accommodate rising deep-sea vessel calls for outbound distribution. |
Methodological Framework
Initial hypotheses were tested against primary input from OEM logistics procurement directors, vehicle carrier fleet operators, port terminal managers, and rail intermodal planners and refined through secondary validation against EU customs trade data, KBA vehicle registration databases, automotive production statistics, and SEC filings from listed logistics providers. Bottom-up volume estimates from corridor-specific carrier capacity were triangulated against top-down OEM production forecasts.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass vehicle class, propulsion architecture, service type intensity, and regional production cluster. CAGRs were derived from fitted growth curves calibrated to OEM production schedules and infrastructure investment pipelines. Industry-specific forecast inputs incorporated EU Green Deal compliance timelines and battery-electric vehicle weight premium impacts on carrier payload economics.
Stress conditions across semiconductor supply recovery trajectories, EU emissions enforcement intensity, and ro-ro port congestion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about OEM production stability and regulatory phase-in schedules. Quarterly review of KBA certification adoption rates and terminal electrification capex disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
GCC Contract Logistics Market
Logistics and Shipping
Peru Freight and Logistics Market
Logistics and Shipping
Nigeria Third-Party Logistics (3PL) Market
Logistics and Shipping
Asean Freight and Logistics Market
Logistics and Shipping
Middle Mile Delivery Market
Logistics and Shipping
Event Logistics Market
Logistics and Shipping
Armenia Freight and Logistics Market
Logistics and Shipping
Europe Domestic Courier Market
Logistics and Shipping
United States 3PL Market
Logistics and Shipping
Australia Mining Logistics Market
Logistics and Shipping
Cross-Border Logistics Services Market
Logistics and Shipping
Brazil Freight and Logistics Market
Logistics and Shipping
Asia-Pacific Container Drayage Market
Logistics and Shipping
Germany Freight and Logistics Market
Logistics and Shipping
Poland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Global Drone Logistics and Transportation Market