
 GCC Automotive Logistics Market | 2026-2036
GCC Automotive Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Automotive Logistics Market Foresight
Connected fleet telematics and AI-driven route optimization is rewriting how automotive parts and finished vehicles move across Arabian Peninsula trade corridors. DHL Supply Chain leverages its multi-modal hub in Dubai South to anchor regional distribution for European and Asian OEMs. Almajdouie Logistics dominates inbound finished-vehicle logistics into Saudi Arabia through its specialized car-carrier fleet and port-side processing facilities. Kuehne + Nagel competes on digital integration, offering real-time visibility platforms that extend customer control over cross-border automotive movements.
GCC automotive logistics encompasses the planning, execution, and control of vehicle and parts movement across six Gulf Cooperation Council states, typically operating through temperature-controlled warehousing, bonded zone management, and customs-cleared transit corridors designed to maintain OEM delivery schedules and vehicle integrity. Freight forwarding and warehousing command the largest service type shares, though inventory management is gaining traction as OEMs adopt leaner supply chain models. Road transport remains the dominant delivery mode for intra-GCC vehicle distribution, while sea freight handles bulk inbound volumes through Jebel Ali, King Abdullah Port, and Sohar. Electric vehicles represent the fastest-growing vehicle type segment, requiring specialized battery handling protocols and hazardous-materials-compliant storage infrastructure that incumbent providers are racing to certify.
Saudi Vision 2030 localization requirements and UAE customs modernization programs are reshaping inbound logistics patterns, with both frameworks incentivizing regional assembly over direct importation. The Saudi Standards, Metrology and Quality Organization and the Emirates Authority for Standardization and Metrology enforce vehicle homologation and parts-quality protocols that logistics providers must navigate at port of entry. Stakeholders should monitor how Gulf standardization convergence and evolving battery-transport regulations alter facility certification requirements and capital deployment timelines.
Market Dynamics
Saudi Vision 2030 localization mandates are compressing inbound supply chains toward regional manufacturing zones, forcing logistics providers to reconfigure port-to-plant networks around King Abdullah Economic City and Ras Al-Khair Industrial City.
Growth Catalysts
- EV battery logistics infrastructure:Specialized hazardous-materials storage and thermal management protocols are expanding facility certification requirements across Dubai South and Jeddah Islamic Port, drawing capital toward compliant warehousing.
- SASO homologation alignment:Converging Saudi Standards, Metrology and Quality Organization protocols with Emirates Authority for Standardization and Metrology standards is streamlining cross-border parts clearance, reducing dwell times at land borders.
- Jebel Ali corridor upgrading:Port-centric vehicle processing investments are consolidating redistribution volumes from Asian and European OEMs, anchoring regional finished-vehicle throughput.
Market Restraints
- Cross-border customs friction:Non-tariff barriers between Saudi Arabia and UAE persist despite GCC customs union frameworks, generating documentation delays at Al Ghuwaifat and Batha border crossings.
- Specialized fleet scarcity:Car-carrier capacity for finished-vehicle transport concentrates with established Saudi operators, limiting new entrant access to bonded trucking licenses.
- Battery transport certification gaps:IMDG Code and ADR-equivalent certifications for lithium-ion handling remain uneven across Bahrain, Kuwait, and Oman, constraining multi-country EV parts distribution.
Strategic Opportunities
- Oman Sohar port expansion:Underutilized vehicle processing capacity at Sohar Industrial Port offers alternative entry points for Asian OEMs seeking to bypass Jebel Ali congestion premiums.
- AI-driven yard management:Computer-vision inventory tracking and automated vehicle inspection systems are converging with existing telematics platforms, enabling real-time condition monitoring across bonded storage facilities.
- Saudi assembly localization:Lucid Motors and Ceer Motors manufacturing commitments under Vision 2030 are creating captive inbound parts logistics demand for tier-1 supplier clusters in King Abdullah Economic City.
Industry Challenges
- Temperature-controlled warehousing capex:Battery storage facilities require redundant cooling systems and fire-suppression infrastructure, extending payback periods for greenfield investments in Riyadh and Dammam logistics zones.
- Cross-platform telematics integration:OEM proprietary fleet management systems resist interoperability with third-party logistics visibility platforms, fragmenting real-time tracking across multi-modal handoffs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Automotive Logistics Market |
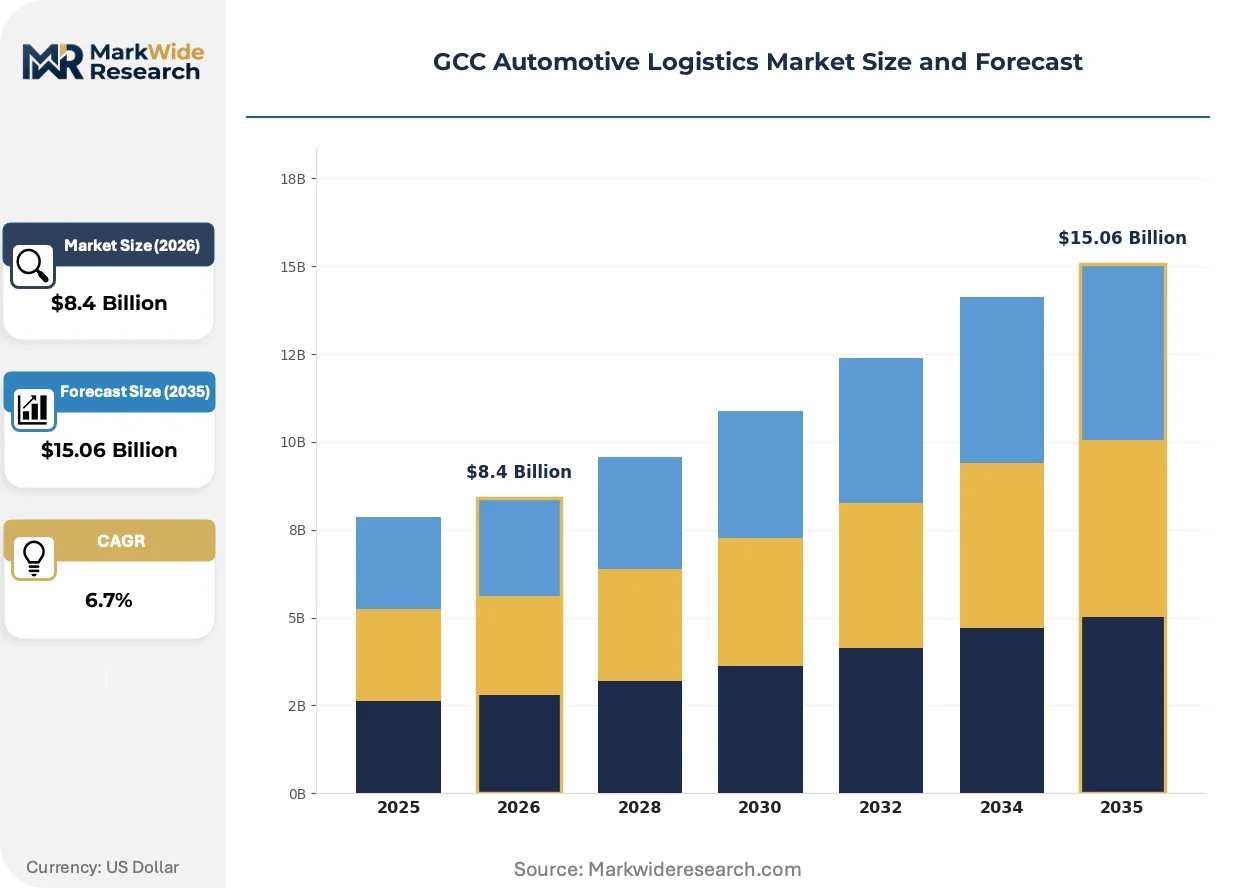
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Warehousing, Freight Forwarding, Inventory Management, Packaging, Distribution Delivery Mode: Road Transport, Rail Transport, Air Freight, Sea Freight Vehicle Type: Passenger Cars, Commercial Vehicles, Electric Vehicles, Two-Wheelers, Heavy Trucks Customer Type: Manufacturers, Dealers, Aftermarket Providers, Fleet Operators |
| Companies Covered | DHL Supply Chain, Kuehne + Nagel, DB Schenker, CEVA Logistics, Al-Futtaim Logistics, Aramex, GEODIS, Almajdouie Logistics, DP World, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Automotive Logistics Market Shifts & Advancements
Connected fleet infrastructure and predictive analytics are compressing planning horizons across Arabian Peninsula automotive corridors, replacing static routing with dynamic load balancing.
Blockchain-enabled documentation is collapsing settlement delays between freight forwarders, customs brokers, and OEM treasury functions. DHL Supply Chain and Almajdouie Logistics are piloting distributed-ledger bills of lading across Dubai-Saudi lanes, cutting document verification from days to hours. This compression is eliminating working-capital buffers that previously padded logistics pricing.
Saudi Standards, Metrology and Quality Organization vehicle homologation protocols are tightening parts-quality traceability requirements, mandating lot-level digital records for safety-critical components entering King Abdulaziz Port. Tier-1 suppliers are responding by embedding RFID tags at manufacturing origin, shifting compliance burden upstream from port-of-entry inspection to supplier certification.
Just-in-sequence delivery contracts are displacing traditional warehouse-and-ship arrangements for Saudi assembly plants. OEM procurement teams now specify hourly delivery windows rather than daily batch releases, compressing inventory buffers at supplier parks adjacent to King Abdullah Economic City. This behavioral shift concentrates logistics risk with providers capable of sub-24-hour replenishment cycles from Jeddah and Dammam feeder hubs.
GCC Automotive Logistics Market Segmentation
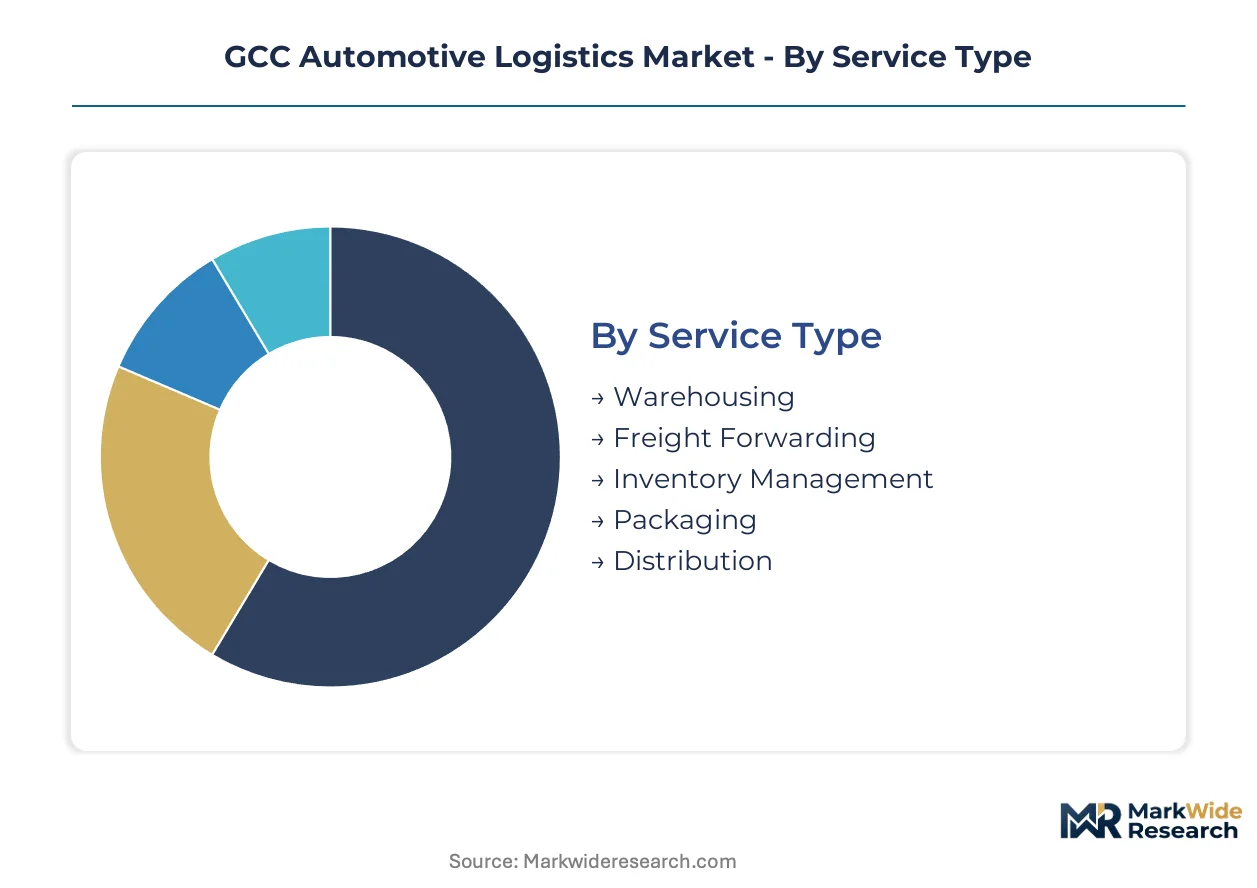
Logistics providers across the Arabian Peninsula configure service portfolios around vehicle handling complexity and regulatory compliance tiers. Segmentation reveals where capital concentrates and which delivery modes capture volume growth from electrification and localization mandates.
Service Type:
Cost tier determines facility investment intensity and margin structure across the GCC logistics stack.
- Freight Forwarding:Customs brokerage and documentation management anchor cross-border movements through Jebel Ali, King Abdulaziz Port, and Sohar. Demand clusters with European and Asian OEMs requiring bonded transit corridors into Saudi Arabia's King Abdullah Economic City manufacturing zones under Vision 2030 localization pressure.
- Warehousing:Temperature-controlled storage and bonded zone management maintain OEM delivery schedules and vehicle integrity across Dubai South and Dammam logistics corridors. Saudi Standards, Metrology and Quality Organization homologation protocols mandate lot-level digital records for safety-critical components, shifting compliance burden toward certified facilities.
- Inventory Management:Just-in-sequence delivery contracts now specify hourly replenishment windows rather than daily batch releases, compressing supplier park buffers adjacent to regional assembly plants.
- Packaging:Specialized crating and containerization for knock-down kits and battery modules protects high-value components through multi-modal handoffs.
- Distribution:Last-mile vehicle processing and dealer allocation systems manage finished-vehicle redistribution from port-centric hubs to showroom networks.
Freight forwarding commands the established base. The steepest expansion runs through inventory management as lean supply chain models displace traditional warehouse-and-ship arrangements.
Delivery Mode:
Volume throughput and infrastructure maturity shape modal selection across Arabian Peninsula trade corridors.
- Sea Freight:Bulk inbound vehicle and parts volumes move through Jebel Ali, King Abdullah Port, and Sohar Industrial Port, where port-centric processing capabilities are being upgraded to anchor regional redistribution.
- Road Transport:Car-carrier fleets and bonded trucking networks dominate intra-GCC finished-vehicle distribution, though capacity concentrates with established Saudi operators holding specialized licenses.
- Air Freight:Premium parts and urgent replenishment movements leverage Dubai's cargo infrastructure for time-critical assembly line feeds.
- Rail Transport:Etihad Rail network expansion offers intermodal alternatives for bulk container movements between UAE ports and Saudi inland logistics zones.
Sea freight commands the established base. The steepest expansion runs through road transport as Saudi assembly localization intensifies port-to-plant network requirements.
Vehicle Type:
Application complexity drives specialized handling protocols and facility certification demands.
- Electric Vehicles:Lithium-ion battery logistics requires hazardous-materials-compliant storage infrastructure with redundant cooling systems and fire-suppression protocols. IMDG Code and ADR-equivalent certifications remain uneven across Bahrain, Kuwait, and Oman, constraining multi-country parts distribution networks.
- Passenger Cars:Finished-vehicle processing and yard management systems handle the highest volume throughput across GCC port facilities, with computer-vision inventory tracking enabling real-time condition monitoring.
- Commercial Vehicles:Heavy-duty truck and bus logistics involves specialized lifting equipment and oversized transport permits across cross-border corridors.
- Heavy Trucks:Mining and construction equipment movements require low-loader fleets and route planning around infrastructure weight restrictions.
- Two-Wheelers:Motorcycle and scooter distribution leverages consolidated container stuffing for cost-efficient last-mile delivery to dealer networks.
Passenger cars command the established base. The steepest expansion runs through electric vehicles as battery transport regulations and thermal management infrastructure draw capital toward compliant warehousing.
Customer Type:
Customer maturity and procurement sophistication determine contract structures and service level requirements.
- Manufacturers:OEM procurement teams specify sub-24-hour replenishment cycles and real-time visibility platforms, concentrating logistics risk with providers capable of just-in-sequence delivery to Saudi assembly plants.
- Dealers:Franchise network distribution requires flexible allocation systems responding to regional demand variation across UAE showroom clusters and Saudi provincial markets.
- Aftermarket Providers:Spare parts logistics demands high-SKU warehousing with rapid pick-and-pack operations serving independent repair networks.
- Fleet Operators:Commercial vehicle leasing companies require consolidated maintenance parts logistics and vehicle lifecycle management services.
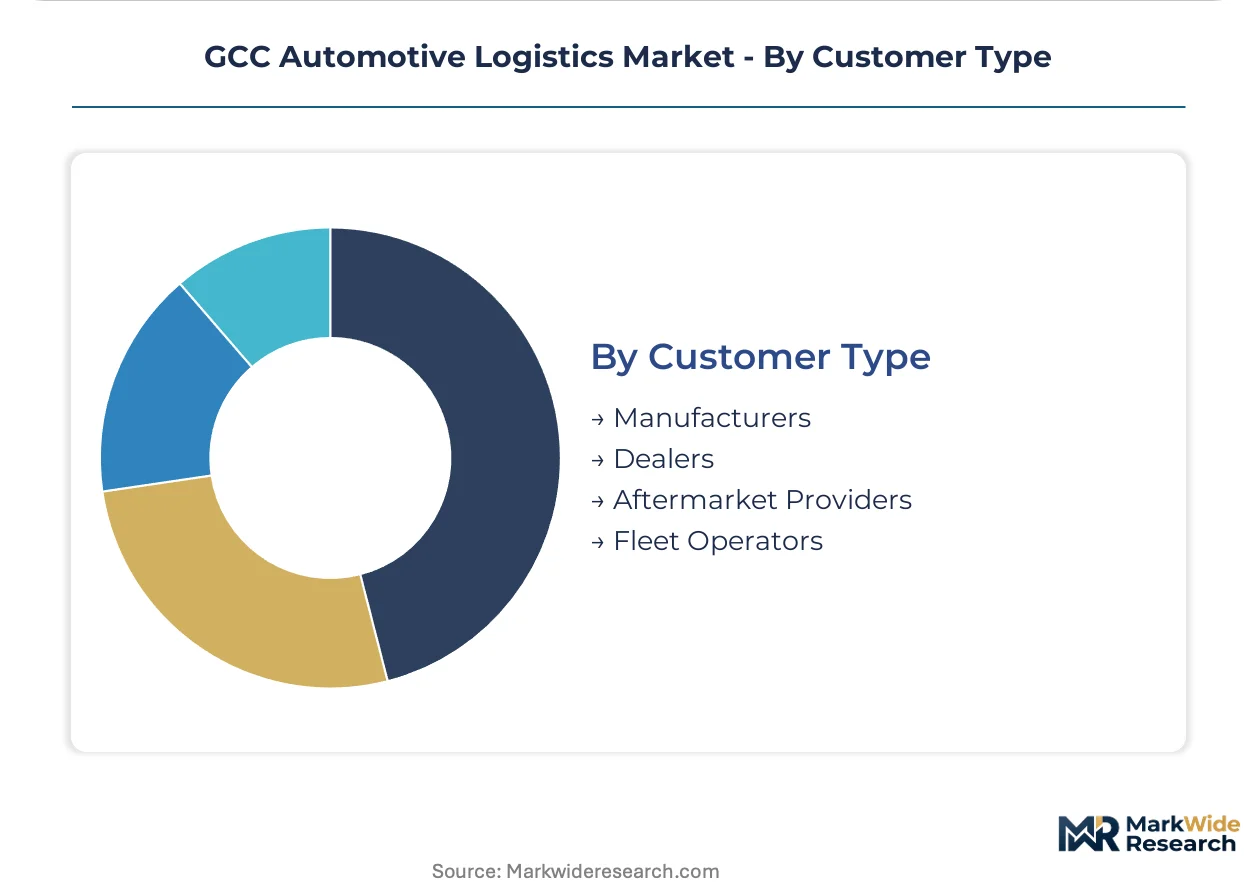
Manufacturers command the established base. The steepest expansion runs through aftermarket providers as vehicle parc growth and service interval compression expand addressable logistics demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia exports finished vehicles and knock-down kits across Arabian Peninsula corridors, while the UAE re-exports Asian and European OEM volumes through Jebel Ali's redistribution hub. This bilateral trade flow anchors GCC automotive logistics infrastructure investment and cross-border capacity allocation.
Saudi Arabia
Lucid Motors and Ceer Motors assembly commitments under Vision 2030 are compressing inbound parts supply chains toward King Abdullah Economic City. The Saudi Standards, Metrology and Quality Organization enforces lot-level digital traceability for safety-critical components entering King Abdulaziz Port. Dammam logistics zones are absorbing temperature-controlled warehousing capex for battery storage compliance.
United Arab Emirates
Jebel Ali corridor upgrading consolidates redistribution volumes from Asian and European OEMs seeking regional market access. The Emirates Authority for Standardization and Metrology aligns homologation protocols with Saudi counterparts, streamlining cross-border parts clearance. Dubai South anchors DHL Supply Chain's multi-modal hub for European and Asian manufacturer distribution networks.
Oman
Underutilized vehicle processing capacity at Sohar Industrial Port offers Asian OEMs alternative entry points bypassing Jebel Ali congestion premiums. The country's national transport regulator maintains IMDG Code certification gaps for lithium-ion handling that constrain multi-country EV parts distribution. Sohar Freezone is attracting bonded warehousing investment for regional redistribution plays.
Qatar
Luxury vehicle import demand supports premium finished-vehicle logistics through Hamad Port's specialized car-carrier facilities. The Qatar Financial Centre regulatory framework incentivizes logistics provider regional headquarters establishment. Ras Laffan industrial corridor remains peripheral to automotive logistics flows but offers contingency port capacity.
Kuwait
Aftermarket parts distribution dominates logistics demand through Shuwaikh Port's high-SKU warehousing operations serving regional repair networks. The country's national standardization body maintains uneven ADR-equivalent certifications for battery transport that fragment EV logistics network integration. Mina Abdullah vehicle terminal expansion targets transshipment volume capture from Saudi border delays.
GCC Automotive Logistics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across bonded warehousing, port-centric processing, and cross-border trucking segments. The vendor base concentrates around three strategic archetypes: global forwarders with digital visibility platforms, regional specialists with captive fleet assets, and port operators with integrated yard management capabilities. Dominant competitive moves include M&A-driven geographic expansion and strategic partnerships for battery-handling certification.
Among global forwarders, DHL Supply Chain and Kuehne + Nagel exemplify the digital-integration archetype, occupying positions anchored on real-time visibility platforms that extend customer control over cross-border movements. Almajdouie Logistics represents the regional specialist tier, with its position deriving from specialized car-carrier fleet concentration and port-side processing facility control in Saudi Arabia.
| Leading Market Players |
|---|
| DHL Supply Chain |
| Kuehne + Nagel |
| DB Schenker |
| CEVA Logistics |
| Al-Futtaim Logistics |
| Aramex |
| GEODIS |
| Almajdouie Logistics |
| DP World |
| Others |
Supply & Pricing Matrix
Car-carrier fleet concentration in Saudi Arabia funnels margin capture toward established operators holding bonded trucking licenses, while European and Asian OEM procurement teams squeeze logistics providers through just-in-sequence contract terms that compress payment cycles.
Pricing Analysis
Current-generation EV battery handling commands premium facility rates against prior-generation finished-vehicle storage and next-generation autonomous logistics infrastructure still in pilot phase. Contract-based long-term offtake structures dominate manufacturer relationships, with price differentiation hinging on SASO certification tier and volume scale commitments. Cost compression in standard warehousing tiers is intensifying because Jebel Ali corridor congestion premiums are eroding. Fleet operators exhibit highest price sensitivity due to thin maintenance parts margins, while luxury OEMs tolerate premium rates for bonded zone integrity.
Supply Chain Analysis
Extended payment terms from Saudi assembly plants toward tier-1 suppliers are straining working capital across Dubai South feeder networks. Component sourcing draws from Germany, China, and Japan for precision parts, while battery cell supply rests on South Korea and China. Single-source vulnerability concentrates in specialized car-carrier capacity controlled by Almajdouie Logistics and select Saudi operators. Distribution runs through port-centric hubs at Jebel Ali, King Abdulaziz Port, and Sohar, with bonded trucking completing last-mile dealer allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC automotive logistics represents an early-cycle expansion story, with EV battery logistics infrastructure buildout and Saudi assembly localization creating fresh capacity demand that incumbent providers are racing to capture.
For Market Incumbents: Insulate core port-to-plant networks by securing IMDG Code certifications for lithium-ion handling ahead of regulatory harmonization across Bahrain, Kuwait, and Oman. Expand temperature-controlled warehousing in Dammam logistics zones to preempt battery storage compliance requirements. Vertical integration into yard management technology through computer-vision partnerships defends against digital-forward global forwarders. For New Entrants and Emerging Players: Sohar Industrial Port's underutilized vehicle processing capacity represents the most penetrable entry point for Asian OEMs seeking Jebel Ali bypass strategies. Saudi tier-1 supplier clusters adjacent to King Abdullah Economic City offer white-space inventory management contracts as just-in-sequence mandates displace traditional warehouse-and-ship arrangements. A digital-native visibility platform targeting mid-size European OEMs provides the strongest go-to-market angle against established operator telematics fragmentation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional specialists holding captive fleet assets but lacking battery-handling certification. Long-term viability across the projection horizon favors providers with demonstrated compliance navigation across SASO and ESMA convergence. Watch for Saudi Vision 2030 localization milestone announcements as the signal indicating accelerated inbound parts logistics demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell logistics capacity with hazardous-materials-certified warehousing at Jeddah Islamic Port. |
| Geographic Manufacturing Footprint | Establishes tier-1 supplier park proximity to King Abdullah Economic City assembly plants for sub-24-hour replenishment. |
| Platform Integration | Unifies OEM proprietary telematics with third-party visibility platforms across Dubai-Saudi cross-border corridors. |
| Strategic Partnership | Aligns Etihad Rail intermodal capacity with port-centric vehicle processing for bulk container movements. |
| Acquisition of Specialist Firm | Consolidates bonded trucking licenses and car-carrier fleet assets in Saudi Arabia's concentrated operator market. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, tier-1 supplier procurement leads, bonded warehouse operators at Dubai South, and customs brokerage specialists at Jebel Ali. Secondary validation incorporated customs and trade data from GCC national statistics offices, vehicle production databases tracking Saudi assembly localization, IHS Markit registration data, and SASO homologation filing records. Bottom-up service-type volume estimates and top-down regional GDP elasticity models were triangulated to anchor market sizing.
Calibration against historical capacity deployment patterns and announced facility investments shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, delivery mode, vehicle propulsion architecture, and regional production cluster. CAGRs were derived from trend extrapolation adjusted for policy-driven inflection points, with forecast inputs incorporating Vision 2030 localization milestone schedules and battery transport regulation harmonization timelines.
Macroeconomic conditions sit as an overlay; deviation in oil price volatility, GCC currency peg stability, or regional construction activity would shift the trajectory. Forecasts reflect documented assumptions around regulatory implementation pace and infrastructure completion schedules. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Last Mile Delivery Transportation Market
Logistics and Shipping
Japan Freight and Logistics Market
Logistics and Shipping
Express Delivery Market
Logistics and Shipping
Sweden Freight and Logistics Market
Logistics and Shipping
North America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Freight Brokerage Market
Logistics and Shipping
GCC Contract Logistics Market
Logistics and Shipping
Saudi Arabia Secure Logistics Market
Logistics and Shipping
UAE Contract Logistics Market
Logistics and Shipping
Smart Container Market
Logistics and Shipping
GCC Secure Logistics Market
Logistics and Shipping
Global Load Planning Services and Solutions Market
Logistics and Shipping
South Korea Third-Party Logistics (3PL) Market
Logistics and Shipping
Straddle Carrier Market
Logistics and Shipping
Cargo Transportation Market
Logistics and Shipping
Global Courier Market