
 Middle East Paper Making Machine Market | 2026-2036
Middle East Paper Making Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Paper Making Machine Market Insights
After-sales maintenance contracts is expanding across the Middle East Paper Making Machine Market as Gulf buyers prioritize uptime guarantees over upfront equipment discounts. Crown Paper Mill leverages captive technical teams to reduce third-party service dependency. Middle East Paper Company (MEPCO) anchors its regional position through integrated spare parts warehousing in Jeddah. Obeikan Investment Group differentiates by bundling operator training with multi-year service agreements.
Paper making machines form continuous webs of cellulose fibers through wet-laid formation, pressing, drying, and calendering stages, typically operating at speeds exceeding 1,000 meters per minute for packaging grades. These systems transform wood pulp or recycled furnish into finished reels for downstream converting. Sheet Machines dominate current order books across the Middle East as carton board producers prioritize cut-size flexibility for corrugated box plants. Automation technology commands premium pricing as labor scarcity in Saudi Arabia pushes converters toward reduced-headcount operations. Specialty Machines represent the fastest-growing segment as regional tissue producers invest in through-air-drying configurations for premium hygiene products.
Saudi Standards, Metrology and Quality Organization (SASO) enforces energy efficiency labeling on imported paper machinery, while the UAE's Ministry of Industry and Advanced Technology ties industrial incentives to local content thresholds. Both frameworks compel foreign suppliers to establish regional assembly or certification partnerships. Stakeholders must monitor how Egypt's pending harmonization with Gulf technical regulations reshapes cross-border equipment flows and aftermarket service obligations.
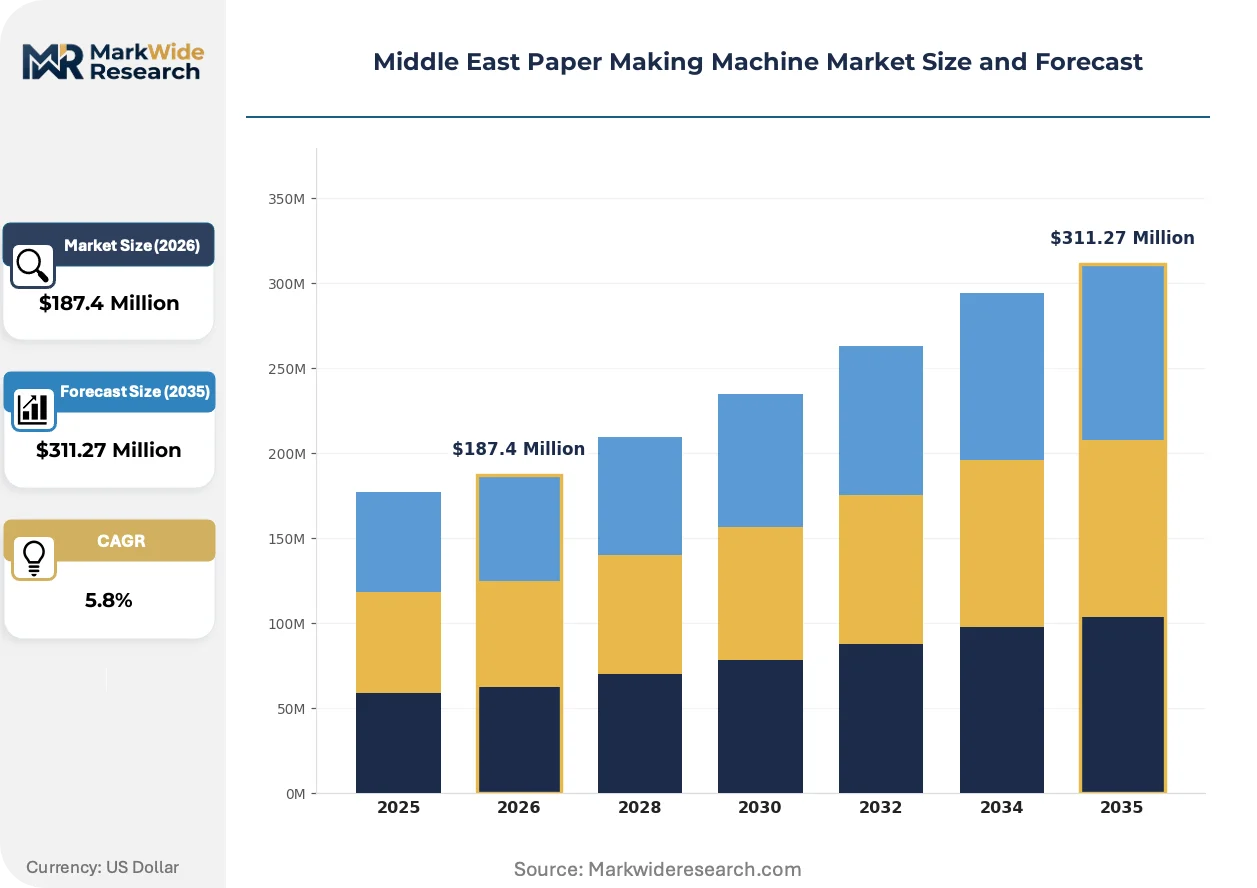
Market Dynamics
E-commerce packaging demand across Saudi Arabia and the UAE is compressing replacement cycles for aging machinery fleets, while SASO energy efficiency mandates force equipment upgrades that prioritize automated quality control systems over manual inspection stations.
Growth Catalysts
- SFDA packaging safety standards:Saudi food-grade paperboard regulations mandate contamination detection systems that only newer machine vintages can integrate, pulling forward capital expenditure timelines for Jeddah-based converters.
- Recycled furnish processing:Regional deinking and dispersion technologies now handle mixed recovered fiber streams that previously required virgin pulp, lowering raw material costs for corrugated medium producers.
- UAE industrial incentives:The Ministry of Industry and Advanced Technology ties tariff reductions to local assembly partnerships, accelerating foreign supplier establishment of Dubai-based technical service hubs.
Market Restraints
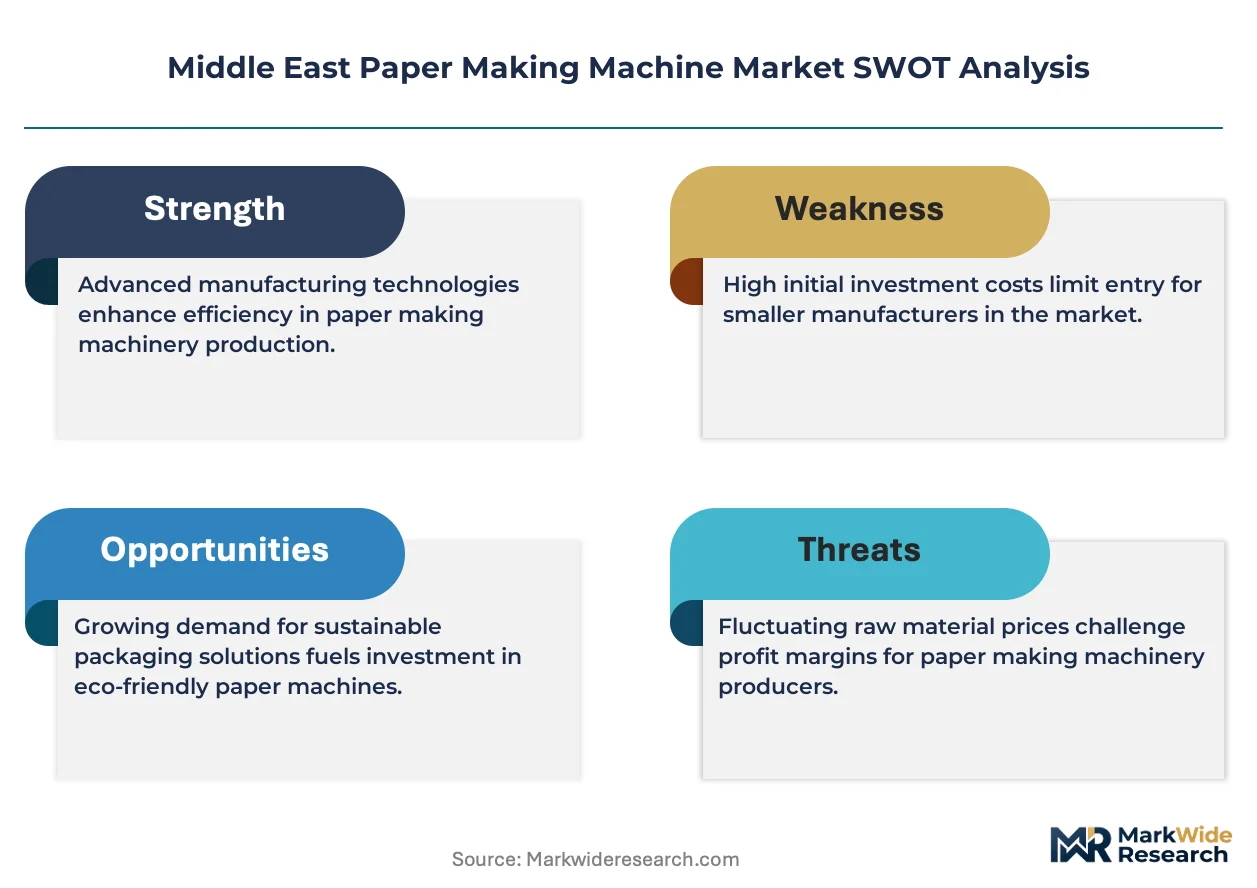
- Specialized alloy supply concentration:Dryer cylinder castings and Yankee metallurgy depend on European and East Asian foundry capacity, exposing delivery timelines to ocean freight volatility.
- Technical skill scarcity:Wet-end chemistry optimization and creping blade geometry adjustment require experience that regional technical institutes have not yet scaled to match machine installation rates.
- Water treatment capex burden:Closed-loop effluent systems for tissue machines add installation costs that stretch payback periods beyond typical financing tenors available to mid-size Gulf producers.
Strategic Opportunities
- Egyptian regulatory harmonization:Pending alignment with Gulf technical regulations would unlock cross-border service obligations and create integrated spare parts distribution spanning Cairo to Jeddah corridors.
- Through-air-drying tissue configurations:Premium hygiene product demand in Saudi Arabia and the UAE creates white space for specialty machine orders that command higher margins than commodity packaging lines.
- Remote diagnostics convergence:Machine learning predictive maintenance layered on existing automation platforms enables Gulf converters to reduce headcount while guaranteeing uptime through vendor-managed service contracts.
Industry Challenges
- Commissioning timeline compression:E-commerce delivery windows pressure packaging converters to accelerate machine acceptance testing, straining vendor technical teams already stretched across multiple simultaneous installations.
- Legacy control system integration:Brownfield sites in Riyadh's industrial corridor struggle to synchronize new quality control modules with decades-old distributed control architectures without full line replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Paper Making Machine Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheet Machines, Roll Machines, Specialty Machines, Integrated Lines Technology: Traditional, Digital, Automation, Eco-Friendly End User: Packaging Industry, Printing Industry, Stationery Manufacturers, Tissue Producers Capacity: Small Scale, Medium Scale, Large Scale, High Capacity |
| Companies Covered | Crown Paper Mill, Middle East Paper Company (MEPCO), United Carton Industries Company (UCIC), Obeikan Investment Group, Gulf Carton Factory Company, Arabian Kraft Paper Manufacturing LLC, NAPCO National, DKM Machine Manufacturing Inc, Qingdao Perfect Equipment, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Paper Making Machine Market Trends and Innovations
Machine intelligence and regulatory stringency are converging to redefine equipment specification criteria across Middle Eastern paper mills, with buyer priorities shifting from throughput metrics to guaranteed operational continuity under tightening environmental and safety frameworks.
Automated quality control systems using machine vision and spectroscopic sensors are automating defect detection in linerboard and medium production, eliminating manual inspection stations that previously required three-operator shifts. Major corrugated packaging converters in Saudi Arabia's Jeddah-Riyadh corridor are specifying these systems as standard rather than optional equipment. The technology is automating workforce reduction strategies that address labor scarcity while simultaneously satisfying SASO traceability requirements for export-bound carton board.
SASO energy efficiency labeling mandates now require imported paper machinery to display standardized consumption metrics, compelling European and Asian original equipment manufacturers to redesign thermal systems and establish regional certification partnerships. The framework compresses allowable dryer section energy intensity thresholds on a three-year ratchet schedule. Packaging grade producers face the steepest compliance trajectory, as tissue machines already incorporate heat recovery systems that meet near-term benchmarks.
After-sales service unbundling is fragmenting traditional equipment procurement patterns across the UAE and Saudi Arabia, with converters separating capital acquisition from multi-year maintenance and spare parts agreements. Vendor technical teams now compete for standalone service contracts that previously bundled automatically with machine sales. This behavioral shift concentrates most visibly in Dubai's converting cluster, where packaging specialists prioritize uptime guarantees over upfront equipment discounts when evaluating supplier proposals.
Middle East Paper Making Machine Market Segmentation
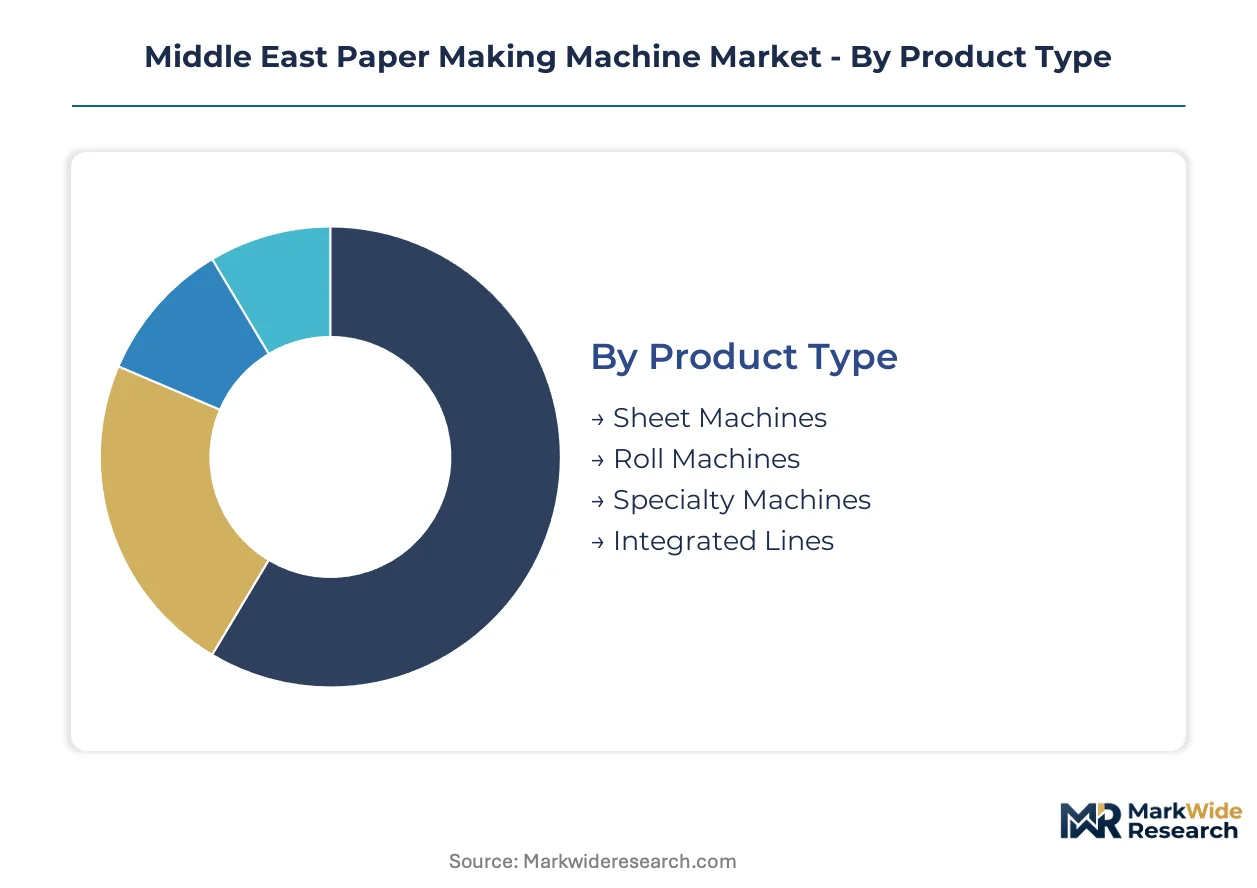
Paper making machine procurement across the Middle East diverges sharply by operational scale and downstream application. Saudi and UAE buyers prioritize configurable platforms that accommodate rapid grade changes, while Egyptian producers emphasize capital efficiency over customization depth.
Product Type:
Customization intensity spans from standardized commodity platforms to fully engineered specialty configurations, with buyer willingness to pay premium engineering fees correlating directly with downstream margin capture.
- Sheet Machines:Cut-size formation systems dominate order books across Jeddah and Riyadh converting corridors. Carton board producers specify these platforms for corrugated box plants requiring rapid format changes between linerboard and medium grades.
- Specialty Machines:Through-air-drying configurations command premium positioning as Saudi and UAE tissue producers expand premium hygiene capacity. These systems integrate creping blade geometry controls that manual adjustment cannot replicate.
- Roll Machines:Continuous reel production systems serve high-volume kraft paper operations with limited grade variation requirements.
- Integrated Lines:Complete stock-preparation-to-reel systems reduce installation complexity for greenfield sites in Dubai's industrial zones.
Leading the category by volume: Sheet Machines. Growing fastest: Specialty Machines.
Technology:
Capital allocation splits between proven mechanical platforms and digitally augmented systems, with labor scarcity in Saudi Arabia accelerating the shift toward reduced-headcount operations.
- Automation:Machine vision quality control and predictive maintenance modules now specify as standard rather than optional across UAE packaging converters. Dubai-based technical service hubs support these installations with vendor-managed uptime contracts.
- Eco-Friendly:Heat recovery dryers and closed-loop effluent systems align with SASO energy efficiency ratchet schedules. Packaging grade producers face steepest compliance trajectories as tissue machines already meet near-term benchmarks.
- Traditional:Conventional mechanical drives persist in Egyptian operations where capital constraints outweigh efficiency gains.
- Digital:Distributed control architectures enable remote diagnostics convergence, though brownfield Riyadh sites struggle with legacy system synchronization.
Automation captures the largest share of technology spending. Eco-Friendly configurations are expanding most quickly.
End User:
Demand concentration maps directly to e-commerce logistics infrastructure buildout, with packaging converters outspending all other downstream categories on replacement cycles.
- Packaging Industry:Corrugated medium and linerboard producers across Saudi Arabia's Jeddah-Riyadh corridor drive equipment replacement. SFDA food-grade regulations mandate contamination detection systems that accelerate capital expenditure timelines.
- Tissue Producers:Premium hygiene product demand in Saudi Arabia and the UAE creates capacity expansion requirements. Through-air-drying technology investments target absorbent product segments with higher margin profiles.
- Printing Industry:Newsprint and publication grade producers maintain selective investment patterns amid digital substitution pressures.
- Stationery Manufacturers:Cut-size copy paper operations serve regional education and office supply channels with stable but muted growth.
Packaging Industry leads end user spending. Tissue Producers show the steepest expansion trajectory.
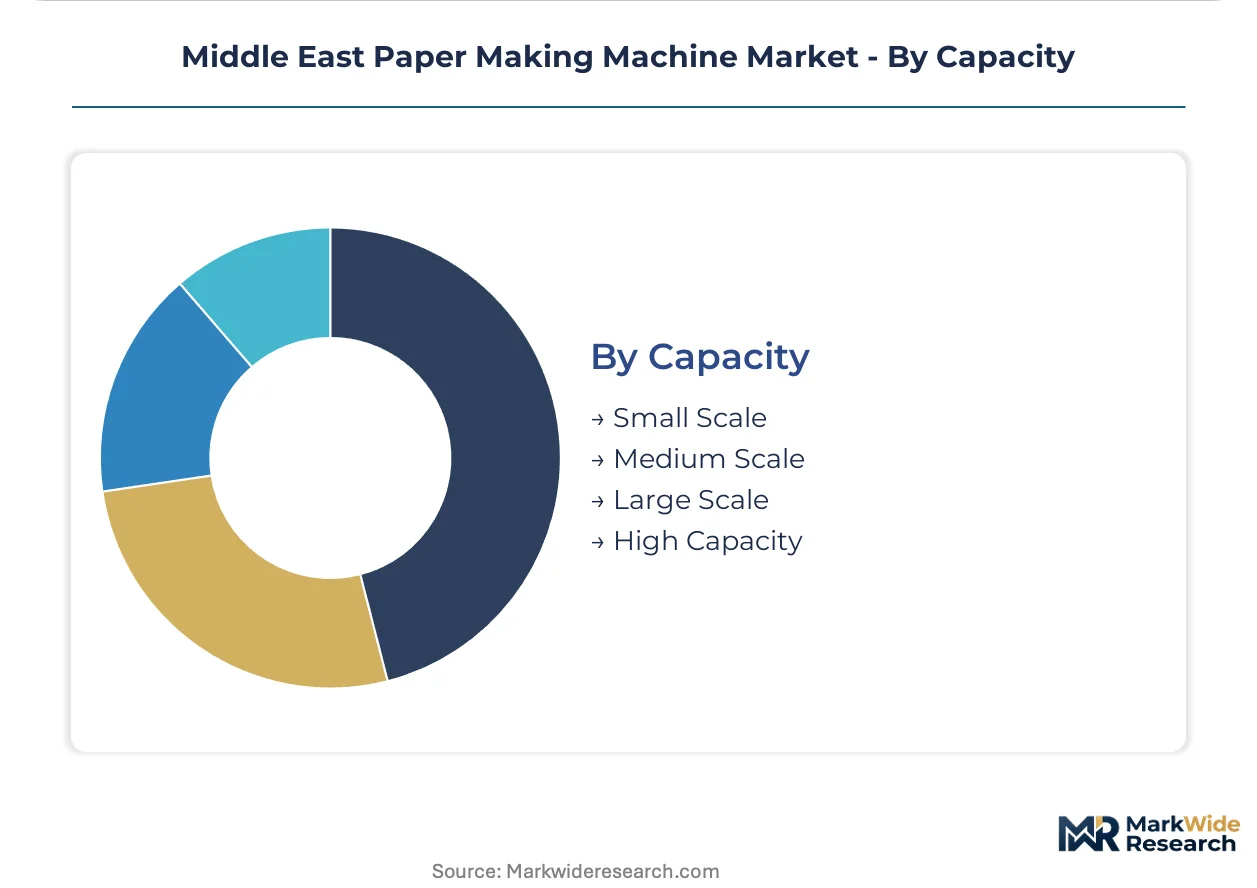
Capacity:
Scale selection reflects financing availability and raw material security, with integrated pulp producers favoring maximum throughput configurations.
- Large Scale:High-speed formation and drying sections exceed 1,000 meters per minute for packaging grades. These systems require captive wood pulp or deinked furnish supply security that only major Saudi producers can guarantee.
- High Capacity:Maximum throughput configurations serve regional export-oriented producers targeting Asian tissue and board markets.
- Medium Scale:Mid-tonnage platforms balance capital efficiency with grade flexibility for independent Egyptian converters.
- Small Scale:Compact installations serve specialized niche grades and pilot production requirements.
Large Scale systems anchor the category by installed base. High Capacity configurations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional production capacity outpaces domestic consumption across the Middle East, creating export-oriented investment patterns that concentrate machinery procurement near port infrastructure and industrial zones with captive pulp supply.
Saudi Arabia
E-commerce logistics expansion drives corrugated packaging demand across the Jeddah-Riyadh corridor. SASO energy efficiency labeling mandates compress replacement cycles for aging dryer sections. Jeddah's industrial zone anchors the kingdom's paperboard capacity, with converters upgrading formation systems to meet SFDA food-grade contamination detection requirements.
United Arab Emirates
Dubai's converting cluster prioritizes uptime guarantees through vendor-managed service contracts over upfront equipment discounts. The Ministry of Industry and Advanced Technology ties tariff reductions to local assembly partnerships, accelerating foreign supplier establishment of technical service hubs. Abu Dhabi's industrial zones attract integrated line installations for greenfield packaging operations.
Egypt
Pending harmonization with Gulf technical regulations would unlock cross-border spare parts distribution spanning Cairo to Jeddah corridors. Capital constraints favor mid-tonnage platforms over maximum throughput configurations. Alexandria's port-adjacent industrial zones serve as the primary entry point for European machinery imports.
Qatar
Specialty tissue capacity expansion targets premium hygiene export markets with through-air-drying configurations. Local content requirements in government procurement shape supplier partnership structures. Doha's industrial area concentrates small-scale pilot installations for niche grade development.
Kuwait
Packaging converter consolidation creates demand for flexible sheet machines accommodating rapid grade changes between linerboard and medium. Water scarcity drives investment in closed-loop effluent systems that extend payback periods. Shuwaikh's industrial district hosts the country's primary paperboard manufacturing base.
Middle East Paper Making Machine Market Competitive Landscape
Top-tier vendors anchor premium automation and service-contract offerings, while mid-tier fabricators compete on capital efficiency and regional assembly partnerships. European and East Asian original equipment manufacturers dominate high-speed formation and drying technology. Strategic archetypes separate into full-line system integrators, specialty machine builders, and aftermarket service specialists. Competitive moves concentrate on establishing Dubai-based technical service hubs and securing multi-year maintenance agreements independent of initial equipment sales.
Within the regional converter tier, Crown Paper Mill and Middle East Paper Company (MEPCO) represent integrated producers with captive technical capabilities that reduce third-party service dependency. Obeikan Investment Group occupies a position bundling operator training with extended service agreements. These three anchors exemplify the shift toward unbundled procurement patterns where uptime guarantees outweigh upfront equipment discounts in supplier selection criteria.
| Leading Market Players |
|---|
| Crown Paper Mill |
| Middle East Paper Company (MEPCO) |
| United Carton Industries Company (UCIC) |
| Obeikan Investment Group |
| Gulf Carton Factory Company |
| Arabian Kraft Paper Manufacturing LLC |
| NAPCO National |
| DKM Machine Manufacturing Inc |
| Qingdao Perfect Equipment |
| Others |
Pricing and Supply Chain Analysis
Wet-end chemistry specialists concentrated in Germany and Finland command wage premiums that widen spreads between premium automation tiers and standard mechanical configurations across Middle Eastern procurement decisions.
Pricing Analysis
Margin tightening in standard-grade sheet machines reflects European foundry capacity constraints on dryer cylinder castings. Three-tier pricing structure across premium, standard, and economy levels separates vendors offering integrated predictive maintenance from those selling bare mechanical platforms. Price differentiation hinges on after-sales service bundling and SASO energy efficiency certification tier. Egyptian converters exhibit highest price sensitivity due to capital constraints, while UAE packaging clusters prioritize uptime guarantees over upfront discounts.
Supply Chain Analysis
Yankee dryer metallurgy and specialized alloy castings rest on German, Italian, and Japanese foundry capacity. Critical inputs span high-grade steel forgings, ceramic coating substrates, and precision creping blade materials. Single-source vulnerability concentrates in European thermal system engineering for through-air-drying configurations. Distribution runs through Dubai-based technical service hubs that anchor spare parts warehousing for Gulf converter clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East Paper Making Machine Market sits in a technology-transition phase where machine vision quality control systems displace manual inspection stations across Saudi and UAE packaging corridors.
For Market Incumbents: Deploy captive technical service teams to reduce third-party dependency as Gulf buyers unbundle procurement patterns. Secure multi-year maintenance contracts independent of initial equipment sales to lock in recurring revenue streams. Crown Paper Mill and MEPCO already demonstrate this model through integrated spare parts warehousing in Jeddah. For New Entrants and Emerging Players: Launch via remote diagnostics partnerships with established automation vendors to bypass capital-intensive field service infrastructure. Target Egyptian mid-tonnage converters awaiting regulatory harmonization with Gulf technical standards. Bundle operator training programs with equipment sales to differentiate against incumbents lacking regional workforce development capabilities. For Investors and Strategic Acquirers: Re-rating potential sits with aftermarket service specialists given the unbundling trend accelerating across Dubai's converting cluster. Long-term viability favors vendors with established regional certification partnerships under SASO energy efficiency frameworks. Watch Egyptian regulatory harmonization progress as the signal indicating cross-border spare parts distribution integration timing.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Assembly Partnership | UAE Ministry of Industry tariff reductions accelerate Dubai-based technical hub establishment. |
| Predictive Maintenance Platform | Machine learning modules reduce Gulf converter headcount while guaranteeing uptime through vendor contracts. |
| Spare Parts Warehousing | Jeddah-anchored distribution cuts service response times for Saudi Arabia's industrial corridor. |
| Operator Training Bundling | Obeikan Investment Group differentiates extended service agreements with workforce development programs. |
| Energy Efficiency Certification | SASO labeling mandates force thermal system redesigns that compress replacement cycles for aging dryer sections. |
Research Methodology
Trade customs databases, OEM technical documentation, and Gulf industrial zone investment filings formed the secondary backbone for this analysis. Primary interviews with maintenance directors at Saudi packaging converters, procurement leads at UAE carton board producers, aftermarket service heads at European suppliers, and plant engineers across Egypt's Alexandria corridor combined with secondary validation. Bottom-up and top-down triangulation cross-checked installation data against regional capacity announcements.
Bottom-up modeling aggregated individual machine orders by product type, technology tier, and end-user segment across the projection horizon. Segmentation dimensions spanned machine configuration, automation intensity, downstream application, and operational scale. CAGRs derived from fitted growth curves applied to verified baseline values. Industry-specific forecast inputs incorporated SASO regulatory ratchet schedules and e-commerce packaging demand trajectories from logistics infrastructure buildout data.
Regulatory enforcement delays, foundry capacity disruptions, and financing availability constraints for Egyptian mid-size producers are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about technology adoption curves and trade policy continuity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Gas Holders Market
Others
Global Sportswear Market
Others
Latin America Domestic CEP Market
Others
Rope Market
Others
PC As a Service Market
Others
Mainframe Computers Market
Others
Global Animal Feed Protein Ingredients Market
Others
Animal Feed Alternative Protein Market
Others
Workbench Tanks Market
Others
Global Smart Kitchen Market
Others
AC Switchgear Market
Others
Refractometer Market
Others
Deep Sea Mining Market
Others
Floor Cleaning and Mopping Machine Market
Others
High Frequency Vibrator Market
Others
Digital Bass Processor Market