
 Digital Bass Processor Market | 2026-2036
Digital Bass Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Bass Processor Market Insights
Digital signal processing architectures with real-time parametric equalization is rewriting how bass processors integrate into modern audio chains. AudioControl leverages proprietary DSP algorithms to sustain technology leadership in vehicle-specific tuning solutions. Hifonics anchors its competitive stance through manufacturing scale across North American distribution channels. Soundstream differentiates via specialized amplifier-processor hybrid designs that occupy niche aftermarket segments.
A digital bass processor is an electronic audio device that manipulates low-frequency signals through adjustable crossover points, subsonic filtering, and phase alignment to optimize subwoofer performance in professional and consumer environments. These units typically operate below 120 Hz with 24 dB/octave slope capabilities, serving primarily to correct acoustic anomalies and extend clean bass output without driver distortion. DSP-Based Solutions command the fastest expansion as live sound engineers adopt laptop-controlled tuning workflows, while Analog Processing retains margin pools among studio purists seeking transformer-coupled signal paths. Rack-Mount Units dominate installed broadcasting infrastructure, though Software Plugins erode that base among project-studio operators.
The FCC governs electromagnetic emissions for electronic audio equipment sold in the United States, compelling manufacturers to secure equipment authorization before market entry. CE marking under the EU's EMC Directive shapes access to European consumer channels, while RoHS restrictions constrain solder and component selections across all export-bound production. Stakeholders must monitor whether automotive OEMs internalize bass processing into head-unit firmware, potentially collapsing standalone processor demand in factory-install segments.
Market Dynamics
The automotive audio aftermarket is experiencing structural pressure from OEM integration of bass processing into factory head units, forcing standalone processor manufacturers to pivot toward retrofit specialists and commercial sound contractors. This concentration of demand is reshaping channel economics and R&D allocation across the value chain.
Growth Catalysts
- FCC Equipment Authorization:The United States regulator mandates electromagnetic compliance for electronic audio devices, creating a certification moat that filters low-quality imports and sustains margin pools for authorized manufacturers serving the aftermarket automotive segment.
- Live Sound Reinforcement:Touring audio engineers now deploy laptop-controlled DSP workflows for real-time venue tuning, expanding processor adoption beyond fixed installations into mobile production environments.
- German Automotive Corridor:Stuttgart and Ingolstadt host dense clusters of OEM integration partnerships, where specialized bass processor development for factory audio systems concentrates engineering talent and testing infrastructure.
Market Restraints
- Semiconductor Input Volatility:DSP chip fabrication depends on concentrated foundry capacity in Taiwan, exposing processor manufacturers to lead-time volatility and margin compression during supply crunches.
- Software Plugin Substitution:Universal Audio and Waves plugins now offer subsonic filtering and phase alignment within DAW environments, eroding demand for hardware rack-mount units among project-studio operators.
- CE Marking Complexity:The EU's EMC Directive requires extensive testing documentation for electronic audio equipment, extending time-to-market for smaller manufacturers lacking dedicated compliance departments.
Strategic Opportunities
- India Aftermarket Expansion:Delhi and Mumbai show underpenetrated demand for vehicle audio upgrades as disposable income rises among urban car owners, creating first-mover advantages for distributors establishing local installation networks.
- PLI Scheme Alignment:India's Production Linked Incentive scheme for electronics manufacturing offers cost offsets for domestic assembly operations, enabling landed-cost advantages for processors produced in Noida or Chennai facilities.
- Amplifier-Processor Convergence:Hybrid designs integrating DSP with Class-D amplification reduce rack space and cabling complexity, appealing to mobile DJs and compact venue operators seeking streamlined signal chains.
Industry Challenges
- DSP Firmware Talent Scarcity:Real-time audio algorithm development requires specialized expertise in filter topology and latency optimization, with qualified engineers concentrated among a handful of semiconductor and pro-audio firms.
- Legacy Analog Integration:Studio facilities with transformer-coupled signal paths demand careful impedance matching when inserting digital processors, complicating sales cycles and technical support burdens.
- RoHS Component Sourcing:Lead-free solder and restricted substance compliance constrains component selection across all export-bound production, particularly affecting capacitor and connector specifications in high-current audio paths.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Bass Processor Market |
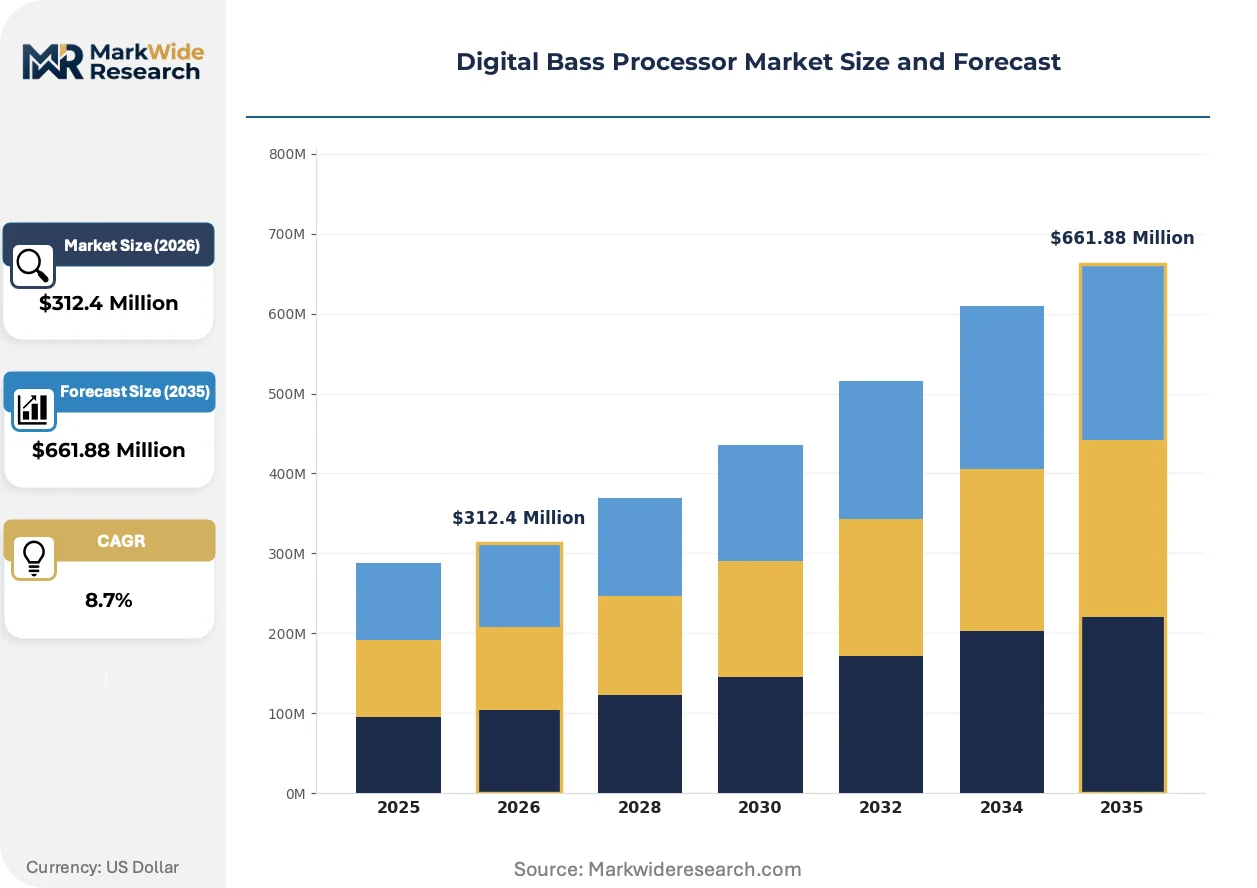
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Processors, Integrated Solutions, Software Plugins, Rack-Mount Units End User: Musicians, Recording Studios, Live Sound Engineers, Audio Professionals Technology: Analog Processing, Digital Processing, Hybrid Systems, DSP-Based Solutions Application: Live Performances, Studio Recordings, Broadcasting, Home Audio Systems |
| Companies Covered | AudioControl, Hifonics, Soundstream, Blaupunkt, Precision Power, Earthquake Sound, Taramp's, Audiobank, Memphis Audio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Bass Processor Market Trends and Innovations
DSP architectures are compressing the traditional separation between signal processing and amplification, while regulatory frameworks on both sides of the Atlantic reshape product development roadmaps. These forces are converging to redefine what constitutes a bass processor in professional and consumer contexts.
FPGA-based DSP engines are digitizing the low-frequency signal path with sub-millisecond latency, enabling previously impossible filter precision in live performance environments. Touring sound companies in Nashville and London now specify these units for arena-scale subwoofer arrays. The technology is digitizing the competitive boundary between installed and portable audio systems, as rack-mount processors acquire road-case durability ratings previously reserved for amplifiers.
The EU's F-Gas Regulation constrains refrigerant-based cooling in high-power audio amplifiers, indirectly pressuring processor manufacturers to demonstrate thermal efficiency in adjacent amplification products. German engineering firms now prioritize convection-cooled DSP designs to maintain CE marking pathways. This regulatory pressure is compressing development timelines for integrated amplifier-processor units targeting the European commercial installation segment.
Vehicle audio upgrade specialists are consolidating procurement around distributor-managed inventory programs, reducing direct manufacturer relationships. Independent installers in Texas and California now rely on regional distributors for technical training and warranty support rather than factory channels. This channel concentration is most visible in the United States, where national chains like Mobile Electronics Association members command increasing leverage over pricing and product mix decisions.
Digital Bass Processor Market Segmentation
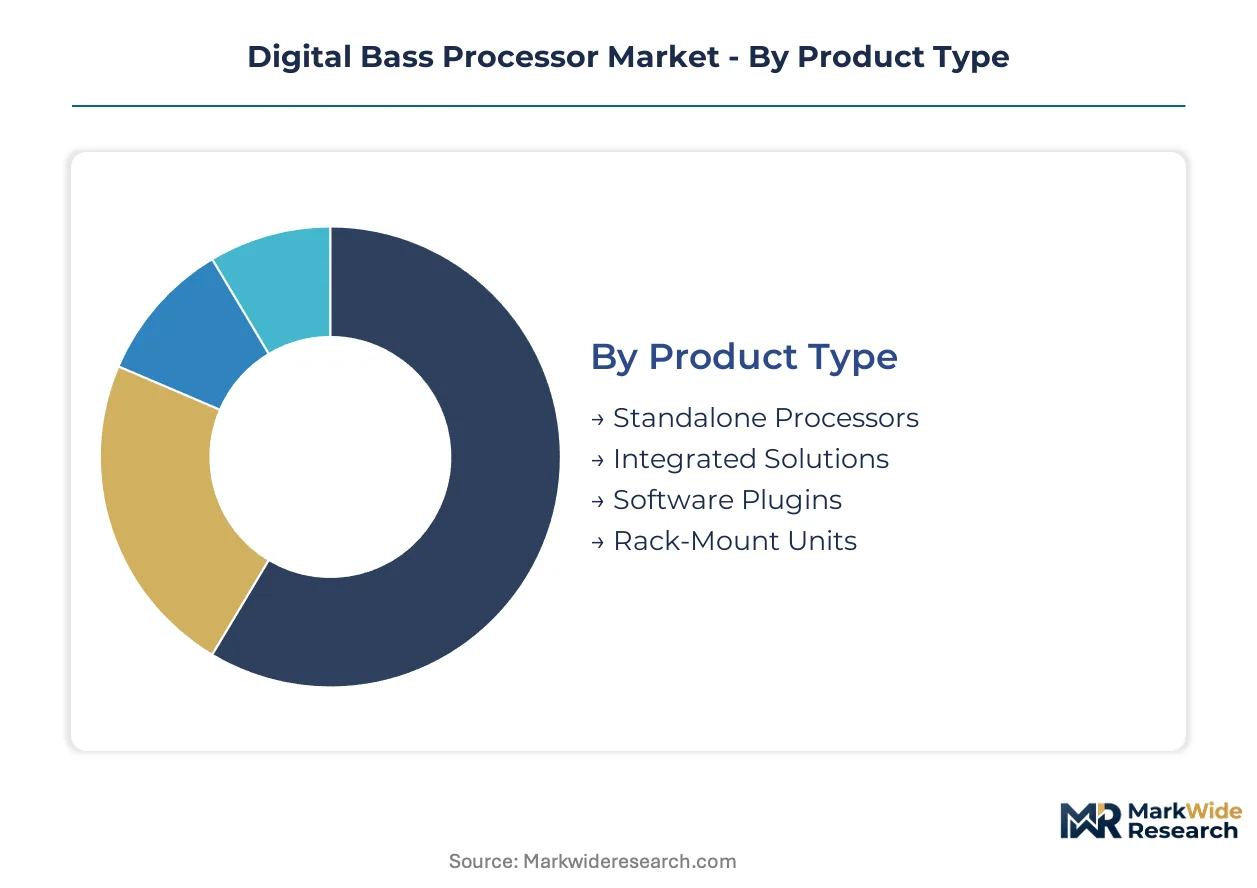
Segmentation in the digital bass processor market reveals divergent service intensity requirements across product architectures. Standalone hardware demands calibration support and warranty networks, while software solutions shift burden toward update infrastructure and license management.
Product Type:
After-sales-service intensity varies sharply across physical and intangible product forms, with hardware categories requiring field technician networks and plugin formats depending on cloud-based support portals.
- Integrated Solutions:These units combine DSP processing with amplification stages in single chassis designs, reducing rack space and cabling complexity. Automotive retrofit specialists in Texas and California concentrate procurement here, drawn by streamlined installation workflows and reduced troubleshooting surface area. Service intensity runs highest due to thermal management and firmware update requirements.
- Standalone Processors:Dedicated signal processing boxes operating below 120 Hz with 24 dB/octave slope capabilities. Live sound engineers in Nashville and London specify these for arena-scale subwoofer arrays where precise phase alignment proves critical. Warranty claims concentrate around power supply failures and connector wear.
- Software Plugins:DAW-integrated subsonic filtering and phase alignment tools from developers like Universal Audio and Waves. License renewal cycles and version compatibility queries dominate support tickets rather than physical repair.
- Rack-Mount Units:Broadcasting infrastructure installations favor these for standardized 19-inch form factors. Fixed installation environments reduce mobility-related service demands compared to touring applications.
By volume, Integrated Solutions lead. By growth pace, Software Plugins are expanding most quickly.
End User:
Cost tier stratification separates professional broadcast infrastructure from project-studio operators and consumer musicians, with support expectations scaling accordingly.
- Live Sound Engineers:Touring professionals operating laptop-controlled DSP workflows for real-time venue tuning. These users demand 24-hour technical support hotlines and rapid replacement programs due to zero-failure-tolerance performance environments.
- Recording Studios:Facilities with transformer-coupled signal paths require careful impedance matching when inserting digital processors. Support cycles extend longer due to integration complexity with legacy analog chains.
- Musicians:Individual performers and small ensembles purchasing through distributor-managed inventory programs. Price sensitivity concentrates demand in entry-level and mid-tier processor categories.
- Audio Professionals:System integrators and commercial installation contractors specifying for corporate, hospitality, and worship venues. Procurement runs through regional distributors rather than direct manufacturer relationships.
By revenue, Recording Studios lead. By growth pace, Live Sound Engineers are climbing the fastest.
Technology:
Application context determines technology selection, with latency-critical live environments favoring dedicated hardware and studio flexibility enabling software alternatives.
- DSP-Based Solutions:Real-time parametric equalization architectures with sub-millisecond latency. These command the steepest expansion trajectory as live sound engineers adopt laptop-controlled tuning workflows across mobile production environments.
- Hybrid Systems:Designs combining analog signal path warmth with digital control precision. Niche demand concentrates among studio purists seeking transformer-coupled front ends with programmable filter backends.
- Analog Processing:Traditional circuitry retaining margin pools among audiophile segments valuing discrete component signal paths. Limited growth due to fixed functionality and calibration drift.
- Digital Processing:General-purpose digital architectures without specialized DSP optimization. Price-competitive positioning in entry-level consumer segments.
By installed base, Digital Processing leads. By growth pace, DSP-Based Solutions are gaining share fastest.
Application:
Volume concentration and margin structure diverge across fixed versus mobile deployment contexts, with touring applications demanding ruggedization and broadcast emphasizing reliability certification.
- Studio Recordings:Controlled acoustic environments where precise subsonic filtering prevents driver damage during monitoring. Post-production facilities in Los Angeles and London anchor demand for transparent processing chains.
- Live Performances:Arena and festival deployments requiring road-case durability and rapid deployment. FPGA-based engines digitize competitive boundaries here as touring companies specify sub-millisecond latency units.
- Broadcasting:Radio and television infrastructure with rack-mount standardization and failover redundancy requirements. Long replacement cycles limit volume but sustain premium pricing.
- Home Audio Systems:Consumer vehicle and residential upgrades, particularly aftermarket automotive installations in the United States where FCC equipment authorization filters import competition.
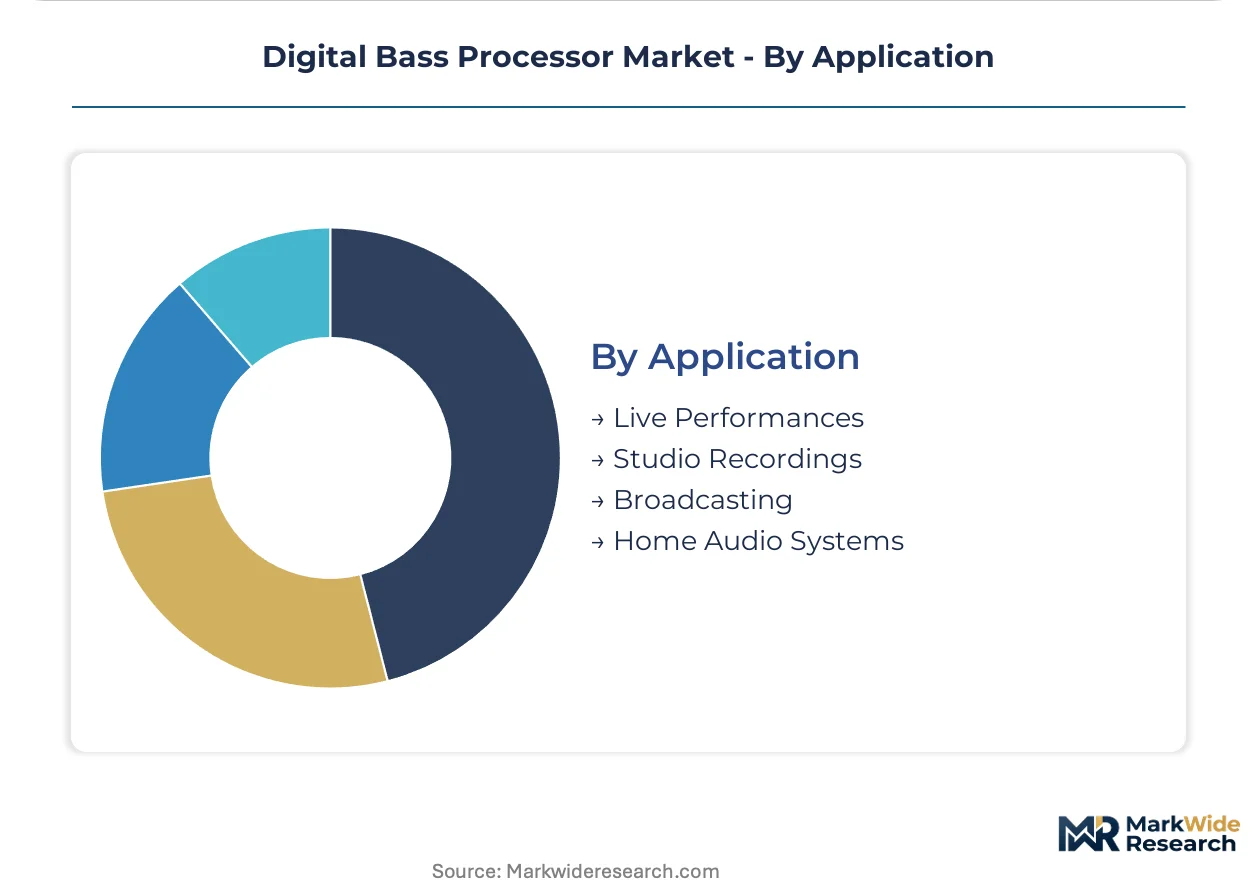
By volume, Home Audio Systems lead. By margin contribution, Studio Recordings are ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering firms export specialized bass processor designs to North American aftermarket installers, while Taiwanese semiconductor foundries supply DSP chips to assembly operations across multiple continents.
United States
Aftermarket automotive audio installers in Texas and California drive retrofit demand as consumers upgrade factory sound systems. The FCC's equipment authorization requirements filter import competition and sustain margin pools for compliant manufacturers. Nashville's live sound engineering cluster specifies FPGA-based processors for touring subwoofer arrays.
Germany
OEM integration partnerships in Stuttgart and Ingolstadt concentrate specialized processor development for factory audio systems. The EU's F-Gas Regulation pressures thermal design choices in adjacent amplification products. Bavarian engineering firms prioritize convection-cooled DSP architectures to maintain CE marking pathways for European commercial installations.
India
Delhi and Mumbai exhibit underpenetrated vehicle audio upgrade demand as urban car owners gain disposable income. The PLI scheme for electronics manufacturing offers cost offsets for domestic assembly in Noida or Chennai facilities. Karnataka's emerging electronics corridor attracts processor assembly investments targeting price-sensitive aftermarket segments.
Japan
Professional broadcast infrastructure in Tokyo and Osaka sustains rack-mount processor demand with long replacement cycles. METI standards shape electromagnetic compatibility testing protocols for domestic audio equipment. Nagoya's automotive supplier network explores bass processor integration for premium vehicle audio tiers.
United Kingdom
London's post-production facilities anchor transparent processing chain demand for film and television mixing stages. CE marking under the EMC Directive governs market access for electronic audio equipment. Manchester's live music venues adopt laptop-controlled DSP workflows for rapid venue tuning.
Digital Bass Processor Market Competitive Landscape
On the supply side, the industry is moderately concentrated around established automotive audio specialists and professional sound equipment fabricators. Three strategic archetypes dominate: integrated amplifier-processor hybrid manufacturers, standalone DSP specialists, and diversified car audio conglomerates. Competitive moves center on geographic distributor consolidation and firmware talent acquisition.
Within the North American specialist tier, AudioControl and Hifonics occupy distinct positioning archetypes, while Soundstream exemplifies the amplifier-processor hybrid design approach. These entities represent varying scale levels and channel strategies across aftermarket automotive and professional sound segments. Blaupunkt's European heritage and Precision Power's manufacturing focus illustrate geographic diversification patterns among mid-scale competitors. Earthquake Sound, Taramp's, and Memphis Audio each sit within specific price-performance tiers that align with regional installer preferences and vehicle upgrade budgets.
| Leading Market Players |
|---|
| AudioControl |
| Hifonics |
| Soundstream |
| Blaupunkt |
| Precision Power |
| Earthquake Sound |
| Taramp's |
| Audiobank |
| Memphis Audio |
| Others |
Pricing and Supply Chain Analysis
Taiwanese DSP chip foundries concentrate upstream capacity for digital bass processor fabrication, anchoring margin pools with authorized manufacturers who navigate FCC equipment authorization and CE marking pathways. This concentration of semiconductor supply shapes downstream pricing power across aftermarket automotive and professional audio segments.
Pricing Analysis
Next-generation FPGA-based DSP engines command substantial premiums over legacy analog architectures and entry-level digital units. Pricing stratifies across premium, standard, and economy tiers based on latency specifications and certification grade, with FCC-authorized units sustaining margin pools against unauthorized imports. Cost compression in mid-tier integrated solutions is intensifying because amplifier-processor hybrid designs reduce bill-of-materials redundancy. Musicians and entry-level consumers exhibit highest price sensitivity, while live sound engineers and broadcast infrastructure buyers prioritize performance specifications over unit economics.
Supply Chain Analysis
Export controls on advanced semiconductor manufacturing equipment constrain DSP chip flows from Taiwan to mainland assembly operations, reshaping sourcing strategies. Supply draws from Taiwan for DSP fabrication, China for PCB assembly and passive components, and Mexico for final integration serving North American automotive aftermarket demand. Dependencies include ADC/DAC converters, FPGA modules, and lead-free capacitors compliant with RoHS restrictions. Single-source vulnerability concentrates in 7nm and below DSP foundry capacity. Distribution runs through regional distributor-managed inventory programs rather than direct manufacturer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists across this market as OEM integration of bass processing into factory head units displaces traditional demand pools, creating specialized niches for retrofit specialists and commercial sound contractors.
For Market Incumbents: Harden firmware update infrastructure and thermal management capabilities to defend against software plugin substitution eroding hardware rack-mount demand. Deepen backward integration into DSP algorithm development to offset talent scarcity in real-time audio engineering. Prioritize captive supply of convection-cooled architectures to maintain CE marking pathways under EU F-Gas Regulation pressure. For New Entrants and Emerging Players: Build out local installation networks in Delhi and Mumbai to capture underpenetrated vehicle audio upgrade demand among rising-disposable-income urban car owners. Target India's PLI scheme-aligned assembly operations in Noida or Chennai for landed-cost advantages against established import channels. Lead with amplifier-processor hybrid designs appealing to mobile DJs and compact venue operators seeking streamlined signal chains. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive audio specialists holding concentrated distributor relationships across Texas and California aftermarket channels. Long-term viability hinges on whether standalone processor demand collapses under OEM integration or pivots successfully toward commercial installation and retrofit specialization. Watch for inflection signals in automotive OEM head-unit firmware roadmaps indicating internalization versus outsourcing decisions for bass processing functionality.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Talent Acquisition | Real-time DSP algorithm expertise concentrates among AudioControl and semiconductor firms, constraining competitor R&D velocity. |
| PLI Scheme Manufacturing Alignment | Domestic assembly in Noida or Chennai unlocks cost offsets for price-sensitive Indian aftermarket penetration. |
| Amplifier-Processor Hybrid Development | Integrated designs reduce rack space and cabling complexity for mobile DJs and compact venue operators. |
| FCC Equipment Authorization Investment | Compliance moat filters low-quality imports and sustains margin pools for authorized manufacturers. |
| Regional Distributor Consolidation | Texas and California installer networks increasingly rely on distributor-managed inventory over factory channels. |
Research Methodology
Initial hypotheses were tested against primary input from aftermarket automotive installers, live sound engineers, OEM audio system procurement leads, and DSP firmware developers, then refined against secondary validation. Sources included FCC equipment authorization databases, EU EMC Directive compliance registries, automotive production data from IHS Markit, and trade flow records for electronic audio equipment. Bottom-up triangulation across product architecture segments and top-down cross-checks against regional aftermarket spending patterns anchored volume and value estimates.
Demand-supply balance framing structured the analytical approach across the projection horizon, modeling adoption trajectories by product type, end user tier, technology generation, and application context. Segmentation dimensions included integrated versus standalone versus software plugin formats, professional versus consumer versus commercial installation end users, DSP-based versus analog versus hybrid architectures, and live performance versus studio recording versus broadcasting versus home audio applications. CAGRs derived from fitted growth curves calibrated to technology substitution rates and regulatory compliance timeline impacts, with specific inputs from laptop-controlled DSP workflow adoption curves and automotive OEM integration roadmaps.
Stress conditions across semiconductor supply volatility, software plugin substitution velocity, and automotive OEM internalization decisions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding FCC authorization timelines and PLI scheme implementation pace. Material shifts in automotive OEM head-unit firmware development strategies or export control expansions on DSP manufacturing equipment would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Asia-Pacific Laser Hair Removal Market
Others
Safety Critical Software Testing Market
Others
Global Supply Chain Risk Management Software Market
Others
Global Sports and Fitness Wears Market
Others
Workbench Tanks Market
Others
Aircraft Switches Market
Others
Global Hydraulics Market
Others
Cremation Furnace Market
Others
Kuwait Retail Market
Others
South Asia Geosynthetics Market
Others
Coconut Activated Carbon Market
Others
Smart Home As a Service Market
Others
Pollen Allergy Market
Others
Asia-Pacific Adtech Market
Others
Traditional PC Market
Others
North America Forklift Truck Market