
 Workbench Tanks Market | 2026-2036
Workbench Tanks Market Size, Share, and Industry Trends Forecast 2026-2036
Workbench Tanks Market Analytics
Preventive maintenance contracts and calibration subscriptions is decoupling hardware sales from pure capital expenditure cycles in the workbench tanks sector. RDI Solutions Inc. leverages its service infrastructure to sustain recurring revenue streams alongside tank installations. Fluidall anchors its competitive stance through specialized fluid handling configurations that reduce client downtime. OnePointe Solutions differentiates by controlling custom fabrication workflows for laboratory-grade containment systems.
Workbench tanks are sealed or vented vessels engineered for benchtop deployment, typically fabricated from polyethylene, stainless steel, or fiberglass with wall thicknesses ranging from 0.125 to 0.5 inches depending on chemical compatibility requirements. These units serve primarily to contain, dispense, or temporarily store liquids in proximity to analytical or production workstations. Rigid tanks and skid-mounted configurations command the largest installed base due to structural reliability under sustained load, while collapsible tanks are gaining traction in mobile and space-constrained research environments where rapid deployment matters more than permanent fixture integrity. Stainless steel and polyethylene together absorb the dominant share of material demand, with fiberglass capturing niche applications requiring extreme corrosion resistance against sulfuric or hydrochloric acid exposure.
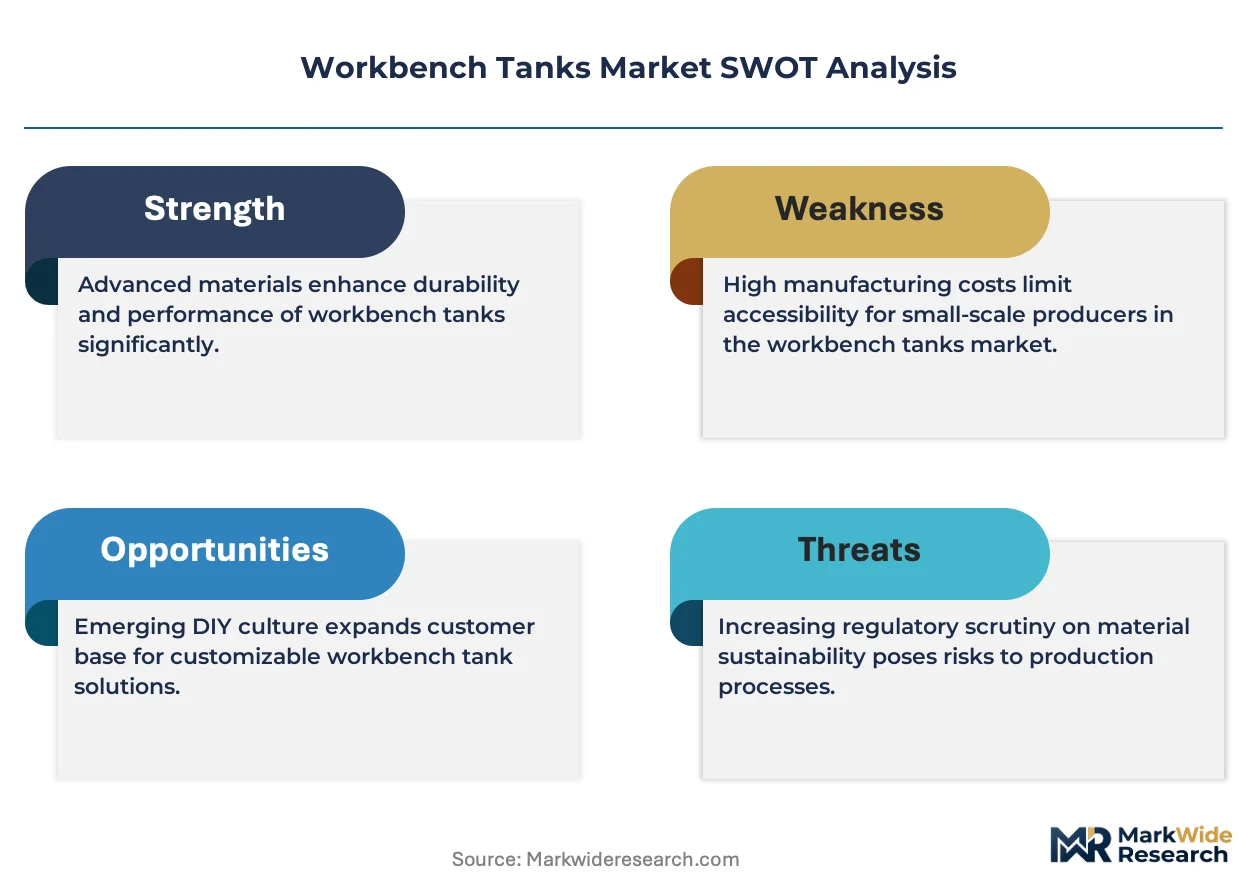
EPA regulations under 40 CFR 264 and OSHA's Process Safety Management standard constrain tank design, venting architecture, and secondary containment specifications for hazardous material handling in U.S. workplaces. ISO 9001 quality management certification and NSF/ANSI 61 drinking water system components standards further govern product eligibility for municipal and potable-water-adjacent applications. Buyers must weigh total cost of ownership against evolving state-level environmental enforcement intensity when selecting material grades and containment architectures.
Market Dynamics
Preventive maintenance contracts and calibration subscriptions are decoupling hardware sales from pure capital expenditure cycles, forcing vendors to build recurring revenue infrastructure alongside tank installations.
Growth Catalysts
- EPA 40 CFR 264 Secondary Containment Mandates:Tightened spill prevention requirements at U.S. research facilities are accelerating replacement cycles for non-compliant legacy vessels.
- Biopharma Manufacturing Expansion:Cell culture media preparation and buffer storage workflows in Massachusetts and North Carolina clusters are driving demand for single-use compatible tank architectures.
- Polyethylene Rotational Molding:Advances in seamless fabrication techniques are reducing lead times for custom chemical-grade containment configurations.
Market Restraints
- High-Density Polyethylene Resin Volatility:Feedstock price swings tied to ethylene cracker capacity constrain margin predictability for tank fabricators.
- Specialty Steel Supply Concentration:316L stainless coil availability concentrates among a limited supplier base in Pennsylvania and Ohio mill corridors.
- Fiberglass Delamination Risk:Extended sulfuric acid exposure above 80% concentration degrades structural laminate integrity, limiting application scope.
Strategic Opportunities
- Modular Skid Systems for Contract Research Organizations:Rapidly reconfigurable containment platforms address facility relocation cycles in Texas and California life sciences corridors.
- OSHA Process Safety Management Alignment:Vendors bundling compliance documentation with tank deliveries capture premium positioning in hazardous material handling segments.
- IoT Sensor Integration:Real-time level monitoring and leak detection capabilities are opening service revenue streams in pharmaceutical quality control environments.
Industry Challenges
- Welding Certification Bottlenecks:ASME Section IX qualified pressure vessel welders remain scarce in secondary manufacturing markets, extending fabrication timelines.
- NSF/ANSI 61 Certification Timelines:Potable water adjacent applications face 6-12 month testing protocols that delay product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Workbench Tanks Market |
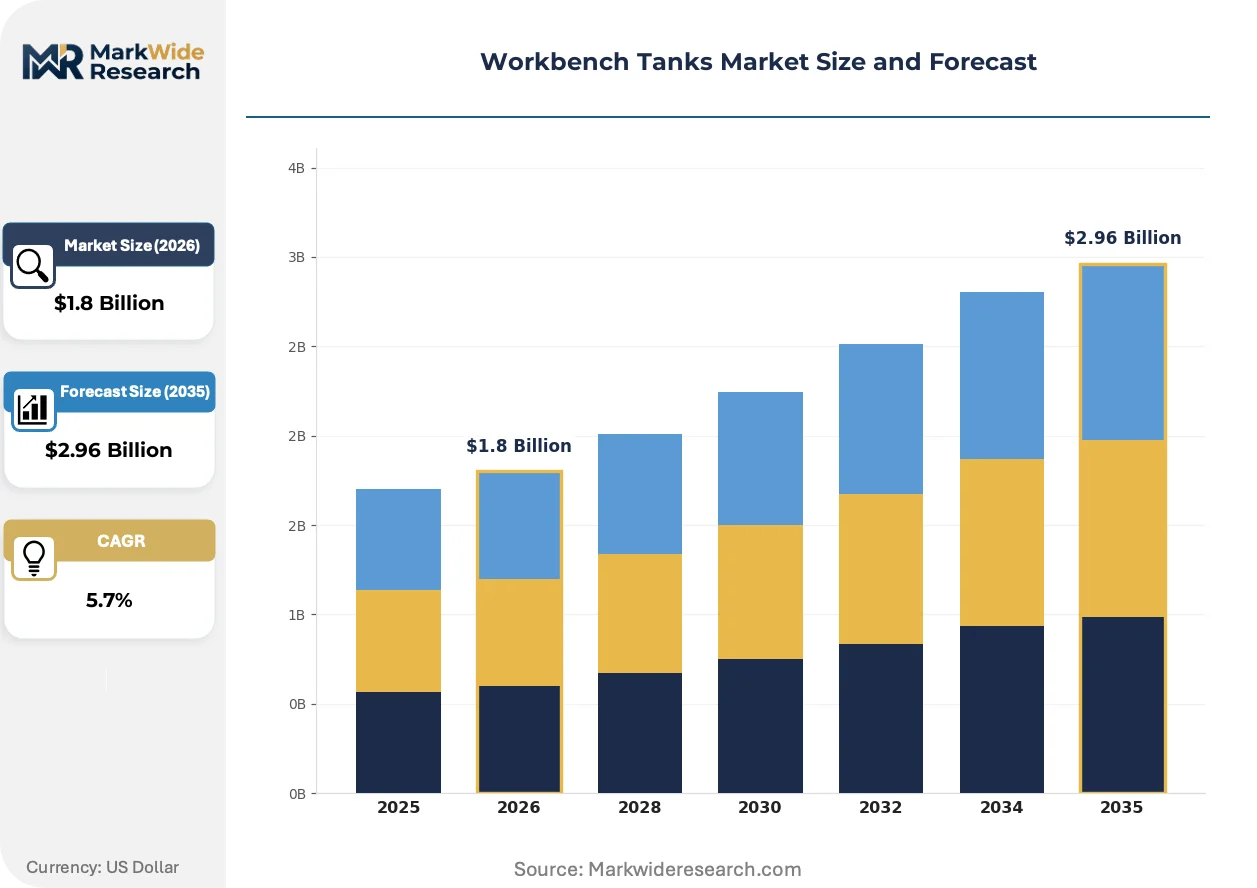
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collapsible Tanks, Rigid Tanks, Skid-mounted Tanks, Dual-layer Tanks Material: Polyethylene, Stainless Steel, Fiberglass, Aluminum Application: Industrial Use, Agricultural Use, Waste Management, Chemical Storage End User: Manufacturing Facilities, Research Laboratories, Construction Companies, Municipalities |
| Companies Covered | RDI Solutions Inc., Loraday Environmental Products Ltd., Hassco Industries, Fluidall, RDM Industrial Products, Inc., BenchPro, OnePointe Solutions, Steel Sentry, Inc., Formaspace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Workbench Tanks Market Evolving Landscape
Digital service layers and material science advances are compressing traditional hardware margins while opening recurring revenue channels for vendors who integrate monitoring and compliance capabilities.
Cross-linked polyethylene (XLPE) tank construction is consolidating market preference for chemical storage applications requiring enhanced stress-crack resistance. Pharmaceutical quality control departments in New Jersey and Illinois manufacturing belts are specifying XLPE over standard linear polyethylene for aggressive solvent handling. The technology is consolidating vendor differentiation around material performance warranties rather than pure fabrication capacity.
OSHA's updated Process Safety Management enforcement memorandum is tightening secondary containment documentation requirements for facilities handling threshold quantities of highly hazardous chemicals. Tank specifiers now face expanded recordkeeping burdens for venting architecture and spill capacity calculations. California and Texas industrial corridors are seeing accelerated replacement of grandfathered installations ahead of state-level inspection intensification.
Service contract unbundling is fragmenting traditional capital equipment purchasing into discrete hardware, installation, calibration, and compliance monitoring transactions. Large research universities in Massachusetts and North Carolina are negotiating multi-year maintenance agreements separately from initial tank procurement. The shift concentrates purchasing leverage among facilities management departments rather than principal investigators.
Workbench Tanks Market Segmentation
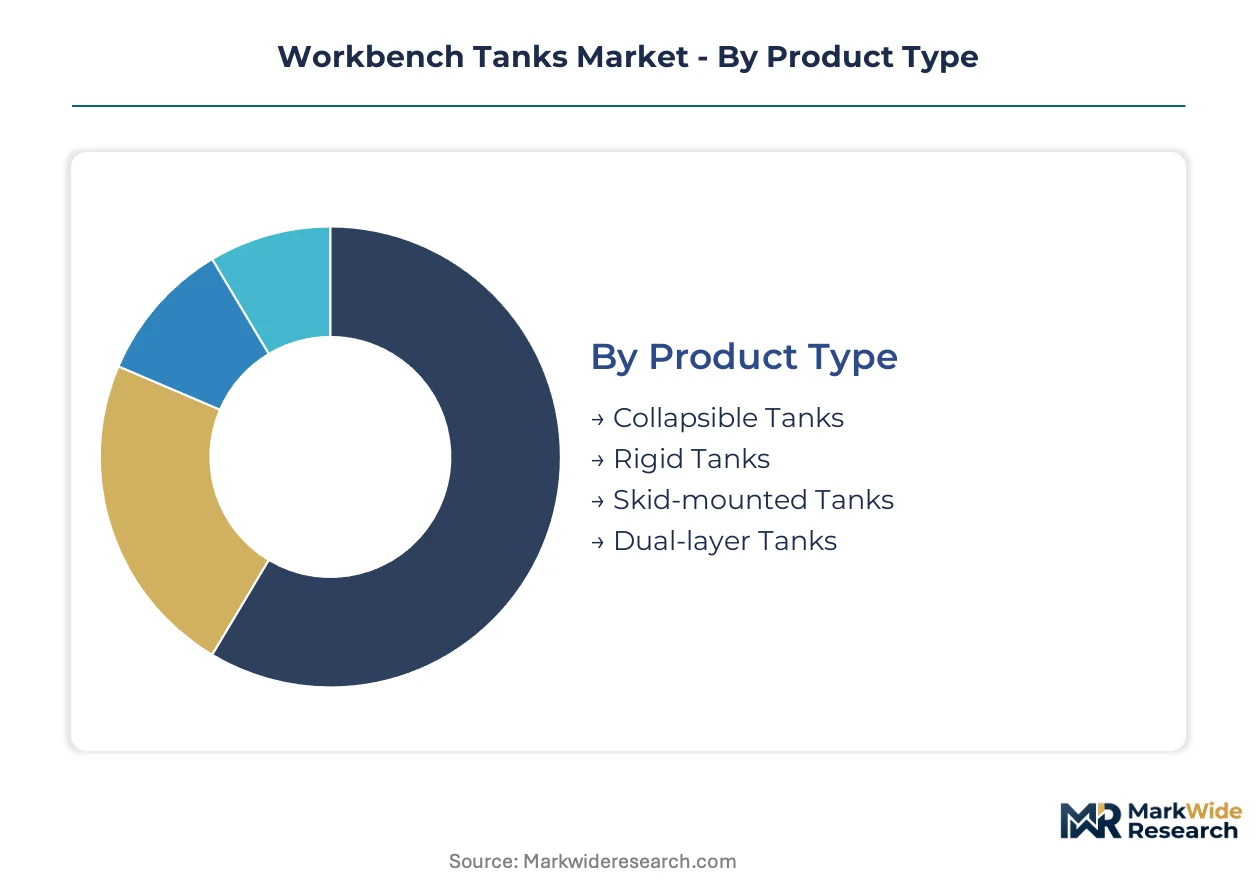
Workbench tank procurement decisions hinge on containment integrity requirements, chemical compatibility matrices, and facility mobility needs. Segmentation reveals how certification burdens, material specifications, and end-use environments reshape vendor positioning across distinct buyer categories.
Product Type:
EPA 40 CFR 264 secondary containment mandates and OSHA Process Safety Management standards apply differentially across product architectures, with rigid and skid-mounted configurations facing the most intensive documentation requirements for hazardous material handling.
- Rigid Tanks:Fixed-wall vessels fabricated from rotationally molded polyethylene or welded stainless steel deliver structural reliability under sustained static loads. Manufacturing facilities in Texas and California industrial corridors specify these for permanent buffer storage and chemical dispensing stations where floor loading capacity exceeds 500 pounds per square foot.
- Skid-mounted Tanks:Pre-engineered containment platforms integrate primary vessels with secondary containment sumps and pump assemblies on steel frames. Contract research organizations in Massachusetts and North Carolina life sciences clusters favor these for rapid facility reconfiguration and leasehold compliance.
- Collapsible Tanks:Flexible fabric-reinforced elastomer vessels deploy for temporary containment in mobile research environments.
- Dual-layer Tanks:Nested vessel designs with interstitial leak detection zones address aggressive chemical storage in pharmaceutical quality control departments.
Rigid tanks sit at the top of the volume ranking, with skid-mounted configurations climbing the fastest.
Material:
Cost tiers stratify sharply across material grades, with polyethylene commanding the lowest installed cost per gallon and fiberglass carrying premium positioning for extreme corrosion resistance.
- Polyethylene:Linear and cross-linked polyethylene grades dominate benchtop chemical storage through seamless rotational molding and stress-crack resistance. Research laboratories in New Jersey and Illinois manufacturing belts specify XLPE variants for aggressive solvent handling where standard polyethylene fails.
- Stainless Steel:316L austenitic grades provide temperature tolerance and pressure rating headroom for steam sterilization cycles. Biopharma manufacturing expansion in North Carolina clusters drives demand for electropolished finishes meeting ASME BPE surface specifications.
- Fiberglass:Vinyl ester and isophthalic resin laminates serve sulfuric and hydrochloric acid exposure above standard polyethylene limits.
- Aluminum:Lightweight alloy vessels address weight-constrained mobile applications and aviation-adjacent fuel handling.
Polyethylene absorbs the dominant share of unit volume, while stainless steel gains share fastest in biopharma-qualified installations.
Application:
Customer maturity varies across application segments, with chemical storage buyers exhibiting the most sophisticated total-cost-of-ownership analysis and waste management purchasers prioritizing regulatory documentation bundles.
- Chemical Storage:Containment of acids, bases, solvents, and reactive intermediates demands material compatibility verification against EPA 40 CFR 264 spill prevention requirements. Texas and California industrial facilities accelerate replacement of grandfathered installations ahead of state inspection intensification.
- Industrial Use:Process fluid buffering, coolant reservoirs, and wash station supply tanks serve manufacturing floor operations. Massachusetts research universities negotiate multi-year maintenance agreements separately from initial procurement, concentrating leverage with facilities management.
- Waste Management:Accumulation tanks for hazardous waste streams pending off-site treatment.
- Agricultural Use:Pesticide mixing and fertilizer solution preparation in extension service and commercial farming operations.
Chemical storage anchors the revenue base, with industrial use expanding most quickly through preventive maintenance contract unbundling.
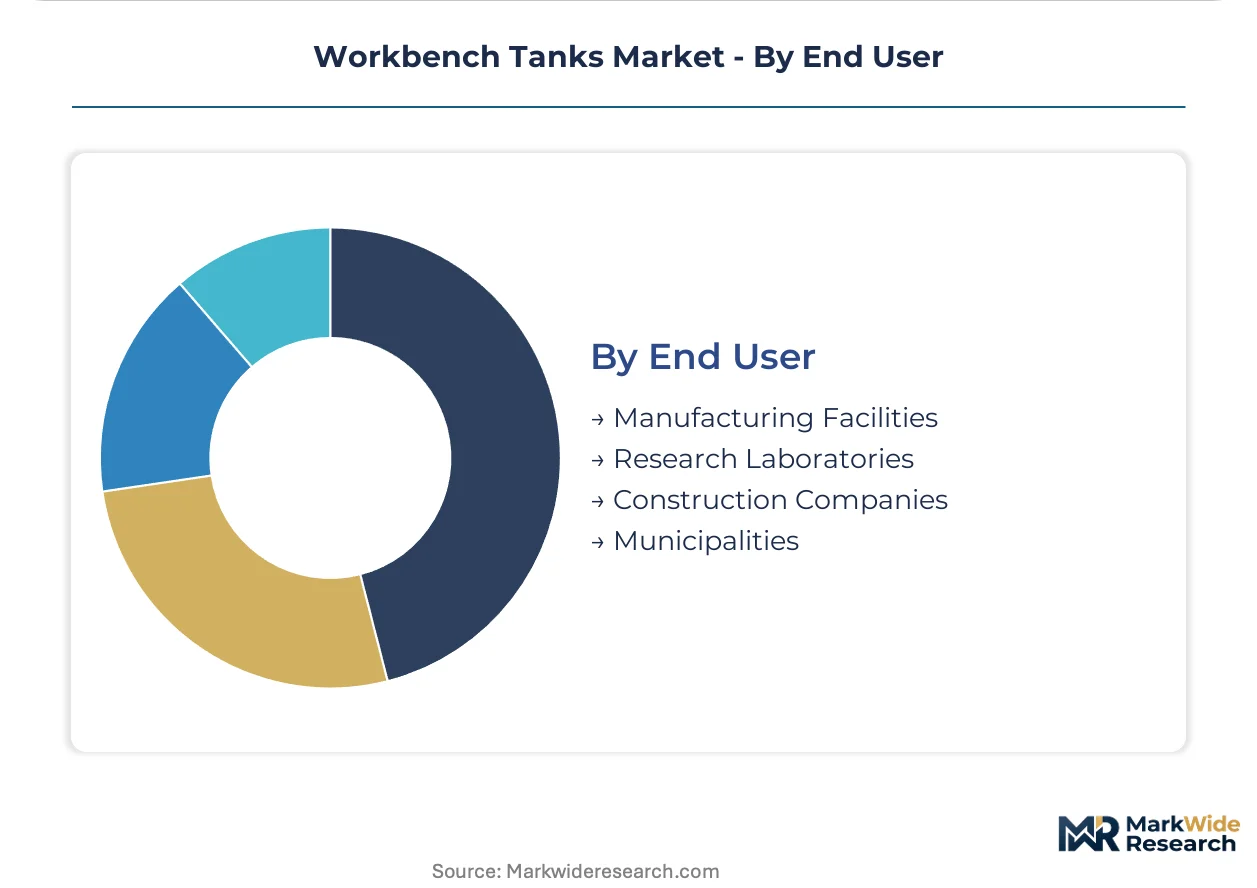
End User:
Procurement authority fragmentation distinguishes end user segments, with research laboratories delegating specification decisions to principal investigators while manufacturing facilities centralize purchasing through engineered equipment committees.
- Manufacturing Facilities:Chemical processing, electronics fabrication, and food production operations require containment systems integrated with process control architectures. California industrial corridors specify IoT sensor integration for real-time level monitoring and leak detection.
- Research Laboratories:Academic and commercial R&D operations prioritize flexibility and single-use compatibility for cell culture media preparation. North Carolina biopharma clusters drive demand for custom fabrication workflows and rapid design iteration.
- Construction Companies:Temporary dewatering, fuel storage, and concrete curing water supply at active job sites.
- Municipalities:Potable water adjacent applications requiring NSF/ANSI 61 certification face extended testing protocols.
Manufacturing facilities represent the largest addressable base, with research laboratories posting the steepest expansion trajectory through biopharma manufacturing buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as fabricators migrate toward jurisdictions with streamlined certification timelines and lower compliance overhead. The United States retains demand dominance through EPA and OSHA enforcement intensity, while manufacturing capacity disperses across cost-optimized North American and Asian supply bases.
United States
Texas and California industrial corridors concentrate replacement demand as EPA 40 CFR 264 secondary containment mandates accelerate obsolescence of grandfathered installations. OSHA Process Safety Management enforcement memoranda tighten documentation burdens for venting architecture and spill capacity calculations. Massachusetts biopharma clusters and North Carolina life sciences corridors drive specification complexity for single-use compatible tank architectures.
Germany
REACH compliance and CE marking requirements elevate material traceability standards for chemical-grade containment systems serving Rhineland industrial zones. The country's national environmental regulator enforces spill prevention protocols that exceed baseline EU directives. Bavaria-based precision manufacturing operations specify electropolished stainless steel vessels meeting ASME BPE surface specifications for bioprocessing applications.
China
GB standards and MIIT industrial policy accelerate domestic rotational molding capacity expansion for polyethylene chemical storage. NMPA pharmaceutical manufacturing guidelines drive demand for contamination-controlled containment in Yangtze River Delta biopharma zones. Shandong Peninsula chemical processing hubs import corrosion-resistant fiberglass architectures for sulfuric acid handling above standard polyethylene limits.
India
BIS certification timelines and state-level factory inspection regimes create compliance bottlenecks for imported containment systems. The country's national pharmaceutical regulator enforces material compatibility documentation for active pharmaceutical ingredient manufacturing. Maharashtra and Gujarat industrial corridors specify modular skid-mounted configurations for rapid facility reconfiguration in contract manufacturing operations.
Japan
METI energy efficiency directives and JIS quality standards constrain vessel design specifications for precision chemical handling. PMDA pharmaceutical manufacturing guidelines mandate validated containment for cell culture media preparation workflows. Kansai/Osaka electronics fabrication clusters drive demand for ultra-pure chemical dispensing stations with real-time leak detection capabilities.
Workbench Tanks Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated service providers capturing premium positioning against pure fabrication houses. The vendor base organizes around three strategic archetypes: full-service maintenance bundlers, custom fabrication specialists, and scale-driven rotational molders. Consolidation pressure concentrates among polyethylene fabricators facing resin volatility, while stainless steel specialists defend margin through ASME certification scarcity. Competitive moves center on preventive maintenance contract unbundling and IoT sensor integration for recurring revenue capture.
Within the service-integrated tier, RDI Solutions Inc. exemplifies the maintenance bundler archetype through its recurring revenue infrastructure. Fluidall occupies a position among specialized fluid handling configurators reducing client downtime. OnePointe Solutions represents custom fabrication workflow control for laboratory-grade containment systems. These three anchors illustrate how vendor differentiation is concentrating around material performance warranties and compliance documentation bundling rather than pure manufacturing scale.
| Leading Market Players |
|---|
| RDI Solutions Inc. |
| Loraday Environmental Products Ltd. |
| Hassco Industries |
| Fluidall |
| RDM Industrial Products, Inc. |
| BenchPro |
| OnePointe Solutions |
| Steel Sentry, Inc. |
| Formaspace |
| Others |
Value Network & Pricing Analysis
Captive rotational molding capacity in Texas and Ohio mill corridors anchors supply positioning and pricing power for polyethylene fabricators serving EPA-regulated containment markets. This integration choice insulates tier-one vendors from ethylene cracker volatility while forcing smaller competitors into spot resin markets with compressed margin headroom.
Pricing Analysis
Distributor margin layers compress as direct-to-OEM contracts expand among Massachusetts and North Carolina biopharma clusters. Three-tier pricing structure across premium ASME-certified, standard NSF/ANSI 61-compliant, and economy-grade polyethylene configurations stratifies buyer access. Pricing pressure stems from HDPE resin volatility tied to Gulf Coast petrochemical capacity. Research laboratories exhibit highest price sensitivity due to grant-funded procurement cycles, while manufacturing facilities prioritize total cost of ownership over unit price.
Supply Chain Analysis
Single-source vulnerability sits with 316L stainless coil concentration in Pennsylvania and Ohio mill corridors serving biopharma-qualified installations. Raw material flows draw from domestic polyethylene resin producers, specialty steel mills, and vinyl ester laminate importers. Tariff exposure on fiberglass roving and corrosion-grade resins elevates landed costs for sulfuric acid containment architectures. Distribution runs through regional industrial distributors and direct specification sales to engineered equipment committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Workbench Tanks Market functions as a stable compounder anchored by perpetual EPA and OSHA compliance upgrade cycles that regenerate replacement demand regardless of macroeconomic conditions.
For Market Incumbents: Anchor defensive positioning through ASME Section IX welding certification scarcity and captive rotational molding capacity in Texas industrial corridors. Consolidate regional service infrastructure to capture preventive maintenance contract unbundling revenue. Threat substitution from single-use bioprocessing bags demands accelerated XLPE material performance warranty differentiation.
For New Entrants and Emerging Players: Contract research organizations in California life sciences corridors represent an underserved buyer archetype seeking rapid-deployment skid-mounted configurations with leasehold compliance documentation. White-space targets include IoT sensor integration for real-time leak detection and modular containment platforms for facility relocation cycles. Go-to-market execution should emphasize OSHA Process Safety Management alignment bundled with tank deliveries.
For Investors and Strategic Acquirers: Roll-up economics work for regional polyethylene fabricators with EPA 40 CFR 264 compliance documentation capabilities because regulatory certification barriers prevent price-based competition from unqualified entrants. Long-term viability centers on recurring service revenue attachment rates rather than pure hardware replacement cycles. Acquisition targets should demonstrate installed base density in Texas or California industrial corridors. The signal to watch is state-level inspection intensification timing that accelerates grandfathered installation replacement waves.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into HDPE Resin Supply | Captive ethylene sourcing from Gulf Coast crackers insulates margin from feedstock volatility. |
| ASME Section IX Welding Certification Investment | Qualified pressure vessel fabrication capacity commands premium positioning in biopharma segments. |
| IoT Sensor Platform Integration | Real-time level monitoring opens recurring service revenue streams in pharmaceutical quality control. |
| NSF/ANSI 61 Certification Acceleration | Potable water adjacent eligibility captures municipal infrastructure replacement cycles. |
| Modular Skid System Standardization | Rapid reconfiguration platforms address contract research organization facility relocation demands. |
Research Methodology
Multiple input streams — primary interviews with plant engineers and procurement leads at downstream OEMs, regulatory filings with EPA and OSHA, and trade data from customs records — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from SEC 10-K disclosures of listed industrial equipment manufacturers, ACC industry reports, and state-level environmental enforcement databases. Conversations with maintenance directors, aftermarket service heads, and distribution channel partners informed operational dynamics.
Data-stream reconciliation across product type, material grade, application environment, and end-user procurement authority shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories and value-per-unit trends. Forecast inputs incorporated EPA 40 CFR 264 compliance upgrade timelines, biopharma manufacturing expansion patterns in Massachusetts and North Carolina clusters, and polyethylene rotational molding capacity utilization rates.
Underlying measurement precision varies by segment; rigid and skid-mounted tank categories carry tighter precision than collapsible configurations due to established installation tracking systems. Forecasts reflect assumptions around regulatory enforcement intensity and resin price normalization. Specific risk factors include OSHA Process Safety Management memorandum revisions and ethylene cracker outage events. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
High Voltage Measuring Equipment Market
Others
Italy 3D Printing Construction Market
Others
Rotary Dial Machine Market
Others
Process Spectroscopy Market
Others
Global Multi-Access Edge Computing Market
Others
UAE Location-Based Services Market
Others
North America Commercial Vehicles Lubricants Market
Others
Architectural Fabrics Market
Others
North America IT Device Market
Others
United States Cigarette Market
Others
North America Industrial Wearable Devices Market
Others
North America Orange Market
Others
Silicone Molding Machinery Market
Others
Fluorapatite Market
Others
Global Car Wax Market
Others
Paper Shredder Market