
 Paper Making Machine Market | 2026-2036
Paper Making Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Making Machine Market Analytics
Finnish engineering capacity is realigning around high-speed tissue and packaging lines. Valmet leverages its automation-integrated platforms to dominate rebuild and greenfield projects across Nordic and Baltic markets. Andritz AG anchors its position through in-house production of key components like headboxes and press sections, reducing external dependency. Voith Group differentiates via hydraulic technology leadership in heavy-duty packaging paper machines.
A paper making machine is an integrated industrial system that converts pulp slurry into continuous paper webs through forming, pressing, drying, and finishing stages, operating at speeds from several hundred to over two thousand meters per minute depending on grade. Its primary purpose is to produce standardized paper rolls for downstream converting into packaging, printing, or hygiene products. Fully automatic machines command the premium tier as mills prioritize labor reduction and real-time quality control, while recycle paper machines are gaining traction amid fiber sustainability mandates. Packaging paper applications absorb the largest share of new capacity investments as brands shift from plastic.
EMA's Industrial Emissions Directive and REACH chemical compliance shape machine material specifications and coating chemistries in European installations. China's MEE enforces wastewater discharge limits that push mills toward closed-loop water systems in machine design. India's BIS mandates equipment certification for domestic suppliers under its quality control orders. Stakeholders must weigh regulatory compliance costs against operational savings when selecting between mechanical and pneumatic technology configurations.
Market Dynamics
E-commerce packaging demand is concentrating machine orders among fewer, larger buyers while China's dual carbon goals and GB standards force energy-efficiency redesigns across supplier engineering roadmaps.
Growth Catalysts
- PLI Scheme for Paper Products:India's production-linked incentive scheme accelerates domestic capacity buildouts by subsidizing capital equipment for packaging-grade machines.
- EMA's Industrial Emissions Directive:European mills must retrofit or replace aging stock with closed-loop water systems, creating replacement demand for compliant forming and drying sections.
- Fiber Sustainability Mandates:Recycled pulp integration requirements across consumer brands pull demand toward machines with advanced de-inking and contaminant removal capabilities.
Market Restraints
- Stainless Steel Input Volatility:Machine frames and dryer cylinders depend on nickel-alloy grades whose price swings compress fabrication margins unpredictably.
- Headbox Supplier Concentration:Precision hydraulic forming equipment concentrates among German and Finnish engineering houses, creating single-source vulnerability for Asian greenfield projects.
- Technical Limitation in Speed-Tissue Tradeoffs:Tissue machines above two thousand meters per minute sacrifice bulk softness, capping premium product yields.
Strategic Opportunities
- Underpenetrated Indian Tissue Market:Per-capita consumption remains below two kilograms annually versus Western benchmarks, positioning domestic machine builders for sanitation-grade expansion.
- Automation-Convergence:Machine vision and predictive maintenance algorithms are unifying with legacy DCS platforms to enable autonomous speed adjustments.
- China's Dual Carbon Tailwind:Provincial subsidies for energy-efficient installations create preferential financing for heat-recovery drying sections.
Industry Challenges
- Commissioning Engineer Scarcity:Start-up specialists for high-speed packaging lines command premium contracts that extend project timelines.
- BIS Certification Timelines:India's quality control orders require six to nine months for equipment approval, delaying revenue recognition for domestic suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Making Machine Market |
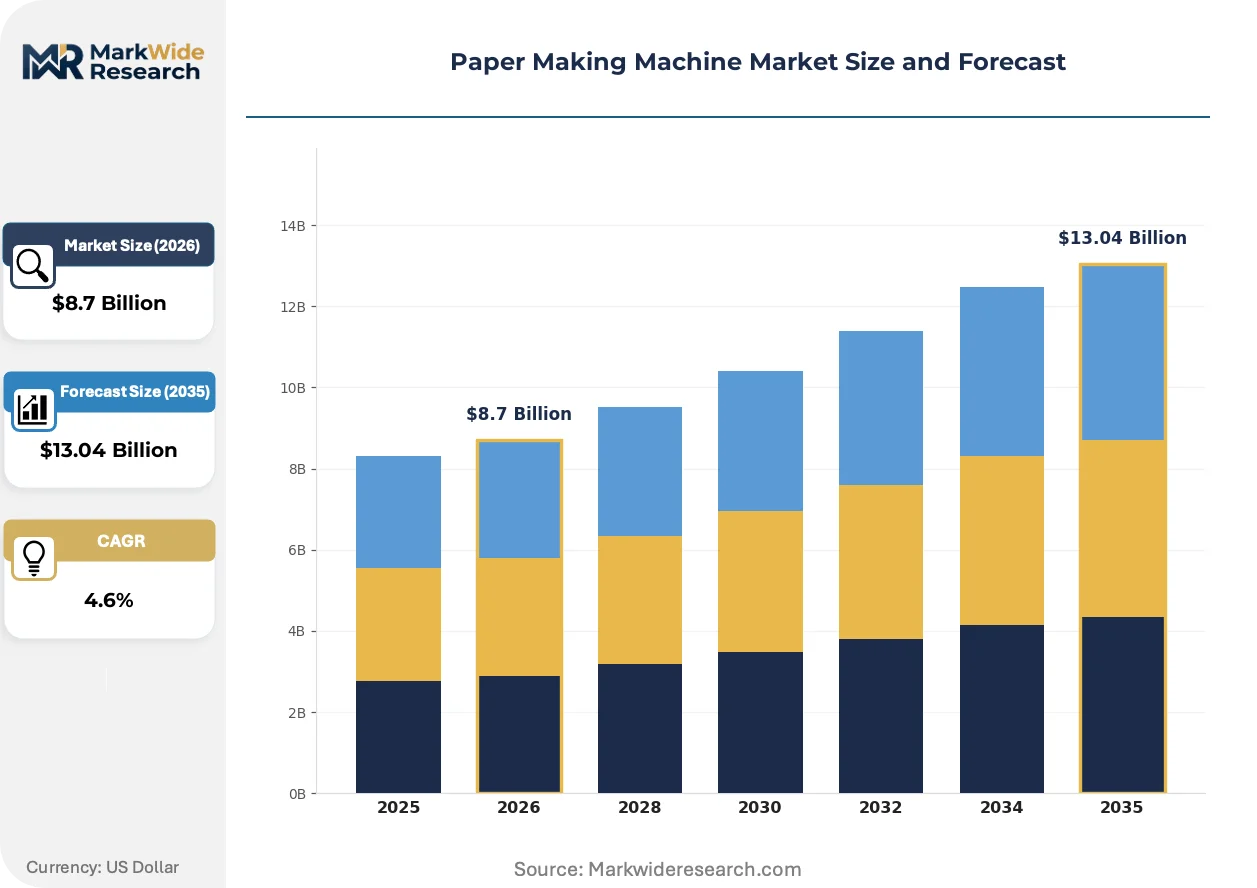
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Machine, Semi-Automatic Machine, Fully Automatic Machine, Recycle Paper Machine Technology: Mechanical, Electrical, Pneumatic, Hydraulic End User: Commercial Paper Manufacturers, Specialty Paper Producers, Publishers, Packaging Companies Application: Newsprint, Writing Paper, Packaging Paper, Tissue Paper |
| Companies Covered | Valmet, Andritz AG, Voith Group, Mitsubishi Heavy Industries, Bellmer GmbH, Parason Machinery, Kadant Inc., IHI Corporation, Toscotec SPA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Making Machine Market Evolving Landscape
Digital thread integration across forming, pressing, and drying stages is compressing quality variance while regulatory chemistry restrictions reshape coating and surface treatment specifications.
Advanced press felts with embedded moisture sensors are unifying real-time sheet profile data with machine directional controls. Packaging mills in Germany and the United States are retrofitting these systems to reduce broke rates. The technology is unifying previously separate quality and process control departments into single accountability structures.
China's MEE wastewater discharge limits are forcing closed-loop water system adoption across Yangtze River basin installations. Mills must eliminate external effluent streams through internal filtration and evaporation. Tissue producers in Jiangsu and Zhejiang provinces are absorbing capital costs to maintain operating licenses.
Buyer concentration among e-commerce fulfillment networks is compressing specification negotiation cycles. Amazon and Alibaba logistics subsidiaries now dictate machine speed, width, and automation tiers through master service agreements. This pattern concentrates most visible in China's corrugated medium sector.
Paper Making Machine Market Segmentation
Machine specification tiers determine capital allocation patterns across mill modernization cycles. Technology configurations and automation levels segment procurement decisions based on labor costs, fiber input variability, and end-product quality requirements.
Product Type:
Automation depth defines the specification axis, separating labor-intensive configurations from integrated control platforms.
- Fully Automatic Machine:Integrated DCS platforms with real-time moisture profiling and autonomous speed adjustment dominate Nordic and German mill rebuilds. Demand concentrates among packaging producers serving Amazon and Alibaba fulfillment networks where specification negotiation cycles have compressed.
- Recycle Paper Machine:Advanced de-inking and contaminant removal systems process post-consumer fiber streams. India's PLI scheme for paper products accelerates domestic capacity buildouts for packaging-grade recycled output.
- Traditional Machine:Mechanical drive systems with manual reel handling persist in emerging market small-scale operations.
- Semi-Automatic Machine:Partial automation of wet-end sections with manual dry-end finishing suits mid-tier producers balancing capital constraints against quality targets.
Mature deployment sits with Traditional Machine configurations. Newer deployment is concentrated in Fully Automatic Machine platforms.
Technology:
Power transmission architecture governs energy efficiency compliance and maintenance cost structures across installation bases.
- Hydraulic:Precision pressure control in headbox and press sections enables heavy-duty packaging paper machines operating above 1500 meters per minute. Voith Group leverages this technology leadership in corrugated medium lines serving China's Yangtze River basin mills facing MEE wastewater discharge limits.
- Mechanical:Gear and shaft drive systems dominate legacy tissue and newsprint installations where speed requirements remain below 1000 meters per minute.
- Electrical:Variable frequency drives with regenerative braking reduce energy consumption in drying sections, aligning with China's dual carbon goals and provincial subsidies for heat-recovery configurations.
- Pneumatic:Compressed air systems for felt conditioning and sheet transfer offer lower capital cost but higher operational expenditure in high-humidity environments.
Mechanical technology anchors existing installed base. Hydraulic systems are gaining share fastest in greenfield packaging investments.
End User:
Customer scale and product mix determine machine width, speed, and automation tier procurement decisions.
- Packaging Companies:E-commerce demand concentration among fewer, larger buyers drives orders for high-speed corrugated medium and linerboard machines. Amazon and Alibaba logistics subsidiaries now dictate automation tiers through master service agreements.
- Specialty Paper Producers:Security paper, thermal receipt, and label stock manufacturers require precision coating and calendering modules with narrow web configurations.
- Commercial Paper Manufacturers:Integrated pulp-to-paper operations prioritize energy recovery and closed-loop water systems to meet EMA's Industrial Emissions Directive retrofit requirements.
- Publishers:Declining newsprint and magazine paper demand constrains new machine orders to replacement cycles rather than capacity expansion.
Publisher installations represent mature, declining deployment. Packaging company procurement shows the steepest expansion trajectory.
Application:
Product grade determines forming fabric selection, press configuration, and drying energy intensity specifications.
- Packaging Paper:Corrugated medium and linerboard machines absorb the largest share of new capacity investments as brands shift from plastic. China's GB standards enforce energy-efficiency redesigns across supplier engineering roadmaps for this segment.
- Tissue Paper:Creping and through-air drying technology trade speed against bulk softness, capping premium product yields above 2000 meters per minute. India's per-capita consumption below two kilograms annually positions domestic machine builders for sanitation-grade expansion.
- Newsprint:Groundwood pulp integration and de-inking capabilities serve declining demand in Western markets while persisting in emerging economies.
- Writing Paper:Wood-free pulp processing with multi-ply forming for opacity and printability serves office and educational demand.
Newsprint application reflects mature, contracting deployment. Packaging paper represents the fastest-climbing application category.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finnish spruce fiber deposits and Yangtze River basin bamboo pulp clusters anchor machinery demand across distinct geographies. Regional regulations and industrial clustering patterns create divergent procurement cycles for forming and drying equipment.
China
E-commerce fulfillment networks concentrate machine orders among Alibaba and JD.com logistics subsidiaries. MEE wastewater discharge limits force closed-loop water system adoption across Jiangsu and Zhejiang tissue mills. Yangtze River Delta producers absorb capital costs for heat-recovery drying sections to maintain operating licenses under dual carbon timelines.
India
Per-capita tissue consumption below two kilograms annually positions domestic builders for sanitation-grade expansion. BIS quality control orders require six to nine months for equipment certification, delaying revenue recognition. Maharashtra and Gujarat packaging corridors absorb PLI scheme subsidies for corrugated medium capacity buildouts.
Germany
EMA's Industrial Emissions Directive mandates closed-loop water retrofits across aging forming and drying sections. Voith Group anchors hydraulic technology leadership for heavy-duty packaging lines. Baden-Württemberg engineering clusters supply precision headbox components to Nordic rebuild projects.
United States
Amazon logistics subsidiaries dictate automation tiers through master service agreements for corrugated medium specifications. EPA effluent guidelines push mills toward internal filtration systems. Wisconsin and Georgia paper corridors concentrate high-speed packaging machine deployments serving fulfillment network demand.
Finland
Valmet leverages automation-integrated platforms to dominate Nordic and Baltic rebuild markets. REACH chemical compliance shapes coating chemistries for European installations. Helsinki-Tampere engineering clusters concentrate high-speed tissue line expertise for export to Asian greenfield projects.
Paper Making Machine Market Competitive Landscape
Global majors compete with regional champions across technology licensing and rebuild service networks. The supplier base organizes into three tiers: integrated engineering houses controlling headbox-to-reel platforms, component specialists dominating press felt and drying cylinder niches, and emerging Asian fabricators capturing domestic PLI-driven demand. Consolidation pressures concentrate among hydraulic forming equipment suppliers where German and Finnish engineering houses maintain single-source positions. Vertical integration into in-house component production and strategic partnerships for automation convergence represent dominant competitive vectors.
Among Nordic integrated engineering houses, Valmet occupies a position exemplifying automation-platform dominance across rebuild cycles. Andritz AG anchors the component-integration archetype through captive production of headboxes and press sections. Voith Group sits within the hydraulic-specialist tier, representing heavy-duty packaging machine leadership. These three entities collectively illustrate the technology-architecture segmentation governing procurement decisions for speed-critical installations.
| Leading Market Players |
|---|
| Valmet |
| Andritz AG |
| Voith Group |
| Mitsubishi Heavy Industries |
| Bellmer GmbH |
| Parason Machinery |
| Kadant Inc. |
| IHI Corporation |
| Toscotec SPA |
| Others |
Value Network & Pricing Analysis
Nickel-alloy stainless steel for dryer cylinders and machine frames feeds through three distinct pricing tiers based on automation depth and after-sales bundling. Finnish and German engineering houses capture premium positioning through captive component production, while Asian fabricators compete on capital cost for mechanical-drive configurations.
Pricing Analysis
Warranty and commissioning service bundling separates premium hydraulic platforms from unbundled mechanical alternatives. Three-tier pricing structure across premium, standard, and economy levels tracks automation integration, with fully automatic DCS platforms commanding substantial premiums over semi-automatic wet-end configurations. Price differentiation hinges on headbox precision grade and MEE-compliant closed-loop water system certification. Cost compression in standard-tier mechanical machines is intensifying because Indian PLI scheme subsidies favor domestic fabricators. Small-scale emerging market operators show highest price sensitivity, while Amazon and Alibaba logistics subsidiaries prioritize specification compliance over capital cost.
Supply Chain Analysis
Commissioning engineer scarcity in Baden-Württemberg and Helsinki-Tampere clusters constrains expansion timelines for high-speed packaging lines. Supply concentrates in Germany, Finland, and China, with precision headbox production anchored in German engineering clusters and automation platforms emerging from Nordic integration specialists. Raw material dependencies center on nickel-alloy stainless steel grades, synthetic press felts, and ceramic forming fabrics. Single-source vulnerability in hydraulic forming equipment from German and Finnish houses creates procurement risk for Asian greenfield projects. Distribution runs through direct mill relationships for large-capacity orders and regional agent networks for mid-tier rebuild projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
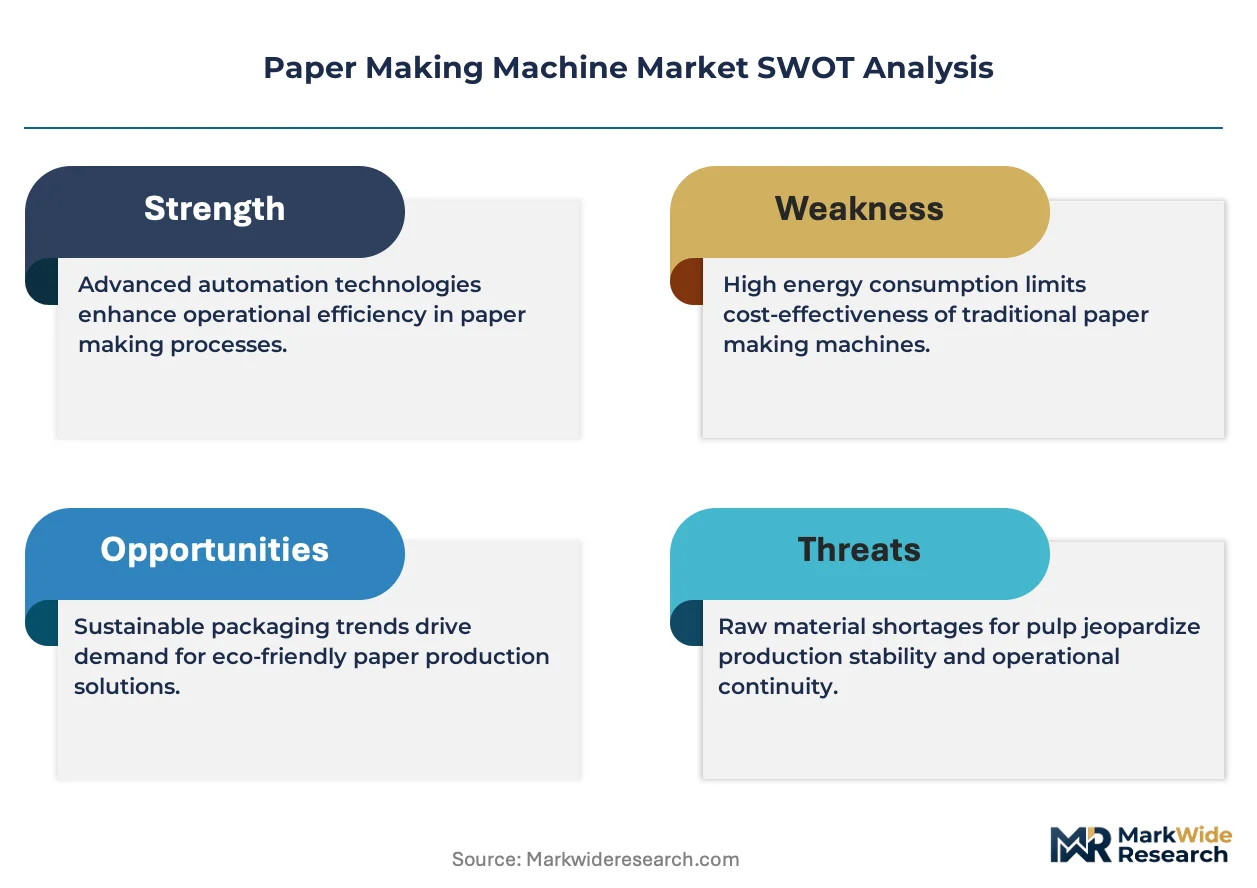
This market functions as a vertical-integration race where captive production of headboxes and press sections determines margin defense against Asian cost competition.
For Market Incumbents: Anchor market position through backward integration into precision headbox manufacturing and press section component production. Valmet, Andritz AG, and Voith Group already demonstrate this archetype. Defend against emerging Asian fabricators by locking Amazon and Alibaba logistics subsidiaries into multi-year master service agreements with embedded automation upgrade clauses. Certification investment in China's GB standards and India's BIS quality control orders creates switching costs for packaging company buyers. For New Entrants and Emerging Players: Enter via India's underpenetrated tissue market where per-capita consumption sits below two kilograms annually and domestic PLI scheme subsidies offset capital equipment costs. Target Maharashtra and Gujarat packaging corridors for corrugated medium capacity buildouts where BIS certification timelines create incumbent vulnerability. Pursue technology licensing partnerships with European engineering houses for hydraulic forming expertise rather than greenfield R&D investment. For Investors and Strategic Acquirers: Amazon and Alibaba master service agreement announcements are the leading indicator that packaging paper machine demand is accelerating beyond replacement cycles. Position portfolios for a 5-10 year window where e-commerce fulfillment network concentration drives specification standardization and consolidates procurement among fewer buyers. Prioritize acquisition targets with captive headbox production and established BIS or GB certification track records. Watch for provincial subsidy announcements under China's dual carbon goals as inflection signals for heat-recovery drying section demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Headbox Production | Captive precision forming equipment supply reduces dependency on German engineering houses for Asian projects. |
| Automation-Convergence Partnership | Machine vision and predictive maintenance algorithm integration with legacy DCS platforms enables autonomous speed adjustments. |
| GB Standards Certification Investment | Energy-efficiency compliance for China's dual carbon goals unlocks provincial subsidy access for heat-recovery configurations. |
| PLI Scheme Alignment in India | Domestic capacity buildout subsidies for packaging-grade machines accelerate revenue recognition despite BIS timeline delays. |
| Closed-Loop Water System Development | MEE wastewater discharge compliance in Yangtze River basin maintains operating licenses for Jiangsu and Zhejiang tissue mills. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study. Primary interviews with paper mill maintenance directors, OEM procurement teams, aftermarket service heads, and plant engineers validated demand assumptions across Nordic, German, and Asian installations. Technical R&D directors at forming equipment suppliers provided insight into speed-tissue tradeoff limitations. Secondary sources included BIS quality control order documentation, MEE wastewater discharge filings, EMA Industrial Emissions Directive compliance databases, and capital equipment import records. Bottom-up machine shipment tallies by speed tier and width converged with top-down pulp capacity expansion projections.
Data-stream reconciliation across machine order backlogs, fiber sustainability mandate timelines, and e-commerce fulfillment network expansion plans shaped the analytical framework. Segmentation modeling tracked automation depth, power transmission architecture, end-user scale, and application grade across the projection horizon. CAGRs derived from capacity utilization rates, replacement cycle timing, and greenfield investment announcements. Industry-specific inputs included PLI scheme disbursement schedules, GB standards enforcement phases, and provincial dual carbon subsidy qualification criteria.
Revisions become necessary when BIS certification timelines extend beyond current six-to-nine-month windows, when nickel-alloy price volatility compresses fabrication margins unpredictably, or when Amazon and Alibaba logistics subsidiaries shift from master service agreements to direct equipment procurement. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Paper Glass Market
Paper Products
Polyester Synthetic Paper Market
Paper Products
Drum Pulper Market
Paper Products
North America Specialty Paper Market
Paper Products
Base Paper Market
Paper Products
Global Cellulose Sponge Market
Paper Products
Global Copier Paper Market
Paper Products
Chemical Pulp Market
Paper Products
Europe Tissue and Hygiene Paper Market
Paper Products
Billing Paper Market
Paper Products
Paper Goods Market
Paper Products
Sawn Wood Market
Paper Products
Clay Coated Paper Market
Paper Products
Saturated Kraft Paper Market
Paper Products
Pigmented Paper Market
Paper Products
Unbleached Hardwood Kraft Pulp Market